
 Global Aerospace Titanium Machining Market | 2026-2036
Global Aerospace Titanium Machining Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aerospace Titanium Machining Market Analysis
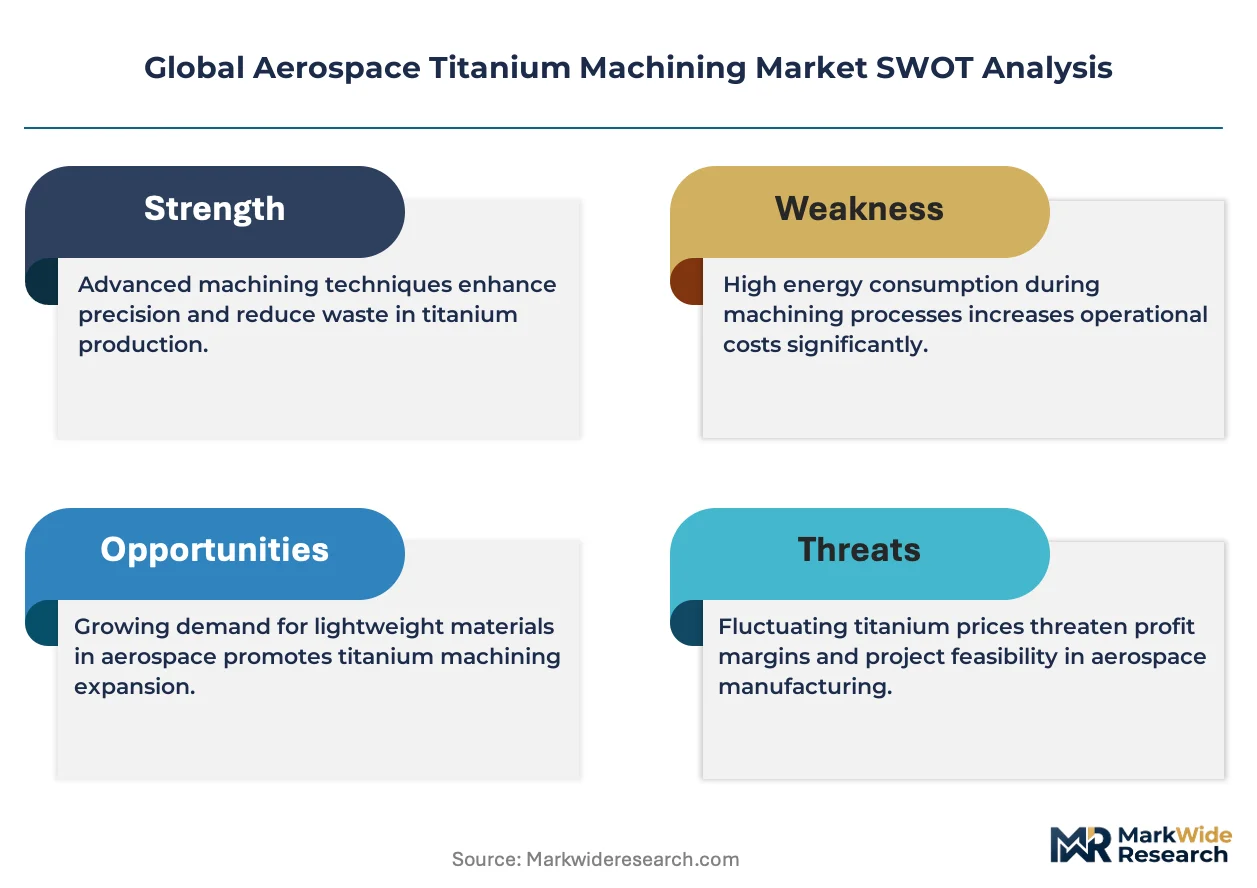
Additive manufacturing integration is tilting traditional titanium machining workflows toward hybrid production models that combine near-net-shape deposition with precision finishing. VSMPO-AVISMA Corporation leverages its integrated titanium sponge-to-forging chain to dominate raw material supply for Western airframers. Precision Castparts Corp anchors the critical engine components segment through captive casting and machining operations. Norsk Titanium US Inc. differentiates via plasma-deposition technology that reduces buy-to-fly ratios on structural brackets.
Aerospace titanium machining encompasses the precision material removal processes applied to titanium alloys—primarily Ti-6Al-4V and Ti-5Al-5V-5Mo-3Cr—to achieve dimensional tolerances within 0.005 inches for flight-critical components, where the metal's high strength-to-weight ratio and corrosion resistance serve propulsion and airframe systems operating at cryogenic to 600°F temperatures. Bars and forgings command the deepest margin pools due to aerospace-grade certification burdens and limited qualified supplier bases, while electrical discharge machining gains share for complex internal geometries in engine components that conventional milling cannot access. The aerostructures application segment sustains the largest absolute volume as single-aisle programs expand output.
FAA, EASA, and China's NMPA enforce divergent material qualification pathways that fragment certification costs and extend supplier onboarding timelines for multinational programs. REACH and RoHS constraints within Europe restrict certain machining fluid chemistries, compelling process requalification investments. Stakeholders must monitor how emerging sustainable aviation fuel mandates reshape engine thermal profiles and the titanium alloy specifications those profiles demand.
Market Dynamics
Hybrid manufacturing workflows are compressing traditional titanium machining cycles as plasma-deposition systems integrate with five-axis finishing centers, forcing suppliers to retool for near-net-shape processing or cede structural bracket contracts to deposition-first competitors.
Growth Catalysts
- Single-aisle production ramp:Boeing and Airbus assembly line expansions in Renton and Toulouse are pulling precision-machined Ti-6Al-4V components through qualified supplier networks at accelerated procurement cadences.
- FAA airworthiness pathway streamlining:The regulator's updated material qualification guidance for additive-enhanced titanium reduces certification timelines for hybrid-processed flight-critical brackets.
- Engine thermal profile escalation:Sustainable aviation fuel combustion temperatures are demanding Ti-5Al-5V-5Mo-3Cr alloys with superior creep resistance, expanding addressable machining content per powerplant.
Market Restraints
- Sponge supply concentration:VSMPO-AVISMA's control over Western titanium sponge creates single-source vulnerability for mills dependent on Russian-origin feedstock qualified under legacy Boeing and Airbus specifications.
- REACH machining fluid constraints:ECHA restrictions on chlorinated paraffin-based coolants force European suppliers into costly process requalification for aerospace-grade surface finish specifications.
- Buy-to-fly ratio compression ceiling:Conventional billet-to-component material efficiency plateaus near 15:1 for complex engine casings, limiting margin recovery from titanium ingot price volatility.
Strategic Opportunities
- India defense aerospace localization:Hindustan Aeronautics Limited's Tejas Mk2 and AMCA programs are mandating indigenous titanium machining capability, creating first-mover advantage for joint-venture precision forgers.
- Plasma-deposition hybrid adoption:Norsk Titanium's Rapid Plasma Deposition technology converging with robotic milling cells enables 80% material reduction on structural brackets, opening previously uneconomical part families.
- EU Green Deal supplier incentives:CSRD-aligned capital expenditure tax treatments for energy-efficient machining centers are accelerating German and French shop-floor electrification investments.
Industry Challenges
- Five-axis programming talent scarcity:CAM software expertise for simultaneous titanium milling lags demand in Wichita, Toulouse, and Hamburg manufacturing clusters, extending lead times for complex engine component orders.
- Dual certification burden:Suppliers serving Boeing and COMAC programs must maintain parallel FAA and NMPA material qualification datasets, duplicating metallurgical testing expenditures.
- Legacy ERP integration friction:Shop-floor data collection from new deposition-monitoring sensors conflicts with established MES architectures at tier-one aerostructure suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aerospace Titanium Machining Market |
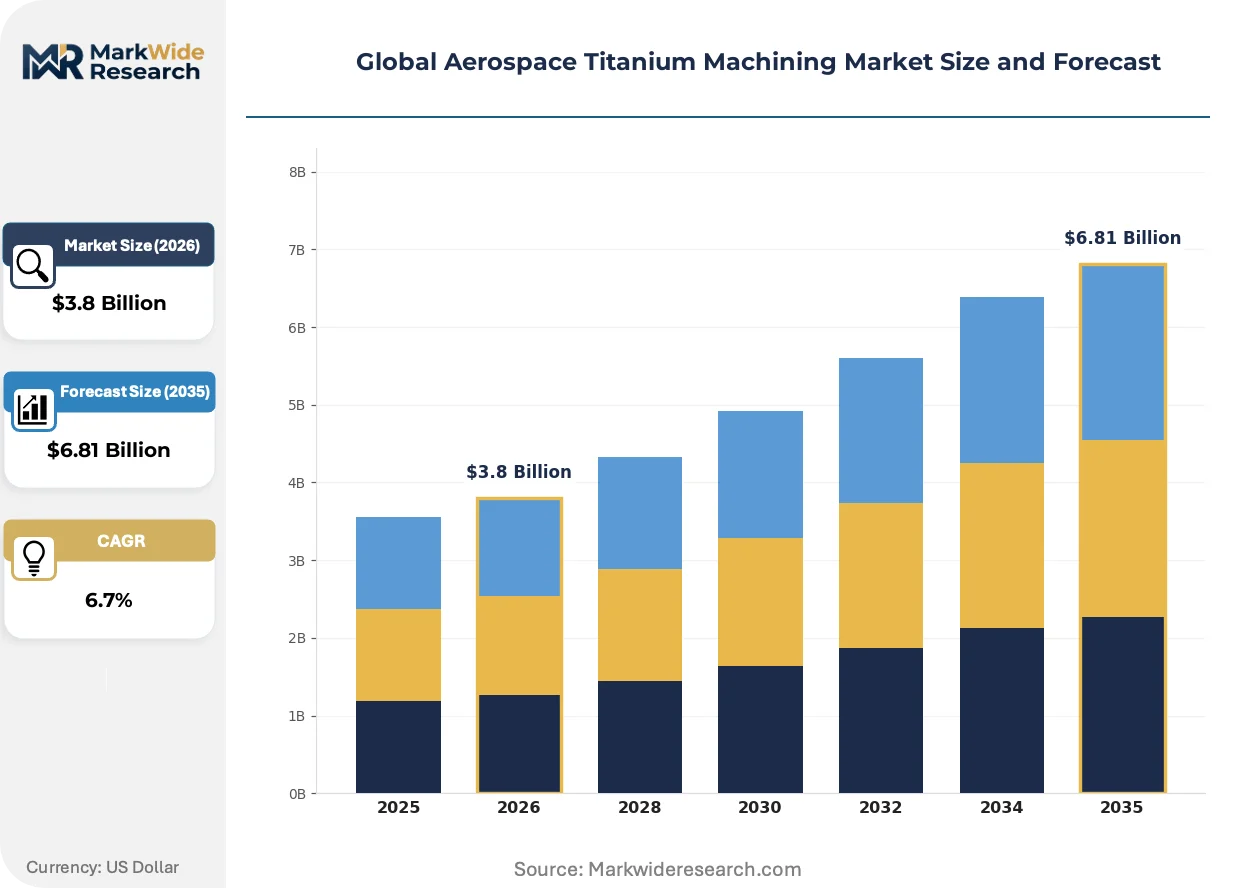
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bars, Sheets, Plates, Forgings Application: Aerostructures, Engine Components, Landing Gear, Fasteners Manufacturing Process: Milling, Turning, Electrical Discharge Machining, Grinding End User: Commercial Aviation, Defense, Space Exploration, OEMs |
| Companies Covered | Titanium Metals Corporation, Carpenter Technology Corporation, Precision Castparts Corp, GKN Aerospace Services Limited, Smiths Advanced Metals, VSMPO-AVISMA Corporation, GE Aviation, Norsk Titanium US Inc., Allegheny Technologies Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aerospace Titanium Machining Market Emerging Trajectories
Digital thread architectures are collapsing design-to-part lead times in titanium machining by connecting generative topology optimization directly to toolpath generation, bypassing traditional CAD-CAM handoffs that introduced iteration cycles.
Digital twin platforms for deposition-machining hybrid cells are virtualizing process validation workflows, allowing GKN Aerospace and Spirit AeroSystems to simulate thermal distortion compensation before physical part commitment, compressing first-article qualification from months to weeks.
EASA's evolving CS-25 material qualification standards for additive-enhanced titanium are mandating expanded metallurgical datasets from suppliers, forcing European machine shops to deploy in-house computed tomography inspection capabilities that were previously outsourced to accredited laboratories.
Airframers are consolidating structural titanium procurement under long-term throughput agreements rather than spot orders, shifting risk to machining suppliers who must now carry finished goods inventory against indexed titanium sponge price mechanisms, a pattern most visible in Airbus's Hamburg and Mobile supply base renegotiations.
Global Aerospace Titanium Machining Market Segmentation
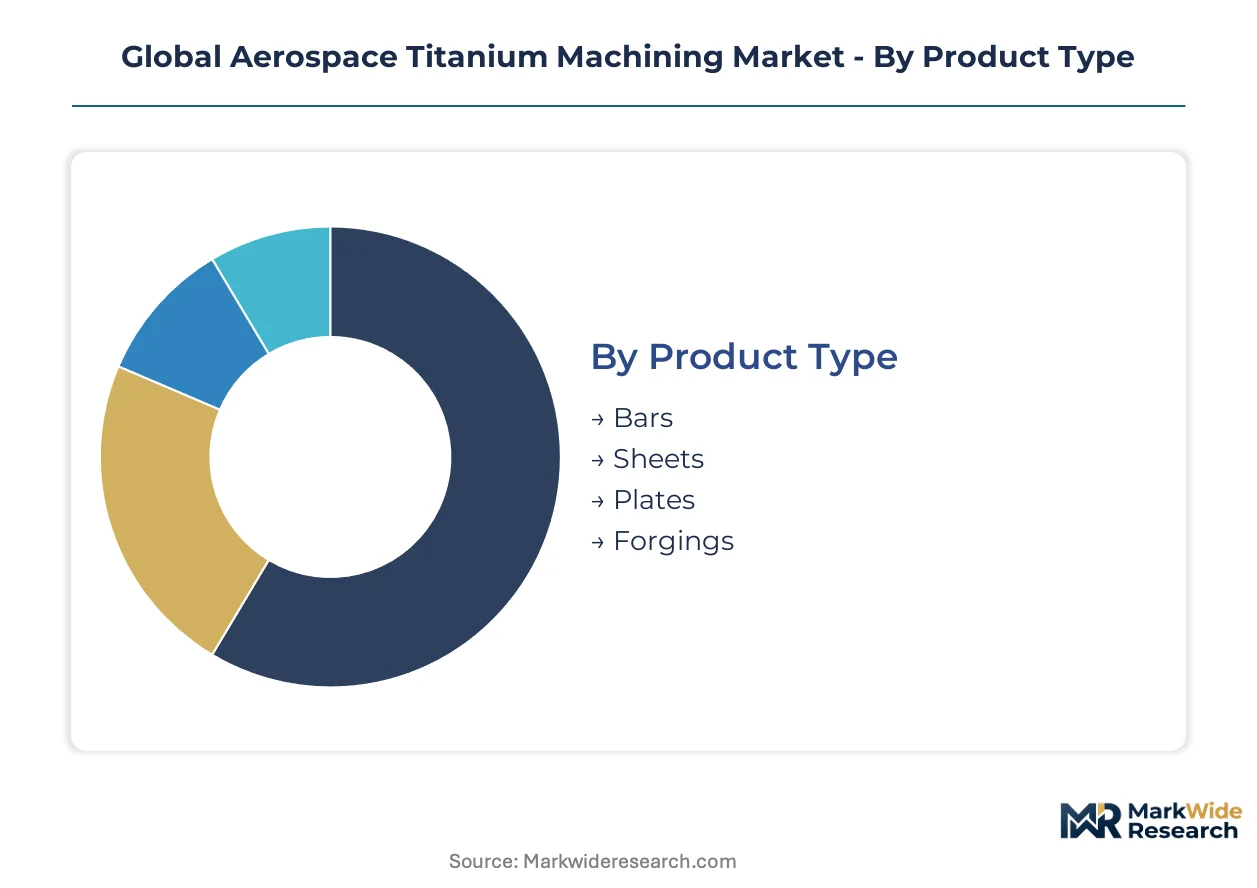
Aerospace titanium machining spans distinct material forms, manufacturing processes, and end-use applications that shape procurement patterns and margin structures. Understanding these divisions reveals where qualification burdens concentrate and where hybrid manufacturing technologies are gaining traction.
Product Type:
Titanium mill products serve different functional roles across airframe and propulsion systems, with certification depth varying dramatically by form factor.
- Bars:Round and hexagonal bar stock in Ti-6Al-4V and Ti-5Al-5V-5Mo-3Cr grades supply fastener blanks and actuator rods. Airbus and Boeing fastener specifications demand vacuum-arc-remelted material with ultrasonic-tested billet integrity, concentrating demand in Germany and Japan where qualified forging houses maintain captive bar conversion.
- Forgings:Closed-die and isothermal forgings command premium positioning for bulkheads, wing carry-through structures, and engine fan disks. The qualification burden—spanning Boeing D1-4426 and Airbus AIPS standards—limits qualified suppliers to VSMPO-AVISMA, PCC Structurals, and Howmet Aerospace facilities in Russia, US, and UK.
- Sheets:Cold-rolled and hot-rolled sheet products serve skin panels and ducting where gauge tolerance drives forming yield.
- Plates:Plate mill products support machined structural brackets and firewalls, with thickness ranges from 6mm to 150mm.
The dominant share belongs to Forgings, while Bars is closing the gap fastest as fastener demand outpaces airframe production rates.
Application:
Component function determines thermal exposure, stress states, and the alloy specifications that machining suppliers must qualify against.
- Aerostructures:Wing ribs, spars, and fuselage frames in Ti-6Al-4V account for the largest machining volume by tonnage. Single-aisle program rate increases at Airbus Toulouse and Boeing Renton pull material through qualified supplier networks, with Norsk Titanium's plasma-deposition brackets gaining share on A321XLR wing attachments.
- Engine Components:Compressor blades, disks, and casings in Ti-5Al-5V-5Mo-3Cr and Ti-6Al-2Sn-4Zr-2Mo operate at 600°F with creep resistance requirements. GE Aerospace and Rolls-Royce specifications mandate grain structure control through alpha-beta processing windows, concentrating machining at PCC Airfoils and Safran facilities.
- Landing Gear:Ti-10V-2Fe-3Al forgings for truck beams and pistons demand high-strength heat treatment protocols.
- Fasteners:Bolts, pins, and collars in Ti-6Al-4V ELI serve structural joints with fatigue-critical thread forms.
Aerostructures maintains volume leadership, though Engine Components exhibits the steepest expansion trajectory as geared turbofan architectures multiply titanium content per powerplant.
Manufacturing Process:
Material removal methods stratify by geometric complexity, surface finish requirements, and the capital intensity of equipment platforms.
- Milling:Five-axis simultaneous machining dominates structural bracket and frame production, with Makino MAG-series and DMG MORI DMU platforms standard at tier-one suppliers. CAM programming talent scarcity in Wichita and Hamburg extends lead times for complex engine casing programs.
- Turning:CNC lathe operations with live tooling produce rotational components like actuator cylinders and fastener blanks. Swisstype configurations at Tornos and Star machines achieve 0.0005-inch tolerances for hydraulic fittings on Airbus A350 programs.
- Electrical Discharge Machining:Wire and sinker EDM access internal geometries in blisks and fuel nozzles that conventional cutting cannot reach.
- Grinding:Creep-feed and surface grinding finish bearing surfaces and seal lands to microinch specifications.
Milling commands the installed equipment base, while Electrical Discharge Machining is gaining share fastest as blisk geometries grow more intricate.
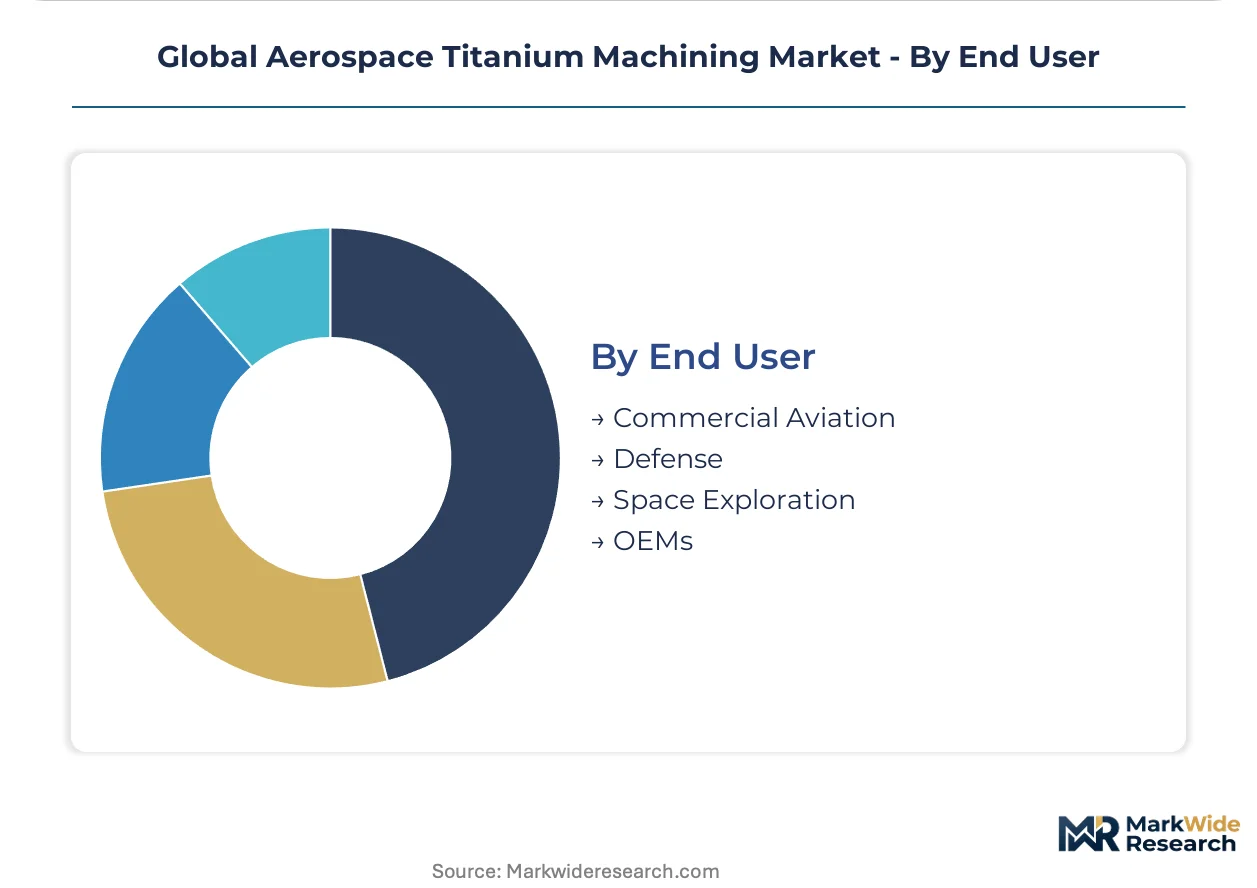
End User:
Customer categories impose divergent qualification timelines, volume predictability, and pricing mechanisms on machining suppliers.
- Commercial Aviation:Airbus and Boeing production systems pull components through long-term throughput agreements with indexed titanium sponge pricing. Spirit AeroSystems and GKN Aerospace have renegotiated Hamburg and Mobile supply bases toward finished goods inventory risk transfer.
- Defense:F-35, B-21, and Eurofighter programs sustain classified machining requirements with longer lead times but greater price stability. US DOD sourcing restrictions on Russian-origin sponge create supply chain tension for legacy qualified material.
- Space Exploration:Reusable launch vehicle programs at SpaceX and Blue Origin demand Ti-6Al-4V pressure vessels with novel thin-wall machining protocols.
- OEMs:Tier-one aerostructure and propulsion manufacturers serve as procurement consolidators, aggregating machining demand from captive and external suppliers.
Commercial Aviation holds the dominant procurement volume, while Space Exploration is climbing the fastest as launch cadence multiplies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Airframers and engine OEMs concentrate procurement authority in manufacturing clusters where qualified titanium machining suppliers maintain FAA and EASA certification. Boeing, Airbus, and COMAC production systems pull material through geographically anchored supplier networks with divergent regulatory burdens.
United States
Boeing's Renton and Everett assembly lines sustain the largest commercial aviation demand pool for Ti-6Al-4V structural components. FAA airworthiness certification requirements govern all flight-critical machining workflows, with D1-4426 specifications limiting qualified suppliers. Wichita, Kansas hosts a dense precision machining cluster where Spirit AeroSystems and tier-two suppliers compete for single-aisle program contracts.
Germany
Airbus Hamburg and Premium AEROTEC facilities anchor European aerostructure demand for titanium brackets and frames. EASA's evolving CS-25 material qualification standards and REACH machining fluid constraints force process requalification investments. Bavaria's aerospace supplier corridor around Munich concentrates five-axis machining capacity for engine component programs.
China
COMAC's Shanghai assembly operations and expanding C919 production rates are pulling domestic titanium machining investment. NMPA material qualification pathways diverge from FAA standards, duplicating metallurgical testing for multinational suppliers. Xi'an and Chengdu manufacturing clusters host state-backed precision forging operations serving military and commercial programs.
Japan
Subcontractor networks around Nagoya supply Boeing and Airbus programs with Ti-6Al-4V fastener blanks and actuator components. METI industrial policy supports titanium sponge production and downstream machining capability retention. Kobe Steel and affiliated suppliers maintain vacuum-arc-remelted material certification for Western airframer specifications.
India
Hindustan Aeronautics Limited's Tejas Mk2 and AMCA programs mandate indigenous titanium machining capacity development. Ministry of Defence localization requirements create joint-venture opportunities for foreign precision forgers. Bangalore and Hyderabad defense aerospace clusters are expanding five-axis machining footprints for indigenous fighter programs.
Global Aerospace Titanium Machining Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered supplier structure. Integrated titanium producers and captive aerostructure manufacturers anchor the premium tier, while independent machine shops populate the fragmented mid-market. Strategic archetypes include sponge-to-forging integrators, deposition-technology disruptors, and precision-forging specialists. Competitive moves center on hybrid manufacturing adoption and long-term throughput agreement renegotiation with indexed material pricing.
Among integrated material suppliers, VSMPO-AVISMA Corporation exemplifies the sponge-to-forging archetype with upstream control over titanium feedstock. Precision Castparts Corp occupies a position within the captive manufacturing tier, while Norsk Titanium US Inc. represents deposition-first challengers to conventional machining workflows. These three entities anchor distinct competitive vectors: raw material security, vertical manufacturing integration, and additive-hybrid technology adoption.
| Leading Market Players |
|---|
| Titanium Metals Corporation |
| Carpenter Technology Corporation |
| Precision Castparts Corp |
| GKN Aerospace Services Limited |
| Smiths Advanced Metals |
| VSMPO-AVISMA Corporation |
| GE Aviation |
| Norsk Titanium US Inc. |
| Allegheny Technologies Incorporated |
| Others |
Supply Flow & Price Mechanics
VSMPO-AVISMA's Verkhnyaya Salda metallurgical complex anchors Western titanium sponge supply, and its capacity allocation decisions cascade directly into billet pricing power for downstream precision forgers serving Boeing and Airbus programs. Long-term throughput agreements with indexed material pricing now dominate procurement, transferring inventory risk to machining suppliers while locking in volume commitments.
Pricing Analysis
Cost-plus contracts with titanium sponge indexation govern Airbus and Boeing procurement, with pricing stratifying across aerospace-grade certification tiers, volume scale commitments, and geographic delivery zones. Cost compression in structural bracket machining is intensifying because Norsk Titanium's plasma-deposition hybrid cells achieve 80% material reduction, forcing conventional mills to absorb margin erosion. Tier-two suppliers serving single-aisle programs exhibit highest price sensitivity, while engine component specialists with FAA D1-4426 certification command premium positioning.
Supply Chain Analysis
PCC Structurals, Howmet Aerospace, and Safran Landing Systems hold captive machining capacity for flight-critical forgings, with supply concentrating in the United States, United Kingdom, and Russia for qualified titanium sponge. The chain draws from titanium sponge, vacuum-arc-remelted ingot, and specialized cutting tool inputs. Single-source vulnerability around VSMPO-AVISMA's Russian-origin feedstock creates structural risk given Boeing and Airbus legacy specifications. Distribution runs through tier-one aerostructure consolidators like Spirit AeroSystems and GKN Aerospace, which aggregate demand from qualified supplier networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid manufacturing platforms are redefining competitive economics in aerospace titanium machining, with interoperability between plasma-deposition and five-axis finishing creating ecosystem lock-in for early adopters.
For Market Incumbents: Build certification moats around FAA-EASA dual qualification datasets to defend against deposition-first challengers. Deepen backward integration into vacuum-arc-remelted ingot production to reduce sponge price volatility exposure. Expand five-axis programming talent pipelines in Wichita and Hamburg to compress complex engine component lead times. For New Entrants and Emerging Players: Pursue India's defense aerospace localization mandate through joint ventures with Hindustan Aeronautics Limited for Tejas Mk2 and AMCA programs. Target structural bracket applications where plasma-deposition hybrid technology opens previously uneconomical part families. Lead with EU Green Deal-aligned energy-efficient machining center investments to capture CSRD capital expenditure incentives. For Investors and Strategic Acquirers: Long-term, this sits as a materials-technology consolidation play because hybrid manufacturing adoption will separate deposition-capable suppliers from conventional mills. Focus acquisition screening on mid-cap precision forgers with captive metallurgical testing and in-house computed tomography inspection. Monitor Norsk Titanium contract wins at Airbus Hamburg as the signal for plasma-deposition technology inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Manufacturing Adoption | Plasma-deposition integration with five-axis finishing compresses buy-to-fly ratios for structural brackets. |
| Dual Certification Investment | Parallel FAA and NMPA qualification datasets unlock Boeing and COMAC program access for multinational suppliers. |
| Backward Integration into Sponge | Captive titanium sponge supply insulates margin volatility from VSMPO-AVISMA concentration risk. |
| Energy-Efficient Machining Deployment | CSRD-aligned capital expenditure tax treatments accelerate German and French shop-floor electrification. |
| Defense Localization Partnership | Joint ventures with HAL address India's indigenous titanium machining mandate for fighter programs. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with aerospace procurement directors, CAM programming specialists, metallurgical qualification engineers, and tier-one supplier operations managers; and secondary validation against FAA airworthiness directives, EASA CS-25 material standards, SEC filings from publicly traded aerostructure manufacturers, and customs trade data on titanium sponge flows. Bottom-up segment sizing triangulated with top-down macroeconomic drivers across the analysis window.
Forecast inputs span product type segmentation by mill product form, application segmentation across aerostructures and propulsion systems, manufacturing process technology adoption curves, and end-user category procurement patterns. CAGRs derive from regression analysis against single-aisle production rate trajectories, engine thermal profile escalation from sustainable aviation fuel mandates, and hybrid manufacturing penetration assumptions. Titanium alloy specification shifts and REACH machining fluid regulatory constraints anchor scenario modeling.
Sensitivities concentrate around VSMPO-AVISMA supply disruption, EASA additive-enhanced titanium qualification timeline extensions, and sustainable aviation fuel combustion temperature effects on Ti-5Al-5V-5Mo-3Cr alloy demand. Quarterly review of Airbus and Boeing assembly line rate announcements, Norsk Titanium contract disclosures, and India defense procurement tenders is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aeroengine Composites Market
Aerospace and Aircraft Materials
Global Aerospace Insulation Market
Aerospace and Aircraft Materials
Coated Fabrics for Defense Market
Aerospace and Aircraft Materials
Aerographene Market
Aerospace and Aircraft Materials
Aerospace Fiber Optics Market
Aerospace and Aircraft Materials
Advanced Materials for Flying Cars Market
Aerospace and Aircraft Materials
Aerospace Titanium Market
Aerospace and Aircraft Materials
Aircraft Carbon Brake Disc Market
Aerospace and Aircraft Materials
Aircraft Coatings Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives and Sealants Market
Aerospace and Aircraft Materials
Aluminum Beryllium Market
Aerospace and Aircraft Materials
Fiberglass for Aerospace Market
Aerospace and Aircraft Materials
Composites in United States Defense Market
Aerospace and Aircraft Materials
Global High Strength Aluminum Alloys Market
Aerospace and Aircraft Materials
Aerospace and Defense Materials Market
Aerospace and Aircraft Materials
Magnesium Beryllium Alloy Market