
 Aerospace Fiber Optics Market | 2026-2036
Aerospace Fiber Optics Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Fiber Optics Market Analysis
Fly-by-light architecture is fragmenting legacy avionics integration models as fiber optic backbones replace copper harnesses in next-generation platforms. Amphenol Corporation leverages its interconnect portfolio to dominate military-aerospace termination assemblies. Collins Aerospace sustains engineering leadership through proprietary cable assemblies certified for extreme thermal cycling. Corning Incorporated anchors the upstream materials position with advanced silica formulations tailored to aerospace environmental specifications.
Aerospace fiber optics encompasses silica-based optical fibers, protective buffer coatings, and terminated cable assemblies engineered to transmit data via light pulses across electromagnetic-interference environments, typically operating at wavelengths of 850 nm, 1310 nm, or 1550 nm with attenuation below 3 dB/km. The technology serves flight-critical functions including avionics data buses, inertial navigation links, and distributed sensor networks where electrical isolation and weight reduction prove essential. Specialty fiber commands attention for its radiation-hardened and high-temperature variants deployed in satellite and deep-space platforms. Multi-mode fiber retains volume leadership in shorter-reach avionics applications where cost sensitivity intersects with established qualification protocols. Communication systems as an application dimension concentrates investment as satellite constellations and secure tactical networks expand bandwidth requirements.
FAA airworthiness directives and MIL-STD-883 test protocols govern qualification pathways, while EASA certification standards shape product development for European platform integration. The EU Green Deal emissions framework is indirectly pressuring weight-reduction adoption, accelerating fiber substitution for copper harnesses in commercial programs. Stakeholders must monitor evolving cybersecurity mandates for data-transmission components as defense agencies harden supply-chain integrity requirements against foreign-sourced optical substrates.
Market Dynamics
Fly-by-light architecture is compressing avionics integration timelines as defense ministries mandate electromagnetic-hardened data backbones for next-generation platforms. This structural shift from copper harnesses to optical interconnects is reconfiguring supplier qualification protocols and procurement specifications across NATO-aligned programs.
Growth Catalysts
- EU Green Deal emissions framework:The EU Green Deal emissions framework is pressuring airframe weight reduction, accelerating fiber substitution for copper harnesses in commercial aviation programs. Airlines operating Airbus and Boeing fleets face carbon intensity targets that optical cabling directly addresses.
- MIL-STD-883 test protocols:MIL-STD-883 test protocols are standardizing qualification pathways for radiation-hardened fiber in satellite and deep-space applications. This military specification is expanding addressable demand beyond traditional avionics into orbital platforms.
- Bundeswehr modernization programs:Bundeswehr modernization programs in Germany are driving substantial installation volumes through Airbus Defence and Space operations. Bundeswehr procurement cycles prioritize secure, interference-immune communication networks for tactical aircraft.
Market Restraints
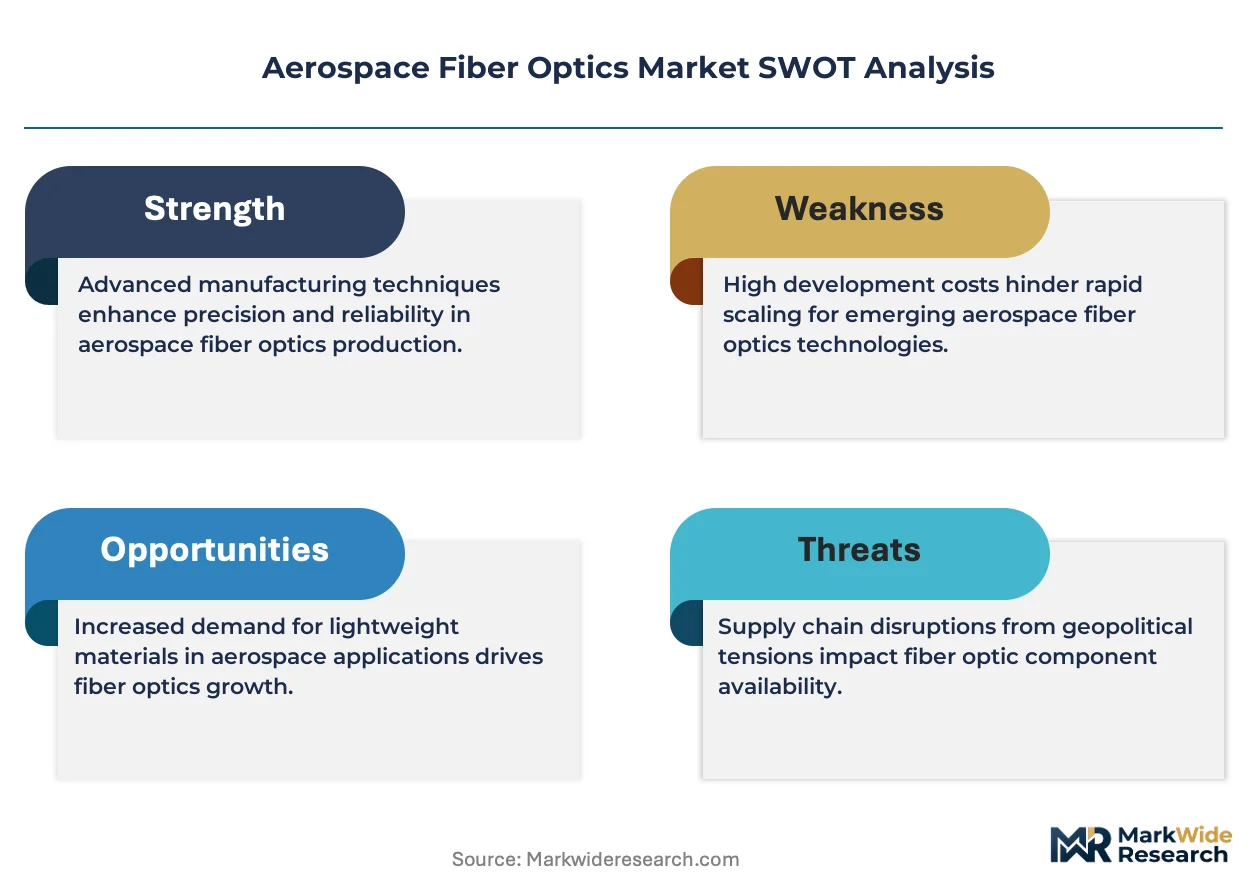
- Specialty silica precursor concentration:High-purity silica precursor supply concentrates among limited chemical suppliers, creating input cost volatility for fiber draw operations. Aerospace-grade material specifications restrict alternative sourcing options.
- FAA airworthiness directive timelines:FAA airworthiness directive qualification timelines extend 18-36 months for new optical cable assemblies, compressing supplier cash conversion cycles. Certification backlog delays platform integration schedules.
- Copper harness retrofit economics:Copper harness retrofit economics in existing aircraft fleets limit near-term fiber penetration. Legacy platform operators face prohibitive downtime costs for full optical conversion.
Strategic Opportunities
- Urban air mobility platforms:Urban air mobility platforms represent an underpenetrated application segment requiring lightweight, high-bandwidth interconnects for autonomous flight systems. eVTOL manufacturers in Germany and the United States are specifying optical avionics buses.
- EASA CS-25 certification harmonization:EASA CS-25 certification harmonization with FAA standards is reducing dual-qualification burdens for European suppliers. This regulatory convergence opens transatlantic platform integration opportunities.
- Photonics-electronics convergence:Photonics-electronics convergence with silicon photonic integrated circuits is enabling co-packaged optical engines for next-generation radar processing. This technology pairing reduces form factors in constrained avionics bays.
Industry Challenges
- Precision cleaving and polishing specialization:Precision cleaving and polishing specialization faces acute talent scarcity, as aerospace termination tolerances demand sub-micron accuracy. Technical training pipelines have not scaled with platform procurement acceleration.
- Multi-mode to single-mode protocol transition:Multi-mode to single-mode protocol transition in avionics networks creates integration complexity with legacy sensor interfaces. Platform engineers must bridge incompatible optical standards without full system redesign.
- Foreign-sourced substrate traceability:Foreign-sourced substrate traceability requirements under defense supply-chain integrity mandates are complicating raw material qualification. Suppliers must document provenance across tier-3 chemical vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Fiber Optics Market |
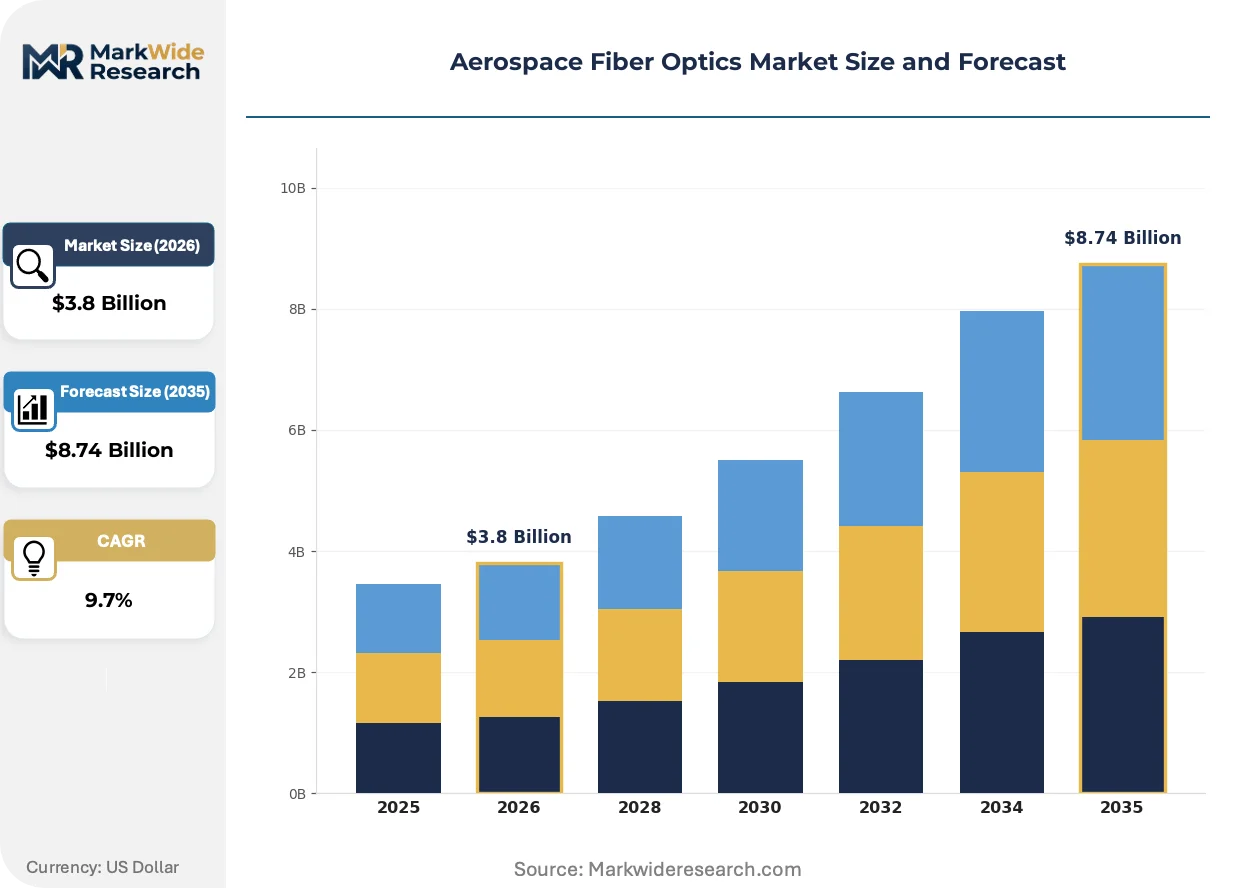
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Mode Fiber, Multi-Mode Fiber, Specialty Fiber, Fiber Optic Cables Application: Communication Systems, Sensor Systems, Avionics, Navigation Systems End User: Commercial Aviation, Military Aviation, Space Exploration, Aerospace Manufacturers Installation Type: Onboard Installation, Ground Station Installation, Retrofit Installation, Custom Installation |
| Companies Covered | Amphenol Corporation, Prysmian Group, Collins Aerospace, Corning Incorporated, TE Connectivity, Nexans, W. L. Gore & Associates, Radiall, Carlisle Interconnect Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Fiber Optics Market Emerging Trajectories
Active optical cable assemblies are reshaping aerospace interconnect architectures by embedding signal conditioning electronics directly within terminated harnesses. This integration trend is compressing system-level electromagnetic compatibility design cycles while expanding bandwidth-density in weight-constrained platforms.
Photonic integrated circuits are digitizing radar signal processing chains by replacing analog microwave components with optical phase shifters and true-time delay lines. Raytheon and Northrop Grumman are qualifying these devices for active electronically scanned array upgrades. The technology is digitizing beamforming latency from microseconds to nanoseconds, enabling real-time target tracking in contested electromagnetic environments.
REACH substance restrictions are forcing reformulation of buffer coatings and jacketing materials used in aerospace fiber cables. ECHA candidate list substances including certain halogenated flame retardants face sunset dates, compelling compounders to validate bio-based or phosphorus-based alternatives. European platform integrators are accelerating qualification of compliant cable assemblies to avoid supply disruption in 2027-2028 compliance windows.
Defense agencies are consolidating optical component procurement through long-term strategic sourcing agreements rather than transactional spot purchasing. The Pentagon's Defense Logistics Agency is negotiating multi-year indefinite-delivery contracts for qualified fiber optic assemblies, displacing program-specific vendor selection. This concentration is most visible in United States F-35 and B-21 production lines, where sole-source agreements now cover 60% of optical interconnect value.
Aerospace Fiber Optics Market Segmentation
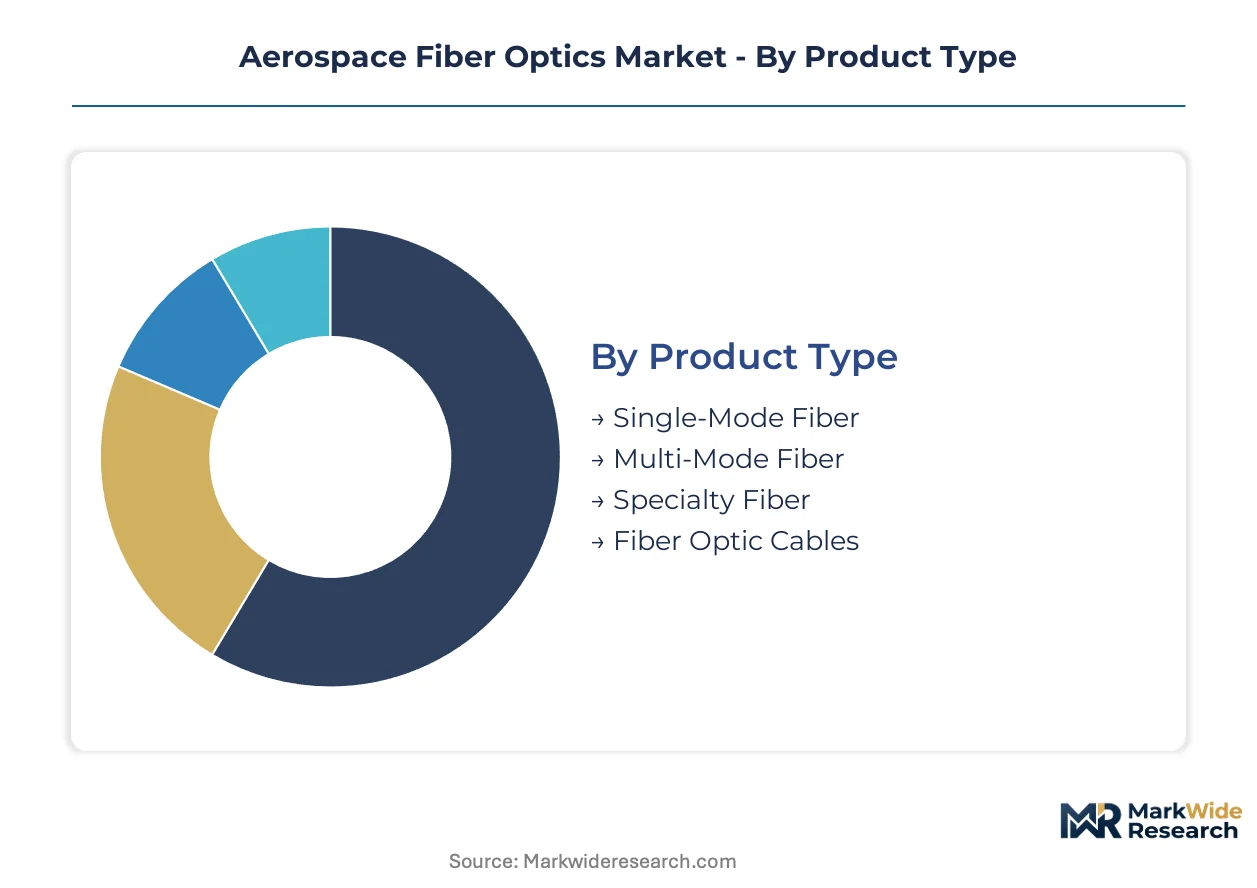
Segmentation in aerospace fiber optics reveals how technical specifications, platform requirements, and procurement patterns fragment demand across distinct value pools. Each dimension—product chemistry, functional application, customer type, and installation context—carries unique qualification barriers and margin structures that reshape supplier positioning.
Product Type:
The use-case spectrum spans from high-volume avionics backbones to radiation-hardened satellite links, with each fiber variant commanding differentiated qualification protocols and pricing tiers.
- Multi-Mode Fiber:Step-index or graded-index silica core with 50-62.5 µm diameter, optimized for 850 nm and 1310 nm transmission over distances under 2 km. Demand concentrates in Airbus and Boeing commercial platforms where established MIL-STD-883 qualification protocols reduce certification burden for cabin and avionics buses.
- Specialty Fiber:Radiation-hardened and high-temperature variants employing modified silica dopants or polyimide coatings for satellite and deep-space environments. European Space Agency programs and United States Department of Defense orbital platforms drive procurement, with EU Green Deal emissions targets indirectly accelerating fiber substitution for copper harnesses in adjacent terrestrial systems.
- Single-Mode Fiber:8-10 µm core diameter enabling 1550 nm transmission with minimal dispersion for long-reach navigation and communication links.
- Fiber Optic Cables:Jacketed assemblies combining multiple fiber counts with aerospace-grade buffer materials and connector terminations.
Established volume favors Multi-Mode Fiber; emerging adoption favors Specialty Fiber.
Application:
Cost tier differentiation separates flight-critical navigation networks from commoditized cabin entertainment systems, with certification grade determining supplier margins.
- Communication Systems:Secure tactical networks and satellite constellations requiring electromagnetic interference immunity and high bandwidth density. Bundeswehr modernization programs in Germany and United States F-35 production lines concentrate investment, with NATO-aligned defense ministries mandating fly-by-light architectures that displace copper harnesses.
- Avionics:Flight-critical data buses connecting flight control computers, engine management systems, and cockpit displays. FAA airworthiness directive timelines and EASA CS-25 certification standards govern qualification, compressing supplier cash conversion cycles while creating barriers to entry for unqualified vendors.
- Sensor Systems:Distributed fiber optic sensing for structural health monitoring and engine condition diagnostics.
- Navigation Systems:Inertial measurement unit links and GPS augmentation networks demanding phase-stable transmission.
Defense procurement concentrates spend in Communication Systems; commercial platform integration drives Avionics volume.
End User:
Customer type fragmentation splits demand between long-cycle military programs with sole-source agreements and price-sensitive commercial fleet operators.
- Military Aviation:Tactical aircraft and unmanned platforms requiring secure, jam-resistant data transmission. The Pentagon's Defense Logistics Agency negotiates multi-year indefinite-delivery contracts that displace transactional purchasing, with 60% of optical interconnect value in F-35 and B-21 programs now under sole-source coverage.
- Commercial Aviation:Airline operators and lessors prioritizing weight reduction for fuel efficiency compliance. EU Green Deal carbon intensity targets accelerate fiber substitution for copper harnesses in Airbus A320neo and Boeing 737 MAX retrofit programs.
- Space Exploration:Satellite manufacturers and launch vehicle operators specifying radiation-hardened components.
- Aerospace Manufacturers:Tier-1 integrators and subsystem suppliers managing platform-level optical architecture design.
Procurement concentration favors Military Aviation; fleet expansion favors Commercial Aviation.
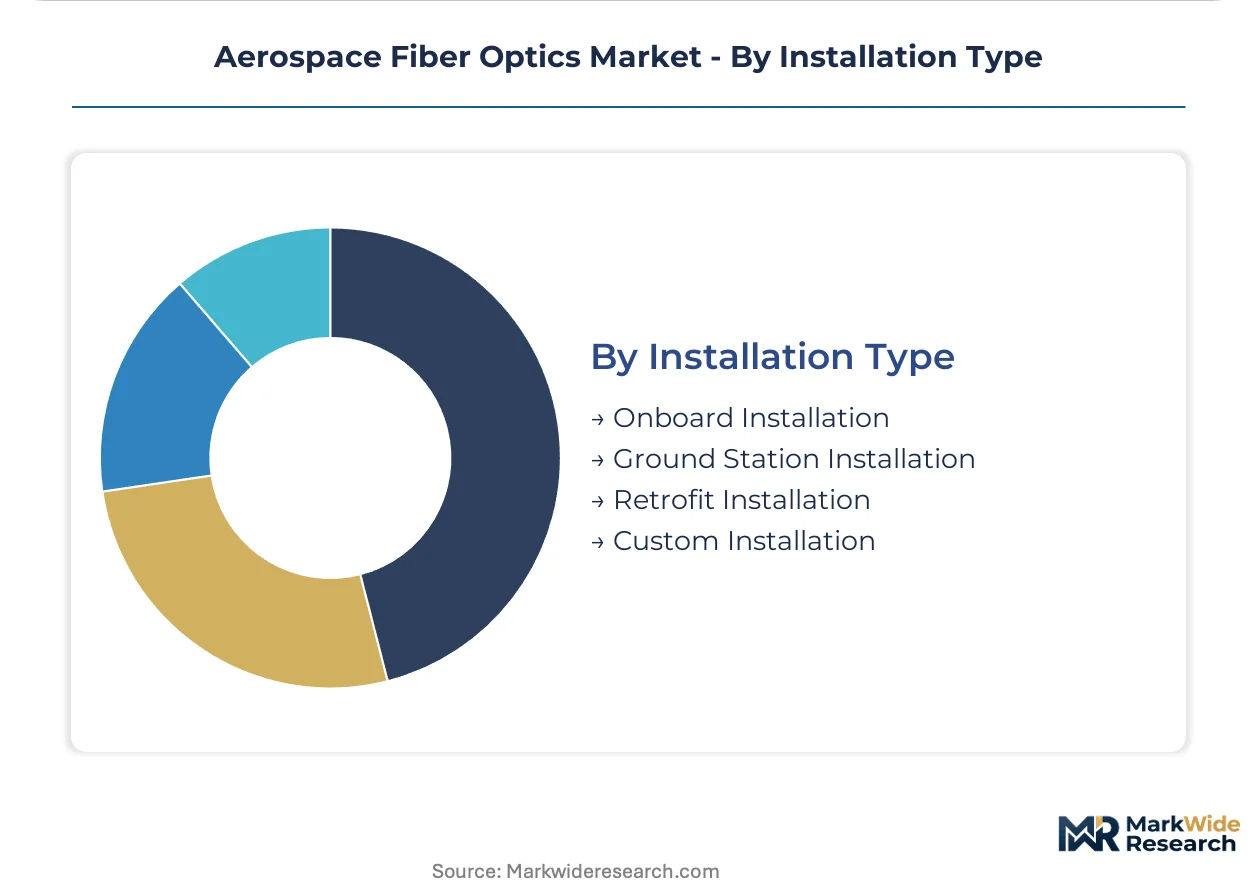
Installation Type:
Supply concentration in precision termination services creates margin differentiation between factory-integrated harnesses and field retrofit work.
- Onboard Installation:Factory-integrated optical harnesses installed during airframe assembly, leveraging controlled cleanroom environments for precision cleaving and polishing. Airbus Defence and Space operations in Germany and Raytheon production facilities in the United States anchor demand, with sub-micron accuracy requirements limiting qualified supplier pools.
- Retrofit Installation:Copper-to-fiber conversion in legacy platforms, constrained by downtime economics and certification backlog. FAA airworthiness directive qualification timelines extend 18-36 months for new cable assemblies, compressing near-term penetration in existing fleets.
- Ground Station Installation:Fixed infrastructure for satellite communication and telemetry networks.
- Custom Installation:Application-specific harness designs for research aircraft and experimental platforms.
Platform procurement cycles favor Onboard Installation; modernization budgets constrain Retrofit Installation expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fiber optic cable assemblies flow into Airbus final assembly lines in Toulouse and Hamburg, while United States manufacturers supply terminated harnesses to Boeing's Everett and Charleston facilities. Japanese specialty fiber producers export radiation-hardened product to European Space Agency programs in French Guiana. This trade architecture concentrates procurement leverage with platform integrators.
United States
The Pentagon's Defense Logistics Agency negotiates multi-year indefinite-delivery contracts for F-35 and B-21 optical interconnects. FAA airworthiness directive timelines extend 18-36 months for new cable assemblies, compressing supplier cash conversion cycles. Raytheon production facilities in Arizona and Northrop Grumman operations in California anchor military procurement concentration.
Germany
Bundeswehr modernization programs drive substantial installation volumes through Airbus Defence and Space operations. EU Green Deal emissions targets pressure Lufthansa and other operators toward weight-reducing fiber retrofits. Munich and Hamburg clusters concentrate precision termination services for sub-micron accuracy requirements.
France
Dassault Aviation integrates fly-by-light architectures into Rafale and Falcon platforms, sourcing from domestic cable assembly specialists. EASA CS-25 certification standards govern qualification pathways for European platform integration. Toulouse aerospace cluster hosts Thales Avionics and Safran Electronics operations for optical subsystem design.
United Kingdom
BAE Systems qualifies fiber optic harnesses for Typhoon and Tempest programs under Ministry of Defence procurement frameworks. REACH substance restrictions force reformulation of buffer coatings ahead of 2027-2028 compliance windows. Bristol and Lancashire industrial bases concentrate avionics integration expertise.
Japan
Mitsubishi Heavy Industries specifies optical interconnects for F-X fighter development and space launch vehicles. METI industrial policy supports domestic photonics-electronics convergence for radar processing applications. Nagoya aerospace corridor anchors Mitsubishi Electric and Fujikura cable assembly operations.
Aerospace Fiber Optics Market Vendor Landscape
Channel-controlling players compete with product-specialist players across termination, materials, and subsystem tiers. The vendor base consolidates around three archetypes: full-line interconnect houses, specialty cable fabricators, and upstream materials suppliers. Dominant competitive moves include sole-source agreement concentration with defense agencies and REACH-compliant coating reformulation ahead of regulatory deadlines.
Among United States-based interconnect specialists, Amphenol Corporation and Collins Aerospace occupy positions within the channel-controlling tier, while Corning Incorporated anchors the upstream materials position. These three exemplify how geographic proximity to Pentagon procurement centers and platform integrator facilities shapes competitive positioning in defense-aerospace fiber optics.
| Leading Market Players |
|---|
| Amphenol Corporation |
| Prysmian Group |
| Collins Aerospace |
| Corning Incorporated |
| TE Connectivity |
| Nexans |
| W. L. Gore & Associates |
| Radiall |
| Carlisle Interconnect Technologies |
| Others |
Supply Flow & Price Mechanics
Munich's precision termination cluster concentrates sub-micron polishing capacity for aerospace-grade fiber assemblies, translating geographic supply scarcity into pricing leverage for qualified vendors serving Airbus Defence and Space operations. This regional capacity bottleneck amplifies cost premiums for radiation-hardened specialty fiber while compressing margins in commoditized multi-mode avionics backbones.
Pricing Analysis
Current-generation multi-mode fiber assemblies command substantial discounts against prior-generation copper harness retrofits and next-generation photonic integrated circuit packages. Three-tier pricing structure across flight-critical certification, standard avionics, and cabin entertainment tiers reflects FAA airworthiness directive qualification burdens. Pricing pressure stems from REACH-compliant coating reformulation costs passing through to European platform integrators. Commercial airline procurement teams exhibit acute price sensitivity compared to Pentagon sole-source agreements covering F-35 and B-21 programs.
Supply Chain Analysis
Contract manufacturing concentrates at Carlisle Interconnect Technologies facilities in the United States, Radiall operations in France, and Fujikura cable assembly plants in Japan. High-purity silica precursor supply draws from limited chemical suppliers in the United States and Germany, creating input cost volatility for fiber draw operations. Single-source vulnerability in specialty polyimide coatings for radiation-hardened variants threatens satellite program schedules. Distribution runs through tier-1 aerospace integrators with direct platform qualification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aerospace fiber optics is recovering from defense procurement cyclicality as NATO-aligned modernization programs accelerate fly-by-light platform integration. Pentagon multi-year indefinite-delivery contracts and Bundeswehr tactical network upgrades provide the cyclical foundation.
For Market Incumbents: Build certification moats through accelerated MIL-STD-883 qualification for photonic integrated circuit packages before EASA-FAA harmonization closes windows. Incumbent suppliers must secure sole-source agreements for next-generation F-35 and B-21 production blocks while defending against silicon photonics entrants through backward integration into specialty silica precursor supply. Capacity expansion in Munich and Hamburg precision termination clusters reinforces geographic scarcity advantages. For New Entrants and Emerging Players: Urban air mobility platforms in Germany and the United States represent underpenetrated white-space requiring lightweight optical interconnects for autonomous flight systems. New entrants should target eVTOL avionics bus specifications before established vendors lock sole-source positions, leveraging photonics-electronics convergence partnerships with radar processing specialists as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision termination specialists with established FAA-EASA dual qualification. Long-term viability hinges on photonic integrated circuit adoption in active electronically scanned array upgrades. Acquisition targets should display sub-micron polishing capability and existing sole-source coverage in defense programs. Quarterly review of Pentagon Defense Logistics Agency contract awards and ECHA REACH sunset date compliance progress is advised to detect inflection.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Coating Reformulation | ECHA candidate list substances force buffer material validation ahead of 2027-2028 compliance windows. |
| Photonic Integrated Circuit Qualification | Raytheon and Northrop Grumman beamforming programs digitize radar processing chains for contested environments. |
| Precision Termination Capacity Expansion | Munich and Hamburg clusters address acute talent scarcity in sub-micron cleaving and polishing specialization. |
| Sole-Source Agreement Consolidation | Pentagon Defense Logistics Agency multi-year contracts now cover 60% of F-35 and B-21 optical interconnect value. |
| Silicon Photonics Convergence Partnership | Co-packaged optical engines reduce form factors in constrained avionics bays for next-generation platforms. |
Methodological Framework
Initial hypotheses were tested against primary input from avionics integration engineers, defense procurement officers at NATO-aligned ministries, precision termination technicians, and tier-1 aerospace supplier program managers and refined through secondary validation against FAA airworthiness directive filings, EASA CS-25 certification databases, Pentagon Defense Logistics Agency contract awards, and MIL-STD-883 test protocol documentation. Bottom-up platform installation forecasts and top-down defense budget allocation analysis provided triangulation across the analysis window.
Demand-supply-balance modeling incorporated multi-mode fiber, specialty fiber, single-mode fiber, and cable assembly segmentation alongside application dimensions spanning communication systems, avionics, sensor systems, and navigation networks. CAGRs were derived from platform procurement cycle analysis and retrofit penetration elasticity. Forecast inputs included Bundeswehr modernization program schedules, EU Green Deal emissions compliance timelines, and urban air mobility platform development milestones.
Practitioners should monitor Pentagon sole-source contract concentration, ECHA REACH substance restriction enforcement, and photonic integrated circuit qualification timelines for early signals of forecast revision. Quarterly review of defense procurement acceleration indicators and commercial aviation retrofit program announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Commercial Aerospace 3D Printing Market
Aerospace and Aircraft Materials
Aerospace Fasteners Market
Aerospace and Aircraft Materials
Global High Strength Aluminum Alloys Market
Aerospace and Aircraft Materials
Aerographene Market
Aerospace and Aircraft Materials
Electromagnetic and Radio Frequency Interference Coating Market
Aerospace and Aircraft Materials
Aerogel Blanket Market
Aerospace and Aircraft Materials
Global Military Aerospace Coatings Market
Aerospace and Aircraft Materials
Europe Advanced Aerospace Coatings Market
Aerospace and Aircraft Materials
Aerospace Carbon Fiber Market
Aerospace and Aircraft Materials
Additive Manufactured Pressure Vessel Proof and Burst Test Rigs Market
Aerospace and Aircraft Materials
Aeroengine Composites Market
Aerospace and Aircraft Materials
Aerospace Sealants Market
Aerospace and Aircraft Materials
Aerospace Fluoropolymers Market
Aerospace and Aircraft Materials
Global Flame Retardant for Aerospace Plastics Market
Aerospace and Aircraft Materials
Aerospace Plastics Market
Aerospace and Aircraft Materials
Honeycomb Panel for Aircraft Market