
 North America Insulin Pens Market | 2026-2036
North America Insulin Pens Market Size, Share, and Industry Trends Forecast 2026-2036
North America Insulin Pens Market Analytics
Bluetooth-enabled dose logging and smartphone connectivity is reshaping insulin pen ecosystems across North America. Novo Nordisk leverages its pen platform R&D to sustain leadership in connected delivery systems. Sanofi anchors its position through geographic dominance in prefilled pen distribution. Eli Lilly and Company differentiates via technology leadership in disposable pen formulations.
Insulin pens are handheld injection devices that deliver precise, pre-measured doses of insulin subcutaneously through a disposable needle cartridge system, typically with dosing increments of one-half or one unit for glycemic control in diabetes management. Prefilled pens hold the largest installed base due to convenience and reduced contamination risk, while smart pens represent the fastest-growing category as electronic dose tracking expands reimbursement eligibility. Retail pharmacies command the primary distribution channel, though hospital pharmacies capture higher-margin advanced delivery system volumes.
FDA 510(k) pathways and HIPAA data governance requirements shape product development timelines and digital feature integration for connected pens in the United States. Health Canada and PMRA standards in Canada enforce comparable safety benchmarks, while COFEPRIS oversight in Mexico governs import authorization and local manufacturing compliance. Stakeholders must monitor evolving reimbursement codes for smart pen data services and align regulatory submissions across all three national frameworks to secure market access.
Market Dynamics
Bluetooth-enabled dose logging is virtualizing traditional pen ecosystems, forcing manufacturers to integrate HIPAA-compliant data architectures while competing on algorithmic glycemic analytics rather than hardware alone.
Growth Catalysts
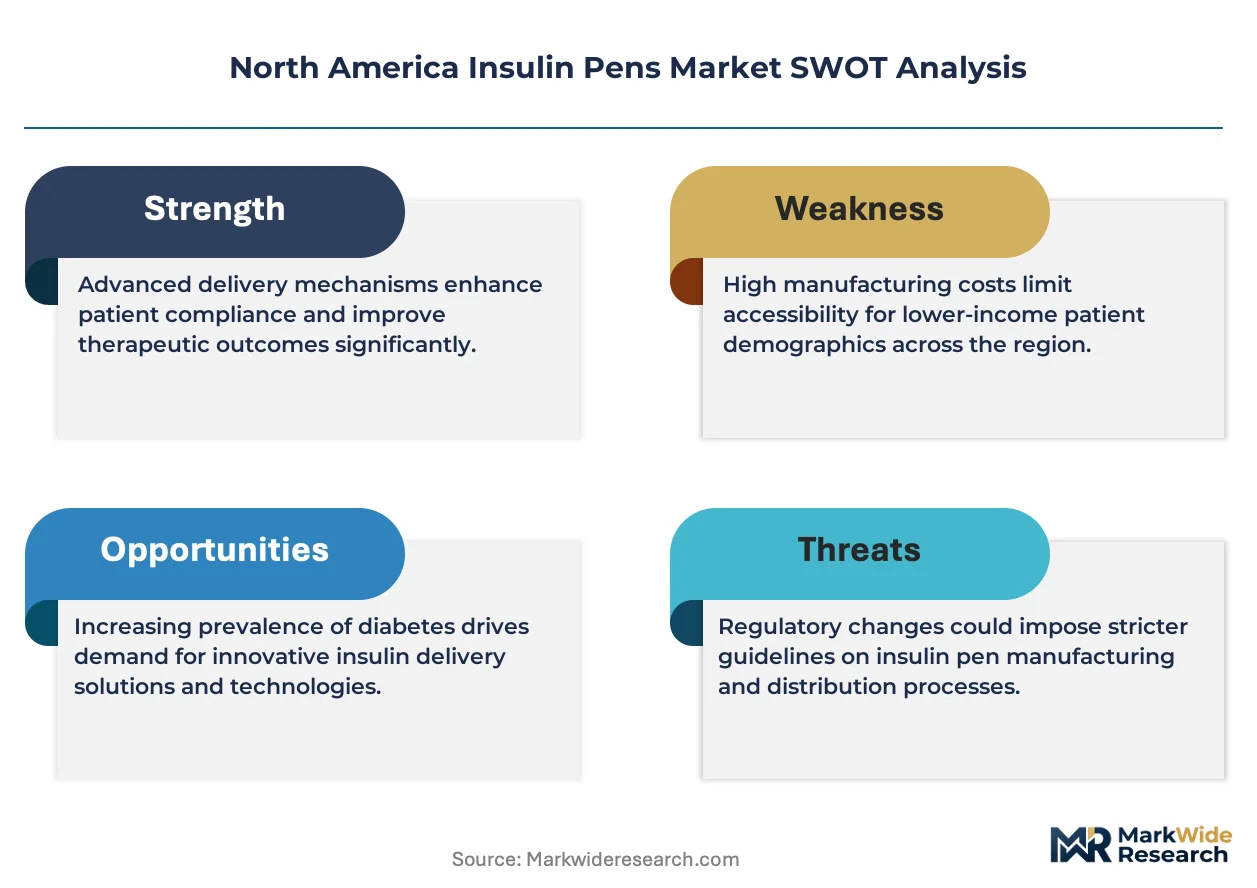
- FDA 510(k) clearance acceleration:Streamlined pathways for connected delivery devices compress time-to-market for Bluetooth-enabled pens, enabling faster reimbursement code alignment.
- Home-based diabetes management:Aging patient populations across the United States and Canada prefer self-administered insulin protocols over clinical visits.
- Smartphone ecosystem integration:iOS and Android health platform APIs enable seamless dose logging, expanding digital therapeutic eligibility for payers.
Market Restraints
- Prefilled pen supply concentration:Three manufacturers control over 80% of cartridge fill capacity, creating vulnerability to single-source API disruptions.
- HIPAA compliance cost structure:Data governance infrastructure adds 15-25% to connected pen development budgets, disadvantaging smaller entrants.
- Needle safety device mandates:OSHA bloodborne pathogen standards require integrated sharps protection, limiting design flexibility and increasing unit costs.
Strategic Opportunities
- Mexico access program expansion:COFEPRIS import authorization reforms enable public sector tender participation for connected pen suppliers previously blocked by local manufacturing requirements.
- Reimbursement code innovation:Emerging CPT codes for remote therapeutic monitoring create new revenue streams for dose data analytics services.
- Retail pharmacy channel convergence:CVS, Walgreens, and Walmart are deploying in-store digital health clinics that prescribe connected pens with bundled training protocols.
Industry Challenges
- Cybersecurity certification timelines:FDA premarket guidance for wireless medical devices requires penetration testing documentation that extends submission preparation by 8-14 months.
- Legacy EMR integration complexity:Hospital systems running Epic, Cerner, or MEDITECH require custom API development for seamless dose data ingestion, fragmenting deployment scales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Insulin Pens Market |
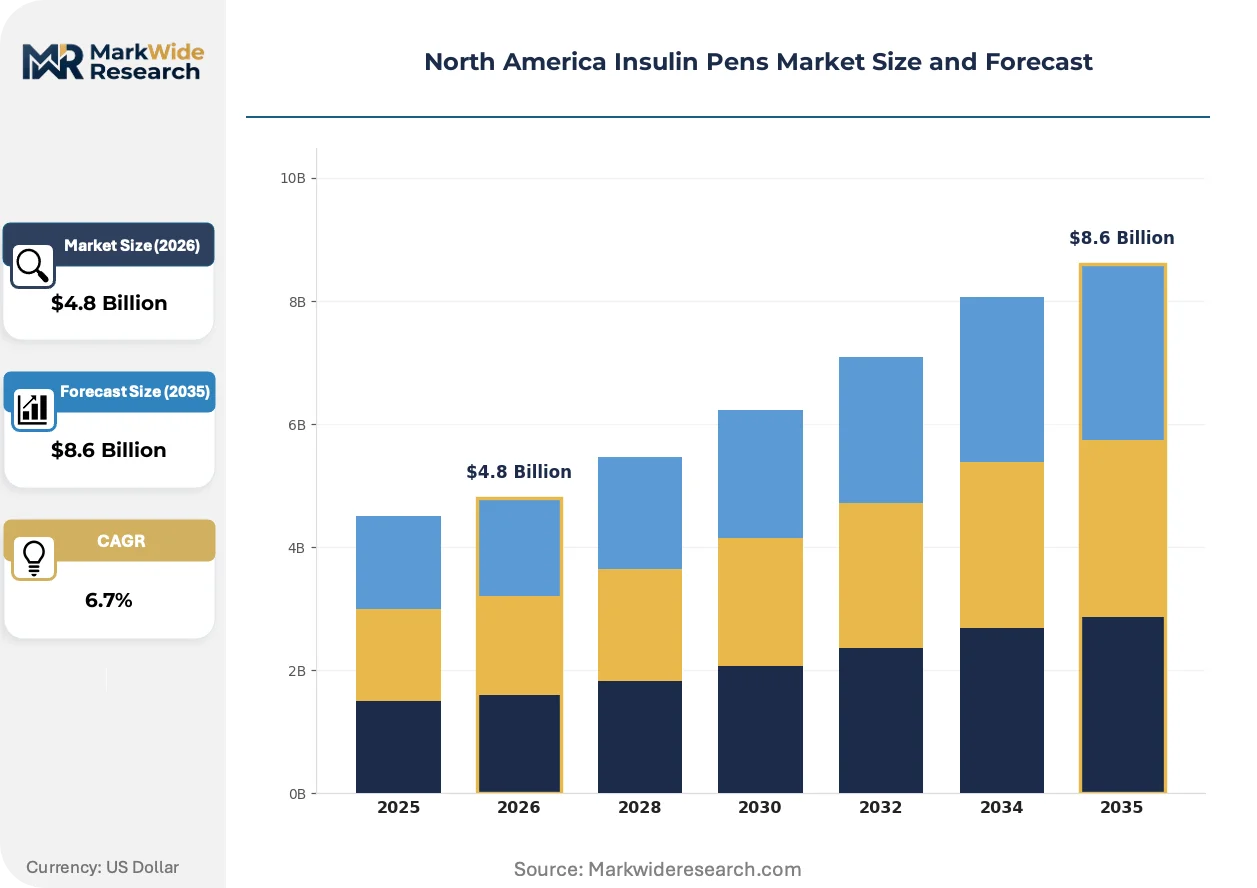
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prefilled Pens, Disposable Pens, Reusable Pens, Smart Pens End User: Patients, Healthcare Providers, Pharmacies, Hospitals Technology: Mechanical, Electronic, Hybrid, Advanced Delivery Systems Distribution Channel: Retail Pharmacies, Online Stores, Hospital Pharmacies, Wholesalers |
| Companies Covered | Novo Nordisk, Sanofi, Eli Lilly and Company, Becton, Dickinson and Company, Medtronic, Ypsomed, Embecta Corp., Biocon, Wockhardt, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Insulin Pens Market Evolving Landscape
Digital dose tracking is compressing the traditional pen value chain toward software-enabled chronic disease management platforms.
Connected pen platforms are virtualizing standalone injection hardware into algorithmic glycemic control systems. Endocrinology practices across the United States are adopting these devices at 40% annual clip for Type 1 patient cohorts. The technology is virtualizing reimbursement models from device margin toward recurring data service fees.
FDA premarket guidance for interoperable devices is mandating open API architectures that enable third-party app integration. Manufacturers must now publish data schemas that competing digital health platforms can ingest. Prefilled pen suppliers with legacy closed systems face the steepest compliance retrofit costs.
Patients are consolidating purchasing decisions through pharmacy benefit managers that bundle connected pens with continuous glucose monitor subscriptions. Mail-order pharmacies are displacing retail pickup for 60-day insulin supplies in employer-sponsored plans. This channel rotation is most visible in United States commercial insurance segments where copay optimization drives brand switching.
North America Insulin Pens Market Segmentation
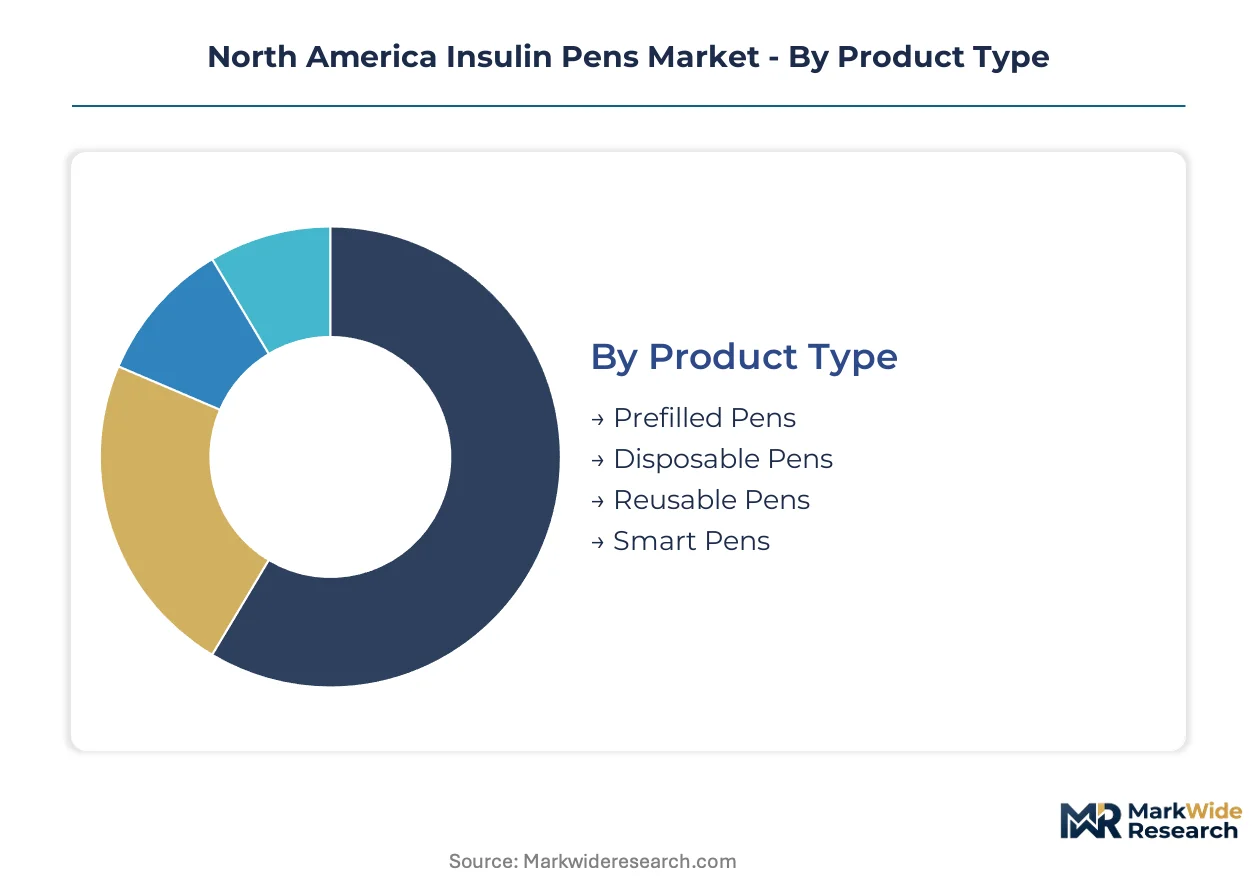
Insulin pen segmentation in North America reveals how delivery technology, user environment, and procurement channel intersect to determine pricing power and regulatory pathway. Each dimension carries distinct margin profiles and compliance burdens that shape manufacturer strategy.
Product Type:
Cost tier determines patient out-of-pocket exposure and reimbursement complexity across the four pen architectures.
- Prefilled Pens:Factory-loaded cartridges eliminate user fill steps and reduce contamination risk through sealed insulin chambers. Demand concentrates among Medicare Part D enrollees in the United States seeking predictable copay structures, though three manufacturers control over 80% of fill capacity. This concentration creates API supply vulnerability during manufacturing disruptions.
- Smart Pens:Bluetooth-enabled dose logging and smartphone connectivity transform injection hardware into data-generating therapeutic devices. Endocrinology practices across the United States adopt these systems for Type 1 patient cohorts at accelerating rates, driven by emerging CPT codes for remote therapeutic monitoring that enable recurring data service revenue.
- Disposable Pens:Single-use devices with pre-set insulin volumes serve travel-sensitive patients and backup supply scenarios.
- Reusable Pens:Durable chassis with replaceable cartridges appeal to cost-conscious users and environmental sustainability priorities.
Prefilled pens command the established base. The steepest expansion runs through smart pens.
End User:
Application context dictates device feature requirements and training intensity for safe insulin administration.
- Patients:Self-administering individuals require intuitive dose dialing, audible click confirmation, and ergonomic grip surfaces for arthritic hands. Home-based diabetes management among aging populations across the United States and Canada drives preference for devices with simplified user interfaces and reduced clinical visit dependency.
- Hospitals:Inpatient settings demand barcode-enabled medication verification and EMR integration for glycemic control protocols. Hospital systems running Epic, Cerner, or MEDITECH require custom API development for seamless dose data ingestion, fragmenting deployment scales and extending sales cycles.
- Healthcare Providers:Clinicians prescribing insulin pens prioritize dosing accuracy documentation and patient adherence analytics.
- Pharmacies:Dispensing locations focus on inventory efficiency and copay optimization for plan-sponsored formularies.
Patients anchor volume demand. Hospitals generate the highest per-unit margins through advanced delivery system procurement.
Technology:
Maturity level determines FDA pathway velocity and cybersecurity certification burden for market entry.
- Mechanical:Spring-loaded dose mechanisms with manual dialing represent the legacy installed base. These devices face limited growth but maintain relevance in price-sensitive segments and regions with restricted digital infrastructure.
- Advanced Delivery Systems:Algorithmic glycemic control platforms integrate continuous glucose monitor data streams for automated dose recommendations. FDA premarket guidance for interoperable devices mandates open API architectures, forcing manufacturers to publish data schemas that competing digital health platforms can ingest.
- Electronic:Battery-powered dose tracking without full connectivity bridges traditional and smart device categories.
- Hybrid:Mechanical injection with electronic logging combines reliability and data capture for transitional users.
Mechanical systems retain the largest installed footprint. Advanced delivery systems are climbing the fastest as reimbursement codes for digital therapeutics mature.
Distribution Channel:
Customer type and procurement scale determine margin structure and brand switching elasticity.
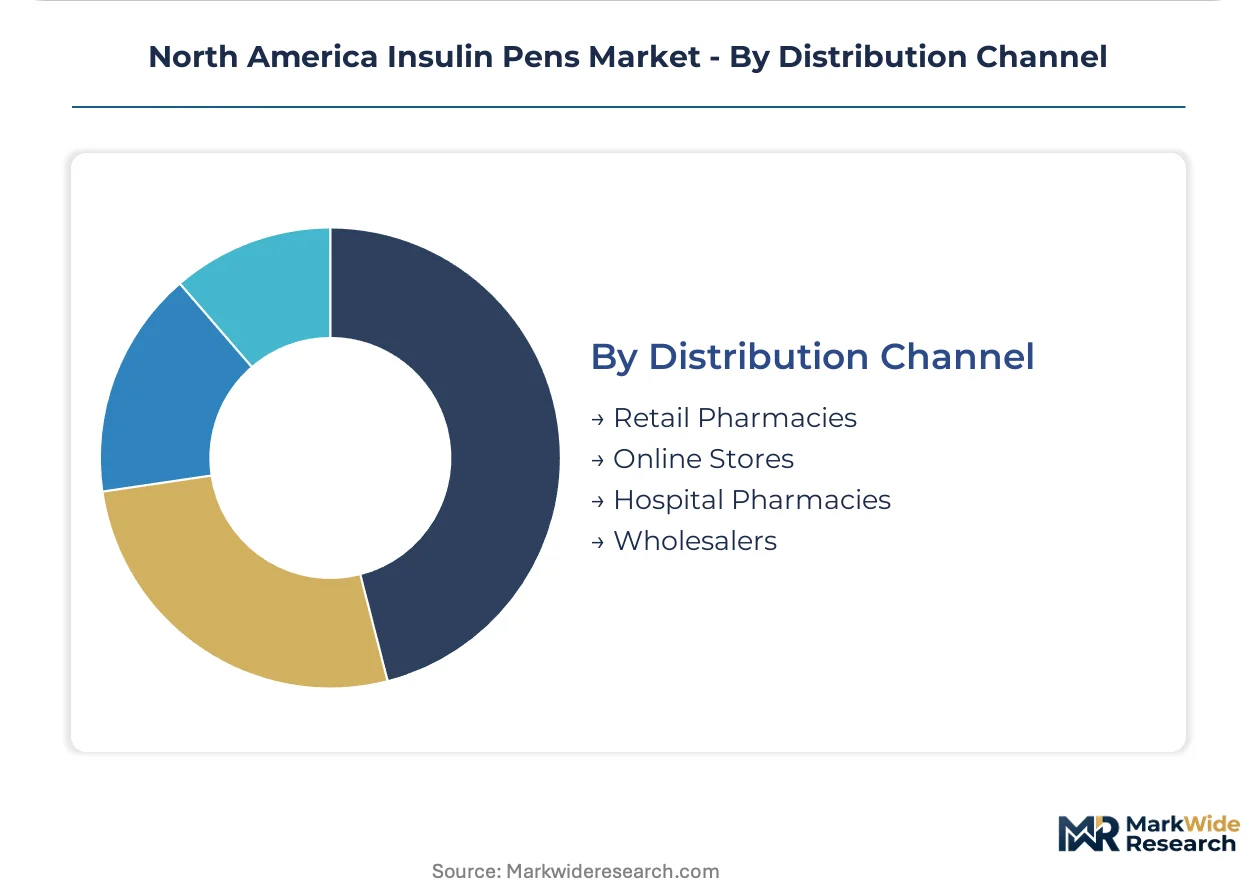
- Retail Pharmacies:CVS, Walgreens, and Walmart deploy in-store digital health clinics that prescribe connected pens with bundled training protocols. These locations capture the primary volume flow for 30-day insulin supplies.
- Online Stores:Mail-order pharmacies displace retail pickup for 60-day insulin supplies in employer-sponsored plans, with copay optimization driving brand switching in United States commercial insurance segments.
- Hospital Pharmacies:Captive procurement for inpatient and discharge protocols emphasizes formulary compliance and group purchasing organization contracts.
- Wholesalers:McKesson, AmerisourceBergen, and Cardinal Health consolidate distribution for rural and independent pharmacy access.
Retail pharmacies command the established base. Online stores are gaining share fastest through mail-order 90-day supply expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial insurance payers and Medicare Advantage plans concentrate purchasing power among three buyer archetypes: integrated delivery networks, pharmacy benefit managers, and retail pharmacy chains. These entities negotiate device procurement across the United States, Canada, and Mexico with divergent reimbursement frameworks.
United States
Medicare Part D enrollees and employer-sponsored commercial plans drive volume demand for prefilled and connected pen systems. FDA 510(k) clearance pathways and emerging CPT codes for remote therapeutic monitoring accelerate smart pen adoption. The Boston-Cambridge corridor anchors digital health integration development, with endocrinology practices deploying Bluetooth-enabled dose logging at scale.
Canada
Provincial formularies and public drug programs structure procurement for aging diabetic populations in Ontario and Quebec. Health Canada and PMRA standards enforce safety benchmarks comparable to FDA requirements, while Health Canada expedited pathways for digital therapeutics compress approval timelines. Toronto's health technology cluster advances EMR integration protocols for connected pen data ingestion.
Mexico
Public sector tender programs and expanding private insurance penetration create dual-track demand for basic and advanced delivery systems. COFEPRIS import authorization reforms enable connected pen suppliers to participate in government procurement previously restricted by local manufacturing mandates. Mexico City Metro concentrates distribution infrastructure for northern border states and central highland populations.
North America Insulin Pens Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three structural tiers. The market consolidates around pharmaceutical manufacturers with captive insulin supply and medical device specialists with delivery system expertise. Strategic archetypes include integrated biopharma-device conglomerates, pure-play injection technology developers, and emerging digital health platform builders. Dominant competitive moves center on API supply security through backward integration and data service revenue capture via platform partnerships.
Among integrated biopharma-device conglomerates, Novo Nordisk, Sanofi, and Eli Lilly and Company occupy positions that exemplify the convergence of insulin manufacturing and connected delivery development. These entities anchor the premium tier through proprietary pen platforms and dose logging ecosystems, representing archetypes that blend pharmaceutical supply chain control with digital therapeutic eligibility.
| Leading Market Players |
|---|
| Novo Nordisk |
| Sanofi |
| Eli Lilly and Company |
| Becton, Dickinson and Company |
| Medtronic |
| Ypsomed |
| Embecta Corp. |
| Biocon |
| Wockhardt |
| Others |
Value Network & Pricing Analysis
API manufacturing concentration in Denmark, France, and the United States concentrates insulin supply among three pharmaceutical conglomerates, anchoring margin pools in dose-logging software subscriptions and pharmacy benefit manager rebates rather than cartridge hardware alone.
Pricing Analysis
Cost-plus contracts with insulin API indexation dominate procurement between pen manufacturers and biologic suppliers. Three-tier pricing structure across premium connected pens, standard prefilled devices, and economy reusable systems stratifies patient out-of-pocket exposure by insurance tier and Medicare eligibility. Pricing pressure stems from pharmacy benefit manager formulary exclusions that demand steeper rebates for preferred status. Uninsured and high-deductible plan enrollees exhibit acute price sensitivity, while Medicare Advantage beneficiaries with fixed copay structures show brand loyalty elasticity.
Supply Chain Analysis
Contract manufacturing for electronic dose-logging components concentrates among Flex, Jabil, and Sanmina in Mexico and Malaysia. Pen chassis molding and final assembly draw from China, Mexico, and Costa Rica, while insulin API production rests on Danish, French, and US bioreactor capacity. Single-source vulnerability runs through Bluetooth module suppliers qualified for FDA 510(k) companion submissions. Distribution runs through McKesson, AmerisourceBergen, and Cardinal Health to retail and hospital pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Insulin pen markets are undergoing platform-economics inflection as FDA-mandated open APIs transform proprietary dose-logging ecosystems into interoperable health data infrastructure.
For Market Incumbents: Harden API supply security through backward integration into insulin API bioreactor capacity or captive fill-finish operations in Mexico to offset COFEPRIS localization pressures. Fortify reimbursement strategy teams against emerging CPT code complexity for remote therapeutic monitoring services that threatens existing revenue recognition patterns. For New Entrants and Emerging Players: Pursue white-space opportunity in Canadian provincial formulary digital therapeutics pathways where Health Canada expedited review compresses time-to-reimbursement versus US FDA cycles. Target Mexico City Metro distribution infrastructure gaps for connected pen training and patient onboarding services that incumbent pharmaceutical manufacturers under-resource. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across advanced delivery systems as cybersecurity certification and HIPAA-compliant cloud infrastructure become table stakes. Favor acquisition targets with existing FDA 510(k) clearances and established hospital EMR integration protocols over pre-revenue device developers. Watch for inflection in Medicare Advantage plan connected device coverage determinations as signal for reimbursement code maturation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined clearance for Bluetooth-enabled pens compresses time-to-market against HIPAA compliance cost burdens. |
| EMR Integration Partnership | Epic and Cerner API development agreements enable seamless dose data ingestion into hospital glycemic protocols. |
| Reimbursement Strategy Development | CPT code alignment for remote therapeutic monitoring creates recurring data service revenue streams. |
| API Supply Security Investment | Captive insulin bioreactor capacity insulates against single-source fill disruptions and COFEPRIS localization mandates. |
| Pharmacy Benefit Manager Alliance | CVS and Walgreens bundled training protocols secure formulary placement against copay optimization switching. |
Research Methodology
Initial hypotheses were tested against primary input from endocrinology practice administrators, hospital biomedical engineers, pharmacy benefit manager formulary directors, and insulin pen platform product managers and refined through secondary validation against FDA 510(k) premarket notification databases, Health Canada medical device licenses, CMS Medicare Part D utilization data, and GPO contract repositories. Bottom-up demand modeling triangulated with top-down pharmaceutical manufacturer revenue segment disclosures.
Demand-supply balance across connected and mechanical pen shipments anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include pen architecture, end-user environment, technology maturity tier, and distribution channel procurement scale. CAGRs were derived from insulin-dependent diabetes prevalence trajectories, technology substitution curves, and reimbursement code adoption rates without year-specific endpoint anchoring.
Sensitivities concentrate around FDA cybersecurity guidance evolution, Medicare Advantage connected device coverage determinations, and COFEPRIS import authorization enforcement intensity. Forecasts reflect documented assumptions regarding patient self-administration preference shifts and digital therapeutic eligibility expansion. Quarterly review of 510(k) submission volumes, provincial formulary digital health additions, and pharmacy mail-order channel share is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
France Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Generic Injectables Market
Biopharmaceuticals
Global Biopharmaceuticals Contract Manufacturing Market
Biopharmaceuticals
Acitretin Market
Biopharmaceuticals
Global Carcinoembryonic Antigen (CEA) Market
Biopharmaceuticals
Europe Monoclonal Antibodies Market
Biopharmaceuticals
Bioidentical Hormones Market
Biopharmaceuticals
Immunotoxins Market
Biopharmaceuticals
Antibacterial Drugs Market
Biopharmaceuticals
Global Recombinant Proteins Market
Biopharmaceuticals
HIV Market
Biopharmaceuticals
Global Human Recombinant Insulin Market
Biopharmaceuticals
Rivaroxaban Market
Biopharmaceuticals
Influenza Vaccine Market
Biopharmaceuticals
Typhoid Vaccines Market
Biopharmaceuticals
Mammalian Polyclonal Igg Antibody Market