
 Global Interferons Market | 2026-2036
Global Interferons Market Size, Share, and Industry Trends Forecast 2026-2036
Global Interferons Market Foresight
Chinese biologics manufacturing is decoupling from traditional Western supply dependencies as domestic fermentation capacity scales for cytokine production. Roche Holding AG leverages its long-standing recombinant protein expertise to sustain leadership in interferon beta formulations. Merck & Co., Inc. anchors its position through integrated fill-finish operations across North American and European sites. Biogen Inc. differentiates via concentrated investment in pegylated interferon delivery technologies.
Interferons comprise a family of glycoprotein cytokines classified by alpha, beta, gamma, and omega subtypes, produced via recombinant DNA technology in bacterial or mammalian expression systems to modulate antiviral, antiproliferative, and immunomodulatory cellular responses. These biologics function therapeutically by binding specific cell-surface receptors to activate JAK-STAT signaling cascades, primarily serving oncology, neurology, and infectious disease protocols. Interferon beta retains the dominant revenue position within product type segmentation due to entrenched multiple sclerosis prescribing patterns, while interferon gamma represents the fastest-expanding category driven by orphan disease designations and niche immunotherapy applications. Subcutaneous delivery mode commands the largest volume share as patient self-administration protocols reduce hospital burden, though intravenous formulations capture premium pricing in acute oncology settings.
The FDA maintains stringent potency and purity standards for interferon lot release through its Center for Drug Evaluation and Research, while the EMA's biosimilar framework under the MDR creates parallel compliance obligations for European market entry. Japan's PMDA imposes additional stability testing requirements that extend development timelines for foreign applicants. WHO prequalification pathways increasingly influence procurement decisions across emerging national immunization programs. Stakeholders must monitor evolving pharmacovigilance mandates and biosimilar interchangeability rulings to anticipate pricing compression and portfolio repositioning requirements.
Market Dynamics
FDA biosimilar interchangeability rulings are compressing originator pricing power while accelerating hospital formulary switches toward lower-cost alternatives across neurology and oncology protocols.
Growth Catalysts
- EMA Biosimilar Framework:The MDR's streamlined approval pathways reduce European entry barriers for recombinant cytokine manufacturers, expanding patient access to interferon beta therapies.
- Multiple Sclerosis Protocols:Expanded first-line prescribing of interferon beta-1a and beta-1b in specialty neurology clinics sustains volume demand across Germany, Japan, and the United States.
- Orphan Disease Designations:Interferon gamma gains traction in chronic granulomatous disease and osteopetrosis treatment, unlocking priority review vouchers and pediatric exclusivity incentives.
Market Restraints
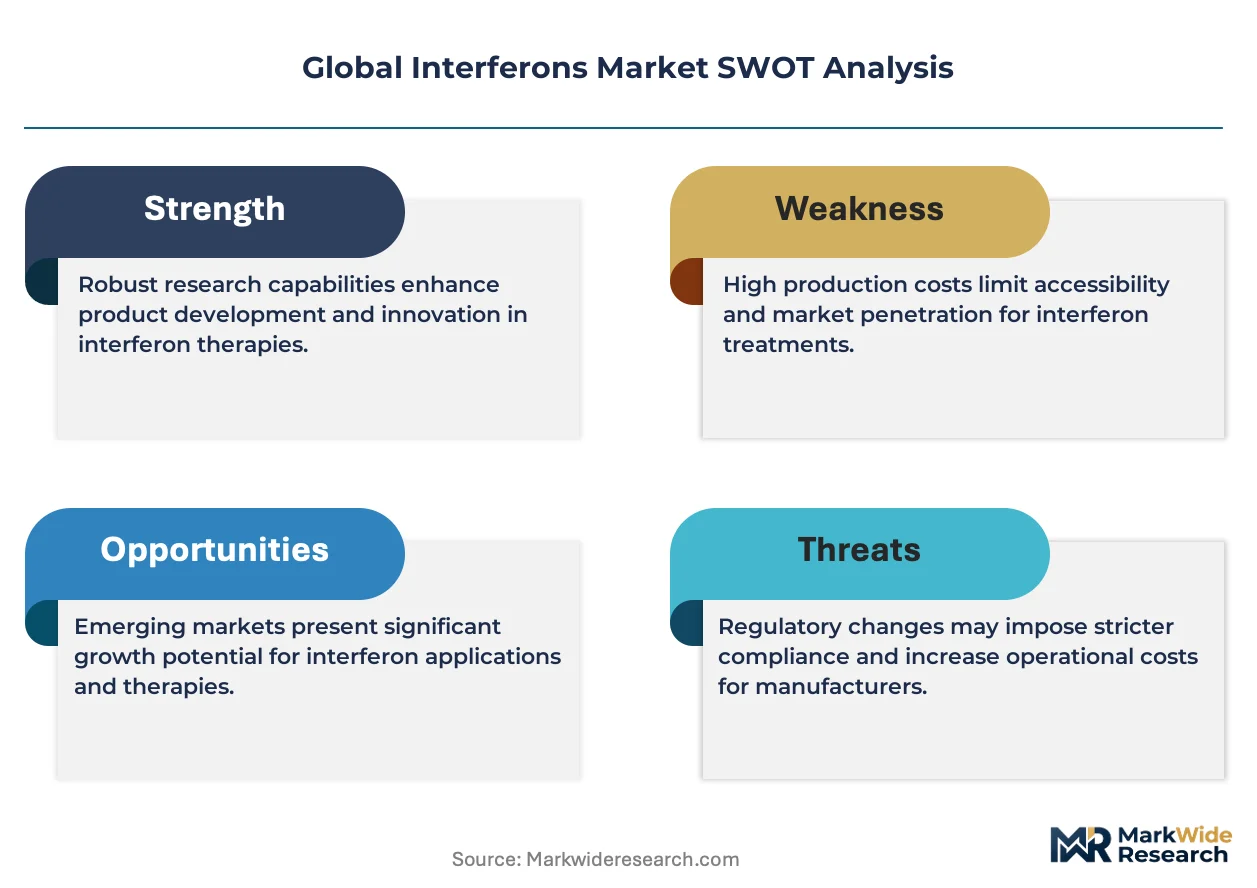
- Mammalian Cell Culture Costs:Serum-dependent CHO expression systems for glycosylated interferons expose manufacturers to fetal bovine serum price volatility and supply interruptions.
- Chinese Fermentation Concentration:Domestic cytokine production capacity expansion creates Western supply dependency risks as bioreactor infrastructure consolidates in Shanghai and Suzhou hubs.
- PEGylation Patent Cliffs:Expiring intellectual property around polyethylene glycol conjugation chemistry erodes formulation differentiation advantages for legacy pegylated interferon products.
Strategic Opportunities
- Indian CDMO Partnerships:Contract development and manufacturing organizations in Hyderabad and Bengaluru offer cost-competitive bacterial expression capacity for non-glycosylated interferon alpha production.
- Subcutaneous Auto-Injector Convergence:Integration of prefilled syringes with wearable electronic adherence monitors creates differentiated value propositions in home-based multiple sclerosis management.
- WHO Prequalification Pathways:Emerging national immunization programs in Southeast Asia and sub-Saharan Africa are adopting WHO-prequalified interferon products for hepatitis C elimination campaigns.
Industry Challenges
- Biologics Master File Navigation:Cross-referencing proprietary cell line and process data across FDA, EMA, and PMDA submissions creates documentation bottlenecks and approval timeline extensions.
- Cold Chain Integrity:Temperature excursion risks during interferon distribution require validated thermal packaging and real-time monitoring infrastructure that elevates logistics costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Interferons Market |
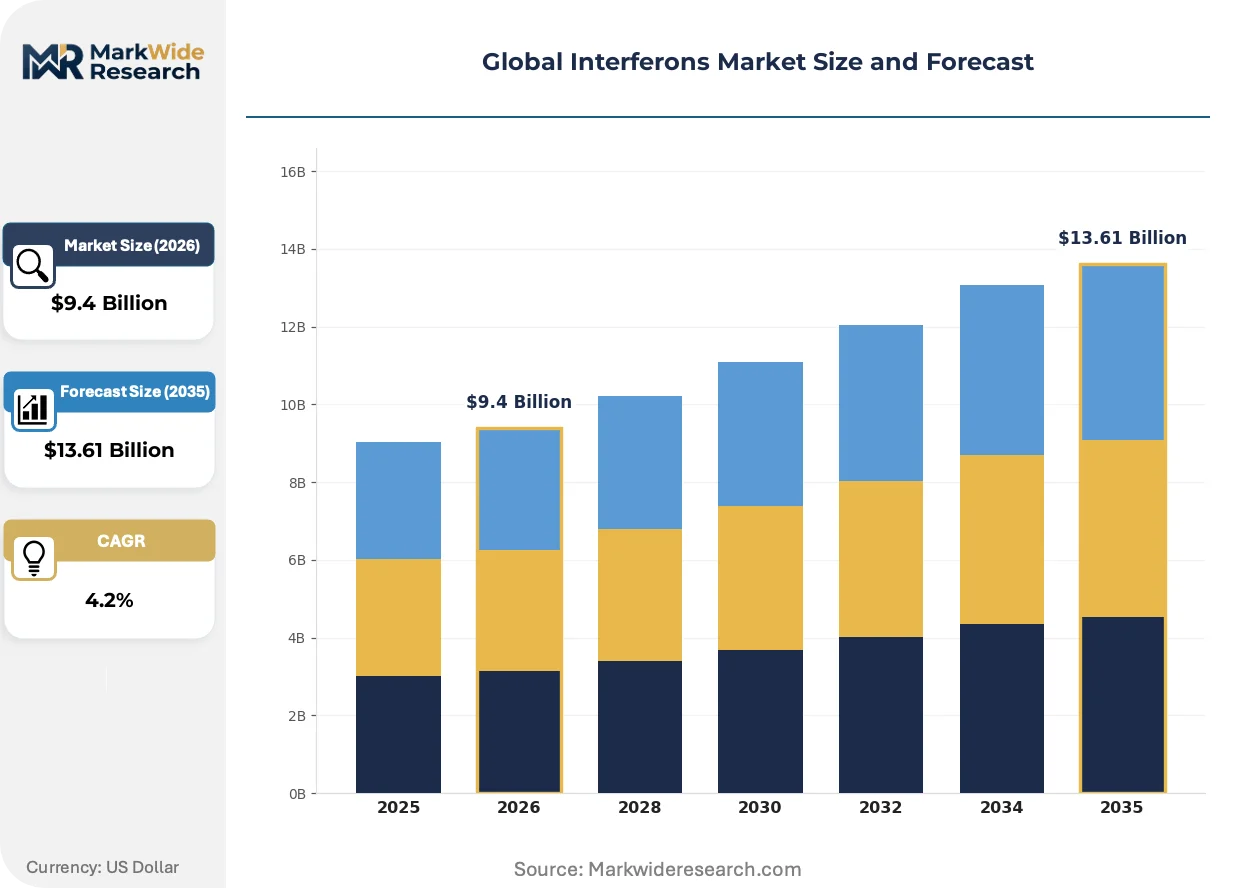
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $13.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interferon Alfa, Interferon Beta, Interferon Gamma, Interferon Omega Therapy Area: Multiple Sclerosis, Hepatitis B, Hepatitis C, Melanoma End User: Hospitals, Specialty Clinics, Diagnostic Laboratories, Ambulatory Care Centers Delivery Mode: Injectable, Subcutaneous, Intramuscular, Intravenous |
| Companies Covered | Biogen Inc., Merck & Co., Inc., Roche Holding AG, Bayer AG, Novartis International AG, Pfizer Inc., Amega Biotech, Zydus Cadila, AOP Orphan Pharmaceuticals AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Interferons Market Shifts & Advancements
Recombinant protein manufacturing is bifurcating between high-complexity mammalian systems for glycosylated products and streamlined bacterial platforms for cost-sensitive segments.
Biosimilar interferon beta formulations are consolidating market share in European hospital procurement tenders as Germany's AMNOG framework mandates rapid price-negotiation post-launch. Neurology departments in France, Italy, and Spain are accelerating formulary switches toward EMA-approved biosimilars. Originators are responding with device-differentiated delivery systems to defend prescriber loyalty.
Japan's PMDA has tightened stability-testing requirements for foreign-manufactured interferons, extending development timelines by 12-18 months for applicants without domestic fill-finish partnerships. This regulatory friction favors Roche and Merck's established Japanese manufacturing infrastructure. Smaller entrants are prioritizing licensing deals with local CDMOs to satisfy PMDA inspection protocols.
Hospital purchasing consortia in the United States are unbundling interferon procurement from bundled oncology contracts, creating direct price competition between originators and FDA-designated interchangeable biosimilars. Specialty pharmacy networks are capturing distribution volume as self-administered subcutaneous protocols displace infusion center visits. This channel shift concentrates negotiating leverage with CVS Caremark, Express Scripts, and OptumRx formulary committees.
Global Interferons Market Segmentation
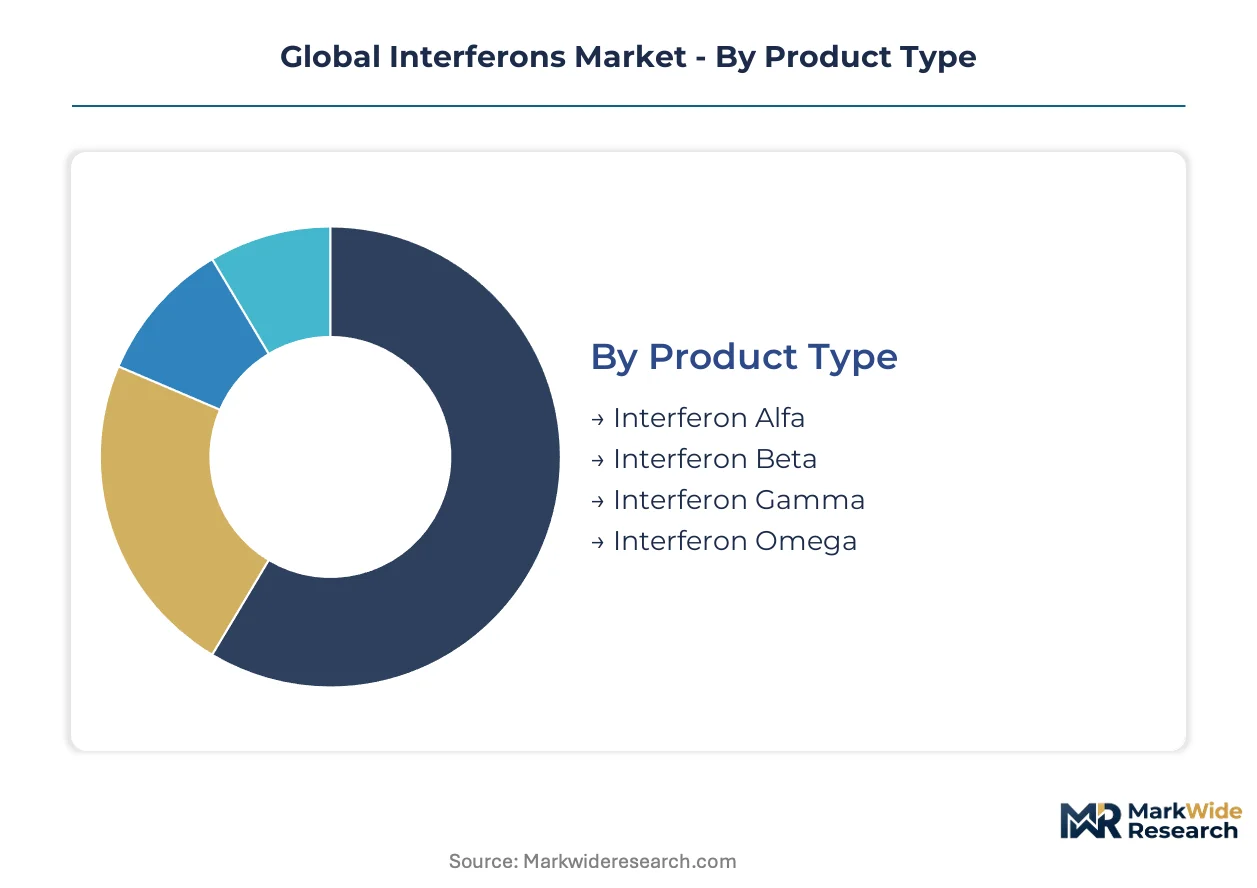
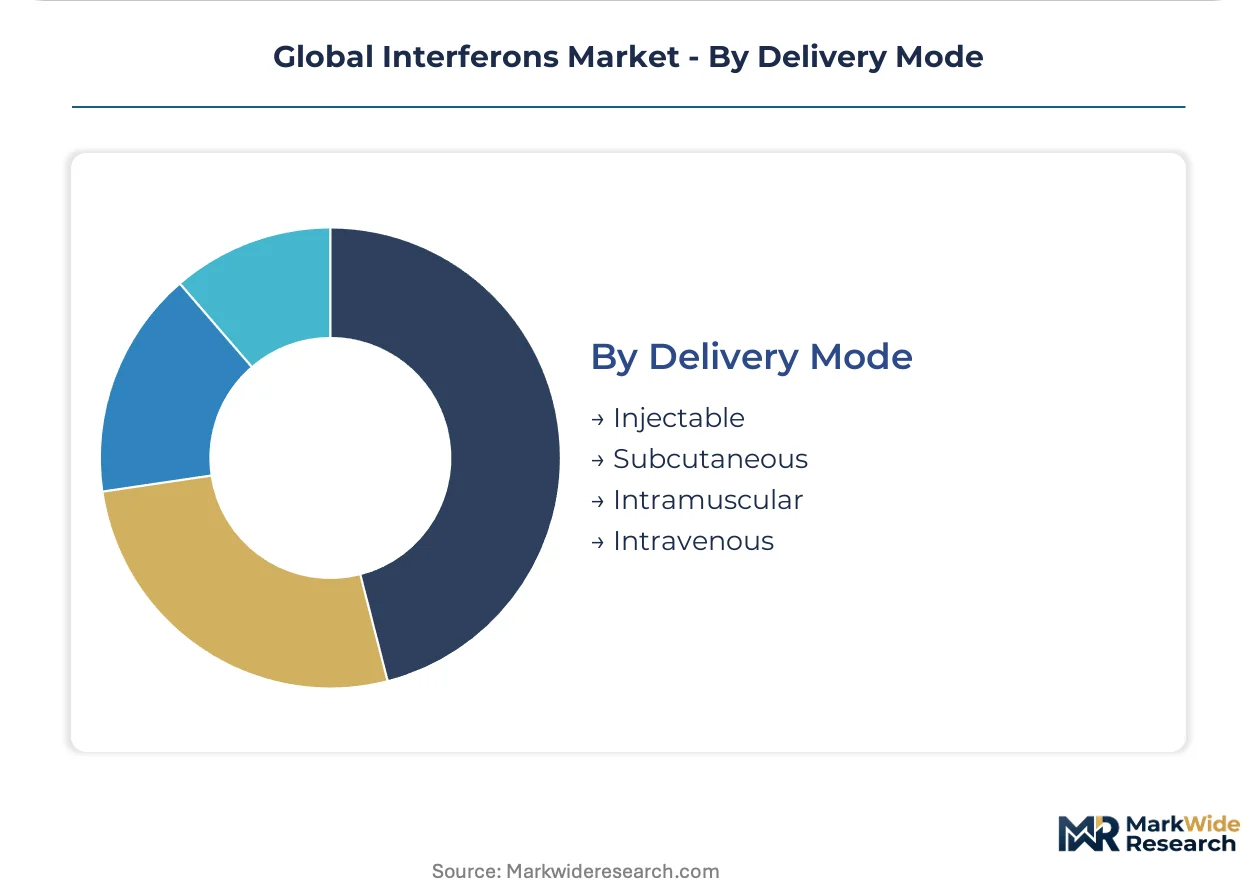
Interferon segmentation reveals distinct manufacturing, regulatory, and clinical pathways that determine procurement priorities across healthcare systems. Product type and delivery mode choices cascade into supply chain requirements, cold chain infrastructure, and reimbursement negotiations.
Product Type:
Purchasing committees weigh glycosylation complexity against clinical indication breadth when allocating formulary budgets across interferon subtypes.
- Interferon Beta:Glycoprotein cytokine produced via mammalian CHO cell culture with site-specific glycosylation patterns essential for receptor binding affinity. Demand concentrates in German and United States neurology clinics where first-line multiple sclerosis protocols sustain high-volume prescribing against biosimilar competition.
- Interferon Gamma:Non-glycosylated protein manufactured through bacterial expression systems, enabling cost-efficient production for orphan disease applications. Prescription growth accelerates in Japanese pediatric immunology centers treating chronic granulomatous disease, supported by PMDA priority review pathways.
- Interferon Alfa:Recombinant protein historically dominant in hepatitis oncology protocols, now facing demand erosion from direct-acting antiviral displacement in hepatitis C.
- Interferon Omega:Emerging subtype with limited commercial presence, currently restricted to investigational applications in select European academic medical centers.
Interferon beta leads on scale; interferon gamma leads on momentum.
Therapy Area:
Reimbursement tier placement and administration setting requirements vary sharply across immunological, oncological, and infectious disease applications.
- Multiple Sclerosis:Chronic autoimmune indication requiring sustained immunomodulation through self-administered subcutaneous protocols. United States specialty pharmacy networks and German neurological rehabilitation centers drive volume concentration as patient adherence monitoring becomes embedded in value-based contracts.
- Hepatitis C:Viral indication experiencing therapeutic paradigm displacement as interferon-sparing direct-acting antiviral regimens capture prescriber preference in France and Spain hospital systems.
- Hepatitis B:Persistent virological suppression indication maintaining stable demand in East Asian markets where vertical transmission prevention programs sustain pediatric and adult prophylaxis protocols.
- Melanoma:Adjuvant oncology application constrained by checkpoint inhibitor competition, now restricted to niche high-risk patient stratification in Italian and Australian tertiary cancer centers.
Multiple sclerosis commands the largest addressable patient population; hepatitis C contracts most rapidly as therapeutic alternatives proliferate.
End User:
Site-of-care economics and reimbursement differentials push interferon administration toward lower-acuity settings where self-injection training and remote monitoring capabilities exist.
- Specialty Clinics:Neurology and immunology-focused outpatient facilities in Japan and Germany where nurse-led injection training and adherence telemetry support long-term multiple sclerosis management. These sites capture margin through bundled care episodes that separate drug procurement from professional fees.
- Hospitals:Acute care institutions retaining intravenous interferon administration for oncology protocols and severe infectious disease presentations requiring inpatient monitoring.
- Ambulatory Care Centers:Federally qualified health centers and community-based clinics in United States underserved regions expanding access to hepatitis B screening and treatment through HRSA-funded programs.
- Diagnostic Laboratories:Reference labs in India and Brazil providing interferon-gamma release assays for tuberculosis latent infection detection, distinct from therapeutic interferon procurement.
Specialty clinics expand fastest as site-of-care migration accelerates; hospitals retain the highest per-dose pricing through acute administration complexity.
Delivery Mode:
Injection route selection determines cold chain requirements, patient training burden, and pharmacokinetic profile optimization for specific therapeutic windows.
- Subcutaneous:Preferred self-administration route for interferon beta multiple sclerosis protocols using prefilled syringes or auto-injector devices. United States and German patients favor this modality for reduced clinic dependency, though injection site reaction management requires nursing support infrastructure.
- Intravenous:Hospital-confined administration for high-dose oncology applications where immediate medical supervision manages cytokine release syndrome and hematologic toxicity.
- Intramuscular:Historical hepatitis B vaccination and treatment route, now declining as subcutaneous bioequivalence data supports route consolidation.
- Injectable:Generic formulation category encompassing unspecified parenteral presentations, primarily legacy products in emerging market tender procurement.
Subcutaneous delivery dominates volume throughput; intravenous commands premium positioning through acute care setting requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing interferon manufacturing capacity as cost-of-compliance gaps between Western and Asian jurisdictions widen, with firms relocating fill-finish operations to capture inspection efficiency advantages while maintaining quality equivalence.
United States
FDA interchangeability designations for biosimilar interferon beta products are accelerating hospital formulary switches toward lower-cost alternatives. The IRA's Medicare price negotiation provisions are reshaping oncology procurement timelines. Boston and San Francisco biotech clusters concentrate pegylation R&D investment as originators defend margin through delivery device differentiation.
Germany
AMNOG framework mandates trigger rapid price negotiations for new interferon beta entrants within twelve months of launch. EMA centralized procedures enable simultaneous market access across federal states. Munich and Heidelberg specialty neurology centers sustain high-volume multiple sclerosis prescribing through integrated adherence monitoring programs.
Japan
PMDA stability-testing extensions for foreign-manufactured interferons add 12-18 months to approval timelines, favoring domestic fill-finish partnerships. METI industrial policy supports local bioreactor capacity expansion for cytokine production. Tokyo and Osaka immunology clinics drive interferon gamma demand for pediatric chronic granulomatous disease protocols.
China
NMPA streamlined biosimilar approval pathways are accelerating domestic interferon beta-1a registration. Dual carbon goals are pressuring energy-intensive mammalian cell culture facilities toward process intensification. Shanghai and Suzhou biomanufacturing hubs consolidate fermentation capacity as Western firms renegotiate supply contracts.
India
CDSCO accelerated approval tracks for non-glycosylated interferon alpha products are expanding export eligibility to WHO prequalification pathways. PLI scheme incentives support bacterial expression system scale-up. Hyderabad and Bengaluru CDMO clusters capture contract manufacturing demand from cost-sensitive emerging markets.
Global Interferons Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biosimilar equivalence and regional market access. The market structure consolidates around three archetypes: integrated pharmaceutical conglomerates with captive biologics capacity, specialty neurology-focused biotech firms, and emerging-market CDMOs supplying cost-optimized non-glycosylated formulations. Dominant competitive moves include vertical integration into device-differentiated delivery systems and strategic licensing of PEGylation technology to circumvent patent cliffs.
Among integrated pharmaceutical conglomerates, Roche Holding AG and Merck & Co., Inc. exemplify the established-tier archetype through sustained recombinant protein expertise. Biogen Inc. occupies a specialist position within the neurology-focused vector. These three entities collectively represent the competitive core against which biosimilar entrants benchmark manufacturing quality and regulatory compliance standards.
| Leading Market Players |
|---|
| Biogen Inc. |
| Merck & Co., Inc. |
| Roche Holding AG |
| Bayer AG |
| Novartis International AG |
| Pfizer Inc. |
| Amega Biotech |
| Zydus Cadila |
| AOP Orphan Pharmaceuticals AG |
| Others |
Supply & Pricing Matrix
Biologics process engineers concentrated in Basel and Boston command wage premiums that widen spreads between originator and biosimilar interferon tiers. This workforce scarcity forces manufacturers to site high-complexity mammalian cell culture in premium-cost jurisdictions while outsourcing bacterial expression to lower-cost CDMO clusters.
Pricing Analysis
Specialty pharmacy distribution margins absorb the largest channel cost layer in United States interferon procurement. Three-tier pricing structure across originator premium, designated-interchangeable biosimilar, and non-interchangeable economy levels reflects FDA certification status and device bundling. Cost compression in the economy tier intensifies as Indian CDMOs scale bacterial expression for non-glycosylated interferon alpha. Hospital purchasing committees exhibit highest price sensitivity; neurology clinics with adherence-monitoring contracts show lowest sensitivity due to outcome-based reimbursement.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Singapore, and Memphis maintain hub-and-spoke patterns for temperature-controlled interferon logistics. Manufacturing concentrates in Switzerland, Germany, and the United States for glycosylated products; India and China anchor bacterial expression capacity. Supply chains draw from fetal bovine serum suppliers in Australia and New Zealand, recombinant protein media from Denmark, and single-use bioreactor components from Massachusetts. Single-source vulnerability in CHO cell line licensing creates concentration risk. Distribution runs through cold-chain-validated 3PL networks with real-time thermal monitoring.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The interferon market functions as a regulatory compounder where FDA interchangeability rulings accelerate demand migration toward lower-cost biosimilars while tightening compliance burdens.
For Market Incumbents: Hedge against biosimilar erosion by deepening captive fill-finish capacity in Japan to satisfy PMDA inspection protocols. Accelerate device-differentiated delivery system R&D in Boston and Basel clusters to defend prescriber loyalty. Secure priority review voucher positions through interferon gamma orphan disease expansion. For New Entrants and Emerging Players: Launch via WHO prequalification pathways targeting Southeast Asian national immunization programs for hepatitis C elimination. Concentrate bacterial expression partnerships with Hyderabad CDMOs to capture cost-sensitive interferon alpha demand. Prioritize subcutaneous auto-injector convergence as the most penetrable differentiation angle. For Investors and Strategic Acquirers: Specialty pharma consolidators with neurology portfolios are the most active acquirer in this space. Long-term viability hinges on sustained multiple sclerosis protocol durability against oral immunomodulator displacement. Monitor FDA biosimilar interchangeability designation velocity as the critical inflection signal for originator pricing power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | CHO cell culture expansion in Switzerland secures glycosylated interferon supply for German neurology clinics. |
| Regulatory Approval Pathway | FDA interchangeability designation unlocks automatic pharmacy substitution for biosimilar interferon beta entrants. |
| Licensing Agreement | PEGylation technology licensing circumvents patent cliffs for legacy pegylated interferon formulations. |
| Pipeline Diversification | Interferon gamma orphan disease programs access pediatric exclusivity incentives through PMDA priority review. |
| Clinical Trial Advancement | Subcutaneous auto-injector adherence trials support value-based contracts with United States specialty pharmacies. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each regional cluster. The analysis combines structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up demand modeling across patient populations, administration routes, and regional regulatory clusters triangulates against top-down manufacturer capacity assessments.
Rate-of-change decomposition isolates volume drivers from price dynamics across the projection horizon. The analytical framework models segmentation across product type, therapy area, delivery mode, and end-user setting, with regional regulatory clusters as an additional dimension. CAGRs derive from patient flow projections, biosimilar penetration curves, and reimbursement tier migration patterns. Forecast inputs include AMNOG price negotiation timelines, PMDA stability-testing duration estimates, and WHO prequalification adoption rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under biosimilar interchangeability ruling delays or mammalian cell culture contamination events. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Triptorelin Market
Biopharmaceuticals
Diabetes Drugs Market
Biopharmaceuticals
In Situ Gel Drug Delivery Market
Biopharmaceuticals
Mammalian Polyclonal Igg Antibody Market
Biopharmaceuticals
Interleukin 1 Beta (IL-1β) ELISA Kit Market
Biopharmaceuticals
Neurodegenerative Diseases Drugs Market
Biopharmaceuticals
Tuberculosis Drugs Market
Biopharmaceuticals
BRAF Kinase Inhibitors Market
Biopharmaceuticals
Somatropin Market
Biopharmaceuticals
Biopharmaceutical Excipients Market
Biopharmaceuticals
Global Myelodysplastic Syndrome (MDS) Drugs Market
Biopharmaceuticals
Linaclotide API Market
Biopharmaceuticals
Global Bovine Blood Plasma Derivatives Market
Biopharmaceuticals
Global Pegylated Proteins Market
Biopharmaceuticals
Spectinomycin Market
Biopharmaceuticals
Chemotherapy Market