
 Biopharmaceutical Contract Research and Manufacturing Services (CRAMS) Market | 2026-2036
Biopharmaceutical Contract Research and Manufacturing Services (CRAMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Biopharmaceutical Contract Research and Manufacturing Services (CRAMS) Market Insights
The shift from captive biologics manufacturing toward multi-source outsourced partnerships is realigning how pharmaceutical innovators allocate capital across development cycles. Lonza Group leverages its mammalian cell culture infrastructure to anchor high-complexity antibody production for global innovators. Samsung Biologics sustains massive single-site bioreactor capacity, competing aggressively on scale for late-stage commercial programs. WuXi Biologics differentiates through integrated discovery-to-commercial platforms that compress timeline risk for biotechnology firms without internal manufacturing.
Biopharmaceutical Contract Research and Manufacturing Services encompass outsourced clinical trial execution, process development, and GMP biologics production under client-specific quality agreements, typically requiring mammalian or microbial expression systems, aseptic filling, and cold-chain distribution validation. The primary purpose is to convert drug candidates into commercially viable therapies without capital-intensive in-house infrastructure. Monoclonal antibodies occupy the largest value pool within product type segmentation due to established purification economics and dosing scale. Biosimilars represent the fastest-expanding demand category as patent cliffs open reference-product opportunities across regulated markets. Clinical research services within service type segmentation retain mature margin profiles, while biologics development commands premium pricing tied to CMC complexity and regulatory submission support.
FDA quality-by-design mandates and EMA's evolving biosimilar guidelines shape facility qualification standards, forcing CRAMS providers to maintain dual-continent regulatory compliance capabilities. China's NMPA alignment with ICH standards accelerates domestic facility upgrades for international contract eligibility. Switzerland's Swissmedic maintains stringent batch-release protocols that filter subscale operators from high-value commercial programs. Stakeholders must monitor how CDMO consolidation and regional biosecurity policies reshape partner qualification criteria and geographic redundancy requirements.
Market Dynamics
The FDA's quality-by-design mandates and EMA's evolving biosimilar guidelines are compressing partner qualification timelines, forcing pharmaceutical innovators to restructure outsourcing portfolios around dual-continent regulatory capabilities rather than single-source captive manufacturing.
Growth Catalysts
- Oncology biologics pipelines:Cell therapy developers are expanding CRAMS partnerships to accelerate IND-to-BLA timelines, outsourcing complex CAR-T manufacturing to specialized mammalian cell culture facilities.
- EMA biosimilar pathway maturation:Streamlined comparability protocols are opening reference-product opportunities as patent cliffs approach for blockbuster monoclonal antibodies across regulated European markets.
- Switzerland's biologics manufacturing clusters:Swissmedic's stringent batch-release standards are attracting high-value commercial programs seeking regulatory credibility for global distribution.
Market Restraints
- Protein A resin supply concentration:Chromatography media for antibody purification relies on limited qualified suppliers, creating input cost volatility and allocation risk during demand surges.
- Single-site bioreactor scale concentration:Massive capacity at individual facilities in South Korea creates geographic redundancy vulnerabilities for sponsors requiring multi-source manufacturing strategies.
- ICH Q5A viral safety testing:Extended adventitious agent clearance timelines for novel expression systems add 4-6 months to process development schedules, delaying tech transfer.
Strategic Opportunities
- China's NMPA ICH alignment:Domestic facility upgrades for international contract eligibility are creating new qualified capacity for Western sponsors seeking cost-optimized late-stage production.
- Continuous bioprocessing convergence:Integration of perfusion cell culture with continuous chromatography is enabling 30-50% footprint reduction for commercial manufacturing suites.
- Cold-chain distribution innovation:Validated cryogenic logistics networks for cell therapies are opening direct-to-clinic channels that bypass traditional wholesale distribution.
Industry Challenges
- Cell therapy manufacturing technologist scarcity:Qualified personnel for aseptic processing in closed-system bioreactors command 40-60% salary premiums over traditional biologics operators, constraining facility expansion.
- Multi-product facility changeover complexity:Campaign-to-campaign cleaning validation for antibody-drug conjugates requires extensive residue clearance studies, compressing facility utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biopharmaceutical Contract Research and Manufacturing Services (CRAMS) Market |
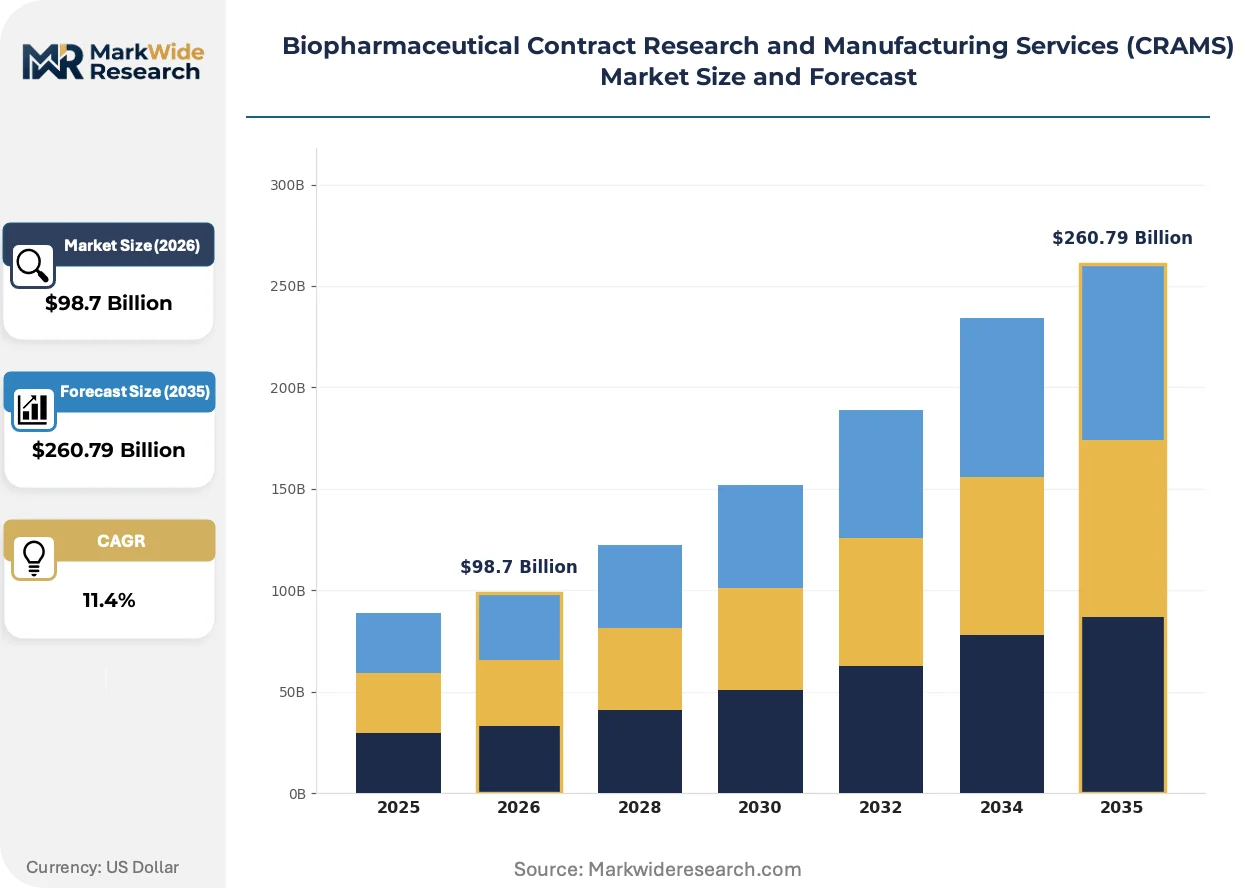
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $260.79 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Clinical Research, Biologics Development, Analytical Services, Formulation Development Product Type: Monoclonal Antibodies, Vaccines, Recombinant Proteins, Biosimilars End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Research Organizations Delivery Model: Project-Based, Retainer-Based, Milestone-Based, Partnership |
| Companies Covered | Lonza Group, Samsung Biologics, WuXi Biologics, Thermo Fisher Scientific Inc., Catalent Inc., Fujifilm Diosynth Biotechnologies, Boehringer Ingelheim, AbbVie Inc., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biopharmaceutical Contract Research and Manufacturing Services (CRAMS) Market Trends and Innovations
Process intensification technologies and regulatory harmonization initiatives are compressing development timelines while reshaping how sponsors evaluate contract partner capabilities beyond traditional capacity metrics.
Single-use bioreactor systems are absorbing stainless-steel infrastructure demand across clinical and early-commercial manufacturing. Mid-stage biotechnology firms are adopting 2,000L disposable stirred-tank configurations to eliminate cleaning validation bottlenecks and accelerate product changeovers. This shift is absorbing capital that previously flowed into fixed equipment, enabling faster facility repurposing for emerging modalities.
EMA's revised biosimilar guidelines are tightening analytical comparability requirements for post-translational modification profiles. Sponsors must now demonstrate glycan pattern equivalence through advanced mass spectrometry methods rather than functional assays alone. High-complexity antibody programs targeting European markets are responding by embedding regulatory CMC specialists earlier into process development teams.
Biotechnology sponsors are consolidating vendor relationships around integrated discovery-to-commercial platforms. Early-stage firms without internal manufacturing infrastructure are replacing fragmented CRO-CDMO handoffs with single-partner accountability for CMC continuity. This concentration is most visible among US and European venture-backed companies pursuing accelerated approval pathways for orphan oncology indications.
Biopharmaceutical Contract Research and Manufacturing Services (CRAMS) Market Segmentation
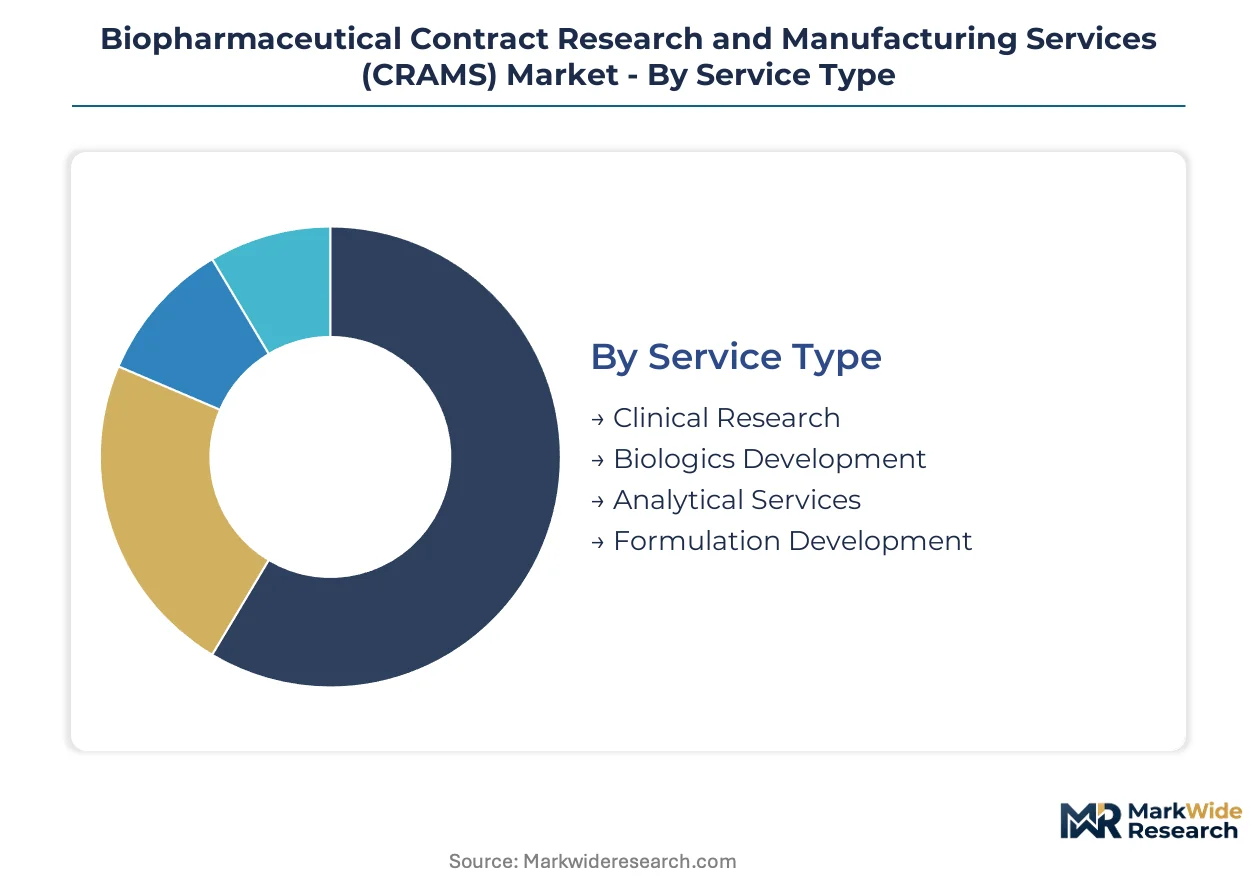
CRAMS market segmentation reveals how contract capacity allocates across development phases and molecular modalities. Sponsors select service tiers based on regulatory complexity, while product type choices reflect purification economics and expression system constraints.
Service Type:
Supply concentration in mammalian cell culture expertise is reshaping how sponsors distribute contracts across development phases.
- Clinical Research:Protocol design, site management, and regulatory submission execution for Phase I-III trials. Demand clusters in Switzerland and South Korea as sponsors seek jurisdictions with streamlined ethics review and established investigator networks for oncology biologics.
- Biologics Development:Cell line engineering, upstream process optimization, and GMP manufacturing for IND-enabling and commercial batches. China's NMPA-aligned facilities are capturing late-stage programs as Western sponsors pursue cost-optimized production without compromising ICH quality standards.
- Analytical Services:Method development, release testing, and stability studies under GMP protocols.
- Formulation Development:Lyophilization cycle optimization, excipient screening, and container closure compatibility studies.
Biologics development absorbs the bulk of installed capacity; analytical services are expanding most quickly as biosimilar comparability requirements intensify.
Product Type:
Cost tier differentiation separates blockbuster-scale antibodies from emerging modalities requiring specialized expression platforms.
- Monoclonal Antibodies:Full-length IgG therapeutics produced via Chinese hamster ovary cell culture with established Protein A purification trains. Lonza's mammalian facilities in Switzerland and WuXi Biologics' integrated platforms in China anchor commercial-scale production for global innovators facing patent cliff pressures.
- Biosimilars:Follow-on biologics requiring analytical comparability to reference products. EMA's tightened glycan equivalence mandates are extending development timelines, yet South Korean CDMOs are capturing share through aggressive capacity expansion for European market entry.
- Vaccines:Viral vector and recombinant subunit formulations for prophylactic and therapeutic indications.
- Recombinant Proteins:Cytokines, growth factors, and enzyme replacements produced in microbial or mammalian systems.
Monoclonal antibodies command the largest facility footprint; biosimilars are gaining share fastest as reference product exclusivities expire across regulated markets.
End User:
Customer type determines contract structure, with venture-backed biotechs driving integrated platform adoption over fragmented vendor management.
- Pharmaceutical Companies:Large-cap innovators outsourcing capacity-constrained modalities or geographic expansion. Swissmedic-qualifying partners in Switzerland retain preference for commercial programs requiring global distribution credibility.
- Biotechnology Firms:Development-stage companies without captive manufacturing. These sponsors are consolidating around single-partner accountability from discovery through commercialization, particularly for accelerated oncology approvals.
- Academic Institutions:Early-stage translational research requiring GMP bridging studies for investigator-initiated trials.
- Research Organizations:Non-profit and government entities pursuing pandemic preparedness or neglected disease therapeutics.
Pharmaceutical companies commit the longest contract durations; biotechnology firms are expanding their CRAMS spend fastest as capital markets recover.
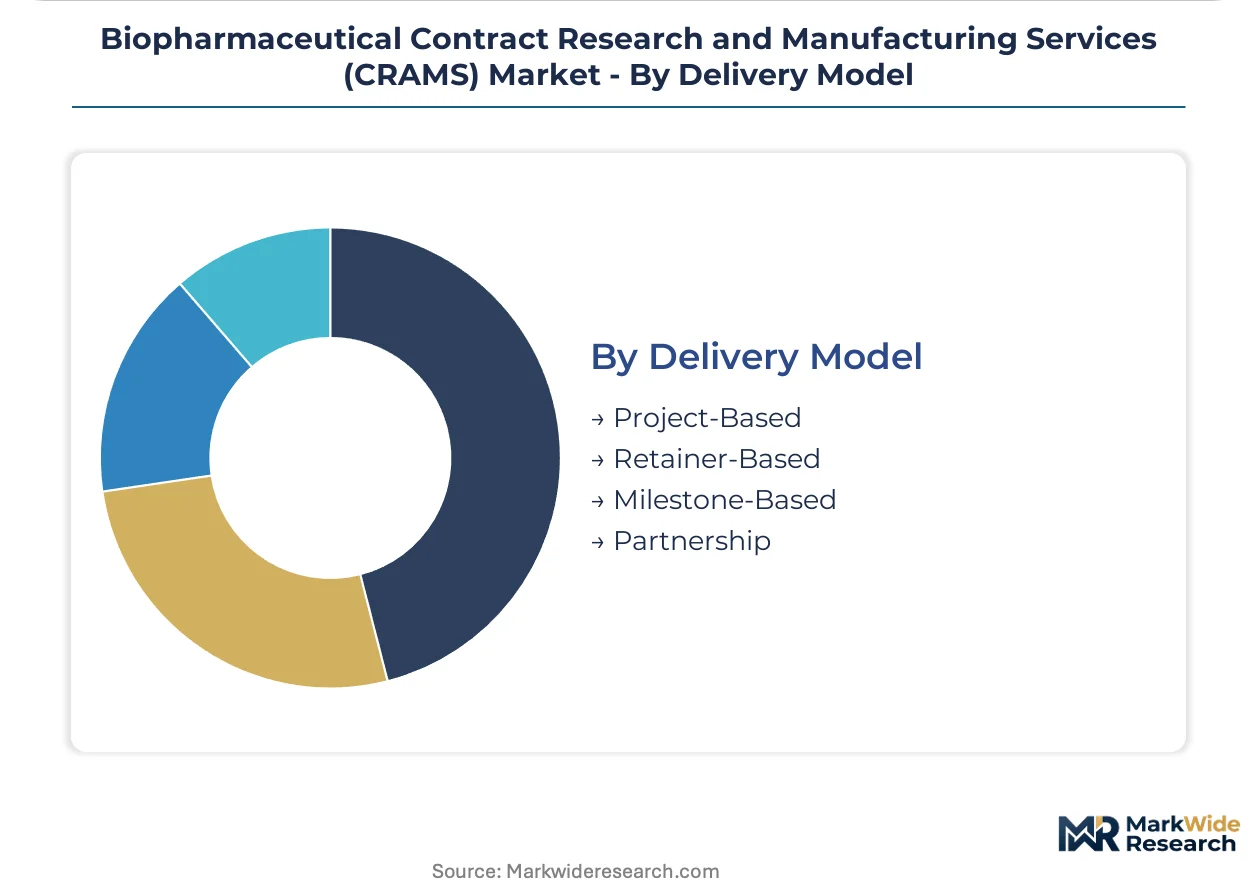
Delivery Model:
Margin profiles diverge sharply between fixed-fee predictability and outcome-contingent structures.
- Project-Based:Scoped deliverables with defined timelines and acceptance criteria. Samsung Biologics leverages this structure for late-stage commercial campaigns where process transfer is complete and batch variability is minimized.
- Milestone-Based:Payments tied to IND acceptance, Phase transition, or regulatory approval. Biotechnology sponsors favor this model to align cash outflows with value inflection points, though it demands rigorous technical specification to avoid dispute.
- Retainer-Based:Ongoing access to dedicated capacity or scientific teams.
- Partnership:Multi-year strategic alliances with preferred capacity allocation and joint governance.
Project-based structures dominate commercial manufacturing; partnership models are proliferating fastest as sponsors prioritize supply security over transactional flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for CRAMS capacity concentrates in jurisdictions with specialized biologics manufacturing clusters and stringent regulatory credibility. Sponsors prioritize partners in Switzerland, South Korea, and China for commercial-scale production.
United States
Oncology biologics developers and cell therapy innovators drive contract demand across Massachusetts and California clusters. FDA quality-by-design mandates compress partner qualification timelines, forcing sponsors toward dual-continent regulatory capabilities. Greater Boston anchors mammalian cell culture expertise for accelerated IND-to-BLA programs.
Switzerland
Swissmedic's stringent batch-release protocols attract high-value commercial programs seeking global distribution credibility. Basel and Zürich host Lonza Group's mammalian facilities serving blockbuster antibody production. The country's regulatory alignment with ICH standards filters subscale operators from premium-tier contracts.
China
NMPA alignment with ICH standards accelerates domestic facility upgrades for international contract eligibility. WuXi Biologics anchors integrated discovery-to-commercial platforms in Shanghai and Wuxi, compressing timeline risk for Western biotechnology sponsors. Cost-optimized late-stage production draws sponsors seeking manufacturing efficiency without quality compromise.
South Korea
Samsung Biologics sustains massive single-site bioreactor capacity competing aggressively on scale for late-phase commercial programs. Incheon's Songdo biocluster concentrates mammalian cell culture infrastructure for biosimilar export to European markets. MFDS regulatory convergence with ICH enables dual-continent qualification for Korean-manufactured biologics.
Germany
Boehringer Ingelheim anchors high-complexity antibody production from its Biberach facility for global innovators. EMA biosimilar pathway maturation tightens analytical comparability requirements, extending development timelines for programs targeting European approval. Baden-Württemberg's pharmaceutical manufacturing heritage supports specialized process development capabilities.
Biopharmaceutical Contract Research and Manufacturing Services (CRAMS) Market Competitive Landscape
Capacity expansion dominates the current landscape as CDMOs race to capture oncology biologics demand before patent cliffs open biosimilar opportunities. The market structures around three tiers: integrated discovery-to-commercial platforms, scale-driven commercial manufacturers, and specialized cell therapy facilities. Strategic archetypes include mammalian cell culture specialists, microbial expression system providers, and viral vector manufacturers. M&A activity and geographic facility diversification represent the dominant competitive moves as sponsors demand multi-source redundancy.
Within the integrated platform tier, WuXi Biologics exemplifies end-to-end accountability from cell line engineering through commercial GMP. Samsung Biologics occupies a position at the scale-driven extreme, leveraging concentrated bioreactor capacity for late-stage campaigns. Lonza Group anchors the premium-regulatory tier, representing Swissmedic-qualified manufacturing credibility for global distribution programs. These three entities collectively illustrate how geographic specialization and service breadth stratify competitive positioning.
| Leading Market Players |
|---|
| Lonza Group |
| Samsung Biologics |
| WuXi Biologics |
| Thermo Fisher Scientific Inc. |
| Catalent Inc. |
| Fujifilm Diosynth Biotechnologies |
| Boehringer Ingelheim |
| AbbVie Inc. |
| Novartis AG |
| Others |
Pricing and Supply Chain Analysis
Protein A resin costs cascade from chromatography media suppliers through antibody purification pricing tiers, with Swissmedic-qualified facilities commanding premiums while Chinese NMPA-aligned sites compress margins for late-stage commercial batches.
Pricing Analysis
Volume-margins split sharply between blockbuster-scale monoclonal antibody campaigns and emerging modality programs. Three-tier pricing structure across premium, standard, and economy levels separates Swissmedic-certified commercial manufacturing from MFDS-aligned South Korean capacity and NMPA-registered Chinese facilities. Pricing pressure stems from biosimilar developers squeezing contract rates as patent cliffs approach. Biotechnology firms without captive infrastructure exhibit highest price sensitivity; large-cap pharmaceutical sponsors prioritize regulatory credibility over unit cost.
Supply Chain Analysis
Direct-to-sponsor channels handle clinical trial material demand, while wholesale distribution with cold-chain validation serves commercial biologics. Supply concentrates in Switzerland, South Korea, and China for mammalian cell culture capacity. Raw material dependencies center on Protein A chromatography resins, single-use bioreactor bags, and viral clearance reagents. Single-site bioreactor scale concentration in South Korea creates geographic redundancy vulnerabilities. Distribution runs through validated cryogenic logistics networks for cell therapies bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into upstream cell line engineering and downstream fill-finish capabilities is reshaping competitive positioning as sponsors consolidate around single-partner accountability.
For Market Incumbents: Extend mammalian cell culture capacity into adjacent viral vector manufacturing to capture cell therapy demand. Lock in long-term Protein A resin supply agreements before allocation crises recur. Samsung Biologics' concentrated bioreactor scale and WuXi Biologics' integrated platforms represent the consolidation threat model to counter.
For New Entrants and Emerging Players: Capture analytical services demand from biosimilar developers facing EMA's tightened glycan comparability mandates. Target China's NMPA-aligned facilities for Western sponsors seeking cost-optimized late-stage production. Lead with continuous bioprocessing expertise as a differentiation wedge against stainless-steel incumbents.
For Investors and Strategic Acquirers: FDA quality-by-design enforcement actions against subscale operators are the leading indicator that regulatory credibility premiums will widen. Five-to-ten year viability favors CDMOs with dual-continent ICH compliance and closed-system bioreactor capabilities. Watch for MFDS-Swissmedic mutual recognition agreements as capacity allocation signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Investment | FDA quality-by-design and EMA biosimilar mandates filter subscale operators from premium contracts. |
| Capacity Expansion in Biologics Clusters | Switzerland, South Korea, and China concentrate mammalian cell culture infrastructure for global sponsors. |
| Continuous Bioprocessing Adoption | Perfusion cell culture integration reduces commercial manufacturing footprints for cost-competitive production. |
| Integrated Discovery-to-Commercial Platforms | Single-partner accountability compresses timeline risk for biotechnology firms without internal manufacturing. |
| Cold-Chain Distribution Network Buildout | Validated cryogenic logistics enable direct-to-clinic cell therapy channels bypassing wholesale intermediaries. |
Research Methodology
Document review covered FDA filings, EMA submissions, ClinicalTrials.gov records, and MFDS approval databases, complemented by interviews with drug development executives, regulatory affairs leads, CMC directors, and hospital formulary managers. Secondary validation drew from SEC 10-K disclosures, CDMO capacity announcements, and ICH guideline revisions. Bottom-up facility capacity assessments and top-down sponsor outsourcing spend estimates were triangulated for market sizing.
Segment-level outputs across service type, product modality, and end-user archetype were generated through the projection horizon. The analytical framework modeled biologics development, clinical research, and analytical services demand separately, with CAGRs derived from sponsor pipeline velocity and capacity utilization trends. Forecast inputs incorporated patent cliff timing for reference monoclonal antibodies and cell therapy IND submission rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ICH Q5A viral safety testing timeline extensions and Protein A resin supply disruptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Sodium-Dependent Glucose Co-Transporter 2 (SGLT 2) Market
Biopharmaceuticals
Conjugated Estrogen Market
Biopharmaceuticals
Global Myelodysplastic Syndrome (MDS) Drugs Market
Biopharmaceuticals
Human Chorionic Gonadotropin Market
Biopharmaceuticals
Global Antibody Market
Biopharmaceuticals
Global Hairy Cell Leukemia Drugs Market
Biopharmaceuticals
Insulin Delivery Pens Market
Biopharmaceuticals
Diabetes Drugs Market
Biopharmaceuticals
Global Monoclonal Antibodies (Mabs) Market
Biopharmaceuticals
Human Combinatorial Antibody Libraries (Hucal) Market
Biopharmaceuticals
US Generic Injectables Market
Biopharmaceuticals
Global Interferons Market
Biopharmaceuticals
Global Immuno Oncology Assays Market
Biopharmaceuticals
Triclabendazole Market
Biopharmaceuticals
Interleukin-6 (IL-6) Inhibitors Market
Biopharmaceuticals
North America Insulin Pens Market