
 Self Inflating Bag Market | 2026-2036
Self Inflating Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Self Inflating Bag Market Insights
Multi-source procurement is pivoting toward vertically integrated suppliers as hospitals and emergency services seek supply chain resilience for critical respiratory equipment. Ambu A/S leverages its European manufacturing footprint to sustain consistent delivery to Nordic and German health systems. Laerdal Medical anchors its position through specialized training partnerships with emergency medical services worldwide. Medline Industries competes aggressively on scale, using its broad distribution network to control hospital procurement channels across North America.
A self-inflating bag is a manually operated, valve-controlled device constructed from medical-grade PVC or thermoplastic polyurethane with an integrated reservoir bag, designed to deliver positive-pressure ventilation to patients with inadequate spontaneous respiration. The device operates through a self-filling mechanism where a compressed gas source or ambient air enters via a one-way valve, with flow rates typically calibrated between 10 and 15 liters per minute for adult applications. Emergency bags dominate the product type landscape due to their irreplaceable role in cardiac arrest and trauma protocols, while camping mats within the outdoor segment represent the fastest-expanding application as ultralight nylon constructions displace foam pads among long-distance hikers. Medical facilities command the highest-margin end-user channel because of stringent certification requirements and recurring replacement cycles, whereas PVC remains the volume-leading material despite TPU gaining ground in premium outdoor applications.
The FDA's 510(k) clearance pathway and the EU MDR's Class IIa designation for manual resuscitators impose substantial documentation and clinical testing burdens on manufacturers seeking market access. ISO 10651 standards for lung ventilators and Japan's PMDA quality management requirements further fragment compliance obligations across major commercial territories. Stakeholders must monitor how evolving sustainability mandates from ECHA and state-level procurement preferences in the United States reshape material selection and end-of-life disposal protocols for disposable components.
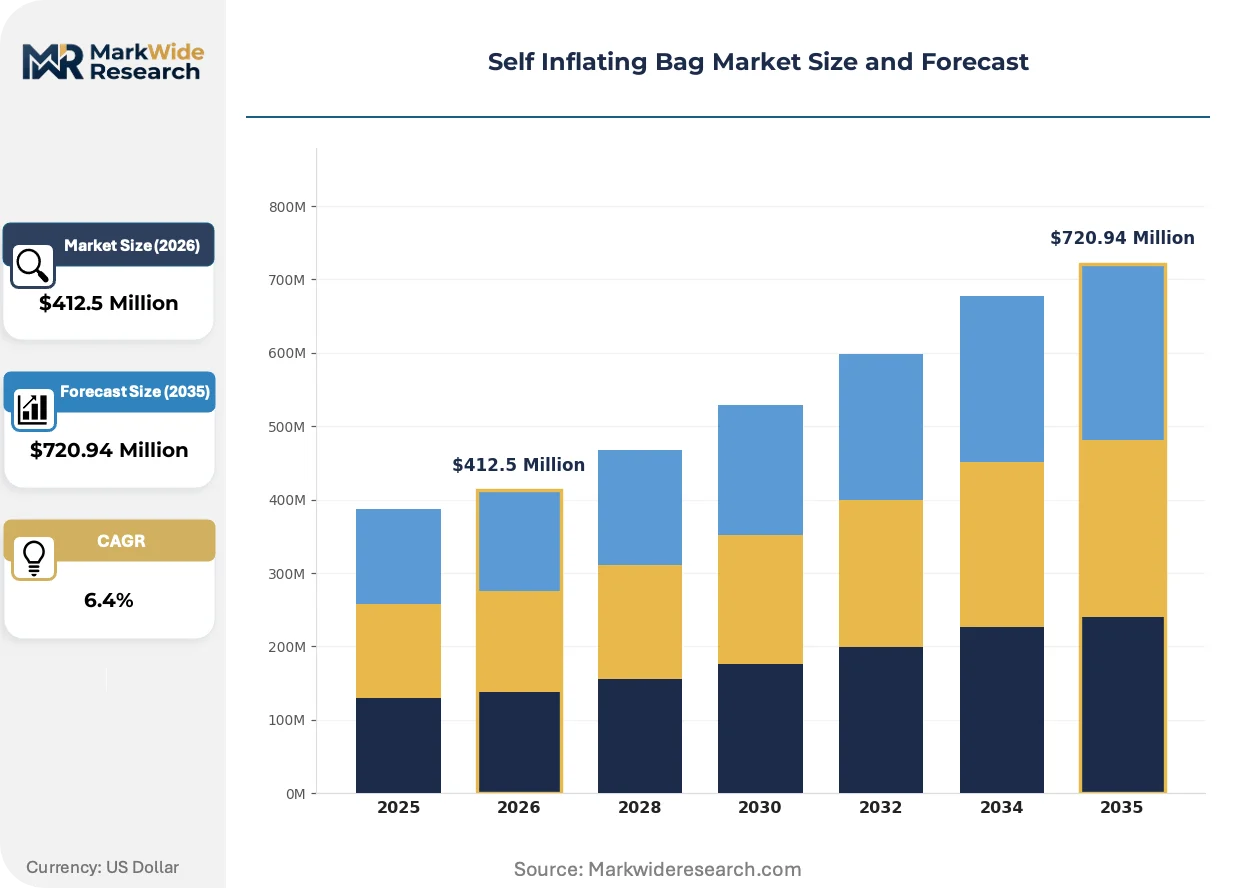
Market Dynamics
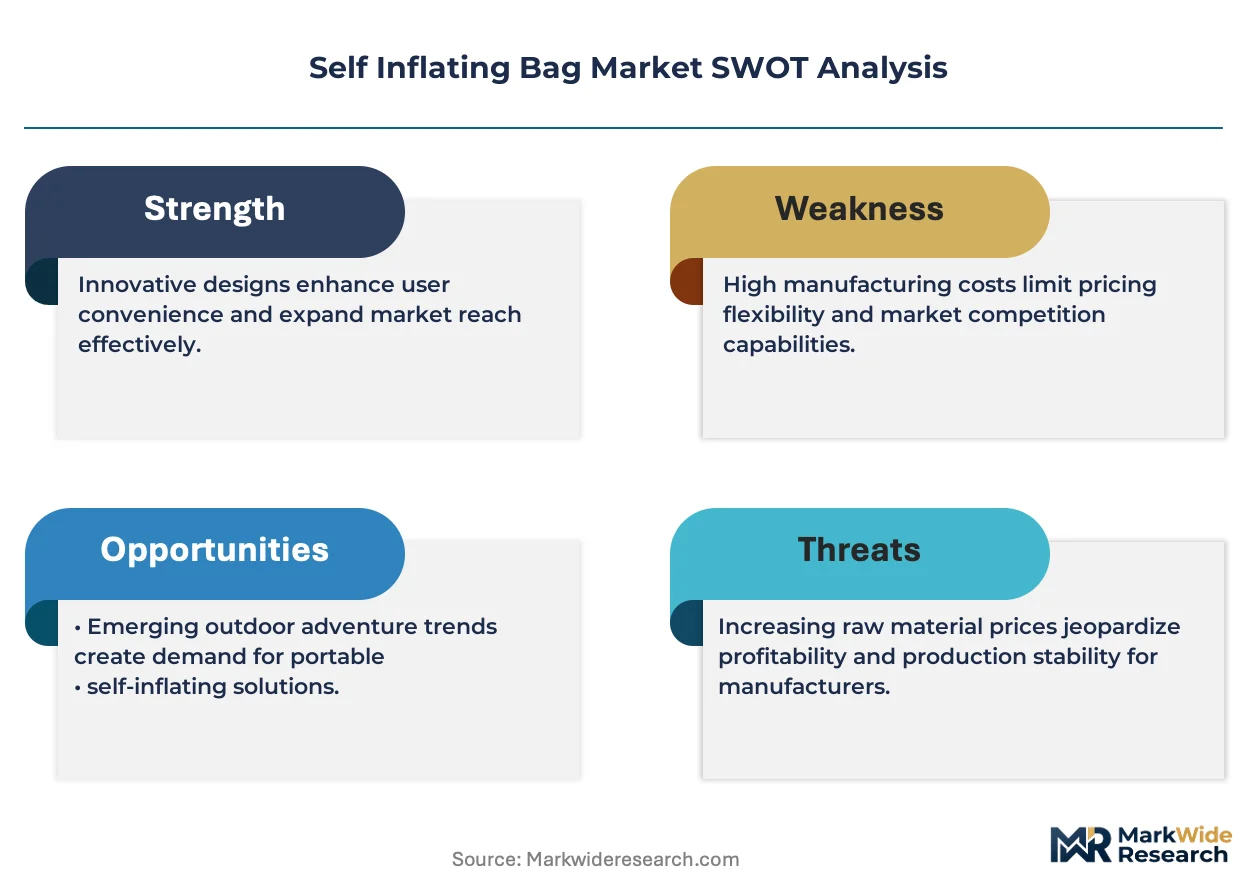
Emergency medical services are consolidating supplier relationships around vertically integrated manufacturers capable of guaranteeing continuous availability of Class IIa respiratory devices amid regulatory tightening across North America and Europe.
Growth Catalysts
- FDA 510(k) pathway streamlining:The FDA's updated premarket notification requirements for manual resuscitators are accelerating clearance timelines for manufacturers with established quality management systems, expanding addressable market access.
- Pre-hospital care expansion:Municipal emergency services in Germany and Japan are scaling ambulance fleet modernization programs, directly lifting procurement volumes for disposable resuscitation equipment.
- Thermoplastic polyurethane migration:TPU's superior cold-weather flexibility and reduced environmental persistence are displacing PVC in premium outdoor sleeping pad applications among alpine and Nordic equipment suppliers.
Market Restraints
- Medical-grade PVC feedstock volatility:Chlor-alkali production constraints and ethylene price swings are compressing margins for manufacturers locked into long-term hospital supply contracts with fixed pricing terms.
- EU MDR clinical documentation burden:The Medical Device Regulation's enhanced clinical evidence requirements for Class IIa manual resuscitators are extending time-to-market by 12-18 months for new entrants lacking predicate device pathways.
- Reusable mechanical ventilator substitution:Transport ventilators with turbine-based oxygen delivery are capturing share in inter-facility patient transfer scenarios where manual bagging previously dominated.
Strategic Opportunities
- Indian emergency infrastructure buildout:The country's National Health Mission ambulance expansion and 108 emergency response network scaling create unmet demand for cost-optimized disposable resuscitators compliant with BIS standards.
- Outdoor rental channel penetration:Gear rental cooperatives and thru-hiking logistics providers represent an underdeveloped channel for ultralight self-inflating pads, bypassing traditional retail markup structures.
- ECHA sustainable chemistry mandates:The European Chemicals Agency's restrictions on phthalate plasticizers in medical devices are creating first-mover advantages for manufacturers with bio-based alternative formulations already validated.
Industry Challenges
- ISO 10651-4 testing capacity bottleneck:Limited accredited laboratory availability for manual resuscitator performance validation is creating queue delays that compress product launch windows against competitor timelines.
- Legacy ERP integration with UDI compliance:Medical device manufacturers are struggling to retrofit existing inventory systems to support FDA Unique Device Identifier traceability requirements without disrupting just-in-time hospital replenishment flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self Inflating Bag Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emergency Bags, Camping Mats, Inflatable Pillows, Travel Cushions End User: Outdoor Enthusiasts, Travelers, Medical Facilities, Emergency Rescuers Material: Nylon, Polyester, PVC, TPU Application: Camping, Hiking, Medical Emergency, Water Sports |
| Companies Covered | Ambu A/S, Laerdal Medical, Medline Industries, Teleflex, Vyaire Medical, Medtronic, Smiths Medical, Mercury Medical, Weinmann Emergency, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self Inflating Bag Market Trends and Innovations
Material science advances and regulatory digitization are converging to reshape competitive positioning across both medical and outdoor segments, with sustainability mandates accelerating substitution timelines previously measured in decades.
Silicone-based bladder construction is expanding into emergency resuscitation equipment, replacing traditional PVC assemblies in premium product tiers. Nordic health systems and Japanese emergency medical technicians are adopting these configurations for extreme-temperature reliability. This material transition is expanding into previously price-sensitive procurement categories as total cost-of-ownership calculations incorporate extended device lifespan and reduced cold-weather failure rates.
The EU Medical Device Regulation's EUDAMED database implementation is mandating end-to-end traceability for Class IIa manual resuscitators sold across member states. Manufacturers must now maintain serialized production records linkable to individual patient use events, fundamentally restructuring quality management system investments. German and French hospital procurement consortia are prioritizing suppliers with demonstrated EUDAMED connectivity ahead of full enforcement deadlines.
Direct-to-outfitter contracting is displacing traditional wholesale distribution for ultralight camping pad procurement among Appalachian Trail and Pacific Crest Trail support service providers. These specialized logistics operators now negotiate volume commitments directly with TPU fabricators, bypassing outdoor retail intermediaries. This channel compression is most visible in the United States, where long-distance trail participation has concentrated demand among a narrow cohort of high-volume gear rental specialists.
Self Inflating Bag Market Segmentation
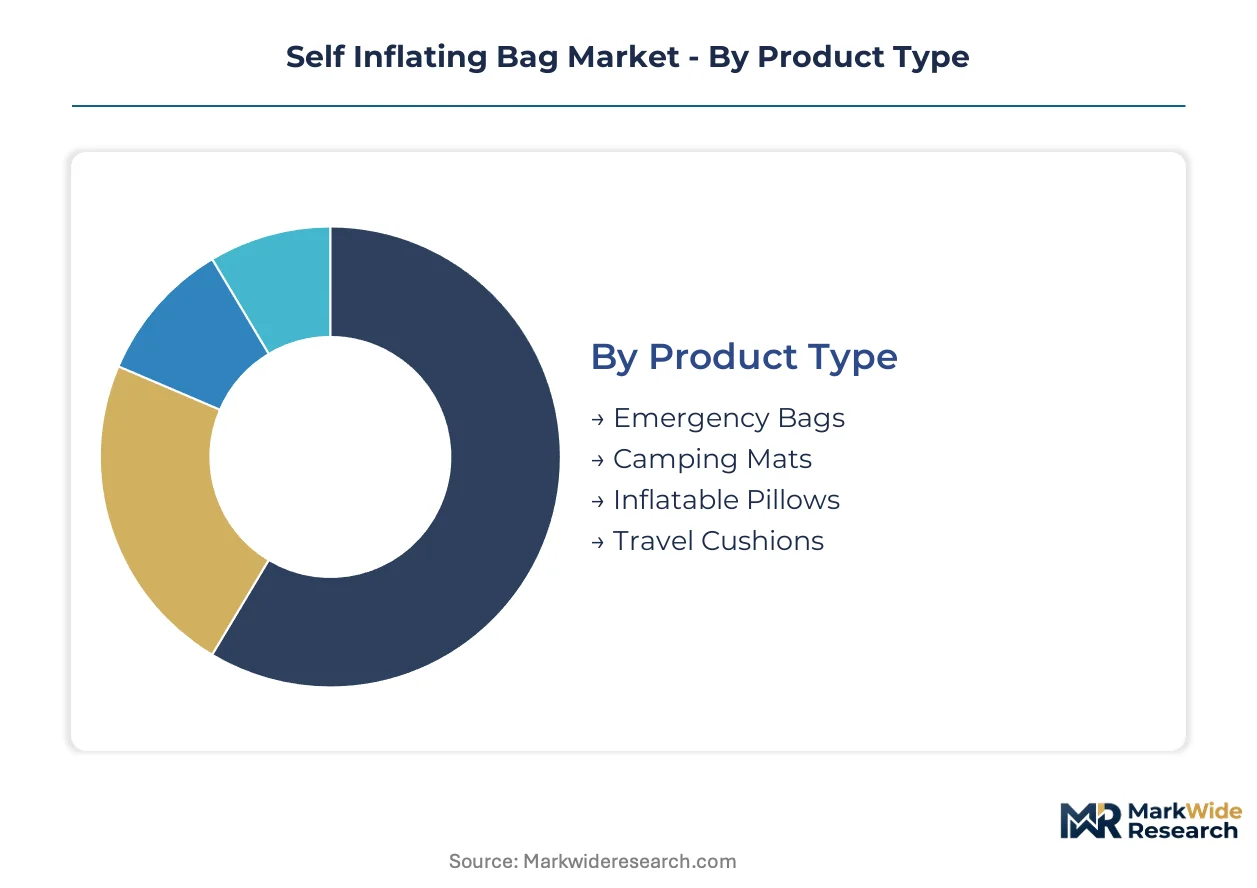
Segmentation in the self-inflating bag market reveals divergent supply chain architectures between medical and outdoor applications. Material selection and certification requirements create distinct procurement channels that rarely overlap, forcing manufacturers to specialize around either PVC-based emergency equipment or TPU-focused outdoor gear.
Product Type:
Supply concentration clusters around manufacturers with dual medical and outdoor capabilities, though emergency bags command dedicated production lines due to FDA and EU MDR compliance burdens.
- Emergency Bags:These valve-controlled resuscitation devices incorporate medical-grade PVC or silicone bladders with calibrated flow rates between 10-15 liters per minute. Demand concentrates in German and Japanese municipal ambulance fleets where pre-hospital care protocols mandate disposable equipment for cardiac arrest response.
- Camping Mats:Ultralight nylon-TPU laminates with open-cell foam cores dominate long-distance hiking applications. Appalachian Trail and Pacific Crest Trail logistics providers are bypassing retail channels to contract directly with TPU fabricators, compressing traditional distribution margins.
- Inflatable Pillows:Compact travel accessories using polyester topsheets and polyurethane air chambers. Japanese outdoor retailers and European alpine outfitters stock these as add-on purchases alongside sleeping systems.
- Travel Cushions:Pressure-relief seating pads for extended transit. Airlines and rail operators in Germany and Japan procure these for crew rest facilities and premium passenger accommodations.
Today's leader: Emergency Bags. Tomorrow's challenger: Camping Mats.
End User:
Cost tier differentiation separates premium medical procurement from price-sensitive outdoor consumers, with emergency rescuers occupying the highest-margin position due to regulatory compliance costs embedded in pricing.
- Outdoor Enthusiasts:Individual hikers and campers purchasing through retail or direct-to-consumer channels. Ultralight TPU constructions from Nordic suppliers are gaining preference among weight-conscious long-distance trekkers in the United States.
- Travelers:Casual consumers seeking compact comfort accessories for air and rail transit. This segment shows price elasticity, with polyester-based products dominating mass-market sales through airport retail and online marketplaces.
- Medical Facilities:Hospitals and clinics requiring Class IIa certified manual resuscitators with full EUDAMED traceability. German and French hospital procurement consortia prioritize suppliers with demonstrated regulatory connectivity ahead of enforcement deadlines.
- Emergency Rescuers:Municipal EMS, fire departments, and disaster response teams operating under strict protocol requirements. North American and European services are consolidating supplier relationships around vertically integrated manufacturers capable of guaranteeing continuous availability amid regulatory tightening.
Medical Facilities capture margin premiums. Outdoor Enthusiasts drive volume scaling.
Material:
Application requirements dictate material selection, with medical-grade PVC facing sustainability pressure from ECHA phthalate restrictions while TPU gains ground in cold-weather outdoor performance.
- Nylon:Lightweight woven face fabrics for camping mat topsheets, typically 20-40 denier ripstop constructions. United States-based thru-hiking specialists specify silicone-coated variants for moisture resistance.
- Polyester:Cost-optimized alternative for entry-level travel cushions and mass-market inflatable pillows. Lower tear strength limits application to low-stress indoor environments.
- PVC:Medical-grade formulations dominate emergency resuscitation bags due to established biocompatibility profiles and sterilization compatibility. Chlor-alkali feedstock volatility is compressing margins for manufacturers locked into fixed-price hospital contracts.
- TPU:Thermoplastic polyurethane films and coatings provide superior cold-weather flexibility for alpine sleeping pads. ECHA restrictions on conventional plasticizers are accelerating bio-based TPU development among European fabricators.
PVC holds current volume leadership. TPU represents the steepest expansion trajectory.
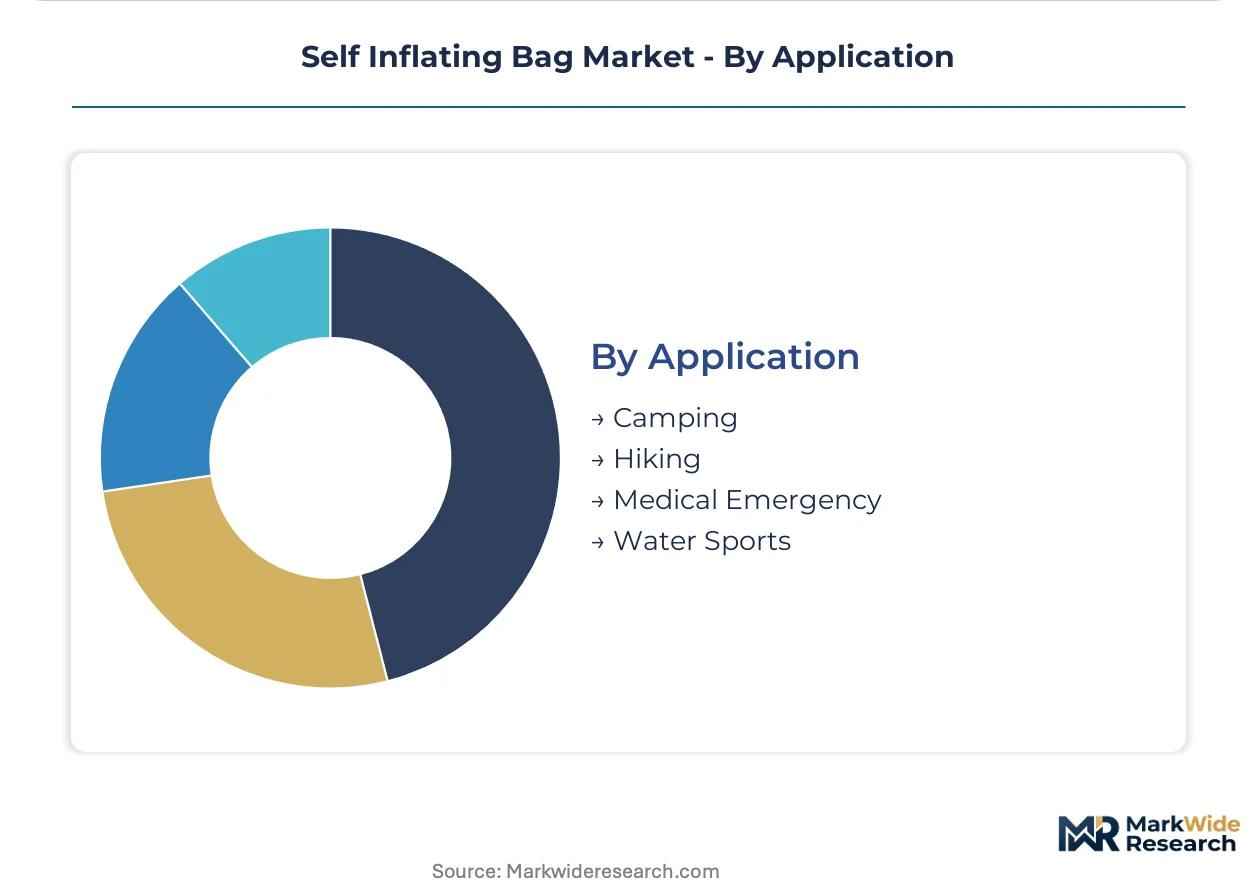
Application:
Geography shapes demand patterns, with medical emergency applications concentrated in aging populations and water sports penetration tracking coastal recreation infrastructure development.
- Camping:Established outdoor recreation in the United States, Germany, and Japan drives consistent replacement demand. Gear rental cooperatives are emerging as a volume channel for ultralight self-inflating pads.
- Hiking:Long-distance trail participation concentrates demand among specialized logistics providers. Direct contracting between Pacific Crest Trail support services and TPU manufacturers is compressing traditional wholesale structures.
- Medical Emergency:Cardiac arrest and trauma protocols in North American and European EMS systems mandate disposable resuscitation equipment. India's National Health Mission ambulance expansion is creating unmet demand for cost-optimized BIS-compliant devices.
- Water Sports:Inflatable rescue platforms and flotation accessories for coastal and riverine operations. Japanese maritime safety agencies and German water rescue services specify TPU constructions for saltwater durability.
Medical Emergency commands certification premiums. Hiking is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity is migrating toward jurisdictions with streamlined medical device registration pathways, as the cost differential between FDA 510(k) preparation and emerging-market quality system audits widens compliance arbitrage opportunities.
United States
Municipal EMS modernization and aging demographics sustain procurement volumes for disposable resuscitators. FDA's updated 510(k) requirements for Class IIa manual resuscitators impose documentation burdens that favor established quality management systems. Boston and Minneapolis medical device clusters concentrate production of emergency respiratory equipment for domestic hospital networks.
Germany
Pre-hospital care protocol standardization across federal states drives consistent replacement demand for ambulance fleets. EU MDR's EUDAMED traceability mandates are restructuring procurement priorities toward suppliers with demonstrated connectivity. Baden-Württemberg and Bavaria host vertically integrated manufacturers serving Nordic and domestic health systems.
Japan
PMDA quality management requirements and METI emergency infrastructure investments align procurement toward cold-weather reliable configurations. Aging population demographics expand home-care and pre-hospital equipment budgets. Osaka and Nagoya industrial corridors concentrate silicone-bladder fabrication for extreme-temperature applications.
India
National Health Mission ambulance expansion and 108 emergency response network scaling create unmet demand for cost-optimized disposable resuscitators. BIS standards compliance offers faster market access than FDA or EU pathways for qualified manufacturers. Gujarat and Maharashtra medical device parks attract contract manufacturers seeking export-oriented production bases.
China
NMPA regulatory harmonization efforts and domestic emergency medical system upgrades expand addressable market for certified manual resuscitators. Yangtze River Delta manufacturing clusters leverage existing PVC and TPU supply chain infrastructure. Shanghai and Suzhou medical device zones concentrate export-oriented production for Southeast Asian and African markets.
Self Inflating Bag Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent outdoor and rental-channel applications. Market structure tilts toward consolidation around manufacturers with captive medical-grade material supply and validated quality systems. Three archetypes dominate: vertically integrated European specialists with EUDAMED-ready infrastructure, North American scale players leveraging broad distribution networks, and Asian contract manufacturers capturing cost-optimized public-sector procurement. Competitive moves center on backward integration into TPU and silicone feedstock, plus direct-to-outfitter channel compression in outdoor segments.
Among Danish and Norwegian medical device fabricators, Ambu A/S and Laerdal Medical exemplify the vertically integrated archetype with European manufacturing footprints. Medline Industries anchors the North American scale-driven tier. These three occupy positions reflecting divergent strategic bets: European regulatory pre-positioning versus distribution network dominance versus integrated production control.
| Leading Market Players |
|---|
| Ambu A/S |
| Laerdal Medical |
| Medline Industries |
| Teleflex |
| Vyaire Medical |
| Medtronic |
| Smiths Medical |
| Mercury Medical |
| Weinmann Emergency |
| Others |
Pricing and Supply Chain Analysis
Specialized polymer compounding expertise concentrated in Baden-Württemberg and the Yangtze River Delta creates labor-cost differentials that widen pricing-tier spreads between premium silicone-bladder emergency bags and economy PVC alternatives. German manufacturers capture margin premiums through captive TPU formulation capabilities, while Asian contract producers compete on scale for public-sector procurement tenders.
Pricing Analysis
Distributor margins of 18-25 percent in traditional hospital supply channels are compressing as direct-to-outfitter contracting for camping mats bypasses wholesale markups entirely. Three-tier pricing structure across premium, standard, and economy levels separates EUDAMED-traceable silicone devices from ISO 10651-compliant PVC units and unbranded outdoor accessories. Pricing pressure stems from chlor-alkali feedstock volatility squeezing manufacturers locked into fixed-price hospital contracts. Emergency rescuers show lowest price sensitivity due to protocol-mandated replacement cycles, while individual outdoor enthusiasts exhibit highest elasticity.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme for medical devices are reshaping sourcing patterns toward Gujarat and Maharashtra production parks for regional ambulance fleet procurement. Supply concentration clusters in Germany, China, and the United States for finished device assembly, with TPU film and medical-grade PVC resin feeding from specialized polymer corridors. Raw material dependencies center on ethylene feedstock, chlor-alkali capacity, and specialty silicone rubber formulations. Single-source vulnerability runs through European TPU compounding assets exposed to ECHA phthalate restriction timelines. Distribution runs through hospital GPOs and emergency services procurement consortia in medical segments, direct-to-outfitter channels in outdoor applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through bio-based TPU formulation shifts that command sustainability premiums in European hospital and alpine outdoor procurement. Silicone-bladder reliability in extreme temperatures justifies price-tier elevation against legacy PVC alternatives.
For Market Incumbents: Acquire captive TPU compounding assets to secure formulation control against ECHA plasticizer restrictions and chlor-alkali volatility. Consolidate testing capacity partnerships with ISO 10651-4 accredited laboratories to compress queue delays that threaten launch windows. Defend hospital GPO relationships through EUDAMED connectivity investments ahead of full enforcement deadlines. For New Entrants and Emerging Players: The 40-60 percent price-point gap between premium silicone emergency bags and economy PVC units opens entry space for hybrid constructions. India's National Health Mission ambulance buildout represents the most penetrable geography for cost-optimized BIS-compliant devices. Gear rental cooperatives for Appalachian Trail and Pacific Crest Trail logistics offer a direct-contracting go-to-market angle that bypasses retail margin extraction. For Investors and Strategic Acquirers: Valuations sit cheapest among Asian contract manufacturers with validated FDA 510(k) quality systems but limited brand presence in Western hospital networks. Long-term viability over a 5-10 year window hinges on regulatory pre-positioning rather than scale alone. Watch for EUDAMED database connectivity demonstrations as the inflection signal separating acquisition-ready assets from compliance laggards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into TPU Compounding | ECHA phthalate restrictions reward manufacturers with bio-based formulation control. |
| EUDAMED Database Connectivity Investment | German and French hospital consortia prioritize traceability-ready suppliers. |
| Direct-to-Outfitter Channel Development | Pacific Crest Trail logistics providers bypass retail markup for volume TPU procurement. |
| ISO 10651-4 Testing Capacity Partnership | Limited accredited laboratory availability creates queue bottlenecks for new entrants. |
| Silicone-Bladder Product Line Extension | Nordic health systems and Japanese EMTs adopt extreme-temperature configurations. |
Research Methodology
Direct dialogue with biomedical engineers, hospital GPO contracts managers, emergency medical services procurement leads, and alpine outfitter purchasing directors grounded qualitative findings in operational realities. Secondary validation drew from FDA 510(k) filings, EU MDR EUDAMED implementation notices, BIS medical device standards, and customs trade data for PVC and TPU feedstock flows. Bottom-up demand modeling across ambulance fleet procurement databases and top-down macroeconomic triangulation anchored volume estimates.
Segment-level outputs across product type, end user, material composition, and application dimensions were generated through the projection horizon. CAGRs were derived from regression analysis against historical replacement cycle data and regulatory implementation timelines. Forecast inputs incorporated PMDA quality management audit schedules, National Health Mission ambulance deployment targets, and ECHA restriction phase-in calendars without year-specific anchoring.
Caveats apply where FDA 510(k) pathway modifications, EU MDR enforcement intensity variations, or chlor-alkali supply disruptions could materially shift the outlook. Forecasts reflect assumptions about regulatory harmonization progress and polymer feedstock cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Care Supplies
Therapy Pillow Market
Patient Care Supplies
Hip Shield Market
Patient Care Supplies
Reusable Nursing Pads Market
Patient Care Supplies
Physical Therapy Supplies Market
Patient Care Supplies
GCC Adult Diaper Market
Patient Care Supplies
Ice Packs for Pain Market
Patient Care Supplies
Global Patient Lateral Transfer Market
Patient Care Supplies
US Pressure Ulcer Prevention Market
Patient Care Supplies
Asia-Pacific Hospital Supplies Market
Patient Care Supplies
Shoe Cover Market
Patient Care Supplies
Disposable Incontinence Products (Dips) Market
Patient Care Supplies
Stretcher Accessories Market
Patient Care Supplies
Abdominal Pads Market
Patient Care Supplies
Reusable Incontinence Products Market
Patient Care Supplies
External Urine Management Products Market
Patient Care Supplies
Patient Identification Wristbands Market