
 North America Non-Invasive Aesthetic Treatment Market | 2026-2036
North America Non-Invasive Aesthetic Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Non-Invasive Aesthetic Treatment Market Intelligence
Medspa end-use is broadening beyond traditional dermatology referral channels into standalone retail locations and hotel-based wellness concepts. AbbVie leverages its Allergan Aesthetics portfolio to sustain brand loyalty across injectable and device categories. Galderma competes through differentiated biostimulator positioning against legacy hyaluronic acid fillers. Cutera anchors its presence in laser hair removal while extending into skin revitalization platforms.
Non-invasive aesthetic treatment encompasses procedures that modify appearance without incision or general anesthesia, typically employing energy delivery systems operating at wavelengths between 532 nm and 10,600 nm or injectable biocompatible compounds administered at specified tissue depths. These interventions serve commercial purposes across cosmetic medicine, reconstructive support, and preventive aging management. Injectables occupy the largest revenue pool due to repeat purchase frequency and low capital requirements for providers. Laser treatments command premium pricing in skin resurfacing segments where outcomes correlate directly with device specifications. RF devices represent the fastest-expanding technology category as radiofrequency platforms integrate real-time temperature monitoring for enhanced safety profiles.
FDA device clearance requirements under 510(k) and de novo pathways shape product launch sequencing and clinical evidence investment for manufacturers. Health Canada and the EPA additionally influence market access through energy-based device registration and disinfectant chemistry approvals. State-level medical board regulations in California, Texas, and Florida determine supervision ratios and scope-of-practice boundaries for non-physician operators. Stakeholders must monitor evolving FDA guidance on combination product classifications where devices deliver previously approved pharmaceutical agents.
Market Dynamics
Radiofrequency platforms with real-time temperature monitoring are compressing treatment safety timelines and expanding operator pools beyond traditional physician supervision, restructuring competitive advantage toward device intelligence rather than clinical credential density.
Growth Catalysts
- FDA 510(k) pathway streamlining:De novo clearances for novel energy-based devices accelerate commercialization timelines, enabling manufacturers to reach medspa channels faster than historical dermatology-focused distribution.
- Injectable biostimulator demand:Poly-L-lactic acid and calcium hydroxylapatite formulations generate repeat purchase cycles that sustain clinic revenue without capital equipment investment.
- Texas and Florida clinic density:State-level scope-of-practice expansions for nurse practitioners and physician assistants multiply addressable provider bases in high-disposable-income metros.
Market Restraints
- Capital equipment depreciation cycles:Laser and RF platforms require replacement every 5-7 years, compressing clinic margins during technology transition periods.
- California medical board supervision ratios:Stricter physician oversight requirements for energy-based procedures limit treatment volume scalability in the largest state market.
- Hyaluronic acid filler commoditization:Biosimilar formulations and multi-source manufacturing erode pricing power for legacy injectable portfolios.
Strategic Opportunities
- Canadian provincial expansion:Ontario and British Columbia show underpenetrated medspa density relative to comparable US metropolitan markets.
- Hotel-based wellness integration:Luxury hospitality channels in Miami and Los Angeles create new patient acquisition pathways outside traditional referral networks.
- Combination product classification clarity:Evolving FDA guidance on devices delivering pharmaceutical agents opens regulatory pathways for enhanced topical-device protocols.
Industry Challenges
- RF device calibration expertise:Temperature monitoring systems require specialized training that outpaces current aesthetic nursing curriculum coverage.
- Multi-platform integration complexity:Clinics operating mixed laser and injectable portfolios face workflow fragmentation across incompatible software systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Non-Invasive Aesthetic Treatment Market |
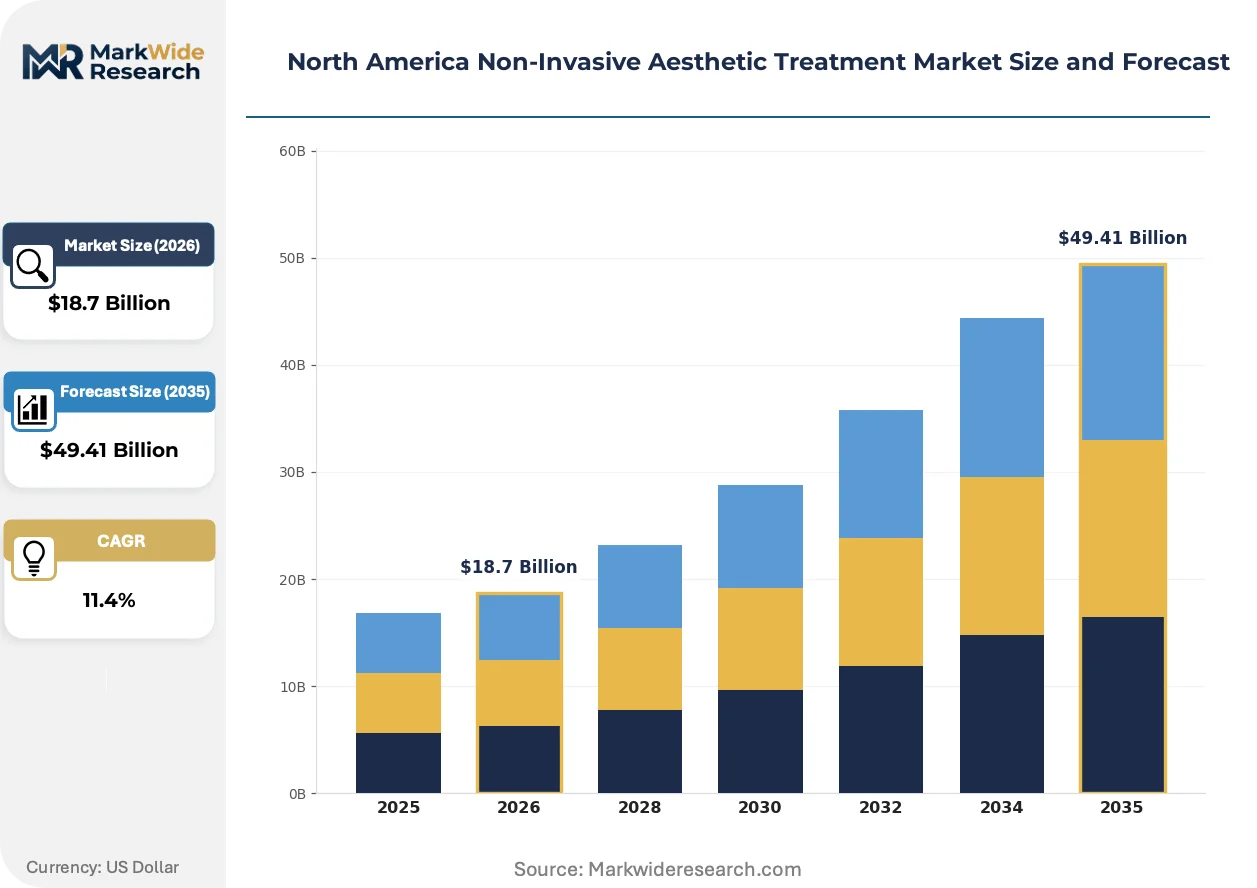
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectables, Laser Treatments, RF Devices, Chemical Peels Technology: Laser, Ultrasound, Radiofrequency, Cryolipolysis Customer Type: Clinics, Medspas, Hospitals, Home Users End User: Cosmetologists, Dermatologists, Surgeons, Aesthetic Practitioners |
| Companies Covered | Hologic, Bausch Health Companies, AbbVie, Lumenis, Cutera, Galderma, Johnson & Johnson, Cynosure, Merz Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Non-Invasive Aesthetic Treatment Market Strategic Shifts & Innovations
Intelligent energy delivery systems are restructuring treatment protocols toward algorithmic parameter optimization, while regulatory clarity on combination products and shifting patient acquisition channels reshape commercial architecture.
AI-guided treatment planning software is automating energy dosage calculations for fractional laser and RF platforms, reducing operator-dependent outcome variability. Medspa chains in Texas and Florida deploy these systems to standardize results across multi-location networks. The technology is automating clinical decision support functions previously requiring physician-level judgment, compressing training timelines for non-physician operators.
Health Canada's evolving device registration requirements for energy-based systems with integrated cooling mechanisms are extending pre-market review timelines. Manufacturers must demonstrate thermal injury prevention efficacy through expanded clinical datasets. RF platforms with cryogen spray integration face the most significant evidentiary burden, prompting firms to sequence launches in US markets first.
Direct-to-consumer booking platforms are disintermediating traditional dermatology referral channels, capturing patient acquisition economics previously retained by physician practices. California-based medspa operators now derive majority volume from Instagram and TikTok-driven discovery rather than professional referral. This channel shift concentrates marketing spend toward social proof generation and before-after content licensing.
North America Non-Invasive Aesthetic Treatment Market Segmentation
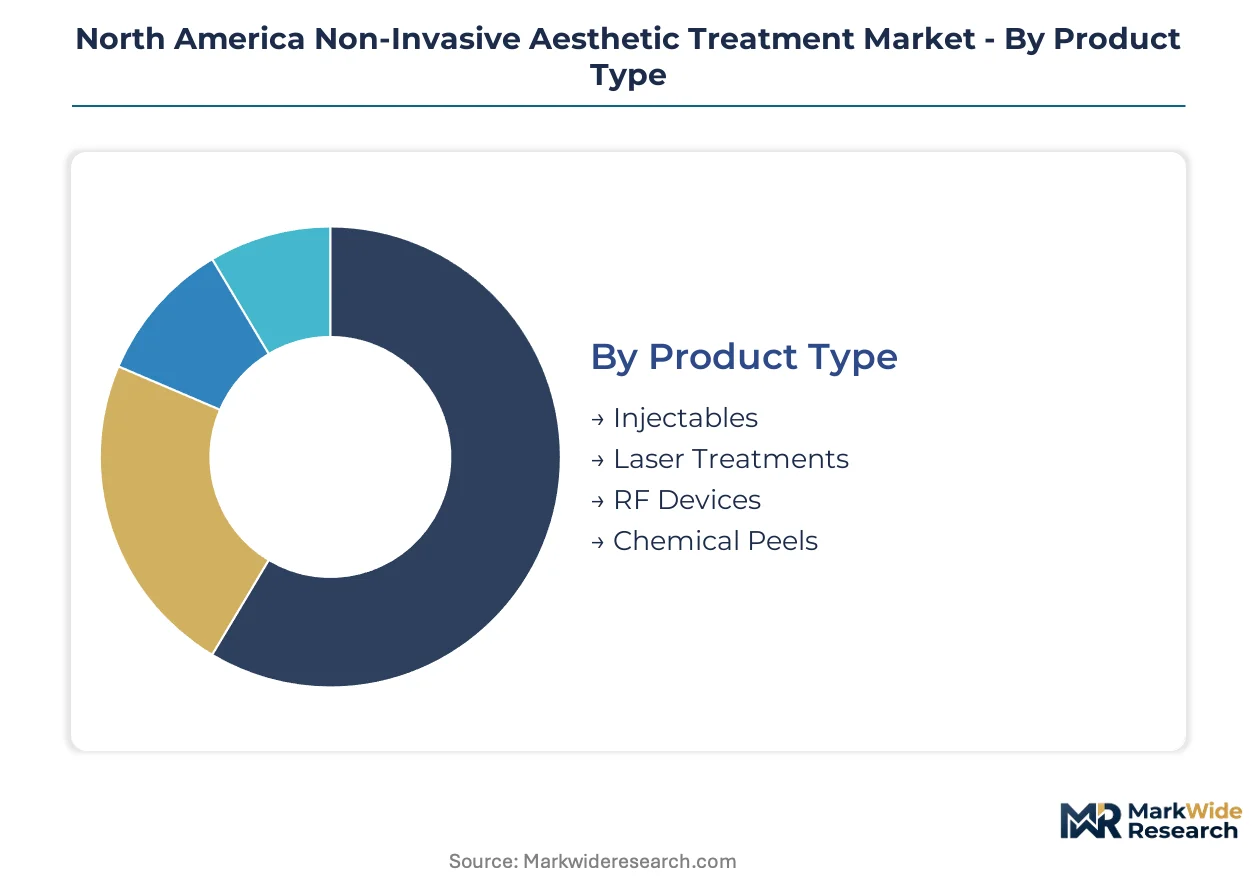
Segmentation in non-invasive aesthetic treatments reveals how capital intensity, regulatory burden, and operator credentialing reshape competitive boundaries across product categories. Understanding these divisions clarifies why injectables dominate recurring revenue while energy-based platforms concentrate in high-density metropolitan markets.
Product Type:
Volume leadership belongs to injectables with minimal equipment overhead, while premium positioning clusters around laser systems requiring substantial capital deployment and maintenance protocols.
- Injectables:Biocompatible compounds including hyaluronic acid fillers and biostimulators administered at specified tissue depths. Demand concentrates in Texas and Florida medspa chains where repeat purchase cycles sustain clinic revenue without equipment depreciation burdens.
- Laser Treatments:Energy delivery systems operating between 532 nm and 10,600 nm for skin resurfacing and hair removal. California dermatology practices command premium pricing where outcomes correlate directly with device specifications and FDA 510(k) clearance tier.
- RF Devices:Radiofrequency platforms with integrated temperature monitoring for tissue tightening protocols.
- Chemical Peels:Topical acid formulations for epidermal renewal requiring minimal capital investment.
Mature deployment sits with injectables. Newer deployment is concentrated in RF devices with real-time safety monitoring.
Technology:
Application focus separates surface-level interventions from subcutaneous tissue remodeling, with cryolipolysis occupying a distinct position in fat reduction protocols.
- Laser:Coherent light systems for precise thermal injury control in resurfacing and vascular applications. California clinic density supports the specialized training and maintenance infrastructure these platforms demand.
- Radiofrequency:Electromagnetic energy delivery with cryogen spray integration for dermal heating. Texas and Florida scope-of-practice expansions enable nurse practitioner operation of these systems outside traditional physician supervision models.
- Ultrasound:High-frequency acoustic energy for microfocused tissue lifting.
- Cryolipolysis:Controlled cooling protocols for adipocyte apoptosis without thermal damage.
Established clinical validation sits with laser. Expanding most quickly is radiofrequency with enhanced safety profiles.
Customer Type:
Channel structure differentiates institutional procurement with centralized decision-making from fragmented consumer-direct acquisition patterns.
- Medspas:Standalone retail and hotel-based wellness concepts capturing patient acquisition through direct-to-consumer booking platforms. Instagram and TikTok-driven discovery now generates majority volume in California markets, disintermediating traditional dermatology referrals.
- Clinics:Physician-supervised facilities with mixed laser and injectable portfolios facing workflow fragmentation across incompatible software systems.
- Hospitals:Reconstructive and post-surgical aesthetic support integrated with broader medical services.
- Home Users:Consumer-grade devices for low-intensity maintenance protocols outside clinical settings.
Volume concentration sits with medspas. Credentialing complexity is highest in hospitals.
End User:
Scope-of-practice boundaries determine which professional categories may independently operate energy-based devices versus supervise-only roles.
- Aesthetic Practitioners:Nurse practitioners and physician assistants operating under variable supervision ratios. Texas and Florida regulations permit independent practice for these operators, multiplying addressable provider bases in high-disposable-income metros.
- Dermatologists:Board-certified physicians with unrestricted device operation authority and legacy referral network control.
- Cosmetologists:Licensed professionals with limited scope restricted to topical and non-energy protocols.
- Surgeons:Physicians integrating non-invasive treatments with surgical aesthetic practice.
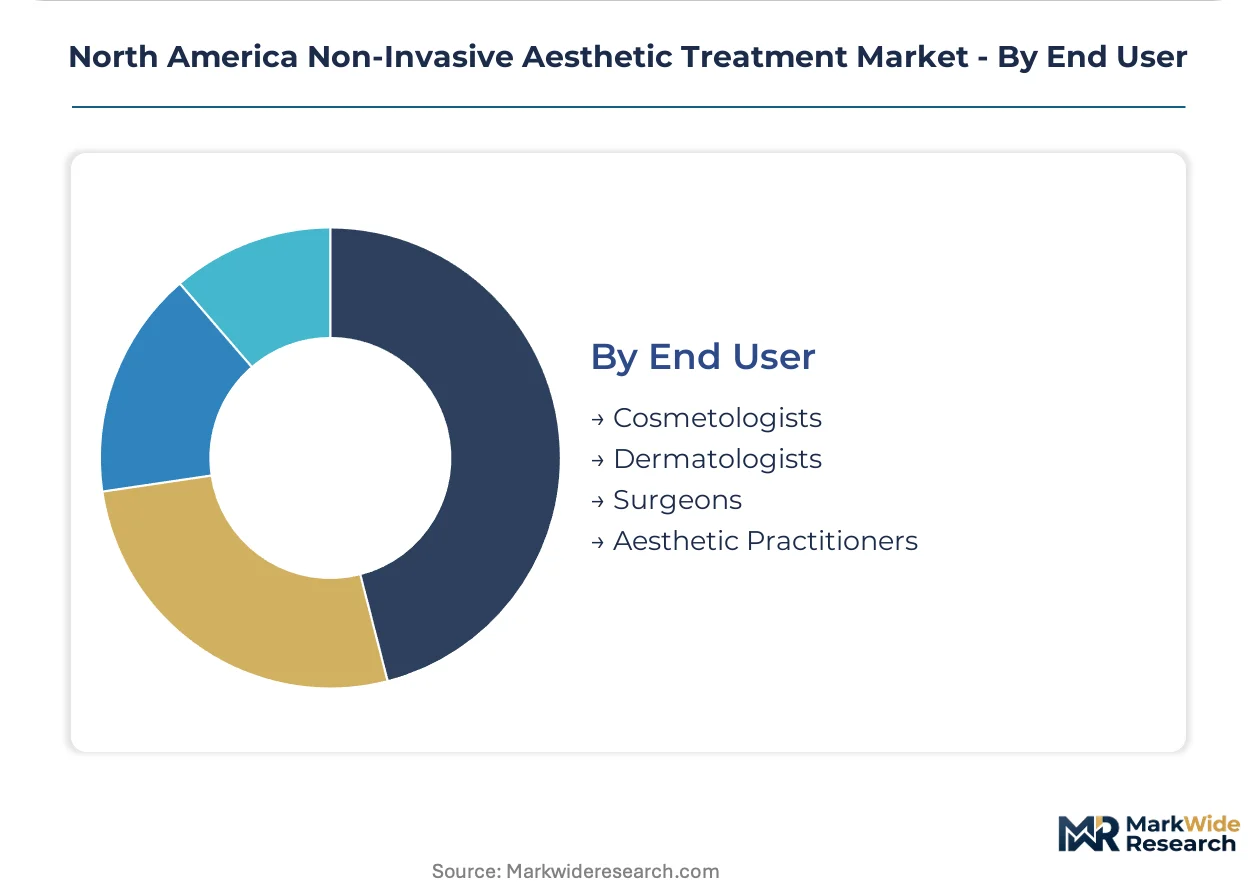
Regulatory expansion sits with aesthetic practitioners. Training standardization concentrates with dermatologists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity zones in Texas and Florida accelerate clinic concentration through state tax incentives for medical device deployment. California's aesthetic corridor generates premium procedure volumes despite tighter supervision requirements. Canadian provincial markets present expansion vectors for US-based medspa chains seeking regulatory arbitrage.
United States
Texas and Florida medspa chains capture younger demographics through standalone retail locations and hotel-based wellness concepts. FDA 510(k) pathway streamlining accelerates commercialization timelines for energy-based devices entering these markets. Miami and Los Angeles concentrate direct-to-consumer booking platform adoption, with Instagram and TikTok-driven discovery displacing traditional dermatology referrals.
California
Stricter physician oversight requirements from the California medical board limit treatment volume scalability despite highest disposable income levels. Los Angeles and San Francisco Bay Area command premium pricing for laser resurfacing where outcomes correlate with device specifications. AbbVie leverages its Allergan Aesthetics portfolio to sustain brand loyalty across injectable categories in this high-value market.
Texas
Scope-of-practice expansions for nurse practitioners and physician assistants multiply addressable provider bases in Houston and Dallas metros. RF platforms with real-time temperature monitoring deploy rapidly under independent practice regulations. Medspa density growth outpaces national averages as operators exploit lower supervision ratios and favorable commercial real estate costs.
Florida
Miami anchors hotel-based wellness integration with luxury hospitality channels creating new patient acquisition pathways. Injectable biostimulator demand sustains clinic revenue through repeat purchase cycles without capital equipment investment. State-level regulations permit expanded non-physician operation of energy-based devices, accelerating technology adoption timelines.
Canada
Ontario and British Columbia show underpenetrated medspa density relative to comparable US metropolitan markets. Health Canada's evolving device registration requirements for energy-based systems with integrated cooling mechanisms extend pre-market review timelines. Toronto and Vancouver concentrate reconstructive and post-surgical aesthetic support integrated with broader medical services.
North America Non-Invasive Aesthetic Treatment Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with injectable portfolios commanding recurring revenue streams and device manufacturers capturing premium pricing through technology differentiation. The market structure consolidates around pharmaceutical conglomerates with aesthetic divisions and specialized energy-based device fabricators. Three archetypes dominate: diversified healthcare conglomerates, pure-play aesthetic device specialists, and dermatology-focused pharmaceutical firms. Competitive moves concentrate on portfolio diversification through biostimulator development and geographic expansion into underpenetrated Canadian provincial markets.
Among diversified healthcare conglomerates, AbbVie and Johnson & Johnson occupy positions spanning injectable and device categories. Cutera and Lumenis exemplify pure-play energy-based device specialists with concentrated laser and RF platform development. Galderma and Merz Pharma sit within the dermatology-focused pharmaceutical tier, differentiating through biostimulator positioning against legacy hyaluronic acid formulations.
| Leading Market Players |
|---|
| Hologic |
| Bausch Health Companies |
| AbbVie |
| Lumenis |
| Cutera |
| Galderma |
| Johnson & Johnson |
| Cynosure |
| Merz Pharma |
| Others |
Cost & Logistics Intelligence
Medical-grade hyaluronic acid raw material indices cascade through North American contract manufacturing networks into three-tier pricing structures across premium, standard, and economy device tiers. Injectable biostimulator procurement costs in Texas and Florida medspa chains compress margins when FDA 510(k) clearance delays extend inventory carrying periods beyond typical depreciation cycles.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to RF device platforms with integrated temperature monitoring systems, while spot inventory of legacy laser modules trades at distressed valuations. Pricing stratifies across premium, standard, and economy tiers based on FDA clearance tier and geographic delivery cost from California assembly facilities. Cost compression in standard-tier injectables intensifies because biosimilar hyaluronic acid formulations multiply manufacturing sources. Hospital systems demonstrate least price sensitivity due to bundled reimbursement protocols, while independent medspa operators in Canadian markets exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements for critical optical components mandate multi-supplier qualification across German laser cavity manufacturers and Japanese RF generator specialists. Device assembly draws from Mexico, China, and domestic US facilities for cryogen spray canisters, sapphire delivery tips, and control system chipsets. Single-source vulnerability concentrates in high-power diode arrays from Taiwanese foundries. Distribution runs through direct manufacturer-to-clinic relationships in California and Texas, with Canadian provincial markets served through Health Canada-authorized distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American non-invasive aesthetic treatment markets are consolidating through vertical-integration races, with manufacturers pursuing backward integration into biostimulator compound production to capture margin pools currently retained by pharmaceutical subcontractors.
For Market Incumbents: Lock in exclusive supply agreements with German and Japanese optical component suppliers before capacity constraints tighten. Acquire FDA 510(k) consulting firms to compress clearance timelines for next-generation RF platforms. Biostimulator commoditization threatens pricing power; captive production of poly-L-lactic acid raw materials defends margin structures.
For New Entrants and Emerging Players: Hotel-based wellness concepts in Miami and Los Angeles represent underserved buyer archetypes with fragmented incumbent presence. Canadian provincial markets in Ontario and British Columbia offer lowest competitive density relative to comparable US metropolitan markets. Pursue direct-to-consumer booking platform partnerships rather than traditional dermatology referral channel penetration.
For Investors and Strategic Acquirers: The window for entry favors pure-play RF device specialists with real-time temperature monitoring IP portfolios. Long-term viability hinges on regulatory arbitrage capabilities across FDA and Health Canada parallel submission strategies. Watch Health Canada's evolving cooling mechanism registration requirements as the inflection indicator for Canadian market access timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compresses commercialization timelines for energy-based devices entering Texas and Florida medspa channels. |
| Biostimulator Manufacturing Scale-Up | Captures margin pools from poly-L-lactic acid and calcium hydroxylapatite compound production. |
| Hotel-Based Wellness Partnership | Creates patient acquisition pathways outside traditional dermatology referral networks in Miami and Los Angeles. |
| Health Canada Registration Pathway | Opens regulatory arbitrage opportunities in Ontario and British Columbia provincial markets. |
| AI-Guided Treatment Software Development | Standardizes outcomes across multi-location medspa networks in scope-of-practice expansion states. |
Research Approach
Document review covered FDA 510(k) clearance databases, Health Canada device registration filings, and state medical board supervision ratio regulations, complemented by interviews with medspa chain operations directors, biomedical engineers at laser device manufacturers, and GPO contracts managers at hospital systems. Secondary validation drew from CMS Medicare procedure volume data, SEC 10-K filings of publicly traded aesthetic device firms, and clinical trial registries for biostimulator formulations. Bottom-up clinic density modeling and top-down revenue aggregation triangulated market size estimates.
Cross-reference between historical FDA clearance velocity patterns and expert panel input on de novo pathway evolution shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology platform, customer channel, and end-user credentialing requirements. CAGRs derived from procedure volume growth rates correlated with disposable income indices and regulatory scope-of-practice expansion timelines. Forecast inputs incorporated real-time temperature monitoring adoption curves and social media-driven patient acquisition channel shifts.
Revisions become necessary when FDA guidance on combination product classifications materializes or when Health Canada extends pre-market review timelines for cryogen-integrated RF platforms. Deviation in Texas and Florida scope-of-practice regulations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Europe Dermal Fillers Market
Aesthetic Medicine
Spa Market
Aesthetic Medicine
Dermal Fillers and Botulinum Toxin Market
Aesthetic Medicine
Non-Invasive Aesthetic Treatment Market
Aesthetic Medicine
Global Cellulite Treatment Market
Aesthetic Medicine
Hirsutism Treatment Market
Aesthetic Medicine
Professional Beauty Services Market
Aesthetic Medicine
Platysmaplasty Treatment Market
Aesthetic Medicine
North America Aesthetic Dermatology Market
Aesthetic Medicine
Aesthetic Medicine Market
Aesthetic Medicine
Asia-Pacific Facial Aesthetics Market
Aesthetic Medicine
Non-Invasive Fat Reduction Market
Aesthetic Medicine
Colombia Facial Aesthetics Market
Aesthetic Medicine
Global Aesthetic Dermatology Market
Aesthetic Medicine
Aesthetic Medicine and Cosmetic Surgery Market
Aesthetic Medicine
Japan Facial Aesthetics Market