
 Head and Neck Cancer Market | 2026-2036
Head and Neck Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Head and Neck Cancer Market Intelligence
Biologics manufacturing capacity in North America and Western Europe is hardening as multi-product facilities face scheduling constraints for checkpoint inhibitor production. Merck & Co., Inc. leverages its Keytruda franchise to dominate PD-1 positioning in first-line recurrent or metastatic disease. Bristol-Myers Squibb Company anchors its portfolio through Opdivo combinations, while AstraZeneca competes with durvalumab-tremelimumab regimens in the locally advanced setting.
Head and neck cancer comprises malignancies arising from the oral cavity, pharynx, larynx, paranasal sinuses, and salivary glands, with squamous cell carcinoma representing over ninety percent of cases and HPV-driven oropharyngeal subsets exhibiting distinct molecular profiles and treatment sensitivities. Immunotherapy now leads product type dynamics as PD-1/PD-L1 inhibitors displace platinum-doublet chemotherapy in frontline metastatic indications, while radiation therapy sustains its structural role through intensity-modulated and proton platforms that preserve organ function. Targeted therapy occupies narrower but higher-margin pools through EGFR-directed agents in cetuximab-eligible populations.
FDA breakthrough therapy designation and EMA conditional marketing authorization frameworks compress development timelines but intensify post-approval evidence requirements for overall survival endpoints. The EU MDR and FDA's evolving real-world evidence standards are forcing sponsors to integrate patient-reported outcome measures into registrational trials. Stakeholders must monitor how CMS and national health technology assessment bodies weigh progression-free survival against quality-of-life metrics in reimbursement decisions for combination immuno-oncology regimens.
Market Dynamics
The transition from platinum-doublet chemotherapy to PD-1/PD-L1 checkpoint inhibitors as first-line standard of care is compressing treatment paradigms and forcing hospital-based oncology departments to restructure staffing, infusion capacity, and reimbursement workflows around immuno-oncology delivery models.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The accelerated approval pathway compresses Phase II-to-commercialization timelines for novel checkpoint inhibitors, enabling earlier patient access and faster revenue realization for sponsors.
- HPV-driven oropharyngeal subsets:Distinct molecular profiles in this patient population demonstrate enhanced immunotherapy sensitivity, expanding addressable pools beyond traditional smoking-related cohorts.
- Intensity-modulated radiotherapy platforms:Precision dose delivery preserves organ function in locally advanced disease, sustaining structural demand for combination regimens with systemic agents.
Market Restraints
- Biologics manufacturing bottlenecks:Multi-product facilities in North America and Western Europe face scheduling constraints for checkpoint inhibitor production, limiting supply elasticity.
- EMA conditional marketing authorization evidence requirements:Post-approval obligations for overall survival endpoints intensify trial costs and extend development risk windows.
- Platinum-doublet chemotherapy displacement:Established reimbursement pathways and clinical familiarity with cytotoxic regimens create inertia against rapid immuno-oncology adoption in community oncology settings.
Strategic Opportunities
- Japan's aging demographics:Elevated incidence of head and neck malignancies in this population creates concentrated demand for organ-preserving combination therapies.
- Patient-reported outcome integration:CMS and national health technology assessment bodies are weighting quality-of-life metrics more heavily, creating differentiation opportunities for sponsors with robust PRO data packages.
- Real-world evidence frameworks:FDA's evolving standards for post-market surveillance enable label expansion through observational studies rather than randomized controlled trials alone.
Industry Challenges
- Immuno-oncology nursing specialization:Management of immune-related adverse events requires dedicated training programs that community hospitals struggle to fund and staff.
- EU MDR technical documentation:In-vitro diagnostic companion devices for PD-L1 testing face extended conformity assessment timelines, delaying coordinated therapy launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Head and Neck Cancer Market |
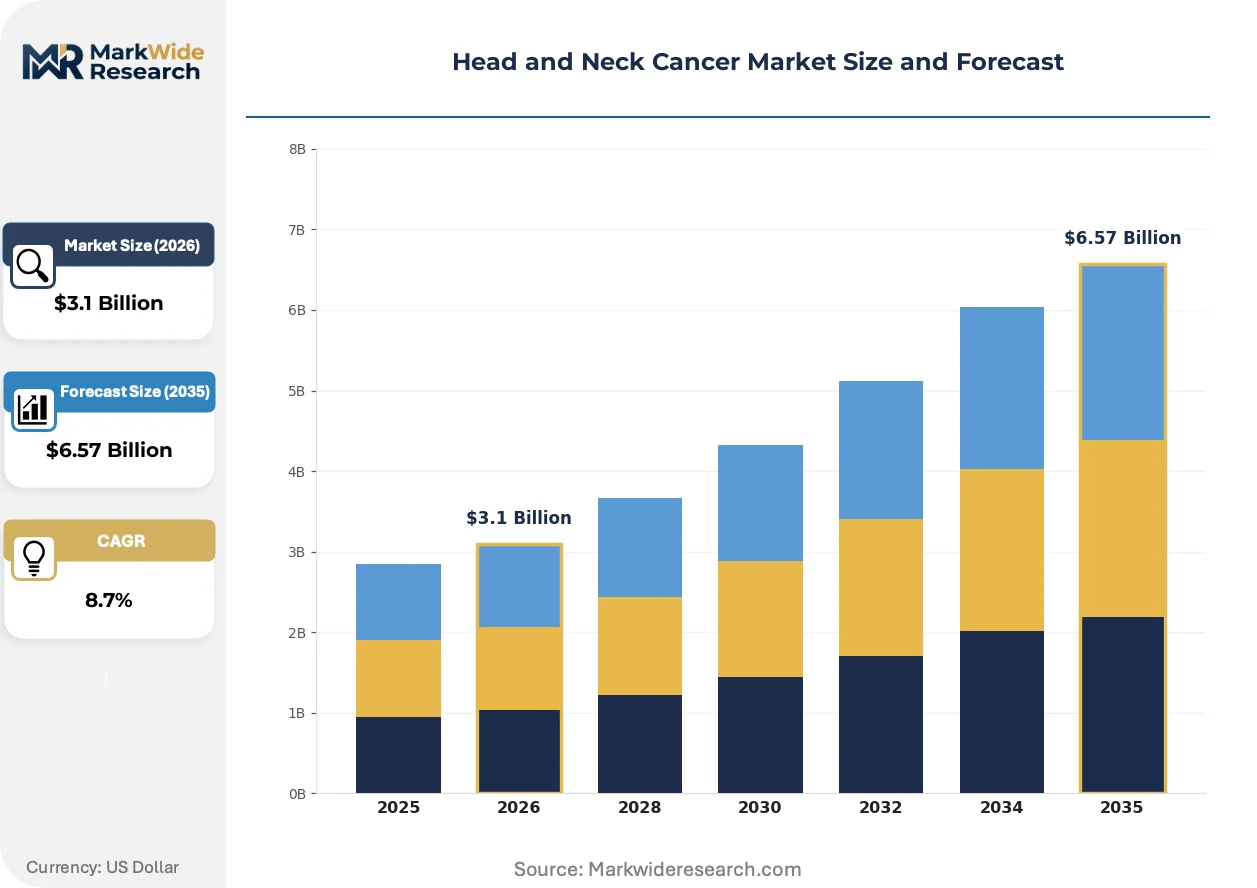
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.57 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Radiation Therapy, Targeted Therapy End User: Hospitals, Outpatient Clinics, Cancer Research Institutes, Ambulatory Surgical Centers Treatment Type: Surgery, Chemoradiotherapy, Palliative Care, Reconstructive Surgery Stage: Early Stage, Locally Advanced Stage, Metastatic Stage, Recurrent Stage |
| Companies Covered | Merck & Co., Inc., Bristol-Myers Squibb Company, Eli Lilly and Company, Sanofi, AstraZeneca, F. Hoffmann-La Roche Ltd., Takeda Pharmaceutical Company Limited, Teva Pharmaceutical Industries Ltd., Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Head and Neck Cancer Market Strategic Shifts & Innovations
Artificial intelligence applications are penetrating every stage of head and neck cancer care, from radiomics-based treatment planning to real-world evidence generation, compressing decision cycles and forcing traditional stakeholders to restructure service delivery models around data-centric workflows.
Deep learning algorithms trained on CT and MRI datasets are automating tumor segmentation and nodal staging assessments, reducing inter-observer variability in radiation oncology departments. Academic medical centers in the United States and Germany are deploying these tools for routine contouring, cutting planning time from hours to minutes. This compression is automating workflow standardization across previously siloed hospital systems and enabling centralized expertise models.
EMA's Medical Device Regulation is tightening clinical evidence requirements for software-as-medical-device applications in oncology diagnostics, forcing AI developers to conduct prospective validation studies. The regulation is diverting R&D budgets from algorithm refinement to regulatory compliance infrastructure. Radiotherapy planning software vendors with European market exposure are responding by embedding clinical affairs functions earlier in product development cycles.
Hospital procurement committees are consolidating vendor relationships around integrated platform contracts that bundle imaging, pathology, and treatment planning systems. This bundling is displacing point-solution purchasing patterns that dominated the 2010s. Germany's university hospital networks are pioneering these consolidated agreements, pressuring specialized software vendors to either integrate or exit the market.
Head and Neck Cancer Market Segmentation
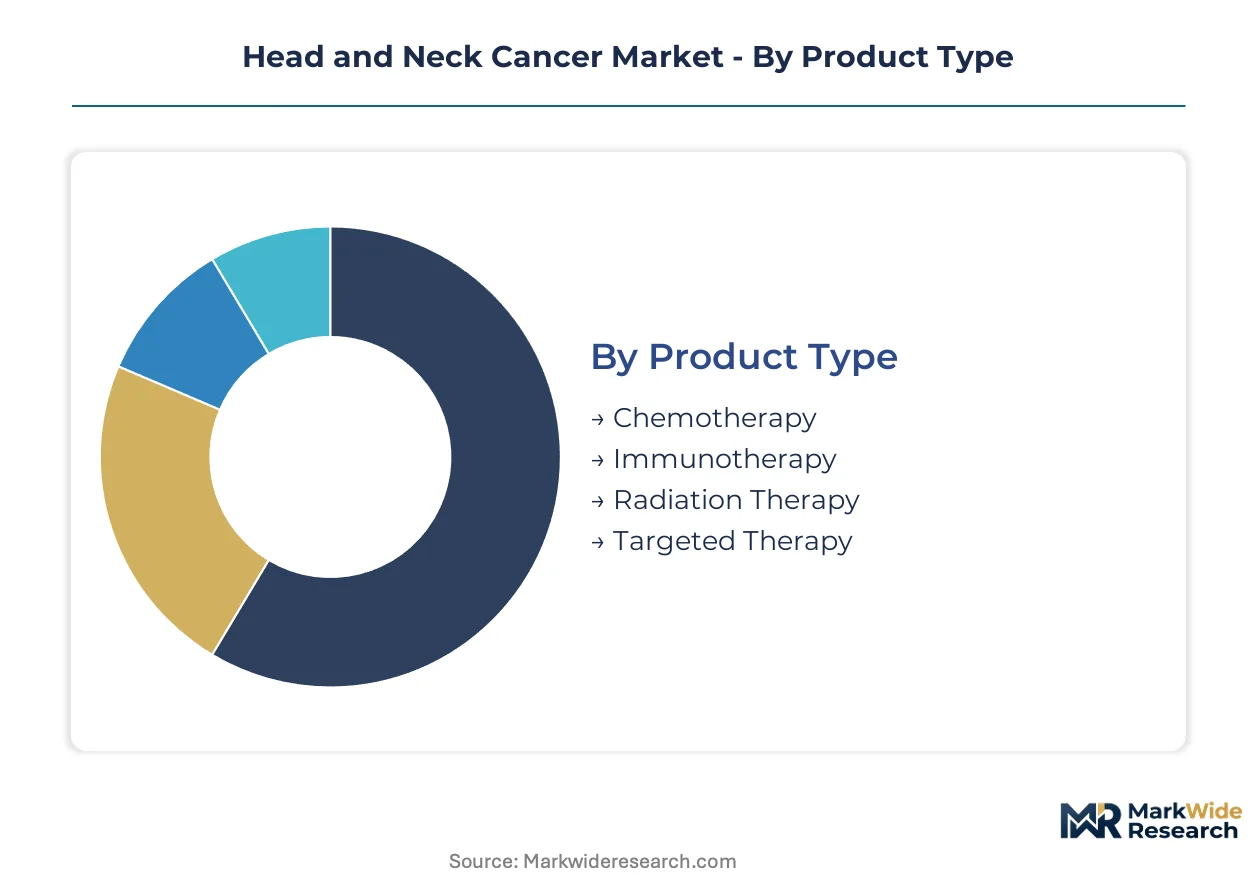
Segmentation in head and neck cancer care reveals how treatment modalities, care settings, and disease stages concentrate purchasing power and dictate infrastructure requirements. Understanding these divisions exposes where biologics manufacturing capacity, specialized nursing expertise, and reimbursement frameworks face the greatest strain.
Product Type:
Supply concentration for active pharmaceutical ingredients and radiotherapy isotopes clusters around multi-product facilities in North America and Western Europe, creating scheduling bottlenecks that favor sponsors with vertical integration or captive manufacturing networks.
- Immunotherapy:PD-1/PD-L1 checkpoint inhibitors now anchor first-line recurrent or metastatic protocols, displacing platinum-doublet chemotherapy through FDA breakthrough therapy designations that compress commercialization timelines. Demand concentrates in hospital-based oncology departments across the United States, Germany, and Japan, where reimbursement pathways for novel biologics have matured fastest.
- Radiation Therapy:Intensity-modulated and proton platforms deliver precision dose distributions that preserve organ function in locally advanced disease, sustaining structural demand despite capital intensity. Germany's university hospital networks and Japan's aging demographics drive adoption of integrated imaging-planning-treatment systems that bundle vendor relationships.
- Chemotherapy:Platinum-doublet regimens retain residual share in community oncology settings where clinical familiarity and established reimbursement pathways create adoption inertia against immuno-oncology transition.
- Targeted Therapy:EGFR-directed agents serve narrower but higher-margin pools in cetuximab-eligible populations with specific molecular profiles.
Today's leader: Immunotherapy. Tomorrow's challenger: Radiation Therapy.
End User:
Cost tier stratification across care settings determines staffing models, infusion capacity investments, and procurement committee priorities, with academic medical centers commanding premium pricing for complex combination regimens.
- Hospitals:Hospital-based oncology departments absorb the majority of advanced-stage patients requiring combination immuno-oncology delivery, driving demand for specialized nursing training and immune-related adverse event management protocols. CMS reimbursement frameworks and EMA health technology assessment bodies in Germany weight progression-free survival against quality-of-life metrics in purchasing decisions.
- Cancer Research Institutes:These institutions concentrate early-phase clinical trial enrollment for checkpoint inhibitor combinations, generating real-world evidence that feeds FDA and EMA accelerated approval pathways.
- Outpatient Clinics:Community settings face staffing constraints for immuno-oncology specialization, limiting rapid adoption despite patient convenience preferences.
- Ambulatory Surgical Centers:Narrow procedural focus restricts these facilities to selected early-stage surgical interventions and reconstructive procedures.
Volume concentrates in Hospitals. Margin expansion concentrates in Cancer Research Institutes.
Treatment Type:
Application-specific workflow requirements dictate capital deployment patterns, with multimodal approaches demanding coordinated investments across surgical, medical, and radiation oncology disciplines.
- Chemoradiotherapy:Concurrent systemic and radiation delivery remains standard for locally advanced disease, requiring synchronized scheduling of infusion capacity and linear accelerator time that strains hospital resource coordination. The United States and Germany lead protocol standardization through academic consortiums that define organ-preservation endpoints.
- Surgery:Resection protocols for early-stage disease concentrate in high-volume centers where robotic and minimally invasive platforms differentiate patient outcomes and referral patterns.
- Palliative Care:Symptom-focused interventions address quality-of-life metrics that CMS and national health technology assessment bodies increasingly weight in reimbursement frameworks for advanced disease.
- Reconstructive Surgery:Microvascular free flap procedures restore function following ablative resections, concentrating in tertiary centers with specialized plastic surgery infrastructure.
Standard of care: Chemoradiotherapy. Fastest protocol evolution: Palliative Care integration.
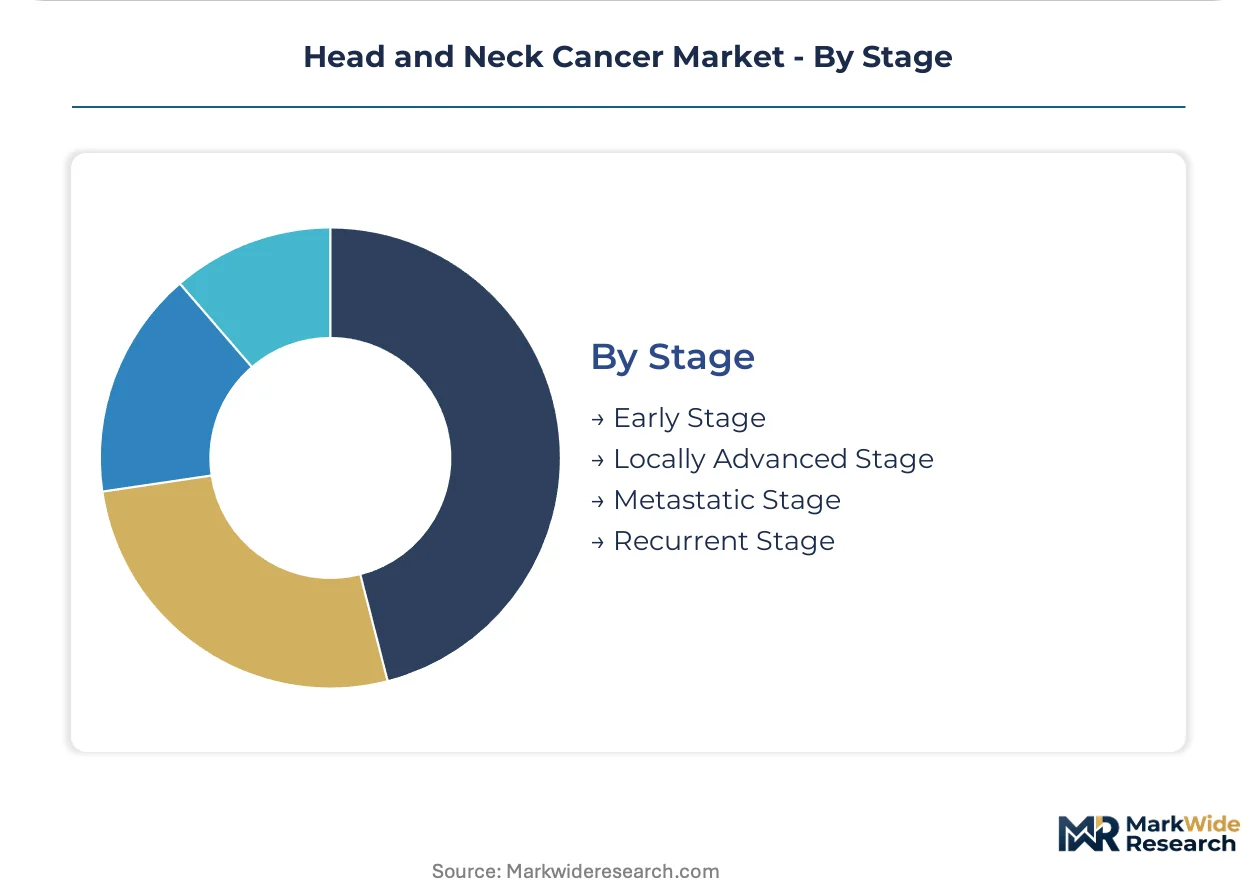
Stage:
Customer type differentiation across disease progression dictates therapy intensity, with metastatic and recurrent populations driving biologics consumption while early-stage patients concentrate surgical and radiation therapy demand.
- Metastatic Stage:First-line PD-1/PD-L1 inhibitor eligibility has redefined this population's treatment paradigm, with HPV-driven oropharyngeal subsets demonstrating enhanced immunotherapy sensitivity that expands addressable pools beyond traditional smoking-related cohorts. FDA accelerated approval pathways enable earlier commercial access for sponsors.
- Locally Advanced Stage:Organ-preservation strategies combining radiation with systemic agents dominate this segment, with AstraZeneca's durvalumab-tremelimumab regimens competing for positioning against established chemoradiotherapy protocols.
- Early Stage:Surgical resection with or without adjuvant radiation retains curative intent focus, concentrating in centers with minimally invasive expertise.
- Recurrent Stage:Salvage protocols face limited evidence bases, creating uncertainty in reimbursement negotiations and clinical trial design.
Commercial gravity centers on Metastatic Stage. Unmet need concentrates in Recurrent Stage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologics manufacturing migrates toward jurisdictions with streamlined regulatory pathways, as FDA breakthrough therapy designations and EMA conditional marketing authorizations compress development timelines and reshape facility location decisions.
United States
Hospital-based oncology departments absorb advanced-stage patients requiring combination immuno-oncology delivery, driving demand for specialized nursing infrastructure. FDA accelerated approval pathways enable earlier commercial access for checkpoint inhibitor sponsors. The Greater Boston and San Francisco Bay Area biotech clusters concentrate Phase I-II trial enrollment and manufacturing facility investments.
Germany
University hospital networks pioneer integrated platform contracts bundling imaging, pathology, and treatment planning systems. EMA health technology assessment bodies weight progression-free survival against quality-of-life metrics in reimbursement negotiations for combination regimens. The Munich and Heidelberg medical technology corridors anchor proton therapy platform deployment and radiomics software development.
Japan
Aging demographics elevate head and neck malignancy incidence, creating concentrated demand for organ-preserving combination therapies. PMDA regulatory frameworks align with FDA standards for immuno-oncology approval, accelerating cross-border trial data acceptance. The Tokyo-Osaka corridor concentrates radiation therapy infrastructure and biologics import distribution networks.
United Kingdom
NHS England's specialized commissioning frameworks concentrate complex head and neck cancer care in designated tertiary centers, consolidating referral patterns and procurement authority. MHRA post-Brexit regulatory autonomy enables tailored accelerated access pathways for novel biologics. The London-Southeast and Manchester clusters host the majority of clinical trial units and proton beam therapy capacity.
India
Domestic pharmaceutical manufacturing expands API and biosimilar production for export markets, leveraging CDSCO streamlined approval pathways for oncology generics. Cost-of-care differentials attract medical tourism for reconstructive surgery following ablative resections. The Hyderabad and Ahmedabad pharmaceutical manufacturing belts concentrate contract manufacturing organization capacity for global sponsors.
Head and Neck Cancer Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue radiomics software and AI-enabled treatment planning adjacent spaces. The vendor base stratifies across three tiers: multinational biopharmaceuticals with checkpoint inhibitor franchises, specialized radiation therapy equipment manufacturers, and diagnostic platform developers. Three archetypes dominate: immuno-oncology specialists, precision radiotherapy integrators, and real-world evidence aggregators. Competitive moves concentrate on strategic partnerships combining biologics with companion diagnostics, and geographic expansion into Japan's aging demographic markets.
Within the immuno-oncology tier, Merck & Co., Inc. and Bristol-Myers Squibb Company exemplify established checkpoint inhibitor positioning, while AstraZeneca occupies a differentiated position through dual-agent combination regimens in locally advanced settings. These three anchors represent contrasting strategic postures: single-agent dominance, combination portfolio breadth, and dual-immunotherapy innovation.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| Eli Lilly and Company |
| Sanofi |
| AstraZeneca |
| F. Hoffmann-La Roche Ltd. |
| Takeda Pharmaceutical Company Limited |
| Teva Pharmaceutical Industries Ltd. |
| Novartis |
| Others |
Cost & Logistics Intelligence
EMA's Medical Device Regulation gates qualified supply for AI-enabled radiotherapy planning software and premium-tier pricing access for proton therapy platforms that bundle imaging and treatment systems. Hospital procurement committees in Germany and the United States now demand MDR-compliant technical documentation as a threshold condition for vendor qualification, compressing the supplier base and concentrating pricing power among integrated platform providers.
Pricing Analysis
Direct-to-hospital contracting discounts dominate the checkpoint inhibitor segment, with Merck and Bristol-Myers Squibb leveraging volume commitments to secure formulary placement against emerging dual-immunotherapy regimens. Price differentiation rests on FDA breakthrough therapy designation status and companion diagnostic bundling. Cost compression in the chemotherapy residual tier intensifies as platinum-doublet protocols face displacement pressure from PD-1/PD-L1 frontline adoption. Community oncology settings exhibit highest price sensitivity due to reimbursement lag and staffing constraints for immune-related adverse event management.
Supply Chain Analysis
Reverse-logistics flows for radiotherapy isotopes and expired biologics remain underdeveloped, creating compliance cost burdens for hospital pharmacies managing cold-chain returns. Active pharmaceutical ingredient production concentrates in India, China, and Switzerland, with checkpoint inhibitor drug substance manufacturing anchored in North American and Western European multi-product facilities. Supply chain risk centers on single-source vulnerability for monoclonal antibody cell lines and sterile fill-finish capacity. Distribution runs through specialized oncology distributors with temperature-controlled infrastructure and GMP-certified warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
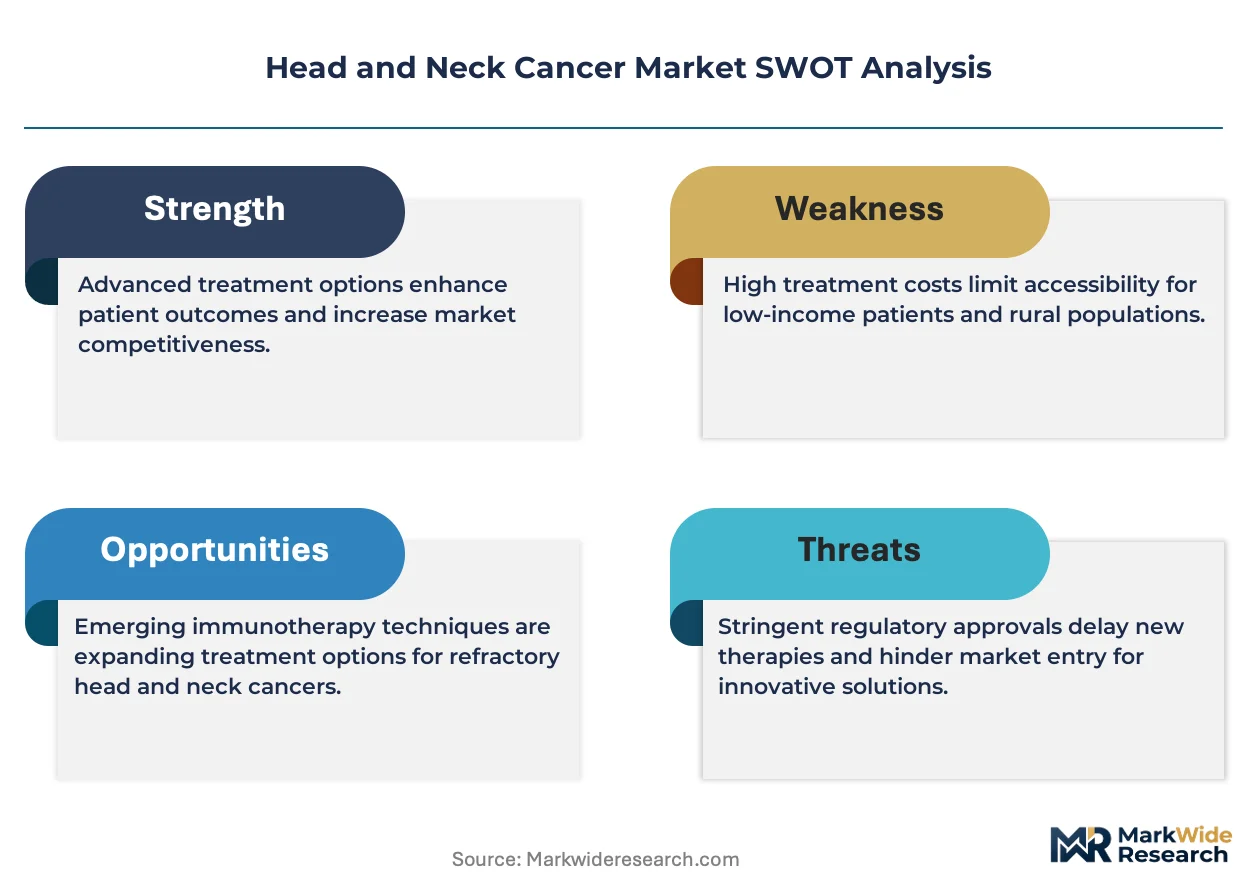
The Head and Neck Cancer Market functions as a regulatory compounder, with FDA breakthrough therapy designations and EMA conditional marketing authorizations accelerating commercial access while intensifying post-approval evidence obligations that reshape competitive economics.
For Market Incumbents: Deploy backward integration into biologics drug substance manufacturing to mitigate scheduling constraints at multi-product CMO facilities. Incorporate patient-reported outcome measures into registrational trials to defend positioning against AstraZeneca's dual-immunotherapy challenge in locally advanced settings. Lock in proton therapy platform partnerships with Germany's university hospital networks before AI-enabled planning software consolidates vendor relationships.
For New Entrants and Emerging Players: Launch via real-world evidence generation partnerships with cancer research institutes to bypass traditional randomized controlled trial barriers for label expansion. Target Japan's aging demographic corridor with organ-preserving combination therapy protocols that align with PMDA regulatory standards. Pursue radiomics software development for automated tumor segmentation as the most penetrable adjacent space before EMA MDR compliance costs escalate.
For Investors and Strategic Acquirers: Roll-up economics work for AI-enabled radiotherapy planning specialists because hospital procurement committees are consolidating vendor relationships around integrated platform contracts. Monitor FDA accelerated approval conversions to full approval based on overall survival endpoints as the critical inflection signal for checkpoint inhibitor franchise valuations. Favor targets with proprietary PD-L1 companion diagnostic coordination and established CMS reimbursement pathways.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Checkpoint inhibitor combinations in HPV-driven oropharyngeal subsets expand addressable pools beyond smoking-related cohorts. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses Phase II-to-commercialization timelines for novel immuno-oncology agents. |
| Manufacturing Scale-Up | Captive biologics capacity in North America reduces scheduling constraints at multi-product CMO facilities. |
| Platform Integration | Bundled imaging-pathology-treatment planning contracts consolidate procurement authority in Germany's university hospital networks. |
| Reimbursement Strategy | CMS and EMA health technology assessment integration of patient-reported outcomes differentiates combination regimens. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down market sizing triangulated volume and value estimates across treatment lines and regional regulatory clusters.
Historical reference periods anchored the projection horizon through documented protocol adoption curves for platinum-doublet chemotherapy displacement and checkpoint inhibitor penetration rates. The analytical framework modeled segmentation across treatment setting, disease stage, and molecular profile subsets. CAGRs derived from fitted adoption curves and pricing trajectory assumptions, with immuno-oncology nursing capacity constraints and biologics manufacturing throughput serving as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated immuno-oncology adoption or prolonged platinum-doublet chemotherapy residual share. Practitioners should monitor FDA accelerated approval conversion rates, EMA MDR compliance timelines for companion diagnostics, and CMS quality-of-life metric weighting in reimbursement decisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
North America Proton Therapy Market
Oncology
Global Metastatic Cancer Treatment Market
Oncology
Tumor Lysis Syndrome Treatment Market
Oncology
US Veterinary Oncology Market
Oncology
Tumor Embolization Market
Oncology
Throat Cancer Market
Oncology
Paraneoplastic Syndromes Market
Oncology
Radiation Therapy Software Market
Oncology
Angiosarcomas Treatment Market
Oncology
Bone Cancer Treatment Market
Oncology
Europe Radiotherapy Patient Positioning Market
Oncology
PD1 Non-Small Cell Lung Cancer Treatment Market
Oncology
Oncology Market
Oncology
Gallbladder Cancer Treatment Market
Oncology
US Radiation Oncology Market
Oncology
Global Interventional Oncology Market