
 Probiotics After Antibiotic Recovery Market | 2026-2036
Probiotics After Antibiotic Recovery Market Size, Share, and Industry Trends Forecast 2026-2036
Probiotics After Antibiotic Recovery Market Analytics
Denmark is tilting toward specialized fermentation capacity for medical-grade probiotic strains. Chr. Hansen Holding A/S anchors this Nordic cluster through its decades-long culture collection and strain banking infrastructure. BioGaia AB differentiates via its L. reuteri-focused pediatric positioning and pharmacy-level prescription support programs. Probi AB competes through clinically validated strain combinations targeting gastrointestinal recovery protocols.
Probiotics after antibiotic recovery comprise live microbial preparations administered following antibacterial therapy to restore commensal gut flora, typically formulated with colony-forming units ranging from 1 billion to 100 billion per dose and requiring cold-chain stability for viability preservation. Their primary purpose centers on reducing antibiotic-associated diarrhea incidence and accelerating microbiome diversity restoration. Capsules dominate volume due to moisture-barrier protection and precise dosing, while gummies represent the fastest-expanding format as palatability drives pediatric and geriatric compliance. Among applications, digestive health commands the largest revenue pool, though immune support claims are gaining regulatory scrutiny across multiple jurisdictions.
The FDA oversees probiotic labeling as dietary supplements under DSHEA, while EFSA evaluates health claim substantiation through its qualified health claims pathway, and Japan's Ministry of Health, Labour and Welfare regulates FOSHU-designated products with post-antibiotic recovery positioning. These frameworks collectively elevate the barrier for clinical evidence requirements and channel market access toward substantiated formulations. Stakeholders must monitor evolving strain-specific patent landscapes and pharmacy reimbursement tier negotiations as differentiation shifts from generic CFU counts to documented microbiome restoration endpoints.
Market Dynamics
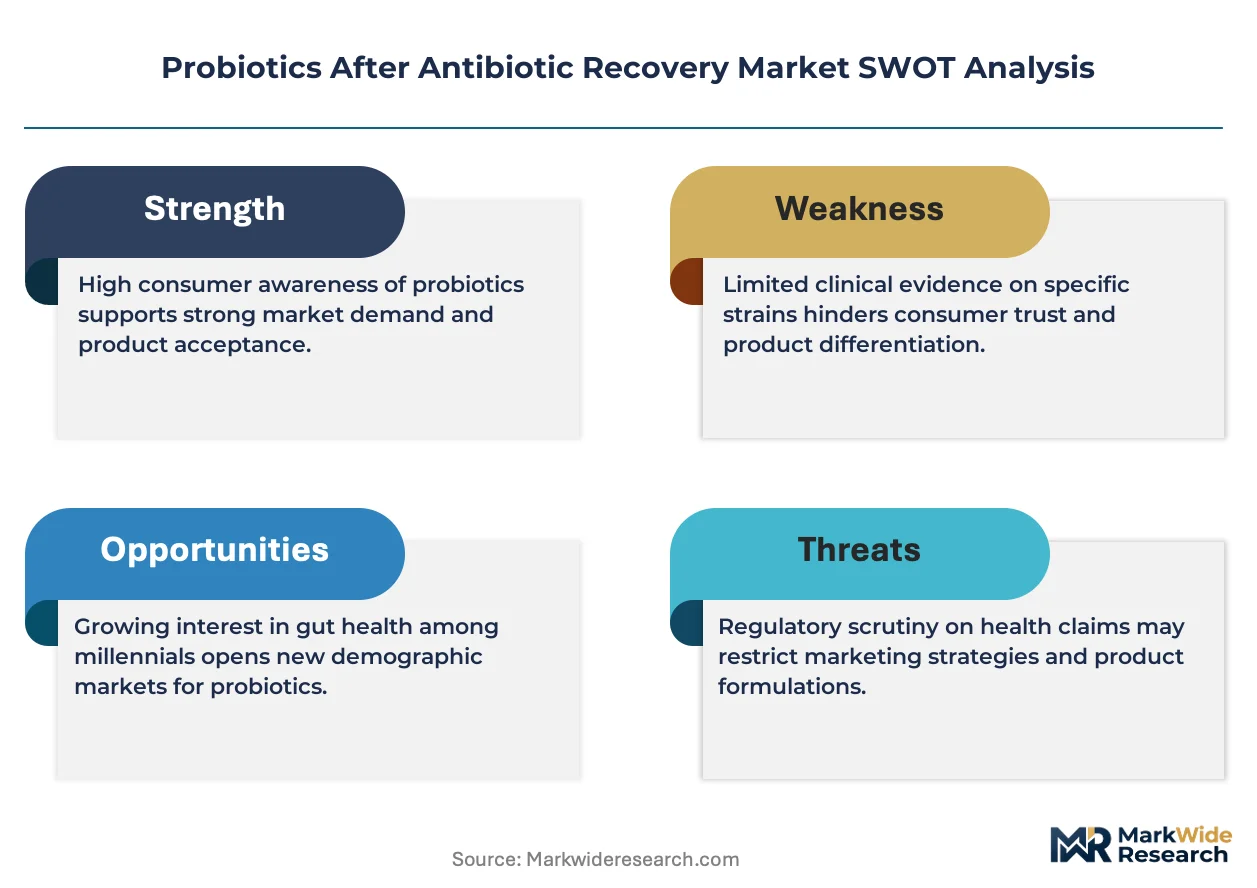
EFSA's tightened health claims substantiation requirements for live cultures are compressing formulation margins and forcing manufacturers toward clinical trial investments that smaller strain developers cannot absorb.
Growth Catalysts
- Japan's FOSHU pathway:The Ministry of Health, Labour and Welfare's functional food designation normalizes post-antibiotic recovery positioning, creating regulatory precedent that accelerates pharmacy channel adoption.
- Pediatric discharge protocols:German outpatient clinics now standardize probiotic supplementation upon antibiotic course completion, embedding consumption into medical workflow.
- Strain banking infrastructure:Decades-long culture collections enable rapid clinical validation pipelines, shortening time-to-market for microbiome-targeted formulations.
Market Restraints
- Cold-chain dependency:Viability preservation requirements lock distribution into refrigerated logistics networks that inflate last-mile costs and limit rural penetration.
- EFSA substantiation barriers:The qualified health claims pathway demands strain-specific clinical evidence that generic CFU-count formulations cannot satisfy, excluding commodity producers.
- Live culture instability:Moisture and temperature sensitivity during manufacturing creates batch-to-batch potency variation that complicates dosing standardization.
Strategic Opportunities
- Geriatric compliance formats:Palatability-driven gummy formulations address swallowing difficulties in aging populations, unlocking pharmacy segments previously resistant to capsule products.
- Pharmacy reimbursement tiers:Negotiated prescription support programs in Nordic markets shift probiotics from wellness to medical adjacency, expanding addressable spend pools.
- Immune support positioning:Regulatory scrutiny of digestive health claims is redirecting R&D investment toward immune modulation endpoints with clearer biomarker pathways.
Industry Challenges
- Microbiome assay standardization:Lack of consensus on diversity restoration endpoints complicates clinical trial design and cross-study comparability.
- Strain-specific patent navigation:Overlapping intellectual property claims on Lactobacillus and Bifidobacterium isolates create licensing friction for multi-strain combinations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Probiotics After Antibiotic Recovery Market |
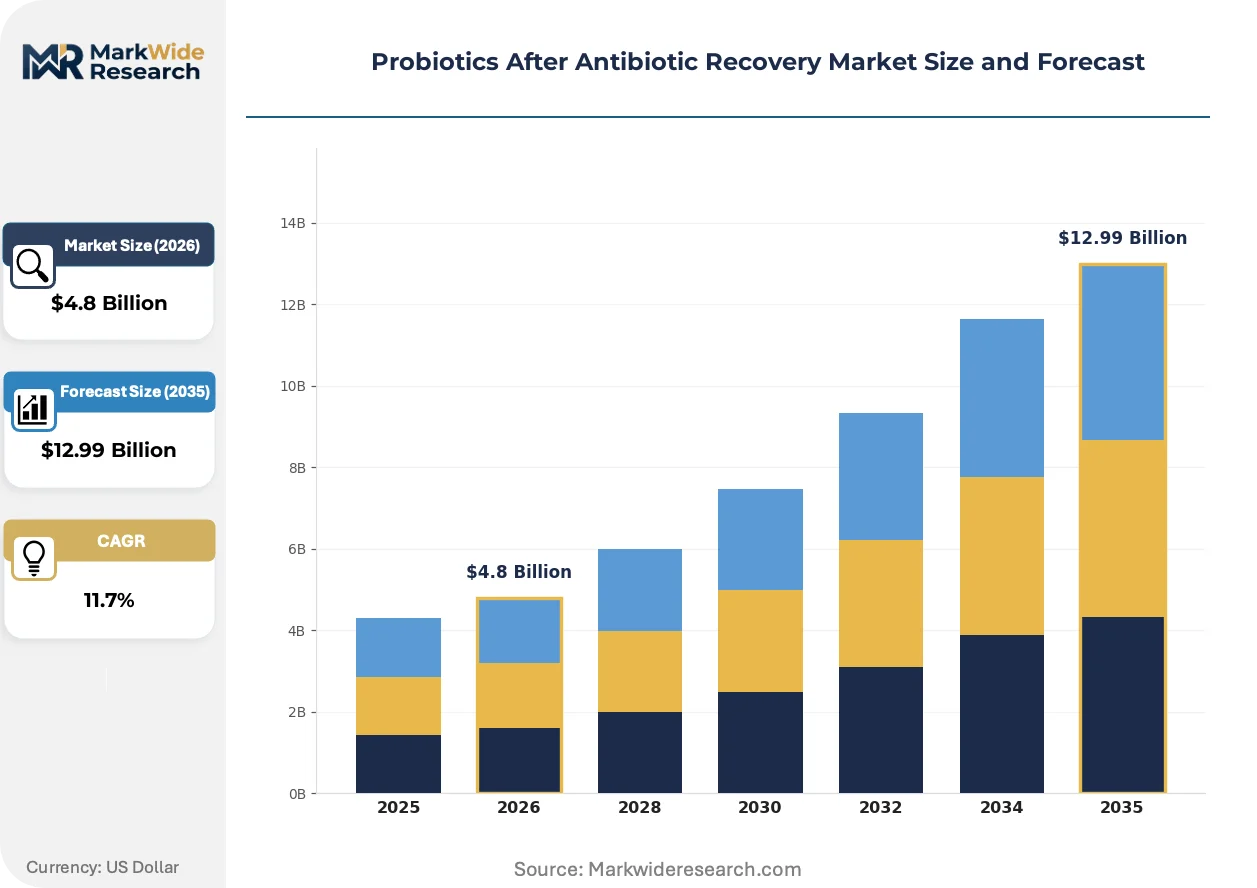
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powders, Gummies, Liquid End User: Patients, Healthcare Providers, Pharmacies, Nutraceutical Companies Dosage Form: Oral, Sublingual, Enteral, Topical Application: Digestive Health, Immune Support, Mental Wellbeing, Weight Management |
| Companies Covered | BioGaia AB, Chr. Hansen Holding A/S, Probi AB, DuPont de Nemours Inc, Danone S.A, Nestlé S.A, Lallemand Inc, Yakult Honsha Co Ltd, Kerry Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Probiotics After Antibiotic Recovery Market Evolving Landscape
Formulation science is hybridizing delivery technologies with microbiome analytics to create dose-response models that tie specific strains to measurable flora restoration outcomes.
Multi-layer encapsulation technology is hybridizing moisture-barrier protection with targeted release mechanisms. Pediatric and geriatric segments are adopting these formats fastest due to taste-masking capabilities and reduced gastric acid degradation. The technology is hybridizing competitive positioning away from raw CFU counts toward documented survival rates through simulated digestion models.
EFSA's updated guidance on live cultures is elevating evidence thresholds for post-antibiotic recovery claims. Manufacturers must now submit strain-specific human intervention studies rather than generic gastrointestinal health data. Capsule and powder categories face the steepest compliance costs, while medical-grade fermentation outputs gain relative positioning strength.
Hospital discharge protocols are embedding probiotic prescriptions into antibiotic stewardship programs. Pharmacy channels in Germany and Japan are displacing direct-to-consumer wellness positioning with clinician-mediated recommendations. This shift concentrates most visibly in pediatric applications where parental compliance rises with medical endorsement.
Probiotics After Antibiotic Recovery Market Segmentation
Segmentation in probiotics after antibiotic recovery reveals how formulation choices, distribution channels, and clinical positioning create distinct value pools. Cold-chain requirements, palatability demands, and regulatory substantiation thresholds fragment the market into specialized competitive arenas where technical capabilities determine access.
Product Type:
After-sales intensity varies sharply across formats, with capsules requiring minimal patient support while gummies demand sustained education on storage protocols and dosing compliance.
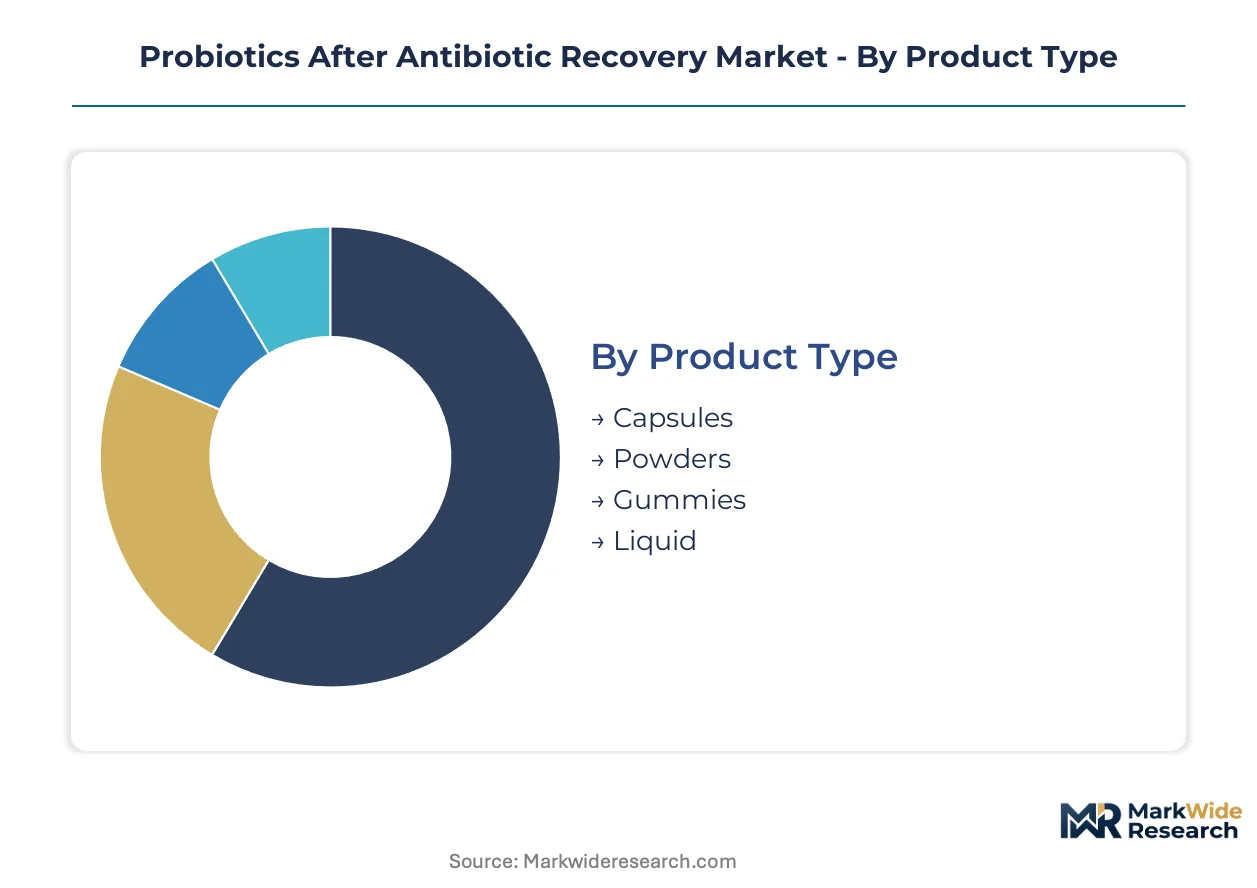
- Capsules:Moisture-barrier gelatin or HPMC shells protect live cultures from gastric acid degradation, enabling precise CFU dosing from 1 billion to 100 billion units. German pharmacy chains and Japanese convenience retailers stock these as default post-antibiotic recommendations, driven by physician familiarity and reimbursement code alignment.
- Gummies:Pectin or gelatin matrices incorporate taste-masking layers and acid-resistant coatings to preserve viability through shelf life. Palatability unlocks pediatric and geriatric segments in Denmark and Sweden where swallowing difficulties limit capsule adoption, though manufacturing complexity elevates per-unit costs.
- Powders:Sachet formats enable flexible dosing titration and combination with enteric coatings for targeted ileal release.
- Liquid:Suspension formats suit enteral feeding protocols and acute care discharge scenarios requiring immediate consumption.
Capsules hold the largest share; momentum sits with gummies as pharmacy channels expand palatability-driven formats for aging populations.
End User:
Cost tier stratification separates direct-to-consumer wellness positioning from medical-adjacent prescription workflows, with reimbursement eligibility determining margin architecture.
- Patients:Individual consumers purchasing through retail or e-commerce channels prioritize convenience and price transparency, with Japanese FOSHU-labeled products commanding premium positioning through regulatory endorsement.
- Healthcare Providers:Hospitals and outpatient clinics in Germany embed probiotics into antibiotic stewardship discharge protocols, creating institutional purchasing volume with formulary compliance requirements.
- Pharmacies:Nordic pharmacy chains negotiate tiered reimbursement for clinically validated strains, shifting procurement toward documented microbiome restoration endpoints.
- Nutraceutical Companies:Bulk strain purchasers supply private-label formulations, with EFSA substantiation barriers excluding generic CFU-count suppliers from premium positioning.
Healthcare providers concentrate the highest-value contracts; pharmacies are expanding fastest as reimbursement negotiations normalize medical adjacency.
Dosage Form:
Volume concentration favors oral administration, with alternative routes serving specialized clinical populations where gastrointestinal integrity is compromised.
- Oral:Capsules, tablets, and suspensions delivered through gastrointestinal tract dominate manufacturing scale and cold-chain infrastructure investment.
- Sublingual:Rapid buccal absorption bypasses gastric acid exposure for patients with severe antibiotic-associated gastritis or post-surgical GI dysfunction.
- Enteral:Tube-feeding compatible formats serve ICU discharge populations and elderly patients with dysphagia, requiring liquid or finely milled powder consistency.
- Topical:Cutaneous probiotic preparations target antibiotic-disrupted skin microbiome restoration in dermatological and wound care applications.
Oral formats command absolute volume; enteral applications climb fastest as hospital-at-home programs expand post-acute care protocols.
Application:
Customer type segmentation separates wellness-oriented consumers from clinically managed populations, with regulatory scrutiny redirecting investment toward biomarker-defensible endpoints.
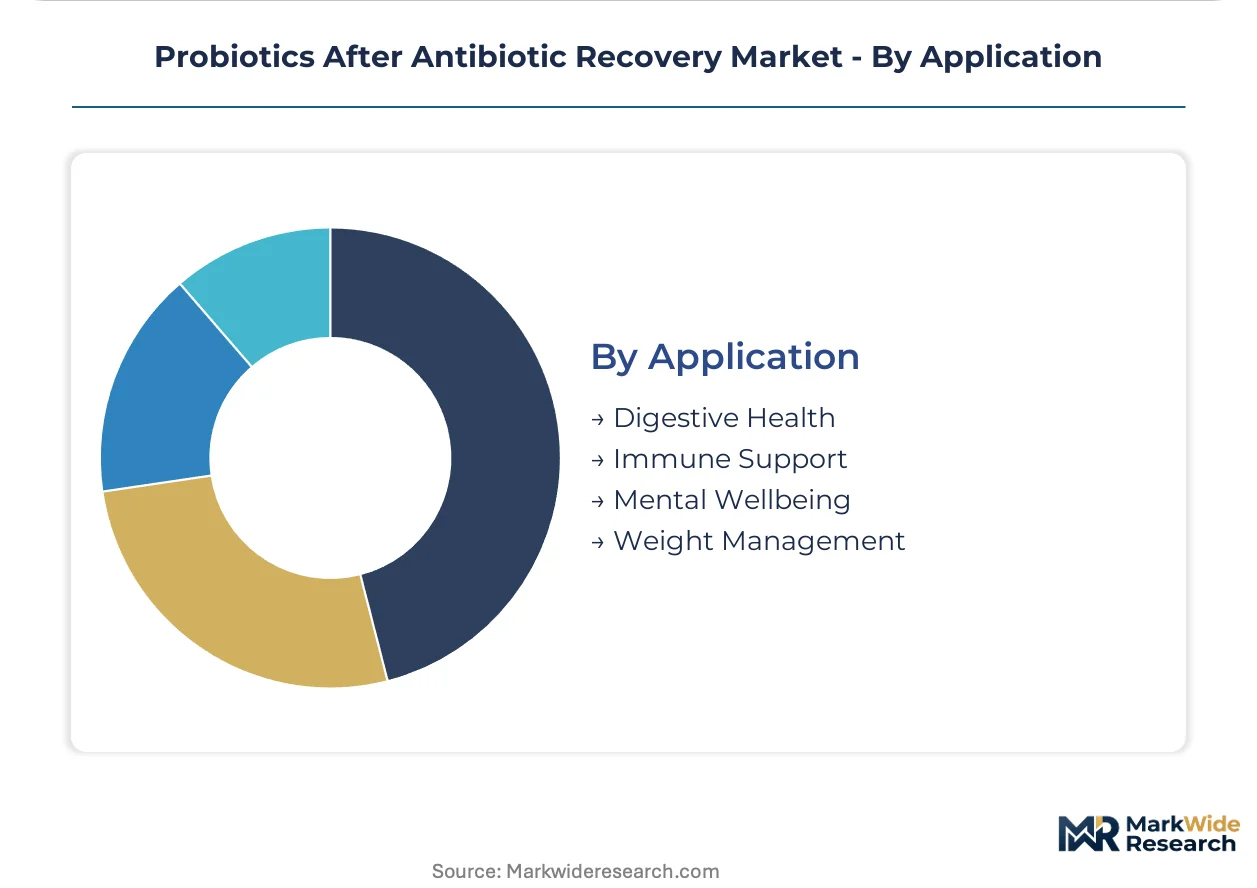
- Digestive Health:Primary positioning targeting antibiotic-associated diarrhea reduction and gut flora diversity restoration commands the largest revenue pool, with EFSA qualified health claims pathway demanding strain-specific human intervention studies.
- Immune Support:Cytokine modulation and mucosal IgA enhancement claims face intensifying regulatory review across FDA and EFSA jurisdictions, redirecting R&D toward clearer biomarker pathways.
- Mental Wellbeing:Gut-brain axis targeting through vagus nerve and neurotransmitter modulation represents emerging positioning with nascent clinical validation frameworks.
- Weight Management:Metabolic endotoxemia and short-chain fatty acid modulation claims attract wellness channel interest but lack standardized microbiome restoration endpoints for regulatory approval.
Digestive health retains dominant share; immune support is gaining fastest as manufacturers navigate EFSA substantiation toward defensible biomarker claims.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Ministry of Health, Labour and Welfare anchors the dominant geography through its FOSHU functional food designation, which normalizes post-antibiotic probiotic positioning and creates regulatory precedent adopted by pharmacy channels worldwide.
Japan
Tokyo and Osaka pharmacy networks stock FOSHU-labeled probiotics as standard discharge accompaniments to antibiotic courses. METI coordinates with the Ministry of Health to streamline functional food approval pathways for microbiome restoration claims. The Kanto region concentrates manufacturing partnerships between fermentation specialists and retail pharmacy chains.
Germany
Pediatric outpatient clinics in Bavaria and North Rhine-Westphalia embed probiotic protocols into antibiotic stewardship discharge workflows. The Federal Institute for Drugs and Medical Devices oversees qualified health claims substantiation for live culture products. Berlin anchors strain banking infrastructure that supplies clinical validation pipelines across Nordic markets.
Denmark
Pharmacy reimbursement negotiations in Copenhagen and Aarhus shift probiotics from wellness to medical adjacency for post-antibiotic recovery. The Danish Medicines Agency evaluates strain-specific evidence for prescription-tier positioning. The Øresund region concentrates specialized fermentation capacity serving medical-grade probiotic production.
United States
Hospital-at-home programs in California and Massachusetts expand enteral probiotic protocols for post-acute antibiotic recovery. The FDA oversees dietary supplement labeling under DSHEA while requiring strain-specific evidence for structure-function claims. The Boston-Cambridge cluster anchors microbiome analytics firms developing dose-response models for flora restoration endpoints.
Sweden
Geriatric compliance formats gain pharmacy traction in Stockholm and Gothenburg as palatability-driven gummies address swallowing difficulties. The Swedish Food Agency enforces EFSA-aligned substantiation requirements for post-antibiotic positioning statements. The Medicon Valley biotech corridor links strain developers with clinical trial networks targeting immune modulation biomarkers.
Probiotics After Antibiotic Recovery Market Competitive Landscape
Capability concentration sits with specialized strain developers possessing decades-long culture collections; scale advantage sits with diversified nutrition conglomerates with refrigerated distribution networks. The market structures around three tiers: clinical-validation specialists, pharmacy-channel integrators, and private-label commodity suppliers. Strategic moves center on strain-specific patent licensing and pharmacy reimbursement tier negotiations.
Among Nordic clinical-validation specialists, Chr. Hansen Holding A/S, BioGaia AB, and Probi AB occupy positions defined by strain banking depth and pediatric-focused prescription support programs. These Danish and Swedish entities exemplify the medical-adjacent archetype through pharmacy-level partnerships and documented microbiome restoration endpoints. DuPont de Nemours Inc and Danone S.A represent scale-driven nutrition conglomerates with refrigerated logistics networks spanning multiple continents.
| Leading Market Players |
|---|
| BioGaia AB |
| Chr. Hansen Holding A/S |
| Probi AB |
| DuPont de Nemours Inc |
| Danone S.A |
| Nestlé S.A |
| Lallemand Inc |
| Yakult Honsha Co Ltd |
| Kerry Group plc |
| Others |
Value Network & Pricing Analysis
Overcapacity in Nordic medical-grade fermentation facilities is compressing contract manufacturing margins while simultaneously elevating pricing power for strain developers with validated culture collections. This utilization asymmetry forces generic probiotic suppliers toward commodity positioning as specialized players capture premium tiers through documented microbiome restoration endpoints.
Pricing Analysis
Geographic price spreads between Japanese pharmacy channels and Nordic direct-to-consumer wellness platforms exceed threefold for equivalent CFU-count formulations. Three-tier pricing structure across premium, standard, and economy levels separates FOSHU-certified medical-grade strains from generic CFU-count supplements and private-label commodities. Price differentiation hinges on EFSA substantiation status and cold-chain integrity certification. Pricing pressure stems from EFSA's tightened evidence requirements excluding unsubstantiated formulations from pharmacy reimbursement tiers. Pediatric healthcare providers demonstrate lowest price sensitivity due to formulary compliance mandates, while direct-to-consumer wellness buyers exhibit highest elasticity.
Supply Chain Analysis
Contract manufacturing concentration sits with Chr. Hansen Holding A/S, Lallemand Inc, and Kerry Group plc holding specialized fermentation capacity across Denmark, France, and Ireland. Geographic supply concentration centers on Denmark, Sweden, and Japan for medical-grade strain production. Raw material dependencies include glucose feedstock for fermentation, cryoprotectants for viability preservation, and acid-resistant coating polymers for encapsulation. Single-source vulnerability in L. reuteri and L. rhamnosus GG strain licensing creates supply friction for multi-strain combination developers. Distribution runs through refrigerated pharmacy networks in Germany and Japan, with direct-to-consumer e-commerce channels serving price-sensitive wellness segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Post-antibiotic probiotic markets are approaching platform-economics inflection as pharmacy reimbursement systems and EFSA substantiation frameworks create two-sided network effects between validated strain developers and institutional procurement channels.
For Market Incumbents: Pre-empt commoditization pressure by securing exclusive strain banking licenses for pediatric-focused L. reuteri isolates before patent cliffs open generic competition. Accelerate backward integration into captive fermentation capacity in the Øresund region to defend margin structure against contract manufacturing cost volatility.
For New Entrants and Emerging Players: Rural German pharmacy networks outside Bavaria and North Rhine-Westphalia remain underpenetrated by medical-adjacent probiotic protocols, creating whitespace for clinically validated entrants. Target geriatric gummy formulations in Swedish pharmacy channels where swallowing difficulties limit incumbent capsule dominance. Pursue white-label partnerships with Nordic strain developers lacking downstream formulation capabilities.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across medical-grade fermentation sub-segments as EFSA evidence requirements demand dedicated clinical trial infrastructure. Five-to-ten-year viability favors acquisition targets possessing strain-specific patent estates with documented microbiome restoration endpoints rather than generic CFU-count positioning. Monitor pharmacy reimbursement tier negotiations in Copenhagen and Stockholm as early signals of medical-adjacency valuation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Strain Banking Acquisition | Chr. Hansen's culture collection infrastructure accelerates clinical validation pipelines for post-antibiotic positioning. |
| FOSHU Pathway Navigation | Japan's Ministry of Health approval creates regulatory precedent adopted by pharmacy channels across multiple geographies. |
| Geriatric Format Development | Pectin-based gummy formulations unlock Swedish pharmacy segments previously resistant to capsule products. |
| Pharmacy Reimbursement Negotiation | Nordic tiered procurement shifts probiotics from wellness to medical adjacency with formulary compliance requirements. |
| Microbiome Analytics Partnership | Boston-Cambridge dose-response modeling firms tie specific strains to measurable flora restoration endpoints. |
Research Methodology
A standing panel of probiotic formulation scientists, pharmacy procurement managers, pediatric clinicians, and regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from EFSA qualified health claims registers, Japanese FOSHU approval databases, German hospital formulary listings, and Nordic pharmacy reimbursement tariff schedules. Bottom-up strain-level demand modeling triangulated against top-down category spend estimates from institutional procurement disclosures.
Scenario-bracketing framed projections across base, upside, and downside regulatory trajectories over the analysis window. Segmentation dimensions modeled include product format, end-user channel, dosage administration route, application endpoint, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to strain-specific volume estimates, with cross-validation against cold-chain logistics capacity expansion plans and pharmacy channel partnership announcements.
Practitioners should monitor EFSA substantiation ruling timelines, Japanese FOSHU approval cadence, and Nordic pharmacy reimbursement tier renegotiations for early signals of medical-adjacency valuation shifts. Quarterly review of strain-specific patent expiration schedules and clinical trial readout calendars is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
North America Oral Health Probiotics Market
Probiotic Supplements
Probiotics Market
Probiotic Supplements
Shelf Stable Probiotics Market
Probiotic Supplements
ASEAN Probiotic Supplements Market
Probiotic Supplements
United States Probiotics Market
Probiotic Supplements
Bifidobacteria Lysates Market
Probiotic Supplements
United States Feed Probiotics Market
Probiotic Supplements
Digestion Aids Market
Probiotic Supplements
D-Lactate Free Probiotics Market
Probiotic Supplements
Stirred Yogurt Culture Market
Probiotic Supplements
Asia-Pacific Feed Probiotics Market
Probiotic Supplements
Herbal Yeast Market
Probiotic Supplements
Women Probiotic Market
Probiotic Supplements
Asia-Pacific Drinkable Yogurt Market
Probiotic Supplements
Multistrain Probiotics Market
Probiotic Supplements
North America Microbial Food Culture Market