
 Europe Microbial Food Culture Market | 2026-2036
Europe Microbial Food Culture Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Microbial Food Culture Market Foresight
Plant-based protein substrates is realigning fermentation economics as dairy alternatives require specialized bacterial cultures with tailored acidification profiles. Chr. Hansen Holding A/S leverages its culture collection to dominate strain development for clean-label applications. Kerry Group plc sustains competitive advantage through integrated fermentation ingredient supply chains across Ireland and continental Europe. Koninklijke DSM NV anchors its position in enzyme-culture synergies for accelerated ripening processes.
Microbial food culture comprises viable bacteria, yeasts, and molds deliberately introduced to food matrices to catalyze biochemical transformations, typically operating at controlled temperatures between 20°C and 45°C depending on strain thermotolerance and target metabolite production. These cultures serve industrial and artisanal food manufacturers by standardizing flavor development, texture formation, shelf-life extension, and nutritional enhancement across fermented product categories. Probiotics command premium positioning due to health claim substantiation requirements under EFSA guidelines, while fermentation starters represent the highest-volume segment driven by dairy and meat processing automation. Yeast applications in bakery and beverages maintain mature growth trajectories, whereas bacteria-focused cultures for plant-based alternatives are capturing expanding margin pools.
EFSA's Qualified Presumption of Safety framework and the EU's General Food Law Regulation shape strain approval timelines and commercialization pathways for novel culture introductions. REACH compliance for culture media components and the EU Green Deal's pesticide reduction targets are redirecting R&D investment toward biocontrol cultures that replace synthetic preservatives. Stakeholders must monitor evolving strain patent landscapes and regulatory divergence between EU member states on artisan versus industrial production classifications.
Market Dynamics
EFSA's Qualified Presumption of Safety framework is compressing strain approval timelines while the EU Green Deal redirects R&D investment toward biocontrol cultures that displace synthetic preservatives across dairy and meat processing corridors.
Growth Catalysts
- Clean-label mandates:The EU's Farm to Fork Strategy under the European Green Deal tightens microbiological safety standards while promoting regional food heritage, expanding artisan cheese applications across France and Italy.
- Precision fermentation scale-up:Germany's biotechnology corridor attracts capital for bacterial culture production serving plant-based protein substrates with tailored acidification profiles.
- Biocontrol substitution:REACH compliance pressures and pesticide reduction targets accelerate adoption of protective cultures in cured meat processing across the Iberian Peninsula.
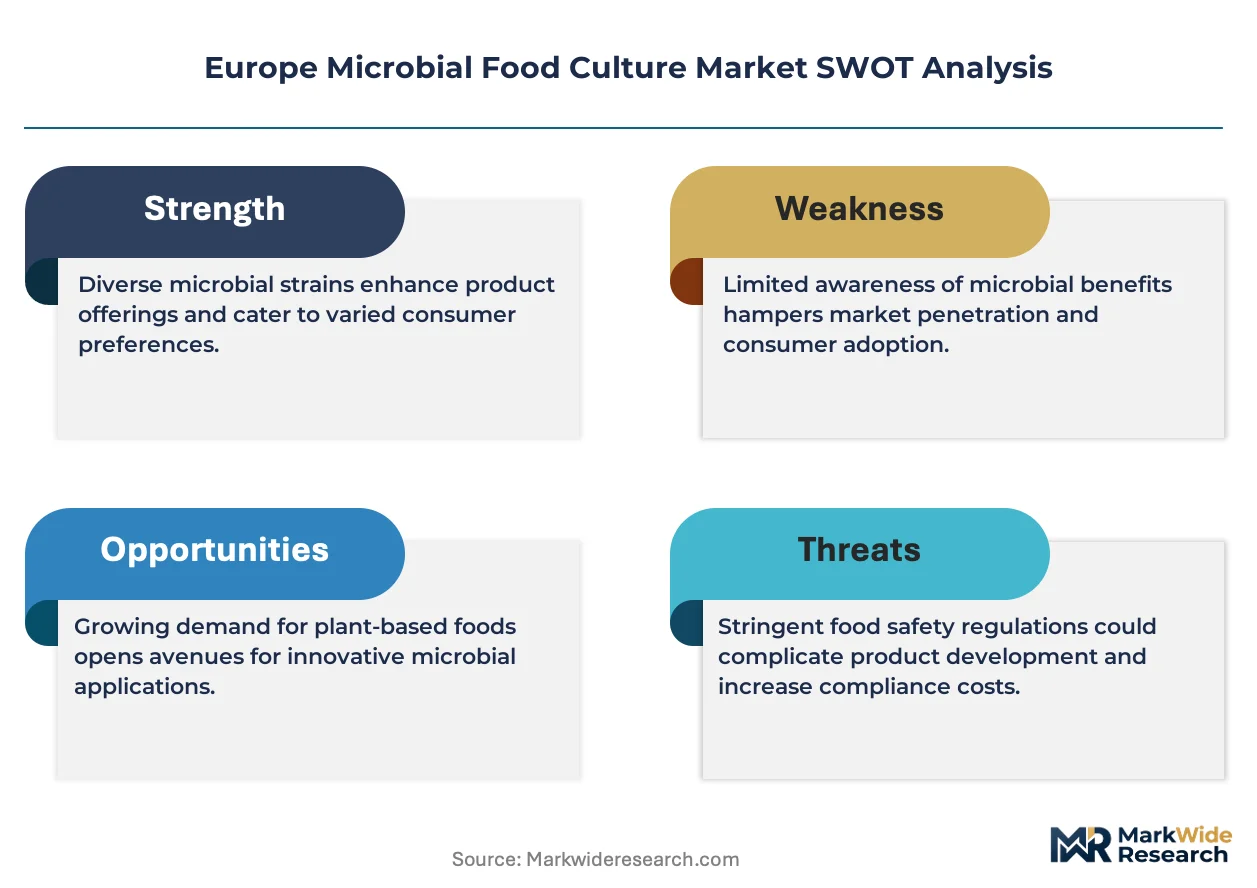
Market Restraints
- Strain patent thickets:Dense intellectual property landscapes surrounding proprietary starter cultures restrict new entrants from commercializing competitive formulations without licensing agreements.
- Culture media cost volatility:Fluctuating prices for peptone and yeast extract inputs destabilize production economics for small-scale fermentation facilities.
- EFSA substantiation barriers:Health claim approval requirements under EFSA guidelines extend commercialization timelines for probiotic positioning by 18-36 months.
Strategic Opportunities
- Poland's underdeveloped artisan sector:Traditional dairy regions in Lesser Poland and Podlaskie lack native starter culture infrastructure, creating first-mover advantages for regional strain banking.
- Enzyme-culture synergies:Accelerated ripening technologies combining proteolytic enzymes with tailored bacterial cultures address capacity constraints in aged cheese production.
- CSRD disclosure requirements:Corporate Sustainability Reporting Directive mandates drive demand for verified sustainable culture production methods and supply chain traceability systems.
Industry Challenges
- Strain characterization expertise gap:Shortages of metabolomics and genomics specialists delay novel culture development cycles in mid-sized fermentation operations.
- Legacy equipment retrofitting:Integration of precision fermentation controls with existing dairy processing infrastructure requires capital outlays that strain artisan producer balance sheets.
- Cross-border strain transfer protocols:Divergent national implementations of EU General Food Law Regulation create compliance friction for culture shipments between member states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Microbial Food Culture Market |
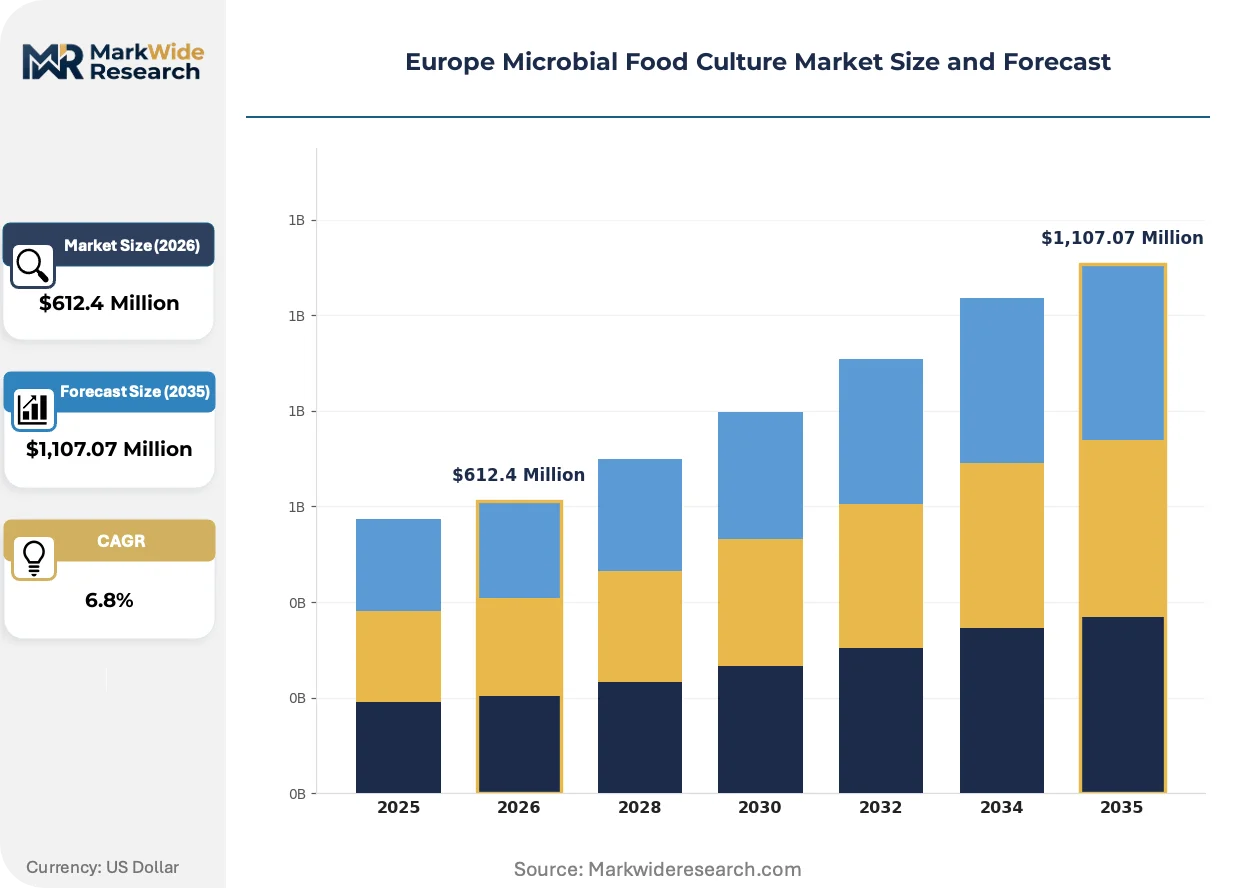
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Yeasts, Bacteria, Fermentation Starters Application: Dairy Products, Meat Products, Bakery, Beverages End User: Food Manufacturers, Restaurants, Retailers, Home Cooks Distribution Channel: Online Stores, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Chr. Hansen Holding A/S, Kerry Group plc, Koninklijke DSM NV, DuPont de Nemours Inc., Lesaffre, Lactina Ltd., Mediterranea Biotecnologie SRL, Angel Yeast Co., Ltd., Dalton Biotecnologie, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Microbial Food Culture Market Shifts & Advancements
Bioprocess engineering advances are fragmenting traditional culture production hierarchies as digital fermentation controls and synthetic biology tools democratize strain development capabilities across the value chain.
Single-use bioreactor systems with integrated sensors are modularizing production scale decisions for microbial food culture manufacturers. Mid-sized dairy processors in the Netherlands and Denmark adopt these systems to bypass fixed-asset commitments while maintaining pharmaceutical-grade contamination control. The technology is modularizing entry barriers, enabling regional culture banks to serve niche artisan segments previously captive to multinational supply agreements.
REACH registration requirements for novel culture media components are tightening substance safety documentation obligations across the European Economic Area. Industrial enzyme manufacturers must now submit extended toxicity datasets for fermentation byproducts, extending commercialization timelines. Dairy culture suppliers face particular pressure as peptone sources derived from animal tissues trigger additional scrutiny under BSE-TSE regulations.
Direct-to-producer culture banking is displacing traditional distributor intermediation in artisan cheese corridors. French and Italian consortia now maintain cooperative strain repositories where member-producers exchange region-specific cultures through formalized germplasm agreements. This pattern concentrates most visibly in PDO-designated zones where terroir-linked microbiomes constitute enforceable origin protections.
Europe Microbial Food Culture Market Segmentation
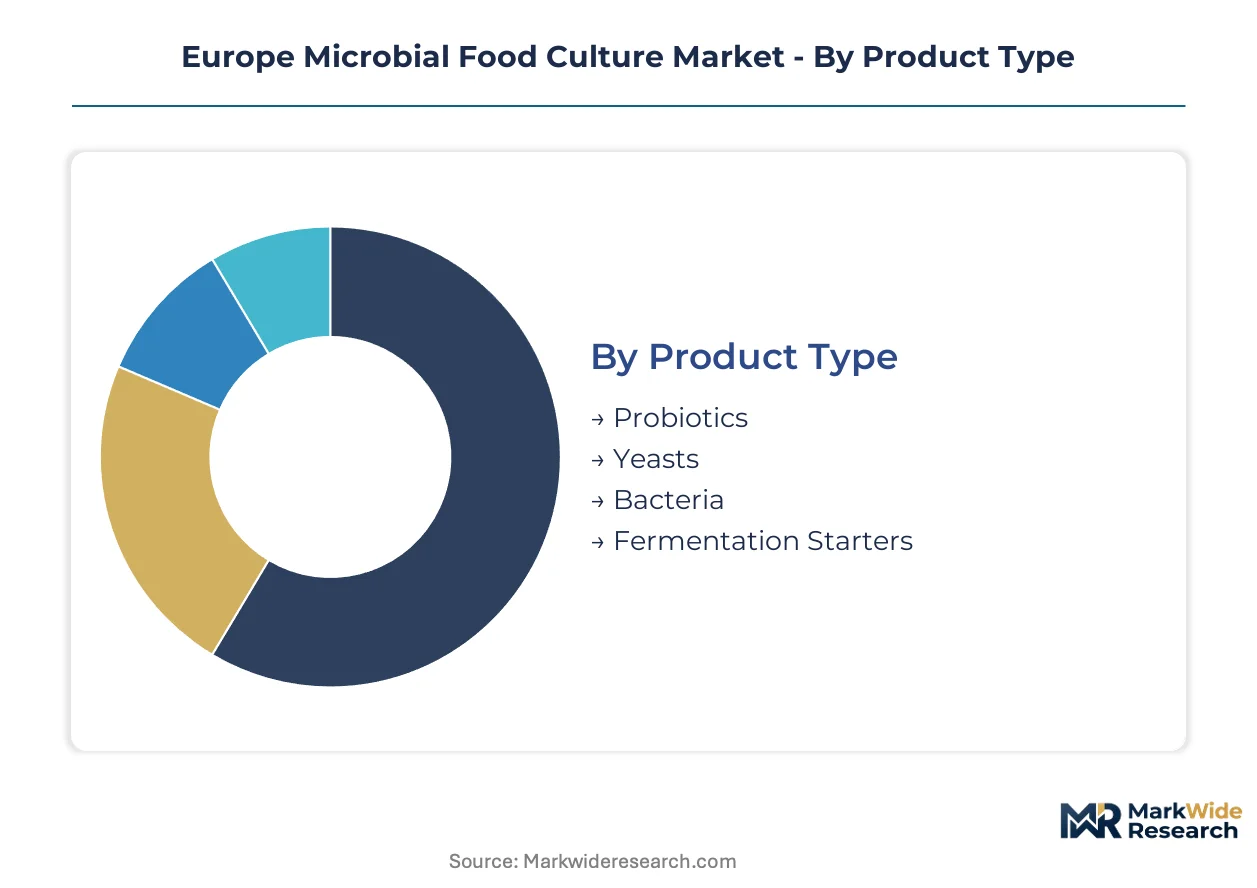
Microbial food culture segmentation reveals divergent margin architectures across the value chain. Volume-driven fermentation starters contrast with premium-priced probiotic strains requiring EFSA health claim substantiation. Understanding these tiered economics guides capital allocation between commoditized bulk supply and differentiated positioning.
Product Type:
Volume concentration sits with standardized fermentation inputs, while premium capture clusters around clinically validated strains.
- Fermentation Starters:Standardized bacterial and yeast blends designed for consistent acidification kinetics in dairy and meat matrices. Demand concentrates in Germany's precision fermentation corridor and Iberian cured meat facilities, driven by automation requirements in industrial processing lines.
- Probiotics:Viable cultures with documented health benefits requiring EFSA substantiation under Regulation (EC) No 1924/2006. France and Italy's artisan cheese consortia command premium positioning through germplasm-linked terroir claims in PDO-designated zones.
- Yeasts:Saccharomyces and non-conventional yeast strains for bakery leavening and beverage alcohol fermentation.
- Bacteria:Lactic acid bacteria and acetic acid bacteria for targeted metabolite production in plant-based alternatives.
Today's leader: Fermentation Starters. Tomorrow's challenger: Probiotics.
Application:
Traditional dairy and meat processing anchors current demand, while plant-based substrates emerge as the margin expansion frontier.
- Dairy Products:Cheese, yogurt, and fermented milk applications utilizing mesophilic and thermophilic starter combinations. Netherlands and Danish processors drive adoption of single-use bioreactor systems for pharmaceutical-grade contamination control in aged cheese production.
- Meat Products:Protective cultures for cured and fermented sausages across Spain and Portugal, replacing synthetic preservatives under REACH compliance pressures and EU Green Deal pesticide reduction targets.
- Bakery:Sourdough starters and commercial yeast formulations for industrial and artisan bread production.
- Beverages:Kombucha, kefir, and alcoholic fermentation cultures for functional and traditional drinks.
Dairy Products retain the largest revenue footprint. Meat Products gain share fastest through biocontrol substitution mandates.
End User:
Industrial scale dominates procurement volumes, though artisan segments command price premiums through direct strain banking relationships.
- Food Manufacturers:Industrial processors requiring standardized culture performance across automated production lines. Poland's underdeveloped dairy regions in Lesser Poland and Podlaskie present first-mover opportunities for regional strain infrastructure deployment.
- Restaurants:Fine-dining and fermentation-focused establishments sourcing specialty cultures for menu differentiation.
- Retailers:Private-label fermented product lines requiring consistent supplier quality agreements.
- Home Cooks:Direct-to-consumer culture kits for sourdough, cheese making, and vegetable fermentation.
Food Manufacturers capture the bulk of volume. Restaurants represent the steepest expansion trajectory through experiential dining trends.
Distribution Channel:
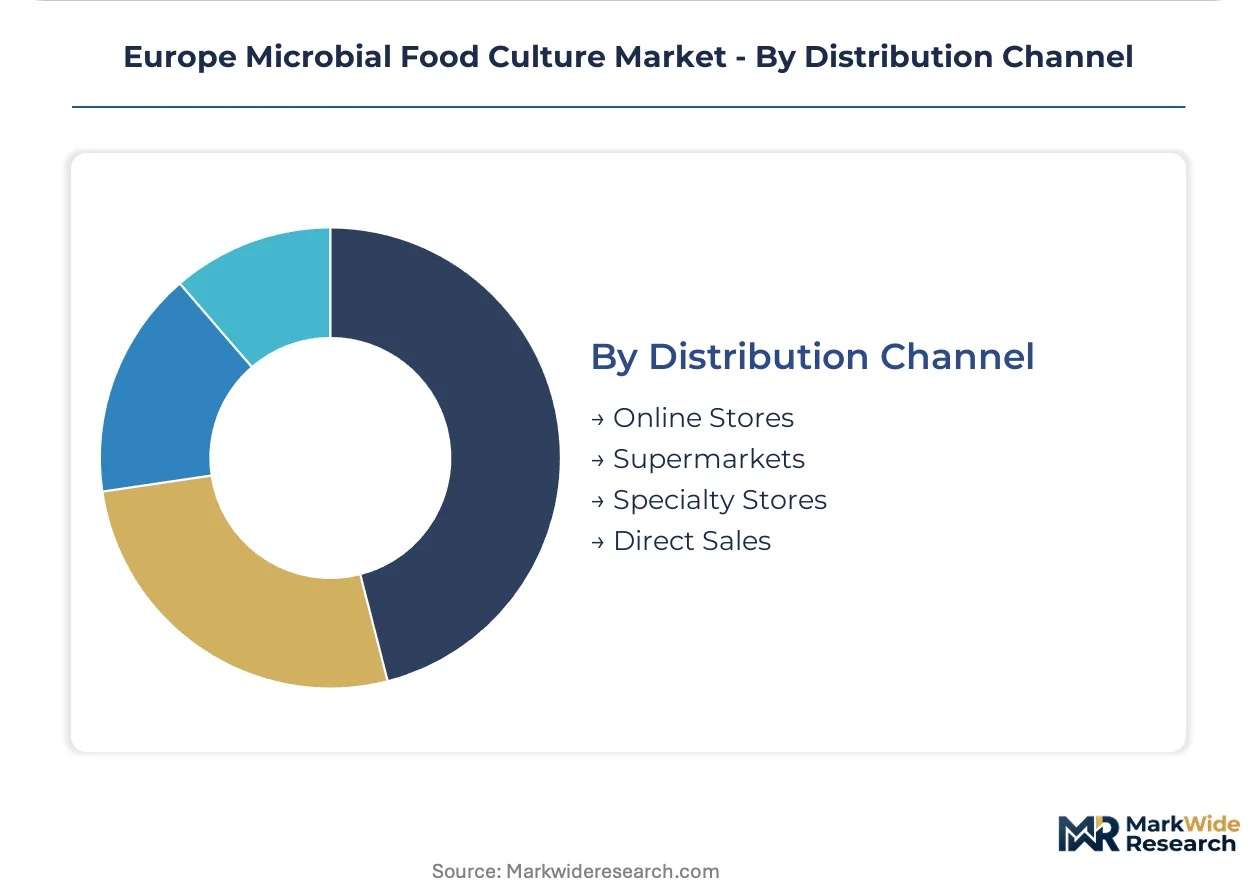
Direct relationships displace intermediation in artisan corridors, while consolidated retail channels serve mass-market segments.
- Direct Sales:Culture banking agreements between producers and fermentation facilities, particularly in French and Italian PDO zones where cooperative strain repositories formalize germplasm exchange protocols.
- Specialty Stores:Regional suppliers serving artisan producers with customized culture formulations and technical support.
- Online Stores:E-commerce platforms for small-batch culture procurement and home fermentation supplies.
- Supermarkets:Mass-market retail distribution for standardized commercial culture products.
Direct Sales commands the highest margin per liter. Online Stores climb fastest through democratized access to strain diversity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision fermentation corridor anchors European microbial food culture demand, with capital flows concentrating in bacterial strain production for plant-based protein substrates. The region's regulatory framework under EFSA's Qualified Presumption of Safety and the EU Green Deal's Farm to Fork Strategy creates divergent compliance pathways across member states.
Germany
Precision fermentation scale-up and automation in dairy processing drive demand for standardized starter cultures. The country's biotechnology corridor attracts investment for bacterial culture production serving alternative protein matrices with tailored acidification profiles. REACH compliance pressures redirect R&D toward biocontrol applications in industrial meat processing facilities near Frankfurt and Munich.
France
Artisan cheese consortia in Auvergne-Rhône-Alpes and Normandy expand native starter culture banking for PDO-designated terroir protection. EFSA health claim substantiation requirements under Regulation (EC) No 1924/2006 extend commercialization timelines for probiotic positioning. Cooperative strain repositories in Roquefort and Comté zones formalize germplasm exchange protocols among member-producers.
Italy
Traditional cured meat industries across Emilia-Romagna and Lombardy accelerate protective culture adoption to replace synthetic preservatives. The EU Green Deal's pesticide reduction targets align with regional heritage promotion in Parmigiano-Reggiano and Grana Padano production zones. Direct-to-producer culture banking displaces distributor intermediation in Modena and Bologna fermentation clusters.
Spain
Iberian Peninsula cured meat processors adopt biocontrol cultures under REACH compliance pressures and Farm to Fork microbiological safety mandates. Andalusian and Extremaduran facilities replace chemical preservatives with bacterial protective strains in chorizo and jamón production. Barcelona-based fermentation ingredient suppliers integrate enzyme-culture synergies for accelerated ripening technologies.
Netherlands
Dairy processors in North Holland and Friesland deploy single-use bioreactor systems for pharmaceutical-grade contamination control in aged cheese production. CSRD disclosure requirements drive demand for verified sustainable culture production methods and supply chain traceability. Wageningen University's research cluster anchors strain characterization expertise for mid-sized fermentation operations.
Europe Microbial Food Culture Market Competitive Landscape
Strategic partnerships dominate the current landscape as culture suppliers integrate with fermentation equipment manufacturers and dairy processors. The market structures around three tiers: multinational ingredient conglomerates with integrated supply chains, specialized culture houses with proprietary strain collections, and regional cooperative banks serving artisan consortia. Two archetypes anchor competitive positioning: precision fermentation specialists leveraging synthetic biology tools, and heritage-focused suppliers emphasizing terroir-linked germplasm. Portfolio diversification into plant-based substrates and geographic expansion into underdeveloped Eastern European markets represent the dominant competitive moves.
Within the multinational tier, Chr. Hansen Holding A/S and Kerry Group plc exemplify divergent strategic anchors. The Danish entity occupies a position emphasizing strain collection depth and clean-label applications, while the Irish group represents integrated fermentation ingredient supply chain control across continental Europe. Koninklijke DSM NV sits within the enzyme-culture synergy archetype, anchoring accelerated ripening process development. These three entities collectively illustrate how competitive positioning fragments between precision biotechnology capabilities and regional heritage preservation.
| Leading Market Players |
|---|
| Chr. Hansen Holding A/S |
| Kerry Group plc |
| Koninklijke DSM NV |
| DuPont de Nemours Inc. |
| Lesaffre |
| Lactina Ltd. |
| Mediterranea Biotecnologie SRL |
| Angel Yeast Co., Ltd. |
| Dalton Biotecnologie |
| Others |
Supply & Pricing Matrix
Metabolomics and genomics specialists concentrated in the Netherlands and Denmark command wage premiums that compress margins for mid-sized fermentation operations, widening spreads between artisan terroir-linked cultures and commodity starter formulations.
Pricing Analysis
Input-cost pass-through from peptone and yeast extract volatility destabilizes production economics for small-scale facilities. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-substantiated probiotic strains from clean-label fermentation starters and bulk commodity blends. Price differentiation hinges on certification grade under REACH and BSE-TSE regulations plus volume scale commitments from industrial dairy processors. Pricing pressure stems from culture media cost volatility, with artisan producers least price-sensitive due to germplasm-linked terroir premiums.
Supply Chain Analysis
Reverse-logistics flows for expired or non-viable culture batches remain underdeveloped across European fermentation corridors, creating disposal cost burdens for small-scale operators. Supply concentrates in Denmark, Ireland, and the Netherlands, with strain collection repositories and precision fermentation infrastructure drawing from dairy and meat processing byproducts. Raw material dependencies center on animal-derived peptones, plant-based nitrogen sources, and pharmaceutical-grade growth media. Single-source vulnerability around proprietary strain collections threatens supply continuity. Distribution runs through direct banking agreements in French and Italian PDO zones alongside consolidated distributor networks serving industrial processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Microbial Food Culture Market functions as a stable compounder anchored by irreversible regulatory mandates under the EU Green Deal's Farm to Fork Strategy that permanently embed biocontrol cultures into food safety compliance frameworks.
For Market Incumbents: Acquire regional strain banks in Poland's Lesser Poland and Podlaskie dairy corridors before first-mover infrastructure solidifies. Deepen backward integration into culture media production to insulate margins from peptone price volatility threatening small-scale competitors. Secure EFSA health claim substantiation pipelines early, as approval timelines extending 18-36 months create moats against late entrants seeking probiotic positioning. For New Entrants and Emerging Players: Capture Poland's underdeveloped artisan sector through cooperative strain repository models adapted from French PDO consortia. Target Spain and Portugal's cured meat biocontrol substitution wave, where REACH compliance pressures displace synthetic preservatives with bacterial protective cultures. Deploy direct-to-producer culture banking relationships to bypass entrenched distributor intermediation in Iberian processing clusters. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized fermentation operations with proprietary strain collections but underutilized precision fermentation capacity. Long-term viability over a 5-10 year horizon rests on regulatory tailwinds from EU pesticide reduction targets and CSRD disclosure mandates driving traceability investment. Monitor EFSA Qualified Presumption of Safety approval velocities as the critical inflection signal for probiotic premium capture potential.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Strain Bank Acquisition | Establishes germplasm control in Poland's underdeveloped dairy corridors before competitive infrastructure deployment. |
| EFSA Health Claim Substantiation Investment | Locks in 18-36 month regulatory moats for probiotic positioning under Regulation (EC) No 1924/2006. |
| Backward Integration into Culture Media | Captive supply of peptone and yeast extract inputs insulates margins from REACH-driven animal-tissue scrutiny. |
| Direct-to-Producer Banking Agreements | Displaces distributor intermediation in French and Italian PDO zones with cooperative germplasm exchange protocols. |
| Precision Fermentation Scale-Up | Single-use bioreactor deployment in the Netherlands and Denmark bypasses fixed-asset barriers for mid-sized processors. |
Research Methodology
Coverage spans Germany, France, Italy, Spain, and the Netherlands, with primary inputs from each region's fermentation corridor. The analysis combines structured interviews with culture collection curators, dairy processing plant managers, regulatory affairs specialists at EFSA, and procurement leads at meat processing facilities with secondary validation from EFSA opinion databases, REACH registration filings, EU Farm to Fork Strategy implementation reports, and national food safety agency guidance documents. Bottom-up strain-level demand modeling triangulates against top-down sectoral expenditure estimates from dairy and meat industry associations.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models segmentation dimensions including product type (fermentation starters, probiotics, yeasts, bacteria), application (dairy, meat, bakery, beverages), and end-user scale (industrial manufacturers, artisan producers, foodservice). CAGRs derive from fitted growth curves calibrated to EFSA approval timelines, precision fermentation capacity buildouts, and biocontrol substitution elasticities in cured meat processing.
EFSA regulatory delays, REACH substance reclassification events, and cross-border strain transfer protocol fragmentation are the dominant revision risks to forecast assumptions. Practitioners should monitor EFSA opinion publication velocities, ECHA substance evaluation schedules, and member state implementation divergences under the EU General Food Law Regulation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Brewer Yeast Powder Market
Probiotic Supplements
South America Digestive Health Supplements Market
Probiotic Supplements
Global Probiotic Based Dietary Supplements Market
Probiotic Supplements
United States Probiotics Market
Probiotic Supplements
United Kingdom Probiotics Market
Probiotic Supplements
Women Probiotic Market
Probiotic Supplements
South America Microbial Food Culture Market
Probiotic Supplements
Global Liquid Feed Supplements Market
Probiotic Supplements
Probiotics Market
Probiotic Supplements
Single-Strain Probiotics Market
Probiotic Supplements
Colon Cleansing Supplements Market
Probiotic Supplements
Asia-Pacific Drinkable Yogurt Market
Probiotic Supplements
United States Digestive Supplement Market
Probiotic Supplements
Synbiotic Foods Market
Probiotic Supplements
Global Probiotics Food and Cosmetics Market
Probiotic Supplements
Probiotic for Men Market