
 D-Lactate Free Probiotics Market | 2026-2036
D-Lactate Free Probiotics Market Size, Share, and Industry Trends Forecast 2026-2036
D-Lactate Free Probiotics Market Outlook
Pharmaceutical-grade strain certification is bifurcating the competitive landscape into validated and commodity tiers. Chr. Hansen leverages its culture collection depth to dominate high-specification contract manufacturing. BioGaia AB anchors its position through proprietary L. reuteri strains with documented D-lactate non-producing phenotypes. Custom Probiotics specializes in practitioner-channel formulations with batch-level third-party verification.
D-lactate free probiotics comprise live microbial preparations selectively screened for absence of D-lactate dehydrogenase activity, ensuring no D-lactate accumulation during intestinal colonization. These formulations serve patients with short bowel syndrome, pediatric populations, and individuals with D-lactate acidosis susceptibility who require L-lactate producing or lactate-neutral strains. Capsule formats with enteric coating and alginate microencapsulation occupy the highest margin pool due to stability premiums and targeted release claims. Gut health applications sustain volume leadership, while women's health segments with vaginal probiotic positioning command price premiums through specialized strain combinations.
The US FDA exercises oversight through GRAS self-affirmation and NDIN pathways for novel probiotic strains, while EFSA's QPS list governs European strain eligibility and health claim substantiation. Health Canada requires site licensing and strain-specific evidence for Natural Product Number designation, creating differentiated market access timelines. Stakeholders must monitor evolving pharmacovigilance requirements for live biotherapeutic products as regulators reconsider classification boundaries between foods and therapeutics.
Market Dynamics
EFSA's strain-specific health claim substantiation requirements are compressing formulation timelines while elevating clinical validation costs, bifurcating manufacturers into those with culture collection depth versus commodity assemblers.
Growth Catalysts
- Pediatric functional food formulations:Germany's clinical validation standards for probiotic strains command premium positioning, accelerating adoption in infant nutrition and early-life gut health applications.
- Alginate microencapsulation:This delivery technology enables targeted release claims and stability premiums, expanding addressable populations in short bowel syndrome management.
- Health Canada's NPN pathway:Strain-specific evidence requirements for Natural Product Number designation create differentiated market access timelines favoring documented D-lactate non-producing phenotypes.
Market Restraints
- Strain certification cost structure:Pharmaceutical-grade validation requires multi-year clinical studies, concentrating viable supply among established culture collections.
- Regulatory friction from FDA reclassification:Evolving pharmacovigilance requirements for live biotherapeutic products blur boundaries between foods and therapeutics, extending approval timelines.
- Substitution threat from L-lactate neutral alternatives:Competing metabolic pathway engineering in conventional probiotics offers functional equivalence without D-lactate screening overhead.
Strategic Opportunities
- Women's health vaginal positioning:Specialized strain combinations for urogenital applications command price premiums through practitioner-channel distribution.
- US GRAS self-affirmation pathway:Novel strain developers leverage this regulatory route to accelerate commercialization versus NDIN timelines.
- Enteric coating convergence with cryoprotectant matrices:Combined stability technologies enable ambient distribution expansion into pharmacy retail.
Industry Challenges
- Batch-level verification skill scarcity:Third-party phenotypic confirmation requires specialized analytical microbiology capabilities concentrated in contract laboratories.
- ISO 17025 accreditation timelines:Testing facility certification delays strain release schedules, compressing working capital cycles for formulation houses.
- Legacy strain IP entanglement:Proprietary L. reuteri deposits create licensing complexity for D-lactate non-producing variant development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | D-Lactate Free Probiotics Market |
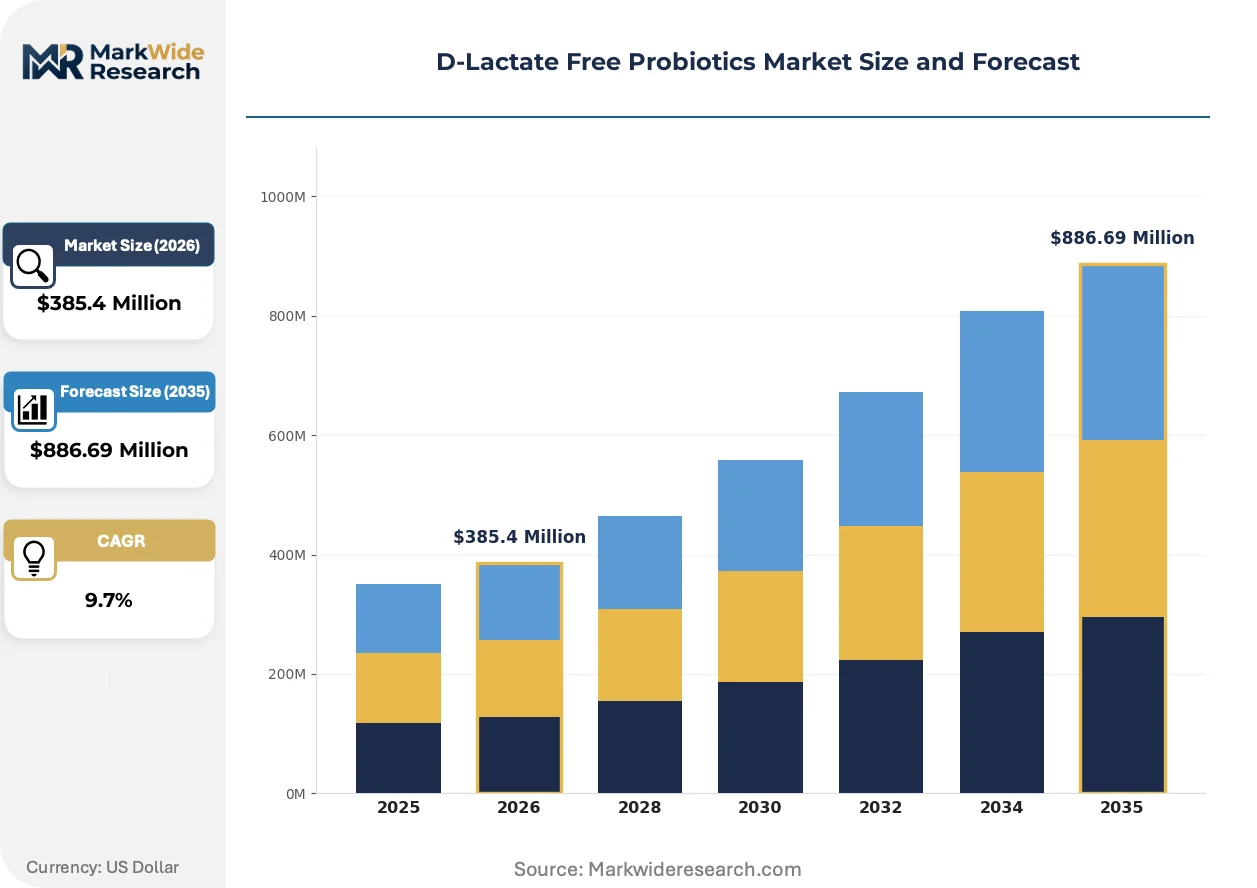
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $886.69 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powders, Liquid, Gummies Application: Gut Health, Immune Support, Women's Health, Athletic Performance Distribution Channel: Online Stores, Health Food Stores, Pharmacies, Supermarkets End User: Adults, Children, Elderly, Athletes |
| Companies Covered | Custom Probiotics, UAS Laboratories, BioGaia AB, Danone, Nestlé, Yakult Honsha, Chr. Hansen, Novozymes, Klaire Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
D-Lactate Free Probiotics Market Strategic Shifts
Manufacturing technology and regulatory classification boundaries are simultaneously shifting, compressing traditional competitive advantages while opening white space for clinically validated positioning.
CRISPR-guided metabolic pathway editing is fragmenting the strain development landscape. Contract manufacturers with in-house genome engineering capabilities now compress phenotype confirmation from months to weeks. Pediatric formulation specialists adopt these tools to accelerate D-lactate dehydrogenase knockout verification, collapsing historical barriers between research-grade and commercial-ready strains.
REACH-aligned strain safety dossier harmonization is reshaping European market entry. EFSA's Qualified Presumption of Safety list updates now require expanded toxicological endpoints, extending preparation timelines for novel submissions. German and Dutch manufacturers respond by pre-submission consultation investments, securing conditional approvals ahead of competitors.
Practitioner-channel certification preferences are displacing mass-market brand loyalty. Clinicians increasingly specify batch-verified D-lactate absence over legacy retail brands, consolidating procurement through compounding pharmacies and direct-to-clinic distribution. This behavioral shift concentrates in North American and Australian naturopathic networks where therapeutic probiotic prescribing authority expanded.
D-Lactate Free Probiotics Market Segmentation
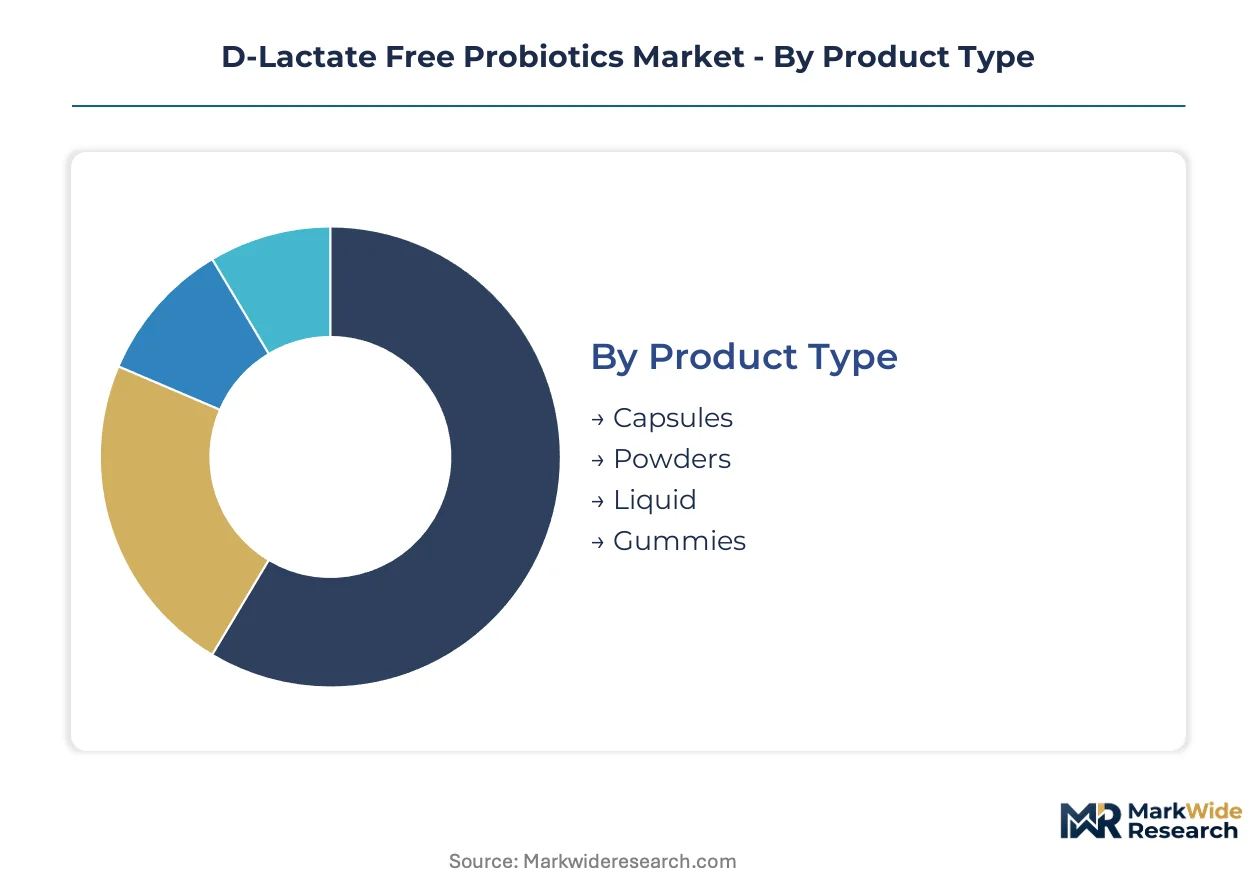
Segmentation in D-lactate free probiotics determines formulation specifications, regulatory pathways, and margin structures. Each dimension carries distinct technical requirements for strain validation, stability engineering, and channel access that shape competitive positioning.
Product Type:
Domestic consumption concentrates in ambient-stable formats suited to pharmacy retail, while export-led demand prioritizes cold-chain-independent technologies for tropical distribution.
- Capsules:Enteric-coated and alginate microencapsulated variants deliver targeted intestinal release with documented stability premiums. Demand clusters in Germany's clinical validation environment where practitioner-channel procurement specifies batch-verified D-lactate absence. EFSA's strain-specific health claim requirements elevate capsule specifications for premium positioning.
- Powders:Sachet and bulk formats serve pediatric functional food integration with cryoprotectant matrices enabling ambient distribution. Health Canada's NPN pathway favors powder formulations with strain-specific evidence dossiers, accelerating adoption in naturopathic networks.
- Liquid:Refrigerated drops and suspensions target infant nutrition applications with short bowel syndrome management protocols.
- Gummies:Palatability-focused formats expand pediatric compliance but face stability constraints for live culture counts.
Capsules command the established base. The steepest expansion runs through powders.
Application:
Cost tier stratification separates clinical-grade strain validation from commodity wellness positioning, with reimbursement eligibility driving specification divergence.
- Gut Health:Volume leadership segment addressing short bowel syndrome, pediatric dysbiosis, and post-antibiotic recovery with L-lactate producing or lactate-neutral strains. Clinical validation requirements from Germany's Federal Institute for Drugs and Medical Devices bifurcate supply between pharmaceutical-grade and dietary supplement tiers.
- Women's Health:Vaginal probiotic applications with specialized strain combinations command price premiums through practitioner-channel distribution. Urogenital positioning requires distinct stability specifications and pH-targeted release engineering.
- Immune Support:Upper respiratory and systemic modulation applications with emerging strain-specific mechanistic claims.
- Athletic Performance:Recovery and gastrointestinal tolerance applications for training-load management with convenience-format preferences.
Gut health anchors volume procurement. Women's health generates the highest margin expansion trajectory.
Distribution Channel:
Customer type fragmentation separates clinical specification from self-directed purchasing, with verification requirements determining channel economics.
- Online Stores:Direct-to-consumer platforms with subscription models and batch-level transparency claims. Australian TGA-registered products and Health Canada NPN-designated strains concentrate in specialized portals serving naturopathic prescribing networks.
- Health Food Stores:Staff-assisted selection environments with growing clinician referral traffic for verified D-lactate absence products.
- Pharmacies:Behind-counter and self-selection formats with cold-chain infrastructure for live culture stability.
- Supermarkets:Mass-market penetration limited to shelf-stable formats with basic strain documentation.
Pharmacies retain the volume base. Online stores are climbing the fastest through practitioner-channel digitization.
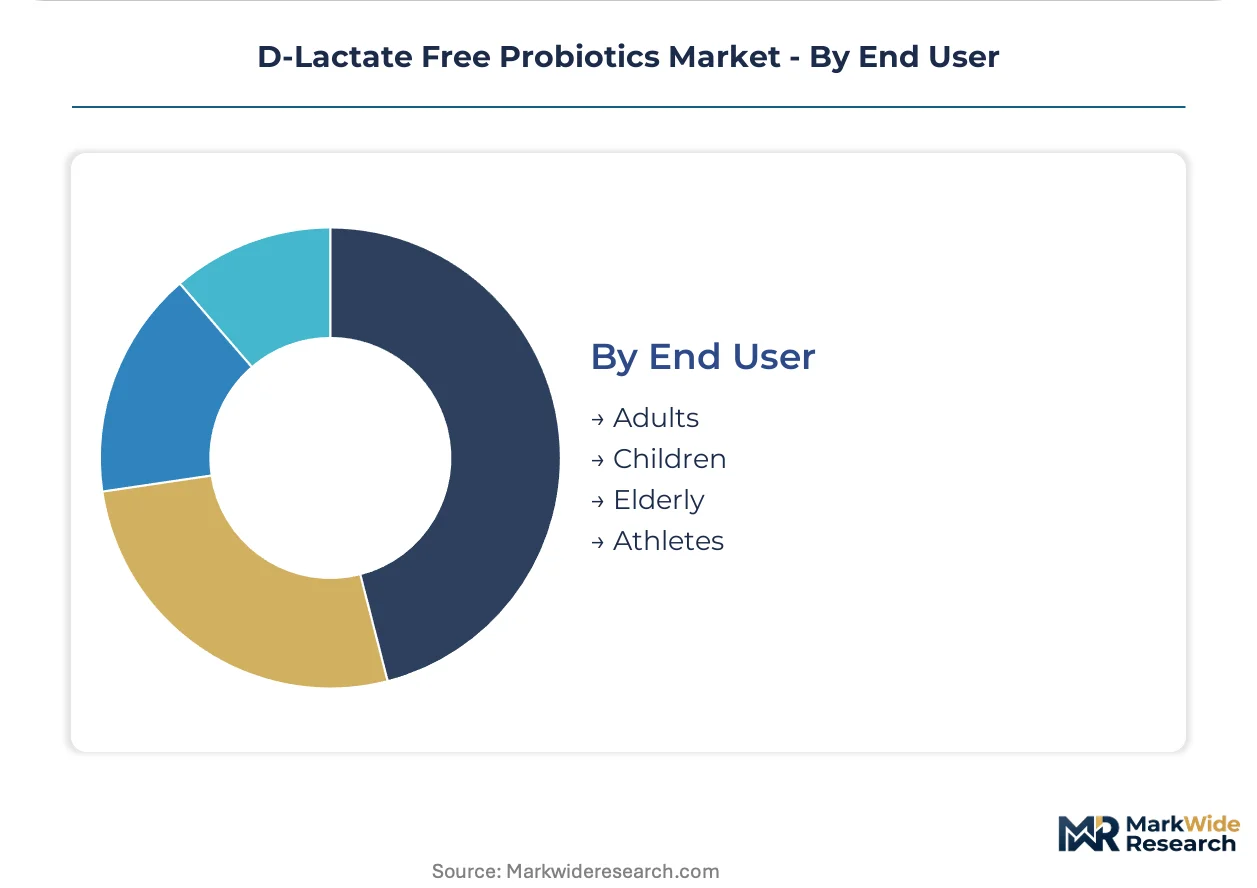
End User:
Maturity gradients separate established adult wellness markets from emerging pediatric and geriatric clinical applications with distinct regulatory pathways.
- Children:Pediatric functional food formulations and infant nutrition applications drive fastest adoption with D-lactate acidosis susceptibility protocols. Germany's clinical validation standards for probiotic strains command premium positioning in early-life gut health.
- Adults:Established base of short bowel syndrome patients and functional gastrointestinal disorder management with practitioner-channel consolidation.
- Elderly:Polypharmacy interaction protocols and immunosenescence modulation with emerging strain-specific evidence requirements.
- Athletes:Training-periodization integration with convenience-format preferences and gastrointestinal tolerance optimization.
Adults represent the established consumption base. Children show the steepest expansion through pediatric formulation specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Strain development capabilities concentrate in jurisdictions with mature biotechnology infrastructure and harmonized regulatory frameworks for live microbial products. Germany's clinical validation environment and Health Canada's strain-specific evidence requirements create distinct premium market tiers.
United States
Pediatric functional food demand and short bowel syndrome management protocols drive formulation specialization. The FDA's GRAS self-affirmation pathway enables accelerated commercialization timelines for documented D-lactate non-producing strains. Greater Boston's biotechnology cluster hosts contract manufacturers with ISO 17025-accredited phenotypic verification laboratories.
Germany
The Federal Institute for Drugs and Medical Devices enforces pharmaceutical-grade certification standards that bifurcate supply between clinical and commodity tiers. EFSA's Qualified Presumption of Safety list updates require expanded toxicological endpoints for novel submissions. Bavaria's culture collection facilities dominate high-specification contract manufacturing for practitioner-channel distribution.
Canada
Naturopathic prescribing networks in Ontario and British Columbia consolidate procurement through compounding pharmacies with batch-level transparency requirements. Health Canada's Natural Product Number pathway mandates strain-specific evidence dossiers, favoring documented phenotypes. Vancouver's analytical microbiology laboratories specialize in third-party D-lactate absence verification.
Australia
TGA-registered products concentrate in specialized portals serving expanded therapeutic probiotic prescribing authority. Practitioner-channel digitization accelerates adoption of verified D-lactate absence formulations over legacy retail brands. Sydney's contract research organizations support phenotypic confirmation for export-oriented manufacturers.
Japan
Infant nutrition applications with D-lactate acidosis susceptibility protocols sustain demand for lactate-neutral strain combinations. METI's guidance on functional food substantiation aligns with emerging pharmacovigilance frameworks for live biotherapeutics. Osaka's fermentation technology cluster supplies cryoprotectant matrices for ambient-stable powder formats.
D-Lactate Free Probiotics Market Competitive Environment
Concentration sits with culture collection holders and specialized formulation houses rather than diversified nutrition conglomerates. The competitive landscape bifurcates between pharmaceutical-grade validators and commodity assemblers lacking batch-level verification capabilities. Three archetypes dominate: proprietary strain depositors, practitioner-channel specialists, and contract manufacturers with in-house genome engineering. Strategic moves center on pre-submission consultation investments for conditional regulatory approvals and backward integration into analytical microbiology capabilities.
Among culture collection holders, Chr. Hansen anchors the high-specification tier through proprietary Lactobacillus deposits. BioGaia AB exemplifies the strain-specific positioning archetype with documented D-lactate non-producing phenotypes. Custom Probiotics occupies the practitioner-channel specialist position with batch-level third-party verification protocols.
| Leading Market Players |
|---|
| Custom Probiotics |
| UAS Laboratories |
| BioGaia AB |
| Danone |
| Nestlé |
| Yakult Honsha |
| Chr. Hansen |
| Novozymes |
| Klaire Labs |
| Others |
Value Chain & Pricing Dynamics
Ninety-day strain release schedules compress working capital cycles for formulation houses, concentrating pricing power with ISO 17025-accredited contract laboratories that control batch-level phenotypic verification bottlenecks. This lead-time structure rewards backward integration into analytical microbiology capabilities while penalizing commodity assemblers dependent on third-party testing queues.
Pricing Analysis
EFSA's strain-specific health claim substantiation requirements dictate the pricing tier structure across pharmaceutical-grade, practitioner-channel, and mass-market tiers. Three-tier pricing separates clinical validation tiers from standard dietary supplement positioning from economy private-label offerings, with certification level and volume scale as primary price differentiation drivers. Cost compression in the standard tier is intensifying because CRISPR-guided metabolic engineering collapses historical barriers between research-grade and commercial-ready strains. Pediatric functional food buyers exhibit lowest price sensitivity due to D-lactate acidosis susceptibility protocols, while supermarket self-selection formats face acute price elasticity.
Supply Chain Analysis
Ninety-day strain release schedules tether inventory management to ISO 17025 accreditation timelines, forcing formulation houses to carry elevated safety stock of cryoprotectant matrices and alginate encapsulation inputs. Supply concentrates in Germany's Bavaria culture collection cluster, Denmark's proprietary strain deposit facilities, and Vancouver's analytical microbiology laboratories. Raw material dependencies include pharmaceutical-grade fermentation media, enteric coating polymers, and cold-chain packaging systems. Single-source vulnerability runs through Chr. Hansen's proprietary Lactobacillus deposits for high-specification contract manufacturing. Distribution runs through practitioner-channel digitization in North American and Australian naturopathic networks, displacing legacy retail brand procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The D-lactate free probiotics market functions as a service-attach opportunity where batch-level third-party verification protocols and subscription-based practitioner-channel replenishment expand faster than hardware-format probiotic delivery systems.
For Market Incumbents: Compound analytical microbiology capabilities through captive ISO 17025 laboratory acquisition or exclusive contract laboratory partnerships, defending against CRISPR-guided metabolic pathway engineering entrants that collapse phenotype confirmation timelines. Prioritize pre-submission consultation investments with EFSA and Health Canada to secure conditional regulatory approvals ahead of competitors, locking in premium positioning before novel strain developers leverage GRAS self-affirmation acceleration. For New Entrants and Emerging Players: Differentiate on women's health vaginal positioning with pH-targeted release engineering, the most penetrable white space commanding price premiums through specialized strain combinations. Target pediatric functional food formulations in Germany where clinical validation standards create defendable moats against commodity assemblers. Pursue direct-to-clinic distribution partnerships with Ontario and British Columbia naturopathic prescribing networks as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified nutrition conglomerates lacking batch-level verification capabilities, specifically divisions with legacy retail brand positioning vulnerable to practitioner-channel displacement. Long-term viability centers on culture collection depth and regulatory submission track records rather than formulation scale. Monitor EFSA Qualified Presumption of Safety list updates as the critical inflection signal for novel strain market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Laboratory Acquisition | Captive phenotypic verification collapses strain release schedules from 90 days to 45 days for formulation houses. |
| Pre-Submission EFSA Consultation | Conditional approval investments secure six-month lead times over competitors in novel strain submissions. |
| Practitioner-Channel Digitization | Direct-to-clinic distribution displaces legacy retail brand loyalty in Australian TGA-registered product networks. |
| CRISPR Metabolic Engineering Integration | In-house genome editing compresses D-lactate dehydrogenase knockout verification from months to weeks. |
| Women's Health Strain Combination Development | Specialized urogenital positioning commands 40-60% price premiums through pH-targeted release engineering. |
Study Parameters
A standing panel of regulatory affairs leads at probiotic formulation houses, clinical microbiologists at German Federal Institute for Drugs and Medical Devices, naturopathic prescribing practitioners in Ontario and British Columbia, and procurement managers at compounding pharmacies provided ongoing calibration across primary interview cycles. Secondary validation drew from EFSA Qualified Presumption of Safety list updates, Health Canada Natural Product Number designation databases, FDA GRAS notification inventories, and ISO 17025 accreditation registries. Bottom-up strain-level demand modeling and top-down functional food category sizing were triangulated against practitioner-channel procurement data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type stability specifications, application cost tier stratification, distribution channel verification requirements, and end-user maturity gradients. CAGRs were derived from strain adoption curve analysis and regulatory pathway timeline differentials. Industry-specific forecast inputs incorporated EFSA toxicological endpoint expansion timelines and Health Canada site licensing backlog observations.
Material uncertainties — EFSA reclassification of live biotherapeutics, FDA pharmacovigilance requirement evolution, and CRISPR strain development cost collapse — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory pathway stability and practitioner-channel behavioral continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Bifidobacterium Probiotics Market
Probiotic Supplements
Psychobiotic Supplements Market
Probiotic Supplements
Herbal Yeast Market
Probiotic Supplements
United States Probiotics Market
Probiotic Supplements
Brewer Yeast Powder Market
Probiotic Supplements
United States Feed Probiotics Market
Probiotic Supplements
Europe Microbial Food Culture Market
Probiotic Supplements
Vegan Probiotics Market
Probiotic Supplements
Shelf Stable Probiotics Market
Probiotic Supplements
Probiotic Confectionery Market
Probiotic Supplements
South America Probiotics Market
Probiotic Supplements
Colon Cleansing Supplements Market
Probiotic Supplements
South America Digestive Health Supplements Market
Probiotic Supplements
Multistrain Probiotics Market
Probiotic Supplements
ASEAN Probiotic Supplements Market
Probiotic Supplements
Infant and Kids Probiotics Market