
 North America Microbial Food Culture Market | 2026-2036
North America Microbial Food Culture Market Size, Share, and Industry Trends Forecast 2026-2036
North America Microbial Food Culture Market Analytics
Specialized fermentation microbiologists is reorganizing how North American suppliers scale production capacity for dairy cultures and probiotic strains. Chr. Hansen Holding A/S leverages its culture collection depth to dominate strain development for yogurt and cheese applications. Lallemand Inc. competes through yeast and bacteria portfolios that span brewing, baking, and human nutrition. Kerry Group anchors its position with integrated taste and nutrition platforms that bundle microbial cultures with flavor systems.
Microbial food cultures comprise defined, viable preparations of bacteria, yeasts, or molds selected for specific metabolic activities including acidification, proteolysis, or flavor biogenesis, typically delivered at 10^9 to 10^12 colony-forming units per gram through freeze-drying or liquid suspension. These organisms serve industrial food manufacturing by converting substrates into preserved, palatable, or nutritionally enhanced products. Dairy cultures command the largest current volume given entrenched cheese and yogurt production infrastructure across the United States and Canada. Probiotics represent the fastest-expanding product category as consumer willingness to pay for gut-health positioning intensifies. Freeze-drying technology captures disproportionate margin pools due to extended shelf stability and reduced cold-chain dependency.
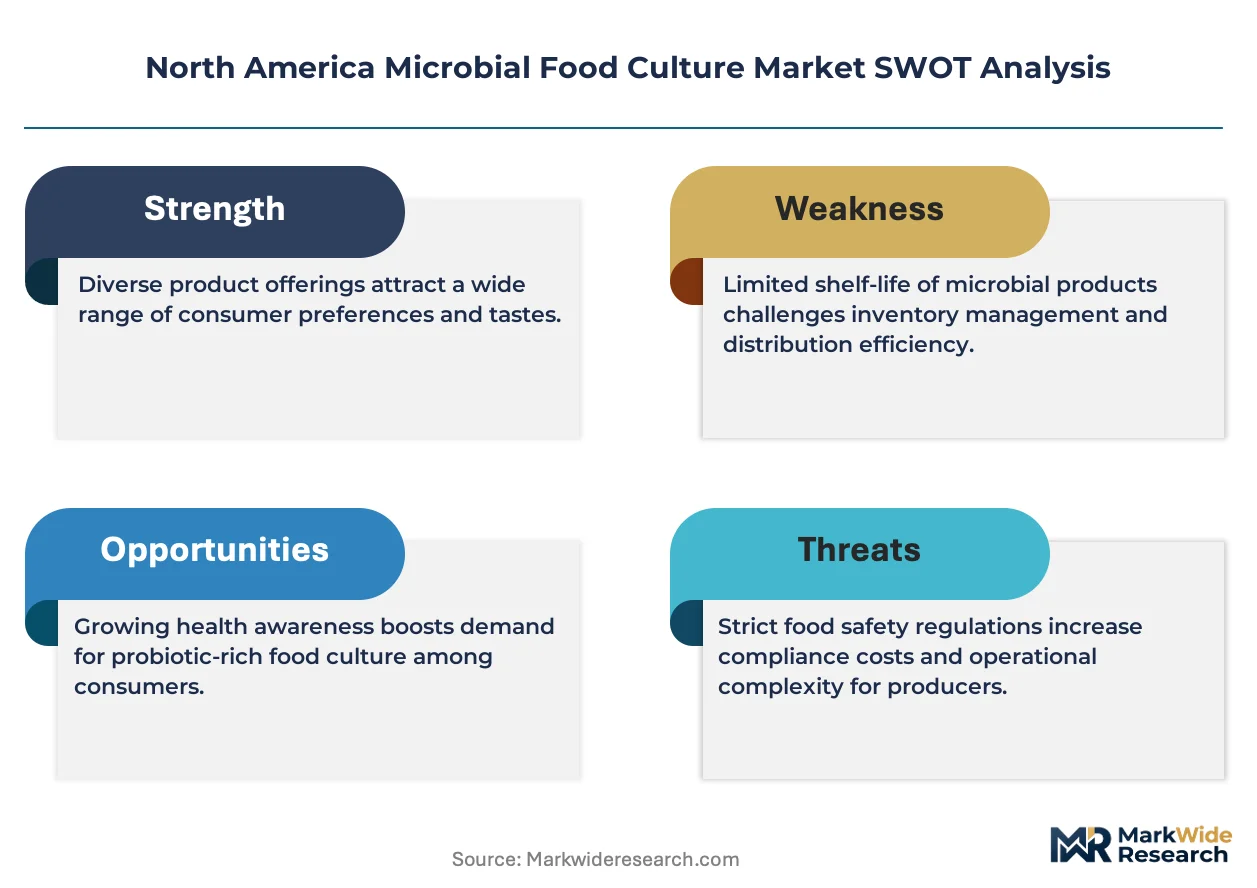
FDA oversight of Generally Recognized as Safe determinations and Health Canada's Novel Food regulations jointly govern which strains enter North American food and supplement channels. The FDA's evolving framework for live microbial ingredients in infant formula and medical foods creates compliance complexity that favors larger culture houses with dedicated regulatory affairs teams. Strain-level substantiation requirements from both agencies are intensifying documentation burdens for smaller suppliers. Stakeholders must monitor how harmonization pressures between U.S. and Canadian safety assessment protocols reshape market access timelines for new culture submissions.
Market Dynamics
Freeze-drying technology is compressing shelf-life constraints and cold-chain dependencies across dairy and probiotic culture supply chains, forcing mid-tier suppliers to absorb capital intensity or exit.
Growth Catalysts
- FDA GRAS pathway modernization:Streamlined safety determinations for qualified presumption of safety strains accelerate time-to-market for yogurt culture developers targeting infant formula applications.
- Precision fermentation infrastructure:Contract manufacturing capacity expansion in Wisconsin and California enables rapid strain scale-up without captive bioreactor investment.
- Health Canada Novel Food harmonization pressure:Convergence with U.S. safety assessment protocols reduces dual-submission burdens for cross-border culture suppliers.
Market Restraints
- Phage contamination vulnerability:Open-vat cheese production in Wisconsin and Quebec exposes artisanal producers to culture failure and batch loss without redundant strain sourcing.
- Freeze-dryer capital intensity:Industrial-scale lyophilization equipment requires seven-figure investment, concentrating viable production among culture houses with captive equipment.
- Strain-level documentation burden:FDA and Health Canada substantiation requirements for whole-genome sequencing and safety studies favor incumbents with dedicated regulatory affairs teams.
Strategic Opportunities
- Plant-based dairy alternatives:Fermentation-derived precision dairy proteins in California and Illinois create demand for specialized non-dairy culture matrices and co-culture systems.
- Direct-to-consumer probiotic channels:Refrigerated e-commerce logistics enable shelf-stable freeze-dried formats to bypass traditional foodservice distribution.
- Biomanufacturing tax incentives:U.S. Inflation Reduction Act credits for domestic bioproduction equipment reduce effective capex for culture expansion projects.
Industry Challenges
- Fermentation microbiologist scarcity:Academic pipeline gaps in industrial microbiology strain recruitment for culture development and scale-up troubleshooting functions.
- Legacy dairy equipment retrofit complexity:Existing tank infrastructure in Wisconsin cheese plants requires significant modification for aseptic probiotic culture handling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Microbial Food Culture Market |
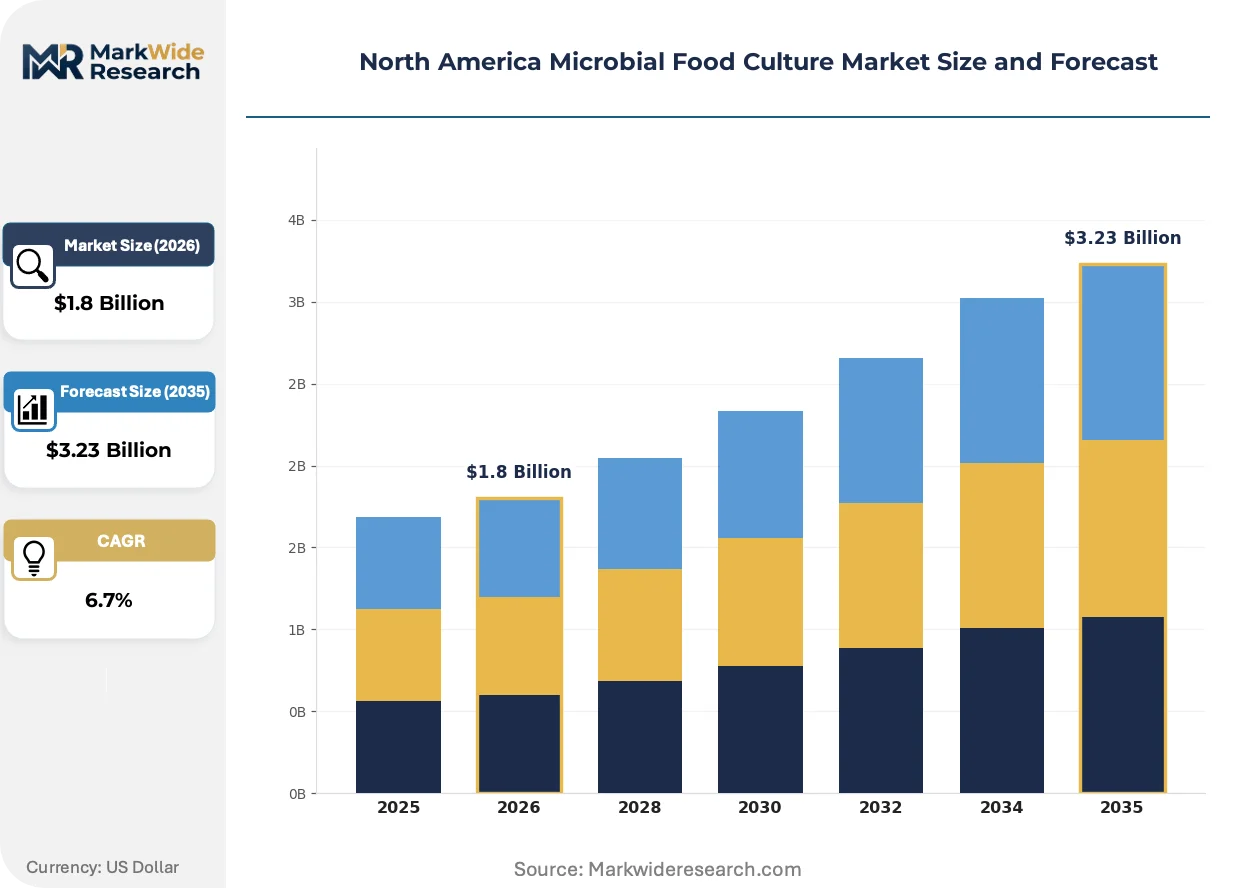
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Fermented Vegetables, Dairy Cultures, Fermented Beverages End User: Food Manufacturers, Beverage Producers, Household Consumers, Restaurants Technology: Freeze-Drying, Liquid Culture, Spray-Drying, Batch Fermentation Application: Food Preservation, Flavor Enhancement, Nutritional Enrichment, Texture Improvement |
| Companies Covered | Koninklijke DSM N.V., Corbion N.V., Kerry Group, CSK Food Enrichment, Cargill Incorporated, Chr. Hansen Holding A/S, Lallemand Inc., Lesaffre Group, DuPont Nutrition & Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Microbial Food Culture Market Evolving Landscape
Strain development workflows are fragmenting between high-throughput genomic screening and artisanal co-culture preservation, creating divergent capability requirements across the supplier base.
Single-cell genomics is bifurcating culture characterization standards. High-throughput droplet-based sequencing identifies metabolic traits invisible to plate-based methods. Large dairy culture houses adopt these platforms for accelerated strain selection. The technology is bifurcating competitive positioning between genomic-capable developers and traditional phenotype-screening suppliers.
FDA's evolving framework for live microbial ingredients in infant formula and medical foods intensifies documentation requirements. Strain-level safety substantiation now demands whole-genome sequencing and toxigenicity screening. Smaller culture suppliers without captive regulatory affairs capacity face extended review timelines. Dairy and probiotic segments respond by consolidating submissions through larger culture houses.
Foodservice buyers are unbundling culture supply from flavor system procurement. Integrated taste-and-nutrition platforms face disintermediation pressure as dairy processors seek direct strain sourcing for cost transparency. Independent culture specialists capture volume from bundled suppliers. This pattern concentrates in California and Wisconsin processing corridors where buyer scale supports dual-vendor strategies.
North America Microbial Food Culture Market Segmentation
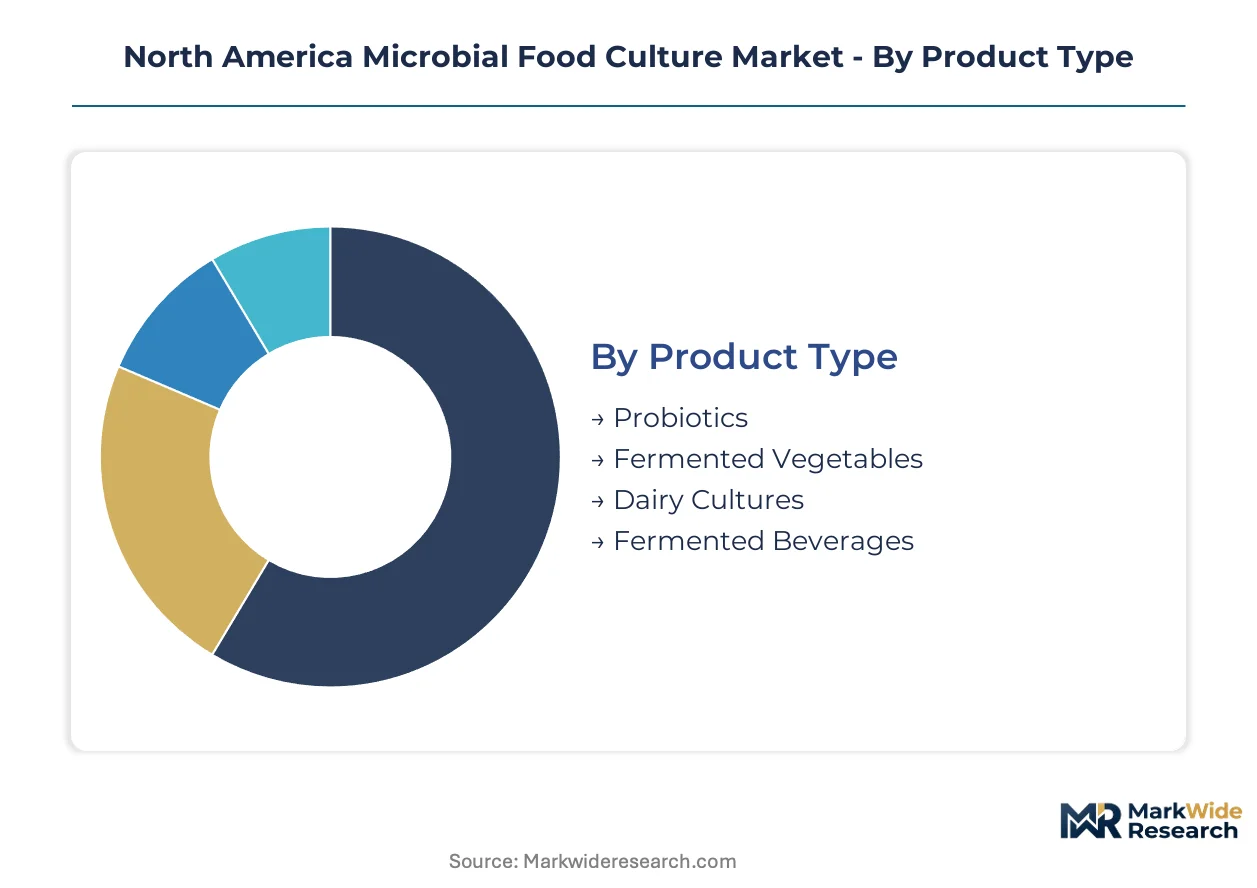
Microbial food culture suppliers structure their portfolios across four intersecting dimensions. Product type and technology choices determine capital allocation, while end-user concentration shapes geographic deployment of fermentation capacity.
Product Type:
Dairy cultures dominate domestic production volumes across Wisconsin and California processing corridors, while probiotic strains increasingly serve export channels to Asia-Pacific markets.
- Dairy Cultures:Defined bacterial preparations including thermophilic and mesophilic strains for cheese acidification and yogurt texturization. Demand concentrates in Wisconsin cheese plants and California yogurt facilities where FDA GRAS documentation requirements favor established culture houses with regulatory capacity.
- Probiotics:Viable preparations of Lactobacillus, Bifidobacterium, and emerging next-generation strains delivered at therapeutic concentrations. California and Illinois precision fermentation facilities drive strain development for gut-health positioned supplements and functional foods.
- Fermented Beverages:Yeast and bacterial cultures for kombucha, kefir, and craft brewing applications spanning craft producers in Colorado and Vermont.
- Fermented Vegetables:Lactobacillus-based cultures for kimchi, sauerkraut, and pickled vegetable production concentrated in Korean-American processing clusters in Los Angeles and New York.
Dairy cultures hold the largest share; momentum sits with probiotics.
End User:
Food manufacturers command volume through captive fermentation infrastructure, while beverage producers drive technology adoption for precision strain handling.
- Food Manufacturers:Integrated dairy processors and plant-based alternative producers operating fermentation at scale. Wisconsin cheese cooperatives and California yogurt multinationals specify strain performance metrics for acidification rates and proteolytic activity.
- Beverage Producers:Kombucha, craft beer, and functional drink manufacturers requiring specialized yeast and bacterial co-cultures. Colorado and Pacific Northwest craft breweries source regionally for strain freshness.
- Household Consumers:Direct-to-market starter cultures for home fermentation enthusiasts purchasing through refrigerated e-commerce channels.
- Restaurants:Artisanal kitchens and fermented menu specialists sourcing small-batch cultures for house-made preparations.
Food manufacturers anchor volume; beverage producers show the steepest expansion trajectory.
Technology:
Freeze-drying commands premium positioning through shelf stability advantages, while liquid culture retains cost leadership for high-turnover dairy applications.
- Freeze-Drying:Lyophilization technology delivering 10^9 to 10^12 CFU/gram with 24-month ambient stability. Capital intensity concentrates viable production among culture houses with captive seven-figure equipment investments in Wisconsin and California.
- Liquid Culture:Fresh fermentation broth requiring cold-chain distribution within 14-day windows. Dairy processors in Wisconsin and Quebec favor liquid formats for open-vat cheese production where phage rotation demands frequent strain refresh.
- Spray-Drying:Lower-cost dehydration for non-viable culture fractions and enzyme preparations.
- Batch Fermentation:Traditional tank-based propagation for captive culture production in large integrated dairy operations.
Freeze-drying captures margin concentration; liquid culture maintains volume dominance.
Application:
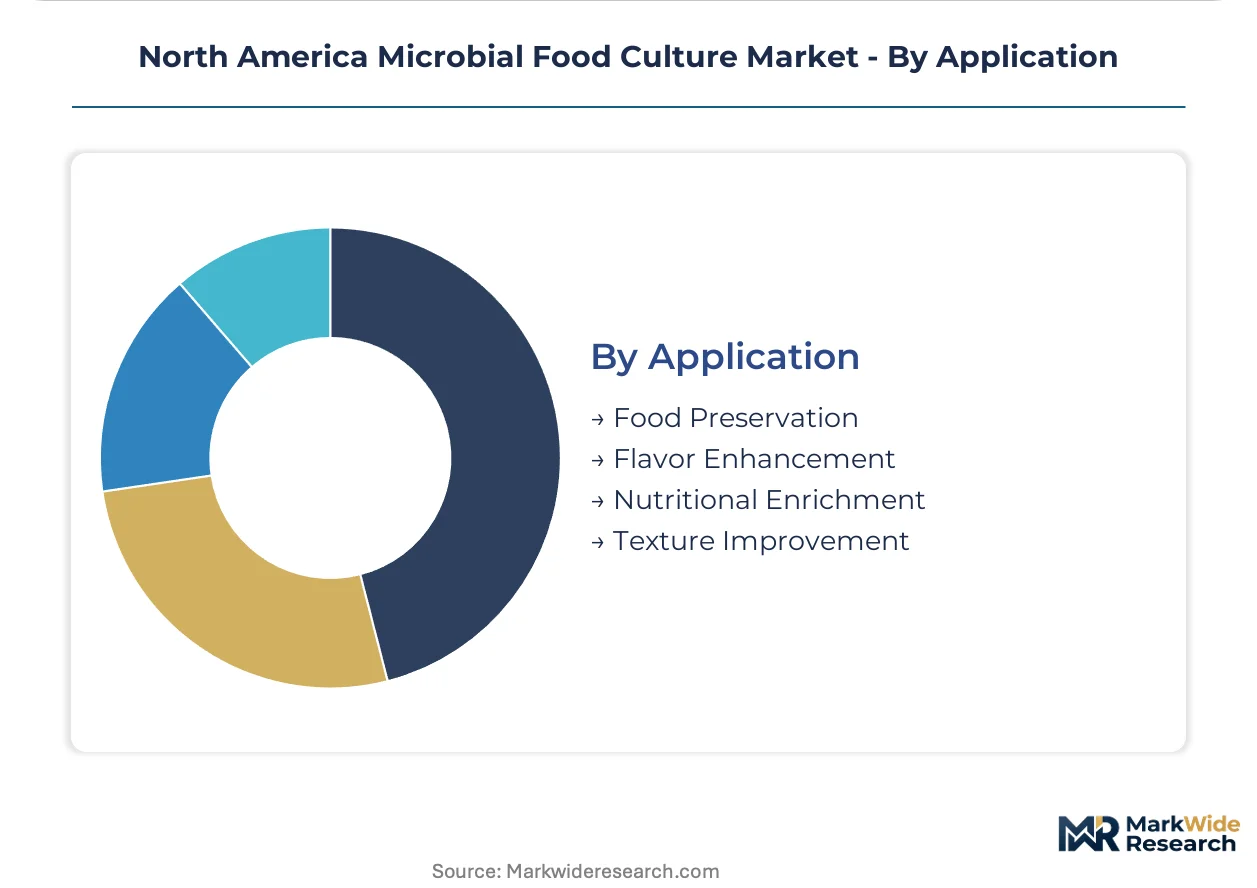
Flavor enhancement and nutritional enrichment applications command price premiums over commodity preservation functions.
- Flavor Enhancement:Proteolytic and lipolytic culture activities generating diacetyl, esters, and sulfur compounds for cheese and fermented beverage depth. Wisconsin aged cheddar and California wine-country artisan producers specify extended culture aging protocols.
- Nutritional Enrichment:Probiotic viability maintenance through gastric transit, vitamin K2 synthesis, and bioactive peptide generation. Health Canada Novel Food substantiation requirements shape strain selection for cross-border products.
- Food Preservation:Acidification for shelf-life extension in traditional fermented products.
- Texture Improvement:Exopolysaccharide production for yogurt viscosity and cheese body.
Flavor enhancement leads value capture; nutritional enrichment is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA GRAS determinations and Health Canada Novel Food regulations anchor North American market access protocols for microbial food cultures, with production infrastructure concentrating in dairy processing corridors across the United States and Canada.
United States
Wisconsin cheese cooperatives and California yogurt multinationals drive bulk demand for thermophilic and mesophilic dairy cultures. The FDA's qualified presumption of safety pathway accelerates strain approvals for infant formula applications. Milwaukee and Madison processing clusters host captive fermentation capacity for aged cheddar and specialty cheese production.
Canada
Quebec artisan cheese producers and Ontario dairy processors sustain liquid culture demand for open-vat production with frequent phage rotation. Health Canada Novel Food substantiation requirements for whole-genome sequencing shape cross-border product development timelines. Montreal and Toronto fermentation facilities specialize in probiotic strain handling for functional food applications.
Mexico
Jalisco and Nuevo León dairy processors expand culture adoption for queso fresco and yogurt production serving domestic retail channels. Mexican federal sanitary regulations for live microbial ingredients align with FDA safety assessment frameworks. Guadalajara processing clusters develop regional distribution networks for freeze-dried culture formats.
North America Microbial Food Culture Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North American microbial food culture market. The supplier base consolidates around culture houses with captive freeze-drying infrastructure and dedicated regulatory affairs capacity. Strategic archetypes include genomic-capable strain developers, integrated taste-and-nutrition platforms, and specialized yeast and bacteria portfolios. Dominant competitive moves encompass precision fermentation capacity expansion in Wisconsin and California corridors, plus strategic partnerships for cross-border regulatory harmonization.
Within the integrated platform tier, Kerry Group anchors bundled taste and nutrition offerings that combine microbial cultures with flavor systems. Chr. Hansen Holding A/S and Lallemand Inc. occupy positions spanning dairy, brewing, and human nutrition applications, representing the diversified culture house archetype with multi-segment strain portfolios. These three entities exemplify how regulatory capacity and production scale concentrate competitive positioning.
| Leading Market Players |
|---|
| Koninklijke DSM N.V. |
| Corbion N.V. |
| Kerry Group |
| CSK Food Enrichment |
| Cargill Incorporated |
| Chr. Hansen Holding A/S |
| Lallemand Inc. |
| Lesaffre Group |
| DuPont Nutrition & Biosciences |
| Others |
Value Network & Pricing Analysis
FDA GRAS determinations and Health Canada Novel Food regulations gate both supplier qualification and price differentiation simultaneously, forcing culture houses to absorb documentation costs that stratify pricing across regulatory-capable and non-capable tiers. Freeze-drying equipment investments concentrate margin capture among seven-figure-capable producers while liquid culture formats compete on volume through cold-chain efficiency.
Pricing Analysis
Wisconsin-to-California price spreads reflect divergent cold-chain costs and phage-rotation frequency demands. Three-tier pricing structure across premium freeze-dried, standard liquid, and economy spray-dried formats dominates procurement. Price differentiation hinges on strain certification depth and captive freeze-dryer ownership. Cost compression in liquid culture intensifies because dairy processors consolidate volume for acidification-rate guarantees. Artisanal cheese cooperatives show highest price sensitivity; infant formula culture buyers show least.
Supply Chain Analysis
Container availability constraints on trans-Pacific lanes elevate inbound logistics costs for specialized fermentation media components sourced from European suppliers. Production gravity centers on Wisconsin, California, and Quebec where dairy processing infrastructure anchors culture propagation. Raw material dependencies include whey permeate, yeast extract, and cryoprotectant formulations. Single-source vulnerability concentrates in phage-resistant strain repositories held by dominant culture houses. Distribution runs through temperature-controlled dairy ingredient channels terminating at processor fermentation facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a capital-investment trough as precision fermentation infrastructure buildouts signal cyclical recovery. FDA pathway modernization for qualified presumption of safety strains provides the demand-side confirmation.
For Market Incumbents: Compound regulatory capacity advantages by acquiring boutique strain developers lacking whole-genome sequencing documentation resources. Expand captive freeze-drying footprints in California corridors to capture probiotic margin pools before contract manufacturing commoditization accelerates. Emerging precision fermentation entrants threaten specialized culture demand for alternative protein applications. For New Entrants and Emerging Players: Anchor in plant-based dairy alternative co-culture systems where incumbent dairy culture houses lack optimized non-dairy matrices. Mexican queso fresco processors present the most penetrable geographic entry point given regulatory alignment with FDA frameworks. Direct-to-consumer freeze-dried starter formats bypass entrenched foodservice distribution gatekeepers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across contract precision fermentation capacity as biomanufacturing tax credits reduce effective equipment capex. Five-to-ten year viability favors genomic-capable strain developers with regulatory submission track records. Watch FDA infant formula culture approvals as inflection indicator for platform valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Wisconsin and California buildouts enable rapid probiotic strain scale-up without captive bioreactor investment. |
| Regulatory Affairs Team Augmentation | FDA GRAS documentation depth determines market access timelines for novel strain submissions. |
| Phage-Resistant Strain Repository Acquisition | Consolidation of redundant culture sources protects Wisconsin cheese cooperatives from batch failure. |
| Direct-to-Consumer Channel Development | Refrigerated e-commerce logistics bypass traditional foodservice distribution for home fermentation enthusiasts. |
| Cross-Border Regulatory Harmonization Partnership | Health Canada alignment with FDA safety protocols reduces dual-submission burdens for culture suppliers. |
Research Methodology
A standing panel of fermentation microbiologists, dairy processing plant managers, regulatory affairs directors at culture houses, and probiotic supplement brand managers provided ongoing calibration across the study period. Primary interview insights combined with secondary validation from FDA GRAS notification databases, Health Canada Novel Food submission records, USDA dairy production statistics, and SEC filings from publicly traded culture suppliers. Bottom-up strain-level volume estimates triangulated against top-down dairy and probiotic category consumption data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, technology format, end-user industry, and application function dimensions. CAGRs derived from segment-level growth rate reconciliation with macro dairy consumption trends and precision fermentation capacity expansion announcements. Strain approval timelines and phage contamination frequency data informed forecast sensitivity ranges.
Material uncertainties — regulatory pathway delays, phage outbreak severity, precision fermentation substrate cost volatility — sit outside the modeled envelope. Forecasts reflect assumptions about continued FDA-Health Canada protocol convergence and sustained dairy processing infrastructure investment. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
South America Microbial Food Culture Market
Probiotic Supplements
South America Feed Probiotics Market
Probiotic Supplements
Asia-Pacific Probiotics Market
Probiotic Supplements
South America Probiotics Market
Probiotic Supplements
Global Enteric Softgel Capsules Market
Probiotic Supplements
Lactobacillus Acidophilus Market
Probiotic Supplements
Asia-Pacific Feed Probiotics Market
Probiotic Supplements
Asia-Pacific Drinkable Yogurt Market
Probiotic Supplements
United States Digestive Supplement Market
Probiotic Supplements
Japan Probiotics Market
Probiotic Supplements
Europe Probiotics Market
Probiotic Supplements
Synbiotic Foods Market
Probiotic Supplements
Mediterranean Probiotic-Polyphenol Synbiotic Concepts Market
Probiotic Supplements
Probiotics Gummies Market
Probiotic Supplements
Global Liquid Feed Supplements Market
Probiotic Supplements
Bifidobacterium Probiotics Market