
 Vegan Probiotics Market | 2026-2036
Vegan Probiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Probiotics Market Analytics
Athletes and sports nutrition buyers is reorganizing demand away from traditional dairy-based probiotic users in the vegan probiotics space. DSM leverages its strain development capabilities to supply fermented food applications across European retail channels. Lallemand Inc. anchors its position through specialized yeast and bacteria cultures optimized for plant-based substrates. BioGaia AB differentiates via clinically documented strains targeting digestive health in vegan formulations.
Vegan probiotics comprise live microbial cultures derived entirely from non-animal sources, typically fermented in plant-based media such as oat, coconut, or pea protein substrates, with colony-forming unit counts ranging from one billion to fifty billion per serving. These cultures colonize the human gut microbiome to support digestive function, immune modulation, and nutrient absorption without reliance on dairy or animal-derived growth factors. Capsule formats dominate current shelf space due to stability advantages and precise dosing, while gummies represent the fastest-expanding format as taste-sensitive consumers enter the category. Fermented foods and beverages command premium positioning in health stores, whereas supplements distributed through online retail channels capture volume scale among price-sensitive vegetarians and health-conscious consumers.
The FDA regulates probiotic labeling and health claims under its dietary supplement framework, while EFSA in Europe evaluates novel food approvals and substantiates gut health benefit claims through rigorous clinical evidence requirements. REACH compliance shapes strain sourcing and fermentation input chemistry for manufacturers accessing European markets. Stakeholders must monitor evolving strain-specific approval pathways and adapt formulation portfolios to preempt tightening clean-label and animal-free certification standards.
Market Dynamics
Sports nutrition formulators are pulling vegan probiotic strains into recovery and performance positioning, compressing the traditional dairy-based dominance in functional beverages. This demand rotation is forcing fermentation houses to reconfigure substrate compatibility and shelf-stability protocols.
Growth Catalysts
- EU Green Deal compliance pressure:Fermentation facilities across Germany, France, and the Netherlands are retrofitting bioreactors to meet F-Gas Regulation standards, accelerating plant-based media adoption over animal-derived growth factors.
- Sports nutrition vertical expansion:Functional beverage makers targeting endurance athletes and CrossFit participants are integrating vegan probiotics into pre-workout and recovery formulations, creating strain demand at billion-CFU dosing levels.
- Clean-label certification proliferation:V-Label and Vegan Society certifications are becoming non-negotiable entry tickets for retail distribution in German supermarkets and health food chains.
Market Restraints
- Substrate cost volatility:Organic oat and pea protein hydrolysates face agricultural commodity swings, compressing margin predictability for fermentation runs.
- Strain IP concentration:Proprietary Lactobacillus and Bifidobacterium libraries remain concentrated among a handful of European culture houses, limiting new entrant access to clinically documented strains.
- Stability-versus-viability trade-off:Microencapsulation technologies required for ambient shelf life add processing costs that outpace conventional dairy-probiotic economics.
Strategic Opportunities
- Pediatric and geriatric white space:Underpenetrated age-specific formulations in Germany and Scandinavia offer first-mover positioning for taste-masked gummy and liquid formats.
- Direct-to-consumer subscription models:Online channels bypassing pharmacy and supermarket intermediaries are capturing recurring revenue from health-conscious urban professionals.
- Dual carbon goal alignment:China's national emissions targets are opening procurement pathways for fermentation inputs with verified lifecycle credentials.
Industry Challenges
- Strain-specific regulatory dossier assembly:EFSA novel food approvals require 18-24 month clinical substantiation timelines, delaying product launches.
- Fermentation scale-up talent scarcity:Industrial microbiologists with plant-based substrate expertise command premium compensation, constraining mid-tier manufacturer expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Probiotics Market |
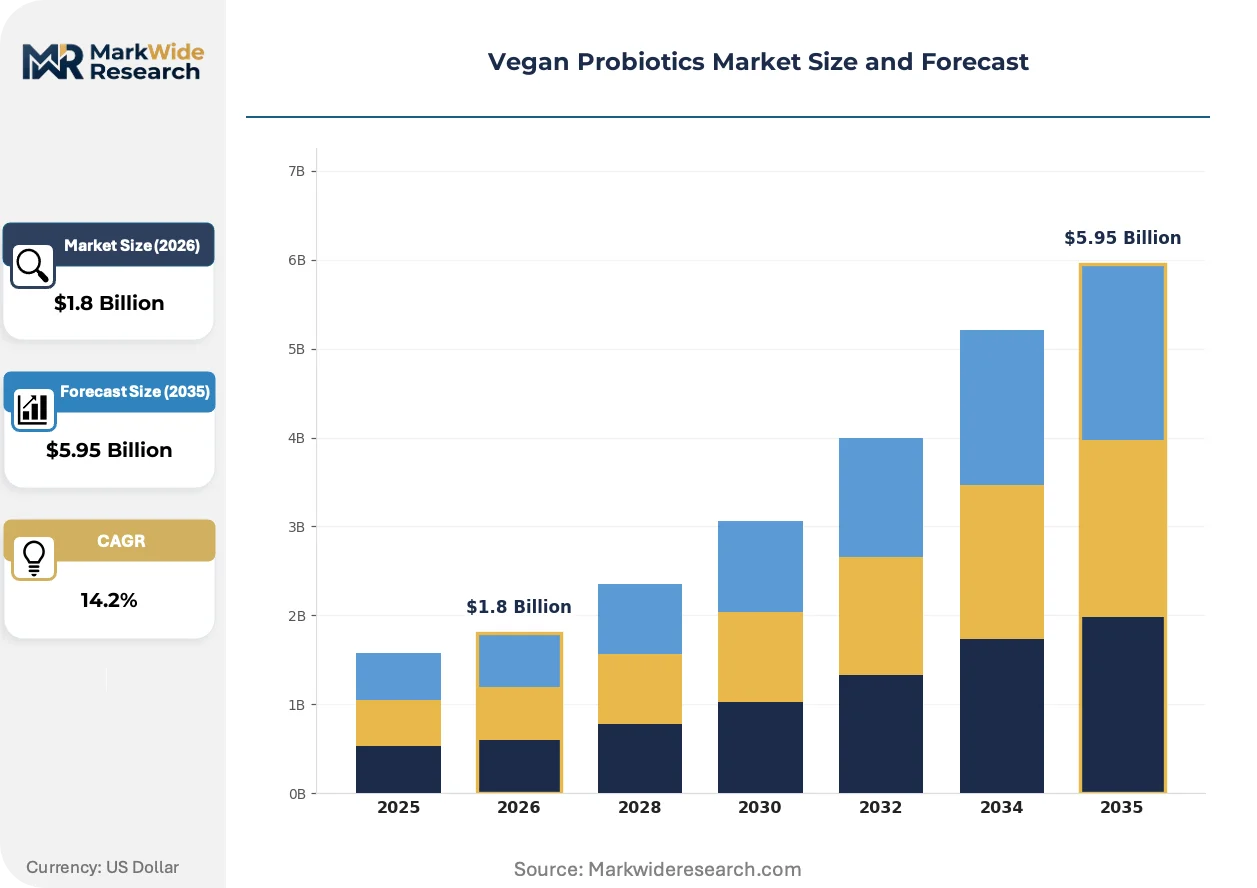
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powders, Gummies, Liquid Formulation: Fermented Foods, Supplements, Beverages, Yogurt Alternatives Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies End User: Health-Conscious Consumers, Vegetarians, Vegans, Athletes |
| Companies Covered | DSM, BioGaia AB, Yakult, PlantFusion, Lifeway Foods, Naturelo, Lallemand Inc., LoveBug Probiotics, Nature's Bounty, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Probiotics Market Evolving Landscape
Next-generation delivery formats and precision fermentation techniques are fragmenting the traditional capsule-dominated landscape. Formulators are racing to match dairy-based probiotic efficacy claims while satisfying clean-label scrutiny.
Precision fermentation using CRISPR-edited chassis organisms is bifurcating the strain development pipeline. Biotech startups and established culture houses are adopting metabolic engineering to boost short-chain fatty acid yields from plant-based media. This capability compression is enabling direct comparison with dairy-derived benchmark strains in clinical trials.
EFSA's evolving guidance on gut health claim substantiation is tightening evidence requirements for vegan formulations. Manufacturers must now generate strain-specific human intervention studies rather than borrowing generic probiotic literature. German and French applicants are responding by commissioning dedicated clinical programs before market entry.
Athlete and fitness influencer endorsement is displacing traditional healthcare practitioner recommendation as the primary purchase trigger. Social media channels and sport-specific podcasts are capturing discovery and education moments previously owned by pharmacies. This shift is most visible in urban German markets where CrossFit and triathlon participation concentrates.
Vegan Probiotics Market Segmentation
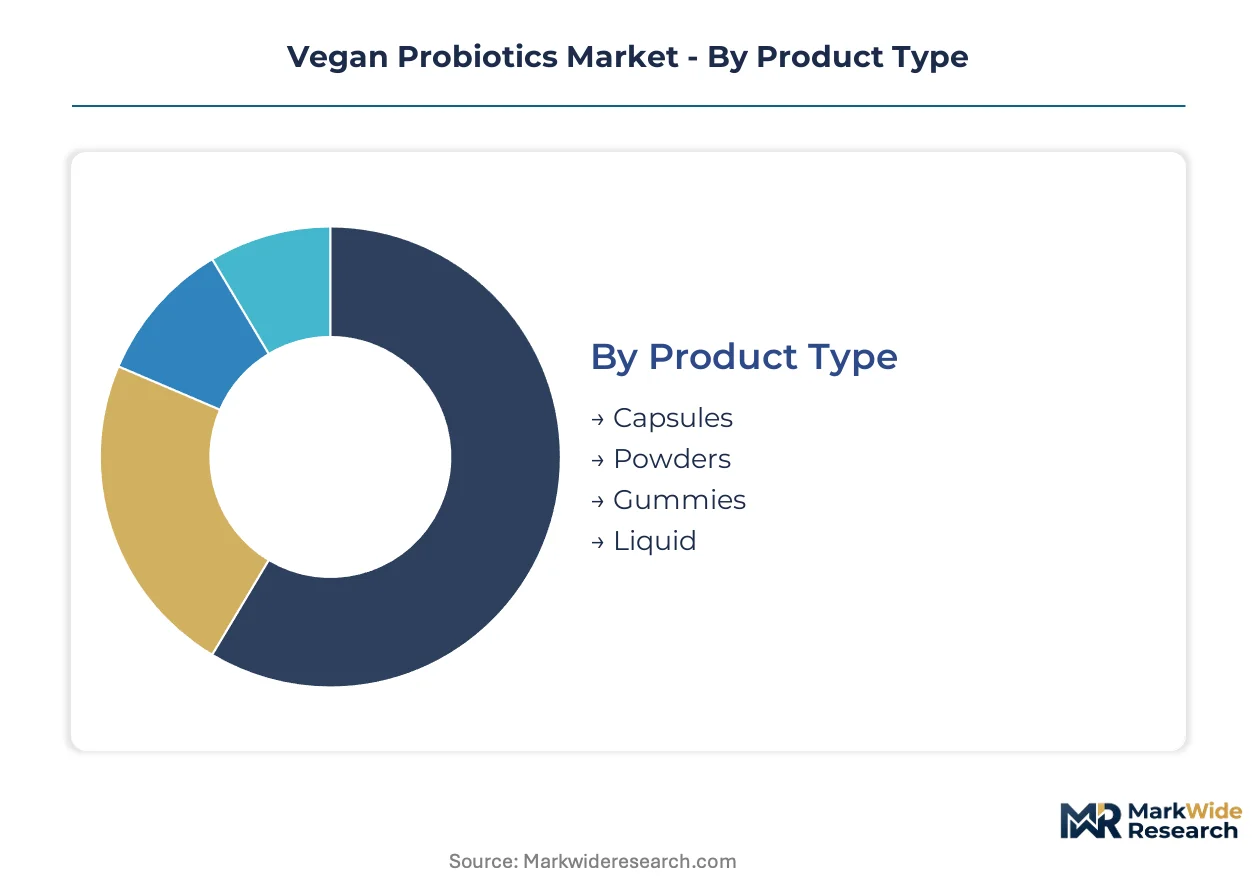
Vegan probiotics fragment across four intersecting dimensions that determine margin structure and channel strategy. Product format dictates stability investment and shelf positioning, while end-user identity shapes dosing requirements and certification premiums.
Product Type:
Domestic production concentrates on capsule and powder formats for German retail, whereas gummies and liquids flow through export-oriented e-commerce channels.
- Capsules:Hard-shell gelatin-free delivery systems with enteric coatings protect cultures through gastric passage, commanding pharmacy and health store placement in Berlin and Munich where precision dosing drives repeat purchase.
- Powders:Bulk formats with ten billion to one hundred billion CFU per serving integrate into smoothie and meal-replacement routines, finding traction among CrossFit communities in Hamburg and Stuttgart.
- Gummies:Pectin-based matrices mask bitterness through fruit-derived flavoring systems, expanding fastest among parents seeking pediatric compliance.
- Liquid:Ready-to-drink shots with shorter shelf lives concentrate in refrigerated health store sections and direct-to-consumer subscription models.
Capsules hold the largest share; momentum sits with gummies.
Formulation:
Cost tier separation runs deepest here, with fermented foods commanding premium positioning and supplements scaling through volume efficiency.
- Fermented Foods:Kimchi, sauerkraut, and tempeh carrying live cultures retail through organic chains and farmers markets in Cologne and Frankfurt, with V-Label certification adding fifteen to twenty percent price premiums.
- Supplements:Standardized CFU counts in blister packs and bottles dominate online retail through Amazon and dedicated wellness platforms, capturing recurring revenue from urban professionals.
- Beverages:Kombucha and water kefir variants with probiotic strain additions occupy refrigerated sections in REWE and Edeka supermarkets.
- Yogurt Alternatives:Coconut, oat, and almond-based fermented bases compete directly with dairy yogurt in German chilled dairy aisles.
Supplements generate the highest volume; fermented foods capture the steepest expansion trajectory.
Distribution Channel:
Customer type determines channel mix, with athletes clustering online and health-conscious seniors preferring pharmacy consultation.
- Online Retail:Subscription models and influencer-driven discovery through Instagram and sport-specific podcasts capture endurance athletes and triathlon participants across Germany.
- Supermarkets:REWE, Edeka, and Aldi Süd stock capsule and beverage formats in dedicated wellness sections, requiring mass-market pricing and prominent shelf positioning.
- Health Stores:Alnatura and independent organic retailers carry fermented foods and premium supplements with trained staff recommendation.
- Pharmacies:Apotheke channels demand EFSA-compliant health claims and clinical documentation, serving digestive health seekers and physician-referred patients.
Online retail is climbing the fastest; supermarkets maintain the broadest reach.
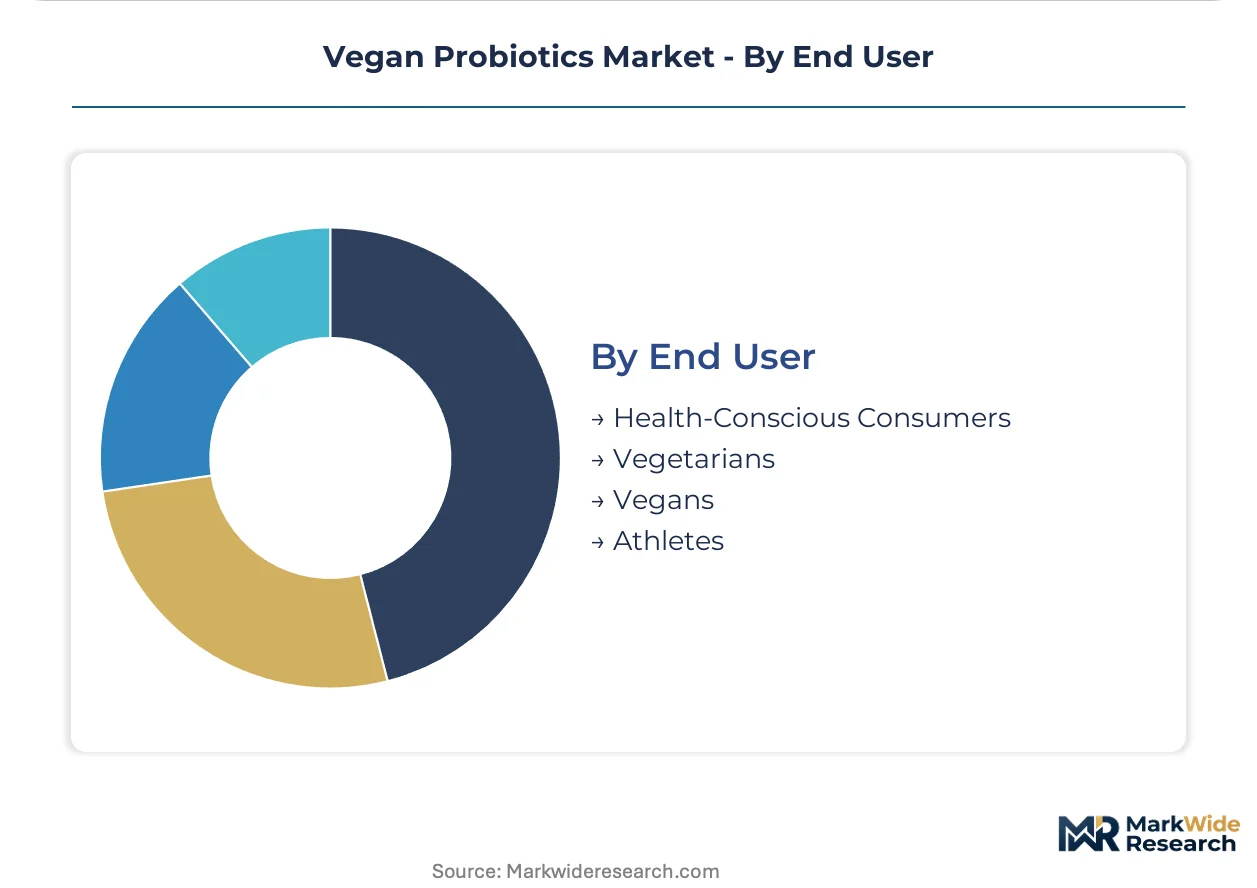
End User:
Application intensity varies sharply, with athletes requiring performance-oriented strains and vegetarians accepting lower CFU thresholds.
- Health-Conscious Consumers:Broad demographic seeking general wellness benefits through convenient daily formats, driving capsule and gummy volume in urban centers.
- Vegetarians:Flexitarian-adjacent buyers accepting occasional dairy crossover, less stringent on vegan certification than core vegan segments.
- Vegans:Ethical purists demanding full supply chain verification including fermentation substrate documentation and animal-free growth factor guarantees.
- Athletes:Endurance and strength-training populations prioritizing recovery strains with documented immune modulation, purchasing through sport nutrition specialists and team dietitian recommendation.
Health-conscious consumers represent the largest addressable base; athletes deliver the highest per-capita spend and brand loyalty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Athletes and endurance sports participants concentrate demand in Germany, while health-conscious urban professionals drive adoption across North American and Asian metropolitan clusters. Regulatory frameworks in the EU, US, and China are reshaping strain development and fermentation facility compliance requirements.
Germany
Plant-based dairy alternatives command strong retail penetration in Berlin and Munich, with V-Label certification becoming mandatory for supermarket placement. The EU Green Deal and F-Gas Regulation are tightening sustainability standards for fermentation-based production across Bavaria and North Rhine-Westphalia. DSM leverages its strain development capabilities to supply fermented food applications through REWE and Edeka distribution networks.
United States
Functional beverage makers are expanding vegan probiotic adoption in the sports nutrition category, targeting CrossFit and triathlon communities in California and Texas. FDA regulates probiotic labeling and health claims under its dietary supplement framework, creating compliance complexity for novel strain introductions. Precision fermentation startups in Boston and San Francisco are adopting CRISPR-edited chassis organisms to boost short-chain fatty acid yields.
China
Dual carbon goal alignment is opening procurement pathways for fermentation inputs with verified lifecycle credentials in Shanghai and Shenzhen. SAMR and national emissions targets are accelerating plant-based media adoption over animal-derived growth factors. Domestic biotech firms are retrofitting bioreactors to meet tightening clean-label standards for export-oriented production.
Japan
Health-conscious seniors in Tokyo and Osaka prefer pharmacy consultation channels for digestive health formulations. METI and PMDA oversight shapes strain-specific approval pathways and clinical evidence requirements. Fermented foods and beverages command premium positioning in health stores, with kombucha variants gaining traction among urban professionals.
France
EFSA novel food approvals require 18-24 month clinical substantiation timelines, delaying product launches for Paris-based applicants. ANSM and CNIL oversight intersects with gut health claim substantiation requirements. Alnatura and independent organic retailers in Lyon and Marseille carry fermented foods with trained staff recommendation driving purchase decisions.
Vegan Probiotics Market Competitive Landscape
Player mix skews toward specialized culture houses and diversified ingredient suppliers with fermentation expertise. The market exhibits moderate concentration, with proprietary strain libraries creating entry barriers for new participants. Strategic archetypes include clinical-documentation specialists, substrate-optimization engineers, and sports-nutrition format innovators. Dominant competitive moves encompass capacity expansion in plant-based fermentation facilities and technology licensing agreements for precision-engineered strains.
Within the clinical-documentation tier, BioGaia AB exemplifies the evidence-based positioning archetype through its focus on digestive health substantiation. DSM and Lallemand Inc. anchor the substrate-optimization segment, representing European culture houses with established fermentation infrastructure. These three entities occupy positions that reflect the industry's bifurcation between strain-specific clinical programs and broad-based supply capabilities.
| Leading Market Players |
|---|
| DSM |
| BioGaia AB |
| Yakult |
| PlantFusion |
| Lifeway Foods |
| Naturelo |
| Lallemand Inc. |
| LoveBug Probiotics |
| Nature's Bounty |
| Others |
Value Network & Pricing Analysis
Pea protein hydrolysate substitution for dairy-derived growth factors is redrawing fermentation facility geography across Germany and the Netherlands while compressing margin structures for mid-tier manufacturers locked into legacy animal-based substrate contracts. This input transition concentrates pricing power with European culture houses controlling certified organic oat and coconut media supply chains.
Pricing Analysis
Cost-plus contracts indexed to agricultural commodity futures dominate long-term supply agreements between German fermentation houses and sports nutrition formulators. Three-tier pricing structure across premium, standard, and economy levels separates V-Label certified strains from conventional vegan formulations and private-label alternatives. Pricing pressure stems from organic substrate cost volatility, with health-conscious consumers in online channels proving most price-sensitive while pharmacy-directed digestive health seekers accept clinical-documentation premiums.
Supply Chain Analysis
Strain IP concentration in Danish and French culture houses underwrites supply security for European vegan probiotic manufacturers. Fermentation capacity draws from Germany, the Netherlands, and France, with plant-based media sourcing resting on organic oat suppliers in Scandinavia and coconut processors in Southeast Asia. Single-source vulnerability around proprietary Lactobacillus libraries threatens new entrant scale-up, while distribution runs through REWE and Edeka supermarket networks alongside direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat story where EFSA novel food approval timelines create entrenched switching costs for documented strain holders. Incumbents benefit from 18-24 month clinical substantiation barriers that freeze out speculative entrants.
For Market Incumbents: Consolidate strain documentation archives through exclusive licensing with German university research centers to preempt competitive clinical programs. Capture backward integration into organic oat fermentation media production in Bavaria to neutralize agricultural commodity volatility threatening margin stability.
For New Entrants and Emerging Players: V-Label certification fast-track through German Vegan Society partnerships unlocks REWE and Edeka shelf placement without full EFSA novel food dossier completion. Target pediatric gummy formulations in Scandinavian markets where taste-masked delivery formats remain underpenetrated and parental compliance concerns override price sensitivity.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision fermentation startups in Boston and San Francisco possessing CRISPR-edited chassis organisms but lacking European regulatory navigation capabilities. Monitor EFSA guidance publication velocity as the inflection signal distinguishing viable acquisition targets from stranded clinical-program investments.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Submission | 18-24 month approval timelines lock in first-mover positioning for German applicants. |
| Precision Fermentation Scale-Up | CRISPR-edited chassis organisms boost short-chain fatty acid yields from oat substrates. |
| V-Label Certification Investment | Mandatory supermarket placement credential across REWE and Edeka wellness sections. |
| Direct-to-Consumer Channel Launch | Subscription models capture recurring revenue from CrossFit and triathlon communities. |
| Organic Substrate Backward Integration | In-house oat protein hydrolysate production insulates margin from commodity swings. |
Research Methodology
Cross-validation between primary interviews with fermentation facility directors and secondary analysis of EFSA novel food approval databases anchors the qualitative findings. This study combined discussions with plant-based substrate procurement managers, sports nutrition formulators, pharmacy category buyers, and clinical research coordinators alongside FDA dietary supplement filings, EU Green Deal compliance disclosures, and German organic certification records. Bottom-up strain volume estimates and top-down category spending patterns were reconciled across the analysis window.
Sensitivity analysis around substrate cost assumptions and regulatory approval timelines shaped the analytical framework. Segmentation dimensions modeled include product format, formulation type, distribution channel, and end-user identity across the projection horizon. CAGRs were derived from fitted trend extrapolation calibrated to historical adoption curves in adjacent functional beverage categories, with inputs from fermentation capacity expansion announcements and clean-label certification penetration rates.
Decision-makers should treat outputs as directional under sustained EU Green Deal enforcement and stable organic commodity supply; material deviation in F-Gas Regulation stringency or agricultural input costs would warrant model refresh. Practitioners should keep alternative scenarios live as EFSA gut health claim guidance evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Brewer Yeast Powder Market
Probiotic Supplements
Colon Cleansing Supplements Market
Probiotic Supplements
Probiotics After Antibiotic Recovery Market
Probiotic Supplements
Asia-Pacific Feed Probiotics Market
Probiotic Supplements
Mediterranean Probiotic-Polyphenol Synbiotic Concepts Market
Probiotic Supplements
Global Enteric Softgel Capsules Market
Probiotic Supplements
Herbal Yeast Market
Probiotic Supplements
Lactobacillus Acidophilus Market
Probiotic Supplements
South America Probiotics Market
Probiotic Supplements
Infant and Kids Probiotics Market
Probiotic Supplements
Poultry Probiotics Market
Probiotic Supplements
Psychobiotic Supplements Market
Probiotic Supplements
South America Digestive Health Supplements Market
Probiotic Supplements
Bifidobacteria Lysates Market
Probiotic Supplements
South America Feed Probiotics Market
Probiotic Supplements
Asia-Pacific Probiotics Market