
 Global Liquid Feed Supplements Market | 2026-2036
Global Liquid Feed Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Global Liquid Feed Supplements Market Outlook
Veterinary nutritionist shortages across North American feedlots is unwinding capacity expansion plans at several major suppliers. Cargill, Incorporated leverages its integrated oilseed processing network to secure cost-advantaged bypass fat inputs for liquid formulations. Archer Daniels Midland Company anchors its position through continent-spanning molasses terminal infrastructure. BASF SE differentiates via precision-delivery vitamin premix technologies that resist degradation in aqueous suspensions.
Liquid feed supplements comprise aqueous or oil-based suspensions of proteins, carbohydrates, minerals, and vitamins designed for incorporation into total mixed rations or free-choice feeding systems, typically achieving dry matter contents of 50-65 percent to ensure pumpability and homogeneous nutrient distribution. Their primary commercial purpose centers on closing nutritional gaps in high-production livestock systems where forage quality fluctuates seasonally or where grain-based diets create specific amino acid or mineral deficiencies. Protein supplements occupy the largest value share due to sustained soybean meal and urea-molasses blending demand across ruminant operations, while mineral supplements represent the fastest-expanding category as precision livestock farming adoption drives customized trace-element programming. The aquaculture end-user segment commands premium formulation margins despite smaller volume, given the species-specific digestibility requirements and water-stability demands of shrimp and salmonid diets.
The FDA's Center for Veterinary Medicine oversees new animal drug approvals for medicated liquid feeds, while the EU's Feed Hygiene Regulation imposes mandatory HACCP documentation on all manufacturing facilities supplying member states. Brazil's Ministry of Agriculture enforces MAPA Normative Instruction requirements for liquid feed labeling and maximum contaminant thresholds that directly shape export-accessible formulation standards. Stakeholders must monitor evolving antibiotic-resistance policies that threaten ionophore inclusion permissions and assess alternative growth-promotion technologies before regulatory deadlines compress formulation transition timelines.
Market Dynamics
The Global Liquid Feed Supplements Market faces intensifying pressure from veterinary nutritionist shortages across North American feedlots, forcing suppliers to automate formulation services and compress technical support margins while herd sizes expand.
Growth Catalysts
- Brazil MAPA Normative Instruction:Export-accessible formulation standards in Brazil's Mato Grosso cattle finishing operations create compliant manufacturing templates that unlock cross-border trade flows.
- Precision livestock farming:Sensor-enabled trace-element programming drives customized mineral supplement demand in high-output dairy systems where seasonal forage variation creates nutritional gaps.
- Molasses terminal infrastructure:Continent-spanning storage and blending networks reduce input cost volatility for energy supplement programs serving Midwest United States dairy cooperatives.
Market Restraints
- Soybean meal price volatility:Protein supplement margins compress when oilseed processing costs spike, squeezing urea-molasses blenders dependent on commodity feedstock arbitrage.
- EU Feed Hygiene Regulation HACCP mandates:Mandatory documented traceability requirements impose fixed compliance costs that disadvantage smaller liquid feed additive manufacturers lacking integrated quality systems.
- Dry supplement substitution:Pelleted mineral and protein products compete on storage stability and transport economics in remote grazing operations beyond liquid distribution radius.
Strategic Opportunities
- Shrimp and salmonid aquaculture:Species-specific digestibility requirements and water-stability demands command premium formulation margins in concentrated coastal farming zones.
- FDA Center for Veterinary Medicine alternative growth-promotion pathways:Pre-regulatory deadline positioning for ionophore replacement technologies creates first-mover advantage in medicated liquid feed segments.
- Blockchain-enabled supply chain verification:Immutable batch documentation satisfies EU Feed Hygiene Regulation audit requirements while opening premium pricing tiers for traceability-guaranteed products.
Industry Challenges
- Veterinary nutritionist talent scarcity:Feedlot technical service capacity constraints delay herd-specific ration optimization and slow customer onboarding at expansion-stage suppliers.
- Aqueous suspension stability:Vitamin premix degradation in high-moisture formulations demands continuous innovation in encapsulation and delivery system design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Liquid Feed Supplements Market |
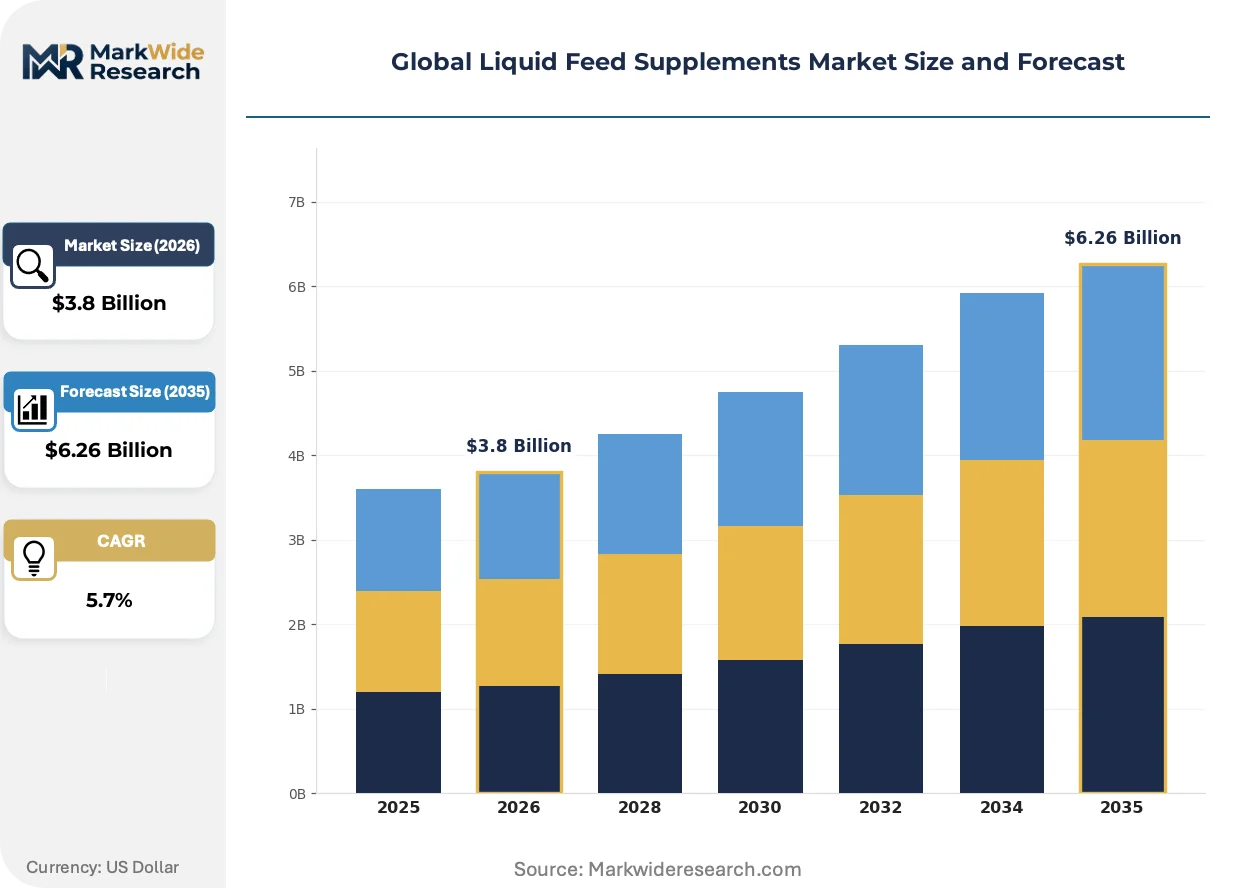
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Supplements, Energy Supplements, Mineral Supplements, Nutritional Additives End User: Livestock, Poultry, Aquaculture, Ruminants Application: Growth Promotion, Milk Production, Weight Gain, Health Improvement Distribution Channel: Direct Sales, Retail, Online, Wholesalers |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Land O'Lakes Inc., BASF SE, GrainCorp Ltd., Bundaberg Molasses, Quality Liquid Feeds, Novus International, Inc, Dallas Keith Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Liquid Feed Supplements Market Strategic Shifts
Formulation science and regulatory compliance architectures are converging to reshape competitive positioning in livestock nutrition, with aqueous delivery systems gaining technical sophistication against traditional dry-feed alternatives.
Microencapsulated bypass fat technologies are displacing unprotected lipid supplements in high-production dairy rations. Large herd operators in the Upper Midwest United States adopt these systems at accelerating rates. The shift compresses commodity fat premix margins while rewarding suppliers with in-house oilseed processing capabilities.
REACH and EU Feed Hygiene Regulation convergence is tightening contaminant thresholds and documentation requirements for all liquid additives entering European supply chains. Manufacturing facilities must now maintain dual-certified quality systems. Protein supplement exporters to Germany and France face the steepest compliance cost escalations.
Direct-to-feedlot technical service models are replacing distributor-mediated sales in North American cattle finishing operations. Nutrition software platforms enable remote formulation support that bypasses traditional dealer networks. The disintermediation is most advanced in Texas Panhandle and Nebraska feedlot clusters where buyer concentration supports dedicated supplier relationships.
Global Liquid Feed Supplements Market Segmentation
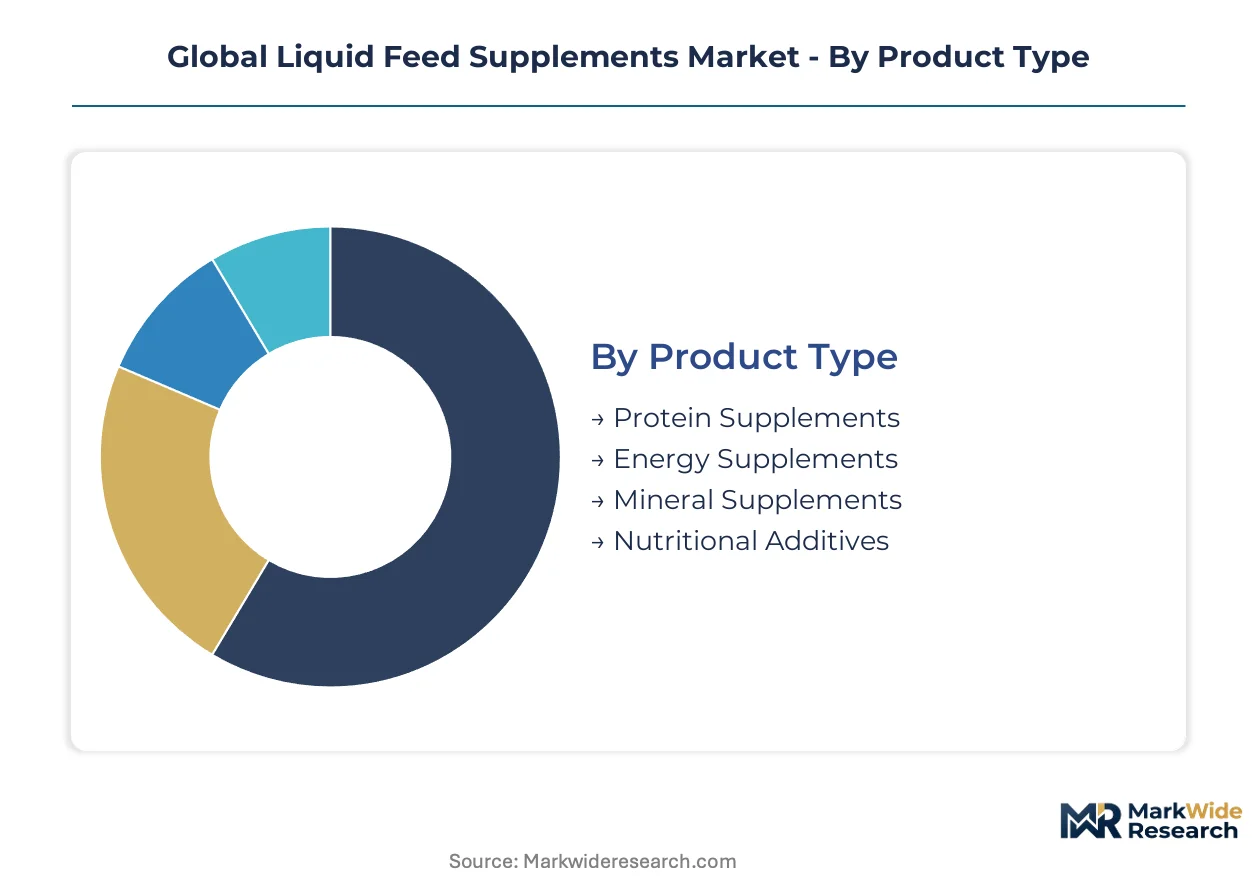
Segmentation in liquid feed supplements reveals divergent margin structures across product categories and distribution pathways. Protein and energy formulations serve fundamentally different herd economics than precision mineral programming, while aquaculture applications command formulation premiums unavailable in commodity livestock channels.
Product Type:
Protein and energy supplements concentrate in domestic North American and Brazilian cattle operations, while mineral formulations and nutritional additives increasingly serve export-led precision livestock farming demand in the European Union and Southeast Asia.
- Protein Supplements:Aqueous suspensions of soybean meal, urea, and molasses blends designed for ruminant rumen-degradable protein delivery. Demand clusters in Mato Grosso cattle finishing yards where cost-per-gain optimization favors liquid over dry inclusion methods.
- Energy Supplements:Molasses-based carbohydrate suspensions achieving 50-65 percent dry matter for pumpable TMR incorporation. Midwest United States dairy cooperatives expand herd programs here as forage quality fluctuates seasonally.
- Mineral Supplements:Precision-delivery trace-element suspensions for customized livestock programming.
- Nutritional Additives:Vitamin premix and specialty compound formulations resisting aqueous degradation.
Protein supplements hold the largest share; momentum sits with mineral supplements.
End User:
Cost tier differentiation separates commodity livestock applications from premium aquaculture and precision ruminant systems requiring species-specific digestibility engineering.
- Livestock:Broad-category cattle and swine operations utilizing energy and protein liquid feeds for growth promotion and feed efficiency. Volume concentrates in Brazilian feedlots and North American finishing operations where labor automation favors pumpable delivery systems over manual dry-feed handling.
- Aquaculture:Shrimp and salmonid farming systems demanding water-stable formulations with species-specific amino acid profiles. Coastal farming zones in Southeast Asia and Norway command premium margins for formulations meeting exacting digestibility coefficients.
- Poultry:Broiler and layer operations incorporating liquid vitamins and minerals into automated drinking systems.
- Ruminants:Dairy and beef cattle systems utilizing bypass fat and rumen-protected nutrient suspensions.
Livestock commands volume leadership; aquaculture delivers the steepest expansion trajectory.
Application:
Application focus shifts from growth-centric formulations toward health improvement and milk production optimization as antibiotic-resistance policies reshape permitted additive categories.
- Growth Promotion:Ionophore and alternative growth-promotion liquid feeds for cattle finishing. Regulatory pressure from FDA Center for Veterinary Medicine deadlines compresses formulation transition timelines toward non-antibiotic technologies.
- Milk Production:Bypass fat and precision mineral suspensions for high-output dairy systems. Upper Midwest United States large herd operators adopt microencapsulated lipid technologies at accelerating rates.
- Weight Gain:Energy-dense molasses-protein blends for feedlot cattle finishing economics.
- Health Improvement:Functional additive formulations supporting immune function and metabolic stability.
Growth promotion retains installed base dominance; health improvement applications gain share fastest.
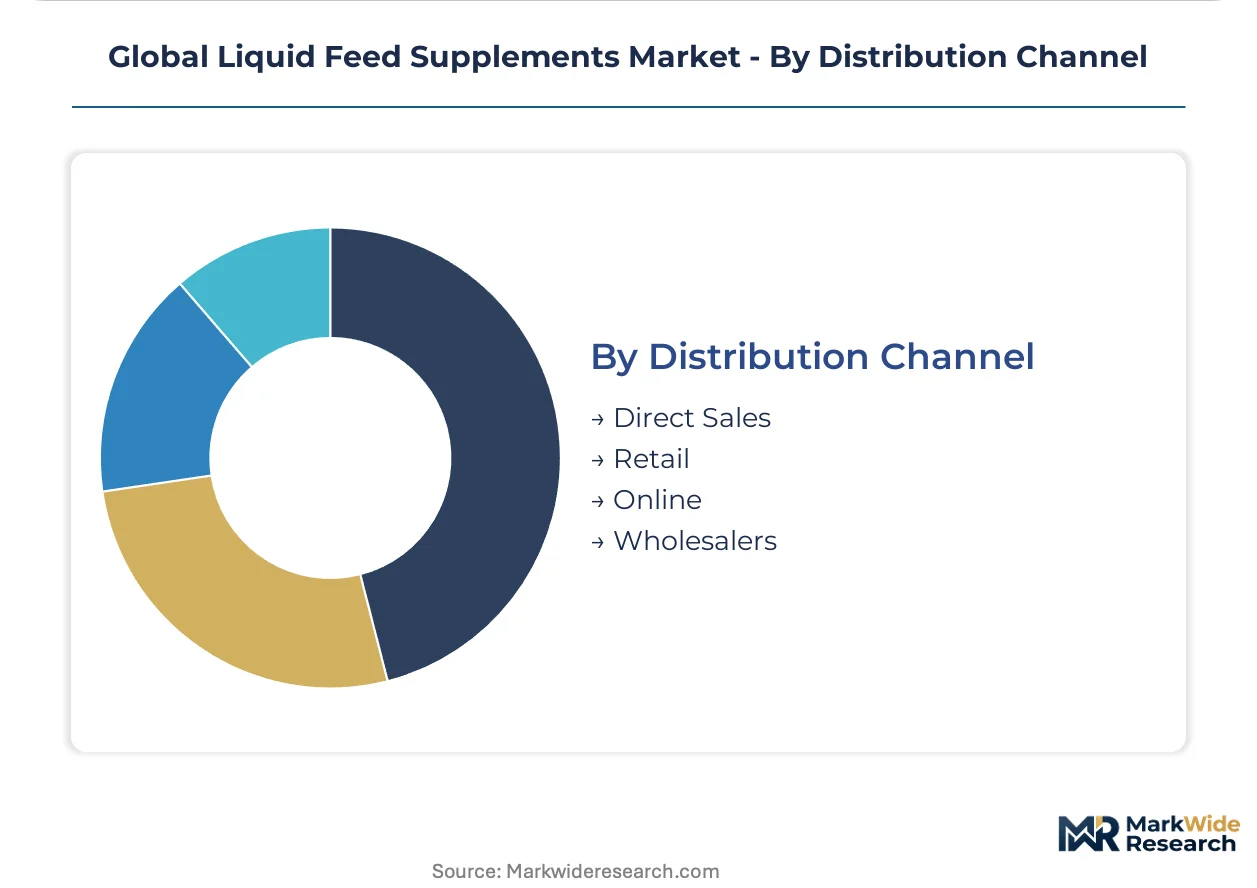
Distribution Channel:
Customer type fragmentation drives channel bifurcation between concentrated feedlot direct relationships and fragmented smallholder retail and digital access pathways.
- Direct Sales:Supplier-to-feedlot technical service models bypassing traditional dealer networks. Texas Panhandle and Nebraska cattle feeding clusters support dedicated nutritionist relationships with formulation software platforms enabling remote ration optimization.
- Online:Digital procurement channels for smaller livestock operators and specialty additive purchases. Platform growth accelerates as veterinary nutritionist scarcity forces automation of technical support functions.
- Retail:Farm supply stores and cooperatives serving mixed livestock and poultry operations.
- Wholesalers:Regional distributors aggregating volume for remote grazing operations beyond liquid distribution radius.
Direct sales capture the largest value contribution; online channels climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA anchors the United States regulatory framework for medicated liquid feeds, while Brazil's MAPA and the EU's EFSA impose parallel compliance architectures that shape export-accessible manufacturing standards across three continents.
United States
Midwest dairy cooperatives expand molasses-based energy programs for lactating herds, while Texas Panhandle feedlots automate liquid delivery systems to reduce labor costs. The FDA's Center for Veterinary Medicine oversees new animal drug approvals for ionophore inclusion. Large herd operators in Nebraska and Wisconsin adopt microencapsulated bypass fat technologies at accelerating rates.
Brazil
Mato Grosso cattle finishing yards favor liquid supplementation for cost-per-gain optimization against dry-feed alternatives. MAPA Normative Instruction requirements govern labeling and maximum contaminant thresholds for export-bound formulations. São Paulo-state processors build compliant manufacturing templates that unlock cross-border trade flows into Mercosur markets.
Germany
Precision livestock farming adoption drives customized trace-element programming in high-output dairy systems across Lower Saxony and Bavaria. REACH convergence with EU Feed Hygiene Regulation tightens contaminant thresholds for all liquid additives entering European supply chains. Manufacturing facilities in North Rhine-Westphalia maintain dual-certified quality systems to serve export demand.
China
Coastal aquaculture zones in Guangdong and Fujian provinces demand water-stable formulations for shrimp farming operations. The Ministry of Agriculture and Rural Affairs enforces feed safety standards that align with import market requirements. Yangtze River Delta integrators develop species-specific digestibility engineering for premium salmonid diets.
Australia
Queensland and New South Wales feedlots deploy liquid protein supplements during drought periods when forage quality deteriorates. The Department of Agriculture, Water and the Environment administers biosecurity protocols for imported feed additives. Melbourne-based nutrition software platforms enable remote formulation support that bypasses traditional dealer networks.
Global Liquid Feed Supplements Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in liquid feed supplements, with oilseed processors and molasses terminal operators commanding input cost advantages over pure-play blenders. The structure rewards backward integration into bypass fat and carbohydrate feedstocks while compressing margins for distributors lacking captive supply. Three archetypes dominate: integrated agribusiness conglomerates with oilseed processing networks, molasses infrastructure specialists with continent-spanning storage assets, and precision-nutrition technology providers with encapsulation capabilities. Competitive moves concentrate on M&A to secure terminal infrastructure and strategic partnerships to embed formulation software into customer operations.
Among integrated agribusiness conglomerates, Cargill, Incorporated and Archer Daniels Midland Company exemplify the oilseed-processing archetype, leveraging in-house supply chains to secure cost-advantaged inputs for liquid formulations. BASF SE occupies a position within the precision-nutrition tier, representing suppliers that differentiate via delivery technologies resisting aqueous degradation. These three anchors illustrate how scale and specialization create defensible positions against commodity blending competition.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Land O'Lakes Inc. |
| BASF SE |
| GrainCorp Ltd. |
| Bundaberg Molasses |
| Quality Liquid Feeds |
| Novus International, Inc |
| Dallas Keith Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Midwest dairy cooperatives and molasses terminal operators lock in supply access while anchoring price visibility against Brazilian spot-market volatility. These arrangements transfer inventory risk upstream and stabilize formulation costs for energy supplement programs serving lactating herds.
Pricing Analysis
Geographic price spreads between Mato Grosso cattle finishing yards and Upper Midwest dairy operations reflect divergent logistics economics and regional input cost structures. Three-tier pricing structure across premium, standard, and economy levels separates aquaculture-grade water-stable formulations from commodity livestock blends and generic mineral suspensions. Price differentiation stems from certification grade against EU Feed Hygiene Regulation standards and volume scale in direct-to-feedlot procurement. Cost compression in protein supplements is intensifying because soybean meal arbitrage margins narrow when oilseed processing spikes. Smallholder poultry operators through retail channels exhibit highest price sensitivity; aquaculture integrators in coastal China and Norway show lowest.
Supply Chain Analysis
Port congestion along Asia-Pacific trade lanes elevates inbound logistics costs for vitamin premix raw materials sourced from European chemical manufacturers. Supply concentrates in Brazil for molasses feedstocks, the United States for oilseed-derived bypass fats, and Germany for precision-delivery encapsulation technologies. Formulation networks draw from urea, soybean meal, and microencapsulation polymers as critical inputs. Single-source vulnerability in veterinary nutritionist technical service capacity threatens feedlot customer onboarding timelines. Distribution runs through direct sales relationships with concentrated feedlot clusters, supplemented by digital platforms for fragmented smallholder access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized talent gaps in aqueous suspension stability engineering and precision livestock farming integration constrain expansion velocity for suppliers serving automated dairy and feedlot systems.
For Market Incumbents: Secure captive molasses terminal infrastructure in Mercosur trade zones to defend against dry supplement substitution threats in remote grazing operations. Deepen backward integration into oilseed processing networks for cost-advantaged bypass fat inputs that protect margin position when commodity fat premix pricing softens. For New Entrants and Emerging Players: EU Feed Hygiene Regulation HACCP fast-track certification unlocks premium pricing tiers in German and French precision livestock farming markets underserved by integrated agribusiness conglomerates. Target shrimp aquaculture zones in Guangdong and Fujian provinces with species-specific digestibility engineering capabilities. Embed formulation software platforms into customer operations as the primary go-to-market mechanism. For Investors and Strategic Acquirers: Precision-nutrition technology providers with aqueous degradation-resistant encapsulation capabilities represent the most defensible acquisition archetype against commodity blending competition. Long-term viability hinges on regulatory positioning ahead of FDA Center for Veterinary Medicine ionophore replacement deadlines. Watch for acceleration in microencapsulated bypass fat adoption rates among Upper Midwest large herd operators as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Processing | Cargill and ADM leverage in-house supply chains to secure cost-advantaged bypass fat inputs for dairy formulations. |
| Molasses Terminal Infrastructure Expansion | Continent-spanning storage networks reduce input cost volatility for Midwest dairy cooperative energy programs. |
| Precision-Delivery Encapsulation R&D | BASF differentiates via vitamin premix technologies resisting degradation in high-moisture aqueous suspensions. |
| Blockchain-Enabled Supply Chain Verification | Immutable batch documentation satisfies EU Feed Hygiene Regulation audit requirements for premium pricing access. |
| Direct-to-Feedlot Technical Service Model | Nutrition software platforms enable remote formulation support bypassing traditional dealer networks in Texas Panhandle clusters. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA Center for Veterinary Medicine filings, EU Feed Hygiene Regulation documentation, and Brazilian MAPA Normative Instruction compliance records. Primary interviews engaged veterinary nutritionists at North American feedlots, procurement directors at Midwest dairy cooperatives, plant managers at molasses terminal facilities, and regulatory affairs specialists at liquid feed additive manufacturers. Secondary validation drew from customs and trade data, SEC 10-K disclosures of integrated agribusiness conglomerates, and industry association production statistics. Bottom-up volume estimates triangulate against top-down value assessments across product type, end user, application, and distribution channel dimensions.
Segmentation dimensions modeled include protein, energy, mineral, and nutritional additive product categories; livestock, aquaculture, poultry, and ruminant end users; growth promotion, milk production, weight gain, and health improvement applications; and direct sales, online, retail, and wholesaler channels. CAGRs derive from trend extrapolation anchored in historical volume trajectories and elasticity-adjusted demand projections across the analysis window. Forecast inputs incorporate veterinary nutritionist capacity constraints, precision livestock farming adoption curves, and regulatory deadline compression effects on ionophore replacement transitions.
Decision-makers should treat outputs as directional under assumptions of stable MAPA and EU Feed Hygiene Regulation enforcement intensity and continued soybean meal price volatility within historical bands; material deviation would warrant model refresh. Specific risk factors include accelerated antibiotic-resistance policy restrictions, drought-induced forage quality deterioration in Australian feedlot zones, and aquaculture disease outbreaks disrupting species-specific formulation demand. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Europe Probiotics Market
Probiotic Supplements
Poultry Probiotics Market
Probiotic Supplements
Infant and Kids Probiotics Market
Probiotic Supplements
Probiotics After Antibiotic Recovery Market
Probiotic Supplements
Lactobacillus Acidophilus Market
Probiotic Supplements
United States Digestive Supplement Market
Probiotic Supplements
Synbiotic Foods Market
Probiotic Supplements
North America Microbial Food Culture Market
Probiotic Supplements
Women Probiotic Market
Probiotic Supplements
Asia-Pacific Drinkable Yogurt Market
Probiotic Supplements
Probiotic Strains Market
Probiotic Supplements
Multistrain Probiotics Market
Probiotic Supplements
ASEAN Probiotic Supplements Market
Probiotic Supplements
Global Probiotic Based Dietary Supplements Market
Probiotic Supplements
Stirred Yogurt Culture Market
Probiotic Supplements
D-Lactate Free Probiotics Market