
 Colombia Road Freight Transport Market | 2026-2036
Colombia Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Road Freight Transport Market Outlook
Colombia's updated axle-load regulations is decoupling fleet modernization from pure volume economics. TCC SAS leverages its integrated warehousing network to sustain temperature-controlled market share across agricultural corridors. Coordinadora Mercantil SA anchors national coverage through dedicated full-truckload lanes between Bogotá and Caribbean ports.
Colombia road freight transport encompasses the movement of goods via motorized vehicles over the national highway network, utilizing trucks with gross vehicle weights from 3.5 tonnes to articulated configurations exceeding 45 tonnes, typically powered by diesel or compressed natural gas engines and governed by Ministry of Transport resolution 1746 technical inspection protocols. The sector serves as the dominant domestic logistics backbone, connecting Andean production zones to Caribbean and Pacific maritime terminals. Trucks dominate vehicle-type deployment due to payload flexibility across mountainous terrain, while full truck load services capture the largest service-type revenue pool from bulk commodity and manufacturing flows. Third-party logistics channels are expanding fastest as shippers outsource fleet ownership to operators like Logistica Transporte Y Servicios Asociados SAS and Operadores Logisticos De Carga S OPL Carga SAS.
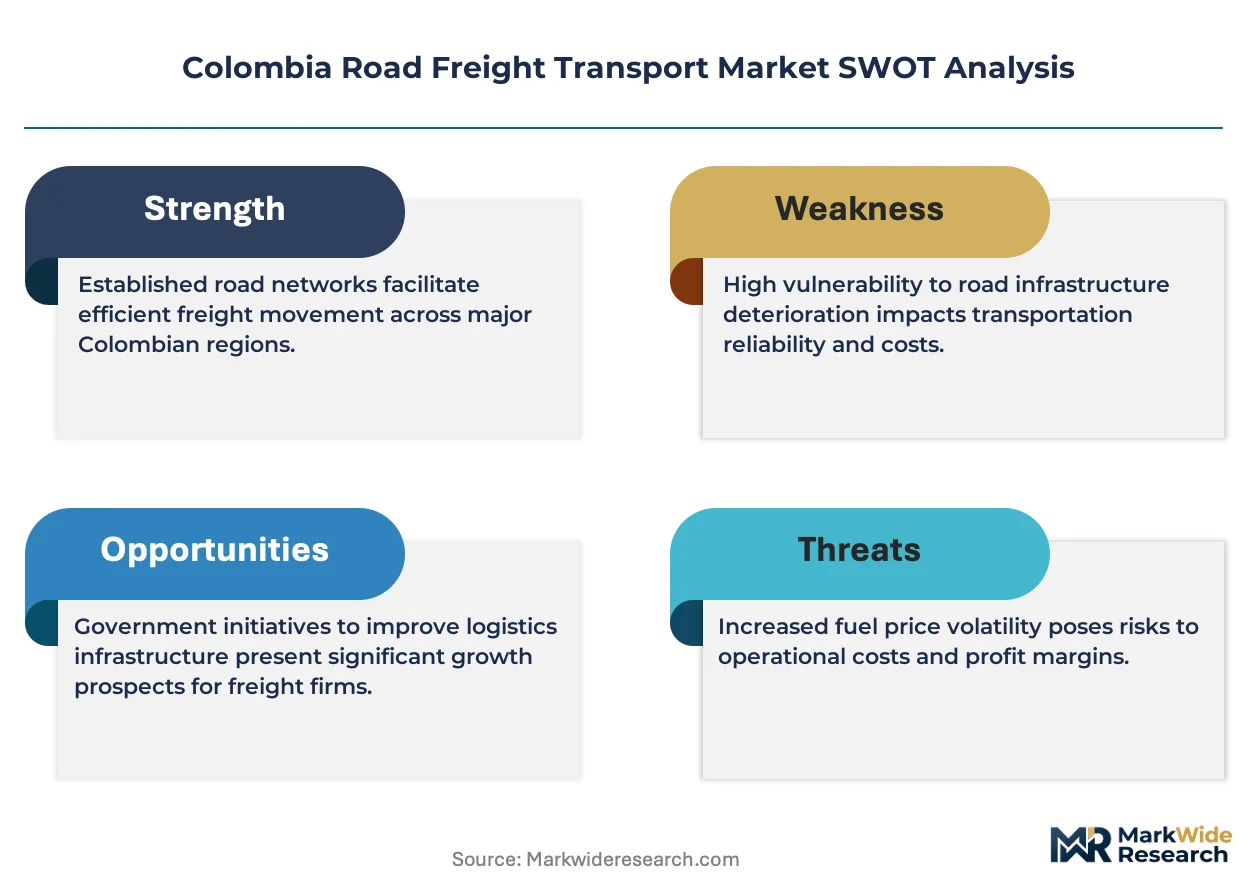
Colombia's Ministry of Transport, the National Infrastructure Agency, and the Superintendency of Ports and Transport shape fleet standards, concession road pricing, and carrier operating authority through mandatory technical inspections and toll-road investment frameworks. These bodies enforce emission benchmarks and driver hour limits that elevate compliance costs for smaller operators. Stakeholders must monitor whether proposed green-fuel subsidies alter the diesel-to-CNG transition pace in long-haul corridors.
Market Dynamics
Colombia's axle-load regulations from the Ministry of Transport are forcing fleet replacement cycles to compress, decoupling carrier profitability from pure freight volume economics and accelerating capital deployment toward compliant tractor-trailer configurations.
Growth Catalysts
- Andean agricultural export corridors:Refrigerated trucking capacity is expanding to serve temperature-sensitive perishables moving from interior production zones to Caribbean maritime terminals.
- Resolution 1746 technical inspection protocols:Mandatory safety and emissions compliance is professionalizing the carrier base and culling informal operators from long-haul lanes.
- Compressed natural gas infrastructure:Conversion subsidies and fuel station density along the Bogotá-Medellín-Cali corridor are pulling diesel displacement in heavy-duty segments.
Market Restraints
- Diesel price volatility:Fuel represents 35-45% of operating costs for Colombian long-haul carriers, compressing margins when international crude benchmarks spike.
- Mountainous terrain technical limitations:Andean topography restricts payload efficiency and accelerates brake and drivetrain wear, elevating maintenance intensity versus flatland corridors.
- Toll-road concession pricing:The National Infrastructure Agency's revenue-sharing frameworks impose fixed per-kilometer costs that small operators cannot negotiate downward.
Strategic Opportunities
- Pacific port connectivity gaps:Underdeveloped road links between Cali and Buenaventura create white space for dedicated container shuttle services with chassis pooling.
- Third-party logistics outsourcing:Manufacturing clusters along the Bogotá-Medellín corridor are shedding captive fleets, opening contract logistics relationships with asset-light operators.
- Green-fuel subsidy frameworks:Proposed Ministry of Transport incentives for CNG and electric tractor adoption would accelerate payback periods for early fleet converters.
Industry Challenges
- Certified mechanic scarcity:Resolution 1746 inspection standards require specialized diagnostic capabilities that vocational training programs have not scaled to match fleet growth.
- Telematics integration complexity:Legacy dispatch systems at mid-sized carriers resist seamless connection with GPS tracking and electronic logging devices mandated for driver hour enforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Road Freight Transport Market |
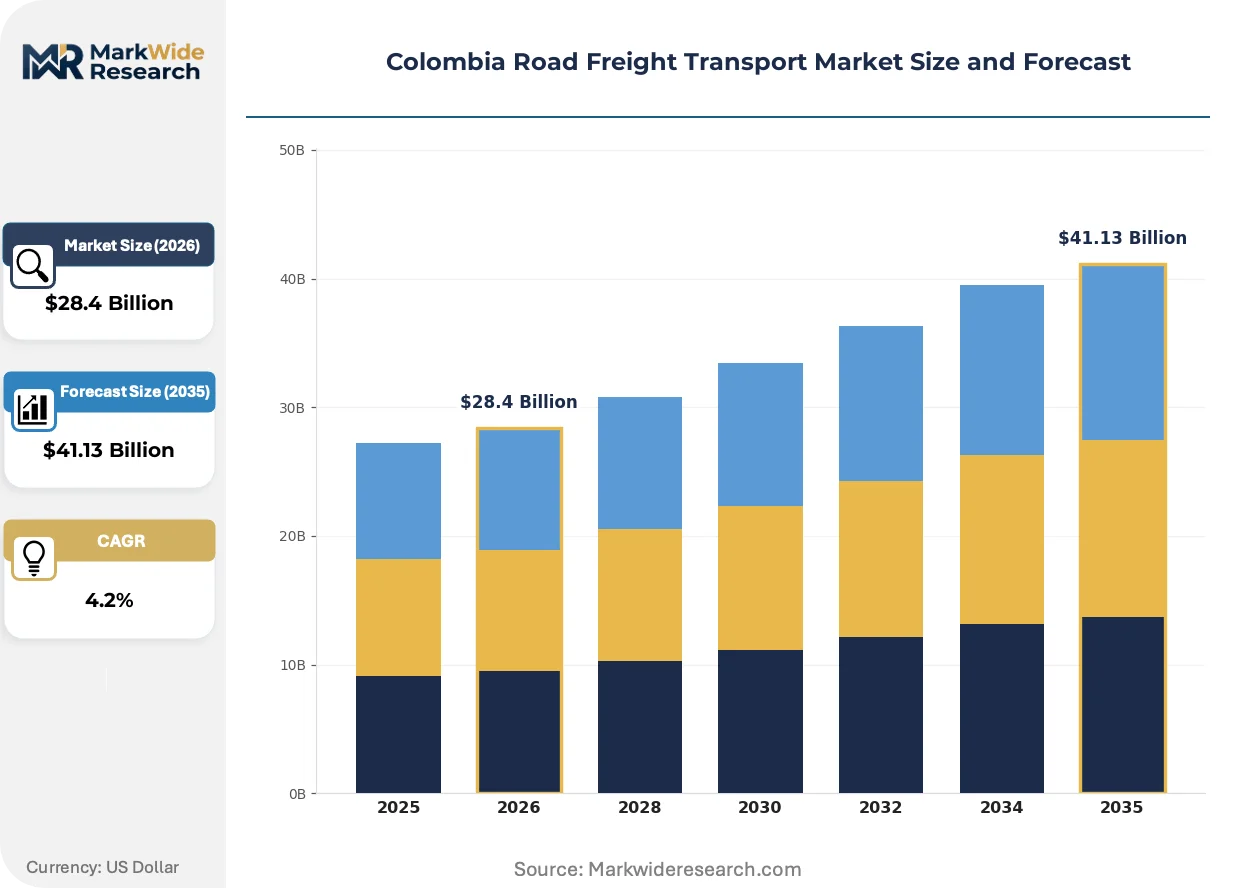
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $41.13 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Trucks, Vans, Trailers, Tankers Service Type: Full Truck Load, Less Than Truck Load, Expedited Shipping, Freight Brokerage End Market: Agriculture, Construction, Retail, Manufacturing Distribution Channel: Direct Sales, Online Platforms, Freight Forwarding, Third-Party Logistics |
| Companies Covered | TCC SAS, Transportes Vigia Sociedad Por Acciones Simplificada SAS, Coordinadora Mercantil SA, Logistica Transporte Y Servicios Asociados SAS, Sercarga SAS, Compania De Distribucion Y Transporte SA Ditransa, Transportes Sanchez Polo SA, Cooperativa Santandereana De Transportadores Limitada, Operadores Logisticos De Carga S OPL Carga SAS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Road Freight Transport Market Strategic Shifts
Digital freight matching platforms are compressing load-board inefficiencies while alternative powertrains and regulatory compliance automation reshape capital deployment and operational workflows across Colombian trucking.
Telematics-enabled predictive maintenance is electrifying fleet management economics. Sensors monitoring engine diagnostics, brake wear, and tire pressure transmit real-time data to cloud platforms. Large agricultural exporters and manufacturing shippers are adopting these systems fastest, prioritizing uptime over lowest-rate carriage. This capability is electrifying competitive differentiation toward reliability metrics rather than pure price competition.
Colombia's Ministry of Transport is tightening driver hour limits through electronic logging device mandates derived from Superintendency of Ports and Transport enforcement frameworks. Carriers must now install tamper-proof recorders or face operating authority suspension. Long-haul full-truckload segments are responding by restructuring relay networks to keep individual drivers within daily limits while maintaining corridor velocity.
Shippers are consolidating vendor relationships around integrated warehousing-transportation bundles. Manufacturing clusters near Bogotá are shedding fragmented spot-market procurement in favor of contracted lane commitments with guaranteed capacity. This concentration is most visible among automotive parts suppliers serving Pacific port assembly plants, where inventory velocity requirements punish unreliable carrier performance.
Colombia Road Freight Transport Market Segmentation
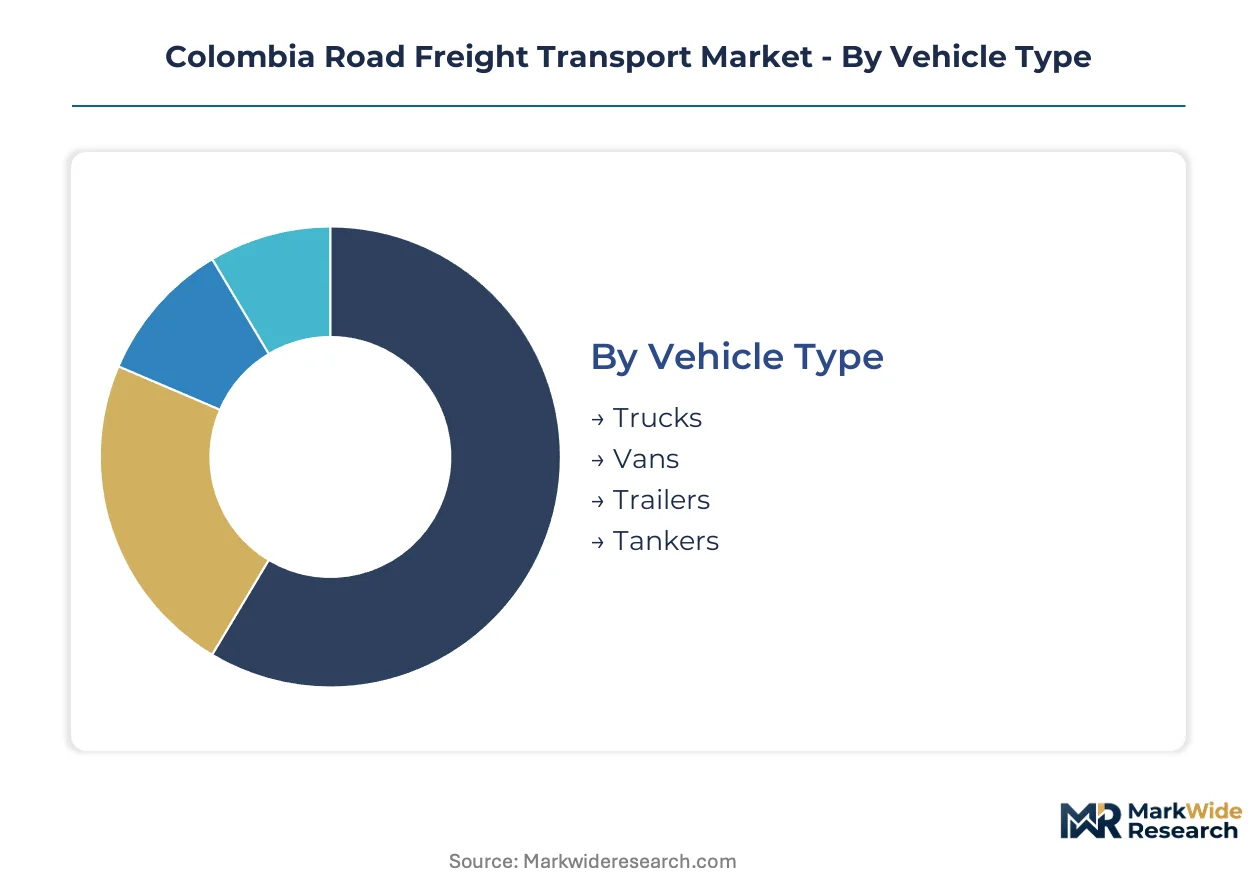
Segmentation in Colombian road freight reveals how regulatory frameworks and terrain constraints reshape equipment deployment across corridors. Resolution 1746 technical inspection protocols and axle-load regulations create divergent compliance burdens that favor certain configurations over others.
Vehicle Type:
Certification intensity varies sharply across this category, with articulated configurations facing the heaviest Ministry of Transport scrutiny while lighter units navigate reduced inspection frequency.
- Trucks:Rigid-body configurations from 3.5 to 26 tonnes dominate Andean corridor operations, with diesel and CNG powertrains both requiring Resolution 1746 emissions certification. Demand concentrates among agricultural exporters moving perishables from interior production zones to Caribbean maritime terminals, where payload flexibility across mountainous terrain outweighs fuel economy penalties.
- Trailers:Semi-trailer and full-trailer combinations exceeding 45 tonnes gross vehicle weight face the strictest axle-load enforcement under updated Ministry of Transport regulations. Manufacturing clusters along the Bogotá-Medellín-Cali corridor drive replacement demand as carriers modernize fleets to comply with highway degradation prevention standards.
- Vans:Light commercial vehicles under 3.5 tonnes serve urban last-mile distribution with reduced technical inspection burdens compared to heavy-duty segments.
- Tankers:Specialized liquid bulk configurations require additional hazardous materials certifications beyond standard Resolution 1746 protocols.
Trucks sit at the top of the volume ranking, with Trailers climbing the fastest as fleet replacement cycles compress under regulatory pressure.
Service Type:
Margin structures diverge based on asset utilization intensity and customer contract duration, with dedicated lane commitments commanding premium positioning over spot-market participation.
- Full Truck Load:Dedicated vehicle allocation for single-shipper cargo dominates revenue pools across bulk commodity and manufacturing flows. Automotive parts suppliers serving Pacific port assembly plants favor contracted FTL relationships with guaranteed capacity over fragmented procurement, prioritizing inventory velocity reliability.
- Freight Brokerage:Digital load-matching platforms are compressing traditional broker margins while expanding market access for smaller carriers. The segment gains traction among mid-sized shippers seeking price transparency without long-term carrier commitments.
- Less Than Truck Load:Consolidated cargo services face network density challenges across Colombia's dispersed population centers and difficult topography.
- Expedited Shipping:Time-definite services command rate premiums for temperature-sensitive agricultural exports requiring rapid transit to maritime terminals.
Full Truck Load maintains the widest revenue footprint, while Freight Brokerage expands most quickly through platform-enabled market access.
End Market:
Customer sophistication levels determine service bundling complexity, with integrated warehousing-transportation demands concentrated among export-oriented sectors.
- Agriculture:Temperature-controlled transport for coffee, flowers, and tropical fruits drives refrigerated trucking investment across Andean production zones. Exporters require seamless cold chain integrity from farm gate to Caribbean port, elevating carrier selection criteria toward telemetry-enabled fleet visibility.
- Manufacturing:Automotive, electronics, and consumer goods producers along the Bogotá-Medellín corridor are shedding captive fleets in favor of third-party logistics partnerships. Inventory velocity requirements punish unreliable carrier performance, consolidating vendor relationships around integrated service bundles.
- Construction:Project-based bulk material movement faces demand cyclicality tied to National Infrastructure Agency concession timelines.
- Retail:Omnichannel distribution networks are restructuring urban delivery patterns toward higher-frequency, smaller-lot shipments.
Agriculture leads end-market revenue contribution, with Manufacturing gaining share fastest through outsourcing acceleration.
Distribution Channel:
Channel selection reflects shipper scale and digital maturity, with enterprise manufacturers favoring direct carrier negotiation while smaller participants aggregate through intermediaries.
- Third-Party Logistics:Asset-light operators like Logistica Transporte Y Servicios Asociados SAS and Operadores Logisticos De Carga SAS capture expanding outsourcing demand from manufacturers divesting captive fleet ownership. Contracted lane commitments with guaranteed capacity replace fragmented spot-market procurement for automotive and electronics shippers.
- Direct Sales:Large agricultural exporters and manufacturing clusters negotiate dedicated capacity agreements directly with certified carriers, prioritizing uptime metrics over lowest-rate carriage through telemetry-enabled performance tracking.
- Freight Forwarding:International trade facilitation links domestic road segments with maritime and air cargo networks.
- Online Platforms:Digital freight matching emerges as a channel for small shippers seeking price discovery without established carrier relationships.
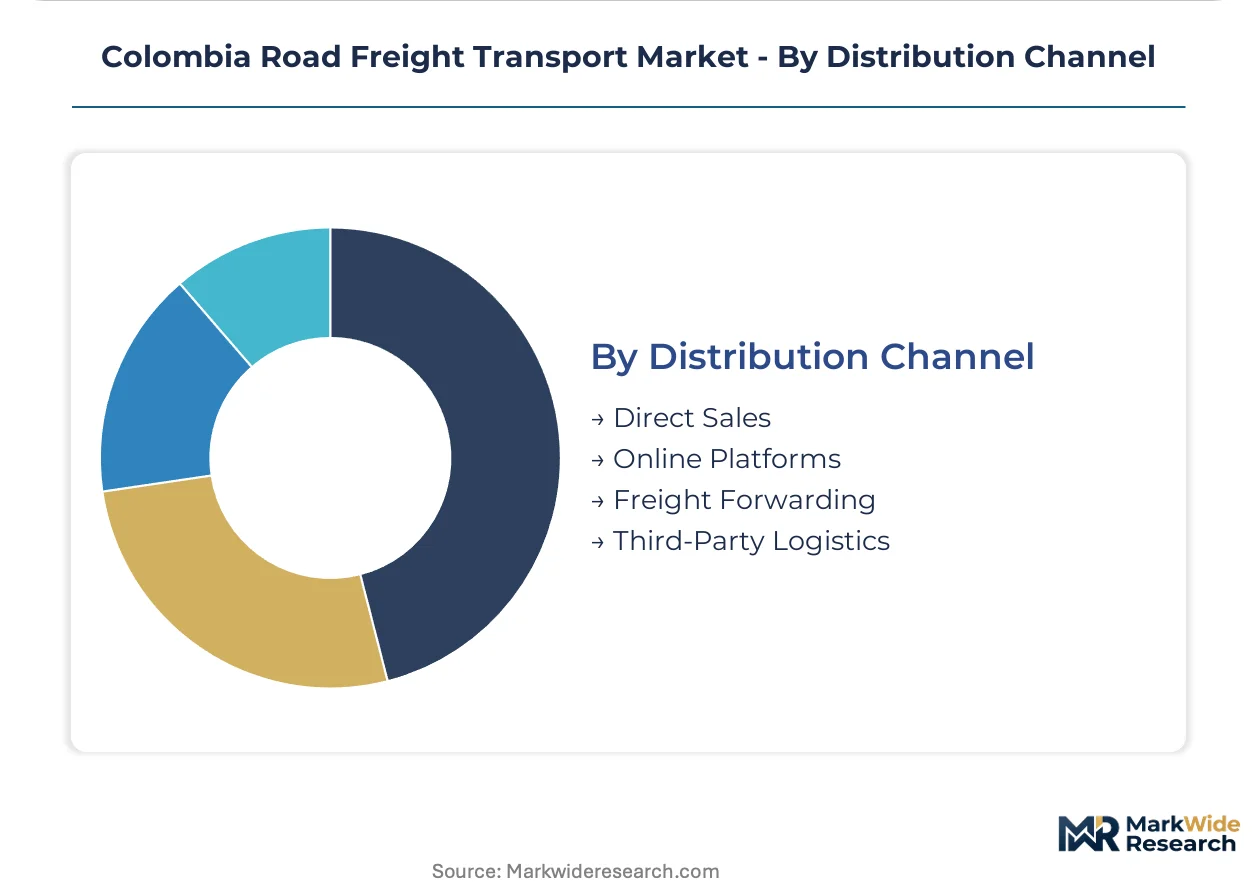
Third-Party Logistics holds the dominant channel position, with Direct Sales expanding most quickly among enterprise manufacturers consolidating vendor bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Colombia's road freight workforce concentrates along the Andean spine, where driver certification pools and mechanical expertise cluster around Bogotá, Medellín, and Cali. This talent distribution shapes corridor-specific capacity deployment and carrier specialization patterns.
Bogotá Capital Region
Manufacturing exporters and third-party logistics providers anchor demand in the Bogotá metropolitan area. The Ministry of Transport's Resolution 1746 enforcement is strictest here, culling informal operators from long-haul lanes. Automotive parts suppliers and electronics assemblers in the Sabana industrial zone are consolidating vendor relationships around contracted capacity with guaranteed uptime.
Antioquia and Medellín
Coffee exporters and textile manufacturers drive refrigerated and dry van demand through the Aburrá Valley. Updated axle-load regulations from the Ministry of Transport are accelerating fleet replacement cycles among carriers serving Caribbean port connections. The Rionegro logistics cluster is expanding cross-dock capacity to handle transshipment between mountain production zones and coastal terminals.
Valle del Cauca and Cali
Sugar cane processors and Pacific port-bound container flows dominate freight volumes in Colombia's southwestern agricultural heartland. The National Infrastructure Agency's toll-road pricing frameworks impose fixed costs that favor larger carriers with negotiated concession access. Buenaventura port connectivity gaps are creating white space for dedicated shuttle services with chassis pooling.
Caribbean Coast
Barranquilla and Cartagena maritime terminals absorb the bulk of Andean agricultural and manufacturing exports. Temperature-controlled trucking capacity is expanding fastest here to serve flower and tropical fruit cold chains. The Superintendency of Ports and Transport maintains heightened inspection protocols at port entry gates, filtering non-compliant carriers from international cargo lanes.
Eje Cafetero
Quindío, Risaralda, and Caldas departments form a specialized corridor for perishable agricultural exports requiring rapid transit to Caribbean ports. Smaller carriers with flexible fleet configurations dominate this terrain, though Resolution 1746 compliance costs are pressuring consolidation. Pereira's logistics parks are attracting third-party operators seeking proximity to coffee and banana loading zones.
Colombia Road Freight Transport Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Colombia's road freight sector. The market structure tilts toward fragmentation at the mid-tier, where family-owned carriers with 20-50 unit fleets resist consolidation despite regulatory pressure. Three archetypes dominate: integrated warehousing-transportation bundlers, dedicated full-truckload lane operators, and asset-light third-party logistics platforms. Competitive moves center on fleet modernization to meet axle-load regulations and strategic partnerships to secure port terminal access.
Among integrated service providers, TCC SAS and Coordinadora Mercantil SA occupy positions representing bundled warehousing and transportation capabilities. TCC SAS exemplifies the temperature-controlled specialist archetype with network density across agricultural corridors. Coordinadora Mercantil SA anchors the dedicated lane operator model through committed capacity between Bogotá and Caribbean ports. At the asset-light end, Logistica Transporte Y Servicios Asociados SAS represents third-party logistics platforms capturing outsourcing demand from manufacturers shedding captive fleets.
| Leading Market Players |
|---|
| TCC SAS |
| Transportes Vigia Sociedad Por Acciones Simplificada SAS |
| Coordinadora Mercantil SA |
| Logistica Transporte Y Servicios Asociados SAS |
| Sercarga SAS |
| Compania De Distribucion Y Transporte SA Ditransa |
| Transportes Sanchez Polo SA |
| Cooperativa Santandereana De Transportadores Limitada |
| Operadores Logisticos De Carga S OPL Carga SAS |
| Others |
Value Chain & Pricing Dynamics
Resolution 1746 emissions certification gates qualified supply and premium-tier pricing access for Colombian carriers, separating compliant operators from informal competitors while compressing margins for those lacking Ministry of Transport credentials.
Pricing Analysis
Bundled warehousing-transportation services command rate premiums over unbundled spot-market procurement across the Bogotá-Medellín corridor. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and telemetry-enabled fleet visibility. Price differentiation stems from axle-load compliance status and guaranteed capacity commitments. Cost compression in standard tiers intensifies because diesel volatility erodes carrier margins, while large agricultural exporters prove least price-sensitive due to cold chain integrity requirements.
Supply Chain Analysis
Direct-to-manufacturer channels handle enterprise shipper demand while freight brokerage platforms aggregate smaller participants through digital load-matching. Vehicle manufacturing concentrates in Brazil, Mexico, and the United States. Diesel fuel, CNG conversion kits, and refrigerated trailer components constitute critical input dependencies. Single-source vulnerability runs through CNG infrastructure deployment along the Bogotá-Medellín-Cali corridor. Distribution runs through third-party logistics operators capturing outsourcing demand from manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Colombia's road freight market functions as a geographic-arbitrage play where Pacific port connectivity gaps and Andean corridor density differentials reward early movers against Caribbean-focused incumbents.
For Market Incumbents: Anticipate regulatory tightening from the Ministry of Transport by accelerating fleet replacement cycles ahead of axle-load enforcement deadlines. Secure backward integration into CNG fueling infrastructure to defend margin position against diesel price volatility. Consolidate vendor relationships with automotive parts suppliers through guaranteed capacity contracts that informal operators cannot match.
For New Entrants and Emerging Players: Telematics-enabled predictive maintenance platforms offer a technology-first wedge into agricultural exporter segments where uptime metrics outweigh rate competition. Target the Buenaventura port shuttle corridor where chassis pooling services face minimal incumbent saturation. Pursue direct sales relationships with coffee and flower exporters in the Eje Cafetero bypassing fragmented brokerage layers.
For Investors and Strategic Acquirers: Roll-up economics work for mid-sized family-owned carriers because Resolution 1746 compliance costs pressure fragmentation toward consolidation. Focus acquisition screening on 20-50 unit fleets with Ministry of Transport certification and established Caribbean port lane density. Monitor CNG subsidy framework announcements from the Ministry of Transport as inflection indicators for alternative powertrain adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Modernization | Resolution 1746 compliance separates certified operators from culled informal competitors. |
| CNG Infrastructure Partnership | Ministry of Transport subsidies accelerate payback for early alternative-fuel adopters. |
| Telematics Platform Integration | Predictive maintenance capabilities shift carrier selection criteria toward reliability metrics. |
| Port Terminal Access Agreement | Buenaventura connectivity gaps create dedicated shuttle service opportunities. |
| Third-Party Logistics Outsourcing | Manufacturing clusters shed captive fleets to asset-light operators. |
Study Parameters
Direct dialogue with fleet operations managers, Ministry of Transport compliance officers, agricultural exporter logistics directors, and third-party logistics contract specialists grounded qualitative findings in operational reality. Secondary validation drew from National Infrastructure Agency concession filings, Superintendency of Ports and Transport enforcement bulletins, customs trade flow data, and carrier association membership records. Bottom-up and top-down triangulation cross-checked vehicle registration trends against corridor-specific freight volume estimates.
Bottom-up modeling aggregated carrier fleet data, toll-road transaction records, and port throughput statistics across vehicle type, service type, and end market segments. Top-down constraints incorporated macroeconomic freight intensity ratios and regional production cluster output. CAGRs were derived from regression-adjusted trend extrapolation incorporating regulatory phase-in schedules and infrastructure investment pipelines. Fuel substitution elasticity and axle-load compliance cost curves informed alternative powertrain adoption trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CNG subsidy implementation timing and Pacific port expansion completion. Forecasts reflect documented assumptions regarding Ministry of Transport enforcement consistency and diesel benchmark stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Transportation and Security System Market
Transportation & Logistics
ASEAN Cold Chain Logistics Market
Transportation & Logistics
Middle-East and North Africa Taxi Market
Transportation & Logistics
Japan Road Freight Transport Market
Transportation & Logistics
Road Haulage Market
Transportation & Logistics
Europe Reverse Logistic Market
Transportation & Logistics
Automatic Vehicle Location System (AVL) Market
Transportation & Logistics
Ski Conveyor Lift Market
Transportation & Logistics
Netherlands Road Freight Transport Market
Transportation & Logistics
Railcar Unloader Market
Transportation & Logistics
Rental and Subscription Product Logistics Orchestration Platforms Market
Transportation & Logistics
Cross-Border Road Transport Market
Transportation & Logistics
Italy Road Freight Transport Market
Transportation & Logistics
Asia-Pacific Customs Brokerage Market
Transportation & Logistics
GCC International Express Service Market
Transportation & Logistics
Spain Cold Chain Logistics Market