
 Spain Cold Chain Logistics Market | 2026-2036
Spain Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Cold Chain Logistics Market Analytics
Pharmaceutical distributors is rotating toward temperature-controlled logistics networks as Spain's biologics and vaccine distribution requirements intensify. Primafrio leverages its extensive refrigerated fleet to dominate Iberian food transport corridors. Lineage Logistics sustains multi-temperature warehousing capacity across strategic Spanish ports. Grupo Mazo anchors domestic fresh produce distribution through regionally dense depot networks.
Cold chain logistics encompasses the temperature-controlled supply chain infrastructure maintaining products between 2°C and 8°C for pharmaceuticals or below -18°C for frozen goods through insulated transport, refrigerated warehousing, and real-time monitoring systems. Transportation services command the largest service-type revenue pool due to fuel and fleet amortization intensity, while IoT Solutions within temperature monitoring represents the fastest-expanding technology segment driven by pharmaceutical traceability mandates. Pharmaceutical product-type handling generates premium margin pools compared to commoditized frozen food logistics.
Spain's Ministry of Health enforces pharmaceutical distribution standards through AEMPS oversight, while EU GDP guidelines and national food safety regulations under AESAN mandate cold chain integrity documentation. These frameworks elevate compliance costs for operators but simultaneously consolidate market access around certified providers with validated temperature monitoring infrastructure. Stakeholders must evaluate fleet electrification timelines against Madrid and Barcelona municipal low-emission zone expansions.
Market Dynamics
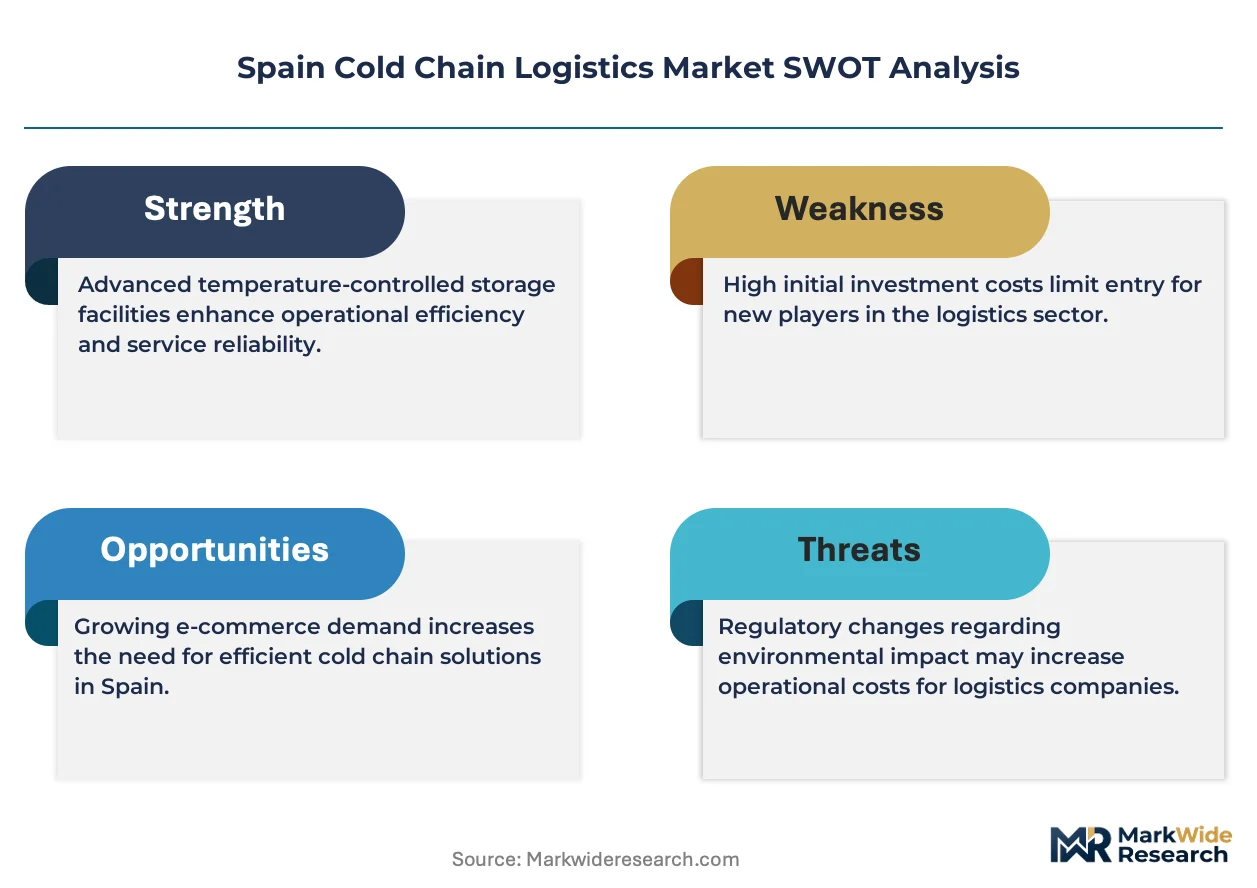
Spain's cold chain logistics sector is restructuring around pharmaceutical traceability mandates and municipal low-emission zone expansions that force fleet electrification timelines. The tension between refrigerated transport reliability and decarbonization compliance is concentrating investment in validated temperature monitoring infrastructure.
Growth Catalysts
- Biologics distribution surge:Spain's AEMPS oversight of temperature-sensitive pharmaceuticals compels distributors to expand validated cold storage networks. Vaccine and cell therapy volumes are pulling specialized handling capacity into Catalonia and Madrid.
- Digital traceability mandate:Royal Decree on food safety traceability requires real-time temperature logging across fresh produce supply chains. AESAN enforcement is accelerating IoT sensor deployment in domestic transport fleets.
- Port-centric multi-temperature warehousing:Barcelona and Valencia container terminals are anchoring integrated cold storage hubs that consolidate Iberian import flows. Refrigerated warehousing investment is clustering at these maritime gateways.
Market Restraints
- Diesel price volatility:Refrigerated transport operators face margin compression from fuel cost swings that cannot be fully passed through in commoditized frozen food segments.
- Certified fleet scarcity:GDP-compliant refrigerated vehicles remain concentrated among established pharmaceutical logistics providers, creating capacity bottlenecks for new market entrants.
- Electrification capex burden:Madrid and Barcelona municipal low-emission zone expansions are forcing premature fleet replacement before battery-electric refrigeration technology achieves cost parity.
Strategic Opportunities
- Andalusian agricultural export corridor:Almería and Huelva fresh produce volumes are underserved by integrated cold chain infrastructure linking farms to European retail networks.
- Cross-dock automation:Robotic pallet handling and automated sortation systems are converging with temperature-controlled environments to reduce labor dependency in high-throughput facilities.
- Pharmaceutical last-mile specialization:Hospital and pharmacy direct delivery networks remain fragmented, creating white space for GDP-certified urban micro-fulfillment nodes.
Industry Challenges
- Refrigeration technician shortage:Specialized maintenance skills for transport refrigeration units and warehouse cooling systems are scarce across Spain's vocational training pipeline.
- Legacy system integration:Temperature monitoring platforms must interface with existing warehouse management systems without disrupting pharmaceutical validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Cold Chain Logistics Market |
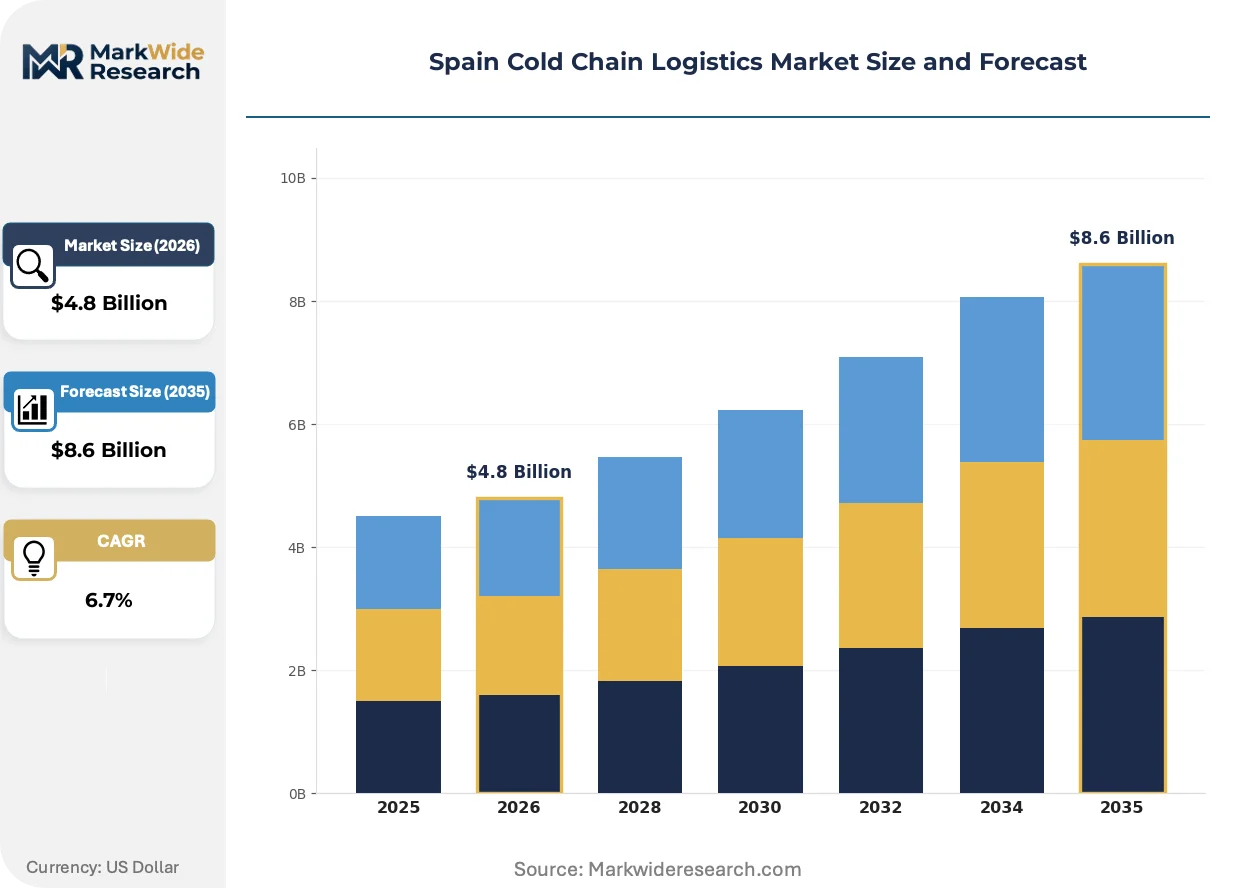
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Packaging, Distribution Product Type: Frozen Food, Dairy Products, Pharmaceuticals, Fresh Produce End User: Retailers, Pharmacies, Food Manufacturers, Distributors Technology: GPS Tracking, IoT Solutions, Refrigeration Units, Temperature Monitoring |
| Companies Covered | Grupo Mazo, Primafrio, Lineage Logistics, ID Logistics, Kuehne + Nagel Spain, STEF, Americold, DB Schenker Spain, DHL Supply Chain Iberia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Cold Chain Logistics Market Evolving Landscape
Telematics-enabled cold chain visibility is compressing operational response times while regulatory pressure on emissions intensifies equipment replacement cycles. Three intersecting developments are restructuring competitive capabilities.
Blockchain-based temperature logging is fragmenting pharmaceutical traceability architectures. Biologics shippers are adopting distributed ledger verification to satisfy EU GDP guidelines for immutable chain-of-custody records. This technology is fragmenting market access between certified providers with validated digital infrastructure and operators relying on conventional paper-based documentation.
Spain's Royal Decree on food safety traceability mandates digital temperature records across perishable supply chains. AESAN enforcement is compelling fresh produce distributors to retire manual logging systems ahead of statutory deadlines. Small and mid-sized transport operators in Andalusia and Extremadura are consolidating to share compliance infrastructure costs.
Hospital procurement departments are unbundling transportation from warehousing contracts to secure dedicated pharmaceutical handling protocols. Large health systems in Madrid and Barcelona are negotiating direct agreements with GDP-certified logistics specialists. This pattern is most visible in oncology and rare disease therapeutic categories where temperature excursions carry patient safety liabilities.
Spain Cold Chain Logistics Market Segmentation
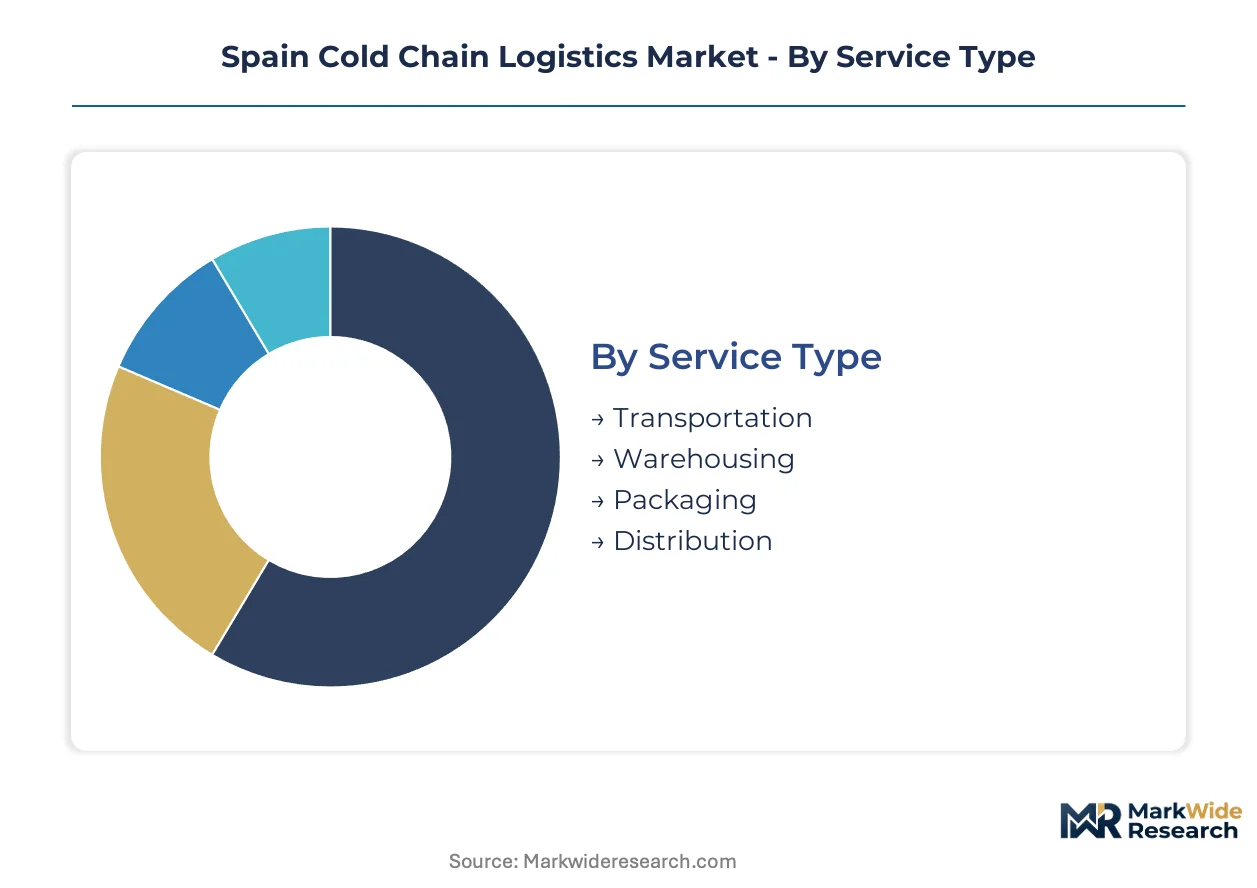
Cold chain logistics operators in Spain configure service portfolios around divergent compliance burdens. AEMPS pharmaceutical validation demands shape infrastructure investment far more than AESAN food safety requirements, creating tiered competitive capabilities across segment boundaries.
Service Type:
Regulatory differentiation separates GDP-certified pharmaceutical handling from commodity food transport, with compliance infrastructure costs determining market access tiers.
- Transportation:Refrigerated fleet operations span long-haul corridors between Almería growing regions and Madrid distribution hubs, with diesel price volatility compressing margins in frozen food segments where fuel surcharges cannot fully pass through contract rates.
- Warehousing:Multi-temperature facilities cluster at Barcelona and Valencia port terminals, consolidating Iberian import flows through integrated cold storage hubs that handle both pharmaceutical validation and fresh produce throughput.
- Packaging:Insulated shippers and gel pack configurations protect temperature-sensitive biologics through last-mile delivery, with hospital procurement departments specifying validated packaging protocols for oncology therapeutics.
- Distribution:Cross-dock operations link farm-gate collection in Extremadura to retail consolidation centers, with manual temperature logging systems retiring ahead of Royal Decree traceability deadlines.
Transportation handles the majority of throughput; IoT-enabled temperature monitoring is the fastest mover on share.
Product Type:
Margin concentration follows product sensitivity, with cell therapy and vaccine handling commanding premium pricing against commoditized frozen protein logistics.
- Frozen Food:Commoditized meat and seafood volumes move through established Iberian corridors with thin margins, where Primafrio's fleet scale defends position against fuel cost swings.
- Dairy Products:Fresh milk and cheese distribution requires precise 2-8°C maintenance through short shelf-life windows, concentrating demand around Madrid's logistics corridor.
- Pharmaceuticals:Biologics and vaccine distribution under AEMPS oversight compels validated cold storage networks, with Catalonia anchoring specialized handling capacity for temperature excursions carrying patient safety liabilities.
- Fresh Produce:Almería and Huelva vegetable exports demand rapid pre-cooling and transit reliability, with AESAN enforcement accelerating digital temperature logging adoption across Andalusian transport fleets.
Pharmaceuticals generates the highest margin pools; fresh produce is expanding most quickly as export volumes climb.
End User:
Procurement authority concentration shapes contract structures, with large health systems unbundling transportation from warehousing to secure dedicated handling protocols.
- Retailers:Supermarket chains in Madrid and Barcelona negotiate integrated cold chain contracts spanning farm-gate to shelf, with traceability documentation required for private-label fresh produce lines.
- Pharmacies:Independent and chain pharmacy networks receive direct vaccine deliveries under GDP guidelines, fragmenting last-mile capacity among certified urban micro-fulfillment specialists.
- Food Manufacturers:Processed meat and dairy producers maintain captive refrigerated fleets for inbound ingredient collection, outsourcing only long-haul distribution to third-party operators.
- Distributors:Pharmaceutical wholesalers consolidate regional storage and transport functions, with Lineage Logistics sustaining multi-temperature capacity at strategic Spanish ports.
Retailers command the largest contract volumes; pharmacies are driving the steepest specialization requirements.
Technology:
Equipment replacement cycles compress as Madrid and Barcelona low-emission zone expansions force premature fleet turnover before battery-electric refrigeration achieves cost parity.
- GPS Tracking:Fleet telematics platforms enable route optimization and arrival-time prediction, with pharmaceutical shippers requiring real-time location verification alongside temperature data.
- IoT Solutions:Connected sensor networks stream temperature and humidity data to cloud platforms, satisfying Royal Decree digital traceability mandates across fresh produce supply chains.
- Refrigeration Units:Transport refrigeration equipment faces technician shortage constraints, with specialized maintenance skills scarce across Spain's vocational training pipeline.
- Temperature Monitoring:Data logger systems must interface with legacy warehouse management platforms without disrupting pharmaceutical validation protocols.
Refrigeration units represent the largest installed base; IoT solutions are climbing the fastest as compliance deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cold chain capacity concentrates along Spain's Mediterranean and Atlantic corridors, with pharmaceutical validation requirements and agricultural export volumes driving infrastructure investment into distinct regional clusters.
Madrid
Madrid's logistics corridor anchors Iberian pharmaceutical distribution under AEMPS oversight, with hospital procurement departments consolidating vaccine and biologics handling contracts. The municipal low-emission zone expansion is forcing premature fleet electrification timelines for refrigerated transport operators. Multi-temperature warehousing clusters at the city's peripheral distribution nodes to serve central Spain's retail networks.
Catalonia
Catalonia's pharmaceutical hub specializes in cell therapy and oncology therapeutic distribution where temperature excursions carry patient safety liabilities. The regional government enforces AESAN food safety coordination alongside national AEMPS standards. Barcelona's port terminals anchor integrated cold storage hubs consolidating Iberian import flows through Lineage Logistics capacity.
Andalusia
Andalusia's agricultural export corridor generates fresh produce volumes from Almería and Huelva that outpace integrated cold chain infrastructure linking farms to European retail networks. Royal Decree digital traceability mandates are accelerating IoT sensor deployment across regional transport fleets. GDP-certified refrigerated vehicles remain scarce, creating capacity bottlenecks for pharmaceutical distribution south of Madrid.
Valencia
Valencia's container terminals sustain multi-temperature warehousing investment clustering at maritime gateways handling both pharmaceutical validation and citrus export throughput. The port authority coordinates with AESAN enforcement on perishable supply chain documentation requirements. Regional transport operators are consolidating to share compliance infrastructure costs ahead of statutory deadlines.
Basque Country
The Basque Country's industrial logistics base supports temperature-controlled handling for specialized manufacturing inputs and premium food exports. Regional vocational training programs address the scarce refrigeration technician skills constraining fleet maintenance capacity. Bilbao's port infrastructure provides Atlantic corridor alternatives to Mediterranean routing for time-sensitive pharmaceutical shipments.
Spain Cold Chain Logistics Market Competitive Landscape
Concentration sits with diversified logistics conglomerates and specialized refrigerated fleet operators that have validated temperature monitoring infrastructure. The vendor base separates into three tiers: international third-party logistics providers with multi-temperature warehousing networks, domestic food transport specialists with dense regional depot coverage, and pharmaceutical-certified operators with GDP-compliant vehicle fleets. Strategic moves center on port-centric capacity expansion and cross-border Iberian network integration.
Within the domestic refrigerated transport tier, Primafrio exemplifies scale-driven fleet coverage across Iberian food corridors, while Grupo Mazo anchors fresh produce distribution through regionally dense depot networks. Lineage Logistics represents the international warehousing archetype with multi-temperature capacity at strategic Spanish ports.
| Leading Market Players |
|---|
| Grupo Mazo |
| Primafrio |
| Lineage Logistics |
| ID Logistics |
| Kuehne + Nagel Spain |
| STEF |
| Americold |
| DB Schenker Spain |
| DHL Supply Chain Iberia |
| Others |
Value Network & Pricing Analysis
Fleet scale economies among Iberian refrigerated transport operators compress unit costs below what fragmented regional carriers can match, concentrating price-setting power with multi-depot networks while establishing hard floors for GDP-certified pharmaceutical handling. Madrid's logistics corridor and Barcelona's pharmaceutical hub anchor this dual-tier structure, where AESAN traceability mandates and AEMPS validation requirements feed compliance premiums back into asset replacement cycles.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical biologics handling from commoditized frozen food transport, with premium-mid-economy pricing differentiation anchored in GDP certification grade and real-time IoT monitoring capability. Pharmaceutical shippers absorb higher rates for validated cold storage networks under AEMPS oversight, while retail chains negotiating frozen protein contracts squeeze margins through fuel surcharge resistance. Cost compression in frozen food segments intensifies because diesel price volatility cannot pass fully through contract rates, making supermarket procurement the most price-sensitive buyer archetype against hospital systems prioritizing patient safety documentation.
Supply Chain Analysis
Just-in-time inventory preferences dominate fresh produce flows from Almería and Huelva, while pharmaceutical distributors maintain strategic stockpiles of temperature-sensitive biologics to buffer against GDP-compliant fleet scarcity. Refrigerated warehousing capacity concentrates in Spain, France, and the Netherlands, drawing from diesel fuel, lithium-ion battery cells, and specialized refrigeration compressor components. Single-source vulnerability sits with certified vehicle chassis suppliers, constraining fleet expansion timelines. Distribution runs through port-centric multi-temperature hubs at Barcelona and Valencia, consolidating Iberian import flows before last-mile fragmentation to pharmacies and hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold chain logistics platforms are approaching an interoperability inflection where blockchain-based temperature logging and legacy warehouse management systems must converge, with Spain's Royal Decree digital traceability mandate forcing ecosystem-wide retrofit investments.
For Market Incumbents: Shield pharmaceutical margin pools by accelerating GDP-certified fleet replacement ahead of Madrid and Barcelona low-emission zone expansions. Consolidate cross-dock automation investments in Valencia and Catalonia to deflect labor cost pressure from refrigeration technician shortages. Vertical integration into IoT sensor deployment captures compliance infrastructure spend that fragmented operators cannot absorb. For New Entrants and Emerging Players: Anchor in Andalusian agricultural export corridors where integrated cold chain infrastructure linking Almería farms to European retail networks remains underserved. Target hospital and pharmacy direct delivery networks in southern Spain, where GDP-certified urban micro-fulfillment nodes face minimal established competition. Pursue white-label temperature monitoring partnerships with regional transport cooperatives seeking shared AESAN compliance costs. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmaceutical-certified operators with multi-year hospital system contracts and validated digital infrastructure. Long-term viability over a five-to-ten-year window favors asset-heavy players with port-adjacent warehousing and backward integration into fleet maintenance capabilities. The signal to watch is municipal low-emission zone enforcement velocity, which would accelerate electrification capex burdens and consolidate market access around capitalized incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| GDP-Certified Fleet Electrification | Madrid's low-emission zone expansion forces premature battery-electric refrigeration adoption before cost parity. |
| Blockchain Temperature Logging Integration | Biologics shippers adopt distributed ledger verification to satisfy EU GDP immutable chain-of-custody requirements. |
| Port-Centric Multi-Temperature Warehousing | Barcelona and Valencia container terminals anchor integrated cold storage hubs consolidating Iberian import flows. |
| Cross-Dock Automation Deployment | Robotic pallet handling reduces labor dependency in high-throughput facilities facing refrigeration technician shortages. |
| Andalusian Agricultural Corridor Infrastructure | Almería and Huelva fresh produce volumes outpace cold chain capacity linking farms to European retail networks. |
Research Methodology
A spread of perspectives from fleet operations managers, pharmaceutical distribution executives, hospital procurement directors, and AESAN compliance officers converged on the working assumptions underlying capacity and pricing projections. Primary interviews with refrigerated transport operators and multi-temperature warehousing providers combined with secondary validation against AEMPS regulatory filings, EU GDP guideline updates, Spanish customs trade data, and port authority throughput statistics. Bottom-up triangulation across service-type revenue pools and top-down cross-checks against national cold storage capacity estimates anchored the analytical framework.
Segmentation dimensions modeled span service type, product sensitivity tier, end-user procurement authority, and technology adoption stage across the projection horizon. The analytical framework incorporated pharmaceutical validation requirements, food safety traceability mandates, and municipal emissions enforcement patterns throughout the forecast period. CAGRs derived from historical capacity expansion rates, fleet replacement cycles, and regulatory compliance cost trajectories, with specific inputs including diesel price volatility assumptions and battery-electric refrigeration technology cost curves.
Decision-makers should treat outputs as directional under stable regulatory enforcement and technology cost assumptions; material deviation would warrant model refresh. Forecasts reflect assumptions about AEMPS oversight continuity and AESAN digital traceability adoption timelines. Revision becomes warranted when electrification subsidy programs or carbon border adjustment mechanisms cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Vietnam Road Freight Transport Market
Transportation & Logistics
India Intra-City Logistics Market
Transportation & Logistics
North America Road Freight Transport Market
Transportation & Logistics
Global Automotive 3PL Market
Transportation & Logistics
Transport Refrigeration Unit (TRU) Market
Transportation & Logistics
Hungary Road Freight Transport Market
Transportation & Logistics
United States Retail 3PL Market
Transportation & Logistics
Nordics Road Freight Transport Market
Transportation & Logistics
France Road Freight Transport Market
Transportation & Logistics
Poland Road Freight Transport Market
Transportation & Logistics
Malaysia Domestic CEP Market
Transportation & Logistics
Brazil Road Freight Transport Market
Transportation & Logistics
Train Collision Avoidance System Market
Transportation & Logistics
Malaysia Refrigerated Trailer Market
Transportation & Logistics
Refrigerated Trailer Market
Transportation & Logistics
Freight Transport Market