
 Europe Reverse Logistic Market | 2026-2036
Europe Reverse Logistic Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Reverse Logistic Market Foresight
The EU Green Deal's circular economy action plan is broadening reverse logistics obligations across European manufacturing. Deutsche Post DHL Group anchors its European returns network through automated sortation hubs in the Netherlands and Germany. C.H. Robinson Worldwide competes by leveraging its digital freight platform to match return shipments with backhaul capacity across the continent. FedEx sustains cross-border e-commerce returns through customs-bonded facilities in Belgium and the United Kingdom.
Europe reverse logistics encompasses the collection, inspection, sorting, and disposition of post-consumer goods flowing backward through supply chains, typically involving barcode-tracked triage protocols and condition-graded routing to resale, repair, or material recovery. Electronics returns dominate product type volume due to short replacement cycles and producer responsibility laws, while refurbishment services capture expanding margin pools as brands seek to certify pre-owned inventory for resale. Third-party logistics providers within the end user segment are consolidating repair and recycling capabilities under single contracts to capture full-service revenue from retailers.
REACH and the EU Green Deal shape material recovery standards and extended producer responsibility obligations across member states, while the F-Gas Regulation governs refrigerant reclamation in appliance returns. EMA and national regulators in Germany and France enforce pharmaceutical reverse distribution protocols for expired or recalled medicines. Stakeholders must monitor divergence between EU-wide circular economy targets and country-specific implementation timelines that fragment compliance costs.
Market Dynamics
The EU Green Deal's circular economy mandates are compressing product lifecycles and mandating recoverability-by-design, forcing manufacturers to internalize end-of-life costs that previously sat outside their balance sheets. This regulatory architecture is reshaping competitive positioning across European supply chains.
Growth Catalysts
- Extended Producer Responsibility:REACH and national implementations in Germany and France obligate manufacturers to fund collection and recycling infrastructure, creating guaranteed revenue pools for logistics operators managing regulated waste streams.
- E-commerce return volumes:Online retail penetration in France and the Netherlands generates predictable reverse flow density that supports dedicated sortation hub investments and automation amortization.
- Appliance refrigerant recovery:The F-Gas Regulation mandates reclamation of fluorinated gases from cooling equipment, creating specialized handling requirements that favor certified third-party logistics networks over informal channels.
Market Restraints
- Input cost volatility:Diesel and electricity price swings across EU member states compress margins on collection routes where fuel represents the dominant operating cost line.
- Regulatory fragmentation:Divergent national timelines for implementing EU Green Deal targets create compliance cost asymmetries between early-mover jurisdictions like Germany and laggard markets in Southern and Eastern Europe.
- Technical limitation:Battery state-of-health diagnostics for electric vehicle returns remain imprecise, creating valuation disputes between OEMs and remanufacturers that delay inventory velocity.
Strategic Opportunities
- Pharmaceutical reverse distribution:EMA and national regulators in France and Germany enforce strict protocols for expired medicines, creating a defensible niche for temperature-validated logistics specialists with serialization capabilities.
- Packaging redesign services:Brands seeking EU Green Deal compliance need engineering partners who can redesign primary and secondary packaging for disassembly and material recovery, extending logistics contracts upstream into product development.
- Cross-border consolidation platforms:Returns aggregation across Belgium, the Netherlands, and Luxembourg enables pooled customs clearance and bonded warehousing that reduces per-unit handling costs for mid-market retailers.
Industry Challenges
- Skills deficit in diagnostic grading:Condition assessment of returned electronics requires technicians trained to manufacturer-specific standards, and certification pipelines in Spain and Italy lag demand from refurbishment hubs.
- Legacy WMS integration:Warehouse management systems designed for forward fulfillment lack native support for variable routing based on condition grades, forcing expensive middleware development for triage protocols.
- Capex intensity of automation:Automated sortation for heterogeneous return streams requires vision systems and robotic handling that demand multi-year payback periods difficult to justify without volume guarantees from anchor retail clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Reverse Logistic Market |
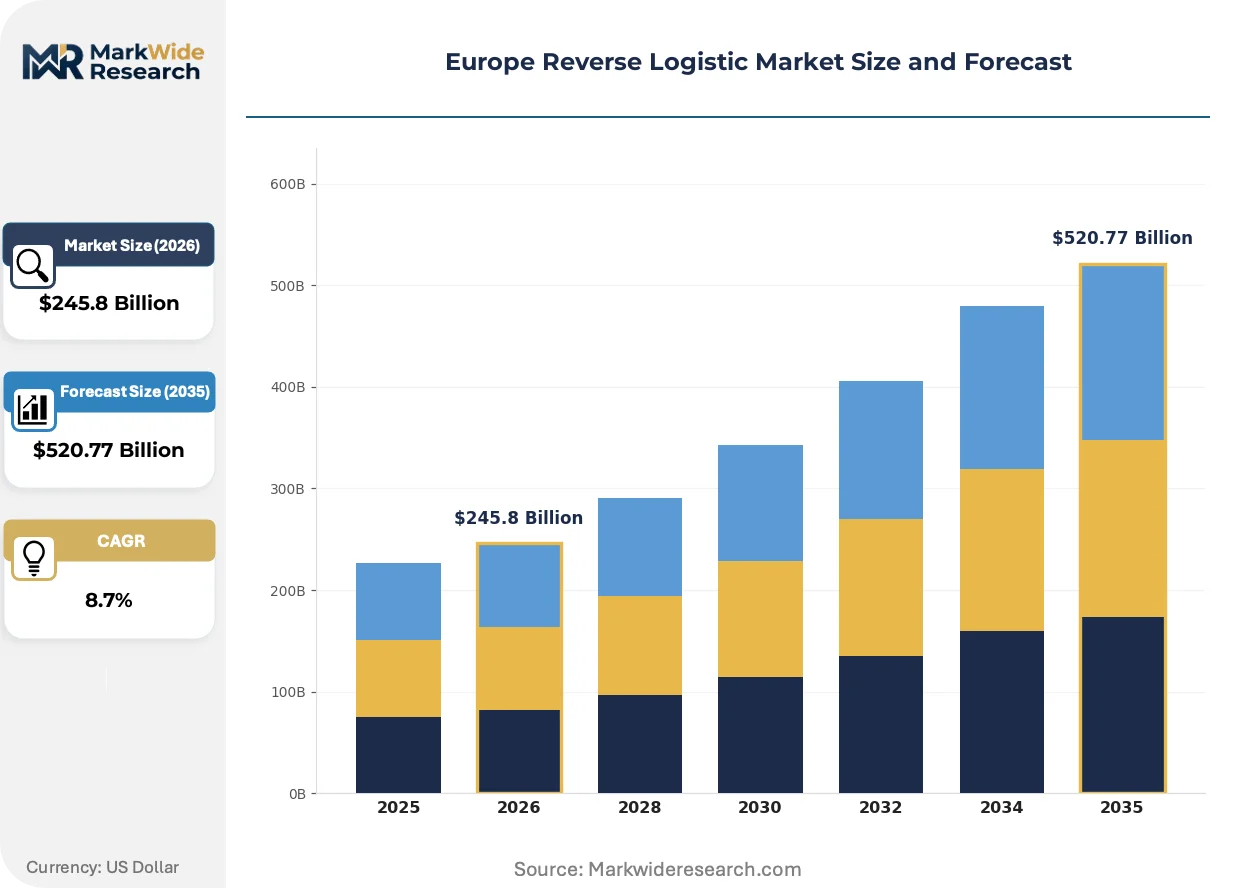
| Market Size in 2026 | $245.8 Billion |
| Market Size in 2035 | $520.77 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronics, Textiles, Furniture, Automotive Parts Service Type: Return Management, Repair Services, Recycling, Refurbishment End User: Retailers, Manufacturers, E-commerce Platforms, Third-Party Logistics Distribution Channel: Online Sales, Brick-and-Mortar, Direct Sales, Wholesale |
| Companies Covered | United Parcel Service, C.H. Robinson Worldwide, Deutsche Post DHL Group, Schenker AG, Reverse Logistics Group, DB Schenker, FedEx, CEVA Logistics, XPO Logistics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Reverse Logistic Market Shifts & Advancements
Digital traceability infrastructure and AI-assisted triage are compressing processing times and enabling condition-based routing decisions that were previously manual and inconsistent. These capabilities are reshaping how value is captured across the reverse chain.
Blockchain-enabled provenance tracking is modularizing custody documentation across multi-handoff return journeys. Third-party logistics providers in Germany and the Netherlands are deploying shared ledger systems to establish immutable records of condition at each transfer point. This technology is modularizing liability allocation between retailers, carriers, and refurbishment contractors who previously disputed damage attribution.
The EU Green Deal's right-to-repair provisions are mandating spare parts availability and disassembly instructions for electronics and appliances sold in member states. Manufacturers must now design for recoverability or face market exclusion, driving investment in modular product architectures. France's repairability index requirements and Germany's national implementation of the Ecodesign Directive are accelerating compliance redesigns in consumer durables.
Retailers are unbundling after-sales service from product sales, creating standalone reverse logistics contracts that third-party providers compete for on outcome metrics rather than cost-plus terms. This procurement evolution concentrates volume with operators who can guarantee processing SLAs and resale yield rates. The shift is most visible in Nordic markets where consumer protection laws already mandated generous return windows that normalized reverse flow as a core operational discipline.
Europe Reverse Logistic Market Segmentation
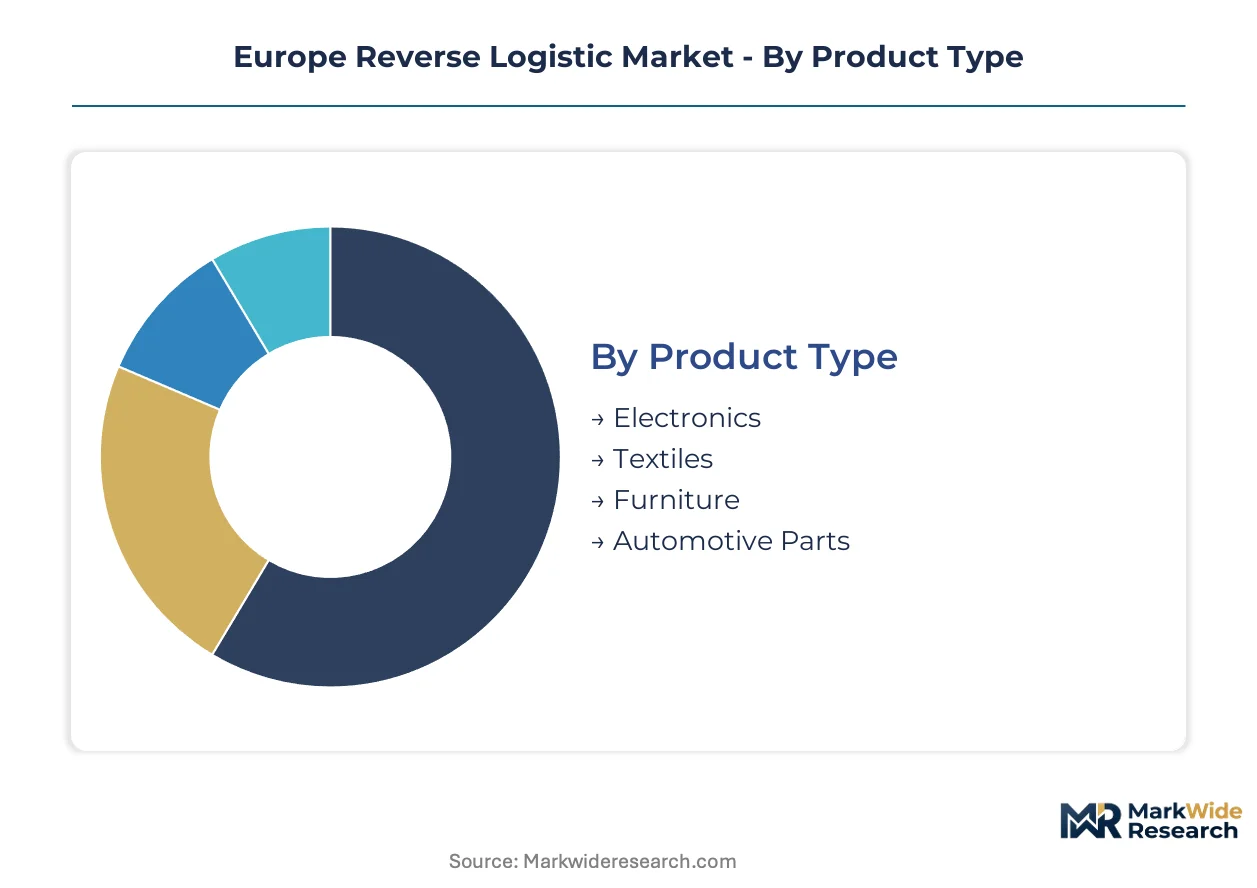
Reverse logistics operators in Europe configure specialized infrastructure around product damage profiles and regulatory handling requirements. Segment-specific investments in temperature control, hazardous materials certification, or automated sortation determine which service providers capture margin in each vertical.
Product Type:
Capital intensity varies sharply across product categories, with refrigerant-bearing appliances and lithium-ion electronics demanding specialized containment and diagnostic equipment that smaller operators cannot finance.
- Electronics:Smartphones, laptops, and consumer electronics require ESD-protected handling environments and battery state-of-health diagnostics. Demand concentrates in Germany's refurbishment corridors around Berlin and Dresden, driven by WEEE directive compliance costs that OEMs prefer to outsource. Most installed capacity flows through Electronics. Expansion is steepest in Automotive Parts.
- Automotive Parts:Powertrain components, electronics modules, and body panels flow through remanufacturing networks with OEM-certified quality protocols. France's Lyon-Clermont-Ferrand corridor anchors continental demand, propelled by EU end-of-life vehicle regulations mandating material recovery rates.
- Textiles:Apparel returns require steam sanitation, fabric grading, and resale channel routing. Netherlands-based operators lead in automated garment sorting for fashion e-commerce.
- Furniture:Bulky flat-pack and upholstered items need disassembly stations and foam recovery capabilities. IKEA's take-back programs in Sweden and Poland drive specialized collection network investments.
Electronics and Automotive Parts absorb the majority of capital deployment due to regulatory complexity and resale value recovery potential.
Service Type:
Margin structure diverges between transaction-heavy return processing and value-added refurbishment where labor arbitrage and technical certification create defendable positions.
- Refurbishment:Condition grading, component replacement, and cosmetic restoration to OEM-resale standards. Germany and France lead adoption, propelled by right-to-repair mandates and certified pre-owned device programs from major electronics brands.
- Return Management: Collection, triage, and routing decisions based on barcode-tracked condition assessment. E-commerce platforms in the Netherlands and Belgium drive volume concentration, supported by dense last-mile networks that reduce per-collection costs.
- Repair Services: Warranty fulfillment and out-of-warranty component-level fixes. Spain and Italy lag in technician certification pipelines relative to Northern European demand.
- Recycling: Material recovery and hazardous substance reclamation under REACH and F-Gas Regulation protocols. Specialized refrigerant handling creates regulatory moats around certified operators.
Refurbishment commands premium pricing through certified resale channels. Return Management scales fastest as e-commerce penetration deepens across Southern Europe.
End User:
Procurement sophistication ranges from cost-plus freight contracts to outcome-based agreements tied to resale yield rates and processing SLAs.
- E-commerce Platforms:High-velocity returns requiring same-day triage and next-day resale routing. Zalando in Germany and Bol in the Netherlands anchor demand for automated sortation hubs.
- Third-Party Logistics:Deutsche Post DHL Group and C.H. Robinson consolidate repair and recycling capabilities under single contracts to capture full-service revenue from retailers.
- Retailers:Omnichannel operators unbundling after-sales service from product sales, creating standalone reverse logistics contracts.
- Manufacturers:OEMs internalizing end-of-life costs under extended producer responsibility frameworks, particularly in Germany and France.
Third-Party Logistics providers concentrate the largest contract values. E-commerce Platforms are expanding their captive reverse infrastructure fastest.
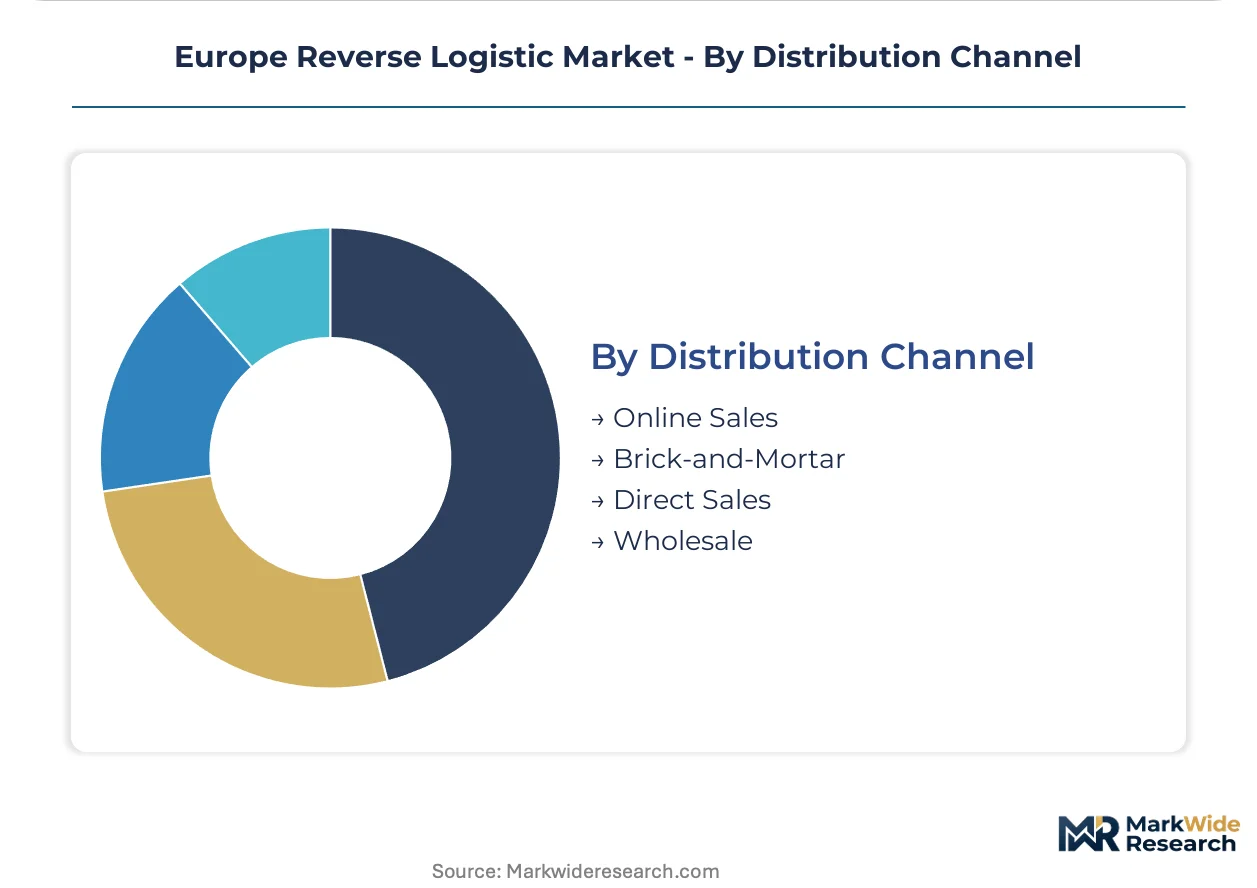
Distribution Channel:
Channel configuration determines return initiation points and consolidation economics, with online sales generating fragmented residential collections that favor pooled logistics networks.
- Online Sales:Direct-to-consumer shipments with prepaid return labels and drop-off point networks. France and the Netherlands show highest return rates, necessitating dedicated sortation investments.
- Brick-and-Mortar:Store-based returns aggregation with backhaul utilization to regional hubs. Nordic markets leverage dense retail footprints for efficient consolidation.
- Wholesale:B2B returns of unsold inventory with palletized handling and volume-based pricing. Belgium's bonded warehousing supports cross-border redistribution.
- Direct Sales:Manufacturer-owned channels with integrated reverse logistics, common in German automotive and appliance sectors.
Online Sales channels process the highest unit volumes. Wholesale is gaining share fastest as B2B marketplaces expand across Central Europe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered extended producer responsibility frameworks for electronics and automotive waste during the 1990s, establishing the operational template that now governs reverse logistics across the continent.
Germany
E-commerce returns volume from Berlin and Hamburg drives investment in automated sortation hubs. The national implementation of the Ecodesign Directive mandates recoverability-by-design for appliances sold in domestic markets. Refurbishment corridors around Berlin and Dresden concentrate WEEE-compliant processing capacity for smartphones and laptops.
France
Automotive remanufacturing demand clusters around Lyon and Clermont-Ferrand, fed by OEM quality protocols for powertrain components. ANSM enforces strict pharmaceutical reverse distribution standards for expired medicines. The repairability index requirement accelerates compliance redesigns in consumer electronics and appliances.
Netherlands
Rotterdam and Amsterdam anchor bonded warehousing infrastructure for cross-border e-commerce returns aggregation. Dense last-mile networks reduce per-collection costs for fashion and consumer electronics. Automated garment sorting systems process high volumes of apparel returns from Zalando and Bol.
Belgium
Customs-bonded facilities in Brussels and Antwerp sustain FedEx cross-border returns operations for UK and continental markets. The F-Gas Regulation drives specialized refrigerant reclamation investments for appliance returns. Pooled logistics networks serve mid-market retailers seeking consolidated customs clearance.
Italy
Technician certification pipelines lag Northern European demand for electronics refurbishment, creating skills bottlenecks in Milan and Turin hubs. REACH implementation drives material recovery investments for industrial packaging. Southern collection routes face margin compression from diesel price volatility across the peninsula.
Europe Reverse Logistic Market Competitive Landscape
Capital-heavy asset owners compete with asset-light platform operators across European reverse logistics. Network density and certification scope determine tier placement. Three archetypes dominate: integrated postal operators with captive infrastructure, digital freight platforms matching backhaul capacity, and specialized refrigerant-handling contractors. Consolidation proceeds through repair capability acquisitions and cross-border hub expansion.
Among integrated postal and parcel operators, Deutsche Post DHL Group anchors returns network capacity through automated hubs in the Netherlands and Germany. C.H. Robinson Worldwide occupies the digital freight platform position, matching return shipments with available backhaul capacity across continental routes. FedEx sustains cross-border e-commerce returns through customs-bonded facilities in Belgium and the United Kingdom.
| Leading Market Players |
|---|
| United Parcel Service |
| C.H. Robinson Worldwide |
| Deutsche Post DHL Group |
| Schenker AG |
| Reverse Logistics Group |
| DB Schenker |
| FedEx |
| CEVA Logistics |
| XPO Logistics |
| Others |
Supply & Pricing Matrix
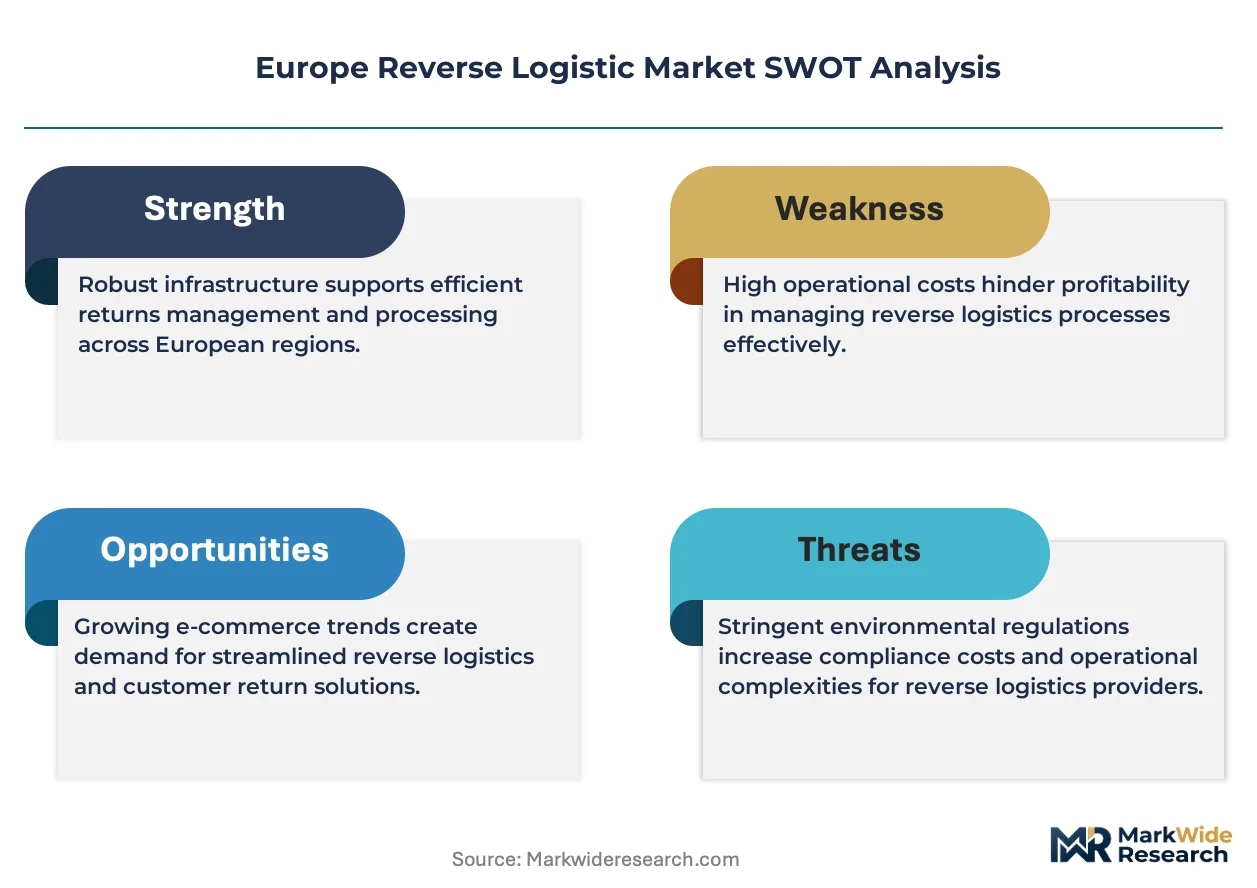
EU Green Deal circular economy mandates are forcing manufacturers to internalize end-of-life collection costs, compelling logistics providers to restructure service bundles and compress margins on standardized return processing. This demand-side regulatory pressure concentrates pricing power with certified operators who can guarantee compliance documentation across multiple member states.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates European reverse logistics contracts. Premium tiers attach to temperature-validated pharmaceutical handling and refrigerant-certified appliance recovery under F-Gas Regulation protocols. Standard pricing covers barcode-tracked electronics triage for major retailers. Economy tiers serve bulk apparel returns with minimal processing. Cost compression in standard electronics processing is intensifying because automated sortation capex demands multi-year amortization. Mid-market retailers show highest price sensitivity, while pharmaceutical manufacturers accept premium rates for serialization and cold-chain validation.
Supply Chain Analysis
Technician certification pipelines in Spain and Italy lag refurbishment demand from Northern European hubs, forcing operators to import skilled labor or delay processing SLAs. Supply concentrates in Germany, France, and the Netherlands where bonded warehousing and automated sortation infrastructure clusters. Raw material flows draw from lithium-ion battery supply chains, refrigerant reclamation networks, and secondary steel markets for automotive remanufacturing. Single-source vulnerability sits with specialized diagnostic equipment for battery state-of-health assessment. Distribution runs through hub-and-spoke networks anchored by Rotterdam, Hamburg, and Antwerp port complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe reverse logistics functions as a stable compounder anchored by regulatory mandates that expand producer responsibility obligations irreversibly. The EU Green Deal's recoverability-by-design requirements ensure baseline demand growth regardless of macroeconomic cyclicality.
For Market Incumbents: Anticipate margin erosion from digital freight platforms matching backhaul capacity with return shipments by securing exclusive refurbishment contracts with major electronics OEMs. Prioritize certification investment for F-Gas refrigerant handling and EMA pharmaceutical serialization to create regulatory moats. Capacity addition in Poland and Czechia captures cost arbitrage on technician labor while maintaining EU market access. For New Entrants and Emerging Players: Launch via cross-border consolidation platforms serving mid-market retailers in Belgium, Netherlands, and Luxembourg with pooled customs clearance and bonded warehousing. White-space targets include pharmaceutical reverse distribution in Southern Europe where ANSM-equivalent enforcement lags Northern standards, and packaging redesign engineering services upstream into product development cycles. Target automotive battery returns as electric vehicle penetration accelerates state-of-health diagnostic demand. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized refrigerant-handling contractors and temperature-validated pharmaceutical logistics specialists given regulatory certification barriers. The five-to-ten year viability window favors asset-heavy operators with integrated repair capabilities over pure-play digital brokers. Monitor divergence between EU-wide circular economy targets and country-specific implementation timelines as the inflection indicator for compliance cost fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Certification Investment | F-Gas Regulation compliance creates defensible revenue pools in appliance returns across Benelux and Germany. |
| Cross-Border Hub Expansion | Belgium and Netherlands bonded warehousing reduces per-unit handling costs for UK-continental e-commerce returns. |
| Repair Capability Acquisition | Consolidating refurbishment skills under single contracts captures full-service revenue from omnichannel retailers. |
| Pharmaceutical Serialization Infrastructure | EMA and ANSM mandates for expired medicines create temperature-validated niche with premium pricing power. |
| Packaging Redesign Services | EU Green Deal recoverability requirements extend logistics contracts upstream into product development engineering. |
Research Methodology
Multiple input streams — primary interviews with logistics operations directors, regulatory compliance officers, and e-commerce supply chain managers; secondary validation through EMA submissions, REACH implementation timelines, and EU customs trade data; plus WEEE directive enforcement records — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured operational metrics from automated sortation hubs and refurbishment facilities across Germany, France, and the Netherlands. Secondary sources included Deutsche Post DHL Group infrastructure disclosures, F-Gas Regulation compliance databases, and national extended producer responsibility implementation schedules.
Data-stream reconciliation anchored volume and value outputs across the analysis window. Segmentation dimensions modeled encompassed product type, service tier, end-user procurement sophistication, and distribution channel configuration. CAGRs were derived from trend extrapolation of e-commerce return rates, regulatory enforcement intensity indices, and circular economy investment flows. Industry-specific forecast inputs included electric vehicle battery replacement cycle projections and right-to-repair legislative adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory fragmentation scenarios where Southern and Eastern European implementation lags Northern timelines. Forecasts reflect assumptions about sustained EU Green Deal enforcement and stable e-commerce penetration rates. Practitioners should monitor country-specific Ecodesign Directive adoption schedules and battery diagnostic technology maturation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Europe Container Drayage Market
Transportation & Logistics
Czech Republic Road Freight Transport Market
Transportation & Logistics
Japan Cold Chain Logistics Market
Transportation & Logistics
Hong Kong Customs Brokerage Market
Transportation & Logistics
Perishable Goods Transportation Market
Transportation & Logistics
Refrigerated Transport Market
Transportation & Logistics
Japan Road Freight Transport Market
Transportation & Logistics
Latin America Customs Brokerage Market
Transportation & Logistics
Vietnam Road Freight Transport Market
Transportation & Logistics
Inland Water Freight Transport Market
Transportation & Logistics
Cross-Border Road Transport Market
Transportation & Logistics
Freight Transport Market
Transportation & Logistics
On Demand Transportation Market
Transportation & Logistics
Netherlands Road Freight Transport Market
Transportation & Logistics
Transportation Aggregators Market
Transportation & Logistics
Railcar Unloader Market