
 Kuwait Major Home Appliances Market | 2026-2036
Kuwait Major Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Kuwait Major Home Appliances Market Foresight
Market Context with Strategic Players
Capital-intensity divergence between integrated manufacturers and brand licensors is unwinding competitive stability in Kuwait's appliance sector. Samsung leverages its captive semiconductor supply chain to dominate smart refrigerator deployments in premium residential towers. Whirlpool sustains manufacturing scale advantages that anchor its position across mid-tier washing machine segments. Midea competes aggressively on cost-optimized production, extending its reach through supermarket and direct sales channels.
Technical Definition and Structural Segments
Kuwait major home appliances encompass electrically powered domestic equipment including refrigeration systems with compressor-driven vapor compression cycles, horizontal and vertical-axis washing machines, convection and conventional ovens, and automated dishwashers designed for residential and commercial food service operations. These appliances primarily serve climate adaptation, food preservation, textile cleaning, and meal preparation functions in high-temperature Gulf environments where ambient conditions exceed standard equipment ratings. Refrigerators and washing machines occupy the deepest margin pools due to mandatory replacement cycles and water scarcity concerns, while smart appliances represent the fastest-expanding technology segment as Kuwait City developers specify connected-device infrastructure in new towers. The hospitality end user category shows concentrated demand for commercial-grade dishwashers and ovens as hotel capacity expands ahead of regional event hosting.
Regulatory Framework and Outlook
Kuwait's Public Authority for Industry administers mandatory energy efficiency labeling and safety certification through KUCGC standards, while the Ministry of Electricity and Water promotes consumption reduction targets that directly shape importer product selection. The country's customs and port authorities enforce GCC-wide technical regulations that filter non-compliant conventional appliances from entering through Shuwaikh and Shuaiba ports. Stakeholders must monitor evolving smart grid integration requirements and water-efficiency mandates that will determine which technology portfolios secure preferential placement in government-procured residential developments.
Market Dynamics
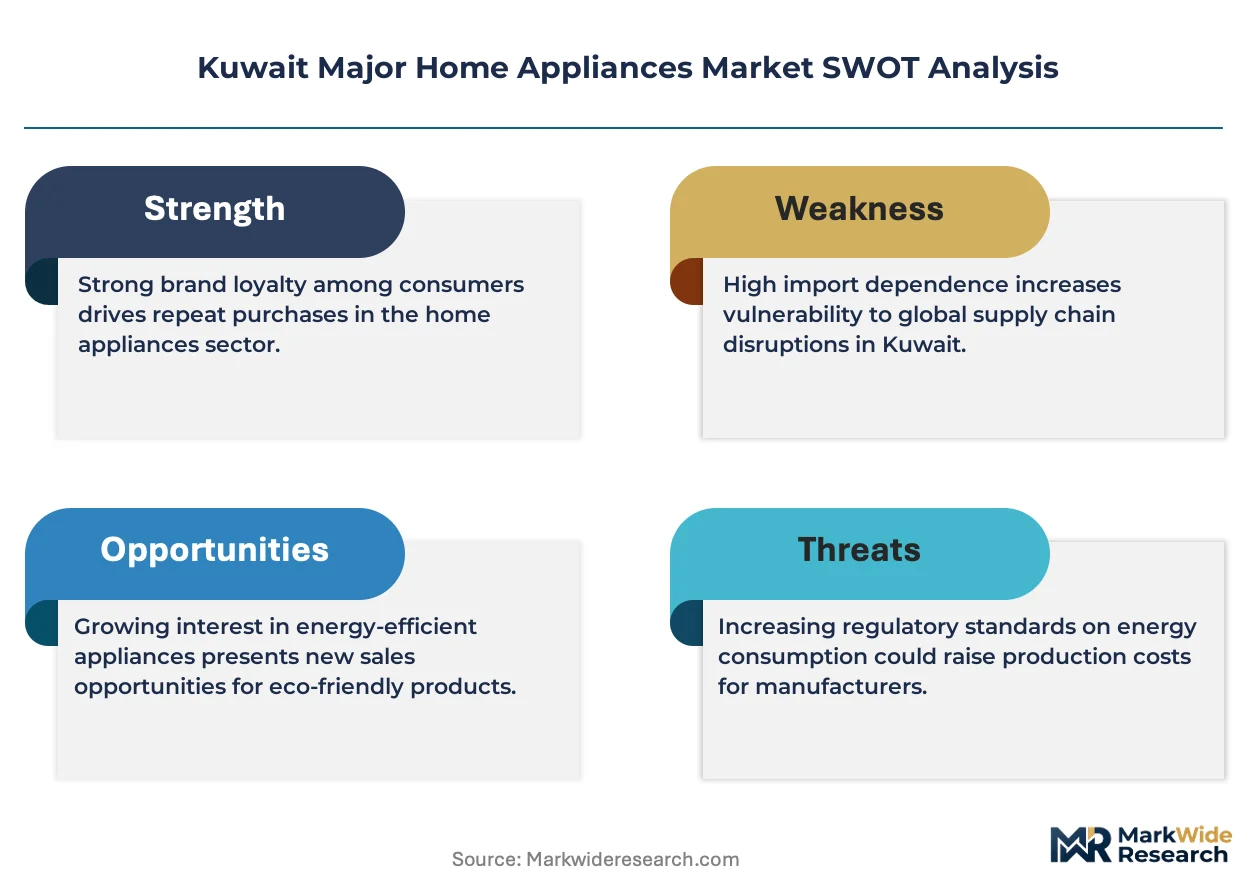
Kuwait's mandatory KUCGC energy labeling standards are compressing product portfolios and forcing importers to purge inefficient inventory before customs clearance at Shuwaikh port. This regulatory pressure intersects with water scarcity mandates to reshape which appliance configurations secure shelf space.
Growth Catalysts
- Water-efficiency mandates:The Ministry of Electricity and Water's consumption reduction targets accelerate replacement of conventional washing machines with low-water-cycle units in residential complexes across Salmiya and Jahra.
- Smart grid integration requirements:Kuwait City developers now specify connected-device infrastructure in upscale residential towers, pulling demand for Wi-Fi-enabled refrigeration systems with remote diagnostics.
- Hospitality capacity expansion:Hotel construction ahead of regional event hosting concentrates procurement of commercial-grade dishwashers and convection ovens in Kuwait City's commercial hospitality developments.
Market Restraints
- Semiconductor supply concentration:Captive chip supply chains controlled by integrated manufacturers create procurement bottlenecks for smart appliance assemblers lacking backward integration into semiconductor fabrication.
- Port clearance friction:GCC-wide technical regulations enforced by customs authorities at Shuaiba port delay entry of non-compliant conventional appliances, extending inventory holding periods for distributors.
- Compressor technology substitution:Linear compressor systems threaten established reciprocating compressor margins in premium refrigeration segments, forcing portfolio rebalancing costs.
Strategic Opportunities
- Direct-to-consumer channels:Supermarket and e-commerce platforms bypass traditional dealer networks, enabling cost-optimized producers to capture margin previously allocated to distributor markups.
- Energy-label premium tier:KUCGC A+++ certification creates pricing stratification that rewards early compliance with preferential placement in government-procured residential developments.
- Commercial food service automation:Automated dishwasher specifications in hotel and catering operations open replacement cycles shorter than residential equipment lifespans.
Industry Challenges
- Retrofit integration complexity:Legacy electrical infrastructure in older residential towers requires costly panel upgrades to support smart appliance connectivity and load management.
- Certification timeline compression:Accelerated KUCGC standard revisions force simultaneous engineering and testing cycles, stretching R&D resources across multiple compliance tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kuwait Major Home Appliances Market |
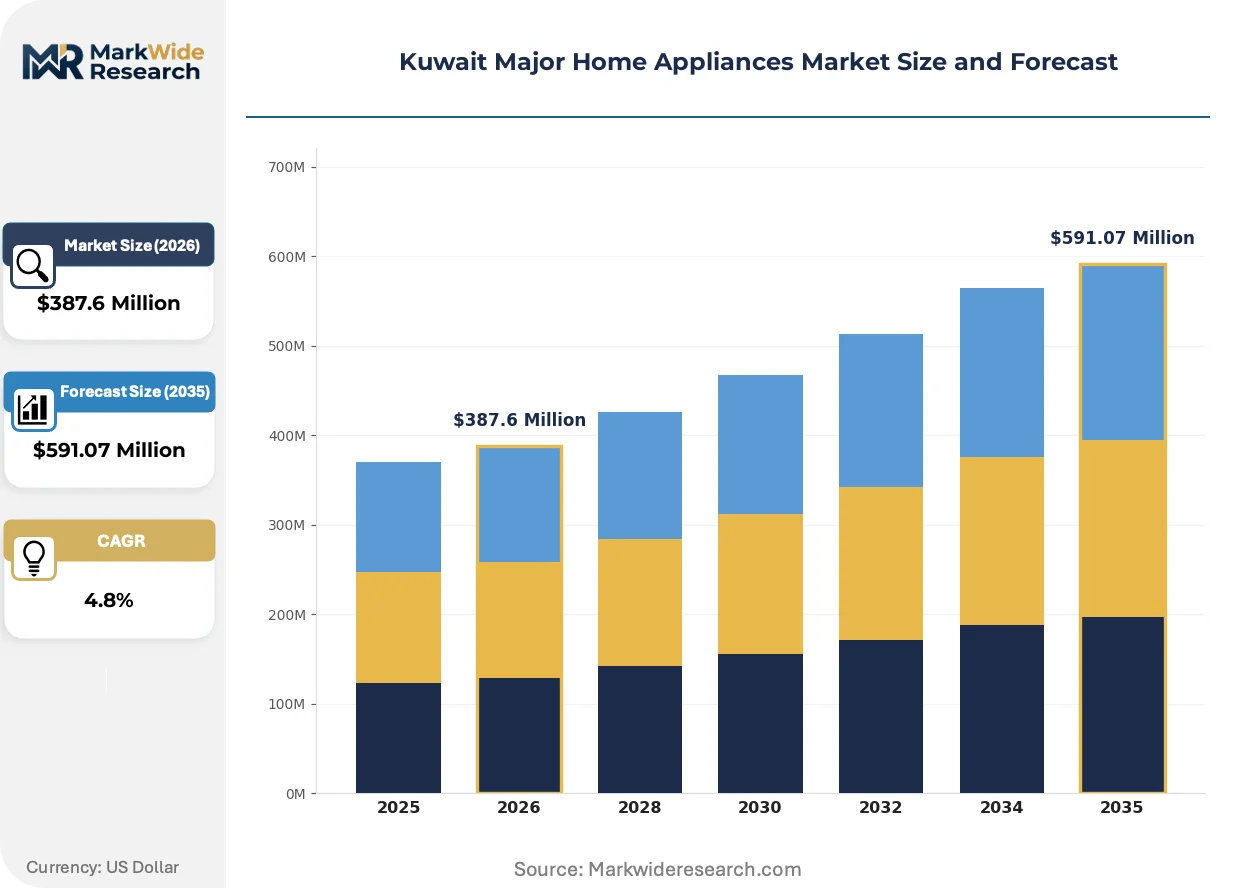
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Ovens, Dishwashers End User: Residential, Commercial, Retail, Hospitality Technology: Smart Appliances, Energy Efficient, Conventional, Hybrid Distribution Channel: Online, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Whirlpool, Midea, Samsung, Sharp, Toshiba, Panasonic, Bosch, Candy, Electrolux, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kuwait Major Home Appliances Market Shifts & Advancements
Inverter-driven compressor technology is rapidly penetrating Kuwait's appliance replacement cycles, enabled by regulatory pressure and developer specifications in new construction. This shift compresses traditional equipment lifespans and reconfigures after-sales service revenue models.
Inverter compressor systems optimize energy consumption through variable-speed motor control rather than fixed-cycle operation. Premium residential towers in Kuwait City now specify these units as baseline requirements in developer fit-out packages. The technology is displacing conventional fixed-speed compressors from mid-tier and premium product lines, compressing margin pools for manufacturers dependent on legacy platform economics.
Kuwait's Public Authority for Industry administers mandatory KUCGC energy efficiency labeling that filters non-compliant products from import channels. The standard creates tiered market access where A-rated appliances secure preferential placement in government-procured housing developments. Mid-tier washing machine segments face the steepest compliance costs as manufacturers rebalance portfolios toward certification thresholds.
Developer-specified smart infrastructure in new residential towers is altering procurement authority away from end-consumers toward construction-phase decision-makers. This channel consolidation concentrates volume with project procurement teams who negotiate multi-unit contracts before individual buyers take possession. The shift is most visible in Kuwait City's upscale tower developments where connected-device specifications are embedded in architectural plans rather than selected at retail.
Kuwait Major Home Appliances Market Segmentation
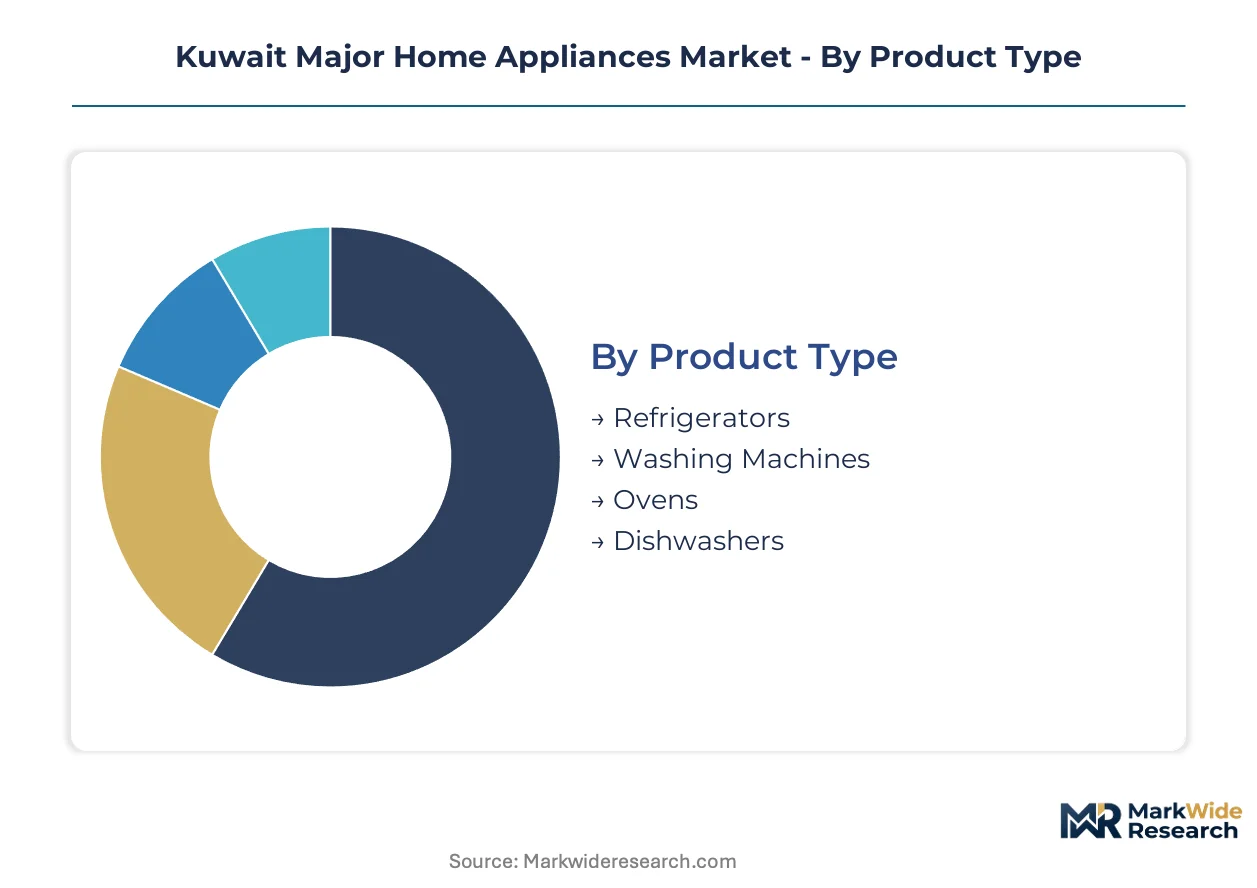
Segmentation in Kuwait's appliance market exposes where regulatory pressure and infrastructure investment concentrate profit pools. Distinct technology tiers and channel configurations face divergent substitution threats from inverter compressors, smart grid integration, and direct-to-consumer platforms.
Product Type:
Refrigerators face the sharpest substitution pressure as linear compressor systems displace reciprocating platforms in premium segments.
- Refrigerators:Compressor-driven vapor compression cycles dominate, with inverter-driven units specified as baseline in Kuwait City upscale towers. Salmiya and Jahra residential complexes drive replacement demand amid mandatory KUCGC energy labeling enforcement.
- Washing Machines:Horizontal and vertical-axis configurations serve textile cleaning functions in high-temperature Gulf environments. Water-efficiency mandates from the Ministry of Electricity and Water accelerate low-water-cycle unit deployment.
- Ovens:Convection and conventional heating systems support meal preparation across residential and food service operations.
- Dishwashers:Automated units designed for residential and commercial food service face concentrated hospitality procurement ahead of regional event hosting.
Refrigerators retain volume leadership; smart-enabled washing machines hold the steepest expansion curve.
End User:
Cost tier stratification separates project-procured volume from individual retail selection, with developer-specified infrastructure altering decision authority.
- Residential:Individual households and family units in established complexes across Salmiya and Jahra drive replacement cycles for energy-efficient refrigerators and washing machines under water scarcity constraints.
- Commercial:Food service enterprises and catering operations generate shorter replacement cycles than residential equipment through intensive utilization patterns.
- Retail:Appliance showrooms and dealer networks face margin compression from supermarket and e-commerce channel expansion.
- Hospitality:Hotel capacity expansion in Kuwait City concentrates procurement of commercial-grade dishwashers and convection ovens for regional event hosting.
Residential maintains absolute volume; hospitality procurement climbs fastest on infrastructure timelines.
Technology:
Application maturity divides segments between regulated efficiency tiers and emerging connectivity platforms.
- Smart Appliances:Wi-Fi-enabled refrigeration systems with remote diagnostics concentrate in Kuwait City upscale residential towers where developers specify connected-device infrastructure during construction phase.
- Energy Efficient:KUCGC A+++ certified units secure preferential placement in government-procured residential developments through mandatory labeling standards administered by the Public Authority for Industry.
- Conventional:Fixed-speed compressor platforms face customs clearance friction at Shuaiba port under GCC-wide technical regulations filtering non-compliant inventory.
- Hybrid:Intermediate efficiency configurations bridge compliance costs for mid-tier washing machine segments facing steepest portfolio rebalancing pressures.
Energy Efficient technology anchors current volume; Smart Appliances gain share fastest on developer specification trends.
Distribution Channel:
Customer type fragmentation separates institutional project procurement from individual retail behavior, with channel consolidation favoring scaled platforms.
- Online:E-commerce platforms bypass traditional dealer markups, enabling cost-optimized producers to capture margin previously allocated to distributor networks.
- Supermarkets:Direct sales through grocery retail chains extend reach for cost-optimized production without dealer infrastructure investment.
- Specialty Stores:Dedicated appliance showrooms retain relevance for complex product consultation and installation service bundling.
- Direct Sales:Manufacturer-controlled channels concentrate volume with project procurement teams negotiating multi-unit contracts before individual buyer possession.
Specialty Stores retain volume leadership; Online channels track the steepest expansion trajectory on margin compression dynamics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kuwait's import-dependent appliance sector sources finished goods and compressor components through maritime corridors connecting East Asian manufacturing hubs to Gulf distribution networks. Trade flows concentrate through Shuwaikh and Shuaiba ports where customs authorities enforce technical compliance before inland distribution to residential and commercial end-users.
Kuwait City
Upscale residential towers in Kuwait City drive specification-grade procurement of smart-enabled refrigeration systems with connected-device infrastructure. The Public Authority for Industry administers mandatory KUCGC energy labeling standards that filter product portfolios entering this sub-market. Developer-led fit-out packages in commercial hospitality developments concentrate demand for commercial-grade dishwashers and convection ovens ahead of regional event hosting timelines.
Salmiya
Established residential complexes in Salmiya generate replacement cycles for energy-efficient refrigerators and washing machines under water scarcity constraints. Ministry of Electricity and Water consumption reduction targets accelerate deployment of low-water-cycle washing machine units across aging apartment stock. Retail channel presence remains dense here, though supermarket and e-commerce platforms erode traditional dealer margins.
Jahra
Family-unit households in Jahra's residential zones sustain mid-tier appliance demand driven by mandatory replacement of fixed-speed compressor platforms. KUCGC labeling enforcement through customs clearance at Shuwaikh port shapes which efficiency tiers reach this price-sensitive sub-market. Local distributor networks maintain stronger footholds here compared to direct-to-consumer channels dominant in central business districts.
Hawalli
Mixed-use developments in Hawalli blend residential and small commercial food service operations requiring diversified appliance configurations. The Public Authority for Industry's safety certification requirements apply uniformly across these hybrid end-use categories. Specialty appliance showrooms retain relevance in this corridor for complex product consultation and installation service bundling.
Ahmadi
Industrial zone proximity in Ahmadi concentrates procurement for commercial food service automation in catering and hospitality support operations. Shorter replacement cycles than residential equipment characterize this sub-market due to intensive utilization patterns. Direct sales channels negotiate multi-unit contracts with project procurement teams before individual operational managers take possession.
Kuwait Major Home Appliances Market Competitive Landscape
Concentration sits with integrated manufacturers possessing captive semiconductor supply chains and brand licensors leveraging outsourced production scale. The vendor base stratifies across three tiers: premium smart-appliance specialists, mid-tier volume manufacturers, and cost-optimized mass-market suppliers. Two strategic archetypes dominate competitive positioning—backward-integrated technology owners and brand-centric asset-light licensors. Dominant competitive moves include portfolio rebalancing toward inverter compressor platforms and channel consolidation through direct-to-consumer platform expansion.
Within the integrated technology tier, Samsung and Whirlpool anchor competitive positioning through contrasting supply chain configurations. Samsung exemplifies the captive-semiconductor archetype with in-house component production supporting smart appliance specifications. Whirlpool occupies a position emphasizing manufacturing scale advantages across conventional efficiency tiers. Midea represents the cost-optimized production archetype, extending market reach through supermarket and direct sales channels that bypass traditional distributor markups. These three companies illustrate the structural divergence between technology ownership and manufacturing scale as competitive foundations.
| Leading Market Players |
|---|
| Whirlpool |
| Midea |
| Samsung |
| Sharp |
| Toshiba |
| Panasonic |
| Bosch |
| Candy |
| Electrolux |
| Others |
Supply & Pricing Matrix
Project-based procurement contracts with Kuwait City developers lock in multi-year compressor supply commitments and price visibility for inverter-driven refrigeration platforms. These agreements tether component sourcing to construction-phase specifications, insulating tier-one suppliers from spot-market volatility while compressing margin pools for distributors excluded from direct negotiations.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in Kuwait's appliance sector. KUCGC A+++ certification and smart-grid connectivity specifications drive price differentiation, with premium tiers commanding substantial markups for Wi-Fi-enabled refrigeration systems. Cost compression in mid-tier washing machine segments is intensifying because water-efficiency mandates force rapid portfolio rebalancing. Residential replacement buyers in Jahra exhibit highest price sensitivity, while hospitality procurement teams in Kuwait City prioritize performance specifications over unit economics.
Supply Chain Analysis
Extended customs clearance timelines at Shuwaikh port are compressing inventory turnover for distributors dependent on East Asian finished goods. Manufacturing concentration in China, South Korea, and Vietnam feeds Kuwait's import-dependent market, with semiconductor components and inverter compressor systems representing critical input dependencies. Single-source vulnerability around captive chip supply chains controlled by integrated manufacturers creates procurement bottlenecks for smart appliance assemblers. Distribution runs through maritime corridors terminating at Shuwaikh and Shuaiba ports, with inland logistics connecting to retail and project-procurement endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kuwait's major home appliances market functions as a defensive-moat arena where regulatory entrenchment through KUCGC certification requirements creates substantial barriers to unqualified entrants. Switching costs for developer-specified infrastructure lock in procurement relationships across multi-year construction cycles.
For Market Incumbents: Compound defensive positioning by deepening backward integration into inverter compressor production and securing exclusive fit-out contracts with Kuwait City tower developers. Linear compressor substitution threatens reciprocating platform margins; counter through accelerated A+++ certification investment and channel control over direct-to-consumer supermarket placements. For New Entrants and Emerging Players: Aftermarket service gaps in Salmiya's aging residential complexes present white-space opportunities where incumbents under-serve legacy equipment maintenance. Target Jahra's price-sensitive family-unit segment through cost-optimized washing machine platforms distributed via local dealer networks rather than project-procurement channels. For Investors and Strategic Acquirers: Brand-centric asset-light licensors with established KUCGC compliance track records represent the most attractive acquisition archetype for portfolio exposure to Kuwait's replacement-driven demand. Monitor smart grid integration mandate announcements from the Ministry of Electricity and Water as the critical inflection signal for connectivity-premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Compressor Platform Migration | Captures KUCGC A+++ certification premiums in government-procured residential developments. |
| Direct-to-Consumer Channel Expansion | Bypasses distributor markups through supermarket and e-commerce platform penetration. |
| Smart Appliance Connectivity Investment | Aligns product portfolios with developer-specified infrastructure in Kuwait City towers. |
| Water-Efficiency Certification Acceleration | Secures preferential placement under Ministry of Electricity and Water consumption mandates. |
| Commercial Food Service Automation Focus | Captures shorter replacement cycles in hospitality procurement ahead of regional event hosting. |
Research Methodology
Operator-level perspectives from appliance procurement managers at hospitality developers, category buyers at supermarket chains, and aftermarket service directors anchored the qualitative base for this study. Primary interviews with distributor network heads and project fit-out consultants combined with secondary validation from customs import records, KUCGC certification databases, and Ministry of Electricity and Water regulatory filings. Bottom-up unit shipment estimates triangulated against top-down construction pipeline data across Kuwait's residential and commercial development zones.
Sensitivity analysis tested forecast robustness across alternative regulatory enforcement scenarios and construction timeline delays over the projection horizon. Segmentation dimensions modeled include product type, end-user category, technology tier, and distribution channel, with additional granularity on developer-specified versus retail-procured volume splits. CAGRs derived from regression-based trend extrapolation incorporating KUCGC standard revision timelines and water-efficiency mandate implementation schedules.
Underlying assumptions cover sustained KUCGC enforcement intensity and continued hospitality capacity expansion, with deviation risk concentrated in semiconductor supply disruptions and customs clearance policy shifts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
North America Electric Fireplace Market
Home Appliances
High-End French Door Refrigerator Market
Home Appliances
Saudi Arabia Major Home Appliances Market
Home Appliances
Electrical Appliances Market
Home Appliances
Electric Fireplace Market
Home Appliances
India Laundry Appliances Market
Home Appliances
Brazil Home Appliances Market
Home Appliances
Middle East and Africa Laundry Appliances Market
Home Appliances
Global Residential Microwave Oven Market
Home Appliances
Oman Major Home Appliances Market
Home Appliances
Europe White Goods Market
Home Appliances
Small Home Appliances Market
Home Appliances
Bahrain Home Appliances Market
Home Appliances
Slovakia Home Appliances Market
Home Appliances
Home Laundry Appliances Market
Home Appliances
Latin America Washing Machine Market