
 Connected Home Appliances Market | 2026-2036
Connected Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Home Appliances Market Analysis
Silicon carbide power modules are pivoting into inverter circuits for smart HVAC compressors, cutting energy losses versus traditional silicon IGBTs. Samsung Electronics leverages captive semiconductor foundry partnerships to secure early supply of these modules. LG Electronics anchors its premium positioning through proprietary ThinQ AI integration across refrigeration and cooking lines. Haier Smart Home dominates connected laundry in China through direct-to-consumer platform control and localized manufacturing scale.
Connected home appliances comprise household equipment with embedded sensors, network interfaces, and software controllers that enable remote operation, automated scheduling, and energy optimization through cloud-based analytics. These systems typically integrate 2.4 GHz Wi-Fi or sub-GHz mesh protocols with power draw below 15 watts in standby networking mode, serving residential and commercial operators seeking operational visibility and demand-response compliance. Smart refrigerators lead product type value pools due to higher unit costs and replacement cycles extending past twelve years, while smart HVAC systems represent the fastest-expanding category as heat pump electrification mandates spread. Wi-Fi technology captures the largest installed base owing to router ubiquity, though Zigbee is gaining in whole-home ecosystems where interoperability with utility demand-response programs creates sticky revenue.
The EU Ecodesign Directive and Energy Labeling Framework tighten minimum efficiency thresholds for networked appliances, forcing redesign of standby power circuits and compressor control algorithms. The US EPA ENERGY STAR specification for smart home energy management systems shapes product certification requirements and retail channel access. China's GB standards for household appliance network security, administered by MIIT, impose firmware update obligations and data localization rules. Stakeholders must monitor how fragmented cybersecurity mandates across Brussels, Washington, and Beijing fragment platform architectures and test compliance budgets.
Market Dynamics
Silicon carbide power modules are compressing inverter losses in smart HVAC compressors, forcing incumbent appliance manufacturers to redesign thermal management systems and secure semiconductor supply through captive foundry partnerships rather than merchant markets.
Growth Catalysts
- EU Ecodesign Directive:Tightening standby power thresholds for networked appliances accelerates redesign of compressor control algorithms and networking circuits across refrigeration and laundry segments.
- Heat pump electrification mandates:National building codes in Germany, France, and the Netherlands mandate fossil fuel heating replacements, pulling smart HVAC systems into residential retrofit pipelines.
- Sub-GHz mesh protocols:Whole-home ecosystems leveraging Zigbee and Thread are displacing standalone Wi-Fi appliances as utility demand-response programs reward interoperable load flexibility.
Market Restraints
- Silicon carbide wafer concentration:Substrate supply concentrates among Japanese and US semiconductor manufacturers, exposing appliance OEMs to allocation risk during power module ramp-ups.
- GB standards compliance:China's MIIT firmware update obligations and data localization rules fragment platform architectures and inflate testing budgets for multinational suppliers.
- Legacy HVAC replacement cycles:Installed base turnover stretches past fifteen years in residential heating, delaying smart system penetration despite regulatory deadlines.
Strategic Opportunities
- India's smart meter rollout:Utility-backed appliance rebate programs are nascent but expanding, creating first-mover positioning for connected HVAC and water heating platforms.
- Voice-native kitchen interfaces:Convergence of natural language processing with induction cooking controls opens premium pricing tiers for hands-free recipe execution and safety interlocks.
- Direct-to-consumer platform control:Bypassing traditional retail channels through manufacturer-owned apps captures recurring service revenue and usage data for predictive maintenance offerings.
Industry Challenges
- Cybersecurity certification timelines:Fragmented mandates across Brussels, Washington, and Beijing force redundant penetration testing and firmware validation cycles before market entry.
- Power electronics integration:Embedding silicon carbide modules requires thermal engineering capabilities scarce among traditional appliance mechanical engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Home Appliances Market |
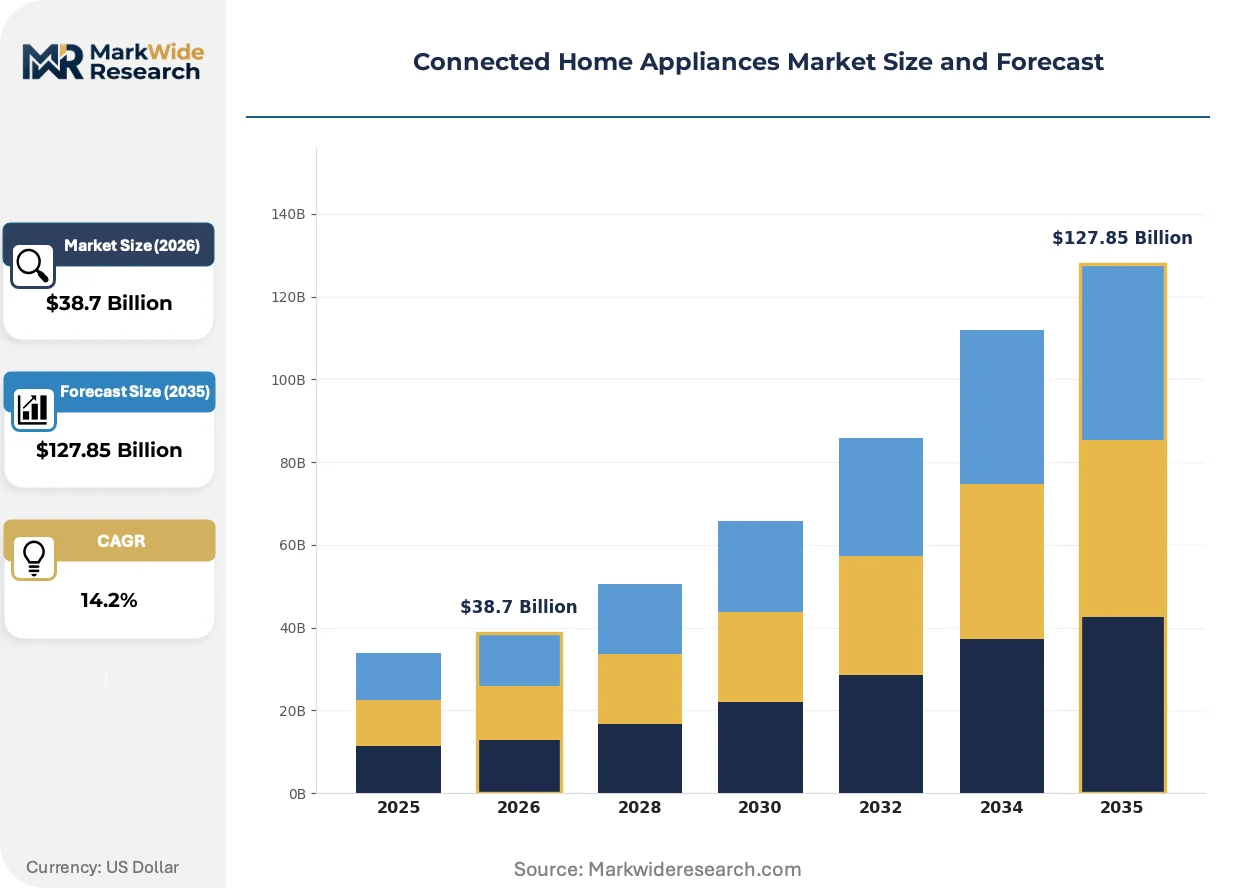
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Refrigerators, Smart Ovens, Smart Washers, Smart HVAC Systems Technology: Wi-Fi, Zigbee, Bluetooth, NFC End User: Residential, Commercial, Retail, Hospitality Feature: Energy Efficiency, Voice Control, Remote Monitoring, Automation |
| Companies Covered | Samsung Electronics, LG Electronics, Haier Smart Home, Robert Bosch GmbH, Whirlpool Corporation, Midea Group, Panasonic Corporation, BSH Hausgeräte GmbH, Xiaomi Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Home Appliances Market Emerging Trajectories
Heat pump technology is compressing the boundary between HVAC and water heating systems, creating unified thermal platforms that challenge traditional product category definitions and supplier specialization.
Silicon carbide MOSFETs are replacing silicon IGBTs in variable-speed compressor drives. Residential heat pump manufacturers in Germany and the Netherlands are adopting these modules at scale for 2025 product lines. This transition is electrifying efficiency benchmarks and forcing incumbent suppliers to secure wafer supply through long-term purchase agreements.
The F-Gas Regulation is phasing down hydrofluorocarbon refrigerants with high global warming potential. Appliance OEMs must qualify alternative refrigerants and redesign sealed system architectures. Smart refrigeration platforms face the steepest compliance curves as replacement refrigerants demand higher-pressure compressors and revised safety interlocks.
Builder procurement is consolidating around whole-home smart system specifications rather than individual appliance brands. Suburban North American property developers now mandate unified platforms controlling HVAC, water heating, and kitchen loads. This specification shift concentrates vendor selection power among a handful of ecosystem providers and squeezes standalone appliance margins.
Connected Home Appliances Market Segmentation
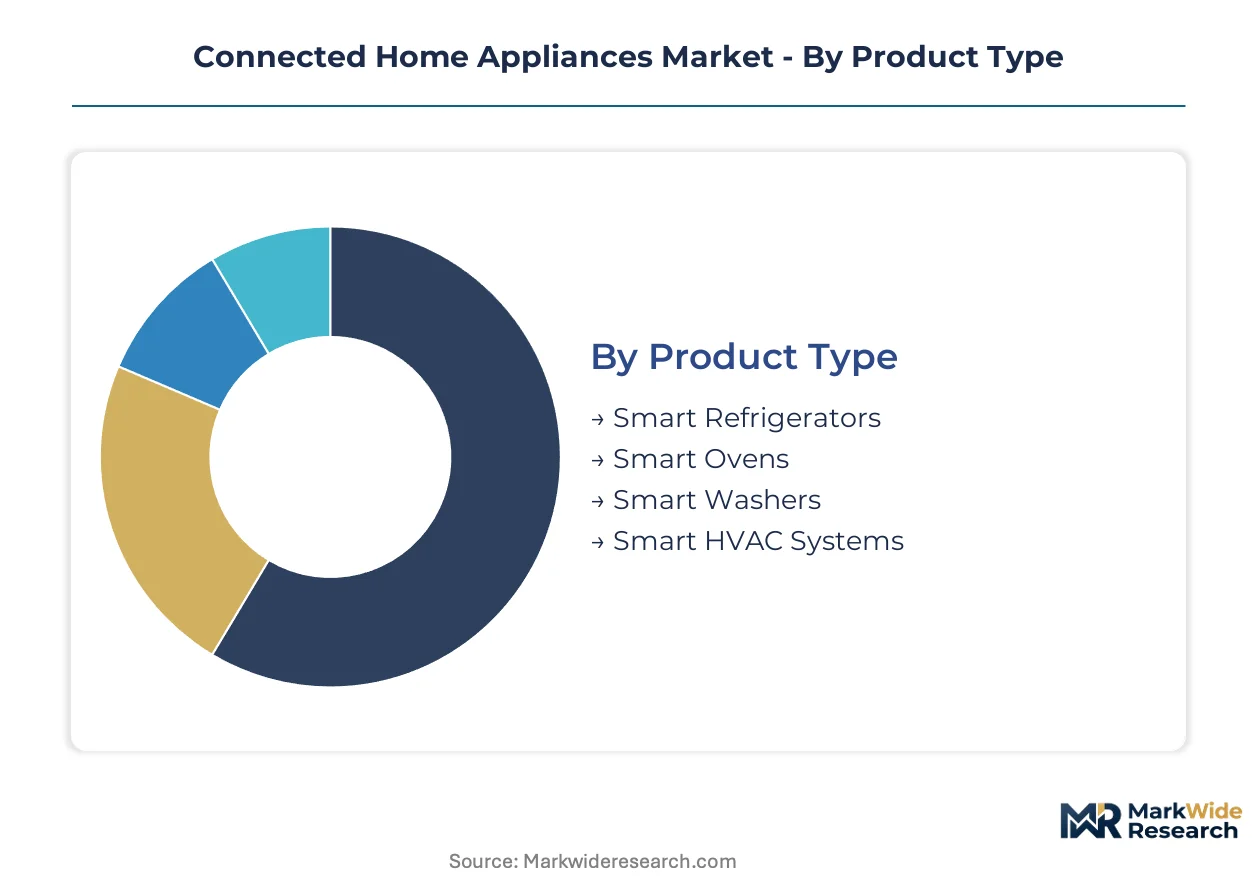
Segmentation in connected home appliances reveals how hardware specifications, network protocols, and end-use requirements fragment both engineering priorities and go-to-market strategies. Understanding these divides helps suppliers allocate R&D budgets across competing connectivity standards and regulatory compliance paths.
Product Type:
Customization intensity varies sharply across this category, with built-in appliances demanding bespoke installation protocols while freestanding units prioritize plug-and-play interoperability.
- Smart Refrigerators:These units integrate multi-zone cooling algorithms with embedded cameras and inventory tracking software. Demand clusters in suburban North American new construction where builder specifications mandate connected kitchen suites. Higher unit costs and replacement cycles exceeding twelve years sustain premium pricing tiers.
- Smart HVAC Systems:Heat pump electrification mandates in Germany and the Netherlands are pulling these systems into residential retrofit pipelines. Utility-backed rebate programs accelerate adoption where demand-response compliance creates sticky revenue streams.
- Smart Ovens:Induction cooking controls with embedded recipe databases serve renovation markets seeking safety interlocks and hands-free operation.
- Smart Washers:Direct-to-consumer platform control dominates in China through localized manufacturing scale and app-based service scheduling.
Most installed capacity flows through Smart Refrigerators. Expansion is steepest in Smart HVAC Systems.
Technology:
Protocol selection hinges on power budget constraints versus ecosystem lock-in value, with mesh architectures commanding higher upfront integration costs but lower lifetime connectivity fees.
- Wi-Fi:Router ubiquity drives the largest installed base despite 2.4 GHz congestion in dense residential environments. Standby power draw below 15 watts meets EU Ecodesign thresholds without hardware redesign.
- Zigbee:Sub-GHz mesh protocols gain traction in whole-home ecosystems where interoperability with utility demand-response programs rewards load flexibility. Thread compatibility is emerging as a convergence pathway.
- Bluetooth:Proximity-based pairing suits point-of-use appliances with intermittent connectivity needs and minimal cloud dependency.
- NFC:Tap-to-configure workflows reduce onboarding friction for rental properties and hospitality deployments with high tenant turnover.
Wi-Fi carries the majority of legacy installations. Zigbee is climbing the fastest as utility program enrollment expands.
End User:
Procurement authority separates this category, with centralized facility managers prioritizing fleet analytics while individual homeowners respond to retail promotion cycles.
- Residential:Single-family homeowners drive replacement demand through twelve-to-fifteen-year appliance cycles. Suburban North American property developers are expanding smart kitchen installations in new construction.
- Commercial:Multi-tenant office buildings require centralized energy dashboards and predictive maintenance contracts to justify connectivity infrastructure spend.
- Retail:Appliance showrooms deploy connected displays to demonstrate remote operation features and capture usage data for manufacturer co-marketing.
- Hospitality:Hotel chains mandate unified platforms controlling in-room HVAC, water heating, and mini-bar refrigeration to standardize guest experience and reduce service calls.
Residential absorbs the highest absolute unit volume. Hospitality is gaining share fastest as brand standards consolidate around ecosystem providers.
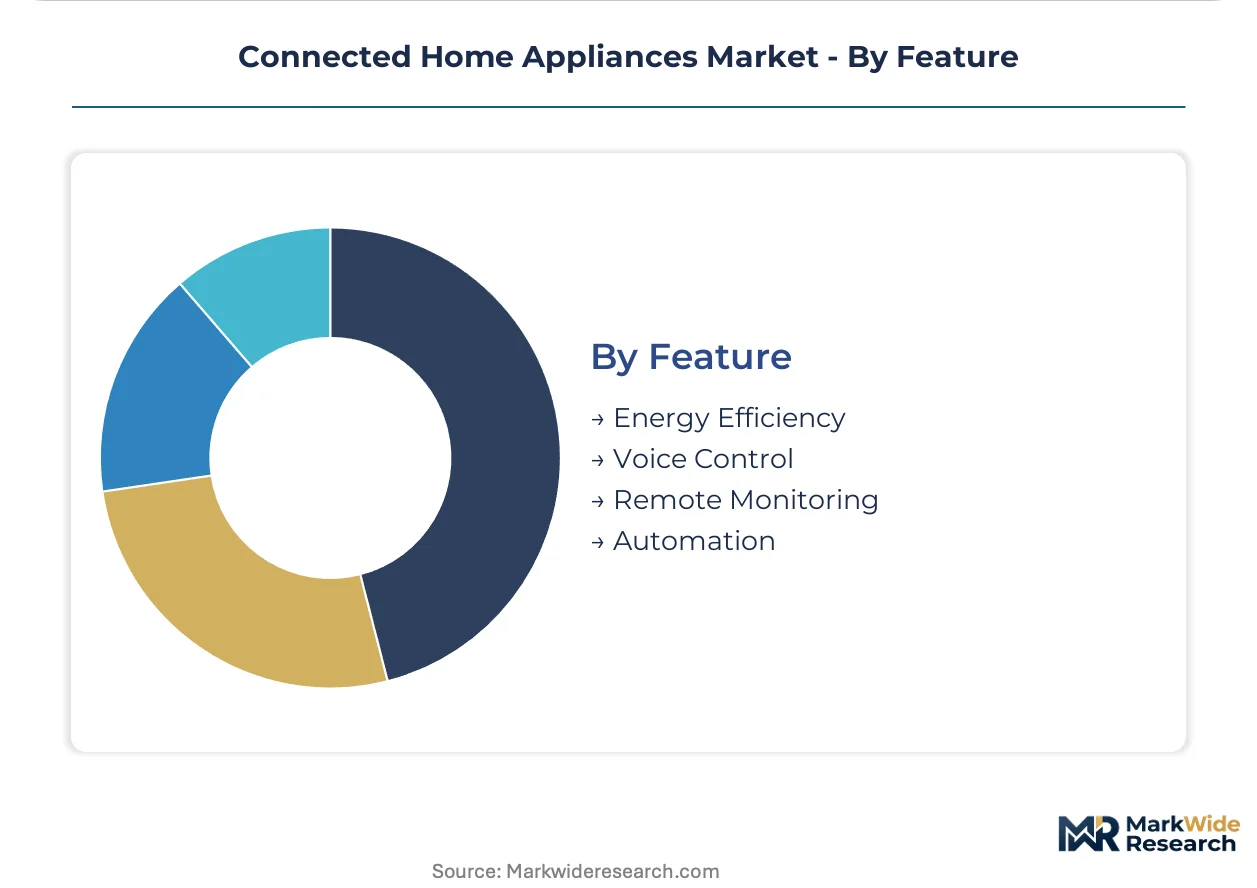
Feature:
Feature bundling reflects regional regulatory pressure, with efficiency mandates compulsory in Europe and voice interfaces optional premium add-ons in North America.
- Energy Efficiency:Compressor control algorithms and standby power circuits face tightening thresholds under the EU Ecodesign Directive and US EPA ENERGY STAR specifications. Redesign costs concentrate in refrigeration and laundry segments.
- Voice Control:Natural language processing integration with cooking controls opens premium pricing tiers for hands-free recipe execution. Convergence with induction safety interlocks differentiates high-end kitchen suites.
- Remote Monitoring:Cloud-based analytics enable predictive maintenance offerings and usage-based service subscriptions through manufacturer-owned apps.
- Automation:Scheduled operation and utility-triggered load curtailment serve demand-response compliance in markets with time-of-use electricity pricing.
Energy Efficiency features are mandatory across the largest addressable markets. Voice Control is expanding most quickly as natural language processing costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors manufacturing scale for connected home appliances, while regulatory divergence across Brussels, Washington, and Beijing fragments platform architectures and compliance budgets for multinational suppliers.
United States
Suburban property developers in Texas and Florida mandate whole-home smart system specifications for new construction, consolidating vendor selection around ecosystem providers. The EPA ENERGY STAR specification shapes product certification requirements and retail channel access. Silicon Valley clusters concentrate voice-native interface development for premium kitchen suites.
Germany
Utility-backed rebate programs in Bavaria and North Rhine-Westphalia accelerate smart HVAC adoption as heat pump electrification mandates pull systems into residential retrofit pipelines. The EU Ecodesign Directive tightens minimum efficiency thresholds for networked appliances. Stuttgart industrial corridors concentrate silicon carbide power module integration for compressor drives.
China
Direct-to-consumer platform control dominates connected laundry demand through localized manufacturing scale and app-based service scheduling. MIIT-administered GB standards impose firmware update obligations and data localization rules. Pearl River Delta manufacturing clusters anchor captive semiconductor foundry partnerships for power electronics.
Netherlands
National building codes mandate fossil fuel heating replacements, pulling smart HVAC systems into residential retrofit pipelines alongside Germany. The F-Gas Regulation phases down hydrofluorocarbon refrigerants with high global warming potential. Eindhoven technical universities anchor refrigerant redesign and sealed system architecture development.
India
Utility-backed appliance rebate programs are nascent but expanding in Maharashtra and Gujarat, creating first-mover positioning for connected HVAC and water heating platforms. Central Electricity Authority guidelines shape smart meter interoperability standards. Bangalore technology corridors concentrate sub-GHz mesh protocol development for whole-home ecosystems.
Connected Home Appliances Market Vendor Landscape
Global majors compete with regional champions across platform architecture and semiconductor supply security, producing a tiered structure where captive foundry partnerships separate premium positioning from merchant-market dependence. Korean and Chinese conglomerates anchor scale-driven segments through vertical integration into power electronics and direct-to-consumer channels. European specialists occupy premium tiers through proprietary AI integration and builder specification relationships. Dominant competitive moves include long-term wafer supply agreements and ecosystem certification partnerships with utility demand-response programs.
Within the scale-driven tier, Samsung Electronics and LG Electronics occupy positions defined by captive semiconductor foundry partnerships and proprietary AI platform integration. Haier Smart Home exemplifies the direct-to-consumer archetype through platform-controlled manufacturing scale in China. Robert Bosch GmbH anchors European premium positioning through builder specification relationships and thermal engineering capabilities.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Haier Smart Home |
| Robert Bosch GmbH |
| Whirlpool Corporation |
| Midea Group |
| Panasonic Corporation |
| BSH Hausgeräte GmbH |
| Xiaomi Corporation |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between ENERGY STAR-qualified smart HVAC systems and uncertified legacy appliances manifests in both pricing premiums and supply chain sourcing strategies, with utility rebate eligibility in Texas and Florida consolidating procurement around verified tier suppliers while merchant semiconductor markets serve price-sensitive retrofit segments.
Pricing Analysis
Silicon carbide wafer cost pass-through from Japanese and US substrate manufacturers compresses margins on premium heat pump inverters while sustaining three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on GB standards compliance tier for China market entry and captive foundry partnerships for supply security. Pricing pressure stems from EU Ecodesign Directive redesign costs for standby power circuits. Commercial facility managers show lowest price sensitivity due to lifecycle cost framing; residential retrofit buyers in Germany and the Netherlands exhibit highest sensitivity to upfront system costs despite mandate-driven replacement timelines.
Supply Chain Analysis
Silicon carbide substrate supply rests on Japanese specialty chemical producers and US wafer manufacturers, with power module assembly concentrating in China and South Korea. Raw material dependencies span high-purity silicon carbide crystals, rare-earth magnets for compressor motors, and copper winding stock for HVAC heat exchangers. Single-source vulnerability in 150mm wafer supply exposes appliance OEMs to allocation risk during heat pump electrification ramps. Distribution runs through builder specification channels in suburban North America and direct-to-consumer platforms in China, with retail appliance showrooms serving demonstration and service contract capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Ecodesign Directive efficiency thresholds and Germany's heat pump electrification mandates pull replacement demand forward regardless of consumer preference cycles.
For Market Incumbents: Anchor premium positioning through long-term silicon carbide wafer purchase agreements that lock substrate supply ahead of merchant-market allocation crunches. Defend against ecosystem consolidation by deepening builder specification relationships in Texas and Florida new construction pipelines. Prioritize thermal engineering capability acquisition to bridge mechanical appliance heritage with power electronics integration demands.
For New Entrants and Emerging Players: Sub-GHz mesh protocol stacks offer a technology-first wedge into utility demand-response program certification gaps where incumbent platforms lack Thread or Zigbee interoperability. Target India's nascent smart meter rebate corridors in Maharashtra and Gujarat before incumbent ecosystem lock-in solidifies. Pursue voice-native kitchen interface partnerships with Silicon Valley natural language processing developers to bypass established brand channels.
For Investors and Strategic Acquirers: Consolidation pressure builds where GB standards compliance costs fragment platform architectures and inflate testing budgets beyond mid-tier R&D capacity. Five-to-ten year viability favors suppliers with captive semiconductor foundry partnerships and direct-to-consumer platform control. Monitor F-Gas Regulation refrigerant phase-down timelines as inflection signal for sealed system engineering acquisition targets.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Silicon Carbide Supply Agreement | Locks wafer allocation ahead of Japanese and US manufacturer capacity constraints during heat pump ramp. |
| Utility Demand-Response Certification | Opens Zigbee and Thread ecosystem enrollment with Germany's E.ON and Netherlands' Enexis rebate programs. |
| Direct-to-Consumer Platform Launch | Captures recurring service revenue and predictive maintenance data through manufacturer-owned apps in China. |
| Voice-Native Kitchen Interface Development | Differentiates premium induction cooking suites through hands-free recipe execution and safety interlocks. |
| Thermal Engineering Capability Acquisition | Bridges mechanical appliance heritage with silicon carbide MOSFET integration for compressor drives. |
Methodological Framework
Multiple input streams — appliance OEM product planning interviews, utility program manager consultations, semiconductor supply chain assessments, and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Primary discussions engaged connected appliance platform architects, HVAC compressor engineering directors, utility demand-response program administrators, and smart home ecosystem certification specialists. Secondary validation drew from EPA ENERGY STAR specification documents, EU Ecodesign Directive implementing measures, MIIT GB standard drafts, and customs trade data for power electronics imports.
Data-stream reconciliation across the analysis window applied segment-specific growth drivers to derive value and volume trajectories. Segmentation dimensions modeled include product type tier, network protocol architecture, end-user procurement authority, and regional regulatory compliance cluster. CAGRs emerged from installer pipeline surveys and replacement cycle elasticity estimates. Forecast inputs incorporated heat pump electrification mandate enforcement timelines and silicon carbide module adoption curves in variable-speed compressor drives.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to F-Gas Regulation refrigerant phase-down schedules and China-US semiconductor export control evolution. Forecasts reflect documented assumptions regarding utility rebate program continuity and builder specification consolidation trends. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Home Appliance (Wet and Cold) Market
Home Appliances
Europe Laundry Appliances Market
Home Appliances
Japan Small Home Appliances Market
Home Appliances
Oman Small Home Appliances Market
Home Appliances
Europe Home Appliances Market
Home Appliances
United Kingdom Washing Machine Market
Home Appliances
Egypt Major Home Appliances Market
Home Appliances
France Household Appliances Market
Home Appliances
India Laundry Appliances Market
Home Appliances
US Household Appliances Market
Home Appliances
Egypt Small Home Appliances Market
Home Appliances
Oman Home Appliances Market
Home Appliances
UAE Major Home Appliances Market
Home Appliances
Household Induction Cooktops Market
Home Appliances
Merchandizing Refrigerators Market
Home Appliances
Italy Home Appliances Market