
 Digital Refrigeration Gauge Market | 2026-2036
Digital Refrigeration Gauge Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Refrigeration Gauge Market Insights
Refrigerant tracking software bundled with gauge hardware is restructuring how distributors monetize technician relationships. Testo SE & Co. KGaA leverages its European service network to anchor recurring calibration revenue. Fieldpiece Instruments dominates the North American contractor channel with specialized wireless gauge sets. Inficon Holding AG extends its industrial leak detection expertise into digital pressure instrumentation for plant maintenance crews.
A digital refrigeration gauge measures refrigerant pressure and temperature with electronic sensors, displaying readings on LCD or smartphone-linked interfaces with accuracy typically within 0.5% of full scale; it replaces mechanical dial gauges to enable data logging, superheat calculations, and compliance documentation for EPA Section 608 technician certification. Wireless gauges lead product type demand as Bluetooth-enabled models displace wired manifold sets in residential HVAC service calls. IoT-based technology segments capture expanding margin pools through cloud-connected refrigerant charge analytics and predictive maintenance alerts for commercial cold chain operators.
The EPA enforces refrigerant management standards under Section 608 of the Clean Air Act, requiring leak repair documentation that digital gauges with timestamped logs directly satisfy. The EU F-Gas Regulation mandates refrigerant phase-down tracking that drives gauge replacement across Germany, France, and Italy. Japan's METI enforces energy efficiency standards for commercial refrigeration that technicians verify using calibrated digital instrumentation. Stakeholders must monitor how refrigerant transition timelines reshape gauge sensor compatibility requirements and technician recertification demand.
Market Dynamics
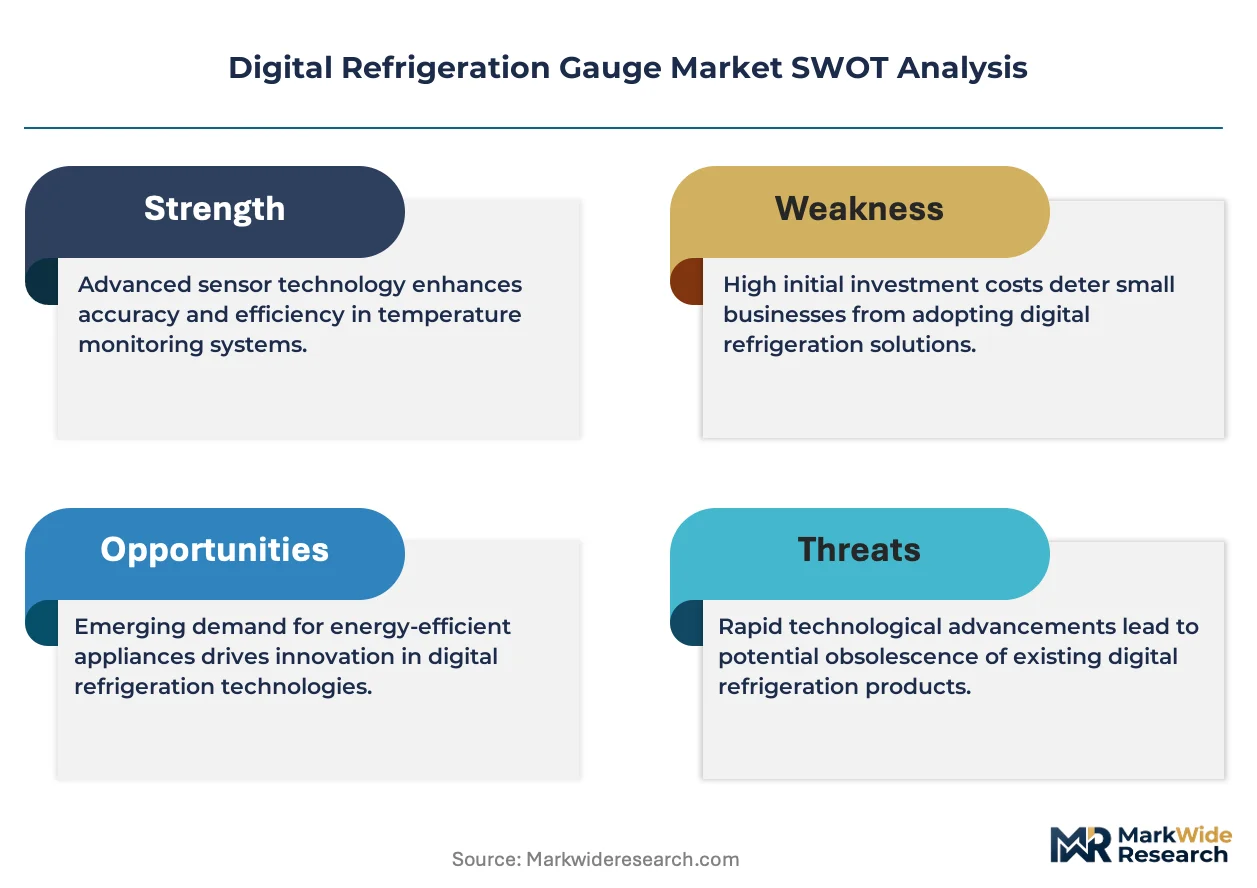
The EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act is forcing wholesale gauge replacement cycles as technicians require new sensor compatibility for low-GWP alternatives. This regulatory compression is restructuring distributor inventory strategies and accelerating hardware refresh timelines across contractor networks.
Growth Catalysts
- AIM Act Compliance Pressure:The EPA's refrigerant management mandates under Section 608 of the Clean Air Act require timestamped leak repair documentation that digital gauges with integrated data logging directly satisfy, compelling hardware upgrades across US HVAC service fleets.
- Commercial Cold Chain Expansion:Food retail and pharmaceutical logistics operators are deploying IoT-connected gauge systems to monitor refrigerant charge levels and trigger predictive maintenance alerts before system failures disrupt temperature-sensitive inventory.
- Wireless Protocol Maturation:Bluetooth-enabled manifold sets are displacing wired configurations in residential service calls, reducing setup time and enabling real-time superheat calculations through smartphone-linked interfaces.
Market Restraints
- Semiconductor Input Volatility:Pressure sensor MEMS and microcontroller availability constraints are extending lead times for gauge manufacturers, compressing margins on mid-tier product lines.
- Calibration Infrastructure Concentration:Accredited calibration services cluster in Germany, Japan, and the United States, creating logistical friction for technicians in secondary markets who must ship units internationally for certification maintenance.
- Mechanical Gauge Substitution Persistence:Cost-sensitive residential contractors in price-pressured markets continue deploying analog dial gauges for basic pressure verification, delaying digital adoption in the economy tier.
Strategic Opportunities
- Refrigerant Tracking Software Bundling:Distributors can anchor recurring revenue streams by packaging cloud-based refrigerant charge analytics with hardware sales, deepening technician relationship lock-in.
- EU F-Gas Regulation Tailwind:The European Union's mandated phase-down tracking requirements are accelerating gauge replacement across France, Italy, and Poland as technicians upgrade to compliant digital instrumentation.
- 5G and Edge Computing Convergence:Low-latency cellular connectivity combined with on-device processing enables real-time refrigerant diagnostics without Wi-Fi dependency, opening plant maintenance applications in remote industrial facilities.
Industry Challenges
- Section 608 Certification Bottlenecks:EPA technician recertification timelines lag behind refrigerant transition schedules, creating compliance gaps as contractors deploy gauges for alternative refrigerants they are not yet legally qualified to handle.
- Legacy System Integration Friction:Building management systems in commercial facilities use proprietary protocols that resist seamless data handoff from wireless gauge sets, requiring custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Refrigeration Gauge Market |
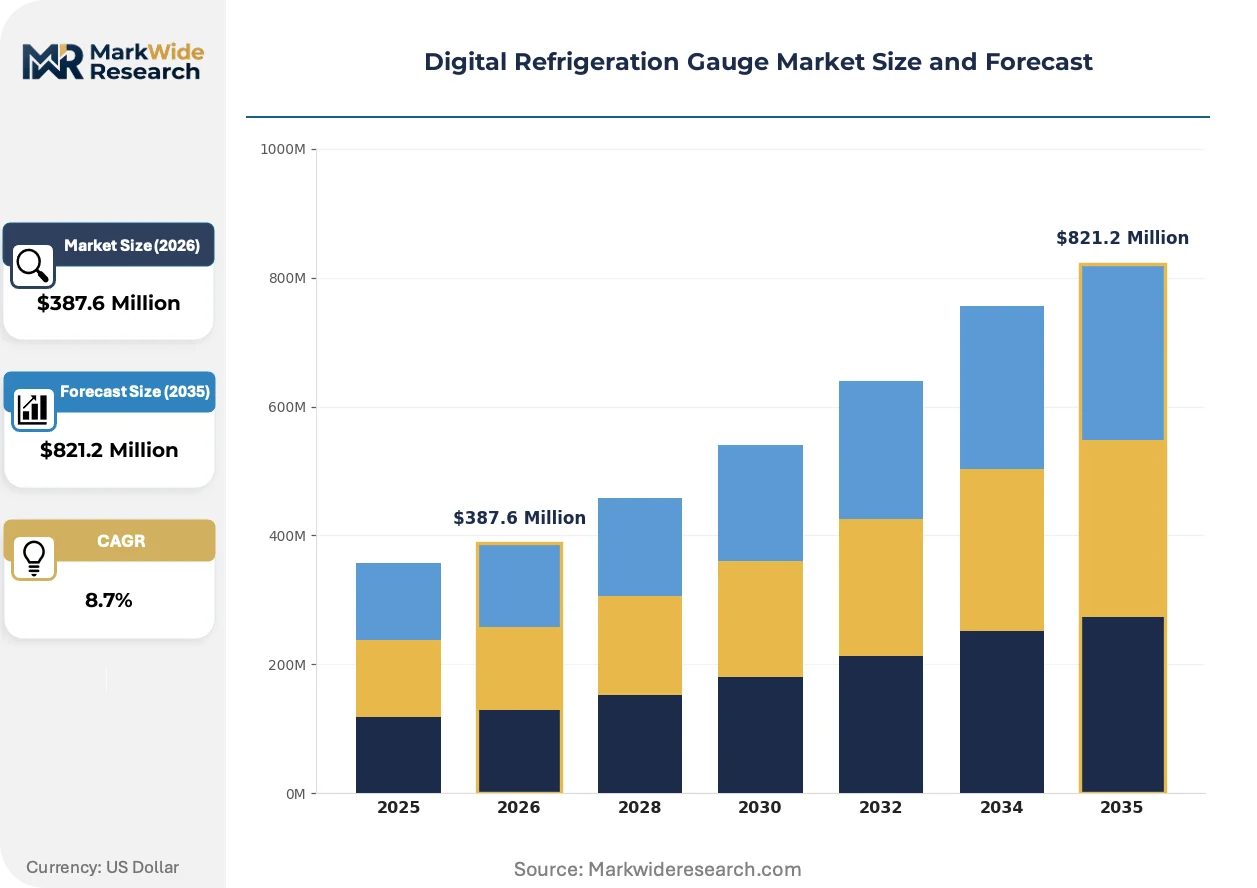
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Gauges, Digital Pressure Testers, Multi-Functional Gauges, Smart Gauges End User: HVAC Technicians, Food Retailers, Industrial Plants, Service Providers Technology: Bluetooth, Infrared, IoT-based, Analog-Digital Hybrid Application: Refrigeration Systems, Air Conditioning, Automotive, Cold Chain Logistics |
| Companies Covered | Testo SE & Co. KGaA, Inficon Holding AG, Yellow Jacket (Ritchie Engineering Company), Fieldpiece Instruments, Emerson Electric Co., Mastercool Inc., CPS Products Inc., JB Industries Inc., Appion Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Refrigeration Gauge Market Trends and Innovations
Refrigerant chemistry transitions and connectivity protocol maturation are compressing product lifecycles and redrawing competitive boundaries between hardware manufacturers and software platforms. The gauge is evolving from measurement tool to compliance node.
Cloud-native refrigerant charge analytics is decentralizing diagnostic expertise from centralized engineering departments to individual field technicians. Commercial refrigeration operators are adopting these systems fastest, with multi-site facility managers rolling out platform-agnostic gauge sets that feed unified dashboards. The technology is decentralizing decision authority, enabling on-site charge adjustments without remote engineering consultation and compressing response times for temperature excursions.
The EU F-Gas Regulation mandates granular refrigerant phase-down tracking that digital pressure instrumentation with embedded mass flow calculation satisfies. Industrial cold chain operators across Germany and France face audit exposure without timestamped, geotagged service records. Plant maintenance crews are responding by specifying gauges with tamper-evident data integrity features and automatic cloud backup.
Certification-driven procurement preferences are restructuring contractor purchasing patterns as EPA Section 608 and METI energy efficiency standards elevate gauge accuracy requirements. Distributor relationships are fragmentating as technicians prioritize vendors offering bundled recertification training and calibration services. Japan's commercial refrigeration sector exhibits this most acutely, where METI enforcement has made calibrated digital instrumentation non-negotiable for facility compliance verification.
Digital Refrigeration Gauge Market Segmentation
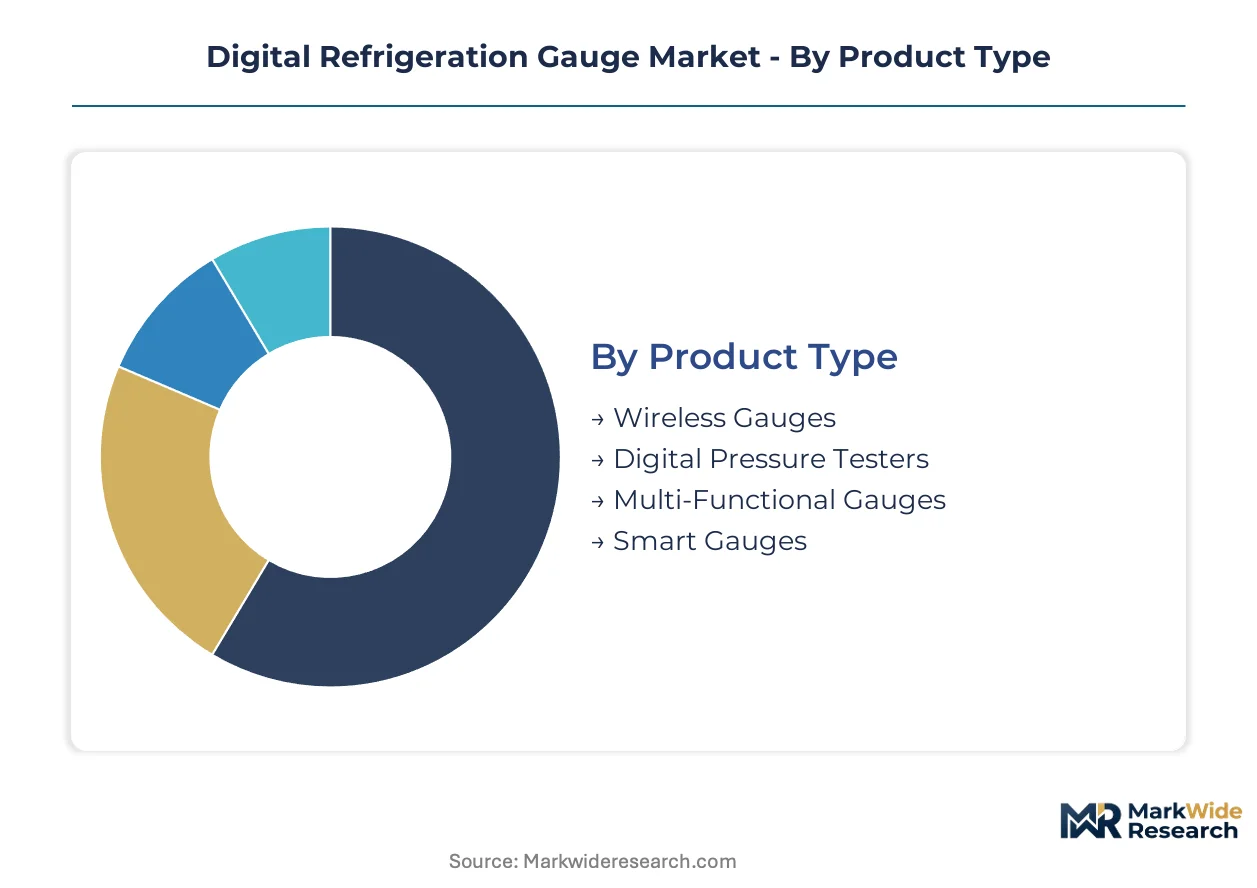
Refrigerant chemistry transitions and connectivity protocol maturation are compressing product lifecycles and redrawing competitive boundaries between hardware manufacturers and software platforms. The gauge is evolving from measurement tool to compliance node, with certification requirements varying sharply across technician, industrial, and commercial end-use profiles.
Product Type:
Certification-burden intensity varies by connectivity architecture and data-logging capability, with EPA Section 608 and EU F-Gas Regulation mandating timestamped documentation that only certain configurations satisfy.
- Wireless Gauges:Bluetooth-enabled manifold sets transmit pressure and temperature readings to smartphone interfaces, eliminating manual transcription errors. Demand concentrates among US HVAC service fleets upgrading to meet EPA leak repair documentation mandates. The AIM Act's hydrofluorocarbon phasedown is accelerating replacement cycles as technicians require sensor compatibility for low-GWP refrigerant alternatives.
- Smart Gauges:Cloud-connected units with embedded edge computing perform real-time superheat calculations and predictive diagnostics without Wi-Fi dependency. Cold chain logistics operators across Germany and Japan deploy these for multi-site facility monitoring, with automatic cloud backup satisfying EU F-Gas audit requirements. METI energy efficiency verification standards in Japan make calibrated digital instrumentation non-negotiable for commercial compliance.
- Digital Pressure Testers:Single-function units offer basic electronic pressure measurement for residential contractors.
- Multi-Functional Gauges:Integrated manifold sets combine vacuum measurement, pressure testing, and refrigerant charging in one housing.
Wireless Gauges sits at the top of the volume ranking, with Smart Gauges climbing the fastest.
End User:
Cost tier stratification separates premium-calibrated instrumentation for regulated facilities from economy-tier tools for residential contractors.
- HVAC Technicians:Individual contractors and service fleet employees constitute the largest addressable base, with procurement patterns fragmenting around bundled recertification training and calibration services. EPA Section 608 certification bottlenecks create compliance gaps as technicians deploy gauges for alternative refrigerants they are not yet legally qualified to handle.
- Food Retailers:Supermarket chains and cold storage operators specify tamper-evident data integrity features for refrigerant charge tracking. EU F-Gas Regulation enforcement across France and Italy drives gauge replacement as facilities face audit exposure without geotagged service records.
- Industrial Plants:Manufacturing facilities with captive refrigeration systems prioritize sensor durability in high-vibration environments.
- Service Providers:Third-party maintenance contractors balance equipment portability against documentation capabilities.
HVAC Technicians dominates absolute unit shipments, while Food Retailers expands most quickly on cold chain compliance investments.
Technology:
Application environment dictates protocol selection, with plant maintenance crews requiring connectivity resilience that residential technicians can sacrifice for cost.
- Bluetooth:Low-energy wireless protocol dominates residential service calls, reducing setup time and enabling smartphone-linked superheat calculations. North American contractor channel demand centers on this standard, with Fieldpiece Instruments and Testo SE anchoring product development around iOS and Android compatibility.
- IoT-based:Cellular and Wi-Fi connectivity enables cloud-native refrigerant charge analytics for commercial cold chain operators. Multi-site facility managers in Germany and Japan roll out platform-agnostic gauge sets feeding unified dashboards, decentralizing diagnostic expertise from centralized engineering departments.
- Infrared:Non-contact temperature sensing complements pressure measurement in specialized industrial applications.
- Analog-Digital Hybrid:Transitional designs persist in cost-sensitive markets delaying full digital adoption.
Bluetooth holds the installed base lead, with IoT-based systems gaining share fastest on commercial refrigeration investments.
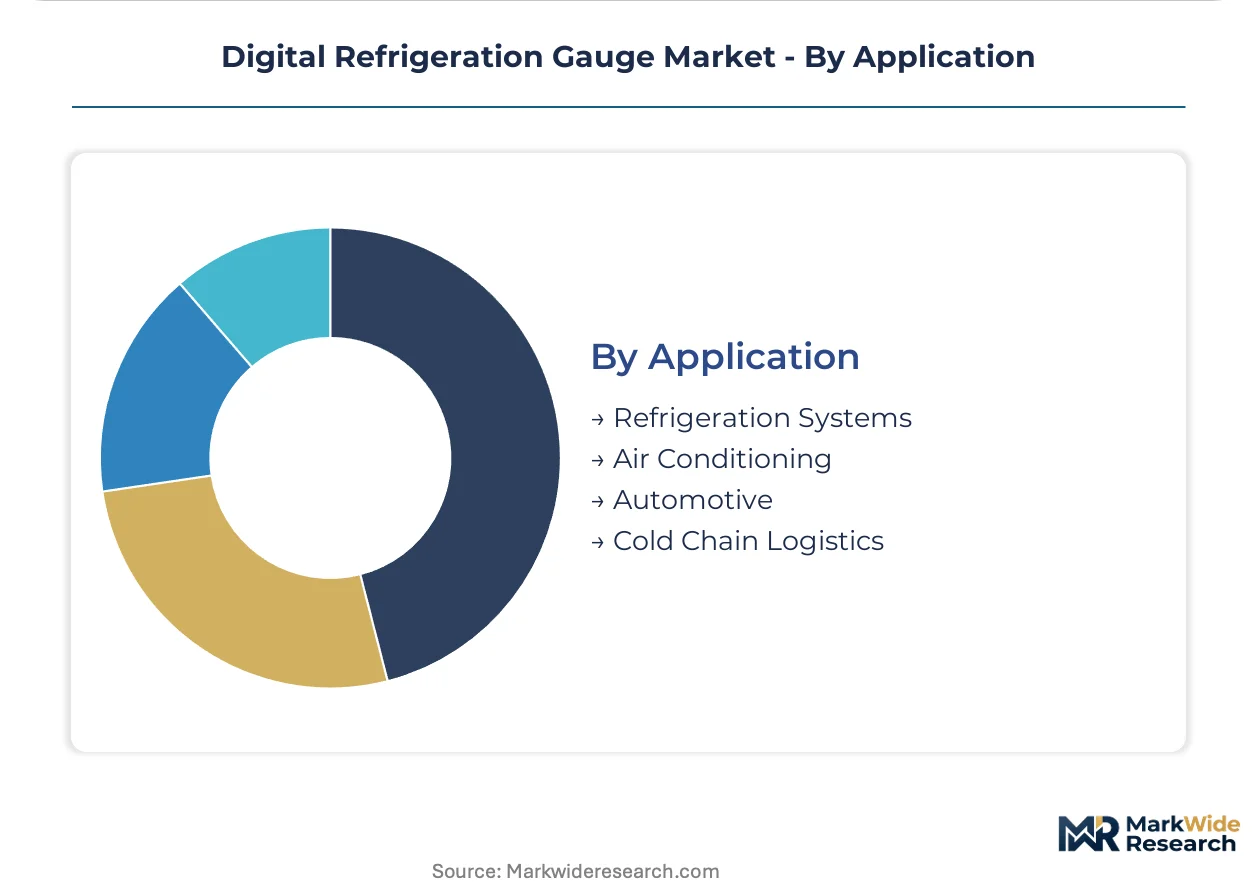
Application:
Margin concentration follows regulatory enforcement intensity, with cold chain and commercial refrigeration commanding premium pricing over residential air conditioning.
- Cold Chain Logistics:Pharmaceutical and food distribution networks deploy IoT-connected gauge systems to monitor refrigerant charge levels and trigger predictive maintenance alerts before temperature excursions disrupt inventory. EU F-Gas and Japan METI enforcement make calibrated instrumentation mandatory for facility compliance verification.
- Refrigeration Systems:Commercial and industrial stationary equipment requires sensor compatibility with evolving refrigerant chemistries. The EPA's AIM Act forces wholesale gauge replacement cycles as low-GWP alternatives displace legacy hydrofluorocarbons.
- Air Conditioning:Residential and light commercial cooling represents volume demand with compressed margins.
- Automotive:Mobile air conditioning service requires portable, battery-operated gauge sets with vehicle-specific refrigerant profiles.
Refrigeration Systems leads by unit volume, while Cold Chain Logistics shows the steepest expansion trajectory on compliance-driven procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan enforce the most stringent certification requirements for digital refrigeration gauges, while the United States drives replacement volume through regulatory phasedown mandates. Contractor procurement concentrates where EPA Section 608, EU F-Gas Regulation, and METI standards elevate accuracy requirements.
United States
HVAC service fleets across Texas and Florida are upgrading hardware to satisfy EPA leak repair documentation mandates. The AIM Act's hydrofluorocarbon phasedown under Section 608 of the Clean Air Act forces sensor compatibility refreshes for low-GWP refrigerant alternatives. Dallas-Fort Worth contractors face compressed replacement timelines as distributor inventory strategies adapt to accelerated refresh cycles.
Germany
Industrial cold chain operators in Bavaria and North Rhine-Westphalia specify tamper-evident data integrity features for refrigerant charge tracking. The EU F-Gas Regulation mandates granular phase-down tracking that digital pressure instrumentation with embedded mass flow calculation satisfies. Munich-based facility managers roll out platform-agnostic gauge sets feeding unified compliance dashboards.
Japan
Commercial refrigeration technicians in Tokyo and Osaka require calibrated digital instrumentation for METI energy efficiency verification. The Ministry of Economy, Trade and Industry enforces standards that make accurate pressure-temperature measurement non-negotiable for facility compliance. Kanto region distributors fragment relationships around bundled recertification training and calibration services.
France
Food retailers in Île-de-France and Auvergne-Rhône-Alpes deploy IoT-connected gauge systems for multi-site facility monitoring. EU F-Gas Regulation enforcement creates audit exposure without geotagged, timestamped service records. Lyon cold storage operators specify automatic cloud backup features to satisfy documentation requirements.
Italy
Service providers in Lombardy and Emilia-Romagna balance equipment portability against documentation capabilities for pharmaceutical logistics clients. The EU F-Gas Regulation drives gauge replacement as technicians upgrade to compliant digital instrumentation. Milan-area contractors prioritize vendors offering integrated refrigerant tracking software with hardware sales.
Digital Refrigeration Gauge Market Competitive Landscape
Top-tier vendors anchor premium-calibrated instrumentation for regulated facilities, while mid-tier specialists and economy-tier manufacturers serve price-pressured residential contractors. The vendor base stratifies across certification-grade accuracy requirements, with Bluetooth-enabled and IoT-connected architectures commanding distinct margin pools. Two archetypes dominate: European service-network operators leveraging calibration infrastructure, and North American channel specialists dominating contractor supply relationships. Competitive moves center on refrigerant tracking software bundling and wireless protocol maturation.
Within the premium-tier vector, Testo SE & Co. KGaA represents the European service-network archetype, anchoring recurring calibration revenue through its regional infrastructure presence. Fieldpiece Instruments and Yellow Jacket occupy positions within the North American contractor channel specialization, exemplifying distribution-centric models that prioritize wireless hardware compatibility with smartphone-linked interfaces. Inficon Holding AG sits within the industrial leak detection extension archetype, representing expertise migration from plant maintenance applications into digital pressure instrumentation. These three named entities illustrate how geographic origin and historical capability bases shape competitive positioning without prescribing specific strategic actions.
| Leading Market Players |
|---|
| Testo SE & Co. KGaA |
| Inficon Holding AG |
| Yellow Jacket (Ritchie Engineering Company) |
| Fieldpiece Instruments |
| Emerson Electric Co. |
| Mastercool Inc. |
| CPS Products Inc. |
| JB Industries Inc. |
| Appion Inc. |
| Others |
Pricing and Supply Chain Analysis
MEMS pressure sensor wafers from Taiwan and South Korea flow through three-tier pricing structures calibrated by certification grade, with EPA Section 608 compliance tiers commanding premiums that residential contractors in price-pressured markets bypass through analog gauge substitution.
Pricing Analysis
Capacity additions in China are reshaping price floors for microcontroller and display module inputs, compressing margins on mid-tier digital gauge lines. Pricing stratifies across premium-calibrated instrumentation for cold chain operators, standard wireless sets for commercial HVAC fleets, and economy-tier digital pressure testers for residential contractors. Price differentiation hinges on certification grade alignment with EPA Section 608 and EU F-Gas audit requirements, plus after-sales calibration bundling. Cost compression in the economy tier is intensifying because mechanical gauge substitution persists among cost-sensitive residential contractors in secondary US markets. Food retailers and pharmaceutical logistics operators exhibit the lowest price sensitivity, prioritizing tamper-evident data integrity and automatic cloud backup over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States anchor hub-and-spoke patterns that extend calibration service reach while creating logistical friction for technicians in secondary markets. Manufacturing concentrates in China for electronic assemblies, Germany for precision sensor calibration infrastructure, and the United States for contractor-channel final assembly. Raw material dependencies draw from Taiwanese MEMS foundries, South Korean display panel suppliers, and Japanese battery cell manufacturers. Single-source vulnerability in pressure sensor MEMS creates exposure when semiconductor allocation shifts toward automotive and consumer electronics. Distribution runs through HVAC wholesale distributors and direct-to-fleet service contracts, with refrigerant tracking software bundling deepening channel control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where the EPA's AIM Act hydrofluorocarbon phasedown creates forced replacement cycles that restructure procurement patterns across contractor networks.
For Market Incumbents: Anticipate sensor compatibility fragmentation as low-GWP refrigerant alternatives multiply, forcing R&D investment in modular sensor architectures that technicians can field-swap without full gauge replacement. Defensive consolidation moves center on acquiring calibration service networks in secondary markets to reduce technician shipping friction, plus backward integration into MEMS pressure sensor sourcing to buffer semiconductor allocation volatility. Channel control through refrigerant tracking software bundling anchors recurring revenue against hardware margin compression. For New Entrants and Emerging Players: Begin with IoT-connected gauge systems for cold chain logistics operators in France and Italy, where EU F-Gas enforcement creates audit exposure without compliant digital instrumentation. The most penetrable segment lies in mid-sized food retailers seeking unified multi-site dashboards without enterprise-tier pricing. A software-first go-to-market angle—lead with cloud-native refrigerant charge analytics and retrofit hardware compatibility—sidesteps incumbent channel lock-in. For Investors and Strategic Acquirers: Consolidation pressure builds where calibration infrastructure concentration creates acquisition targets with regional service network density. Long-term viability favors vendors integrating hardware, software, and compliance documentation into unified platforms that technicians cannot easily unbundle. Acquisition target archetypes include regional calibration service providers with EPA Section 608 training accreditation and IoT platform specialists with edge computing capabilities for predictive diagnostics. The signal to watch is refrigerant transition timeline acceleration that outpaces technician recertification capacity, creating compliance bottlenecks that favor bundled training-and-hardware vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Tracking Software Bundling | Cloud-native analytics deepen technician relationship lock-in beyond hardware transactions. |
| Calibration Service Network Expansion | Regional EPA-accredited facilities reduce technician shipping friction and accelerate replacement cycles. |
| Modular Sensor Architecture Development | Field-swappable pressure sensors accommodate rapid refrigerant chemistry transitions without full gauge replacement. |
| EU F-Gas Compliance Feature Integration | Tamper-evident data integrity and automatic cloud backup satisfy audit requirements across Germany and France. |
| 5G-Enabled Edge Computing Deployment | Low-latency cellular connectivity opens plant maintenance applications in remote industrial facilities without Wi-Fi dependency. |
Research Methodology
Multiple input streams — primary interviews with HVAC service fleet managers, refrigerant compliance officers, and distributor procurement leads; secondary validation through EPA Section 608 enforcement data, EU F-Gas Regulation implementation reports, and METI energy efficiency standard filings; plus customs and trade flow analysis for pressure sensor MEMS and microcontroller imports — were reconciled through bottom-up unit shipment modeling and top-down market sizing triangulation.
Data-stream reconciliation across connectivity protocol adoption curves, refrigerant transition timelines, and certification requirement enforcement intensity informed the analytical framework over the projection horizon. Segmentation dimensions modeled include product connectivity architecture, end-user compliance burden intensity, technology protocol selection, and application regulatory exposure tier. CAGRs were derived from replacement cycle compression analysis and cold chain capital expenditure patterns. Industry-specific forecast inputs incorporated AIM Act phasedown acceleration scenarios and EU F-Gas audit enforcement intensity variations.
Several conditions sit outside the modeled scope, including geopolitical disruption of Taiwan semiconductor foundry operations, abrupt refrigerant chemistry standard reversals, and technician certification backlog resolution timelines. Forecasts reflect documented assumptions around regulatory enforcement continuity and refrigerant transition schedule adherence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Measuring Instruments
TDS Meter Market
Measuring Instruments
Ultraviolet Data Logger Market
Measuring Instruments
Global Process Instrumentation Market
Measuring Instruments
Data Acquisition Market
Measuring Instruments
Global Data Acquisition (DAQ) System Market
Measuring Instruments
Base Station Analyzer Market
Measuring Instruments
Borescope Inspection Camera Market
Measuring Instruments
Global Laser Measuring Instrument Market
Measuring Instruments
North America Scientific Instruments Market
Measuring Instruments
Communication Test Equipment (CTE) Market
Measuring Instruments
3D Metrology Market
Measuring Instruments
India Hydrological and Meteorological Equipment Market
Measuring Instruments
Laser Distance Meter Market
Measuring Instruments
Handheld Wind Anemometer Market
Measuring Instruments
Global Dissolved Oxygen Meters and Controllers Market
Measuring Instruments
3D Laser Scanner Market