
 New York Data Center Market | 2026-2036
New York Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
New York Data Center Market Insights
New York's Climate Leadership and Community Protection Act is pivoting data center development toward carbon-neutral power sourcing, forcing operators to secure renewable energy contracts or face permitting delays. Equinix leverages its Manhattan and Secaucus campuses to sustain interconnection density for financial exchange proximity. Digital Realty anchors hyperscale deployments across northern New Jersey and the Hudson Valley with utility-scale clean power offtakes. CyrusOne competes on wholesale capacity with purpose-built designs for cloud service providers.
New York data centers constitute mission-critical facilities housing servers, storage systems, and networking equipment within controlled environments maintaining temperatures between 18°C and 27°C and uptime exceeding 99.999% through redundant power and cooling architectures; these installations process transactions, host applications, and distribute content for enterprises requiring low-latency access to northeastern U.S. population centers. Colocation deployments command premium pricing in Manhattan and adjacent sub-markets where real estate scarcity and fiber intersection create structural bottlenecks. Cloud service expansion within the region absorbs the fastest-growing capacity share as hyperscalers seek qualified power entitlements. Managed services and disaster recovery offerings concentrate margin pools among operators with certified operational excellence and financial-sector compliance depth.
New York State Department of Environmental Conservation regulations govern emissions thresholds for backup generators, while New York City Local Law 97 imposes carbon intensity caps on large buildings including data centers, effectively conditioning market access on demonstrated sustainability performance. The Federal Energy Regulatory Commission oversees interstate transmission access that determines power cost and availability for Hudson Valley expansion sites. Stakeholders must monitor interconnection queue positions and substation upgrade timelines as these infrastructure constraints increasingly gate deployment velocity regardless of customer demand strength.
Market Dynamics
Artificial intelligence workloads are compressing power density requirements across New York's data center footprint, forcing operators to reengineer cooling architectures and secure megawatt-scale renewable entitlements ahead of interconnection queue bottlenecks.
Growth Catalysts
- Climate Leadership and Community Protection Act:New York State's carbon-neutral mandate is concentrating development in Hudson Valley sub-markets where hydroelectric and offshore wind resources qualify facilities for expedited permitting.
- Financial exchange proximity requirements:High-frequency trading firms maintain colocation demand within single-digit millisecond latency of Manhattan financial districts, sustaining premium pricing power for edge-adjacent facilities.
- Liquid cooling adoption:Direct-to-chip thermal management is enabling 50kW-plus rack densities required for GPU clusters, retrofitting legacy raised-floor environments without full reconstruction.
Market Restraints
- Interconnection queue congestion:Substations serving northern New Jersey and Hudson Valley expansion zones carry 18-24 month upgrade timelines, gating deployment velocity independent of customer commitments.
- Real estate scarcity:Manhattan and adjacent sub-markets face structural land constraints with industrial zoned parcels commanding 3-5x premiums over national secondary markets.
- Backup generator emissions thresholds:New York State Department of Environmental Conservation regulations limit diesel runtime and mandate particulate filtration, adding $2-4 million per facility in compliance capital.
Strategic Opportunities
- Long Island offshore wind integration:South Fork and Sunrise Wind cable landings create qualified power nodes for carbon-neutral hyperscale campuses with direct submarine cable connectivity to European markets.
- Disaster recovery site consolidation:Enterprise financial services buyers are converging secondary and tertiary facilities into single Hudson Valley locations with diverse fiber paths and seismic stability.
- Utility-scale battery co-location:Lithium-ion storage paired with solar offtakes is shifting peak demand charges and qualifying facilities for grid services revenue streams under FERC Order 841 implementations.
Industry Challenges
- Critical facilities engineering talent scarcity:Specialized expertise in medium-voltage electrical distribution and precision cooling design commands 40-60% wage premiums over standard commercial construction markets.
- Legacy building retrofit complexity:Pre-2010 facilities require structural reinforcement, fire suppression replacement, and fiber duct reconfiguration to support liquid cooling infrastructure and modern fiber counts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New York Data Center Market |
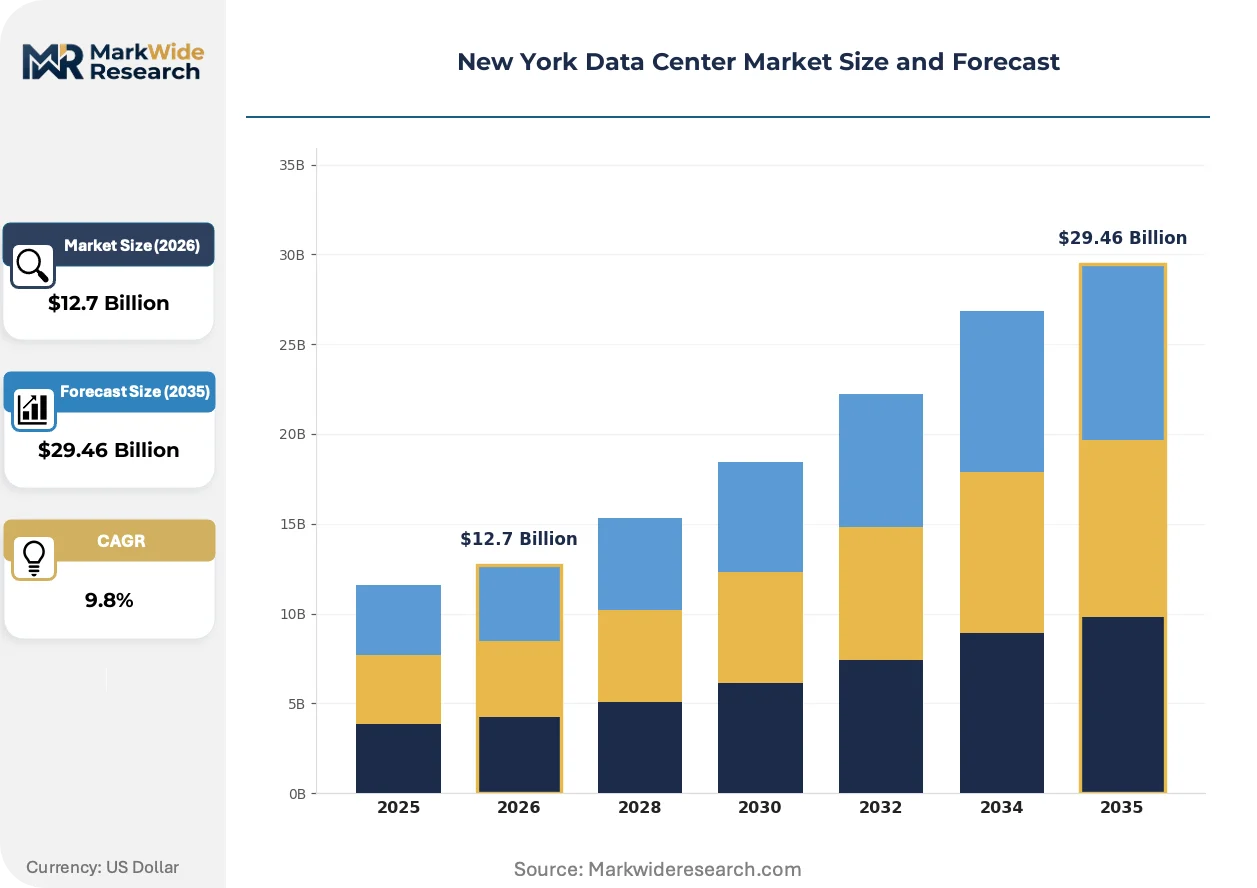
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $29.46 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Type: On-Premise, Colocation, Managed Services, Cloud End User: BFSI, IT & Telecom, Healthcare, Government Service Type: Disaster Recovery, Backup Solutions, Network Security, Load Balancing Infrastructure: Cooling Systems, Power Supply, Networking Equipment, Servers |
| Companies Covered | CoreSite, Telehouse, Equinix, STACK Infrastructure, NTT Global Data Centers, Digital Realty, DataBank, 365 Data Centers, CyrusOne, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New York Data Center Market Trends and Innovations
Computational density requirements from generative AI training clusters are forcing rapid infrastructure reinvention across power, cooling, and network architectures. Established design paradigms face obsolescence within single depreciation cycles.
Immersion cooling systems are integrating fluorocarbon-based dielectric fluids to manage thermal loads exceeding 100kW per rack. Cloud service providers are piloting two-phase immersion at pilot scales in Secaucus and Albany facilities. This thermal approach is integrating with existing chilled water infrastructure through hybrid heat rejection loops, preserving capital in partially depreciated mechanical plants.
New York City Local Law 97 imposes carbon intensity caps on large buildings including data centers, with penalties scaling to $268 per ton of CO2 equivalent excess emissions. Facility operators are responding with hourly-matched renewable energy certificates and building electrification roadmaps. Financial services tenants with net-zero commitments are prioritizing compliant buildings, creating occupancy premiums for early movers.
Enterprise procurement of data center capacity is consolidating from multi-vendor分散 strategies toward single-operator partnerships with guaranteed expansion rights. Buyers are trading price competition for supply security and streamlined compliance auditing. This pattern concentrates most visibly among Manhattan-headquartered asset managers and insurance carriers with multi-hundred-kilowatt steady-state requirements.
New York Data Center Market Segmentation
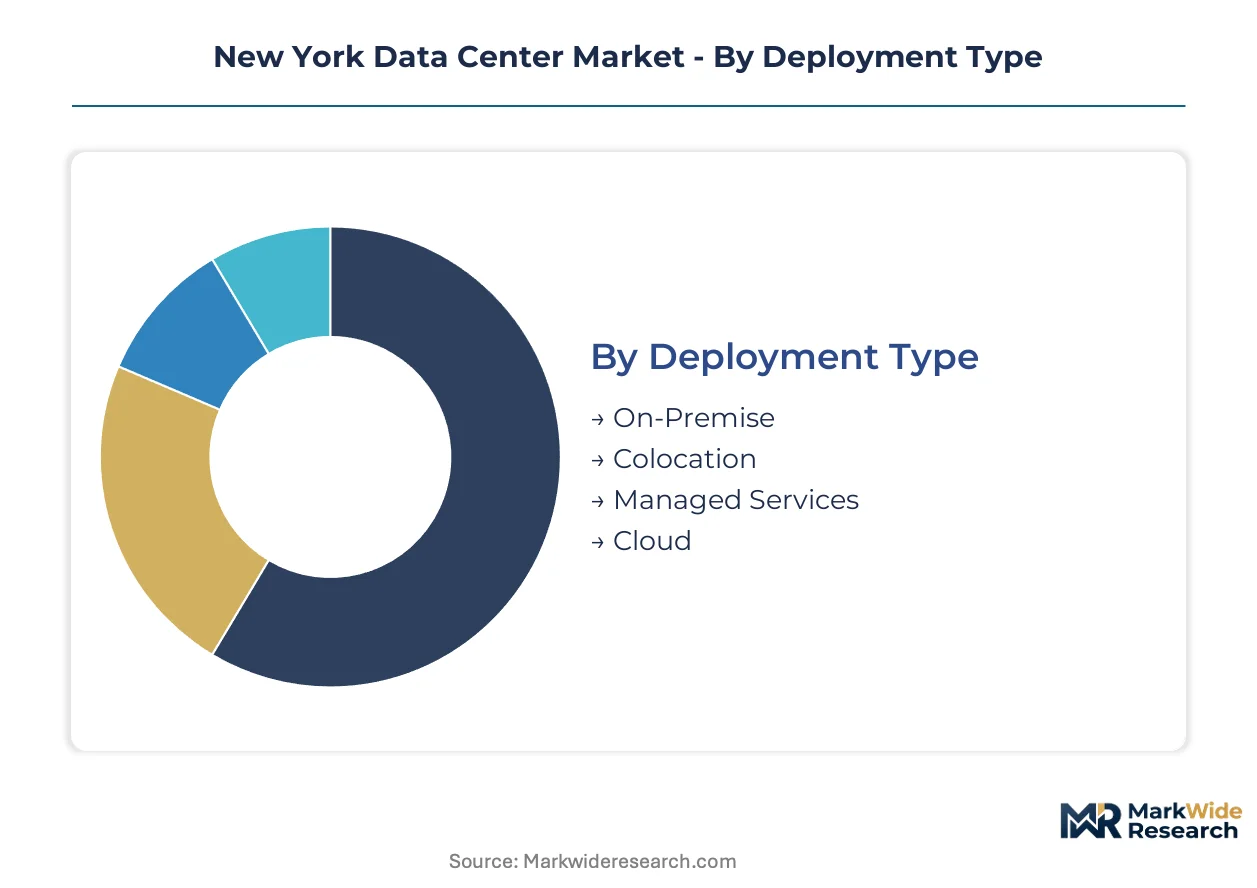
Deployment configurations in New York's data center market concentrate capacity along distinct operational models, each carrying differentiated capital intensity and regulatory exposure. Understanding these segment boundaries clarifies where power entitlements, interconnection density, and compliance architectures create sustainable competitive positions.
Deployment Type:
Supply concentration across deployment models reflects divergent real estate access and power contracting capabilities, with Manhattan proximity commanding structural premiums regardless of technical specification.
- On-Premise:Enterprise-owned facilities integrate directly with trading floors and core banking infrastructure, requiring dedicated substations and N+2 redundancy. Financial institutions in Lower Manhattan and Midtown maintain captive footprints to satisfy sub-millisecond latency requirements for exchange co-location.
- Colocation:Multi-tenant environments leverage shared mechanical and electrical infrastructure across wholesale and retail configurations. Hudson Valley and Secaucus campuses absorb hyperscale demand from cloud service providers seeking qualified renewable power entitlements under New York State climate mandates.
- Managed Services:Operators assume operational responsibility for customer hardware, bundling remote hands, network management, and compliance auditing. Healthcare and mid-market financial firms in Long Island sub-markets outsource facility management to capture operational expertise without capital deployment.
- Cloud:Hyperscale provider regions deliver virtualized compute and storage through availability zones spanning northern New Jersey and Albany corridors. AI training workloads are compressing deployment timelines as GPU clusters require immediate megawatt-scale power access.
Colocation absorbs the bulk of installed capacity; cloud deployment is expanding most quickly.
End User:
Customer concentration patterns trace regulatory complexity and transaction velocity requirements, with compliance depth separating premium-occupancy facilities from commodity alternatives.
- BFSI:Banking, financial services, and insurance institutions dominate Manhattan-adjacent capacity, mandating SSAE-18 attestation and financial-sector operational resilience. High-frequency trading firms sustain premium pricing for single-digit millisecond proximity to equity exchanges.
- IT & Telecom:Technology and telecommunications carriers require dense fiber intersection and cross-connect capabilities for peering and content distribution. Network-neutral facilities in Secaucus and Carteret anchor interconnection ecosystems serving regional internet traffic exchange.
- Healthcare:Hospital systems and health insurers process protected health information under HIPAA security rule mandates, requiring business associate agreements and encrypted data transmission. Disaster recovery site selection prioritizes seismic stability and diverse network paths over raw power cost.
- Government:State and municipal agencies procure through centralized contracts with FedRAMP or StateRAMP authorization requirements. Albany-area facilities capture executive branch data consolidation initiatives under New York State digital transformation programs.
BFSI commands the highest per-kilowatt pricing; healthcare is climbing the fastest as HIPAA-compliant cloud migration accelerates.
Service Type:
Service layering determines margin structure, with operational complexity and recovery time objectives creating tiered value capture across the customer base.
- Disaster Recovery:Secondary site provisioning with automated failover orchestration maintains business continuity for regulated enterprises. Financial services buyers consolidate tertiary facilities into single Hudson Valley locations with diverse fiber paths and grid isolation.
- Backup Solutions:Data protection services spanning snapshot replication, tape vaulting, and immutable object storage address ransomware recovery requirements. Healthcare providers in New York City metropolitan area mandate air-gapped backup architectures under updated cybersecurity directives.
- Network Security:Distributed denial-of-service mitigation, web application firewalls, and zero-trust network access integration protect edge-facing infrastructure. Managed security service providers co-locate scrubbing centers within Equinix and Digital Realty campuses for latency-sensitive protection.
- Load Balancing:Traffic distribution across server pools optimizes application performance and fault tolerance for e-commerce and SaaS platforms. Cloud-native load balancing services integrate with on-premise colocation through hybrid cloud orchestration layers.
Disaster recovery absorbs the bulk of contracted service revenue; network security is gaining share fastest as threat surface expansion outpaces in-house security operations center capacity.
Infrastructure:
Component-level supply concentration reflects manufacturing geography and import dependency, with lead times and tariff exposure conditioning deployment velocity.
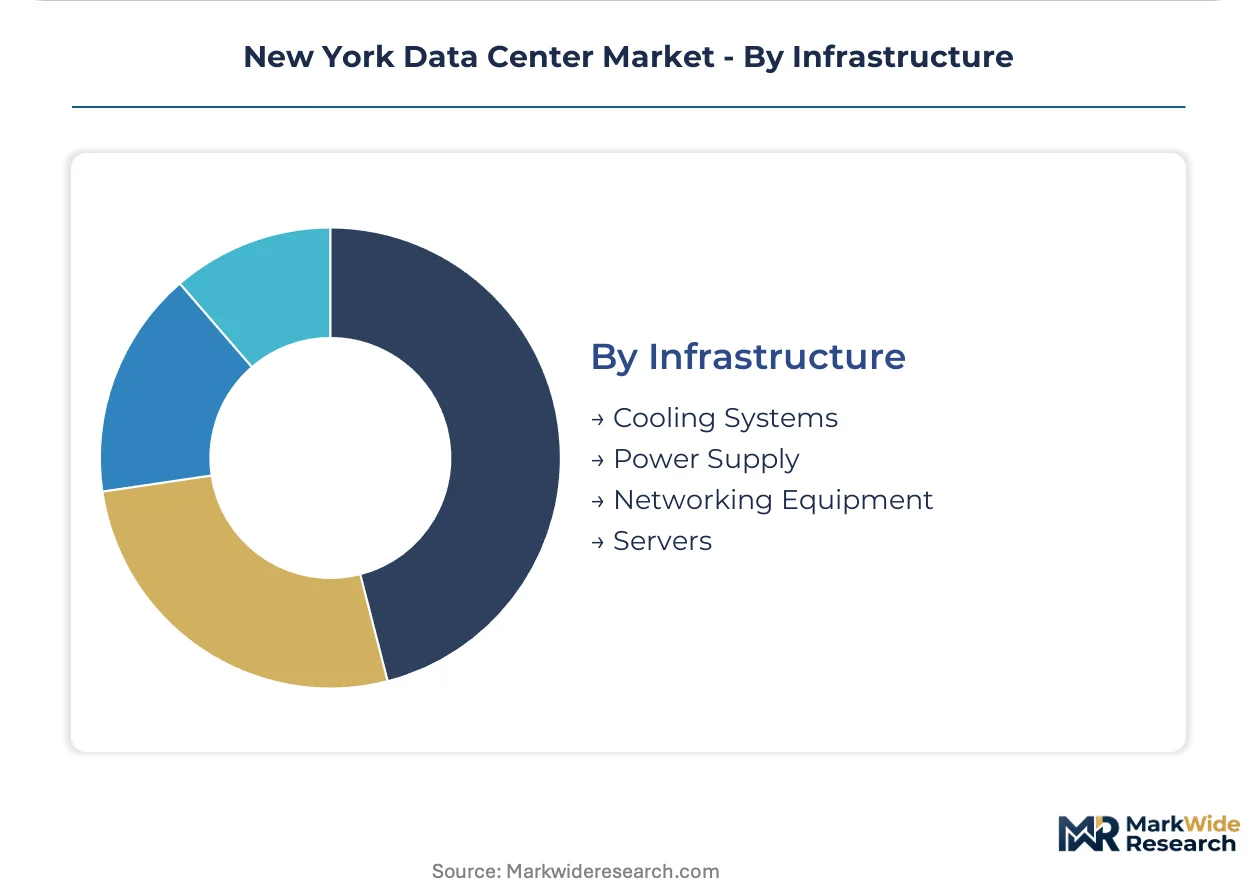
- Cooling Systems:Precision air handling units, chilled water plants, and emerging liquid cooling manifolds maintain thermal envelopes between 18°C and 27°C. Direct-to-chip and immersion cooling pilots in Secaucus and Albany facilities target 100kW-plus rack densities for AI training clusters.
- Power Supply:Uninterruptible power systems, switchgear, and backup generators deliver 99.999% uptime through N+1 or 2N redundancy architectures. New York State Department of Environmental Conservation emissions thresholds add $2-4 million per facility in particulate filtration and diesel runtime limitations.
- Networking Equipment:Routers, switches, and optical transport platforms enable interconnection density and cross-connect velocity for financial exchange proximity. Open networking disaggregation is displacing proprietary hardware in hyperscale deployments across Hudson Valley campuses.
- Servers:Compute nodes, GPU accelerators, and storage arrays constitute the revenue-generating payload housed within facility enclosures. AI-optimized server configurations with NVIDIA H100 and AMD MI300X accelerators are reshaping power density planning across the regional footprint.
Power supply infrastructure absorbs the bulk of capital expenditure; liquid cooling systems are on the steepest expansion trajectory as thermal design power thresholds exceed air-cooled practical limits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manhattan anchors the New York data center demand gravity, with financial exchange proximity sustaining premium colocation pricing across the metropolitan footprint. Sub-regional expansion concentrates in Hudson Valley and Long Island corridors where renewable power entitlements align with state climate mandates.
Manhattan and Hudson Yards
High-frequency trading firms mandate sub-millisecond latency to equity exchanges, sustaining premium pricing for facilities within single-digit miles of financial districts. New York City Local Law 97 imposes carbon intensity caps with penalties scaling to $268 per ton of CO2 equivalent excess emissions. Hudson Yards and Lower Manhattan campuses absorb enterprise financial services demand requiring SSAE-18 attestation and dedicated substations.
Northern New Jersey
Secaucus and Carteret sub-markets leverage dense fiber intersection for network-neutral interconnection ecosystems serving regional internet traffic exchange. Federal Energy Regulatory Commission oversight of interstate transmission access determines power cost and availability for expansion sites. Hyperscale cloud deployments concentrate along utility corridors with qualified renewable power entitlements.
Hudson Valley
Enterprise financial services buyers consolidate disaster recovery facilities into single locations with diverse fiber paths and seismic stability advantages. New York State Climate Leadership and Community Protection Act concentrates development where hydroelectric resources qualify facilities for expedited permitting. Albany-area campuses capture state executive branch data consolidation initiatives under digital transformation programs.
Long Island
South Fork and Sunrise Wind cable landings create qualified power nodes for carbon-neutral hyperscale campuses with direct submarine cable connectivity to European markets. New York State Department of Environmental Conservation regulations govern emissions thresholds for backup generators, adding compliance capital requirements. Healthcare providers mandate air-gapped backup architectures under updated cybersecurity directives.
New York Data Center Market Competitive Landscape
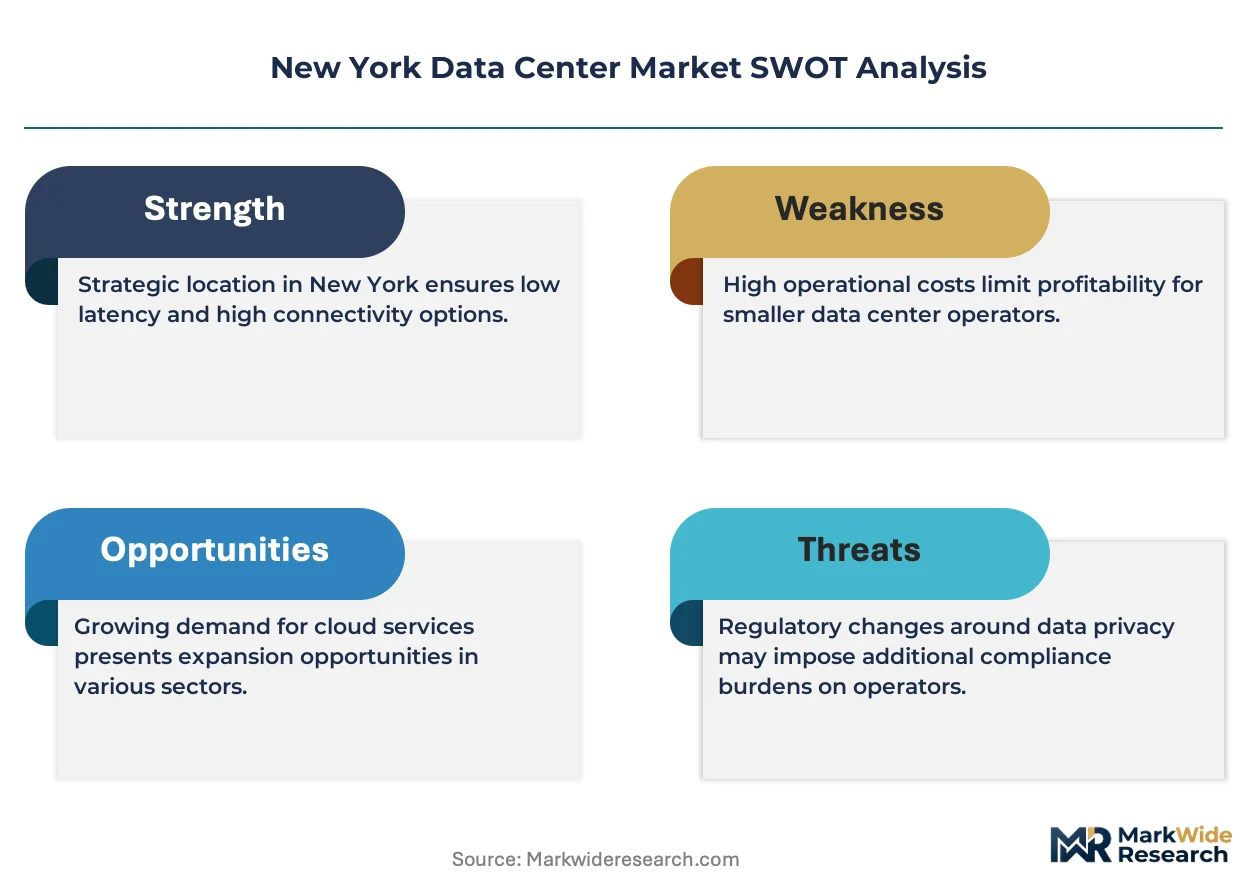
Premium-margin players sit above commodity-margin players across interconnection density and compliance certification depth. The market structures around three tiers: hyperscale campus operators with utility-scale power contracting, network-neutral interconnection specialists with financial exchange proximity, and wholesale capacity providers with purpose-built cloud-optimized designs. Dominant competitive moves include securing renewable energy entitlements ahead of interconnection queue bottlenecks and consolidating operational footprints to streamline compliance auditing.
Among network-neutral interconnection specialists, Equinix occupies a position exemplifying Manhattan and Secaucus campus density for financial exchange proximity. Digital Realty represents the hyperscale campus archetype across northern New Jersey and Hudson Valley deployments with utility-scale clean power offtakes. CyrusOne sits within the wholesale capacity tier, anchoring purpose-built designs for cloud service provider demand.
| Leading Market Players |
|---|
| CoreSite |
| Telehouse |
| Equinix |
| STACK Infrastructure |
| NTT Global Data Centers |
| Digital Realty |
| DataBank |
| 365 Data Centers |
| CyrusOne |
| Others |
Pricing and Supply Chain Analysis
Captive power contracting with utility-scale renewable developers anchors both supply security and pricing power for New York data center operators, creating a structural moat against competitors lacking interconnection queue positions. This vertical integration into qualified clean energy entitlements under the Climate Leadership and Community Protection Act simultaneously locks in carbon-neutral compliance and insulates against volatile wholesale electricity rates.
Pricing Analysis
Uptime guarantees above 99.999% anchor value-based pricing tiers across the New York metropolitan footprint. Three-tier pricing structure across premium Manhattan edge facilities, standard Hudson Valley campuses, and economy northern New Jersey wholesale deployments reflects latency differentials and compliance certification depth. Cost compression in standard-tier colocation intensifies as hyperscale cloud providers negotiate volume-scale offtakes with guaranteed expansion rights. Healthcare and mid-market financial firms exhibit highest price sensitivity, while high-frequency trading operations absorb premium Manhattan rates without elasticity.
Supply Chain Analysis
Domestic-content mandates under New York State procurement guidelines reshape sourcing toward North American-manufactured electrical infrastructure and locally fabricated steel enclosures. Supply concentration centers on the United States for precision cooling systems and medium-voltage switchgear, with Taiwan and South Korea anchoring server and networking equipment production. Lithium-ion battery modules, diesel generator sets, and fluorocarbon-based dielectric fluids constitute critical input dependencies. Single-source vulnerability in GPU accelerator supply from NVIDIA and AMD creates deployment bottlenecks for AI training clusters. Distribution runs through direct OEM relationships with bypass of traditional distribution channels for megawatt-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
New York data center economics function as a cost-of-compliance story where New York City Local Law 97 carbon intensity penalties create a barrier-to-entry moat for operators with certified sustainability performance and hourly-matched renewable energy certificates.
For Market Incumbents: Hedge against interconnection queue congestion by securing substation upgrade commitments with Consolidated Edison and NYPA before competitor filings. Defensive consolidation moves include acquiring Hudson Valley land positions with diverse fiber path access and retrofitting legacy facilities with liquid cooling manifolds to capture GPU cluster demand. The emerging threat of hyperscale cloud providers building captive campuses demands accelerated renewable power contracting to maintain tenant retention.
For New Entrants and Emerging Players: Begin with Long Island offshore wind integration nodes where South Fork and Sunrise Wind cable landings create qualified power positions with submarine connectivity to European markets. The most penetrable white-space target sits in healthcare-compliant disaster recovery facilities serving New York City metropolitan hospital systems. A go-to-market angle emphasizing air-gapped backup architectures and HIPAA business associate agreements differentiates against commodity colocation providers.
For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscale campus operators with utility-scale clean power offtakes and established interconnection density. Long-term viability over the coming decade hinges on renewable energy contracting depth and liquid cooling infrastructure readiness for AI workload migration. The acquisition target archetype combines Hudson Valley or Long Island land positions with active permitting progress under the Climate Leadership and Community Protection Act. Monitor interconnection queue position advancement at NYISO as the critical inflection signal for deployment velocity acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Power Purchase Agreement | Secures carbon-neutral compliance under New York State climate mandates and locks in electricity cost predictability. |
| Liquid Cooling Infrastructure Deployment | Enables 100kW-plus rack densities for NVIDIA H100 GPU clusters without full facility reconstruction. |
| Submarine Cable Landing Proximity | Positions Long Island campuses for direct European connectivity and transatlantic latency arbitrage. |
| SSAE-18 Compliance Certification | Unlocks financial services tenant premiums requiring attested operational resilience for trading infrastructure. |
| Utility-Scale Battery Co-location | Captures grid services revenue under FERC Order 841 while shifting peak demand charge exposure. |
Research Methodology
Independent corroboration across data center development executives, utility interconnection planners, and financial services infrastructure directors underwrites the qualitative findings in this study. Primary interviews with facility operators, renewable energy developers, and enterprise procurement officers combined with secondary validation from FERC interconnection queue filings, NYISO planning documents, and New York State Department of Environmental Conservation permit records. Bottom-up capacity tracking across Manhattan, Hudson Valley, and Long Island sub-markets triangulates against top-down utility load growth projections.
Comparable-period anchoring to historical deployment velocity across the analysis window calibrated the projection framework. Segmentation dimensions modeled include deployment type, end-user vertical, service tier, and infrastructure component category. CAGRs were derived from installed base growth rates adjusted for interconnection constraint timelines and climate mandate compliance trajectories. AI workload power density assumptions and renewable energy certificate pricing volatility constitute key forecast inputs.
Underlying measurement precision varies by segment; Manhattan colocation capacity carries tighter precision than emerging Long Island offshore wind nodes due to disclosure granularity differences. Forecasts reflect assumptions regarding interconnection queue advancement and Local Law 97 enforcement stringency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Global Data Center Accelerator Market
Data Center Infrastructure
Vietnam Data Center Market
Data Center Infrastructure
India Data Center Server Market
Data Center Infrastructure
Switzerland Data Center Rack Market
Data Center Infrastructure
Spain Data Center Power Market
Data Center Infrastructure
Asia-Pacific Virtual Desktop Infrastructure Market
Data Center Infrastructure
Global Terminal Management System Market
Data Center Infrastructure
Norway Data Center Construction Market
Data Center Infrastructure
Australia Data Center Rack Market
Data Center Infrastructure
Delhi-NCR Data Center Market
Data Center Infrastructure
Middle East and Africa Data Center Infrastructure Management Market
Data Center Infrastructure
Data Center Generator Market
Data Center Infrastructure
Middle East Data Center Physical Security Market
Data Center Infrastructure
North America Hosting Infrastructure Services Market
Data Center Infrastructure
Low-Cost Energy Data Center Market
Data Center Infrastructure
Converged Data Center Infrastructure Market