
 Smart Storage Cabinet Market | 2026-2036
Smart Storage Cabinet Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Storage Cabinet Market Insights
REACH compliance is realigning the cost-of-entry calculus for European smart cabinet manufacturers by restricting hazardous substances in electronic locking mechanisms and sensor assemblies. Quadient leverages its parcel locker expertise to anchor automated pickup solutions across retail and logistics networks. Florence Corporation sustains municipal and postal dominance through specialized outdoor cabinet engineering. KEBA differentiates via industrial-grade IoT controllers that extend into manufacturing floor deployments.
A smart storage cabinet integrates electromechanical locking, environmental sensors, and network connectivity into enclosed furniture designed for controlled access and real-time inventory visibility. These systems typically incorporate steel or aluminum enclosures with IP-rated sealing, operating on 12-24V DC power with Ethernet or cellular backhaul for centralized monitoring. Lockable cabinets and modular units together occupy the core revenue pool, while mobile storage segments are gaining traction in flexible manufacturing environments where RFID and biometric access technologies reduce unauthorized retrieval incidents. IoT connectivity and cloud management platforms now concentrate margin pools through recurring software licensing rather than one-time hardware sales.
The FDA enforces pharmaceutical custody chain requirements that drive healthcare facilities toward biometric-access cabinets with audit logging. EMA guidelines across Europe reinforce similar standards for narcotics storage, while China's NMPA aligns hospital procurement with smart device certification under GB standards. Procurement officers and system integrators must weigh total cost of ownership against interoperability commitments as connectivity protocols fragment between proprietary cloud ecosystems and open IoT frameworks.
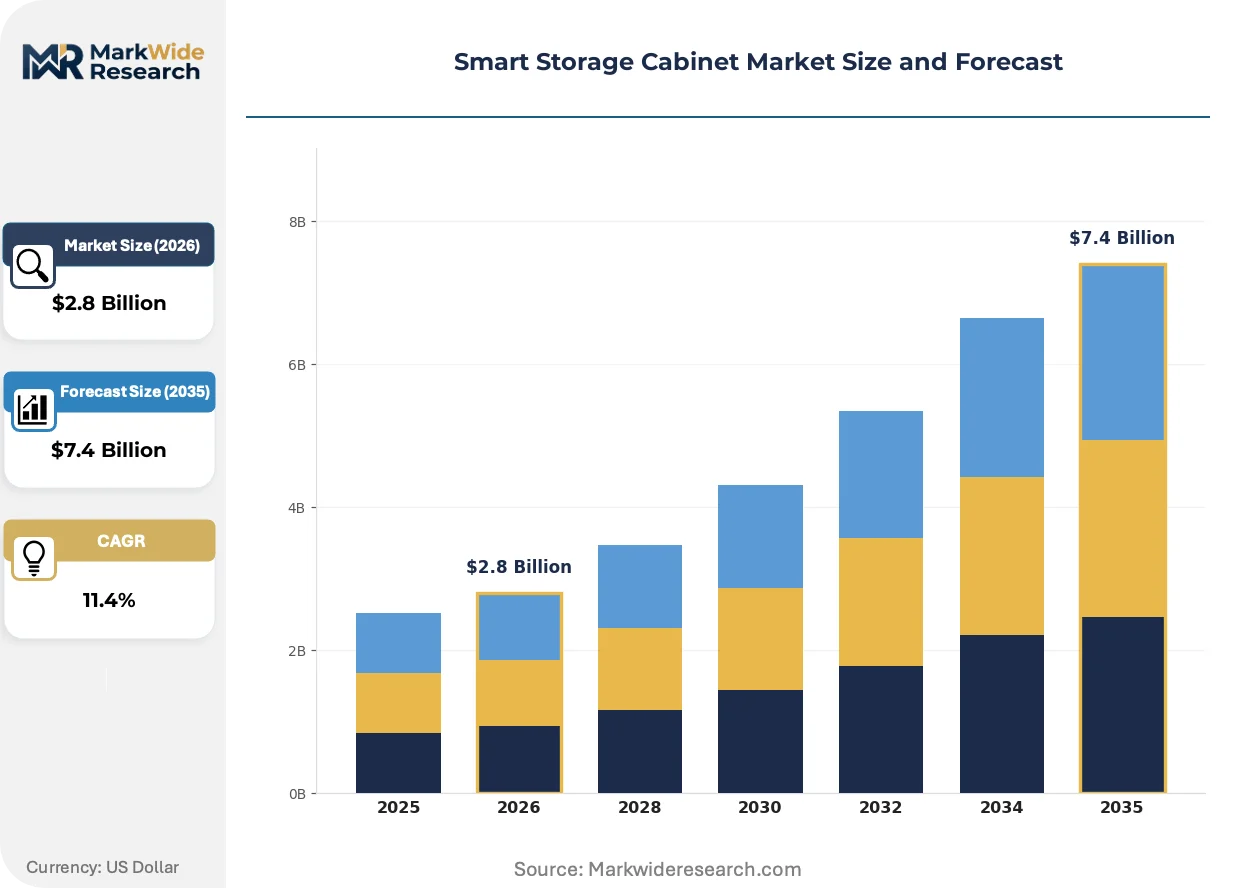
Market Dynamics
Healthcare facilities in the United States are accelerating RFID-enabled cabinet deployment to satisfy FDA track-and-trace mandates for controlled substances, compressing procurement cycles and reshaping vendor selection criteria toward compliance-verified platforms.
Growth Catalysts
- FDA pharmaceutical custody requirements:United States hospitals must maintain auditable chain-of-custody records for narcotics, driving biometric-access cabinet installations with tamper-evident logging systems.
- Germany's Ecodesign Directive:Electronic lock manufacturers face mandatory standby power limits below 0.5 watts, accelerating semiconductor redesign toward ultra-low-consumption microcontrollers.
- China's hospital infrastructure modernization:National smart healthcare mandates under NMPA certification frameworks are channeling procurement budgets toward GB-standard-compliant connected storage systems.
Market Restraints
- Steel and aluminum input volatility:IP-rated enclosure fabrication depends on commodity metal pricing that fluctuates with energy costs and trade tariff adjustments.
- Semiconductor supply concentration:Industrial-grade IoT controllers rely on foundry capacity concentrated in East Asian manufacturing clusters, creating lead-time vulnerability.
- REACH substance restrictions:ECHA limitations on cadmium and lead in electronic assemblies force European manufacturers toward costlier solder formulations and sensor materials.
Strategic Opportunities
- India's healthcare digitization:CDSCO alignment with international pharmaceutical traceability standards creates first-mover advantage for RFID-cabinet vendors in hospital infrastructure tenders.
- Cloud-native platform convergence:Biometric authentication systems are integrating with hospital information networks, enabling recurring software licensing revenue pools beyond hardware margins.
- Brazil's ANVISA serialization mandates:Controlled substance tracking requirements in Latin America's largest healthcare market open deployment pathways for audit-log-capable storage systems.
Industry Challenges
- Cybersecurity certification timelines:IEC 62443 industrial control system security validation for connected cabinets extends product launch schedules by 8-14 months.
- Legacy hospital network integration:Proprietary cloud ecosystems from incumbent vendors create interoperability friction with open IoT frameworks preferred by system integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Storage Cabinet Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lockable Cabinets, Modular Units, Wall-Mounted Cabinets, Mobile Storage, Open Shelving Technology: RFID, Biometric Access, IoT Connectivity, Mobile App Integration, Cloud Management Application: Inventory Management, Secure Asset Storage, Document Protection, Tool Organization, Equipment Tracking End User: Manufacturing Plants, Educational Institutions, Government Agencies, Research Facilities, Corporate Offices |
| Companies Covered | Quadient, TZ, American Locker, Florence Corporation, Hollman, Luxer One, KEBA, InPost, Parcel Pending, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Storage Cabinet Market Trends and Innovations
Electromechanical locking systems are converging with environmental sensing arrays and cellular backhaul modules, transforming enclosed furniture into real-time inventory visibility platforms that command premium positioning through software subscription attach rates.
Multi-factor biometric authentication is integrating fingerprint, facial recognition, and RFID credential verification into unified access control modules. United States hospital pharmacies are adopting these systems fastest to satisfy DEA dual-custody requirements. The technology is integrating audit logging directly into enterprise resource planning workflows, eliminating manual reconciliation steps.
EMA guidelines across Europe are tightening narcotics storage documentation standards, mandating timestamped access records with temperature monitoring for climate-sensitive pharmaceuticals. German and French hospital procurement offices now require CE-marked cabinets with embedded data loggers. Manufacturers are responding by pre-certifying enclosure assemblies to compress tender response timelines.
System integrators and procurement officers are consolidating vendor relationships around platforms offering API-accessible cloud management rather than proprietary dashboards. Healthcare networks in the United States are unbundling hardware acquisition from software licensing, treating connectivity and analytics as separate subscription line items. This purchasing pattern is most visible in multi-site hospital systems standardizing on single-platform deployments to reduce training overhead.
Smart Storage Cabinet Market Segmentation
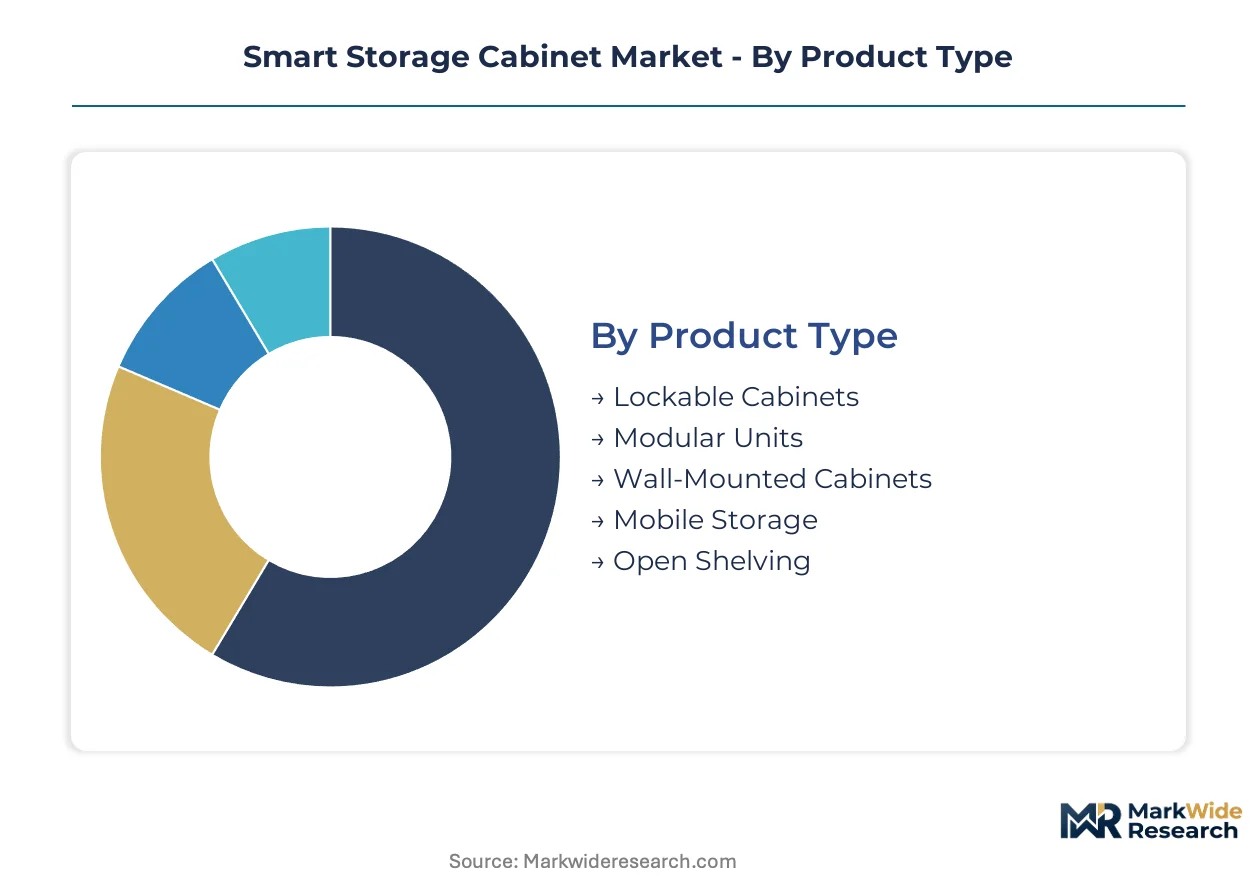
Smart storage cabinet segmentation reveals how hardware specifications, access technologies, and deployment environments concentrate margin pools differently. Procurement patterns across healthcare, manufacturing, and institutional buyers create distinct demand profiles that reshape vendor specialization.
Product Type:
Supply concentration favors enclosure fabricators with captive steel-forming capacity and IP-rated sealing expertise.
- Lockable Cabinets:Steel enclosures with electromechanical or electronic locking mechanisms, typically IP54-rated for dust and moisture protection. United States hospital pharmacies concentrate procurement here to satisfy FDA pharmaceutical custody requirements with tamper-evident logging. Today's leader: Lockable Cabinets. Tomorrow's challenger: Mobile Storage.
- Modular Units:Configurable compartment systems allowing vertical stacking and horizontal expansion with standardized mounting interfaces. German industrial facilities favor these for flexible manufacturing floor layouts under Ecodesign Directive standby power limits. Modular units climb the fastest as reconfigurable infrastructure gains priority.
- Wall-Mounted Cabinets:Space-efficient vertical installations with reduced footprint, common in corridor and entry-point deployments.
- Mobile Storage:Caster-mounted units with integrated power and network connectivity for relocation across facility zones.
- Open Shelving:Unlocked rack systems with sensor overlays for inventory visibility without physical access control.
Cost tier separation runs deepest in locking mechanism grade and environmental sealing certification.
Technology:
Application context determines whether biometric accuracy, RFID read range, or cloud interoperability commands procurement priority.
- RFID:Passive and active radio-frequency identification for automated item-level tracking without line-of-sight requirements. United States healthcare networks deploy these most intensively to meet FDA track-and-trace mandates for controlled substances. Today's anchor: RFID. Tomorrow's disruptor: Biometric Access.
- Biometric Access:Fingerprint, facial recognition, and iris scanning modules integrated into unified authentication workflows. DEA dual-custody requirements in United States hospital pharmacies accelerate fingerprint-plus-credential deployments.
- IoT Connectivity:Embedded cellular or Ethernet modules enabling real-time status transmission to centralized monitoring platforms.
- Mobile App Integration:Smartphone-based credentialing and remote unlock capabilities for distributed workforce access.
- Cloud Management:Subscription-based platform access for multi-site inventory visibility and analytics.
Volume concentration sits with RFID today; margin expansion favors biometric-plus-cloud bundled offerings.
Application:
Customer workflow integration determines whether real-time visibility, physical security, or environmental protection drives specification.
- Inventory Management:Automated stock-level monitoring with reorder-point alerting and consumption analytics. Manufacturing plants in China deploy these under NMPA-aligned smart healthcare mandates for medical supply chain modernization. Today's dominant use: Inventory Management. Tomorrow's expansion zone: Equipment Tracking.
- Secure Asset Storage:Controlled access for high-value items with chain-of-custody documentation and audit trails.
- Document Protection:Climate-controlled enclosures with fire resistance and humidity management for archival materials.
- Tool Organization:Shadow-board configurations with missing-item detection for maintenance and assembly operations.
- Equipment Tracking:Location-aware storage for mobile assets requiring check-out/check-in accountability.
Maturity curves diverge: inventory management approaches saturation in healthcare while equipment tracking gains first deployments in flexible manufacturing.
End User:
Procurement authority structures and compliance exposure create distinct buying behaviors across institutional categories.
- Manufacturing Plants:Industrial environments requiring IP65+ sealing and integration with MES/ERP systems for work-in-process tracking. Germany's automotive sector concentrates demand here under Ecodesign Directive pressure for standby power reduction. Today's volume leader: Manufacturing Plants. Tomorrow's growth engine: Research Facilities.
- Educational Institutions:Campus-wide deployments for equipment lending, lab access, and administrative document security.
- Government Agencies:Classified and controlled unclassified information storage with FIPS-compliant encryption requirements.
- Research Facilities:Climate-sensitive sample and reagent storage with temperature logging and regulatory documentation.
- Corporate Offices:Hot-desking environments with personal locker replacement and visitor management integration.
Margin pools concentrate where compliance documentation requirements intersect with multi-site standardization needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The smart storage cabinet industry traces its commercial origins to automated locker deployments in German industrial facilities and United States postal networks during the early 2000s. These early installations established the electromechanical and connectivity foundations that now scale across healthcare, logistics, and manufacturing sectors worldwide.
United States
FDA pharmaceutical custody mandates drive hospital pharmacy procurement toward biometric-access cabinets with tamper-evident audit logging. DEA dual-custody requirements for controlled substances accelerate fingerprint-plus-credential system installations. Major health systems in Boston and the Research Triangle standardize on single-platform deployments to reduce training overhead across multi-site networks.
Germany
Automotive manufacturing plants in Bavaria and Baden-Württemberg concentrate demand for Ecodesign Directive-compliant cabinets with sub-0.5-watt standby power limits. KBA regulatory alignment pressures enclosure fabricators toward ultra-low-consumption microcontroller redesigns. Industrial clusters around Stuttgart and Munich integrate these systems with MES/ERP workflows for work-in-process tracking.
China
NMPA certification frameworks channel hospital procurement budgets toward GB-standard-compliant connected storage systems. National smart healthcare mandates accelerate medical supply chain modernization in the Yangtze River Delta and Pearl River Delta. Shanghai and Shenzhen health authorities prioritize RFID-enabled inventory visibility platforms in tertiary hospital infrastructure tenders.
India
CDSCO alignment with international pharmaceutical traceability standards creates first-mover opportunities for RFID-cabinet vendors in hospital infrastructure expansion. Government digitization programs target medical device connectivity in Maharashtra and Karnataka. Mumbai and Bangalore hospital networks pilot automated storage systems for narcotics chain-of-custody documentation.
Brazil
ANVISA serialization mandates for controlled substance tracking open deployment pathways for audit-log-capable storage systems. Healthcare infrastructure investment concentrates in São Paulo and Rio de Janeiro metropolitan corridors. Hospital pharmacies in these regions evaluate biometric authentication platforms to satisfy evolving regulatory documentation requirements.
Smart Storage Cabinet Market Competitive Landscape
The competitive structure tilts toward specialized enclosure fabricators with captive metal-forming capacity and compliance pre-certification capabilities. Tier concentration remains moderate, with distinct premium and standard segments separating on locking mechanism grade and environmental sealing certification. Two strategic archetypes dominate: postal-logistics locker specialists extending into healthcare, and industrial automation controllers pivoting toward storage applications. Competitive moves center on geographic licensing partnerships and API-accessible cloud platform development to capture recurring software revenue.
Among parcel locker specialists, Quadient and Florence Corporation exemplify divergent strategic positioning within the competitive set. Quadient leverages its European logistics heritage to anchor automated pickup solutions across retail and last-mile delivery networks. Florence Corporation sustains municipal and postal dominance through specialized outdoor cabinet engineering for United States federal contracts. KEBA occupies a distinct industrial-grade position, with its IoT controller expertise extending into manufacturing floor deployments requiring MES integration and Ecodesign Directive compliance.
| Leading Market Players |
|---|
| Quadient |
| TZ |
| American Locker |
| Florence Corporation |
| Hollman |
| Luxer One |
| KEBA |
| InPost |
| Parcel Pending |
| Others |
Pricing and Supply Chain Analysis
FDA pharmaceutical custody mandates in United States hospital pharmacies are compressing procurement cycles toward compliance-verified platforms, forcing enclosure fabricators to absorb certification costs upfront and shifting margin capture toward recurring software licensing rather than hardware markups.
Pricing Analysis
Hardware-software unbundling now dominates smart storage cabinet transactions, with United States health systems treating biometric authentication modules and cloud management platforms as separate subscription line items from steel enclosure purchases. Three-tier pricing structure across FDA-validated premium, CE-marked standard, and uncertified economy levels separates procurement budgets, with German automotive buyers least sensitive due to Ecodesign Directive compliance requirements and Indian hospital networks most price-constrained. Cost compression in economy-tier lockable cabinets is intensifying because REACH substance restrictions force European manufacturers toward costlier solder formulations and sensor materials. Price differentiation hinges on IP-rated sealing certification and embedded data logger pre-certification rather than raw steel gauge.
Supply Chain Analysis
CE marking and FDA 510(k) qualification gating concentrate supplier relationships around enclosure fabricators with captive metal-forming capacity and pre-certified assembly lines. Manufacturing clusters in China, Germany, and the United States anchor production, with Yangtze River Delta facilities feeding NMPA-aligned hospital infrastructure tenders and Bavarian plants serving Ecodesign Directive mandates. Semiconductor supply for industrial-grade IoT controllers draws from foundry capacity concentrated in East Asian manufacturing clusters, creating single-source vulnerability for microcontroller assemblies. Steel and aluminum input volatility from energy cost fluctuations and trade tariff adjustments feeds from commodity metal pricing indexed to regional energy benchmarks. Distribution runs through system integrators and GPO contracts in healthcare, direct OEM relationships in automotive, and municipal procurement frameworks in postal-logistics deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart storage cabinet markets reward geographic arbitrage between Germany's Ecodesign-driven premium tier and India's CDSCO-aligned standard tier, where identical enclosure specifications face divergent compliance cost burdens and procurement budget constraints.
For Market Incumbents: Anchor defensive positioning by deepening captive steel-forming capacity to offset REACH substance restriction cost inflation, while accelerating API-accessible cloud platform development to capture recurring software revenue pools threatened by open IoT framework preferences among system integrators. Pre-certify enclosure assemblies to FDA and NMPA standards to compress tender response timelines against emerging modular unit specialists. For New Entrants and Emerging Players: Begin with Brazil's ANVISA serialization mandate window and India's CDSCO hospital infrastructure expansion, where audit-log-capable storage systems face limited incumbent saturation and procurement officers prioritize total cost of ownership over brand heritage. Target research facilities as the most penetrable end-use segment, where climate-sensitive sample storage requirements outpace vendor specialization. Lead with equipment tracking applications in flexible manufacturing environments where RFID and biometric convergence remains underdeveloped. For Investors and Strategic Acquirers: Asymmetric upside sits with industrial automation controller specialists pivoting toward storage applications, where MES integration expertise and Ecodesign Directive compliance capabilities command scarcity premiums in manufacturing plant deployments. Long-term viability favors vendors with unbundled hardware-software revenue models and multi-site hospital system standardization track records. Watch for IEC 62443 cybersecurity certification completion as the inflection signal separating compliant platforms from launch-delayed competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Development | API-accessible architectures capture recurring software licensing from United States health systems unbundling hardware procurement. |
| Regulatory Pre-Certification Investment | FDA and NMPA pre-validated assemblies compress tender timelines against competitors facing 8-14 month cybersecurity validation delays. |
| Geographic Licensing Partnerships | Local manufacturing partnerships in India and Brazil navigate CDSCO and ANVISA procurement localization requirements. |
| Biometric-Cloud Bundle Integration | Fingerprint-plus-credential systems with subscription analytics satisfy DEA dual-custody mandates in hospital pharmacy deployments. |
| Ultra-Low-Power Microcontroller Redesign | Sub-0.5-watt standby compliance secures Bavarian automotive plant contracts under Germany's Ecodesign Directive limits. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement managers, biomedical engineers, GPO contracts managers, and industrial automation integrators with secondary validation against FDA filings, NMPA certification databases, ECHA REACH substance restrictions, and customs trade records. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates across the projection horizon.
Comparable-period anchoring linked forward projections to historical reference intervals spanning pre-pandemic baseline, supply disruption peak, and normalization phases without year-specific attribution. Segmentation dimensions modeled include product type, access technology, application workflow, and end-use procurement authority structure, with CAGRs derived from regression analysis of installed base expansion and replacement cycle compression. Forecast inputs incorporated Ecodesign Directive standby power compliance trajectories and NMPA smart healthcare mandate implementation pacing.
Several conditions sit outside the modeled scope, including semiconductor foundry capacity allocation shocks, steel tariff rate adjustments, and cybersecurity certification timeline extensions beyond standard IEC 62443 validation windows. Forecasts reflect assumptions regarding regulatory enforcement consistency and hospital capital expenditure continuity. A model refresh is warranted upon material change in FDA pharmaceutical custody mandate expansion or Ecodesign Directive power limit revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Storage and Organization
Kitchen Storage Market
Home Storage and Organization
Toy Storage Market
Home Storage and Organization
Closet Organizers Market
Home Storage and Organization
Sheds and Outdoor Storage Market
Home Storage and Organization
Scandinavia Self-Storage Market
Home Storage and Organization
Flush Mount Photo Album Market
Home Storage and Organization
Clothes Closets Market
Home Storage and Organization
Wardrobe Boxes Market
Home Storage and Organization
Hong Kong Self-Storage Market
Home Storage and Organization
United Kingdom Home Decor Market
Home Storage and Organization
Jewelry Organizer Market
Home Storage and Organization
Flatware Holders and Organizers Market
Home Storage and Organization
Cabinet & Furniture Drawer Slides Market
Home Storage and Organization
Shoe Storage and Organizers Market
Home Storage and Organization
Smart Shoe Cabinet Market
Home Storage and Organization
Middle East and Africa Kitchen Storage Market