
 Europe and Middle East Demountable Partitions Market | 2026-2036
Europe and Middle East Demountable Partitions Market Size, Share, and Industry Trends Forecast 2026-2036
Europe and Middle East Demountable Partitions Market Analysis
The EU Green Deal's embodied carbon reduction targets is recalibrating procurement criteria for interior fit-out materials across European commercial real estate. Komfort Workspace Plc leverages its UK manufacturing footprint to supply low-carbon steel-framed systems to London and Manchester office developments. Dormakaba Group anchors its position through integrated access-control hardware paired with demountable wall solutions. Maars Living Walls specializes in acoustic-rated modular systems that meet stringent Dutch and German workplace standards.
Demountable partitions are non-load-bearing interior wall systems designed for repeated assembly, relocation, and reconfiguration without structural modification, typically achieving acoustic ratings from 35 dB to 55 dB depending on glass thickness, seal configuration, and core infill material. These systems serve commercial and institutional users requiring spatial flexibility, lease-term adaptability, and minimal waste during tenant turnover. Glass partitions command premium positioning in financial services and legal sector fit-outs where transparency and daylight penetration justify higher installed costs. Acoustic partitions capture expanding share in co-working and healthcare-adjacent office environments where speech privacy regulations tighten. Modular partitions built on aluminum framing dominate retrofit applications across aging Middle East commercial stock where speed of installation reduces revenue loss during building upgrades.
REACH compliance and CE marking requirements govern material composition and fire performance of partition systems sold across EU member states, while UAE Civil Defence and Saudi Building Code provisions dictate fire-resistance ratings for commercial interiors in Gulf markets. ECHA substance restrictions on certain flame retardants and plasticizers are forcing reformulation of sealants and gasket materials used in partition assemblies. The EU AI Act's forthcoming workplace monitoring provisions may accelerate demand for physical privacy solutions as employers balance collaboration spaces with confidential work zones. Stakeholders must track evolving national implementations of the EU Green Deal's embodied carbon reporting rules and assess supplier readiness for circularity certification.
Market Dynamics
Hybrid work mandates from major corporate occupiers are compressing lease cycles and forcing landlords to prioritize speed of reconfiguration over permanent build-outs across European and Gulf commercial portfolios.
Growth Catalysts
- EU Green Deal embodied carbon rules:Commercial landlords in Germany and the Netherlands now specify demountable systems with recycled aluminum content to meet Scope 3 reporting thresholds under CSRD.
- Healthcare-adjacent office fit-outs:Speech privacy regulations in Dutch and German workplace standards are pulling acoustic-rated modular partitions into co-working and medical consulting environments.
- Speed of installation:Aging commercial stock in Dubai and Riyadh drives specification of aluminum-framed retrofit systems that minimize revenue loss during building upgrades.
Market Restraints
- Steel and aluminum price volatility:Input cost swings for primary aluminum and cold-rolled steel compress margins on fixed-price fit-out contracts across European markets.
- Sealant reformulation costs:ECHA substance restrictions on halogenated flame retardants force manufacturers to qualify new gasket compounds, extending product recertification timelines.
- Permanent drywall substitution:Cost-sensitive speculative office developers in secondary UAE markets still default to conventional construction for initial tenant fit-outs.
Strategic Opportunities
- Saudi Vision 2030 commercial pipeline:Giga-project office developments in Riyadh and Jeddah create first-mover positioning for suppliers offering rapid-deployment partition systems with Gulf-specific fire ratings.
- EU AI Act workplace monitoring provisions:Anticipated physical privacy requirements are accelerating demand for switchable glass and solid-core demountable zones within open-plan offices.
- Circularity certification:Early alignment with emerging EU Green Deal circularity scoring creates procurement preference among ESG-mandated institutional investors in London and Paris.
Industry Challenges
- Acoustic engineering talent scarcity:Qualified specifiers who can validate STC ratings across multi-material assemblies remain concentrated in Dutch and German technical consultancies.
- Legacy building integration:Retrofit projects in 1970s Middle East commercial stock encounter slab-level tolerance issues that complicate modular partition anchoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe and Middle East Demountable Partitions Market |
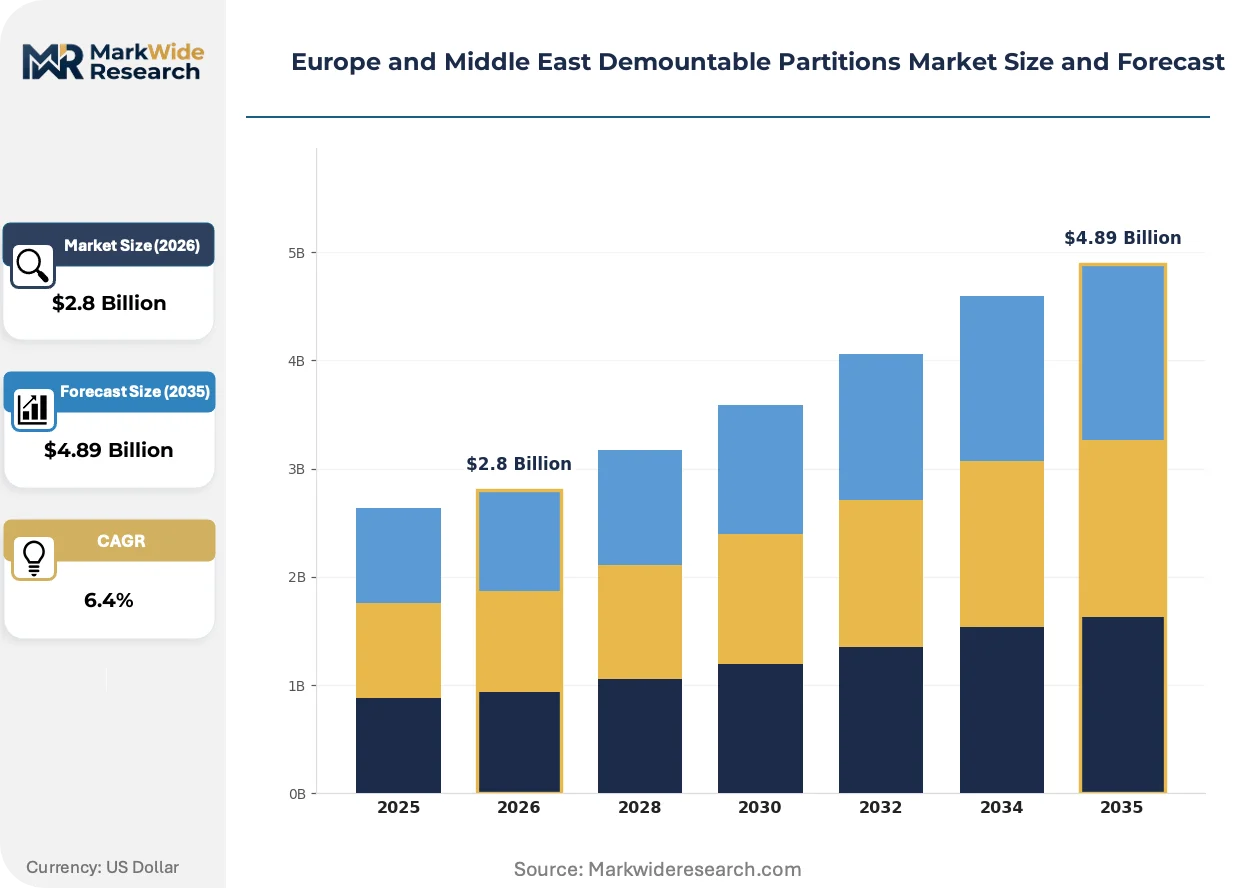
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Partitions, Acoustic Partitions, Modular Partitions, Folding Partitions End User: Corporate Offices, Retail Outlets, Educational Institutions, Hospitality Venues Installation Method: Stick-On, Hanging, Freestanding, Mounted Material: Wood, Aluminum, Steel, Plastic |
| Companies Covered | Avanti Systems USA, Komfort Workspace Plc, Hufcor, Inc., KCC Architectural, GGI Solutions, Dormakaba Group, Apton Partitioning Ltd., Ikon Partitions, Maars Living Walls, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe and Middle East Demountable Partitions Market Emerging Trajectories
Active specification of switchable electrochromic glazing and predictive acoustic modeling software is compressing traditional design-assist timelines for complex fit-out programs.
Electrochromic glass with user-controlled opacity is absorbing specification share in financial services and legal sector fit-outs where confidential work zones must coexist with daylight harvesting mandates. London and Frankfurt occupiers are piloting these systems at scale despite premium installed costs. The technology is absorbing budget allocations previously reserved for permanent solid-core construction.
REACH compliance deadlines for restricted substance categories are forcing reformulation of sealants and gasket materials used in partition assemblies across EU member states. Manufacturers serving Dutch and German markets face compressed qualification windows for alternative compounds. Glass partition suppliers with in-house polymer chemistry capabilities are internalizing testing to maintain CE marking continuity.
Lease-term flexibility clauses are displacing traditional ten-year build-out assumptions in corporate real estate procurement. Occupiers in Manchester and Dubai now demand demountable systems with guaranteed buy-back or redeployment terms at contract expiry. This pattern concentrates among technology and professional services tenants with sub-five-year location commitments.
Europe and Middle East Demountable Partitions Market Segmentation
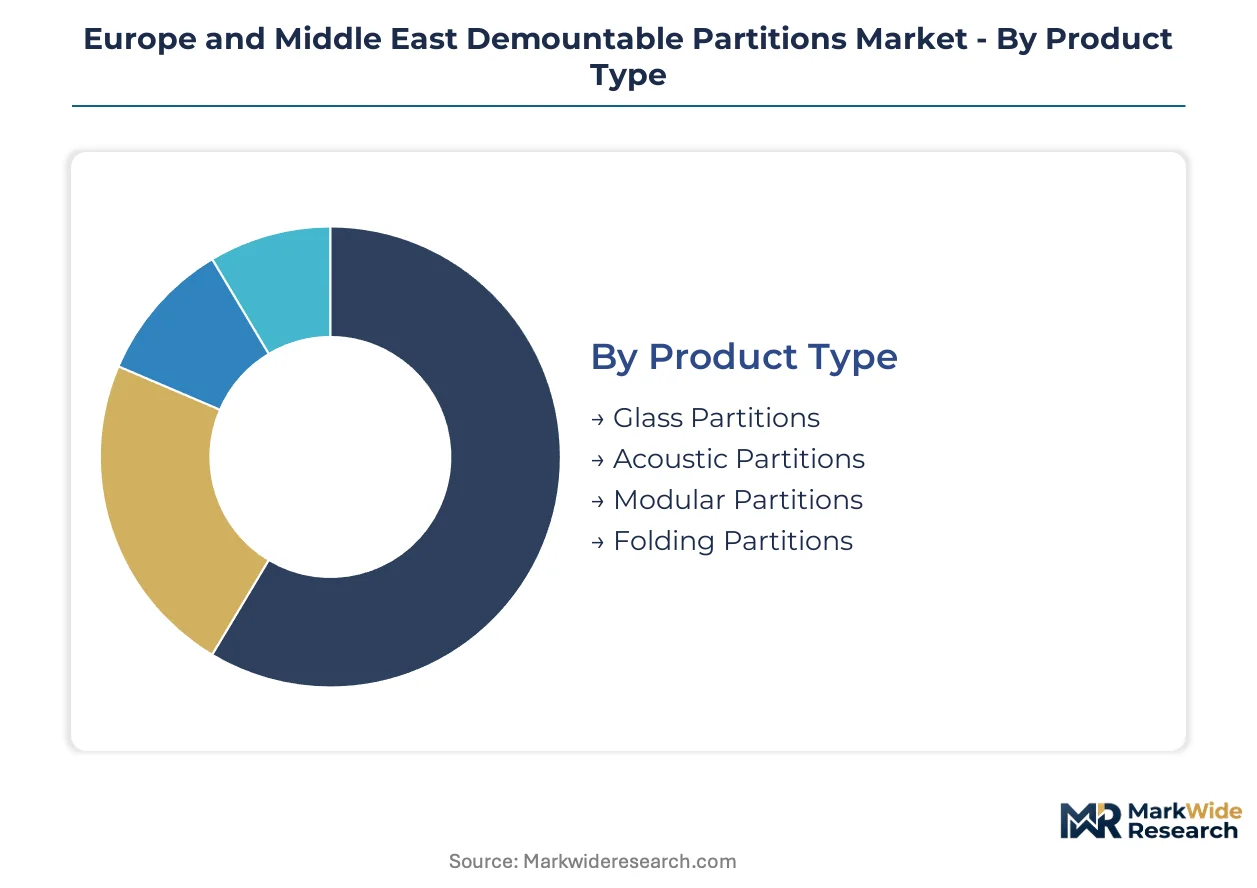
Partition specification varies sharply across building age, lease structure, and acoustic requirements. Procurement teams segment choices by reconfiguration frequency, fire-rating needs, and embodied carbon reporting obligations under EU and Gulf regulations.
Product Type:
Upgrade cycles differ materially: glass systems face pressure from electrochromic retrofit demand, while acoustic partitions respond to tightening workplace privacy standards.
- Glass Partitions:Framed or frameless tempered glazing systems with acoustic laminates achieving 35-45 dB ratings. Financial services fit-outs in London and Frankfurt absorb premium switchable-electrochromic variants despite higher installed costs. Demand concentrates where daylight harvesting mandates conflict with confidentiality requirements.
- Acoustic Partitions:Solid-core modular assemblies with mineral wool or PET core infill engineered for 45-55 dB speech privacy. Dutch and German healthcare-adjacent offices specify these systems under tightened workplace noise regulations. Co-working operators in Dubai deploy them to satisfy multi-tenant confidentiality clauses.
- Modular Partitions:Aluminum-framed clip-together systems designed for repeated reconfiguration without tools. Aging commercial stock in Riyadh and Jeddah drives retrofit specification for speed of installation.
- Folding Partitions:Track-mounted operable wall systems for large-volume space division. Hospitality venues in UAE giga-projects specify fire-rated variants for ballroom and conference flexibility.
Volume placements concentrate in modular aluminum systems; the faster expansion belongs to acoustic-rated partitions.
End User:
Lease-term compression is reshaping procurement patterns across occupier categories, with technology and professional services tenants demanding buy-back guarantees.
- Corporate Offices:Hybrid work mandates from major occupiers are compressing fit-out cycles to sub-five-year horizons. Manchester and Dubai landlords now specify demountable systems with guaranteed redeployment terms.
- Retail Outlets:Pop-up and seasonal retail formats in Gulf markets favor freestanding systems for rapid store-in-store deployment. Visual merchandising teams prioritize frameless glass for brand visibility.
- Educational Institutions:University expansion projects in Saudi Arabia specify modular systems for lecture hall subdivision. Fire-resistance ratings under Saudi Building Code govern material selection.
- Hospitality Venues:Hotel renovation programs in London and Paris prioritize acoustic separation for co-working lobbies and private dining zones. ESG-mandated institutional investors require circularity certification.
Corporate offices dominate current placements; hospitality venues are gaining share fastest as hotel-to-office conversions accelerate.
Installation Method:
Slab tolerance conditions in 1970s Middle East commercial stock are eliminating certain mounting categories from retrofit consideration.
- Stick-On:Adhesive-mounted glazing systems for ultra-fast deployment in pristine slab conditions. Limited to newer UAE commercial stock with flatness tolerances under 3mm per 2m.
- Hanging:Top-track suspended partitions eliminating floor penetration. Preferred in German and Dutch heritage building conversions where slab preservation is mandatory.
- Freestanding:Self-supporting modular units requiring no structural anchoring. Retail and co-working operators in Dubai specify these for maximum lease-term flexibility.
- Mounted:Floor-and-ceiling fixed systems delivering maximum acoustic and seismic performance. Corporate headquarters in Riyadh and Frankfurt default to this category for permanent-adjacent durability.
Mounted systems capture the largest project volumes; freestanding configurations are climbing the fastest as short-term lease structures proliferate.
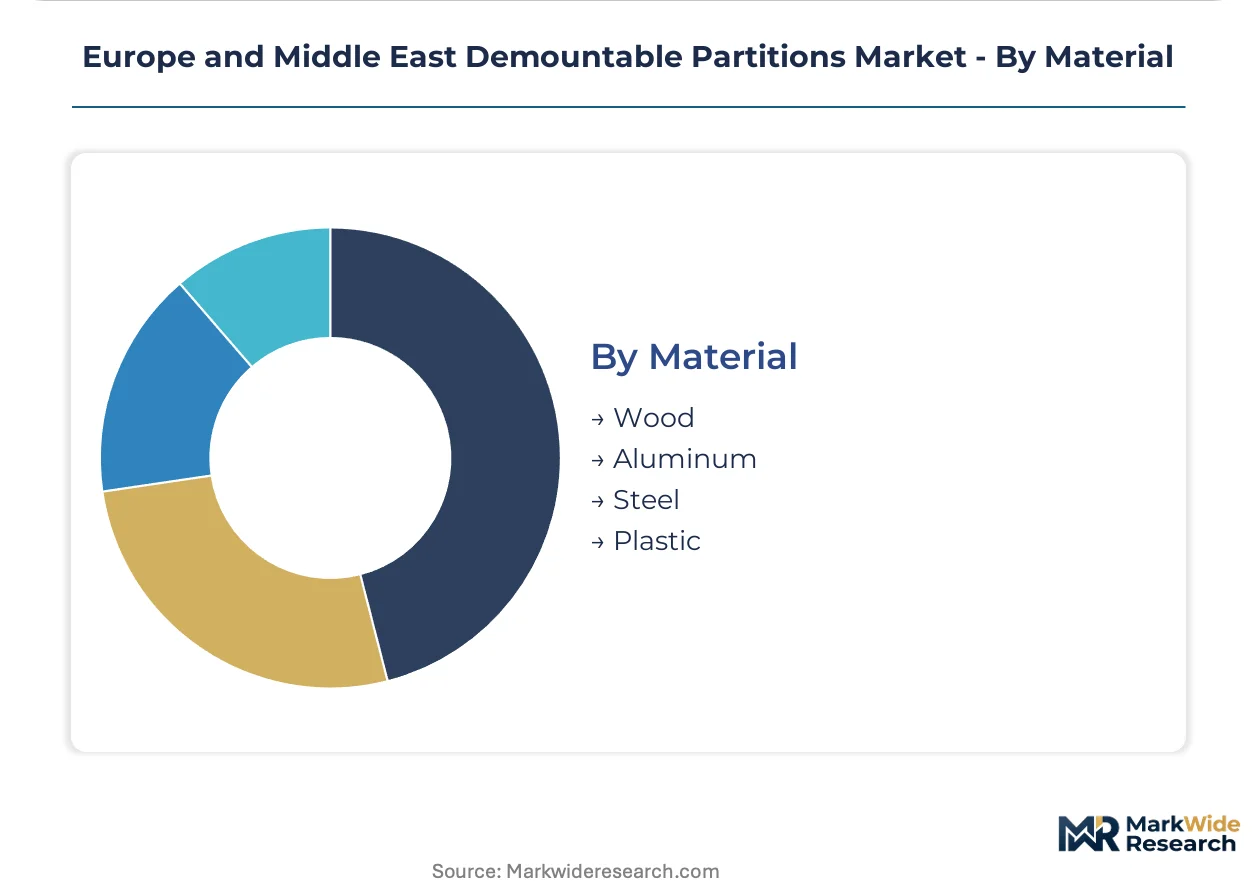
Material:
Embodied carbon reporting under CSRD and EU Green Deal provisions is recalibrating procurement criteria toward recycled content and end-of-life recoverability.
- Wood:Engineered timber framing with FSC chain-of-custody certification. Boutique hospitality fit-outs in Paris and Milan specify these for biophilic design credentials.
- Aluminum:Extruded profiles with 50-75% post-consumer recycled content. German and Dutch commercial landlords specify these systems to meet Scope 3 reporting thresholds.
- Steel:Cold-rolled or stainless framing with high recycled content and magnetic end-of-life recovery. UK manufacturing footprints supply low-carbon variants to London developments.
- Plastic:Polymer components primarily in gaskets, seals, and trim. ECHA substance restrictions on halogenated flame retardants are forcing rapid compound reformulation.
Aluminum dominates specification volume; steel-framed systems are expanding most quickly as UK and German manufacturers scale low-carbon production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London's commercial development pipeline dominates specification activity for demountable partition systems across the Europe and Middle East corridor, with Manchester, Frankfurt, Dubai, and Riyadh forming secondary concentration nodes.
Germany
Corporate headquarters relocations in Frankfurt and Hamburg are compressing fit-out cycles to sub-five-year horizons. The EU Green Deal's embodied carbon reporting rules under CSRD mandate recycled aluminum content in new commercial developments. Bavarian manufacturers supply low-carbon steel-framed systems to Munich office complexes.
United Kingdom
London landlords now specify demountable systems with guaranteed buy-back terms as lease flexibility clauses proliferate. REACH compliance deadlines force reformulation of sealant compounds used in partition assemblies. Manchester technology tenants drive demand for rapid-reconfiguration modular systems.
United Arab Emirates
Dubai's aging 1970s commercial stock requires aluminum-framed retrofit systems that minimize revenue loss during building upgrades. UAE Civil Defence fire-resistance ratings govern material selection for Gulf commercial interiors. Abu Dhabi giga-projects specify track-mounted operable walls for hospitality venues.
Netherlands
Dutch healthcare-adjacent offices specify acoustic-rated modular partitions under tightened workplace noise regulations. ECHA substance restrictions on halogenated flame retardants extend product recertification timelines for gasket manufacturers. Amsterdam and Rotterdam developments prioritize circularity certification for ESG-mandated institutional investors.
Saudi Arabia
Saudi Vision 2030 giga-project office developments in Riyadh and Jeddah create demand for rapid-deployment partition systems with Gulf-specific fire ratings. The Saudi Building Code dictates fire-resistance requirements for commercial interiors. Eastern Province commercial pipelines absorb premium switchable-glazing variants despite higher installed costs.
Europe and Middle East Demountable Partitions Market Vendor Landscape
The competitive structure tilts toward specialized fabricators with integrated access-control capabilities and acoustic engineering expertise. Tier-one suppliers concentrate in German, Dutch, and UK manufacturing clusters, while regional distributors serve Gulf markets through Dubai-based logistics hubs. Two strategic archetypes dominate: vertically integrated systems providers with in-house aluminum extrusion and glass processing, and specification-led consultancies partnering with local installation contractors. Capacity expansion and circularity certification alignment represent the dominant competitive moves as CSRD reporting deadlines approach.
Among UK-based fabricators, Komfort Workspace Plc and Apton Partitioning Ltd. occupy positions within the low-carbon steel-framed segment, while Maars Living Walls anchors the Dutch acoustic-specialist tier. Dormakaba Group exemplifies the integrated hardware-access-control archetype, leveraging its door systems footprint to bundle partition solutions. These three companies represent distinct competitive vectors: manufacturing-scale efficiency, acoustic engineering specialization, and integrated building hardware ecosystems.
| Leading Market Players |
|---|
| Avanti Systems USA |
| Komfort Workspace Plc |
| Hufcor, Inc. |
| KCC Architectural |
| GGI Solutions |
| Dormakaba Group |
| Apton Partitioning Ltd. |
| Ikon Partitions |
| Maars Living Walls |
| Others |
Supply Flow & Price Mechanics
London Metal Exchange aluminum pricing volatility cascades through European and Gulf demountable partition markets, compressing margins on fixed-price fit-out contracts and forcing tiered pricing stratification across recycled-content premium, standard extrusion, and commodity-grade economy levels. Input cost swings for cold-rolled steel and acoustic glass laminates further differentiate procurement tiers, with CSRD-mandated Scope 3 reporting requirements anchoring premium positioning for low-carbon systems.
Pricing Analysis
Lease-term flexibility value anchors pricing architecture across European and Middle Eastern commercial real estate, with guaranteed buy-back provisions commanding 15-25% premiums over conventional transactional models. Price differentiation separates CE-marked acoustic systems meeting Dutch workplace noise regulations from economy-grade modular units serving speculative UAE office developments. Pricing pressure stems from ECHA-mandated sealant reformulation costs extending manufacturer recertification timelines. Technology and professional services tenants with sub-five-year location commitments exhibit highest price elasticity, while ESG-mandated institutional investors in London and Paris demonstrate lowest sensitivity.
Supply Chain Analysis
Dual-sourcing requirements from German and Dutch commercial landlords mandate multi-supplier qualification for aluminum extrusion and glass processing, mitigating single-source vulnerability from concentrated Bavarian and UK manufacturing clusters. Raw material dependencies center on primary aluminum from Norwegian smelters, cold-rolled steel from UK mills, and acoustic laminates from Belgian glass processors. Supply chain risk concentrates in tariff exposure affecting aluminum ingot flows into European extrusion plants. Distribution runs through Dubai-based logistics hubs serving Gulf markets, with specification-led consultancies partnering local installation contractors across Riyadh and Jeddah giga-projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acoustic engineering talent scarcity props pricing power for qualified specifiers, constraining rapid market expansion despite demand acceleration from hybrid work mandates and EU Green Deal compliance deadlines.
For Market Incumbents: Lock in circularity certification alignment ahead of CSRD reporting deadlines to defend procurement preference among ESG-mandated institutional investors in London and Paris. Extend backward integration into aluminum extrusion and glass laminating to capture margin compression from volatile LME pricing. Counter emerging acoustic-specialist entrants by embedding predictive acoustic modeling software into design-assist service offerings. For New Entrants and Emerging Players: Switchable electrochromic glazing integration offers a technology-first wedge into financial services fit-outs where daylight harvesting mandates conflict with confidentiality requirements. Target hospitality-to-office conversion projects in London and Paris where circularity certification gaps create specification white space. Deploy rapid-deployment modular systems with Gulf-specific fire ratings to capture Saudi Vision 2030 giga-project pipelines ahead of incumbent qualification cycles. For Investors and Strategic Acquirers: The window for entry favors vertically integrated fabricators with in-house polymer chemistry capabilities navigating ECHA substance restriction deadlines. Long-term viability hinges on circularity infrastructure investment and buy-back program scalability across compressed lease cycles. Monitor CSRD implementation pace across German and Dutch commercial portfolios as inflection indicator for premium-system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Circularity Certification Investment | CSRD reporting deadlines in Germany and Netherlands create procurement preference for certified systems. |
| Backward Integration into Aluminum Extrusion | Captures margin from LME volatility while securing recycled-content supply for Scope 3 compliance. |
| Acoustic Engineering Talent Acquisition | Qualified STC validators remain concentrated in Dutch and German technical consultancies. |
| Gulf-Specific Fire Rating Qualification | UAE Civil Defence and Saudi Building Code provisions govern commercial interior specifications. |
| Electrochromic Glazing Partnership | Switchable glass demand accelerates from EU AI Act workplace monitoring provisions. |
Methodological Framework
Multi-period observation of LME aluminum pricing, commercial construction permit flows, and tenant lease restructuring patterns anchored the trend analysis, supplemented by interviews with commercial real estate procurement directors, fit-out contractors, acoustic engineering consultants, and aluminum extrusion plant managers. Secondary validation drew from EU construction statistics, Dubai Department of Economic Development licensing data, SEC filings of publicly traded building material suppliers, and REACH compliance disclosure databases. Bottom-up project pipeline assessment triangulated against top-down regional construction spending estimates.
Segment-weighting across product type, end user, installation method, and material composition informed volume and value projections across the analysis window. Modeled dimensions included glass thickness configurations, acoustic rating tiers, fire-resistance classifications, and recycled-content thresholds. CAGRs derived from regression analysis of historical fit-out cycle compression correlated with hybrid work mandate adoption curves. Industry-specific inputs incorporated ECHA substance restriction timelines and Saudi Vision 2030 project announcement velocities.
Several conditions sit outside the modeled scope, including geopolitical disruption to aluminum supply chains, abrupt ECHA substance category expansions, and Gulf sovereign liquidity constraints affecting giga-project pacing. Deviation in CSRD enforcement consistency across EU member states would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Europe Sustainable Mattress Market
Furniture
GCC Home Furniture Market
Furniture
Children's Home Study Desks Market
Furniture
France Furniture Market
Furniture
Europe Free Standing Electrical Height-Adjustable Tables Market
Furniture
Europe Home Furniture Market
Furniture
Global Home Furniture Market
Furniture
Europe Luxury Furniture Market
Furniture
Kids Furniture Market
Furniture
Asia-Pacific Free Standing Electrical Height-Adjustable Tables Market
Furniture
US Secondary Wood Products Market
Furniture
Europe Furniture Market
Furniture
Indonesia Furniture Market
Furniture
Luxury RTA (Ready-To-Assemble) Furniture Market
Furniture
Middle East and Africa Wood Based Panel Market
Furniture
Exam Tables Market