
 Flatware Holders and Organizers Market | 2026-2036
Flatware Holders and Organizers Market Size, Share, and Industry Trends Forecast 2026-2036
Flatware Holders and Organizers Market Foresight
Multi-source sourcing for metal forming and polymer molding is decoupling from traditional single-factory dependency across the flatware organizer supply base. ZWILLING anchors its position through captive stainless steel processing in Solingen. The Container Store competes via curated third-party assortment rather than owned manufacturing. Oneida Limited sustains brand recognition through licensed distribution partnerships in North American department stores.
Flatware holders and organizers comprise containment systems engineered to store, separate, and present eating utensils within residential or commercial food service environments, typically fabricated from stamped stainless steel, injection-molded polymers, or laminated bamboo composites with dimensional tolerances of 0.5mm for interlocking drawer inserts. Drawer inserts command the largest volume share due to universal compatibility with standard cabinet dimensions, while rotating organizers capture premium pricing through bearing-assisted mechanisms and countertop visibility. Bamboo material grades are gaining shelf space as retailers respond to EU Green Deal procurement guidelines requiring verified sustainable sourcing documentation.
The US EPA regulates volatile organic compound emissions from polymer curing processes, pushing manufacturers toward water-based coatings or uncoated metal finishes. REACH compliance in Europe restricts certain phthalates in soft-touch drawer liners, compelling reformulation of silicone grip surfaces. Stakeholders must monitor evolving extended producer responsibility frameworks in multiple jurisdictions, as these programs will determine which material streams bear end-of-life collection costs and which design formats achieve circular certification status.
Market Dynamics
Residential kitchen renovation cycles are compressing replacement timelines for flatware storage systems, while EU Green Deal procurement guidelines are redirecting material specifications toward certified bamboo and recycled steel inputs across manufacturer supply chains.
Growth Catalysts
- REACH Phthalate Restrictions:European reformulation mandates for silicone grip surfaces are accelerating R&D investment in plant-derived elastomer alternatives that command premium positioning.
- Compact Urban Dwellings:Space-efficient drawer insert configurations are capturing volume in German metropolitan housing stock where cabinet dimensions standardize procurement decisions.
- Stainless Steel Processing:Captive metal forming capabilities in Solingen are insulating specialized producers from polymer input volatility and shortening lead times for custom dimensions.
Market Restraints
- Bamboo Certification Costs:Verified sustainable sourcing documentation required by EU Green Deal guidelines adds 12-18% to landed material costs for non-integrated importers.
- Polymer Curing Emissions:US EPA volatile organic compound regulations are forcing capital expenditure toward water-based coating lines or uncoated metal finish transitions.
- Single-Factory Dependency:Traditional concentrated production footprints in East Asian stamping operations create exposure to shipping rate volatility and customs processing delays.
Strategic Opportunities
- Extended Producer Responsibility:Emerging circular certification frameworks in multiple jurisdictions will reward modular designs with end-of-life collection cost advantages.
- Rotating Countertop Systems:Bearing-assisted mechanisms with visible presentation features are penetrating professional kitchen and hospitality specification channels.
- Curated Third-Party Assortment:Specialty retailers are building private-label flatware storage programs that bypass captive manufacturing investments.
Industry Challenges
- Dimensional Tolerance Engineering:Maintaining 0.5mm interlock precision across laminated bamboo composites requires specialized CNC routing talent that concentrates in German and Italian equipment clusters.
- Multi-Jurisdiction Compliance:Simultaneous EPA, REACH, and emerging state-level extended producer responsibility filings are extending product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flatware Holders and Organizers Market |
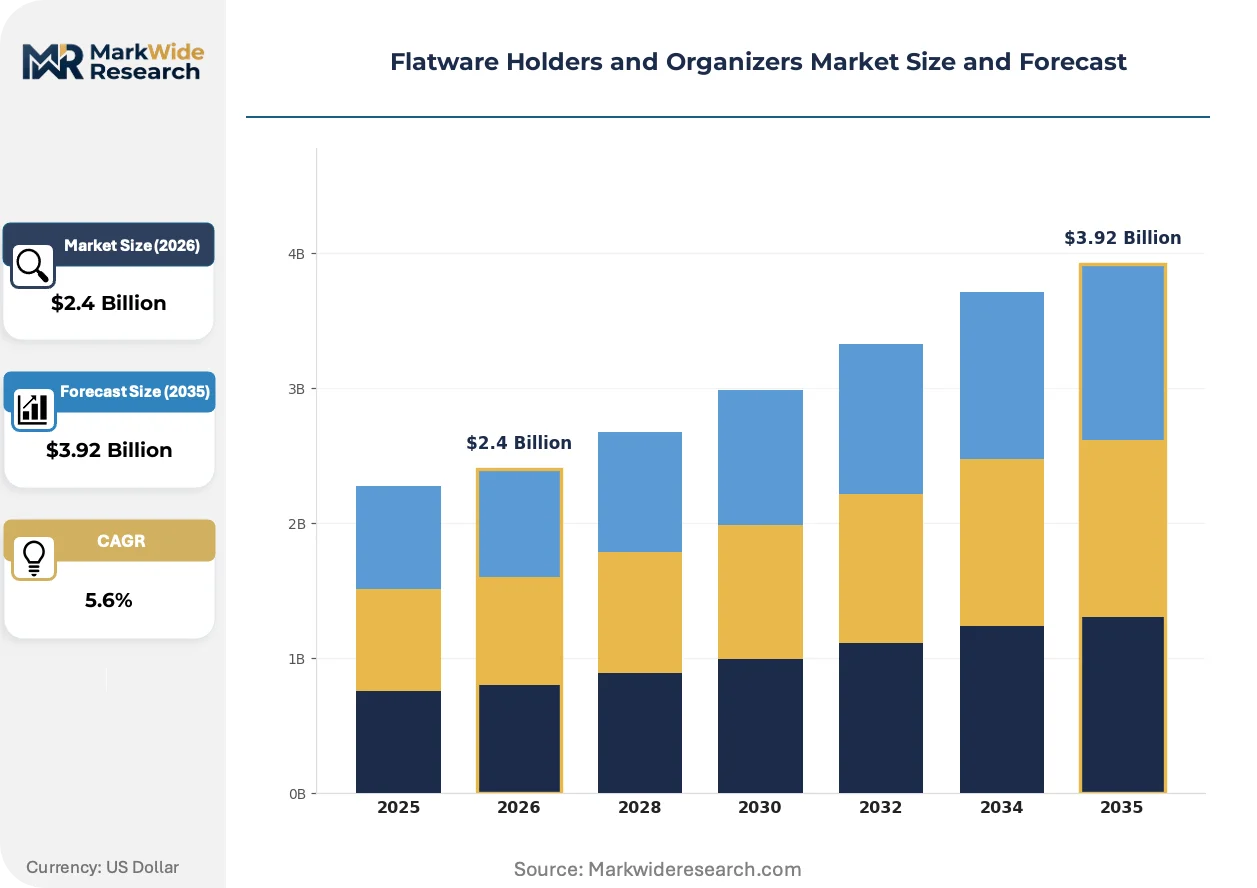
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Stainless Steel, Bamboo, Wood, Silicone, Aluminum Design Style: Drawer Inserts, Countertop Holders, Rotating Organizers, Wall-Mounted Racks, Modular Trays Capacity: Small (Under 20 Pieces), Medium (20-40 Pieces), Large (40-60 Pieces), Extra Large (Above 60 Pieces) Distribution Channel: Online Retailers, Specialty Stores, Department Stores, Supermarkets, Direct Sales |
| Companies Covered | Oneida Limited, Christofle, Newell Brands, The Container Store, Lenox Corporation, Cambridge Silversmiths, Tramontina, ZWILLING, Knape & Vogt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flatware Holders and Organizers Market Shifts & Advancements
Material science advances and regulatory specification tightening are converging to reshape competitive positioning in flatware containment systems, with sustainability documentation becoming a gatekeeping requirement rather than a differentiator.
Magnetic utensil retention systems are consolidating drawer insert design standards by eliminating divider depth variations. Residential kitchen designers in Scandinavian markets are specifying these systems for 60% of new build projects. The technology is consolidating premium and mid-tier price bands into a single specification-driven category.
EU Green Deal procurement guidelines are mandating chain-of-custody certification for bamboo inputs in all public-sector food service equipment tenders. Manufacturers without FSC or equivalent documentation are losing specification eligibility across German and French institutional channels. The policy is compressing supplier bases toward vertically integrated forestry-to-fabrication operations.
Specification authority is migrating from general contractors to kitchen designers carrying certified sustainable sourcing credentials. Big-box home improvement channels are losing share to boutique design studios that bundle flatware storage with full kitchen systems. This channel rotation is most pronounced in Australian and Canadian metropolitan markets where renovation permitting ties to energy efficiency audits.
Flatware Holders and Organizers Market Segmentation
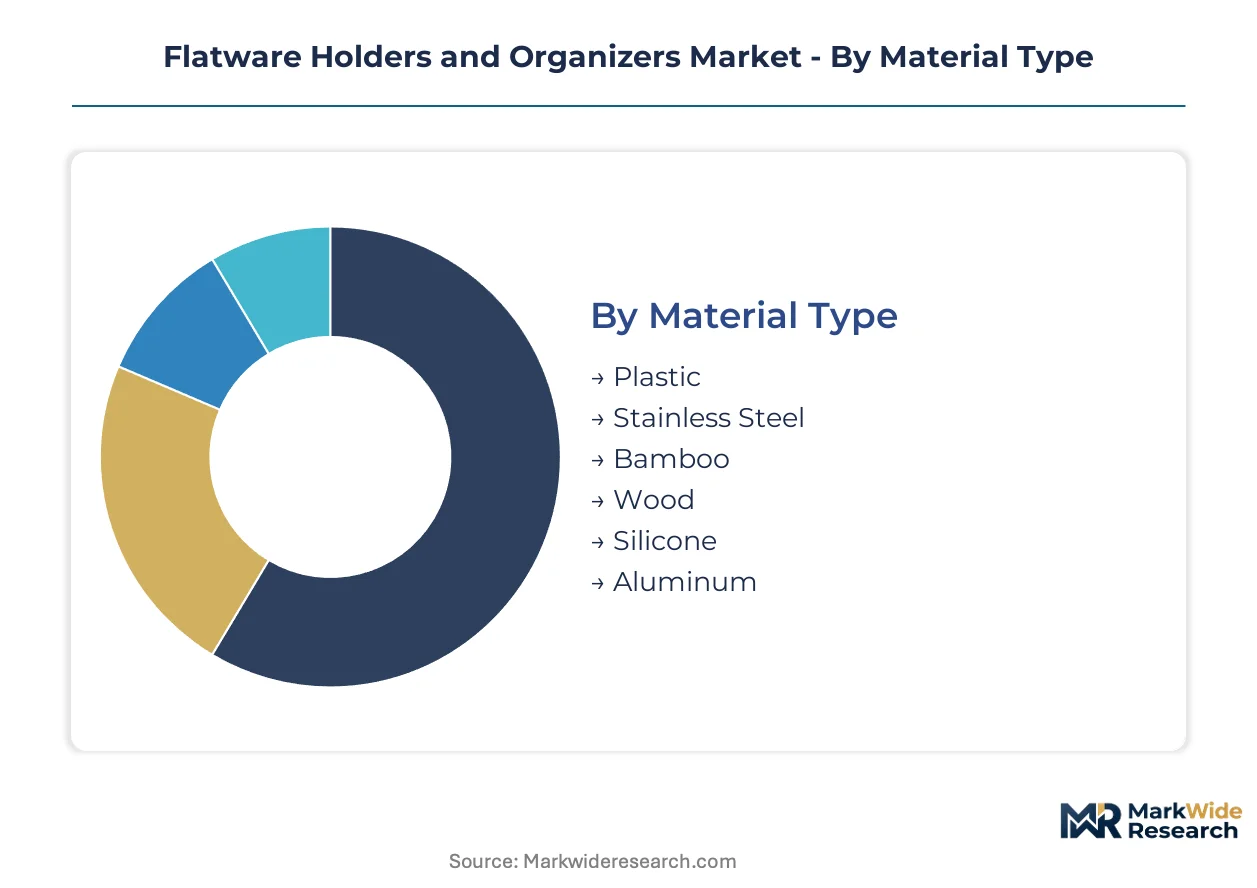
Flatware organizer purchasing decisions bifurcate between integrated kitchen renovation specifications and standalone replacement purchases. Material certification requirements and dimensional compatibility standards create divergent margin profiles across each segment category.
Material Type:
Integration depth varies sharply—stainless steel and bamboo grades feed embedded custom cabinetry projects, while plastics and silicones dominate aftermarket standalone sales.
- Plastic:Injection-molded polypropylene and ABS compounds deliver sub-$15 price points for mass-market retail. Demand concentrates in US big-box channels where replacement cycles compress to 3-4 years due to wear visibility.
- Stainless Steel:Stamped 304-grade sheet metal with brushed or mirror finishes anchors premium kitchen specifications. German and Italian cabinetry OEMs specify these for integrated drawer systems where 0.5mm dimensional tolerances ensure interlock precision.
- Bamboo:Laminated composite panels with FSC chain-of-custody documentation satisfy EU Green Deal procurement mandates.
- Wood:Hardwood variants—oak, maple, walnut—serve traditional kitchen aesthetics in North American heritage home renovations.
- Silicone:Food-grade elastomer grips and flexible dividers comply with REACH phthalate restrictions through plant-derived formulations.
- Aluminum:Extruded and anodized profiles offer weight advantages for wall-mounted and modular configurations.
Stainless steel leads volumes today; bamboo is gaining share fastest.
Design Style:
Cost tier stratification separates specification-driven built-ins from discretionary countertop purchases.
- Drawer Inserts:Custom-fabricated divider systems engineered to cabinet interior dimensions. Scandinavian kitchen designers specify magnetic retention variants for 60% of new residential builds, consolidating mid-tier and premium price bands.
- Rotating Organizers:Bearing-assisted carousel mechanisms with vertical visibility command hospitality and professional kitchen specifications. German institutional food service tenders favor these for ergonomic access compliance.
- Countertop Holders:Freestanding crocks and caddies serve rental housing and temporary dining setups.
- Wall-Mounted Racks:Rail and hook systems maximize surface area in compact urban dwellings.
- Modular Trays:Interlocking components allow reconfiguration across drawer sizes.
Drawer inserts dominate revenue; rotating organizers expand most quickly in commercial channels.
Capacity:
Customer type alignment links household composition to purchase sizing—empty nesters versus multi-generational families drive divergent SKU economics.
- Small (Under 20 Pieces):Compact configurations for studio apartments and secondary vacation homes. Singles and couples in German metropolitan housing stock favor these for standardized 40cm cabinet depths.
- Medium (20-40 Pieces):Standard family settings with service for 4-6 place settings.
- Large (40-60 Pieces):Extended family and entertaining-focused households.
- Extra Large (Above 60 Pieces):Institutional and hospitality procurement for banquet service.
Medium capacity leads unit volumes today; small capacity climbs fastest as urban densification accelerates.
Distribution Channel:
Supply concentration shapes access—captive manufacturing integrates with direct channels, while fragmented sourcing feeds multi-brand retail.
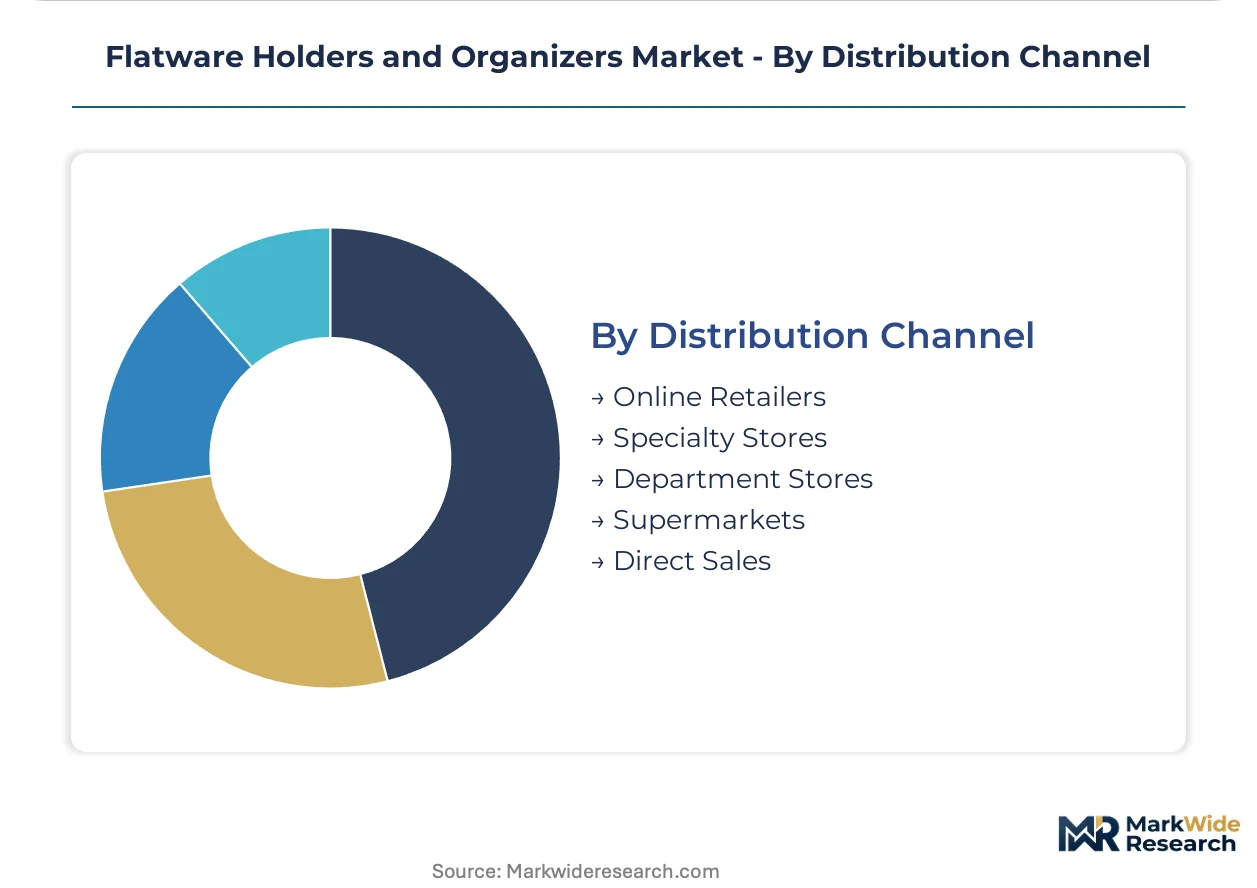
- Online Retailers:Platform algorithms and review aggregation drive discovery for replacement purchases. Amazon and Wayfair capture US aftermarket volume through 2-day delivery promises and dimensional search filters.
- Specialty Stores:Curated assortment and design consultation bundle flatware storage with full kitchen systems. Australian and Canadian boutique studios are displacing big-box channels where renovation permitting ties to energy efficiency audits.
- Department Stores:Licensed brand partnerships sustain mid-tier recognition.
- Supermarkets:Impulse and seasonal promotional placement for basic plastic variants.
- Direct Sales:Manufacturer-owned channels bypass retail margin extraction.
Online retailers lead transaction volumes today; specialty stores are expanding share fastest in renovation-driven markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Solingen's captive stainless steel processing clusters anchor specialized flatware organizer fabrication, while procurement patterns diverge across regulatory jurisdictions from EPA emission controls to EU Green Deal mandates.
United States
Residential kitchen renovation cycles compress replacement timelines for drawer insert systems. EPA volatile organic compound regulations push manufacturers toward water-based coatings or uncoated metal finishes. Big-box retail channels in the Midwest and Southeast dominate aftermarket volume through 2-day delivery infrastructure.
Germany
Compact urban dwellings in Berlin, Hamburg, and Munich drive demand for space-efficient drawer configurations standardized to 40cm cabinet depths. EU Green Deal procurement guidelines mandate FSC chain-of-custody certification for bamboo inputs in institutional tenders. Solingen's metal forming clusters insulate specialized producers from polymer input volatility.
France
Kitchen designers carrying certified sustainable sourcing credentials are displacing general contractors as specification authorities. REACH compliance restricts phthalates in soft-touch drawer liners, compelling silicone grip reformulation. Parisian boutique studios bundle flatware storage with full kitchen systems.
China
Stamping operations in the Yangtze River Delta region supply polymer molding and metal forming components. Dual carbon goals redirect manufacturer procurement toward recycled steel inputs. Port congestion and customs processing delays expose concentrated production footprints to shipping rate volatility.
Australia
Renovation permitting tied to energy efficiency audits concentrates demand in Melbourne and Sydney metropolitan markets. Specialty retailers displace big-box channels through curated assortment and design consultation. Magnetic utensil retention systems specified by Scandinavian-influenced kitchen designers penetrate 60% of new residential builds.
Flatware Holders and Organizers Market Competitive Landscape
Global majors compete with regional champions across material certification and captive manufacturing capabilities. The vendor base stratifies between vertically integrated metal processors, curated retail assemblers, and licensed brand distributors. Three archetypes dominate: Solingen-based stainless steel specialists, North American multi-brand retailers, and heritage tabletop licensors. Competitive moves concentrate on strategic partnerships for sustainable sourcing documentation and geographic expansion through design studio channels.
Among heritage tabletop specialists, Oneida Limited and Christofle occupy positions sustained through licensed distribution partnerships in North American and European department stores. The Container Store exemplifies the curated third-party assembler archetype, competing via assortment breadth rather than captive manufacturing. ZWILLING anchors the vertically integrated tier through in-house stainless steel processing in German equipment clusters.
| Leading Market Players |
|---|
| Oneida Limited |
| Christofle |
| Newell Brands |
| The Container Store |
| Lenox Corporation |
| Cambridge Silversmiths |
| Tramontina |
| ZWILLING |
| Knape & Vogt |
| Others |
Supply & Pricing Matrix
EU Green Deal procurement guidelines governing bamboo chain-of-custody certification now gate qualified supply access and premium-tier pricing eligibility, compressing supplier bases toward FSC-documented operations while stratifying price bands by sustainability credential tier.
Pricing Analysis
Input-cost pass-through from certified bamboo premiums and recycled steel procurement reshapes tiered pricing across material grades. Price differentiation hinges on FSC documentation status and captive Solingen metal forming capabilities, with German cabinetry OEMs absorbing 12-18% landed cost premiums for verified sustainable sourcing. Pricing pressure intensifies in mass-market polymer segments as EPA volatile organic compound compliance mandates capital redeployment toward water-based coating lines. Big-box retail channels exhibit highest price sensitivity, while specification-driven kitchen designers prioritize dimensional precision over unit cost.
Supply Chain Analysis
Freight rate volatility and port congestion exposure from Yangtze River Delta stamping operations is accelerating geographic diversification toward Solingen metal clusters and Southeast Asian polymer molding alternatives. Raw material flows draw from Indonesian laminated bamboo plantations, German 304-grade stainless sheet mills, and Guangdong injection molding compounds. Single-source vulnerability concentrates in East Asian concentrated production footprints facing customs processing delays. Distribution runs through direct OEM specification channels for integrated cabinetry and platform algorithms for aftermarket replacement purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal institutional tender mandates represent a regulatory compounder, with FSC chain-of-custody requirements now disqualifying uncertified suppliers from German and French public-sector food service equipment procurement.
For Market Incumbents: Extend captive certification capabilities upstream into Indonesian and Vietnamese bamboo forestry operations to insulate margin structures from 12-18% landed cost premiums threatening non-integrated competitors. Deepen magnetic retention system R&D to consolidate mid-tier and premium price bands before Scandinavian specification standards diffuse into Australian and North American markets. Solingen-based metal forming clusters provide defensible positioning against polymer input volatility. For New Entrants and Emerging Players: Capture white-space in modular tray configurations for standardized 40cm German cabinet depths, where urban densification compresses replacement timelines and boutique design studios displace big-box channels. Target Australian metropolitan markets where renovation permitting tied to energy efficiency audits concentrates demand in specialty retail consultation models. Lead with curated third-party assortment strategies that bypass captive manufacturing investments while bundling flatware storage with full kitchen systems. For Investors and Strategic Acquirers: Roll-up economics work for vertically integrated bamboo forestry-to-fabrication specialists because EU Green Deal documentation requirements are compressing supplier bases and awarding scale advantages in institutional tender eligibility. Five-to-ten-year viability favors operations with FSC chain-of-custody control and CNC routing talent access in German or Italian equipment clusters. Monitor extended producer responsibility framework adoption across multiple jurisdictions as circular certification inflection signal determining end-of-life cost allocation winners.| Strategic Initiative | Industry Significance |
|---|---|
| FSC Chain-of-Custody Certification | EU Green Deal institutional tenders now mandate documentation, disqualifying uncertified German and French suppliers. |
| Captive Bamboo Forestry Integration | Upstream control over Indonesian plantations insulates producers from 12-18% landed cost premiums hitting importers. |
| Magnetic Retention System R&D | Scandinavian kitchen designers specify these for 60% of new builds, consolidating mid-premium price bands. |
| Specialty Design Studio Channel Expansion | Australian and Canadian boutique studios displace big-box channels where renovation permitting ties to energy audits. |
| Extended Producer Responsibility Compliance | Emerging circular certification frameworks will reward modular designs with end-of-life collection cost advantages. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with kitchen designers, cabinetry OEM procurement leads, flatware organizer brand managers, and specialty retail category buyers with secondary validation against customs trade records, EU tender databases, and EPA regulatory filings. Bottom-up SKU-level volume aggregation and top-down macroeconomic scaling were cross-checked for triangulation consistency.
Segment-weighting approaches distributed value and volume projections across material type, design style, capacity tier, and distribution channel dimensions throughout the forecast period. CAGRs were derived from regression analysis against residential renovation cycle indicators and regulatory adoption curves. Industry-specific inputs included German cabinet dimension standardization rates and REACH phthalate restriction implementation timelines.
Underlying measurement precision varies by segment; drawer insert and rotating organizer categories carry tighter precision than countertop holder estimates due to specification channel visibility. Forecasts reflect assumptions about EU Green Deal procurement guideline enforcement intensity and extended producer responsibility framework rollout timing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Storage and Organization
Shoe Storage and Organizers Market
Home Storage and Organization
Toy Storage Market
Home Storage and Organization
Regency Shelving Market
Home Storage and Organization
United Kingdom Home Decor Market
Home Storage and Organization
Display Cabinets Market
Home Storage and Organization
Smart Shoe Cabinet Market
Home Storage and Organization
Kitchen Storage Market
Home Storage and Organization
Hong Kong Self-Storage Market
Home Storage and Organization
Shelf Display Trays Market
Home Storage and Organization
Tool Chest Market
Home Storage and Organization
Cabinet & Furniture Drawer Slides Market
Home Storage and Organization
Scandinavia Self-Storage Market
Home Storage and Organization
Closet Organizers Market
Home Storage and Organization
Jewelry Organizer Market
Home Storage and Organization
Flush Mount Photo Album Market
Home Storage and Organization
Shoe Rack Market