
 Cabinet & Furniture Drawer Slides Market | 2026-2036
Cabinet & Furniture Drawer Slides Market Size, Share, and Industry Trends Forecast 2026-2036
Cabinet & Furniture Drawer Slides Market Insights
Soft-close damping integration is tilting engineering priorities across the drawer slides industry. Blum Inc. leverages Austrian R&D intensity to dominate European premium kitchen fit-outs. Hettich Holding GmbH & Co. KG anchors German manufacturing scale across automated batch production lines. King Slide Works Co. Ltd. competes on Taiwanese precision metal stamping for North American contract furniture suppliers.
Cabinet and furniture drawer slides are mechanical extension devices, typically fabricated from cold-rolled steel with zinc or epoxy surface treatments, that enable linear withdrawal and retraction of storage compartments while managing load capacities from fifteen to over two hundred pounds. Their primary purpose is to deliver smooth, repeatable motion control in residential kitchens, commercial casework, medical storage, and industrial workstations. Soft-close and ball-bearing mechanisms now capture the bulk of replacement demand in residential end-use, while under-mount installation types command margin premiums through concealed hardware aesthetics. Metal construction still occupies volume leadership, though composite materials are gaining specification in moisture-prone commercial environments.
EPA guidelines govern volatile organic compound emissions from powder-coating operations, while REACH restricts hazardous substances in European-sourced metal finishes. China's GB standards and the EU's RoHS directive together shape export eligibility for Asian manufacturers serving dual markets. Stakeholders must monitor evolving material compliance thresholds and decide whether to regionalize coating capacity or consolidate under unified formulation platforms.
Market Dynamics
Soft-close damping technology is compressing replacement cycles across residential kitchen and commercial casework installations, while precision stamping capacity concentrates in Taiwanese and Chinese export clusters serving North American and European OEM buyers.
Growth Catalysts
- Residential kitchen renovation spending:North American homeowners are refreshing cabinetry hardware at shorter intervals, pulling demand for ball-bearing and under-mount slide configurations.
- REACH compliance in Europe:Tighter material specifications for coated steel finishes are accelerating specification upgrades toward premium epoxy treatments that exceed baseline regulatory thresholds.
- Medical storage casework:Hospital and clinic construction in moisture-prone environments is specifying corrosion-resistant slide mechanisms with enhanced load ratings.
Market Restraints
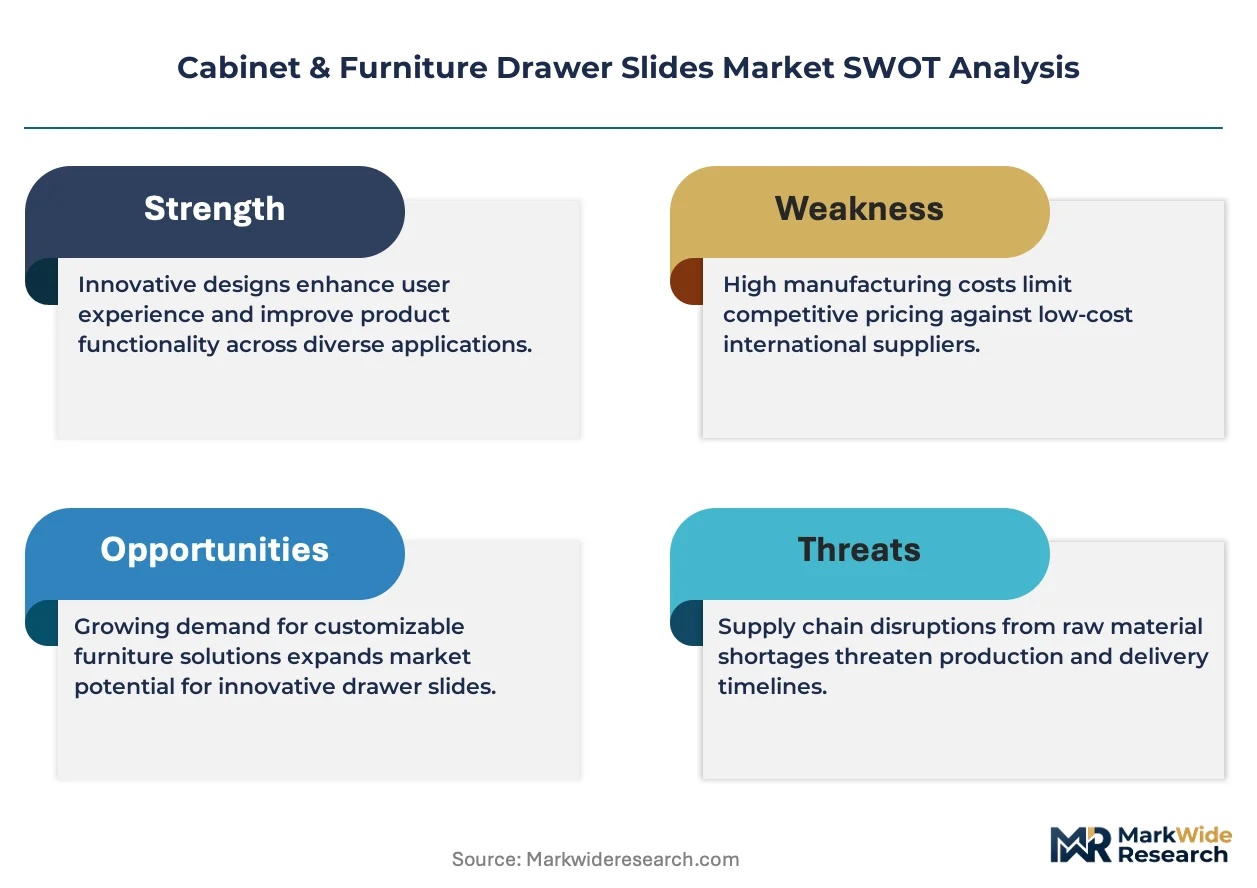
- Cold-rolled steel price volatility:Input cost swings for zinc-coated steel strip constrain margin stability for mid-tier stamping operations.
- Taiwanese supply concentration:Precision metal forming capacity clusters heavily around Taichung and Kaohsiung, creating geographic vulnerability to regional logistics disruptions.
- Polymer substitution limits:Composite slide materials face load-bearing constraints above fifty pounds, capping penetration in heavy-duty industrial workstations.
Strategic Opportunities
- Underpenetrated Southeast Asian furniture manufacturing:Vietnam and Indonesia are scaling cabinet export capacity without captive slide supply, creating white space for component suppliers.
- EPA guideline evolution:Anticipated tightening of volatile organic compound limits for powder-coating operations will favor early movers with low-VOC formulation platforms.
- Smart kitchen integration:Convergence of soft-close mechanisms with sensor-activated drawer systems is opening specification channels among premium appliance-integrated cabinetry lines.
Industry Challenges
- Precision stamping talent scarcity:Tool and die engineering expertise is concentrating at aging specialist shops in Taiwan and southern Germany, constraining capacity expansion.
- Dual certification timelines:Simultaneous pursuit of EPA compliance for US-bound product and REACH registration for European eligibility extends new product introduction cycles.
- Legacy inventory complexity:OEM buyers maintain multi-year service part commitments for discontinued slide generations, fragmenting production scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cabinet & Furniture Drawer Slides Market |
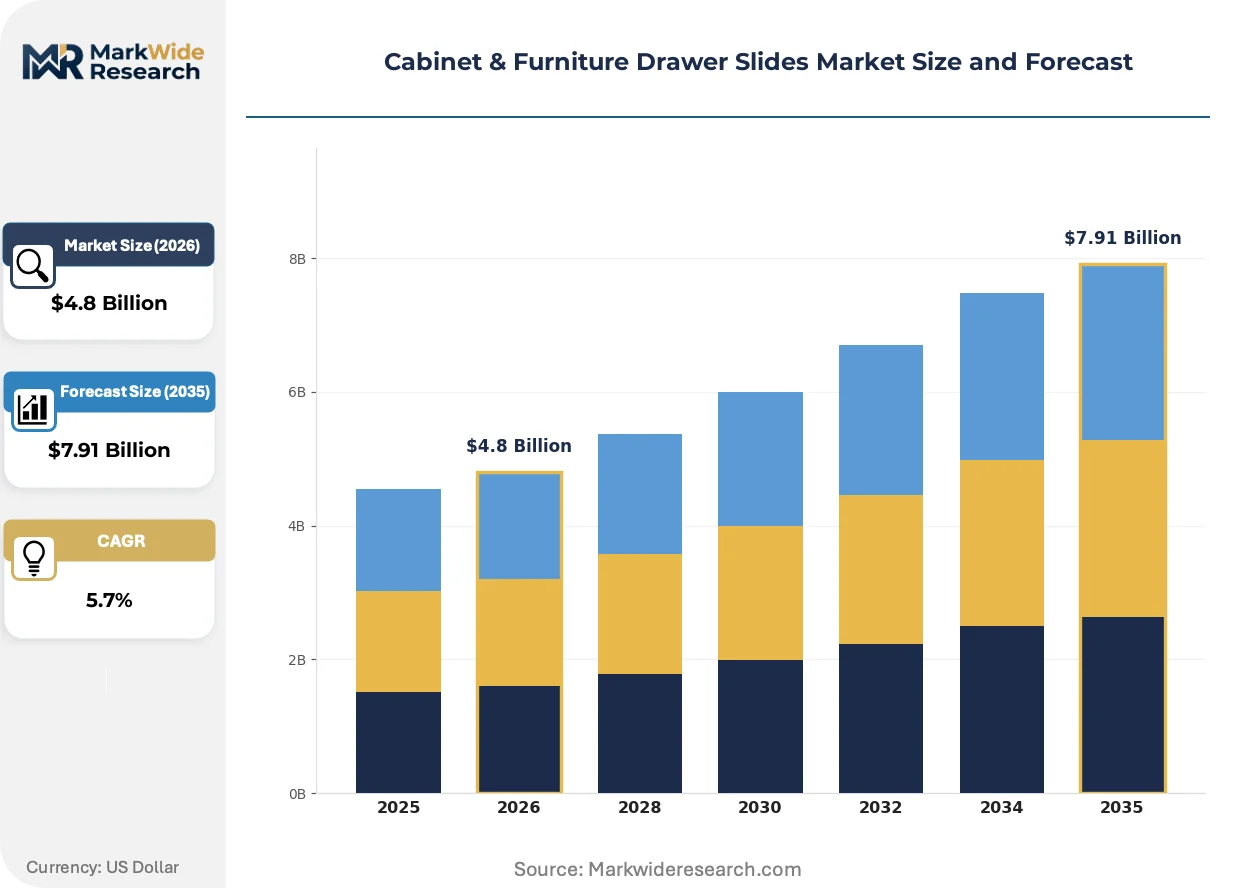
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slide Mechanism, Ball Bearing, Roller, Soft Close Material: Metal, Plastic, Composite, Wood Installation Type: Under-Mount, Side-Mount, Top-Mount, Inset End User: Residential, Commercial, Industrial, Custom Furniture |
| Companies Covered | Blum Inc., Hettich Holding GmbH & Co. KG, Accuride International Inc., Grass GmbH & Co., King Slide Works Co. Ltd., Knape & Vogt, Fulterer, Hafele GMBH & CO KG, Titus Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cabinet & Furniture Drawer Slides Market Trends and Innovations
Material science advances and regulatory stringency are reshaping how drawer slide manufacturers balance load performance, surface durability, and environmental compliance across divergent regional standards.
Hybrid polymer-steel composite slide rails are hybridizing traditional metal construction with fiber-reinforced nylon bearing surfaces. Medical storage and marine cabinetry specifiers are adopting these configurations for corrosion immunity in salt-air or sterilization environments. The technology is hybridizing supplier portfolios, forcing metal-centric stampers to develop polymer overmolding partnerships or captive plastic injection capacity.
REACH Annex XVII restrictions on chromium VI in metal finishes are compelling coating reformulation across European-bound production. Powder-coating operations in China and Taiwan are migrating toward trivalent chrome and zirconium-based pretreatment systems. German kitchen OEMs are most affected, demanding batch-level compliance documentation that extends supplier qualification timelines.
Direct procurement from stamping specialists is displacing traditional hardware distributor intermediaries among large North American contract furniture manufacturers. Volume buyers are consolidating supplier panels and negotiating multi-year blanket orders with Taiwanese precision metal formers. This pattern is most visible in California and Texas, where regional cabinetry clusters have scaled sufficiently to justify container-direct import logistics.
Cabinet & Furniture Drawer Slides Market Segmentation
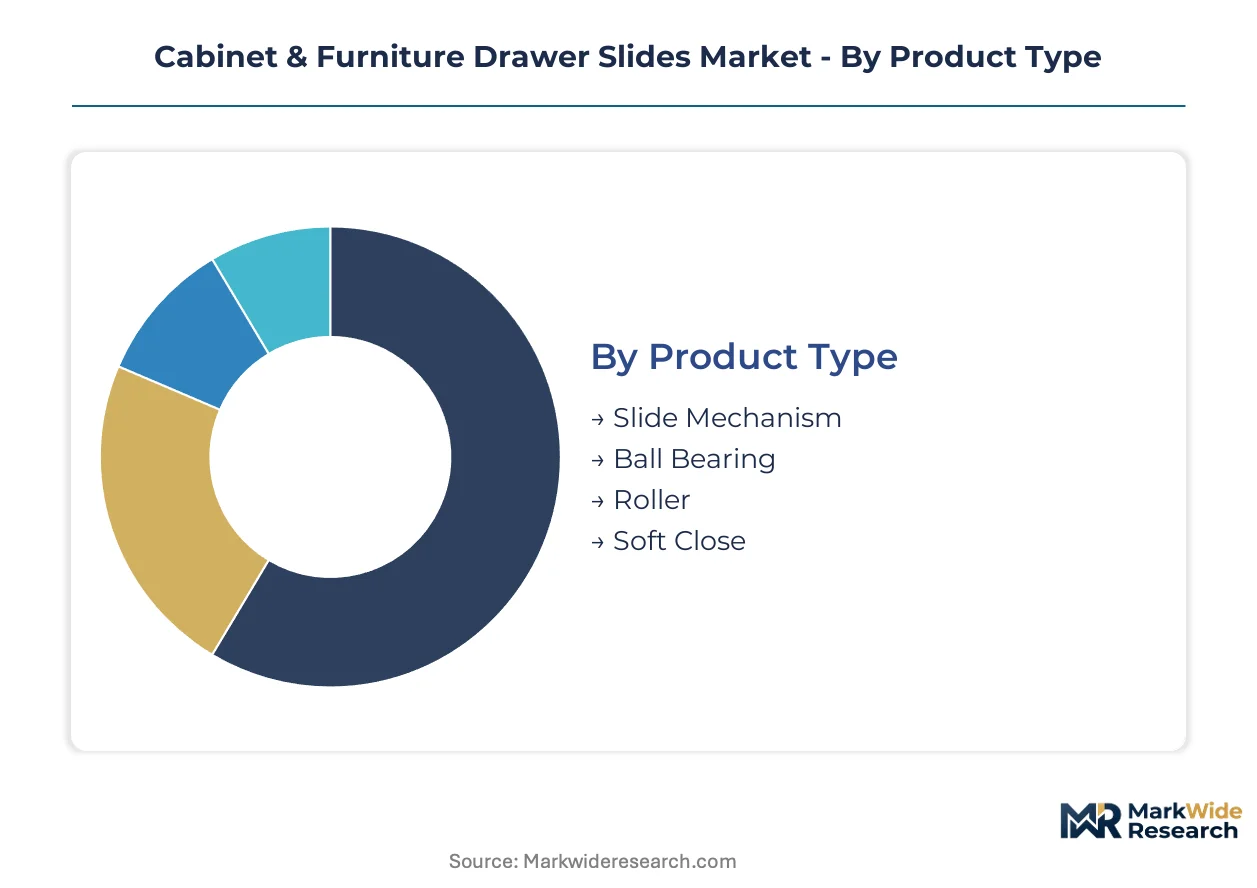
Drawer slide segmentation reveals how engineering specifications, material choices, and installation methods align with distinct after-sales service intensities. Residential kitchen installations demand frequent hardware replacement cycles, while commercial casework contracts impose multi-year service part commitments that fragment production scheduling.
Product Type:
After-sales service intensity varies sharply across mechanism designs, with soft-close systems requiring specialized damping component replacement versus simple roller refurbishment.
- Ball Bearing:Steel raceways with hardened ball elements deliver load capacities exceeding two hundred pounds. Demand concentrates in North American residential kitchen renovations where homeowners upgrade from roller mechanisms during cabinetry refreshes. Cold-rolled steel price volatility constrains margin stability for mid-tier stamping operations supplying this segment.
- Soft Close:Integrated hydraulic or pneumatic damping cylinders arrest drawer motion during final centimeters of closure. Hospital and clinic construction in moisture-prone environments specifies these mechanisms for noise reduction in patient care areas. REACH Annex XVII restrictions on chromium VI in metal finishes compel coating reformulation for European-bound production.
- Slide Mechanism:Basic extension rails without anti-rebound features dominate economy furniture production.
- Roller:Nylon wheel assemblies on stamped steel channels serve price-sensitive contract furniture.
Ball bearing holds the largest share; momentum sits with soft close.
Material:
Cost tier stratification separates premium metal construction from emerging polymer alternatives in moisture-critical applications.
- Metal:Cold-rolled steel with zinc or epoxy surface treatments occupies volume leadership across residential and commercial end-uses. Taiwanese precision metal stamping clusters in Taichung and Kaohsiung supply North American OEM buyers with batch-level compliance documentation.
- Composite:Fiber-reinforced nylon bearing surfaces hybridized with steel substrates gain specification in marine cabinetry and medical storage for corrosion immunity. Composite materials face load-bearing constraints above fifty pounds, capping penetration in heavy-duty industrial workstations.
- Plastic:Injection-molded polymer rails serve lightweight residential applications with minimal load requirements.
- Wood:Traditional wooden runners persist in heritage furniture restoration and artisan craft segments.
Metal dominates volume; composite climbs the fastest on corrosion resistance specifications.
Installation Type:
Volume concentration in side-mount configurations contrasts with margin premiums captured through concealed hardware aesthetics.
- Under-Mount:Concealed rail systems mounted beneath drawer boxes command specification premiums through invisible hardware aesthetics. German kitchen OEMs anchor demand for precision-tolerance under-mount mechanisms in premium European fit-outs.
- Side-Mount:Traditional lateral rail attachment dominates replacement demand and economy new construction. California and Texas cabinetry clusters source container-direct from Taiwanese stampers to serve volume residential production.
- Top-Mount:Overhead rail configurations accommodate specialized file storage and lateral drawer applications.
- Inset:Flush-face drawer designs require precision tolerances for seamless cabinet integration.
Side-mount holds the largest share; under-mount gains share fastest on premium kitchen specifications.
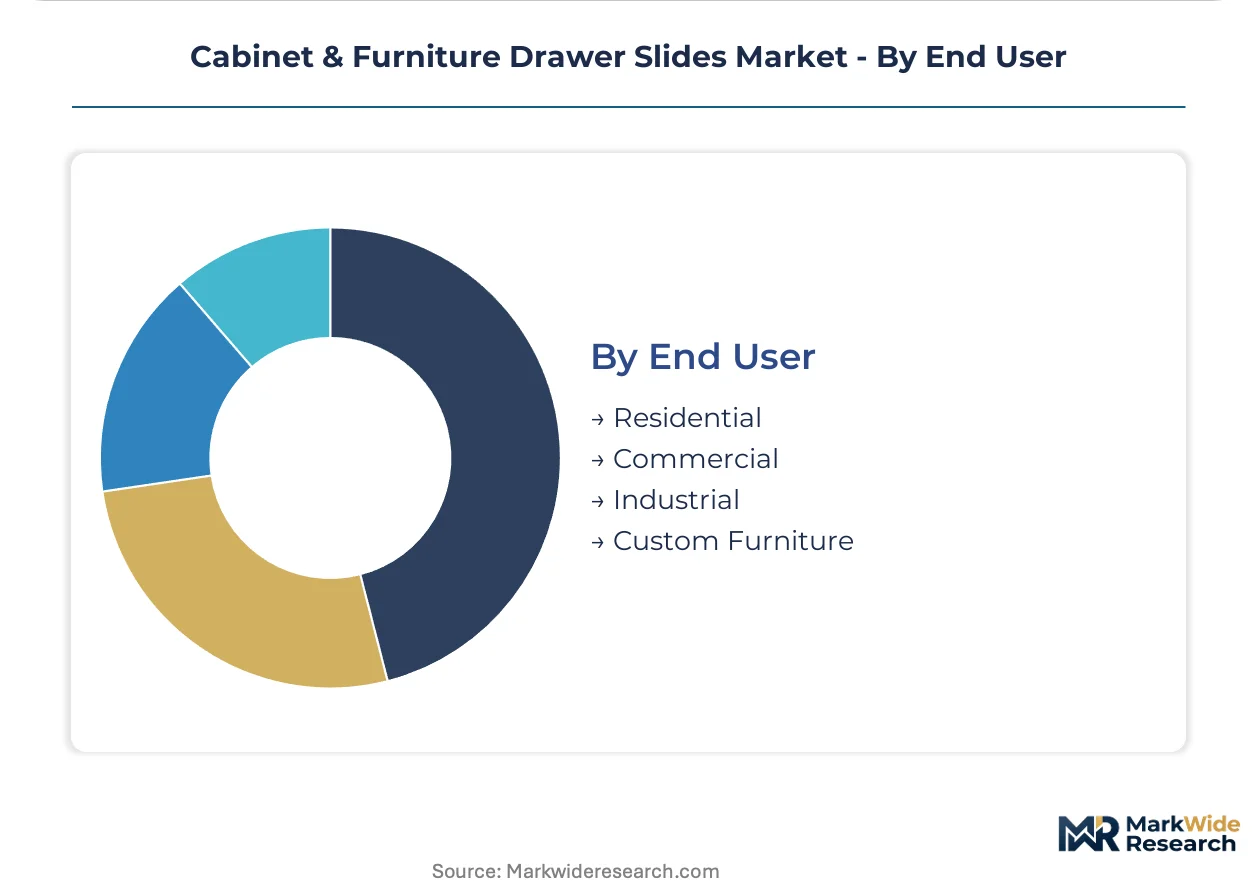
End User:
Customer type determines procurement patterns, with residential renovation cycles contrasting against industrial capital equipment procurement timelines.
- Residential:Kitchen renovation spending pulls demand for ball-bearing and under-mount configurations at shortened replacement intervals. North American homeowners refresh cabinetry hardware independently of full kitchen reconstruction.
- Commercial:Hospital and clinic construction specifies corrosion-resistant slide mechanisms with enhanced load ratings for medical storage casework. EPA guidelines on volatile organic compound emissions from powder-coating operations constrain supplier qualification.
- Industrial:Heavy-duty workstations demand load capacities exceeding two hundred pounds with extended cycle life specifications.
- Custom Furniture:Artisan and bespoke producers require flexible order quantities with specialized finish matching.
Residential holds the largest share; commercial shows steepest expansion trajectory on healthcare construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwanese precision metal stampers in Taichung and Kaohsiung export container-direct to North American cabinetry clusters in California and Texas, while Chinese manufacturers serve European OEM buyers through dual REACH and RoHS certification pipelines.
United States
Residential kitchen renovation spending in California and Texas pulls demand for ball-bearing and under-mount slide configurations. EPA guidelines on volatile organic compound emissions from powder-coating operations constrain supplier qualification timelines. Container-direct procurement from Taiwanese stampers is displacing traditional hardware distributor intermediaries among large contract furniture manufacturers in these states.
Germany
German kitchen OEMs anchor European premium fit-out demand for precision-tolerance under-mount mechanisms. REACH Annex XVII restrictions on chromium VI in metal finishes compel coating reformulation across European-bound production. Manufacturing scale concentrates in automated batch production lines serving automated kitchen furniture assembly.
China
Export manufacturing clusters scale precision stamping capacity for North American and European OEM buyers. GB standards and the EU's RoHS directive together shape export eligibility for Asian manufacturers serving dual markets. Yangtze River Delta and Pearl River Delta production hubs are regionalizing coating capacity to manage divergent regulatory thresholds.
Taiwan
Precision metal forming capacity clusters heavily around Taichung and Kaohsiung, supplying North American contract furniture suppliers with batch-level compliance documentation. Geographic concentration creates vulnerability to regional logistics disruptions. Tool and die engineering expertise is concentrating at aging specialist shops, constraining capacity expansion.
Vietnam
Underpenetrated cabinet export manufacturing is scaling without captive slide supply, creating white space for component suppliers. Furniture production growth in Ho Chi Minh City and Hanoi industrial zones outpaces local hardware sourcing infrastructure. Component suppliers are establishing direct procurement relationships with Vietnamese exporters previously served through distributor networks.
Cabinet & Furniture Drawer Slides Market Competitive Landscape
On the supply side, the industry is tiered between premium European engineering specialists, high-volume Asian metal stampers, and mid-market regional fabricators. Strategic archetypes include Austrian R&D-intensive soft-close innovators, Taiwanese precision stamping exporters, and German manufacturing scale operators. Competitive moves center on geographic expansion through direct procurement relationships and technology licensing for damping mechanism integration.
Within the premium engineering tier, Blum Inc. and Hettich Holding GmbH & Co. KG exemplify European R&D intensity and manufacturing scale respectively. King Slide Works Co. Ltd. occupies a position among Taiwanese precision metal stamping specialists serving North American contract furniture channels. These three anchors illustrate how geographic specialization—Austrian innovation, German automation, Taiwanese metal forming—maps to distinct value chain positions without vertical integration into adjacent component categories.
| Leading Market Players |
|---|
| Blum Inc. |
| Hettich Holding GmbH & Co. KG |
| Accuride International Inc. |
| Grass GmbH & Co. |
| King Slide Works Co. Ltd. |
| Knape & Vogt |
| Fulterer |
| Hafele GMBH & CO KG |
| Titus Group |
| Others |
Pricing and Supply Chain Analysis
Taiwanese precision metal stamping clusters in Taichung and Kaohsiung anchor global cold-rolled steel slide supply, concentrating margin capture with volume OEM buyers who negotiate container-direct terms. This upstream concentration funnels pricing power toward large North American contract furniture manufacturers while fragmenting margin pools for mid-tier distributors.
Pricing Analysis
Soft-close damping mechanisms command 40-60% premiums over basic roller configurations, while under-mount concealed systems price above side-mount alternatives by similar magnitude. Three-tier pricing structure across premium, standard, and economy levels reflects load capacity ratings, surface treatment durability, and batch-level compliance documentation. Pricing pressure stems from cold-rolled steel input volatility and REACH-driven coating reformulation costs. Residential renovation buyers show highest price sensitivity, while medical storage specifiers prioritize corrosion resistance over unit cost.
Supply Chain Analysis
Extended payment terms from North American OEM buyers now stretch 90-120 days, forcing Taiwanese stampers to utilize supply-chain finance facilities or absorb working capital strain. Manufacturing concentrates in Taiwan, China, and Germany, with raw material dependencies on cold-rolled steel strip, zinc coatings, and hydraulic damping cylinders. Single-source vulnerability concentrates in precision tool-and-die engineering expertise aging out of Taichung specialist shops. Distribution runs through direct procurement relationships displacing traditional hardware distributor networks among volume buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Residential kitchen renovation cycles position this market for cyclical recovery as housing turnover accelerates and homeowner discretionary spending redirects toward cabinetry refreshes.
For Market Incumbents: Harden supply chain resilience through dual-source stamping partnerships outside Taiwan's Taichung-Kaohsiung corridor to mitigate geographic concentration risk. Invest in captive polymer overmolding capacity or strategic partnerships to capture hybrid composite specification growth in medical and marine end-uses. Prioritize REACH-compliant coating platform consolidation to streamline dual-certification timelines for European and North American eligibility. For New Entrants and Emerging Players: Vietnamese cabinet export manufacturing zones around Ho Chi Minh City and Hanoi represent the most penetrable entry point, with furniture production growth outpacing local hardware infrastructure. Target direct procurement relationships with scaling exporters previously served through distributor intermediaries. Lead with REACH- and EPA-compliant coating platforms to differentiate against legacy Asian suppliers burdened by reformulation lag. For Investors and Strategic Acquirers: Capital is best deployed toward precision stamping specialists with proven OEM direct procurement relationships and batch-level compliance documentation capabilities. Long-term viability hinges on exposure to medical storage and premium kitchen renovation end-uses rather than commodity contract furniture. Watch for EPA guideline tightening on volatile organic compound limits as inflection signal favoring early movers with low-VOC formulation platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Platform Consolidation | Unified REACH- and EPA-compliant formulations reduce dual-certification timelines for European and North American eligibility. |
| Polymer Overmolding Partnership | Hybrid composite slide production captures medical and marine specification growth beyond traditional metal construction limits. |
| Direct Procurement Expansion | Container-direct relationships with Vietnamese cabinet exporters displace distributor intermediaries in underpenetrated Southeast Asian manufacturing. |
| Tool-and-Die Engineering Investment | Captive precision stamping capacity addresses talent scarcity constraining expansion at aging Taiwanese specialist shops. |
| Smart Kitchen Integration Development | Sensor-activated drawer system partnerships open specification channels among premium appliance-integrated cabinetry lines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cabinet OEM procurement directors, furniture manufacturing plant managers, hardware distributor category buyers, and precision stamping operations executives. Secondary validation drew from customs trade databases, EPA regulatory filings, ECHA REACH registration data, and industry association technical specifications. Bottom-up volume modeling across product type, material, installation method, and end-use segments was triangulated against top-down market sizing from trade flow analysis.
Calibration against historical production capacity utilization rates and input cost indices anchored the analytical framework across the analysis window. Segmentation dimensions modeled include mechanism design, load capacity tier, surface treatment specification, and regional regulatory cluster. CAGRs were derived from regression analysis of renovation spending correlation with replacement cycle compression. Forecast inputs incorporated cold-rolled steel price trajectory assumptions and healthcare construction pipeline tracking.
Macroeconomic conditions sit as an overlay; deviation in housing turnover rates, mortgage interest levels, or construction material cost indices would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation timelines and technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Storage and Organization
Scandinavia Self-Storage Market
Home Storage and Organization
Regency Shelving Market
Home Storage and Organization
Shop Shelving Market
Home Storage and Organization
Asia-Pacific Digital Home Locker Market
Home Storage and Organization
Smart Shoe Cabinet Market
Home Storage and Organization
Kitchen Storage Market
Home Storage and Organization
Slipcases Market
Home Storage and Organization
Small Space Furniture Market
Home Storage and Organization
Display Cabinets Market
Home Storage and Organization
Shoe Rack Market
Home Storage and Organization
Shelf Display Trays Market
Home Storage and Organization
Clothes Closets Market
Home Storage and Organization
Shoe Storage and Organizers Market
Home Storage and Organization
Smart Storage Cabinet Market
Home Storage and Organization
Europe Home Organizers and Storage Market
Home Storage and Organization
United Kingdom Home Decor Market