
 Shelf Display Trays Market | 2026-2036
Shelf Display Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Shelf Display Trays Market Analytics
Germany is rewriting capacity dynamics for European shelf display tray supply as domestic converters expand thermoforming and injection molding operations to serve discount grocery chains. HL Display AB leverages its Nordic manufacturing base to sustain premium positioning across pharmacy and specialty retail channels. Winpak Ltd. competes through advanced barrier film integration for food-contact display applications. LINPAC Packaging anchors volume production of reusable pool trays for supermarket produce sections across the Benelux region.
Shelf display trays are rigid or semi-rigid containers engineered from thermoformed plastics, folded paperboard, stamped metal, or composite laminates, typically featuring raised edges, stacking lugs, and standardized footprint dimensions for palletized distribution. Their primary commercial purpose is to present merchandise at point-of-sale while protecting inventory during transport, replenishment, and customer handling. Plastic trays dominate unit volume due to durability and washability in closed-loop retail systems, though cardboard segments are gaining structural importance as retailers face ESG-driven packaging reduction targets. Custom design types command margin premiums by accommodating irregular product geometries and brand-specific color systems, while tiered configurations capture growth in vertical merchandising for space-constrained urban stores.
EU REACH restrictions on phthalates and heavy metal stabilizers directly constrain polymer formulation choices for food-contact display trays, while CE marking requirements govern mechanical safety in automated handling environments. Germany's national packaging law, implementing the EU Packaging and Packaging Waste Directive, mandates minimum recycled content thresholds that reshape material procurement for cardboard and plastic tray producers. Stakeholders must monitor evolving extended producer responsibility fee structures and recyclability labeling rules to align product portfolios with compliance cost trajectories.
Market Dynamics
The Shelf Display Trays Market is experiencing structural compression from EU Green Deal packaging mandates that favor recyclable cardboard and molded fiber alternatives over conventional plastics, forcing converters to retool thermoforming lines and requalify material specifications for supermarket produce and pharmacy channels.
Growth Catalysts
- EU Packaging and Packaging Waste Directive:Germany's national packaging law mandates minimum recycled content thresholds, compelling retailers to source display trays from certified circular material streams.
- Discount grocery expansion:Aldi and Lidl store format proliferation across Central Europe drives standardized tray footprints for automated replenishment systems.
- Molded fiber thermoforming:Wet-press fiber molding technology achieves structural parity with plastic at lower unit cost for short-use produce applications.
Market Restraints
- Polymer formulation constraints:ECHA REACH restrictions on phthalates and heavy metal stabilizers limit food-contact polymer choices and extend R&D qualification timelines.
- Raw material volatility:OCC (old corrugated containers) price swings disrupt molded fiber tray margins for converters dependent on spot pulp markets.
- Capital intensity:Automated thermoforming lines for thin-gauge PET require seven-figure capital commitments that exclude smaller regional converters.
Strategic Opportunities
- Benelux reusable pool systems:LINPAC-style closed-loop tray pooling for supermarket produce sections remains underpenetrated in France and Spain.
- Pharmacy cold-chain display:Temperature-stable PP trays with integrated RFID tracking address specialty pharmaceutical distribution requirements.
- EU Ecodesign for Sustainable Products Regulation:Upcoming digital product passport requirements create first-mover advantage for traceability-integrated tray suppliers.
Industry Challenges
- Skills deficit in fiber molding:Wet-press thermoforming technicians with food-contact hygiene certification command premium wages and limited availability.
- Legacy ERP integration:Batch-oriented manufacturing execution systems at mid-tier converters struggle to support mass-customization workflows for private-label retail programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shelf Display Trays Market |
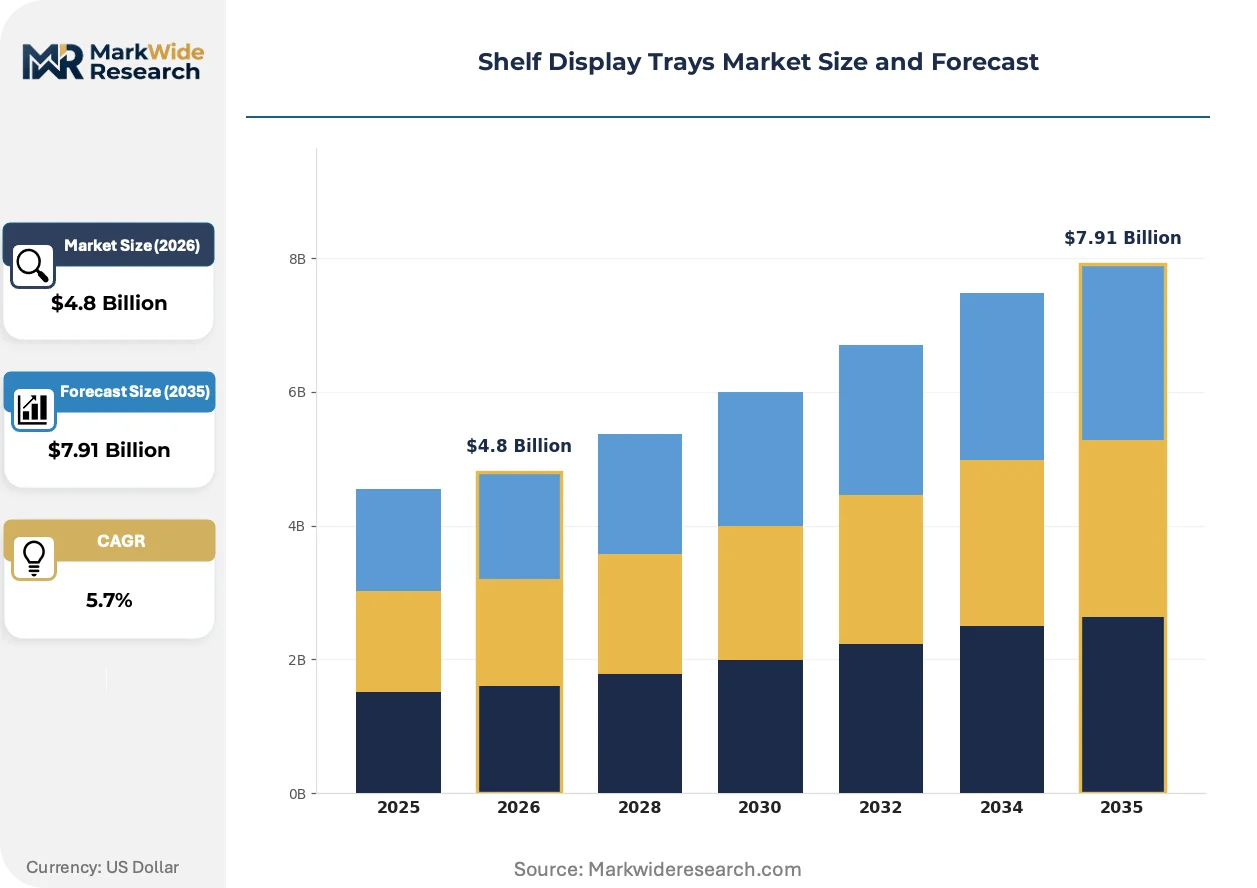
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Metal, Wood, Cardboard End User: Retail Stores, Supermarkets, Pharmacies, Specialty Shops Size: Small, Medium, Large, Extra Large Design Type: Vertical, Horizontal, Tiered, Custom |
| Companies Covered | HL Display AB, Winpak Ltd., LINPAC Packaging, HPM Global Inc., Euro Pool System, Delkor Systems, Inc., Valley Plastics, Inc., BES Packaging Corp., ARTPLEX Jerzy Kalinowski, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shelf Display Trays Market Evolving Landscape
Digital design workflows and material science advances are compressing product development cycles while regulatory pressure accelerates substitution away from petroleum-based substrates toward bio-based and recycled alternatives.
Digital twin simulation software is virtualizing tray structural validation before physical tooling commitment. Retail fixture manufacturers in Germany and the Netherlands deploy finite element analysis to optimize stacking strength and nesting density for palletized distribution. This capability is virtualizing traditional prototype-and-test cycles that previously consumed twelve to sixteen weeks.
ECHA's evolving restrictions on intentionally added microplastics reshape polymer selection for display trays with abrasive surfaces or slip-resistant coatings. The regulation forces compounders to reformulate masterbatches and validate alternative surface treatments. Food-contact applications face the steepest compliance cost trajectory as migration testing protocols expand.
Supermarket category managers now specify tray performance through total cost of ownership metrics rather than unit purchase price. German discount chains evaluate washing durability, nesting ratio, and automated handling compatibility in unified scorecards. This procurement recalibration favors durable PP and PET trays over single-use cardboard in high-velocity produce categories.
Shelf Display Trays Market Segmentation
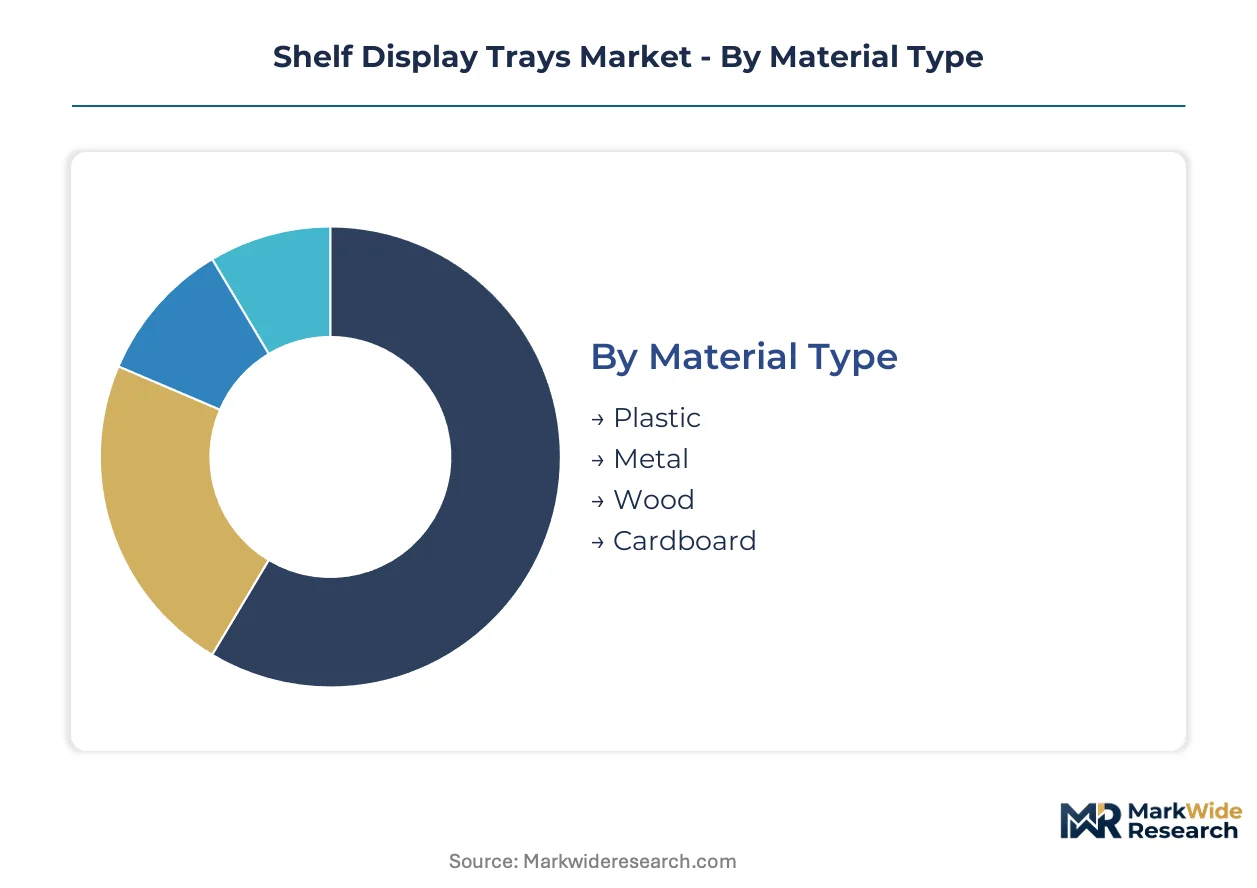
Shelf display trays serve divergent operational requirements across retail formats, from automated replenishment systems in discount grocery to brand-controlled fixtures in specialty channels. Material selection and dimensional specifications directly determine compatibility with existing logistics infrastructure and regulatory compliance obligations.
Material Type:
Cost tiers stratify sharply between virgin polymer formulations and recycled fiber alternatives, with washing durability and ESG credentials driving procurement recalibration.
- Plastic:Thermoformed PET and PP formulations dominate closed-loop retail systems through washability and mechanical resilience. German discount chains specify these for high-velocity produce categories where automated handling compatibility and nesting density determine total cost of ownership.
- Cardboard:Recycled-content corrugated and solid fiberboard variants gain structural importance under EU Green Deal mandates, with wet-press molded fiber achieving cost parity for short-use applications. ECHA REACH compliance on food-contact barriers constrains coating chemistry selection.
- Metal:Stamped aluminum and steel trays serve premium cosmetic and electronics displays requiring magnetic fixture compatibility and extended service life.
- Wood:Finished hardwood and plywood constructions address specialty retail and farmers market segments where tactile aesthetics override logistics efficiency.
Established volume favors Plastic; emerging adoption favors Cardboard.
End User:
Application intensity varies by replenishment velocity and regulatory exposure, with food-contact and pharmaceutical channels imposing distinct material qualification protocols.
- Supermarkets:Automated distribution centers and standardized shelf modules drive demand for uniform footprint dimensions and RFID-traceable pool trays. Aldi and Lidl format proliferation across Central Europe reinforces specification convergence.
- Pharmacies:Temperature-stable display configurations with integrated cold-chain monitoring address specialty pharmaceutical distribution. HL Display AB and comparable suppliers configure premium positioning through compliance with EMA serialization requirements.
- Retail Stores:Department and convenience formats balance durability against capital efficiency, with seasonal promotional cycles favoring lower-unit-cost cardboard over reusable plastic.
- Specialty Shops:Brand-controlled environments specify custom color systems and irregular geometries that command margin premiums from dedicated converter relationships.
Procurement concentration sits with Supermarkets; compliance complexity peaks with Pharmacies.
Size:
Volume throughput and shelf depth constraints determine dimensional specification, with palletization standards limiting deviation from modular footprints.
- Medium:Standard European pallet dimensions and retail shelf depths align procurement around this specification, capturing the majority of supermarket produce and packaged goods applications.
- Large:Bulk merchandise and club store formats drive demand for expanded capacity with reinforced stacking strength, particularly in Benelux distribution networks.
- Small:Countertop confectionery and cosmetics displays favor compact footprints with high visual density for impulse purchase environments.
- Extra Large:Seasonal promotional displays and garden center applications accommodate oversized merchandise with specialized handling equipment requirements.
Operational standardization anchors Medium specifications; promotional flexibility expands Small and Extra Large adoption.
Design Type:
Margin structure separates commoditized horizontal configurations from engineered vertical and custom systems requiring dedicated tooling investment.
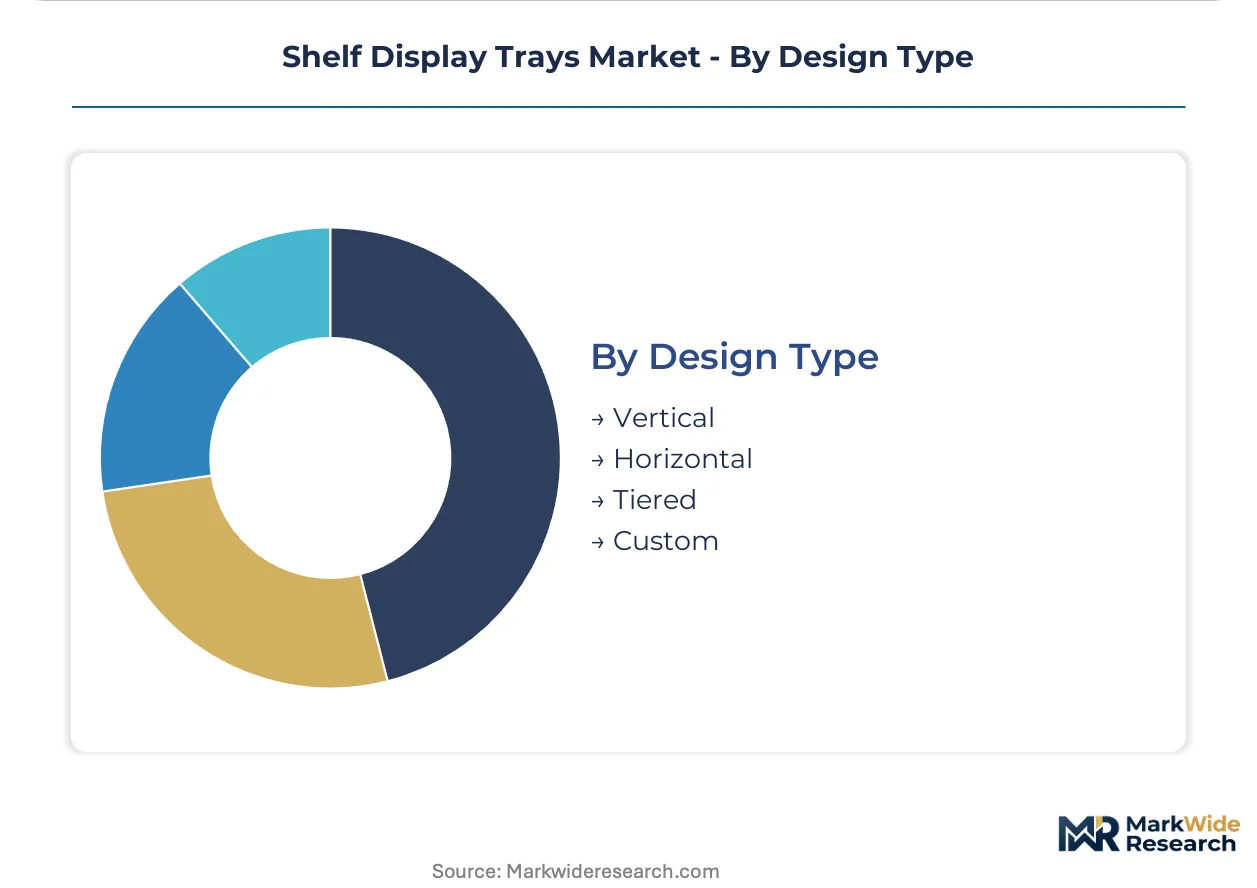
- Horizontal:Flat-bottomed trays with raised edges constitute the baseline specification for palletized distribution and automated replenishment, with limited differentiation beyond material grade.
- Custom:Brand-specific color matching, logo integration, and irregular product geometries command 3-5x unit price premiums from retail chains seeking fixture exclusivity.
- Vertical:Upright configurations with integrated dividers address space-constrained urban store formats where floor area efficiency determines assortment breadth.
- Tiered:Stacked display levels maximize product visibility in high-traffic zones, with structural engineering requirements limiting supplier qualification to thermoforming specialists with finite element analysis capability.
Volume economics favor Horizontal; margin capture concentrates in Custom.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH restrictions on food-contact polymers anchor European procurement standards, with Germany's national packaging law extending recycled content mandates that reshape material sourcing across supermarket and pharmacy channels.
Germany
Discount grocery chains Aldi and Lidl drive standardized tray footprints for automated replenishment systems. The country's national packaging law implements EU Packaging and Packaging Waste Directive minimum recycled content thresholds. Manufacturing clusters in North Rhine-Westphalia and Bavaria host expanding thermoforming operations serving domestic retail fixture demand.
France
Supermarket category managers specify total cost of ownership metrics for produce section pool tray procurement. ANSM pharmaceutical packaging guidelines influence cold-chain display requirements for pharmacy distribution. The Île-de-France region concentrates retail headquarters purchasing decisions that ripple through European supply chains.
Netherlands
Benelux distribution networks anchor reusable pool tray systems for supermarket produce sections. CE marking requirements govern mechanical safety in automated handling environments. The Randstad logistics corridor facilitates closed-loop tray pooling infrastructure across retail distribution centers.
United Kingdom
Retail chains balance ESG-driven packaging reduction targets against washing durability requirements. The UK Packaging Waste Regulations impose extended producer responsibility fee structures. Midlands-based converters retool fiber molding lines to serve supermarket private-label programs.
Poland
Central European location positions the country as a manufacturing base for export to German and Benelux retail markets. EU Green Deal packaging sustainability mandates accelerate cardboard tray adoption. Industrial clusters around Warsaw and Łódź expand molded fiber thermoforming capacity for short-use produce applications.
Shelf Display Trays Market Competitive Landscape
Capability concentration sits with specialty converters possessing finite element analysis and food-contact certification expertise; scale advantage sits with volume producers of standardized pool tray footprints. The market structures around three tiers: premium-positioned specialists serving pharmacy and cold-chain channels, mid-scale regional fabricators supplying private-label retail programs, and commodity producers competing on unit cost for promotional cardboard applications. Dominant competitive moves include portfolio diversification into molded fiber alternatives and strategic partnerships with retail fixture manufacturers for integrated display system supply.
Within the premium-tier specialist segment, HL Display AB and Winpak Ltd. exemplify positioning anchored in compliance-intensive channels. LINPAC Packaging occupies a scale-driven position in reusable pool systems. These named entities represent archetypes rather than exhaustive market coverage, with each sitting within distinct capability-scale trade-offs that shape competitive interaction patterns.
| Leading Market Players |
|---|
| HL Display AB |
| Winpak Ltd. |
| LINPAC Packaging |
| HPM Global Inc. |
| Euro Pool System |
| Delkor Systems, Inc. |
| Valley Plastics, Inc. |
| BES Packaging Corp. |
| ARTPLEX Jerzy Kalinowski |
| Others |
Value Network & Pricing Analysis
Raw material volatility in OCC spot markets and virgin polymer feedstocks compresses margin spreads between economy cardboard and premium thermoformed tiers while forcing converters to reconfigure sourcing footprints across Central European manufacturing clusters.
Pricing Analysis
German discount chains command unit price spreads of three-to-one between standard pool trays and custom pharmacy configurations. Three-tier pricing structure across premium, standard, and economy levels reflects washing durability certification, nesting density ratios, and ECHA food-contact compliance tiers. Cost compression in molded fiber segments intensifies because OCC price swings disrupt converter margins without corresponding pass-through mechanisms. Supermarket category managers exhibit highest price sensitivity through total cost of ownership scorecards, while specialty pharmacy channels accept premium positioning for EMA serialization-ready configurations.
Supply Chain Analysis
Contract thermoforming capacity concentrates with HL Display AB's Nordic manufacturing base, LINPAC Packaging's Benelux operations, and expanding domestic converters across North Rhine-Westphalia and Bavaria. Raw material procurement draws from German polymer compounders, Nordic pulp suppliers, and Benelux recycled fiber streams. Single-source vulnerability concentrates in wet-press fiber molding technicians with food-contact hygiene certification, where limited availability constrains capacity expansion. Distribution runs through retail fixture manufacturers and direct procurement relationships with Aldi and Lidl distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, where ECHA REACH compliance and Germany's national packaging law create switching costs that lock in certified suppliers across pharmacy and supermarket channels.
For Market Incumbents: Insulate market position by deepening captive supply of food-contact certified polymer formulations and expanding thermoforming capacity in Poland to serve Central European discount grocery expansion. Secure exclusive relationships with retail fixture manufacturers for integrated display system supply, countering substitute pressure from molded fiber alternatives. For New Entrants and Emerging Players: Pursue underpenetrated reusable pool tray opportunities in France and Spain where LINPAC-style closed-loop systems remain below German adoption rates. Target pharmacy cold-chain display configurations with temperature-stable PP and integrated RFID tracking as the most penetrable premium segment, leveraging ANSM pharmaceutical packaging guidelines as entry credential. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors converters with food-contact certification expertise and finite element analysis capability over commodity cardboard producers. Long-term viability hinges on portfolio diversification into molded fiber alternatives and digital product passport readiness under EU Ecodesign for Sustainable Products Regulation. Monitor ECHA's evolving restrictions on intentionally added microplastics as inflection signal for reformulation cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Molded Fiber Capacity Expansion | Wet-press thermoforming investment achieves cost parity with plastic for short-use produce applications under EU Green Deal mandates. |
| Backward Integration into Polymer Compounding | In-house production of ECHA REACH-compliant formulations secures supply security against phthalate and heavy metal stabilizer restrictions. |
| Digital Product Passport Integration | Traceability-embedded tray designs capture first-mover advantage under upcoming EU Ecodesign for Sustainable Products Regulation requirements. |
| Reusable Pool System Geographic Expansion | Closed-loop tray pooling infrastructure extension into France and Spain addresses underpenetrated supermarket produce sections. |
| Pharmacy Cold-Chain Certification Investment | EMA serialization-ready display configurations with temperature-stable materials access premium pricing in specialty pharmaceutical distribution. |
Research Methodology
Desk research of EU regulatory filings, trade association statistics, and retail procurement databases preceded structured interviews with thermoforming plant managers, supermarket category buyers, pharmacy procurement leads, and ECHA compliance officers. Primary fieldwork combined with secondary validation across Germany's national packaging law implementation documents, Benelux distribution network analyses, and converter capacity announcements. Bottom-up volume modeling and top-down market sizing triangulated segment-level outputs.
Assumptions held fixed include EU Green Deal packaging mandate timelines and ECHA REACH restriction trajectories, while variables included discount grocery format proliferation rates and OCC pulp market volatility. The analytical framework modeled material type, end user channel, dimensional specification, and design complexity dimensions across the analysis window. CAGRs derived from segment-level growth rate reconciliation against macro retail fixture investment patterns and supermarket automation adoption curves.
Sensitivities concentrate around ECHA microplastic restriction finalization, Germany's recycled content threshold enforcement intensity, and molded fiber thermoforming technician availability constraints. Forecasts reflect documented assumptions on regulatory compliance cost pass-through and retail chain procurement consolidation. Quarterly review of Aldi and Lidl expansion announcements, OCC futures pricing, and ECHA guidance updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Storage and Organization
Small Space Furniture Market
Home Storage and Organization
Kitchen Storage Organization Market
Home Storage and Organization
Closet Organizers Market
Home Storage and Organization
Toy Storage Market
Home Storage and Organization
Middle East and Africa Kitchen Storage Market
Home Storage and Organization
Clothes Closets Market
Home Storage and Organization
Flatware Holders and Organizers Market
Home Storage and Organization
Shoe Storage and Organizers Market
Home Storage and Organization
Slipcases Market
Home Storage and Organization
United States Home Organizers and Storage Market
Home Storage and Organization
Collapsible Wardrobe Market
Home Storage and Organization
Flush Mount Photo Album Market
Home Storage and Organization
Kitchen Storage Market
Home Storage and Organization
Regency Shelving Market
Home Storage and Organization
Hong Kong Self-Storage Market
Home Storage and Organization
Jewelry Organizer Market