
 Slipcases Market | 2026-2036
Slipcases Market Size, Share, and Industry Trends Forecast 2026-2036
Slipcases Market Analytics
FSC chain-of-custody certification is reorganizing supplier eligibility across the slipcases value chain, favoring mills and converters with verified sustainable fiber programs. Smurfit Kappa leverages its integrated European paperboard network to secure certified raw material flows. Huhtamäki Oyj anchors its position through specialized barrier coatings for archival applications. Taylor Box Company differentiates via bespoke rigid box craftsmanship serving luxury publisher accounts.
Slipcases are rigid, form-fitting enclosures—typically constructed from laminated paperboard, cloth-wrapped binder board, or molded rigid plastic—engineered to shield bound volumes from light, dust, and mechanical abrasion while enabling shelf presentation. Board thickness ranges from 80 to 120 pt depending on protection grade, with archival variants incorporating acid-free adhesives and calcium carbonate buffering. Protective slipcases dominate institutional procurement where longevity specifications govern selection, while decorative slipcases command premium positioning among collectors seeking display-grade aesthetics. Custom design work captures disproportionate margin pools relative to standard formats due to setup complexity and client-specific dimensional requirements.
EPA guidelines on recycled content claims and EU REACH restrictions on formaldehyde-based adhesives compel reformulation of binding systems and substrate specifications. FSC and PEFC forest stewardship protocols further constrain material provenance, elevating compliance costs for uncertified competitors. Stakeholders must weigh certification investments against the narrowing supplier base as regulatory stringency tightens across North American and European procurement channels.
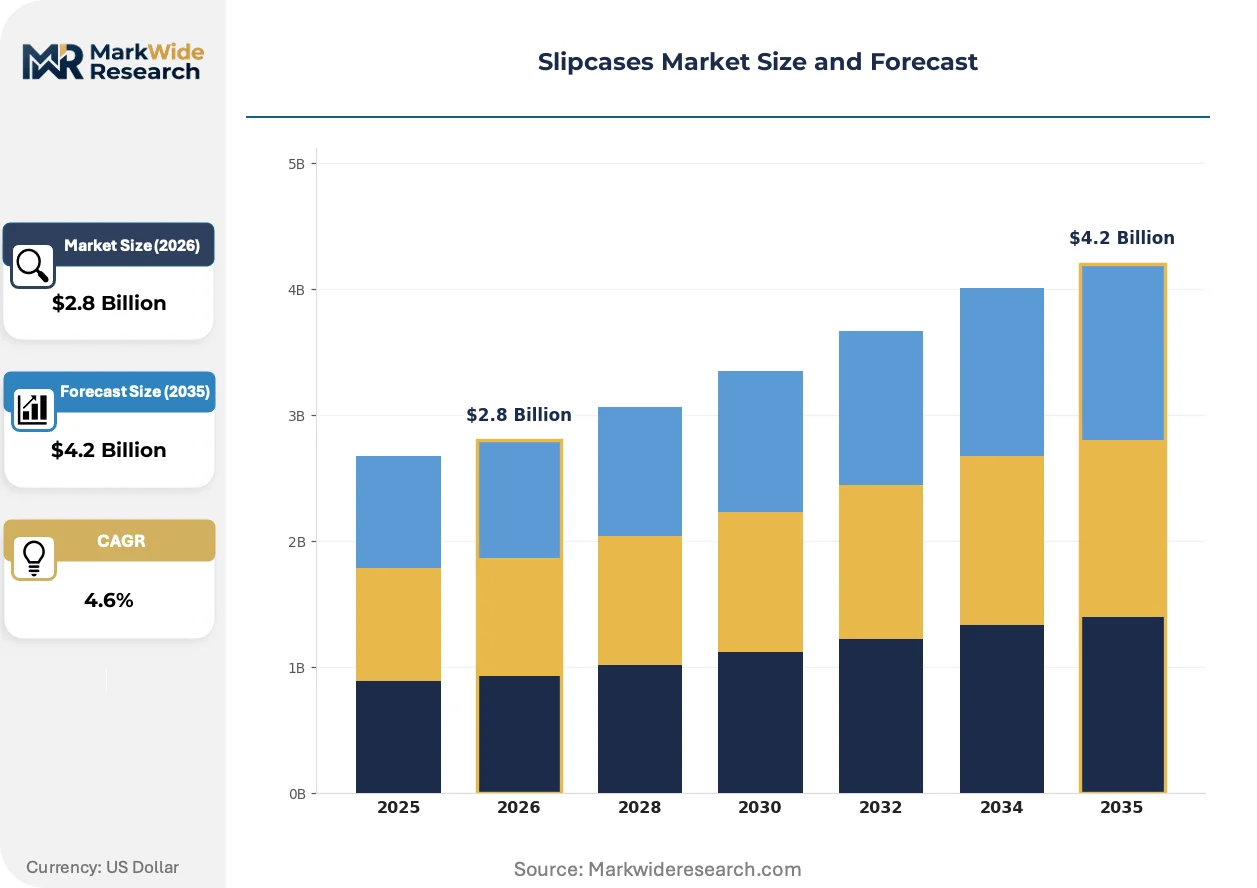
Market Dynamics
REACH restrictions on formaldehyde-based adhesives and FSC chain-of-custody mandates are compressing the supplier base, forcing mills and converters to absorb certification costs or exit European and North American procurement channels entirely.
Growth Catalysts
- Heritage publishing preservation:Institutional library programs in Germany, the United States, and Japan sustain specialized orders for archival-grade protective enclosures with acid-free specifications.
- REACH compliance deadlines:EU adhesive reformulation mandates accelerate substitution toward water-based and bio-based binding systems, creating upgrade cycles across existing installed bases.
- Calcium carbonate buffering:Advanced archival variants incorporating pH-neutral substrates command premium positioning among specialty collectors seeking longevity guarantees.
Market Restraints
- Certified fiber scarcity:FSC and PEFC chain-of-custody requirements constrain raw material provenance, elevating input costs for uncertified competitors.
- Board thickness standardization:Technical limitations in achieving sub-80 pt rigidity without structural compromise limit lightweighting initiatives in protective applications.
- Digital archive substitution:Digitization programs at major university and government libraries reduce physical volume acquisition rates in North America.
Strategic Opportunities
- Limited-edition collector markets:Bespoke craftsmanship capabilities capture disproportionate margin pools through client-specific dimensional requirements and display-grade aesthetics.
- Barrier coating convergence:Integration of moisture-resistant and UV-blocking layers with traditional paperboard substrates enables premium positioning in climate-variable storage environments.
- Japanese institutional procurement:METI-supported cultural preservation initiatives sustain specialized demand for archival-grade enclosures with JIS-standard compliance.
Industry Challenges
- Master craftsperson scarcity:Hand-assembly expertise for cloth-wrapped binder board construction faces generational attrition, compressing production capacity for luxury publisher accounts.
- Multi-certification timeline compression:Simultaneous FSC, PEFC, and REACH compliance audits strain quality assurance bandwidth at mid-scale converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slipcases Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Slipcases, Multi-Slipcases, Decorative Slipcases, Protective Slipcases Material: Cardboard, Rigid Plastic, Paper, Wood Design: Custom Design, Standard Design, Vintage Style, Modern Style Target Audience: Collectors, Retailers, Publishers, Educational Institutions |
| Companies Covered | Taylor Box Company, Vulcan Information Packaging, DELUXE BOXES, SHENZHEN KING FU COLOR PRINTING, Smurfit Kappa, Huhtamäki Oyj, Amcor Plc, Graphic Packaging, Ardagh Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slipcases Market Evolving Landscape
Material science advances and regulatory chemistry mandates are fragmenting traditional supply relationships while creating openings for specialized coating and adhesive formulators with verified sustainable chemistry portfolios.
Molded rigid plastic substrates incorporating recycled content are decomposing the laminated paperboard dominance in high-abrasion institutional environments. University library systems and government archives are piloting these alternatives for high-circulation reference collections. The shift is compressing demand for conventional 100-120 pt paperboard in protection-grade applications where mechanical durability outweighs aesthetic presentation.
EU REACH restrictions on formaldehyde-based adhesives are compelling reformulation of binding systems across European converter operations. Industrial consequence includes accelerated supplier qualification timelines and elevated R&D expenditure for water-based alternatives. Archival-grade slipcase manufacturers serving German and French heritage publishers are most affected, with many pursuing dual-certified adhesive platforms to maintain cross-border eligibility.
Collector procurement patterns are rotating toward direct commissioning relationships with specialized craftsmen, bypassing traditional publisher-specifier intermediaries. Luxury rare book dealers and private collectors are establishing preferred supplier agreements with bespoke box makers for limited-edition releases. This channel disintermediation is most visible in the United States and United Kingdom, where auction house provenance documentation increasingly specifies custom enclosure provenance.
Slipcases Market Segmentation
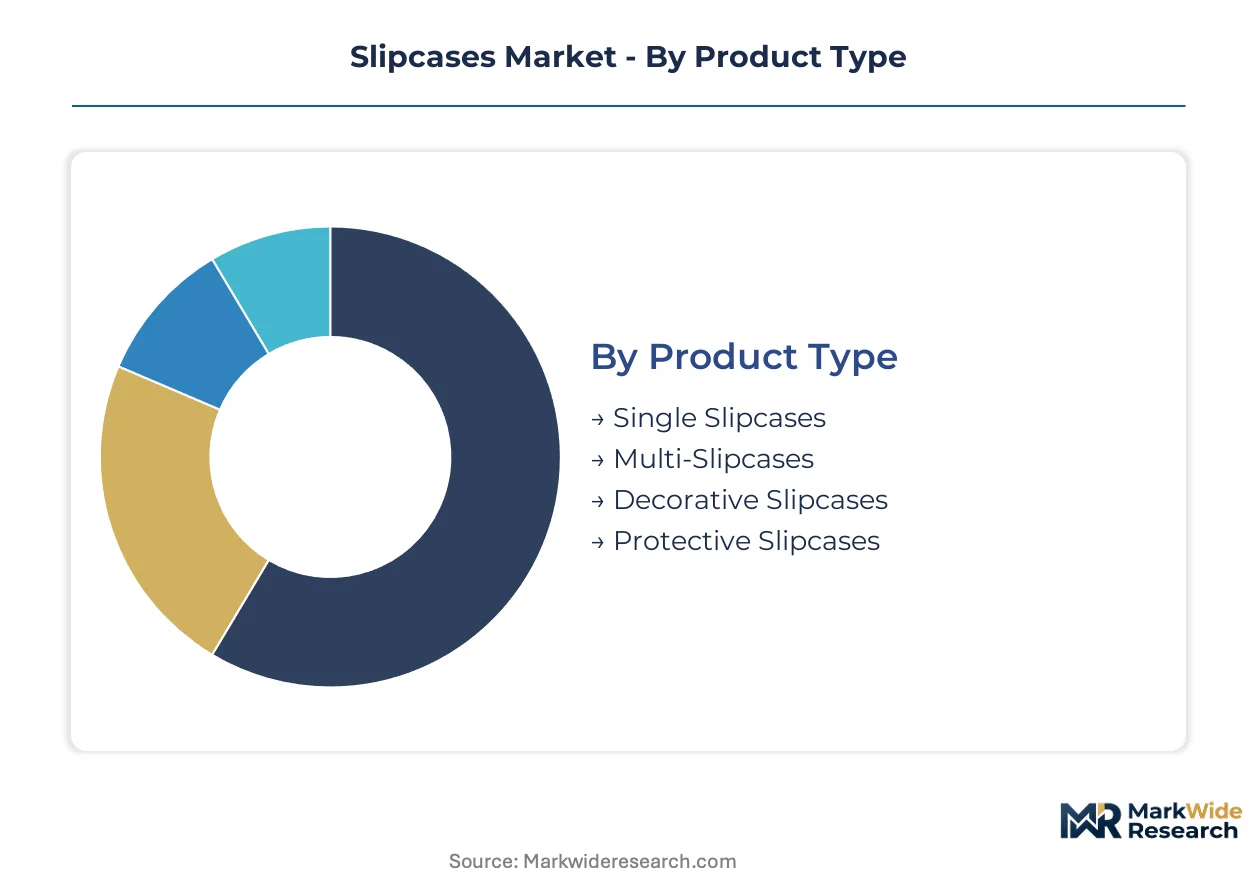
Slipcase segmentation reflects divergent margin structures across protection-grade archival specifications and display-oriented collector aesthetics. Procurement patterns split between institutional longevity mandates and luxury publisher branding requirements.
Product Type:
Protective variants command premium pricing through acid-free specifications and calcium carbonate buffering, while decorative formats compete on craftsmanship differentiation.
- Single Slipcases:Engineered for individual volume protection using 80-100 pt laminated paperboard with cloth or paper wrapping. Heritage publishers in Germany and Japan specify these for limited-edition releases where dimensional precision matches binding specifications exactly.
- Protective Slipcases:Archival-grade enclosures incorporating acid-free adhesives and pH-neutral substrates per ISO 9706 longevity standards. Institutional library systems in the United States sustain specialized procurement through EPA-compliant recycled content programs and FSC chain-of-custody verification.
- Multi-Slipcases:Configured for series or collected works with uniform spine presentation across shelf arrangements.
- Decorative Slipcases:Prioritize display aesthetics over protective specifications for collector markets.
Protective slipcases hold installed capacity. Decorative slipcases are rotating up the share rankings.
Material:
Substrate selection determines regulatory compliance pathways and end-use eligibility across REACH-restricted European channels and FSC-mandated North American procurement.
- Cardboard:Laminated paperboard constructions from 80-120 pt thickness dominate volume production through Smurfit Kappa's integrated European network and similar mill-converter relationships. REACH adhesive reformulation and FSC certification requirements are compressing the uncertified supplier base.
- Paper:Acid-free and buffered variants serve archival applications where longevity specifications govern selection. German heritage publishers and Japanese institutional programs under METI cultural preservation initiatives specify these substrates with JIS-standard compliance.
- Rigid Plastic:Molded substrates with recycled content are displacing paperboard in high-abrasion institutional environments.
- Wood:Limited to premium bespoke commissions where structural rigidity and aesthetic grain presentation justify cost premiums.
Cardboard maintains production scale dominance. Rigid plastic is climbing the fastest in institutional substitution trials.
Design:
Setup complexity and client-specific dimensional requirements create disproportionate margin pools in bespoke segments versus standardized format production.
- Custom Design:Client-commissioned dimensions, material combinations, and finishing specifications requiring hand-assembly expertise. Taylor Box Company and similar craftsmen capture premium positioning through direct relationships with luxury rare book dealers and auction house provenance documentation in the United States and United Kingdom.
- Standard Design:Fixed-format production with minimized setup costs and rapid turnaround for publisher inventory programs.
- Vintage Style:Period-appropriate aesthetics reproducing historical binding and enclosure conventions.
- Modern Style:Minimalist presentation formats emphasizing clean lines and contemporary material finishes.
Custom design commands margin premiums. Standard design anchors volume throughput.
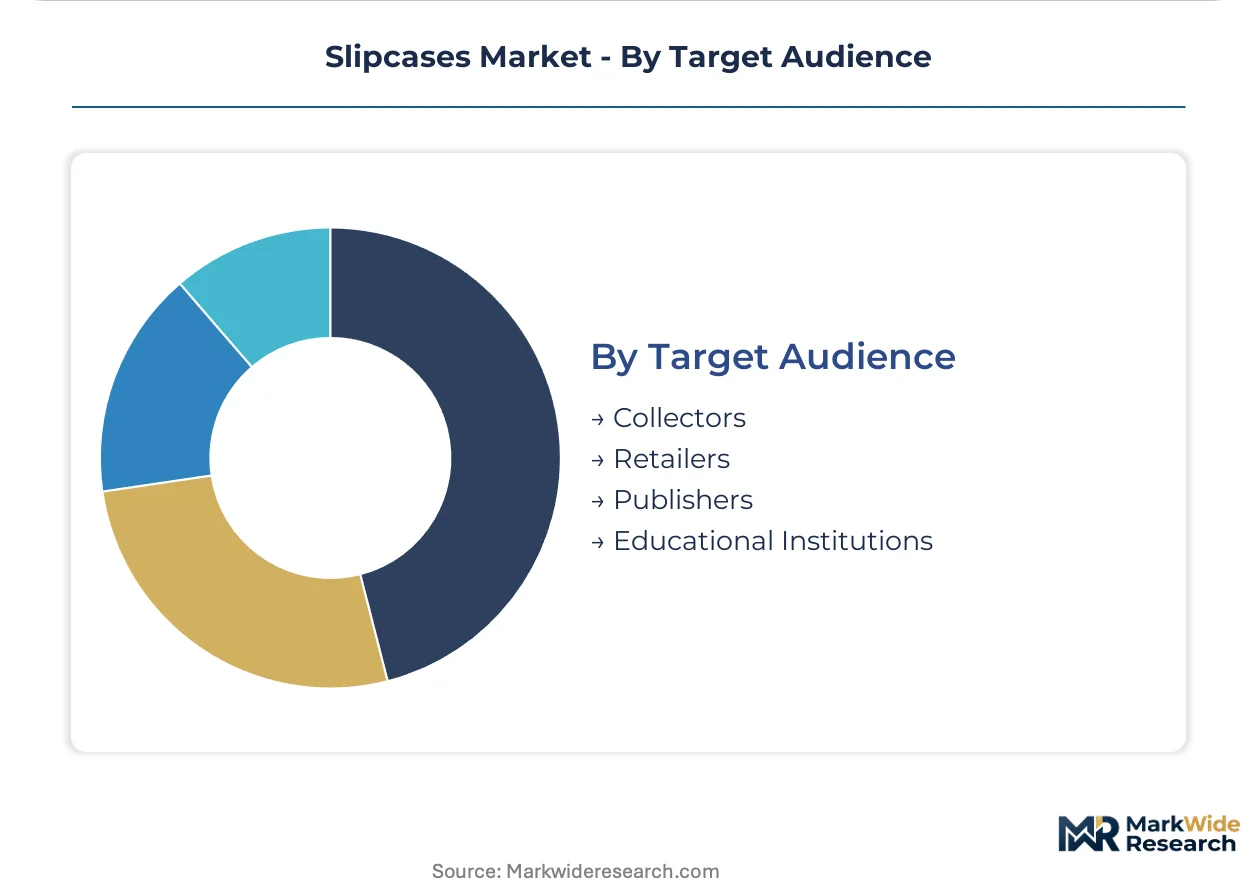
Target Audience:
Procurement authority and specification control vary sharply across collector direct commissioning, publisher inventory management, and institutional compliance mandates.
- Collectors:Private individuals and specialized dealers commissioning bespoke enclosures with provenance documentation requirements. Direct relationships with craftsmen are displacing traditional publisher-specifier intermediaries in the United States and United Kingdom auction markets.
- Publishers:Heritage and luxury houses specifying protective or decorative enclosures for limited-edition releases. German and French publishers face compressed supplier qualification timelines under EU REACH adhesive reformulation mandates.
- Educational Institutions:University library systems and government archives with longevity specifications and digitization program constraints. North American acquisition rates face pressure from digital archive substitution while Japanese programs expand under METI-supported preservation initiatives.
- Retailers:Specialty bookstores and gift channels stocking standardized formats for consumer purchase.
Collectors are gaining specification authority. Educational institutions maintain contract scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European distribution for archival-grade paperboard substrates, while the Port of Long Beach handles Pacific-rim imports of specialty binder materials into North American collector markets.
United States
Heritage publishers in New York and Boston commission bespoke protective enclosures for limited-edition releases. EPA guidelines on recycled content claims govern institutional procurement from university library systems. The Pacific Northwest hosts specialized craftsmen serving auction house provenance documentation requirements.
Germany
Leipzig and Stuttgart anchor demand from heritage publishing houses specifying acid-free archival specifications. EU REACH restrictions on formaldehyde-based adhesives compel binding system reformulation across converter operations. The Rhine-Ruhr industrial corridor concentrates FSC-certified paperboard milling capacity.
Japan
Tokyo and Osaka institutional libraries sustain specialized orders under METI-supported cultural preservation initiatives. JIS standards compliance governs substrate specifications for archival applications. The Kanto region hosts craftsmen serving collector direct commissioning relationships.
United Kingdom
London rare book dealers drive bespoke enclosure demand with provenance documentation requirements. FSC chain-of-custody certification constrains supplier eligibility across procurement channels. The Midlands region concentrates paperboard converting operations serving luxury publisher accounts.
China
Shenzhen and Guangzhou export rigid plastic substrates with recycled content for institutional trial programs. GB standards on packaging materials influence formulation choices for export-bound production. The Pearl River Delta hosts integrated printing and converting clusters.
Slipcases Market Competitive Landscape
Listed leaders compete with private specialists across certification compliance and craftsmanship dimensions. The supplier base compresses under simultaneous FSC, REACH, and archival-grade qualification requirements. Three archetypes dominate: integrated European paperboard networks, specialized barrier coating formulators, and bespoke rigid box craftsmen. Capacity consolidation and dual-certified adhesive platform development represent the dominant competitive vectors.
Within the integrated network tier, Smurfit Kappa and Huhtamäki Oyj exemplify scale-driven positions anchored through certified raw material flows and specialized coating capabilities respectively. Taylor Box Company occupies the craftsmanship-specialist position serving luxury publisher accounts with hand-assembly expertise.
| Leading Market Players |
|---|
| Taylor Box Company |
| Vulcan Information Packaging |
| DELUXE BOXES |
| SHENZHEN KING FU COLOR PRINTING |
| Smurfit Kappa |
| Huhtamäki Oyj |
| Amcor Plc |
| Graphic Packaging |
| Ardagh Group |
| Others |
Value Network & Pricing Analysis
Mill-scale economies in FSC-certified paperboard production anchor price floors across European and North American procurement channels, compressing margins for mid-scale converters lacking integrated fiber sourcing while elevating barriers for uncertified competitors. Capacity utilization at Rhine-Ruhr milling clusters and Pacific Northwest converting operations directly shapes contract pricing leverage for heritage publisher accounts.
Pricing Analysis
Volume-discount tiering structures separate archival-grade protective specifications from decorative collector formats, with acid-free calcium carbonate buffering and REACH-compliant adhesive platforms commanding premium positioning. Price differentiation rests on certification grade and customization level, with bespoke dimensional work capturing disproportionate margin pools. Cost compression in standard-format paperboard production is intensifying as Chinese rigid plastic substrates penetrate institutional trial programs. Educational institutions exhibit highest price sensitivity due to digitization program budget constraints, while private collectors demonstrate lowest sensitivity when provenance documentation requirements govern selection.
Supply Chain Analysis
Inbound logistics costs through the Port of Hamburg and Port of Long Beach fluctuate with container availability across Asia-Europe and trans-Pacific trade lanes, compressing delivery windows for specialty binder materials. Raw material sourcing draws from German FSC-certified paperboard milling, Chinese recycled-content rigid plastic manufacturing, and Japanese JIS-standard substrate production. Single-source vulnerability concentrates in archival-grade adhesive formulators serving EU REACH compliance mandates. Distribution runs through heritage publisher direct procurement, institutional library contract channels, and auction house provenance networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as METI-supported preservation initiatives and heritage publishing limited-edition programs sustain specialized demand growth ahead of digital substitution headwinds.
For Market Incumbents: Compound certification advantages through dual-certified adhesive platform development and FSC chain-of-custody capacity expansion in the Rhine-Ruhr corridor. Master craftsperson attrition threatens bespoke production capacity; secure hand-assembly expertise through apprenticeship pipelines and preferred supplier agreements with luxury rare book dealers. Vertical integration into barrier coating formulation protects margin pools from specialized chemical suppliers.
For New Entrants and Emerging Players: Lead with rigid plastic substrate innovation targeting high-abrasion institutional environments where mechanical durability specifications outweigh aesthetic presentation requirements. Collector direct commissioning relationships in the United States and United Kingdom auction markets present the most penetrable white space, bypassing traditional publisher-specifier intermediaries through provenance documentation partnerships. Position through climate-variable storage solutions integrating moisture-resistant and UV-blocking layers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among bespoke craftsmen with established auction house relationships and institutional library maintenance contract holders. Long-term viability favors dual-certified converters with verified sustainable chemistry portfolios and archival-grade qualification depth. Monitor Japanese institutional procurement expansion under METI cultural preservation initiatives as the signal for inflection in specialized demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certified Adhesive Platform Development | REACH-compliant binding systems maintain cross-border eligibility for German and French heritage publishers. |
| Master Craftsman Apprentice Pipeline | Hand-assembly expertise scarcity threatens production capacity for luxury publisher accounts. |
| Rigid Plastic Substrate Scale-Up | Recycled-content molded alternatives displace paperboard in high-abrasion institutional environments. |
| Barrier Coating Convergence R&D | Moisture-resistant and UV-blocking layers enable premium positioning in climate-variable storage. |
| Collector Direct Channel Establishment | Provenance documentation partnerships bypass traditional publisher-specifier intermediaries in auction markets. |
Research Methodology
Initial hypotheses were tested against primary input from heritage publishing executives, institutional library procurement directors, archival materials conservators, and specialized box craftsmen, then refined through secondary validation against FSC chain-of-custody databases, REACH regulatory filings, Japanese METI preservation program documentation, and customs trade records for paperboard and rigid plastic substrates. Bottom-up volume estimates from converter capacity assessments and top-down demand triangulation from publisher release schedules were cross-referenced.
Variance decomposition across product type, material substrate, design complexity, and target audience dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from installed base upgrade cycles and replacement demand modeling. Forecast inputs incorporated adhesive reformulation timelines under EU REACH mandates and JIS-standard compliance requirements for Japanese institutional programs.
Forecasts assume regulatory continuity in EU REACH enforcement and Japanese METI preservation funding; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as digitization program expansion rates and collector direct commissioning penetration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Storage and Organization
Wardrobe Boxes Market
Home Storage and Organization
Collapsible Wardrobe Market
Home Storage and Organization
Cabinet & Furniture Drawer Slides Market
Home Storage and Organization
Middle East and Africa Kitchen Storage Market
Home Storage and Organization
Hong Kong Self-Storage Market
Home Storage and Organization
Shop Shelving Market
Home Storage and Organization
Clothes Closets Market
Home Storage and Organization
Smart Storage Cabinet Market
Home Storage and Organization
Flatware Holders and Organizers Market
Home Storage and Organization
Kitchen Storage Organization Market
Home Storage and Organization
Sheds and Outdoor Storage Market
Home Storage and Organization
Tool Chest Market
Home Storage and Organization
Asia-Pacific Digital Home Locker Market
Home Storage and Organization
Display Cabinets Market
Home Storage and Organization
United States Home Organizers and Storage Market
Home Storage and Organization
Shoe Storage and Organizers Market