
 Hong Kong Self-Storage Market | 2026-2036
Hong Kong Self-Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Hong Kong Self-Storage Market Foresight
Aftermarket service revenue from value-added offerings such as climate monitoring, insurance bundling, and logistics coordination is fragmenting across Hong Kong's self-storage landscape as operators diversify beyond rental income. Storefriendly Self Storage Group Limited leverages its extensive facility network to dominate premium indoor locations. SC Storage Group Limited anchors its position through specialized climate-controlled infrastructure. Cube Self Storage Hong Kong Limited differentiates via technology-led access systems and digital customer interfaces.
Hong Kong self-storage denotes commercial rental space providing secured, flexible storage units ranging from locker-sized compartments to warehouse-scale facilities, typically constructed with reinforced concrete, steel partitioning, and integrated fire suppression systems designed for temporary or extended goods custody. Indoor units command the largest revenue share due to Hong Kong's dense urban fabric and premium land costs, while climate-controlled storage represents the fastest-expanding type as humidity-sensitive inventory from pharmaceutical and electronics sectors grows. Commercial customers generate the highest per-unit margins, though residential demand sustains volume throughput across smaller capacity tiers.
Hong Kong's Fire Services Department enforces stringent storage facility compliance under the Fire Services Ordinance, mandating sprinkler coverage and egress specifications that shape facility design costs and market entry barriers. The Buildings Department oversees change-of-use approvals for industrial-to-storage conversions, directly constraining supply expansion timelines in prime districts. Stakeholders must monitor regulatory enforcement intensity and emerging district rezoning proposals to anticipate capacity release and competitive positioning shifts.
Market Dynamics
Hong Kong's self-storage sector faces acute supply compression as industrial building conversions lag behind e-commerce inventory overflow, with the Buildings Department's change-of-use approval timelines stretching facility deployment across Kowloon East and New Territories industrial zones.
Growth Catalysts
- E-commerce Inventory Surge:Third-party logistics providers and direct-to-consumer merchants are leasing warehouse-scale units for seasonal overflow, creating sustained absorption in 500+ square foot capacity tiers.
- Fire Services Ordinance Compliance:Stricter sprinkler coverage and egress mandates under Hong Kong enforcement protocols are professionalizing facility standards and accelerating consolidation among subscale operators.
- Pharmaceutical Cold Chain Expansion:Humidity-sensitive biologics and medical device distributors are contracting climate-controlled space, driving specialized infrastructure investment across Tsuen Wan and Kwun Tong districts.
Market Restraints
- Land Cost Escalation:Industrial site premiums in prime logistics corridors constrain facility economics, compressing operator margins on sub-10,000 square foot developments.
- Conversion Approval Bottlenecks:Buildings Department rezoning timelines extend 18-36 months for industrial-to-storage adaptations, freezing supply response to demand spikes.
- Substitute Logistics Models:Bonded warehouse operators and third-party fulfillment centers are capturing commercial inventory that might otherwise flow to self-storage.
Strategic Opportunities
- New Territories Greenfield Development:Underutilized industrial land in Yuen Long and Tuen Mun offers lower entry costs for purpose-built climate-controlled facilities.
- Insurance Bundling Integration:Partnerships with Hong Kong general insurers create value-added revenue streams beyond base rental, capturing risk-averse commercial tenants.
- Mobile Access Technology Convergence:Biometric entry systems paired with real-time inventory tracking apps are enabling premium pricing for tech-enabled facilities.
Industry Challenges
- Fire Safety Engineering Talent Scarcity:Certified sprinkler system designers and compartmentalization specialists command premium wages, inflating development costs.
- Legacy Industrial Infrastructure Retrofit Complexity:Aging factory buildings in Kwun Tong require structural reinforcement and ventilation overhauls to meet current storage codes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hong Kong Self-Storage Market |
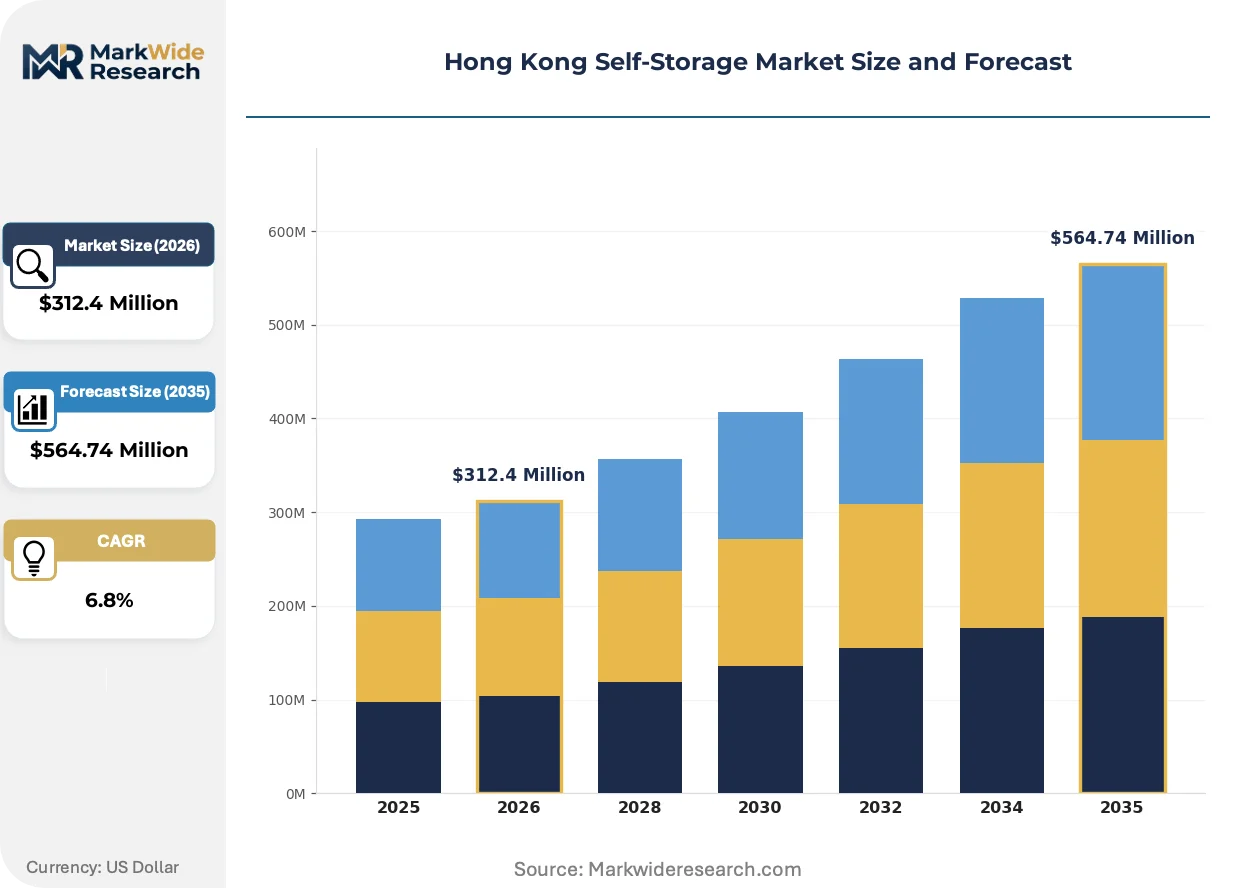
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Indoor, Outdoor, Climate Controlled, Drive-Up Capacity: Small, Medium, Large, Extra Large Customer Type: Residential, Commercial, Students, Businesses Access: 24/7 Access, Business Hours, Scheduled Access, Limited Access |
| Companies Covered | Storefriendly Self Storage Group Limited, SC Storage Group Limited, Tai Yau Storage Group Limited, Cube Self Storage Hong Kong Limited, Red Box Storage (Hong Kong) Limited, Hongkong Storage (Holdings) Limited, Spacebox Holdings Limited, Boxful Storage Limited, In N Out Storage Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hong Kong Self-Storage Market Shifts & Advancements
Digital access infrastructure and climate monitoring systems are redefining facility operations, while regulatory pressure on fire safety and building codes is accelerating capital deployment toward compliant new builds over aging conversions.
Smart locker networks with biometric authentication and mobile app integration are hybridizing traditional self-storage with on-demand logistics. E-commerce merchants and gig economy workers are adopting these systems for rapid inventory turnover. The technology is hybridizing unit economics by compressing labor costs and enabling 24-hour unmanned operations across urban micro-locations.
Hong Kong's Fire Services Department is intensifying enforcement of sprinkler coverage density and emergency egress width under the Fire Services Ordinance. Industrial building owners face mandatory retrofit timelines or operational shutdowns. Climate-controlled pharmaceutical storage operators in Kwun Tong and Tsuen Wan are absorbing compliance capital costs into premium rate structures.
Small-business inventory management is fragmenting across hybrid storage-logistics models, with merchants unbundling long-term warehousing from last-mile fulfillment. Traditional month-to-month storage contracts are losing share to flexible-term agreements tied to seasonal sales cycles. This behavioral pivot is most pronounced among cross-border e-commerce sellers operating from Kowloon East industrial zones.
Hong Kong Self-Storage Market Segmentation
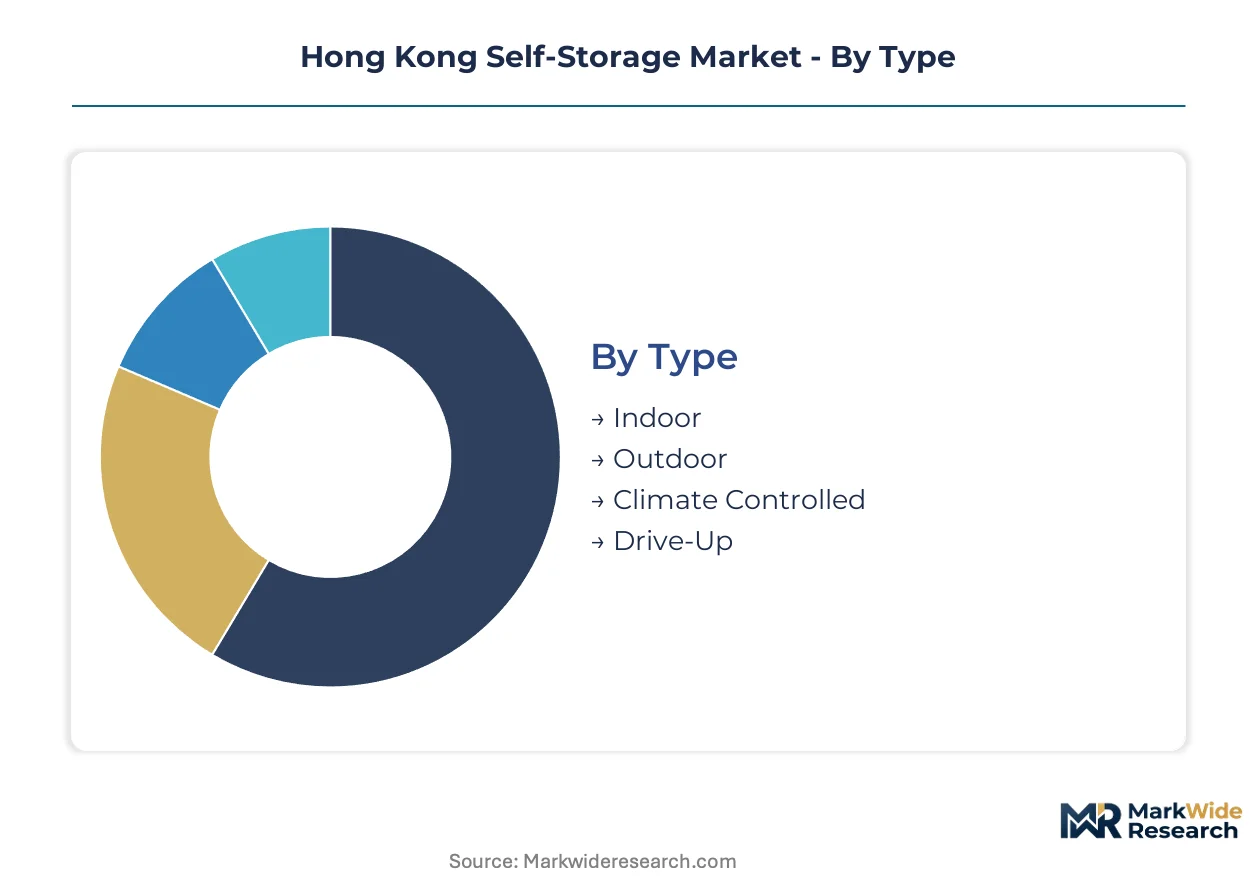
Segmentation in Hong Kong's self-storage sector reveals how land scarcity and regulatory complexity fragment demand across facility types and access models. Understanding these divisions exposes where capital deployment meets operational constraints.
Type:
Mature facility formats coexist with emerging specialized infrastructure as fire safety mandates reshape development economics.
- Indoor:Reinforced concrete structures with steel partitioning dominate Hong Kong's dense urban fabric. Demand concentrates in Kowloon East industrial zones where warehouse conversions intensify, driven by premium land costs that favor vertical development over horizontal expansion.
- Climate Controlled:Humidity-regulated units with integrated HVAC and fire suppression systems serve pharmaceutical and electronics inventory. Biologics distributors in Tsuen Wan and Kwun Tong districts are absorbing specialized capacity as medical cold chain requirements tighten.
- Outdoor:Open-air containerized storage serves construction equipment and vehicle fleets. Limited footprint in Hong Kong due to stringent land use zoning and typhoon exposure risks.
- Drive-Up:Ground-level vehicle-accessible units offer loading convenience for bulky goods. Scarce supply in central districts where multi-story industrial buildings predominate.
Indoor retains volume leadership; climate controlled holds the steepest expansion curve.
Capacity:
Unit sizing stratification mirrors Hong Kong's bifurcated customer base between space-constrained residents and inventory-heavy e-commerce merchants.
- Large:Warehouse-scale compartments exceeding standard locker dimensions accommodate seasonal overflow from third-party logistics providers. E-commerce merchants in Kowloon East industrial corridors are leasing 500+ square foot tiers for sustained absorption.
- Small:Locker-sized units serve document archives and personal effects storage. Residential customers in dense urban districts sustain volume throughput despite compressed per-unit economics.
- Medium:Mid-range compartments balance accessibility with cost efficiency. Small-business inventory management increasingly fragments across hybrid storage-logistics models.
- Extra Large:Maximum-capacity units target bulk commercial users with palletized goods. Limited facility availability constrains supply response to enterprise demand spikes.
Small units sustain residential volume; large capacity segments gain share fastest among commercial tenants.
Customer Type:
Customer composition reflects Hong Kong's economic structure, with commercial accounts generating premium margins against residential volume foundations.
- Commercial:Businesses leasing warehouse-scale space for inventory overflow and document retention generate the highest per-unit margins. Cross-border e-commerce sellers operating from Kowloon East are shifting toward flexible-term agreements tied to seasonal sales cycles.
- Residential:Individuals storing household goods during relocation or space constraints provide consistent baseline demand. Smaller capacity tiers absorb this segment across Hong Kong's dense urban districts.
- Students:Temporary storage during academic term breaks creates cyclical demand patterns. Price-sensitive usage concentrated near university clusters in New Territories.
- Businesses:Corporate accounts with standardized procurement processes seek bundled service offerings. Insurance integration and climate monitoring attract risk-averse enterprise contracts.
Commercial accounts command margin premiums; residential segments anchor volume stability.
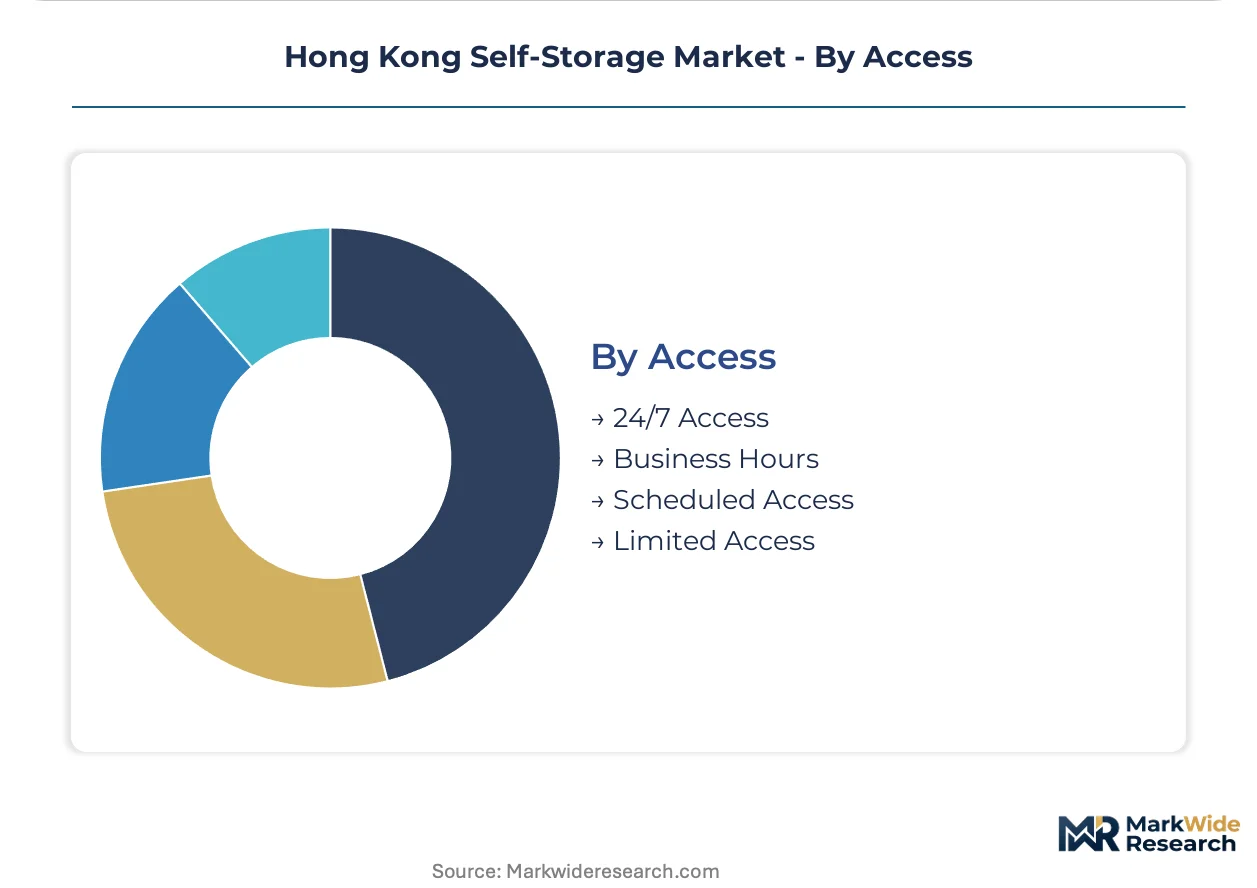
Access:
Access model differentiation increasingly hinges on technology deployment and labor cost compression rather than physical infrastructure alone.
- 24/7 Access:Biometric entry systems paired with mobile app integration enable unmanned operations. Smart locker networks are hybridizing traditional self-storage with on-demand logistics for gig economy workers.
- Business Hours:Staffed facilities during standard operating windows maintain lower technology overhead. Traditional month-to-month contracts persist in this segment.
- Scheduled Access:Appointment-based entry accommodates specialized handling requirements. Pharmaceutical cold chain operators favor controlled access protocols.
- Limited Access:Restricted entry schedules reduce operational costs for price-sensitive segments. Document storage and archival users tolerate constrained availability.
24/7 access commands technology premiums; business hours retains cost-sensitive volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hong Kong's self-storage consumption pattern diverges sharply from mainland China and regional neighbors, with commercial inventory overflow dominating demand rather than residential downsizing that drives Singapore and Sydney markets.
Kowloon East
E-commerce merchants and third-party logistics providers absorb warehouse-scale units across Kwun Tong and Kowloon Bay industrial corridors. The Buildings Department enforces 18-36 month change-of-use approval timelines for industrial-to-storage conversions. Facility operators concentrate along Sheung Yee Road and Wai Yip Street where aging factory stock enables adaptive reuse.
New Territories
Underutilized industrial land in Yuen Long and Tuen Mun attracts purpose-built climate-controlled developments with lower entry costs than island districts. The Fire Services Ordinance mandates sprinkler coverage density upgrades that professionalize facility standards. Tsuen Wan pharmaceutical distributors contract humidity-regulated space for biologics storage.
Hong Kong Island
Space-constrained residents and corporate document archives sustain demand for locker-sized units in dense urban fabric. Premium land costs favor vertical development over horizontal expansion in Central and Wan Chai. Smart locker networks with biometric authentication penetrate Sheung Wan and Causeway Bay micro-locations.
Cross-Border Corridor
Seasonal inventory surges from mainland-bound e-commerce sellers concentrate near logistics interchanges. Flexible-term agreements tied to sales cycles displace traditional month-to-month contracts. Operators near Lantau and airport cargo zones capture bonded warehouse spillover demand.
Hong Kong Self-Storage Market Competitive Landscape
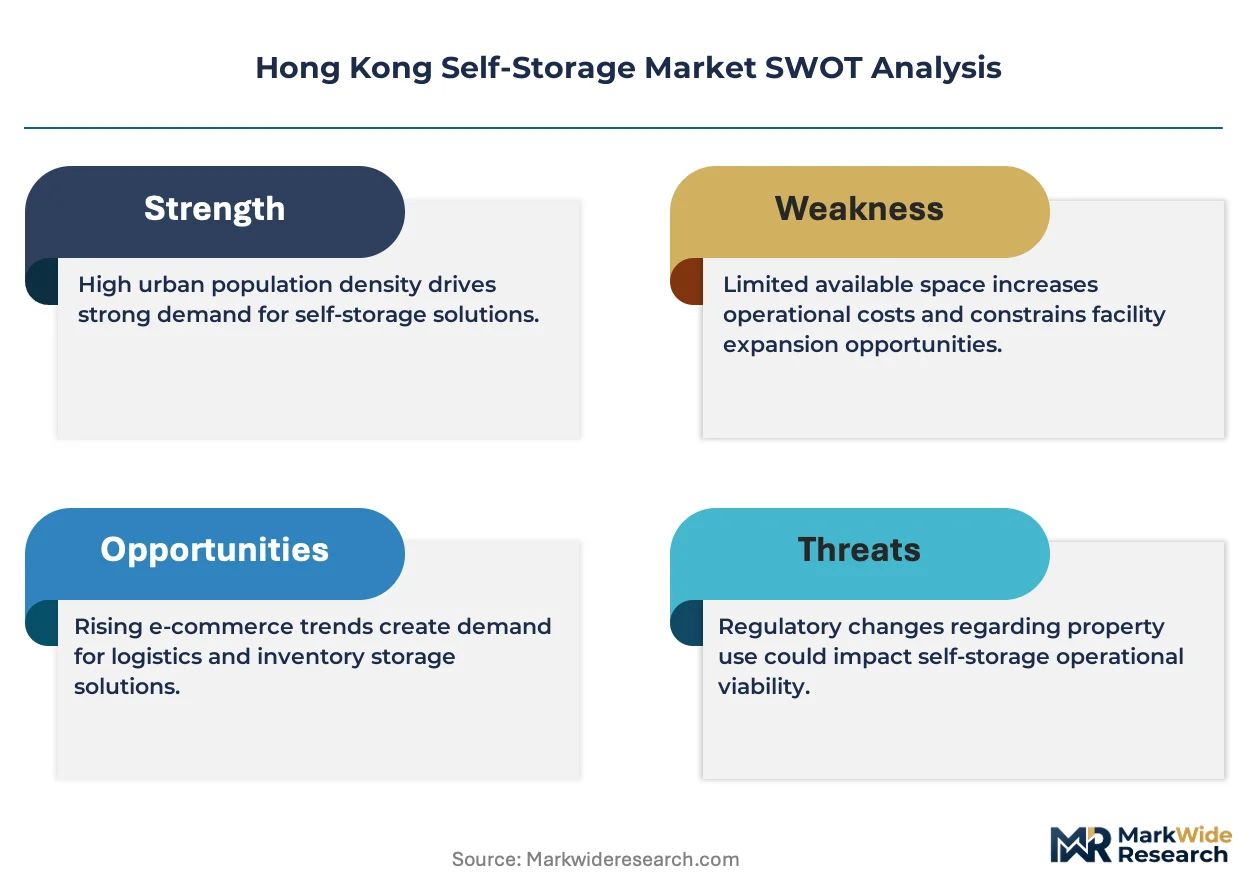
Capability concentration sits with specialized climate-control operators; scale advantage sits with facility network owners spanning multiple districts. The market exhibits tiered fragmentation between premium indoor locations and cost-optimized industrial conversions. Three archetypes dominate: technology-enabled access providers, climate-control specialists, and network-scale portfolio holders. Consolidation accelerates through fire safety compliance mandates that subscale operators cannot absorb, while strategic partnerships with insurers create differentiated service bundles.
Within the network-scale tier, Storefriendly Self Storage Group Limited and Hongkong Storage (Holdings) Limited exemplify geographic coverage strategies across premium indoor locations. SC Storage Group Limited occupies a specialist position through climate-controlled infrastructure investment. Cube Self Storage Hong Kong Limited represents the technology-led archetype with digital customer interfaces. Boxful Storage Limited and Red Box Storage (Hong Kong) Limited sit within the flexible-access segment serving gig economy and e-commerce merchant workflows.
| Leading Market Players |
|---|
| Storefriendly Self Storage Group Limited |
| SC Storage Group Limited |
| Tai Yau Storage Group Limited |
| Cube Self Storage Hong Kong Limited |
| Red Box Storage (Hong Kong) Limited |
| Hongkong Storage (Holdings) Limited |
| Spacebox Holdings Limited |
| Boxful Storage Limited |
| In N Out Storage Limited |
| Others |
Supply & Pricing Matrix
Undercapacity across Kowloon East industrial zones drives facility operators toward premium rate structures while compressing development timelines. The Buildings Department's extended approval windows for change-of-use permits tighten available supply, amplifying pricing power for compliant existing assets.
Pricing Analysis
Long-term offtake agreements dominate commercial tenant relationships, with e-commerce merchants contracting warehouse-scale units on flexible-term structures tied to seasonal inventory cycles. Three-tier pricing structure across premium indoor climate-controlled, standard indoor, and economy outdoor containerized levels reflects fire safety compliance costs and technology integration depth. Pricing pressure stems from bonded warehouse operators capturing overflow inventory that might otherwise flow to self-storage. Residential customers in dense urban districts exhibit highest price sensitivity, while pharmaceutical distributors absorb premium rates for humidity-regulated biologics storage.
Supply Chain Analysis
Tariff exposure between mainland China and Hong Kong dominates cross-border e-commerce inventory routing decisions, redirecting seasonal overflow toward local self-storage facilities. Facility development draws from steel partitioning systems sourced from Guangdong, fire suppression equipment from Japan and Germany, and HVAC components from South Korea. Single-source vulnerability concentrates in certified fire safety engineering talent, where sprinkler system designers command premium wages. Distribution runs through direct lease negotiations with industrial building owners, bypassing traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hong Kong's self-storage sector sits in early-cycle expansion, with e-commerce inventory overflow penetration still below saturation thresholds across Kowloon East industrial corridors.
For Market Incumbents: Build regulatory compliance moats through preemptive Fire Services Ordinance certification investments ahead of mandatory retrofit timelines. Consolidate subscale operators unable to absorb sprinkler density upgrade costs. Deepen backward integration into climate-controlled infrastructure design to capture pharmaceutical cold chain margin expansion. For New Entrants and Emerging Players: Build out purpose-built facilities in Yuen Long and Tuen Mun greenfield zones where land costs enable competitive entry economics. Target climate-controlled segments in Tsuen Wan where biologics distributors face acute humidity-regulated space shortages. Pursue insurance bundling partnerships as differentiated go-to-market positioning against network-scale incumbents. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across climate-controlled infrastructure sub-segments due to HVAC and fire suppression system requirements. Long-term viability favors operators with district-scale portfolio coverage enabling operational leverage. Acquisition targets should demonstrate compliant existing assets with runway for technology-enabled access upgrades. Monitor Buildings Department rezoning proposal velocity as inflection signal for supply release timing.| Strategic Initiative | Industry Significance |
|---|---|
| Climate-Controlled Capacity Buildout | Captures pharmaceutical biologics storage demand from Tsuen Wan distributors facing tightened cold chain requirements. |
| Fire Safety Compliance Pre-Certification | Accelerates market consolidation by absorbing subscale operators unable to meet Fire Services Ordinance sprinkler mandates. |
| Insurance Bundling Partnership | Creates value-added revenue streams beyond base rental through risk-averse commercial tenant capture. |
| Biometric Access Technology Deployment | Enables 24-hour unmanned operations and premium pricing across Sheung Wan and Causeway Bay micro-locations. |
| New Territories Greenfield Development | Exploits lower land entry costs in Yuen Long and Tuen Mun for purpose-built facility economics. |
Research Methodology
Cross-validation between facility operator lease data and Buildings Department change-of-use permit records anchors the qualitative findings on supply constraints. Primary interviews with self-storage facility operators, fire safety engineering consultants, industrial building owners, and e-commerce logistics managers combined with secondary validation from Hong Kong Fire Services Department enforcement bulletins, Buildings Department rezoning proposals, and customs trade data on cross-border e-commerce flows. Bottom-up unit economics modeling and top-down sector revenue triangulation ensure consistency across the analysis window.
Calibration against historical absorption rates in Kowloon East industrial zones shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include facility type, capacity tier, customer archetype, and access technology integration level. CAGRs derive from facility deployment timelines, regulatory approval velocity, and e-commerce merchant inventory cycle patterns. Fire Services Ordinance enforcement intensity and pharmaceutical cold chain expansion rates serve as industry-specific forecast inputs.
Stress conditions across Buildings Department approval timelines, industrial land cost trajectories, and bonded warehouse capacity expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory enforcement consistency and e-commerce penetration trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Storage and Organization
Asia-Pacific Digital Home Locker Market
Home Storage and Organization
Regency Shelving Market
Home Storage and Organization
Collapsible Wardrobe Market
Home Storage and Organization
Jewelry Organizer Market
Home Storage and Organization
Scandinavia Self-Storage Market
Home Storage and Organization
Slipcases Market
Home Storage and Organization
Kitchen Storage Market
Home Storage and Organization
Tool Chest Market
Home Storage and Organization
United States Home Organizers and Storage Market
Home Storage and Organization
Smart Storage Cabinet Market
Home Storage and Organization
Closet Organizers Market
Home Storage and Organization
Kitchen Storage Organization Market
Home Storage and Organization
Flatware Holders and Organizers Market
Home Storage and Organization
Display Cabinets Market
Home Storage and Organization
Shelf Display Trays Market
Home Storage and Organization
Small Space Furniture Market