
 Italy Luxury Furniture Market | 2026-2036
Italy Luxury Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Luxury Furniture Market Foresight
Subscription-based interior refresh services and software-driven customization platforms is expanding the addressable market beyond one-time purchases. B&B Italia leverages its design heritage to sustain premium positioning across European capitals. Molteni&C anchors its competitive stance through integrated manufacturing in the Brianza furniture district. Poliform differentiates via modular systems that command higher lifetime value from repeat residential clients.
Italy luxury furniture denotes handcrafted or precision-manufactured domestic and commercial furnishings using premium materials such as solid walnut, full-grain leather, and hand-blown Murano glass, typically produced in limited batches with artisan techniques passed through regional guilds. Wood and upholstery segments dominate current production volumes, while metal and glass applications are gaining share in minimalist and Art Deco design styles. The hospitality end-user category represents the fastest-growing demand pool, driven by boutique hotel renovations across Tuscany and the Amalfi Coast.
Italy's Ministry of Enterprise and Made in Italy enforces origin labeling standards that protect artisan credentials against counterfeit imports. The EU Green Deal's embodied carbon reporting requirements and REACH chemical restrictions are forcing reformulation of lacquers, adhesives, and textile treatments used in luxury production. Stakeholders must monitor how upcoming Ecodesign for Sustainable Products Regulation thresholds will reshape material qualification and supplier certification timelines.
Market Dynamics
EU Green Deal embodied carbon reporting requirements are forcing Brianza manufacturers to requalify lacquer suppliers and textile finishers, compressing certification timelines from eighteen to nine months. This regulatory compression is reshaping competitive positioning between heritage artisans and industrial-scale producers.
Growth Catalysts
- EU Green Deal:REACH chemical restrictions and Ecodesign thresholds are accelerating reformulation of adhesives and surface treatments, creating first-mover advantages for certified suppliers.
- Boutique hospitality:Renovation cycles across Tuscany and Amalfi Coast properties are pulling demand for limited-batch artisan furnishings with documented provenance.
- Software-driven customization:Parametric design platforms are collapsing lead times for bespoke residential interiors in Milan and Rome.
Market Restraints
- Solid walnut supply:Balkan and French timber sourcing constraints are elevating raw material costs for heritage woodworkers in Como.
- Artisan concentration:Seventy percent of precision metalworking capacity sits within forty kilometers of Monza, creating earthquake and labor-strike exposure.
- Embodied carbon thresholds:Pending Ecodesign for Sustainable Products Regulation thresholds threaten disqualification of traditional resin-based composite finishes.
Strategic Opportunities
- Subscription refresh services:Residential clients in Lombardy are piloting three-year interior replacement cycles with retained asset ownership.
- Murano glass convergence:Venetian furnace operators are integrating LED substrate technology into hand-blown architectural elements.
- EU Green Deal certification:Early compliance with Product Environmental Footprint standards is unlocking preferential procurement from institutional buyers.
Industry Challenges
- Guild-trained upholsterer shortage:Brianza manufacturers face twelve-month recruitment timelines for hand-stitching specialists proficient in full-grain leather.
- Dual certification burden:Simultaneous Ministry of Enterprise origin labeling and EU Green Deal carbon audits are stretching quality assurance departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Luxury Furniture Market |
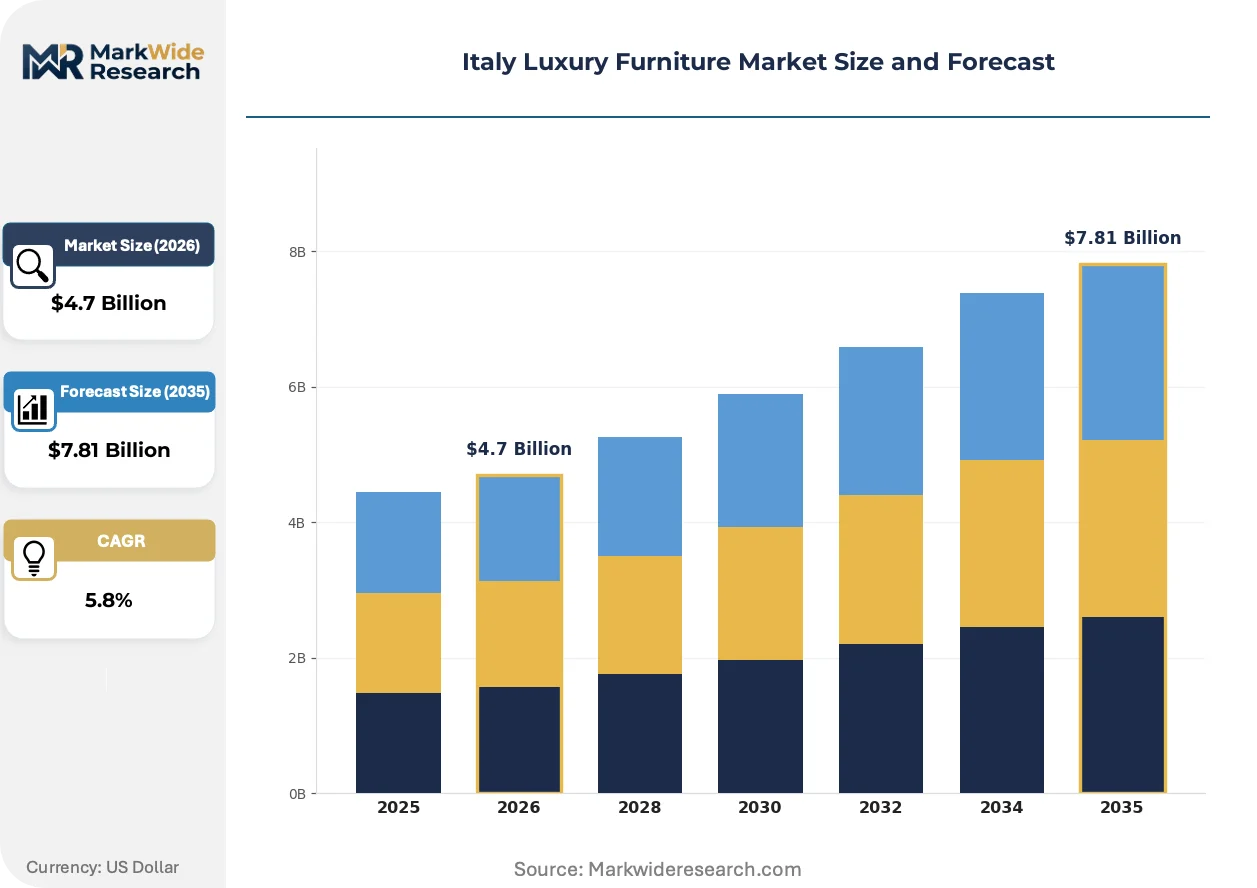
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $7.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Wood, Metal, Glass, Upholstery Design Style: Modern, Classic, Minimalist, Art Deco Functionality: Seating, Storage, Surface, Decorative End User: Residential, Commercial, Hospitality, Retail |
| Companies Covered | B&B Italia, Giorgetti, Minotti, Poliform, Moroso, Poltrona Frau, Flexform, Molteni&C, Cassina, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Luxury Furniture Market Shifts & Advancements
Parametric design software and embodied carbon tracking tools are converging to reshape how Italian luxury furniture is specified, manufactured, and certified. This technological overlay is compressing traditional barriers between artisan craft and industrial precision.
Generative design algorithms are optimizing material yield for solid walnut and marble inlay patterns. Boutique hotel specifiers in Florence and Siena are adopting these tools to visualize bespoke suites within forty-eight hours. The technology is converging with heritage craft knowledge to preserve regional aesthetic codes while collapsing prototype cycles.
EU Green Deal Product Environmental Footprint Category Rules are mandating cradle-to-grave carbon disclosure for upholstered seating. Italian manufacturers must now document emissions across Croatian timber harvest, Romanian tannery processing, and Brianza assembly. The hospitality segment is responding fastest, embedding carbon scores into RFP evaluation matrices.
Residential buyers in Milan are unbundling furniture acquisition from interior design services, contracting directly with Como manufacturers through digital showrooms. Traditional architecture studios are losing specification control to software-enabled clients who configure modular systems independently. This disintermediation is most pronounced among under-forty high-net-worth households purchasing second homes in Lake Como and Val d'Orcia.
Italy Luxury Furniture Market Segmentation
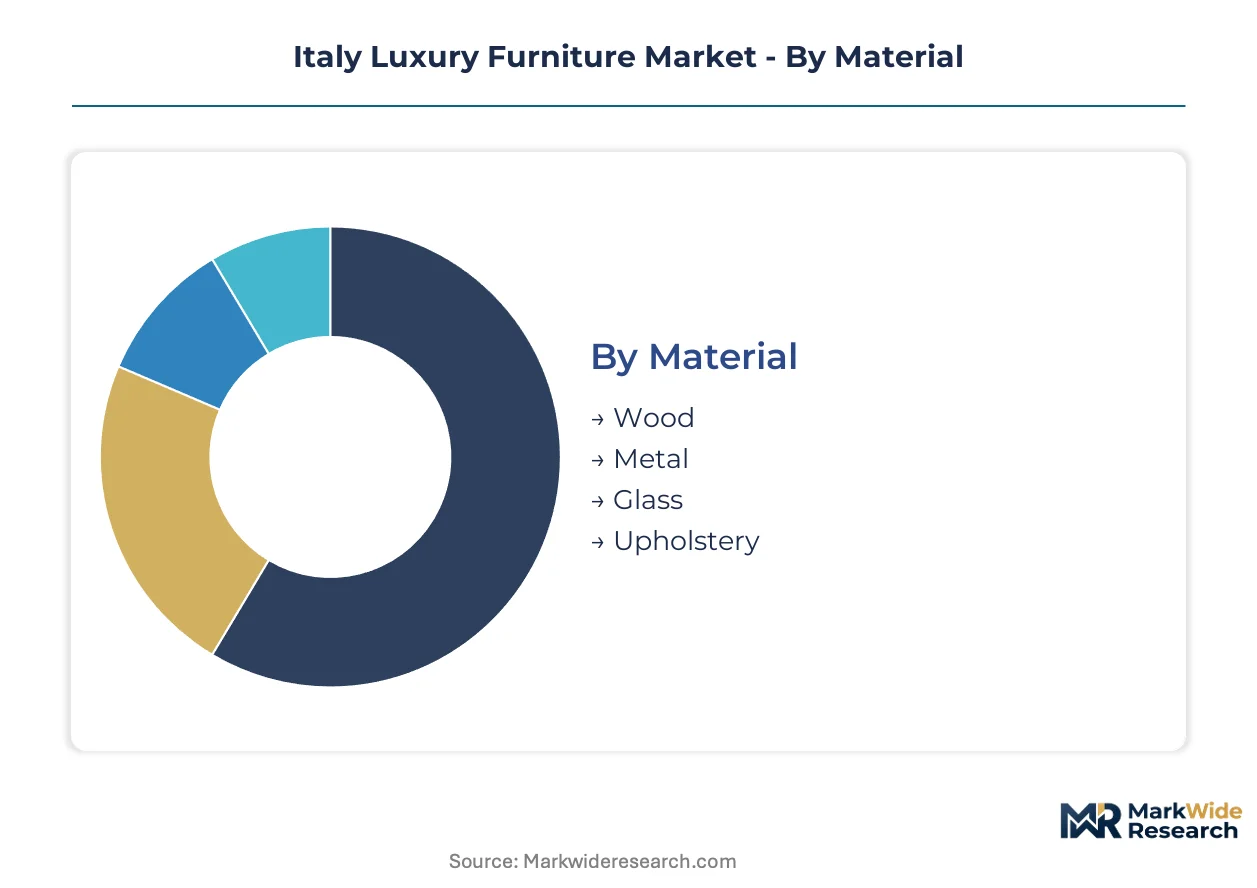
Material heritage and design lineage dictate procurement hierarchies in Italian luxury furniture. Segmentation reveals how artisan capacity concentrates in specific material-design combinations, shaping supplier selection criteria for Milan residential specifiers and Tuscan hospitality developers.
Material:
The customization-vs-standardization spectrum runs from hand-carved solid walnut requiring guild-trained craftsmen to precision-extruded aluminum suitable for parametric mass customization.
- Wood:Solid walnut, oak, and olive burl form the core of Brianza artisan production. Demand concentrates in Como and Monza workshops supplying residential clients in Milan's Porta Nuova district, where EU Green Deal carbon reporting now requires documented chain-of-custody from Croatian and French forests.
- Upholstery:Full-grain leather and high-density foam systems dominate seating production. Tuscan boutique hotels in Florence and Siena are pulling limited-batch production from Brianza tanneries, constrained by REACH chemical restrictions on tanning agents and twelve-month recruitment timelines for hand-stitching specialists.
- Metal:Precision-machined brass and bronze hardware for minimalist frames.
- Glass:Hand-blown Murano architectural elements with emerging LED substrate integration.
Most installed capacity flows through Wood. Expansion is steepest in Upholstery as hospitality renovation cycles accelerate.
Design Style:
Price-to-craftsmanship ratios stratify this category, with heritage techniques commanding premium positioning against digitally-enabled contemporary production.
- Modern:Clean-lined forms leveraging Brianza's precision metalworking and glass capabilities. Milan residential towers specify these systems through software-driven customization platforms that collapse traditional architect-furniture studio relationships.
- Classic:Baroque and neoclassical revivals employing hand-carved walnut and gold leaf. The Ministry of Enterprise origin labeling protects these designs against counterfeit imports, particularly for export markets in the Middle East and Asia-Pacific.
- Minimalist:Reduced material palettes emphasizing negative space and functional purity.
- Art Deco:Geometric inlay patterns combining exotic veneers with polished metal accents.
Classic retains the largest installed base. Modern is gaining share fastest among under-forty high-net-worth households configuring second homes independently.
Functionality:
Application context determines margin structure, with hospitality-specified seating commanding lifetime value premiums over residential decorative objects.
- Seating:Sofas, armchairs, and dining chairs incorporating ergonomic engineering with artisan upholstery. Amalfi Coast boutique properties are embedding Product Environmental Footprint scores into RFP matrices, favoring suppliers with documented cradle-to-grave carbon disclosure.
- Storage:Built-in cabinetry and freestanding case goods. Modular systems from Brianza manufacturers are capturing repeat residential business through three-year refresh subscription pilots in Lombardy.
- Surface:Dining tables, desks, and console tables.
- Decorative:Screens, mirrors, and sculptural objects.
Seating commands the deepest installed base. Storage is expanding most quickly through software-enabled specification disintermediation.
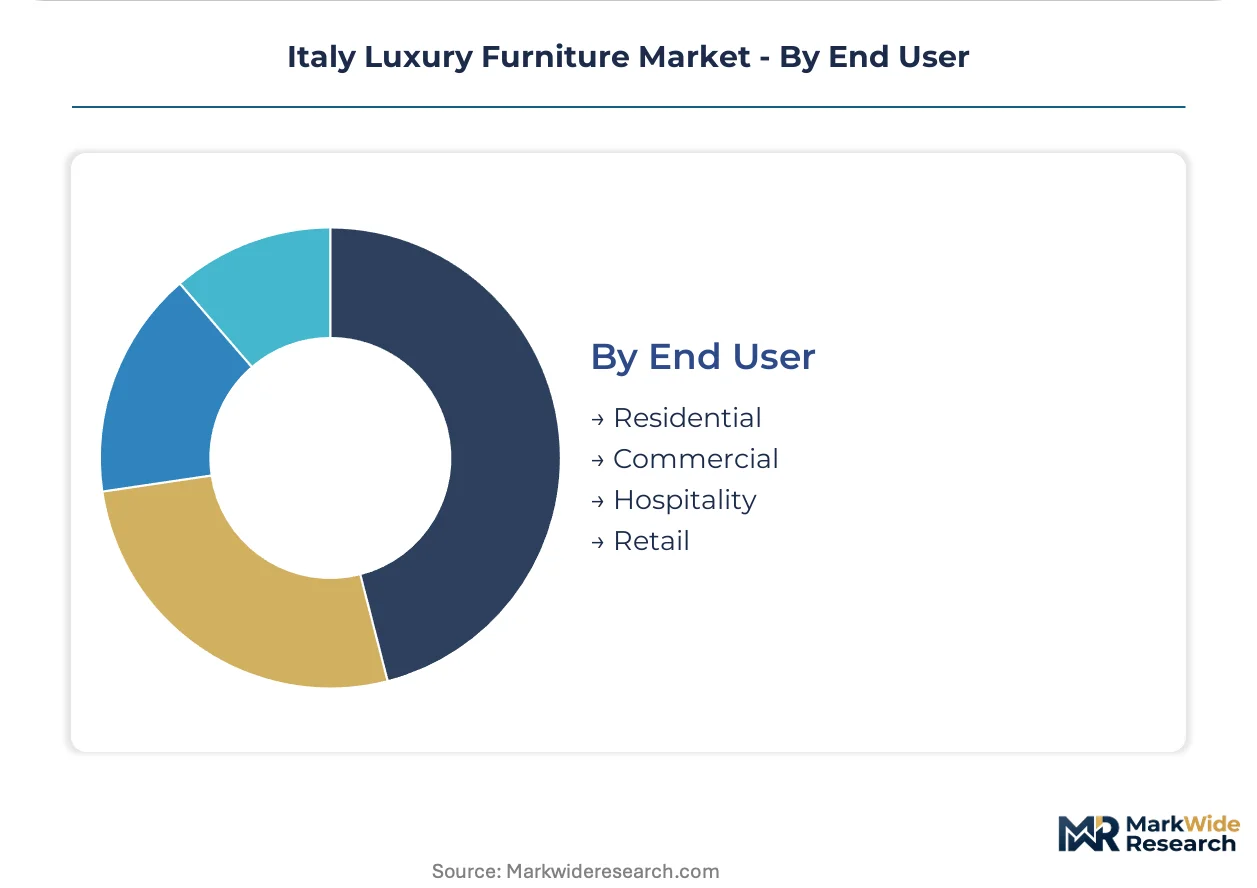
End User:
Procurement sophistication varies sharply, with institutional hospitality buyers driving certification requirements that residential clients later adopt.
- Hospitality:Boutique hotels and luxury resorts across Tuscany, Amalfi Coast, and Lake Como. Renovation cycles are pulling demand for documented provenance and embodied carbon tracking, with EU Green Deal thresholds compressing supplier qualification timelines from eighteen to nine months.
- Residential:High-net-worth households in Milan, Rome, and secondary home markets in Val d'Orcia. Digital showroom adoption is highest here, with clients configuring Poliform and Molteni&C systems independently of traditional architecture studios.
- Commercial:Corporate headquarters and private banking suites.
- Retail:Flagship stores and luxury showroom fit-outs.
Residential maintains the broadest installed base. Hospitality is climbing the fastest as boutique property development outpaces traditional luxury hotel pipeline expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where Italian luxury furniture production concentrates, as EU Green Deal compliance costs in Brianza push some finishing operations toward jurisdictions with shorter certification timelines. This migration pattern favors established manufacturing clusters that can absorb fragmented supply chain stages without sacrificing provenance documentation.
Lombardy
Milan residential towers and Lake Como second-home markets drive demand for modular storage systems and precision metalwork. The Ministry of Enterprise enforces origin labeling standards that protect artisan credentials against counterfeit imports. Brianza manufacturers in Monza and Como are compressing supplier qualification timelines from eighteen to nine months to meet EU Green Deal embodied carbon thresholds.
Veneto
Murano glass furnace operators are integrating LED substrate technology into hand-blown architectural elements for boutique hospitality projects. REACH chemical restrictions on tanning agents are forcing reformulation of surface treatments used in luxury production. Venetian artisans cluster along the lagoon, supplying decorative components to Tuscan hotel renovators seeking documented provenance.
Tuscany
Florence and Siena boutique hotels are embedding Product Environmental Footprint scores into RFP evaluation matrices for seating and case goods. The EU Green Deal's Ecodesign for Sustainable Products Regulation threatens disqualification of traditional resin-based composite finishes. Artisans in the Chianti corridor are piloting subscription-based interior refresh services with Lombardy-based residential clients.
Lazio
Rome high-net-worth households are configuring Poliform and Molteni&C systems independently through digital showrooms, bypassing traditional architecture studios. Italy's stringent environmental certifications under the EU Green Deal are reshaping material sourcing requirements. Upholstery specialists in the capital face twelve-month recruitment timelines for hand-stitching specialists proficient in full-grain leather.
Piedmont
Turin-based precision metalworking suppliers serve minimalist frame manufacturers across the northern industrial triangle. Balkan and French timber sourcing constraints are elevating raw material costs for heritage woodworkers. The concentration of seventy percent of precision metalworking capacity within forty kilometers of Monza creates earthquake and labor-strike exposure for the regional supply base.
Italy Luxury Furniture Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with heritage design houses commanding premium positioning in residential specification while industrial-scale producers capture hospitality volume. The vendor base clusters around three strategic archetypes: integrated manufacturing specialists with captive Brianza production, design-licensing houses leveraging parametric customization platforms, and artisan collectives preserving guild-trained techniques for limited-batch output. Competitive moves concentrate on backward integration into timber harvesting and tannery operations, alongside technology licensing for software-driven configuration tools.
Among design-licensing and integrated manufacturing specialists, B&B Italia, Poliform, and Molteni&C occupy positions that exemplify divergent responses to regulatory compression and specification disintermediation. B&B Italia represents the heritage-design archetype sustaining premium positioning across European capitals through lineage-based brand equity. Poliform sits within the modular-systems tier commanding higher lifetime value from repeat residential clients configuring independently via digital platforms. Molteni&C anchors the integrated-manufacturing archetype through captive production in the Brianza furniture district, exemplifying how geographic concentration can double as competitive moat and regulatory vulnerability.
| Leading Market Players |
|---|
| B&B Italia |
| Giorgetti |
| Minotti |
| Poliform |
| Moroso |
| Poltrona Frau |
| Flexform |
| Molteni&C |
| Cassina |
| Others |
Supply & Pricing Matrix
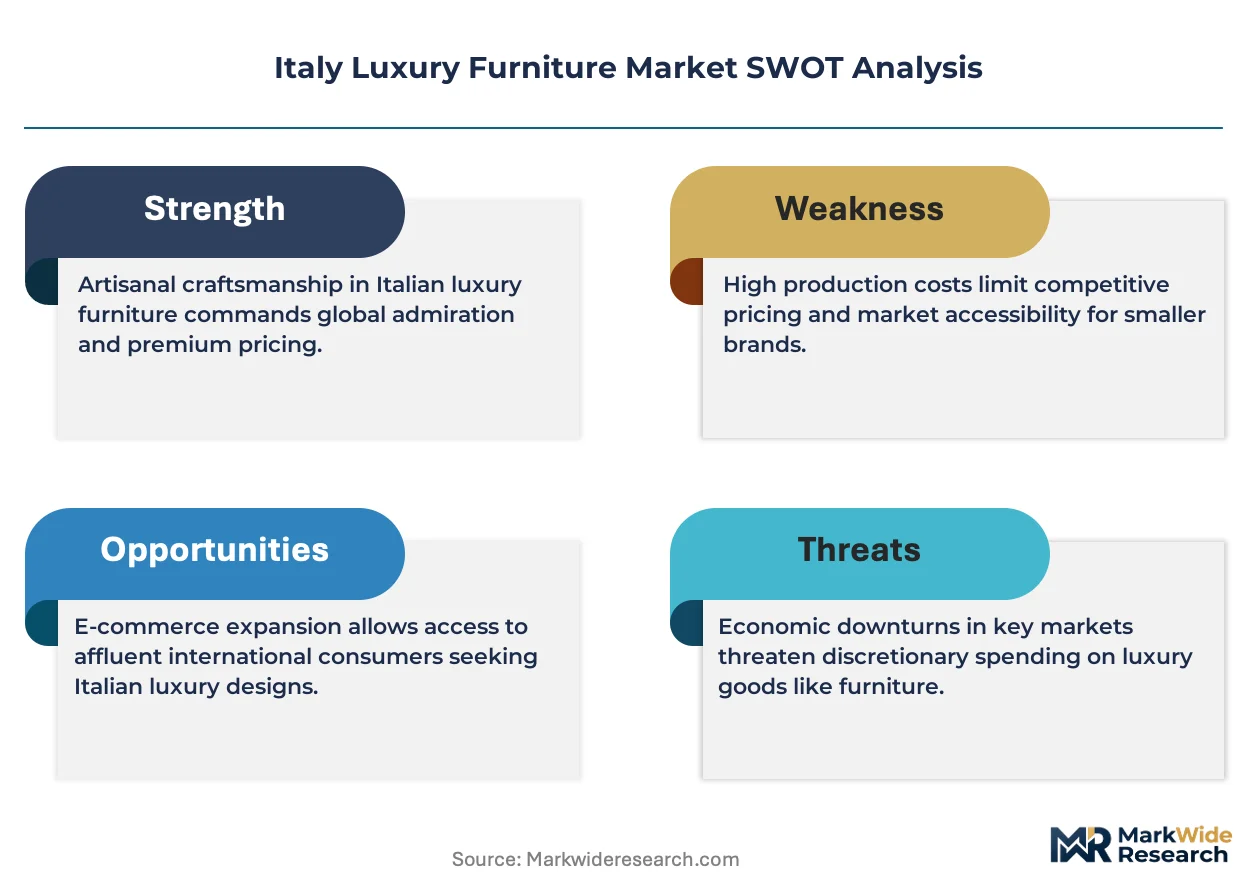
Certification-grade bifurcation between EU Green Deal-compliant producers and legacy finishers splits pricing power across the Brianza manufacturing cluster. Heritage artisans commanding documented carbon credentials extract premium positioning from institutional hospitality buyers, while uncertified workshops face margin compression from compressed supplier timelines and reformulation costs.
Pricing Analysis
Distributor markups of thirty-five to fifty percent separate Brianza manufacturers from Milan residential specifiers and Tuscan hotel developers. Three-tier pricing structure across heritage artisan, industrial-certified, and commodity-import levels tracks EU Green Deal compliance status and origin documentation depth. Pricing pressure stems from REACH-mandated adhesive reformulation costs passed through tannery and lacquer suppliers. Boutique hospitality buyers show lowest price sensitivity, prioritizing provenance documentation and carbon disclosure over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from institutional buyers mandate Croatian and French timber qualification alongside domestic Italian walnut reserves. Solid walnut, full-grain leather from Romanian tanneries, and hand-blown Murano glass form the core material dependencies. Single-source vulnerability concentrates in the forty-kilometer Monza metalworking corridor, where earthquake or labor disruption would stall precision hardware flows. Distribution runs through architect-specified channels, direct digital showroom platforms, and hospitality procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Italy luxury furniture market compounds steadily through regulatory differentiation that rewards early compliance investment and penalizes lagging reformulation.
For Market Incumbents: Extend backward integration into Croatian timber harvesting and Romanian tannery operations to secure chain-of-custody documentation required by EU Green Deal thresholds. Lock in Brianza artisan capacity through exclusive contracting before competitor qualification timelines compress further. Certification investment represents the critical lever against emerging industrial-scale entrants with faster compliance turnaround. For New Entrants and Emerging Players: Launch via direct-to-consumer digital showrooms targeting under-forty high-net-worth households configuring second homes in Val d'Orcia and Lake Como. The residential segment's disintermediation trend offers the most penetrable entry point, with software-driven customization platforms collapsing traditional architect-furniture studio relationships. White-space exists in subscription-based refresh services piloting three-year replacement cycles in Lombardy. For Investors and Strategic Acquirers: Consolidation pressure builds where dual certification burdens stretch quality assurance departments beyond mid-scale operational capacity. The five-to-ten year viability window favors targets with captive Brianza production and early Product Environmental Footprint compliance. Watch for Ecodesign threshold finalization as the signal for accelerated M&A among heritage artisans facing disqualification risk from resin-based composite finishes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timber Harvesting | Secures Croatian and French chain-of-custody documentation for EU Green Deal compliance. |
| Digital Showroom Platform Launch | Captures disintermediated Milan and Rome residential buyers configuring systems independently. |
| Product Environmental Footprint Early Certification | Unlocks preferential procurement from Tuscany and Amalfi Coast boutique hotel developers. |
| Murano Glass LED Substrate Integration | Converges Venetian furnace heritage with architectural lighting demand from hospitality renovators. |
| Subscription Refresh Service Pilot | Extends lifetime value from repeat Lombardy residential clients through retained asset ownership. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged furniture manufacturing executives, hospitality procurement directors, Brianza artisan guild representatives, and EU regulatory compliance officers. Secondary validation drew from Italian Ministry of Enterprise origin labeling databases, ECHA REACH substance restrictions, EU Green Deal implementation guidance, and Brianza industrial association production statistics. Bottom-up capacity modeling and top-down demand estimation triangulated volume and value outputs.
Historical reference periods anchored the projection horizon to pre-pandemic baseline demand and post-regulatory implementation trajectory. Segmentation modeling incorporated material type, design style lineage, functionality application, and end-user procurement sophistication. CAGRs derived from regression analysis against residential construction permits, hospitality development pipelines, and certification adoption curves. Forecast inputs included EU Ecodesign threshold evolution and parametric design software penetration rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated Ecodesign implementation or Balkan timber supply disruption. Deviation in EU Green Deal enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Furniture & Cabinet Hardware Market
Furniture
Asia-Pacific Free Standing Electrical Height-Adjustable Tables Market
Furniture
North America High-End Furniture Market
Furniture
HORECA Furniture Market
Furniture
Ergonomic Chair Market
Furniture
North America School Furniture Market
Furniture
Italy Home Furniture Market
Furniture
Global Multifunctional Home Furniture Market
Furniture
Bean Bag Chairs Market
Furniture
RTA Furniture Market
Furniture
Exam Tables Market
Furniture
Pedicure Chair Market
Furniture
Europe Furniture Market
Furniture
Piano Stools Market
Furniture
High Density Fiberboard (HDF) Market
Furniture
Bar Stools Market