
 South America Bottled Water Market | 2026-2036
South America Bottled Water Market Size, Share, and Industry Trends Forecast 2026-2036
South America Bottled Water Market Analytics
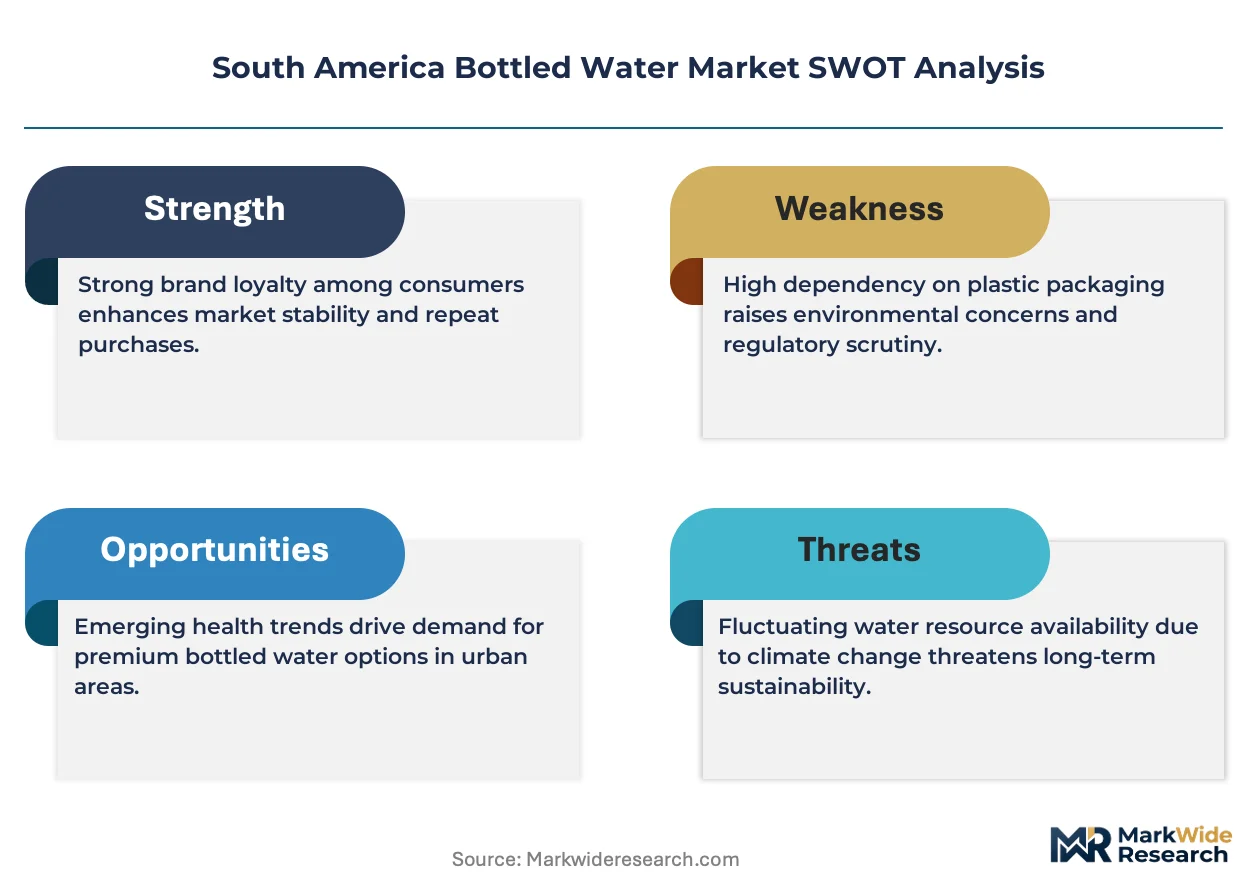
Brazilian spring water extraction capacity is shifting toward sustainable aquifer management as producers face mounting environmental scrutiny. Nestlé S.A. leverages its extensive spring network across Minas Gerais to anchor premium positioning. The Coca-Cola Company sustains volume leadership through Dasani's purified water infrastructure. Danone S.A. competes via Evian's imported mineral water niche in São Paulo's upscale retail channels.
Bottled water in South America comprises packaged drinking water sourced from springs, wells, or municipal supplies, then treated through reverse osmosis, ultraviolet sterilization, or ozonation to meet potable standards with total dissolved solids typically below 500 mg/L for purified variants. Still water dominates supermarket shelves across the region, while sparkling water captures accelerating demand in Brazil's restaurant sector. Plastic bottles remain the volume backbone despite rising PET recycling mandates, whereas glass bottles command margin pools in Argentina's fine-dining HoReCa segment.
ANVISA governs microbiological and chemical safety thresholds for bottled water sold in Brazil, while MERCOSUR's harmonized food code facilitates cross-border trade among member states. Argentina's national food regulator enforces stricter mineral content disclosure for waters marketed with therapeutic claims. Stakeholders must monitor groundwater extraction licensing reforms and packaging waste extended producer responsibility laws that will reshape cost structures and regional competitive dynamics.
Market Dynamics
Groundwater extraction licensing reforms across Brazil and Argentina are forcing producers to reconfigure sourcing strategies while ANVISA tightens microbiological surveillance protocols. These regulatory pressures intersect with PET recycling mandates that elevate packaging compliance costs for regional bottlers.
Growth Catalysts
- Municipal water quality gaps:Persistent contamination concerns in São Paulo and Buenos Aires municipal supplies drive household substitution toward packaged alternatives. Urban distrust of tap infrastructure sustains volume pull across Brazil's southeastern states.
- ANVISA labeling modernization:Enhanced origin disclosure requirements for spring-sourced products create differentiation pathways for verified aquifer claims. Premium positioning gains regulatory reinforcement.
- Reverse osmosis infrastructure:Declining capital costs for purification systems enable mid-tier producers to achieve pharmaceutical-grade water quality without spring access. Technology democratization expands competitive entry.
Market Restraints
- PET resin price volatility:Feedstock fluctuations tied to crude oil benchmarks compress margin stability for volume-dependent purified water producers. Packaging cost exposure concentrates in Brazil's price-sensitive retail channel.
- Spring source concentration:Premium mineral water extraction licenses cluster in Minas Gerais and Córdoba provinces, creating geographic supply risk. Aquifer depletion concerns threaten long-term capacity expansion.
- MERCOSUR harmonization friction:Divergent national interpretations of cross-border food safety codes generate customs delays and redundant testing burdens. Argentina's stricter mineral disclosure rules create non-tariff barriers.
Strategic Opportunities
- Colombia's underdeveloped premium channel:Bogotá and Medellín upscale retail segments show minimal imported mineral water penetration. First-mover positioning in Andean urban centers offers margin expansion.
- Glass bottle HoReCa revival:Argentina's fine-dining sector demonstrates sustained willingness to absorb packaging premiums for tableside presentation. Channel-specific SKUs unlock price architecture elevation.
- Extended producer responsibility alignment:Brazil's advancing packaging waste laws favor producers with established reverse logistics networks. Compliance infrastructure becomes competitive moat.
Industry Challenges
- Aquifer hydrology expertise scarcity:Qualified groundwater resource assessment talent remains concentrated in academic institutions rather than commercial operations. Licensing applications face technical delays.
- Legacy PET line retrofit costs:Lightweighting and recycled content integration require substantial capital redeployment at existing facilities. Balance sheet constraints disadvantage smaller regional bottlers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Bottled Water Market |
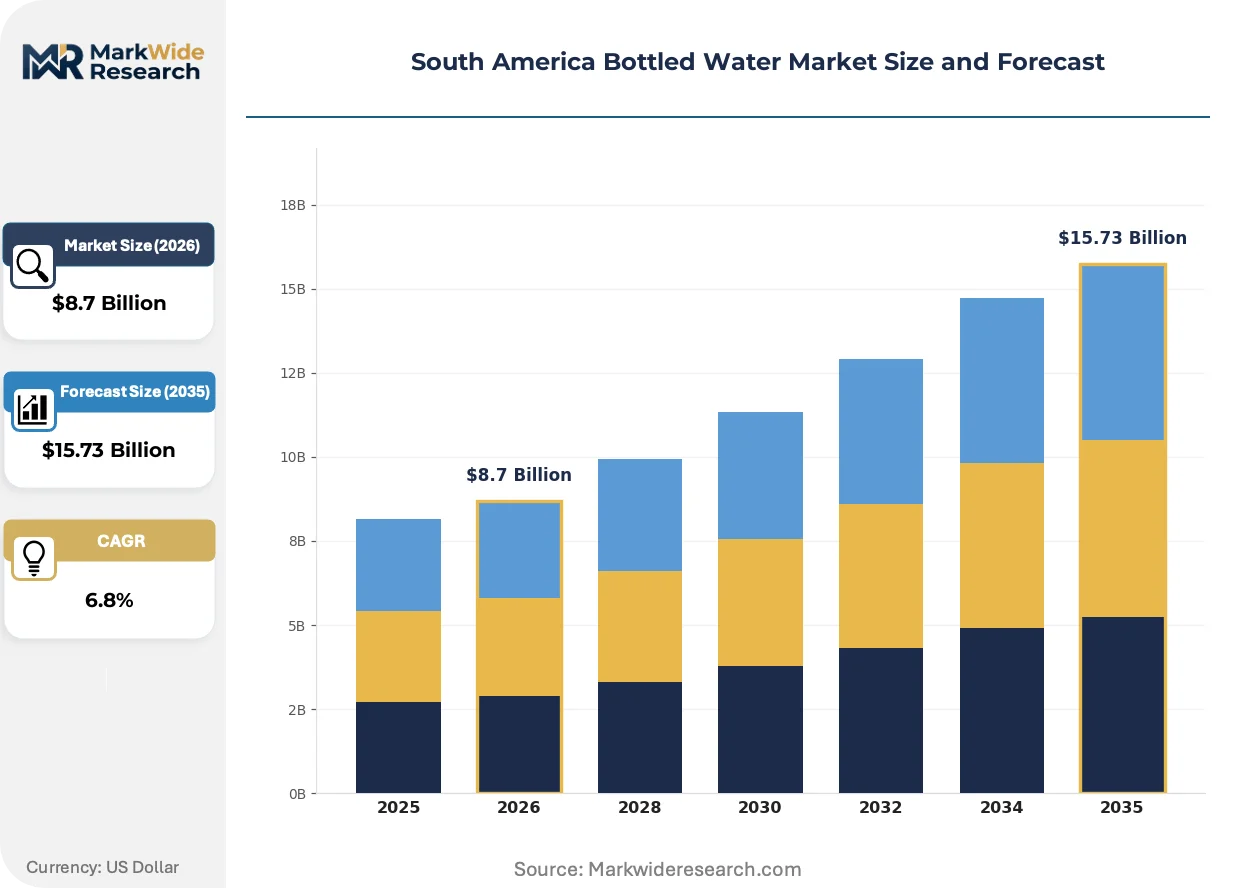
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Still Water, Sparkling Water, Flavored Water, Mineral Water Packaging Type: Plastic Bottles, Glass Bottles, Tetra Packs, Pet Jars Distribution Channel: Supermarkets, Convenience Stores, Online Retail, HoReCa End User: Household, Office, Restaurants, Gyms |
| Companies Covered | Nestlé S.A., The Coca-Cola Company, PepsiCo Inc., Danone S.A., Minalba Brasil, Compañía Cervecerías Unidas (CCU), Ambev S.A., AJE Group, Gota Water S.A., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Bottled Water Market Evolving Landscape
Sustainability certification and digital traceability systems are redefining competitive differentiation in South American bottled water. Producers now face pressure to demonstrate aquifer stewardship and supply chain transparency beyond baseline regulatory compliance.
Ultraviolet-C LED sterilization is electrifying purification workflows across Brazilian bottling facilities. Mid-scale producers in São Paulo's industrial corridor are adopting UV-C arrays to replace legacy ozonation equipment. The technology compresses energy consumption while eliminating chemical residual management, enabling real-time microbiological assurance without batch holding delays.
ANVISA's forthcoming blockchain-integrated labeling mandate is reshaping traceability obligations for spring-sourced products. The regulation will require immutable origin records from extraction point to retail shelf. Premium mineral water SKUs face the steepest compliance curve as existing paper-based chain-of-custody documentation proves inadequate for digital verification.
Direct-to-hospitality subscription models are disrupting traditional wholesale distribution in Argentina's Mendoza province. Boutique hotels and vineyard restaurants are bypassing distributor markups through contracted spring allocation agreements. The channel shift concentrates volume with relationship-managed accounts while eroding supermarket-centric volume strategies in wine-country geographies.
South America Bottled Water Market Segmentation
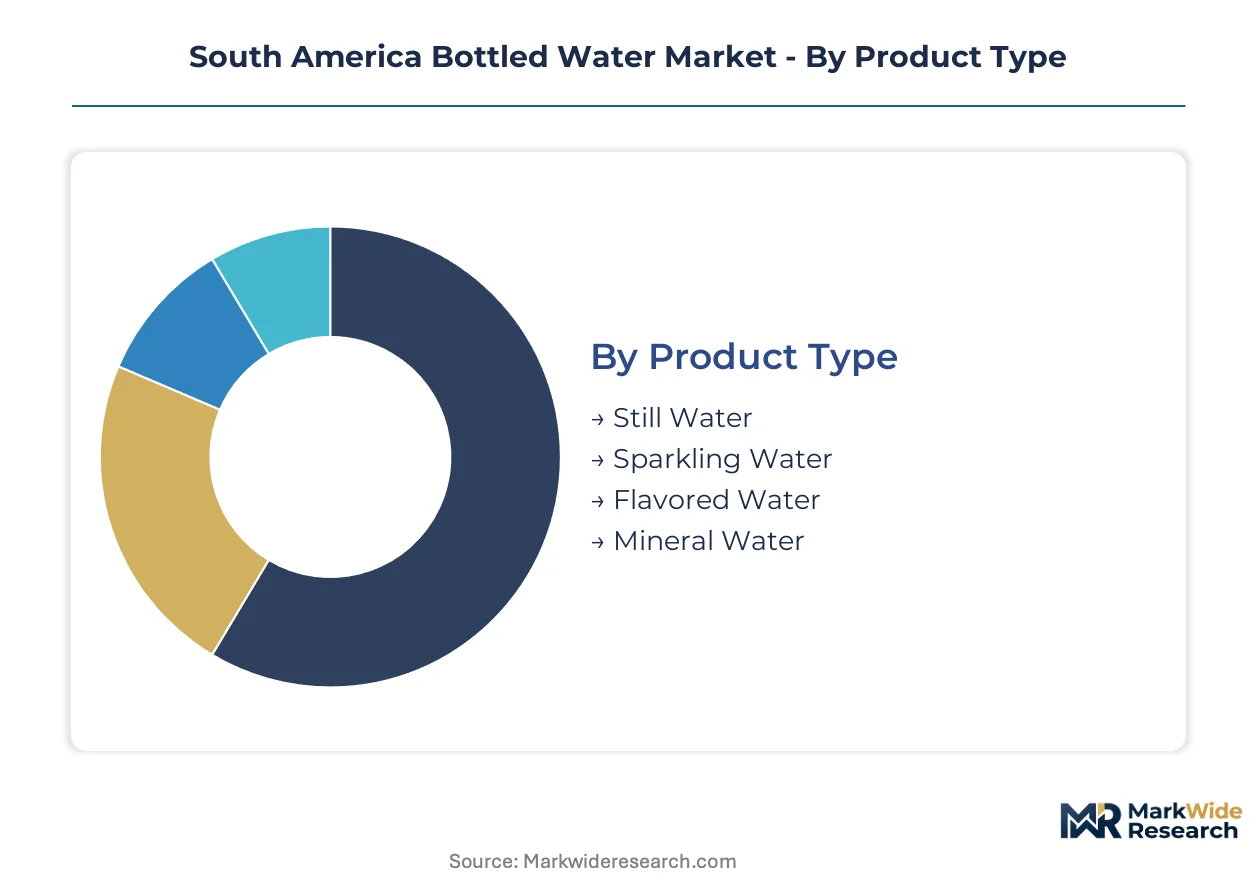
Segmentation in South American bottled water reveals how purification technology, packaging material costs, and channel access fees fragment competitive positioning across price tiers. Producers must align sourcing infrastructure with specific consumption occasions to avoid margin erosion.
Product Type:
Customization intensity runs from commodity purification to terroir-dependent mineral sourcing across this spectrum.
- Still Water:Reverse osmosis and ultraviolet-treated municipal supply dominates volume. Brazilian supermarkets in São Paulo's peripheral districts drive mass-market pull as household substitution accelerates.
- Mineral Water:Naturally sourced from protected aquifers with stable mineral composition verified by ANVISA. Premium positioning concentrates in Argentina's Mendoza province and Brazil's Minas Gerais spring clusters where extraction licensing restricts supply expansion.
- Sparkling Water:Carbonation infrastructure enables restaurant channel penetration. Buenos Aires fine-dining establishments absorb packaging premiums for tableside service.
- Flavored Water:Fruit essence infusion creates incremental margin pools. Colombian urban youth demographics show accelerating trial rates in Bogotá convenience retail.
Most installed capacity flows through Still Water. Expansion is steepest in Mineral Water.
Packaging Type:
Cost tier separation between single-use disposables and returnable systems defines capital deployment patterns.
- Plastic Bottles:PET resin dependency exposes margin volatility to crude oil benchmarks. Brazil's price-sensitive retail channel concentrates volume risk here.
- Glass Bottles:Returnable loop systems command HoReCa premiums in Argentina's Córdoba wine country. Mendoza vineyard restaurants specify tableside presentation standards.
- Tetra Packs:Aseptic carton technology reduces logistics cube for remote distribution. Andean foothill communities outside major bottling radii show adoption concentration.
- Pet Jars:Large-format dispensing containers target office and gym bulk consumption. São Paulo corporate campuses drive replacement cycle demand.
Volume concentrates in Plastic Bottles. Margin expansion concentrates in Glass Bottles.
Distribution Channel:
Geographic reach versus relationship density trade-offs structure channel economics.
- Supermarkets:Shelf-space fees and promotional slotting costs dominate working capital requirements. Brazil's southeastern states anchor national volume distribution.
- HoReCa:Direct-to-hospitality subscription models in Argentina's Mendoza province bypass distributor markups. Boutique hotels contract spring allocation agreements.
- Convenience Stores:Impulse purchase velocity rewards localized bottling proximity. Colombian urban corridors show penetration gaps versus Brazilian density.
- Online Retail:Heavy-weight shipping economics constrain premium mineral water expansion. São Paulo's upscale districts demonstrate viable last-mile fulfillment.
Revenue concentrates in Supermarkets. Relationship intensity concentrates in HoReCa.
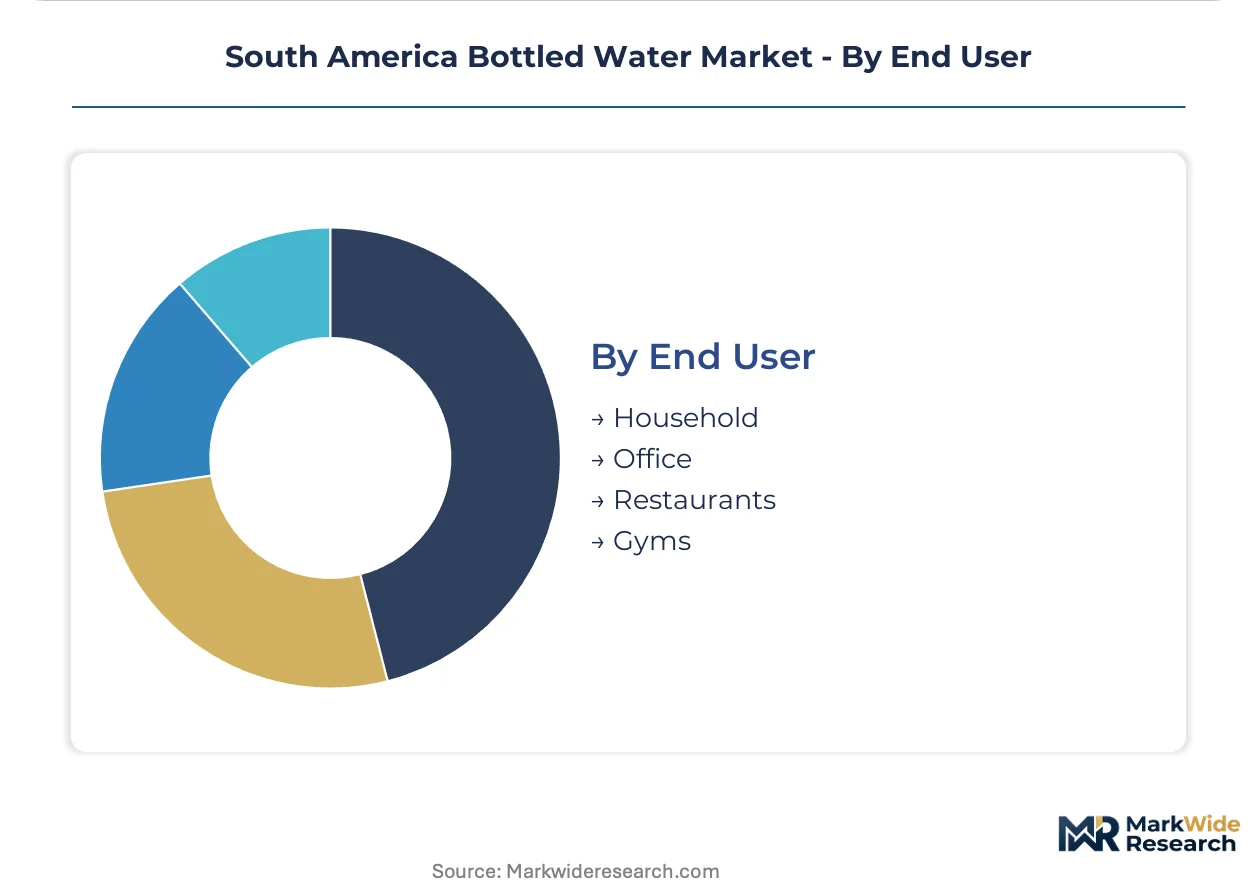
End User:
Consumption occasion specificity determines packaging format and purchase frequency.
- Household:Multi-liter stocking patterns dominate Brazilian urban substitution behavior. Municipal water quality distrust in São Paulo sustains pantry-loading.
- Restaurants:Tableside presentation standards in Argentina's fine-dining segment absorb glass bottle premiums. Mendoza wine tourism concentrates demand seasonality.
- Office:Cooler-based dispensing systems create recurring delivery contracts. São Paulo corporate districts show consolidation toward single-provider agreements.
- Gyms:Single-serve convenience drives vending placement economics. Brazilian fitness chain expansion creates location-specific volume clusters.
Volume concentrates in Household. Premium pricing concentrates in Restaurants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as Brazilian states tighten groundwater extraction licensing while Argentine provinces relax mineral water marketing rules. Producers migrate capacity toward jurisdictions with lower compliance friction.
Brazil
São Paulo's municipal water quality failures sustain household substitution demand across southeastern states. ANVISA's blockchain-integrated labeling mandate elevates traceability costs for spring-sourced producers. Minas Gerais spring clusters concentrate premium mineral water licensing where aquifer access restrictions limit new entrant capacity.
Argentina
Córdoba and Mendoza provinces anchor fine-dining HoReCa demand for glass-bottle tableside presentation. The national food regulator enforces stricter mineral content disclosure than MERCOSUR baseline standards. Mendoza vineyard restaurants bypass traditional distribution through direct spring allocation contracts with boutique producers.
Colombia
Bogotá and Medellín upscale retail segments show underdeveloped imported mineral water penetration versus Brazilian equivalents. The country's national food safety authority applies less stringent origin verification than ANVISA. Andean foothill communities outside major bottling radii drive Tetra Pack adoption for remote distribution economics.
Chile
Santiago's corporate office sector generates cooler-based dispensing contract consolidation toward single-provider agreements. The national economic development agency promotes packaging waste extended producer responsibility alignment. Valparaíso port infrastructure facilitates cross-border trade friction with Argentine producers under MERCOSUR harmonization.
Peru
Lima's urban middle-class expansion creates convenience store impulse purchase velocity for localized bottling proximity. The country's environmental ministry advances PET recycling mandates following Brazilian regulatory precedent. Arequipa's southern industrial corridor shows emerging spring water extraction interest amid coastal aquifer salinity concerns.
South America Bottled Water Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-hospitality subscription models that bypass distributor markups. The market structures around three tiers: multinational beverage conglomerates with purified water infrastructure, regional spring-source specialists with ANVISA-compliant aquifer networks, and niche importers serving São Paulo's upscale retail channel. Strategic archetypes include scale-driven volume leaders, terroir-dependent premium positioners, and technology-enabled mid-tier purifiers. Dominant competitive moves center on M&A consolidation of spring extraction licenses and portfolio diversification into flavored water extensions.
Among Swiss-incorporated beverage conglomerates, Nestlé S.A. exemplifies the premium mineral water archetype through spring network control. The Coca-Cola Company represents scale-driven purified water dominance via infrastructure density. Danone S.A. occupies the imported niche positioning tier in Brazilian upscale channels. These three anchors illustrate how geographic origin and corporate structure map to competitive segmentation without prescribing specific strategic actions.
| Leading Market Players |
|---|
| Nestlé S.A. |
| The Coca-Cola Company |
| PepsiCo Inc. |
| Danone S.A. |
| Minalba Brasil |
| Compañía Cervecerías Unidas (CCU) |
| Ambev S.A. |
| AJE Group |
| Gota Water S.A. |
| Others |
Value Network & Pricing Analysis
Family-owned spring-source specialists across Minas Gerais and Córdoba provinces anchor supply discipline through generational aquifer stewardship, translating extraction-license scarcity into sustained premium pricing power while resisting volume-driven margin erosion.
Pricing Analysis
Distributor margin layers in Brazil's supermarket channel absorb 18-25 percentage points before shelf placement, compressing netback realization for purified water producers competing on ANVISA-compliant volume. Three-tier pricing structure across premium mineral, standard spring, and economy purified levels stratifies by certification depth and origin verification intensity. Pricing pressure stems from PET resin feedstock volatility tied to crude benchmarks, eroding stability for Brazil's price-sensitive retail tier. Household substitution demand in São Paulo's peripheral districts shows highest price elasticity, while Mendoza vineyard restaurants demonstrate lowest sensitivity.
Supply Chain Analysis
Groundwater hydrology expertise scarcity in São Paulo's technical labor pool constrains licensing application velocity, forcing producers to recruit from academic institutions rather than commercial operations. Supply concentration clusters in Brazil's Minas Gerais spring networks, Argentina's Córdoba aquifer systems, and Chile's Valparaíso distribution corridor. Raw material dependencies center on PET resin, glass cullet for returnable loops, and UV-C LED sterilization arrays. Single-source vulnerability concentrates in Minas Gerais extraction licenses where ANVISA restrictions cap new entrant capacity. Distribution runs through supermarket wholesale networks in Brazil, direct-to-hospitality subscriptions in Mendoza, and convenience store density plays in Colombian urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ANVISA's blockchain-integrated labeling mandate creates compliance moats that deepen with each enforcement cycle, structurally advantaging producers with pre-positioned traceability infrastructure.
For Market Incumbents: Lock in spring extraction license renewal priority through documented aquifer stewardship investments ahead of Brazilian groundwater reform implementation. Consolidate reverse logistics networks to capture extended producer responsibility compliance advantages as packaging waste laws advance. Threat concentration sits with mid-tier UV-C enabled purifiers achieving pharmaceutical-grade quality without spring access. For New Entrants and Emerging Players: ANVISA's blockchain labeling mandate in Brazil opens a window for technology-forward entrants with native digital traceability architecture. Target Colombia's Bogotá upscale retail segment where imported mineral water penetration lags Brazilian equivalents by substantial margin. Pursue direct-to-hospitality subscription models in Mendoza wine country bypassing traditional distributor markups. For Investors and Strategic Acquirers: Valuations sit cheapest among regional spring-source specialists with ANVISA-compliant aquifer networks but underdeveloped HoReCa channel penetration. Long-term viability hinges on extraction license renewal security and regulatory compliance infrastructure depth. Watch ANVISA enforcement intensity as inflection signal distinguishing premium-positioned acquirers from commodity-exposed targets.| Strategic Initiative | Industry Significance |
|---|---|
| Spring Extraction License Consolidation | ANVISA compliance moats deepen as Brazilian groundwater reforms restrict new capacity. |
| UV-C LED Sterilization Deployment | São Paulo mid-tier producers replace legacy ozonation with energy-efficient microbiological assurance. |
| Direct-to-Hospitality Subscription Launch | Mendoza vineyard restaurants bypass distributor markups through contracted spring allocation agreements. |
| Blockchain Traceability Integration | ANVISA's forthcoming labeling mandate rewards producers with pre-positioned digital chain-of-custody systems. |
| Extended Producer Responsibility Alignment | Brazil's advancing packaging waste laws favor established reverse logistics network operators. |
Research Methodology
Multiple input streams — regulatory filing analysis, channel inventory audits, and extraction licensing databases — were reconciled against primary interviews with spring-source producers, ANVISA compliance officers, supermarket category buyers, and HoReCa procurement managers. Secondary validation drew from ANVISA public consultation records, MERCOSUR harmonization documentation, Brazilian customs trade data, and provincial environmental ministry groundwater assessments. Bottom-up volume modeling triangulated with top-down macroeconomic consumption elasticity estimates.
Historical consumption patterns were cross-referenced against panel input from regional distribution executives to anchor projection trajectories across the analysis window. Segmentation dimensions modeled include product type, packaging format, distribution channel, and end-user occasion. CAGRs were derived from fitted growth curves incorporating municipal water quality substitution elasticity, PET resin price volatility assumptions, and regulatory compliance cost escalators specific to ANVISA and MERCOSUR frameworks.
Revisions become necessary when ANVISA enforcement intensity exceeds modeled thresholds, MERCOSUR harmonization generates unexpected non-tariff barriers, or aquifer depletion concerns trigger extraction moratoria in Minas Gerais or Córdoba. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Hydration Infusers Market
Beverages
GCC Bottled Water Market
Beverages
Coconut Milk Beverages Market
Beverages
Coconut Water Market
Beverages
South America Energy Drink Market
Beverages
Ready-To-Drink (RTD) Beverages Market
Beverages
Plant-Based Energy Drink Market
Beverages
Baby Drinking Water Market
Beverages
Superfood Infused Beverages Market
Beverages
Mixers Market
Beverages
Latin America Sports and Energy Drinks Market
Beverages
Nitro-Infused Cola Market
Beverages
United Kingdom Energy Drink Market
Beverages
Sparkling Soda Market
Beverages
Commercial Drink Mixers Market
Beverages
Water Flavor Market