
 Global Peelable Lidding Films Market | 2026-2036
Global Peelable Lidding Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global Peelable Lidding Films Market Outlook
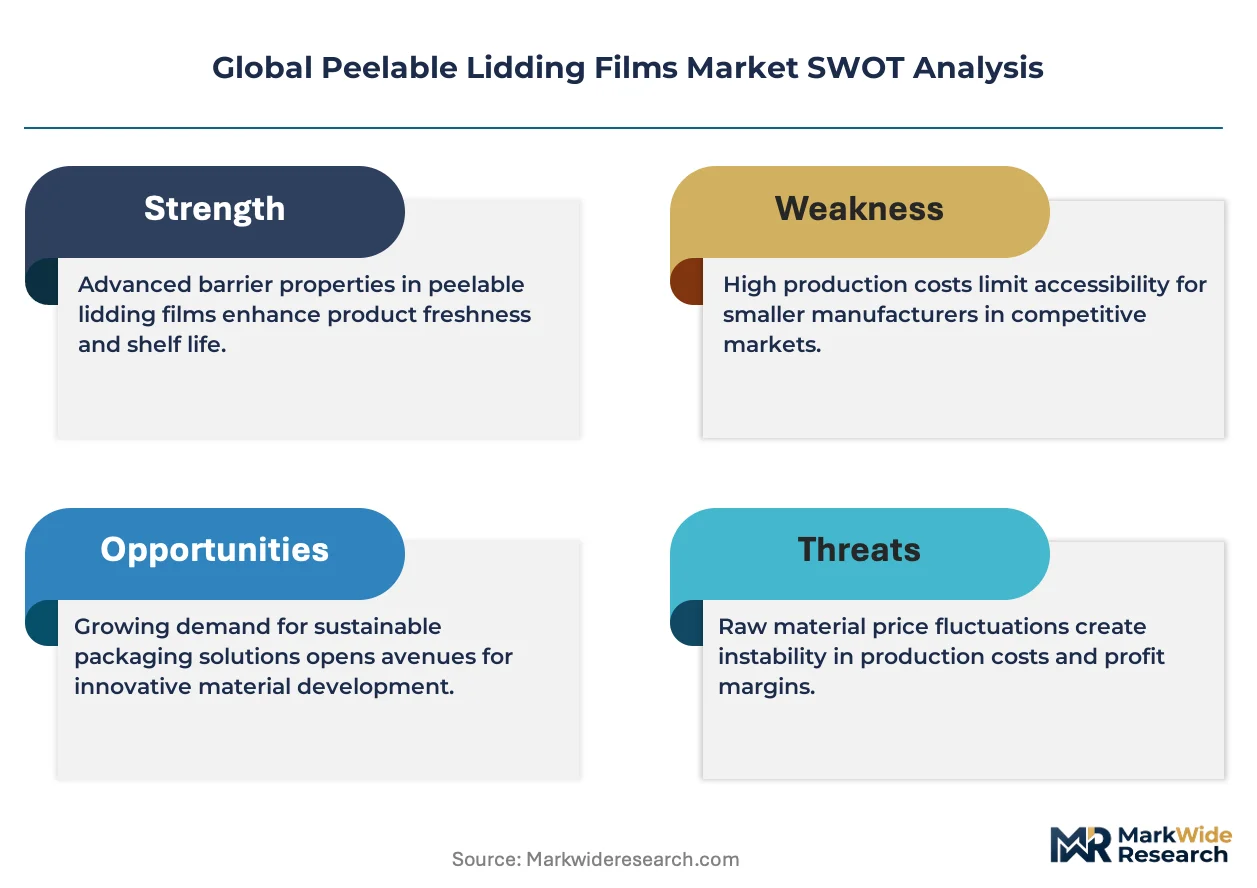
ISO 22000 food safety certification is unwinding competitive access for suppliers lacking integrated quality management systems. Amcor leverages its global manufacturing footprint to sustain multi-regional supply contracts for fresh protein packaging. Toray Plastics anchors Japanese demand through specialized polyester film lines with controlled peel-force tolerances. Berry Global competes via vertical integration from resin compounding through finished rollstock conversion.
Peelable lidding films are multilayer polymer structures, typically 25–75 micrometers thick, engineered with sealant layers that fracture cohesively at predetermined force thresholds to enable clean tray opening without residue transfer. These films serve as hermetic closures for modified-atmosphere and vacuum-sealed containers across refrigerated and shelf-stable distribution chains. Transparent films dominate fresh produce applications where visual product inspection drives purchase decisions, while metalized variants command premium positioning in oxygen-sensitive dairy and ready-meal segments. Heat seal configurations retain volume leadership across tray-sealing equipment installed bases, though cold seal technologies are gaining traction in temperature-critical medical device packaging where thermal exposure risks product degradation.
FDA food contact substance notifications govern resin additive packages in US-bound film production, while EFSA migration limits and REACH substance restrictions constrain European formulation choices. China's GB standards and NMPA medical packaging requirements create parallel compliance pathways for Asia-Pacific supply chains. Stakeholders must monitor evolving extended producer responsibility frameworks and single-use packaging directives across multiple jurisdictions to anticipate material substitution timelines and capital redeployment needs.
Market Dynamics
Europe's F-Gas Regulation is forcing rapid material transitions across sealant layer formulations, compressing development cycles for multilayer structures while REACH substance restrictions simultaneously constrain additive packages available to compounders.
Growth Catalysts
- Modified-atmosphere packaging:Retailers in Germany are standardizing tray specifications across private-label protein programs, pulling volume through centralized distribution networks.
- REACH compliance:ECHA substance restrictions are accelerating substitution toward bio-based sealant chemistries in premium fresh produce segments.
- Cold seal technology:Medical device manufacturers are adopting ambient-temperature sealing to protect temperature-critical sterile contents from thermal degradation.
Market Restraints
- Resin supply concentration:Specialty polyester feedstock production clusters in Japan and Germany, exposing converters to single-source disruption risk.
- Migration limit complexity:EFSA's evolving specific migration limits for oligomers force repeated formulation recertification, extending qualification timelines.
- Paperboard substitution:Fiber-based lidding solutions for dry ambient categories are capturing share in sustainability-driven retail procurement.
Strategic Opportunities
- India cold chain expansion:FSSAI's mandatory food safety audits are driving first-time MAP adoption in organized retail meat and dairy channels.
- RFID integration:Convergence of peelable films with printed electronics enables unit-level traceability for pharmaceutical serialization mandates.
- Extended producer responsibility:EU Green Deal packaging directives will create premium positioning for mono-material recyclable structures versus incumbent multilayer barriers.
Industry Challenges
- Peel-force calibration talent:Thin-gauge coextrusion operators with controlled delamination expertise command scarcity premiums in labor markets.
- ISO 22000 integration:Food safety management system certification requires twelve-to-eighteen-month implementation cycles, gating supplier qualification.
- Legacy tray-sealing equipment:Heat-seal dominant installed bases create retrofit friction for cold-seal film conversions in medical packaging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Peelable Lidding Films Market |
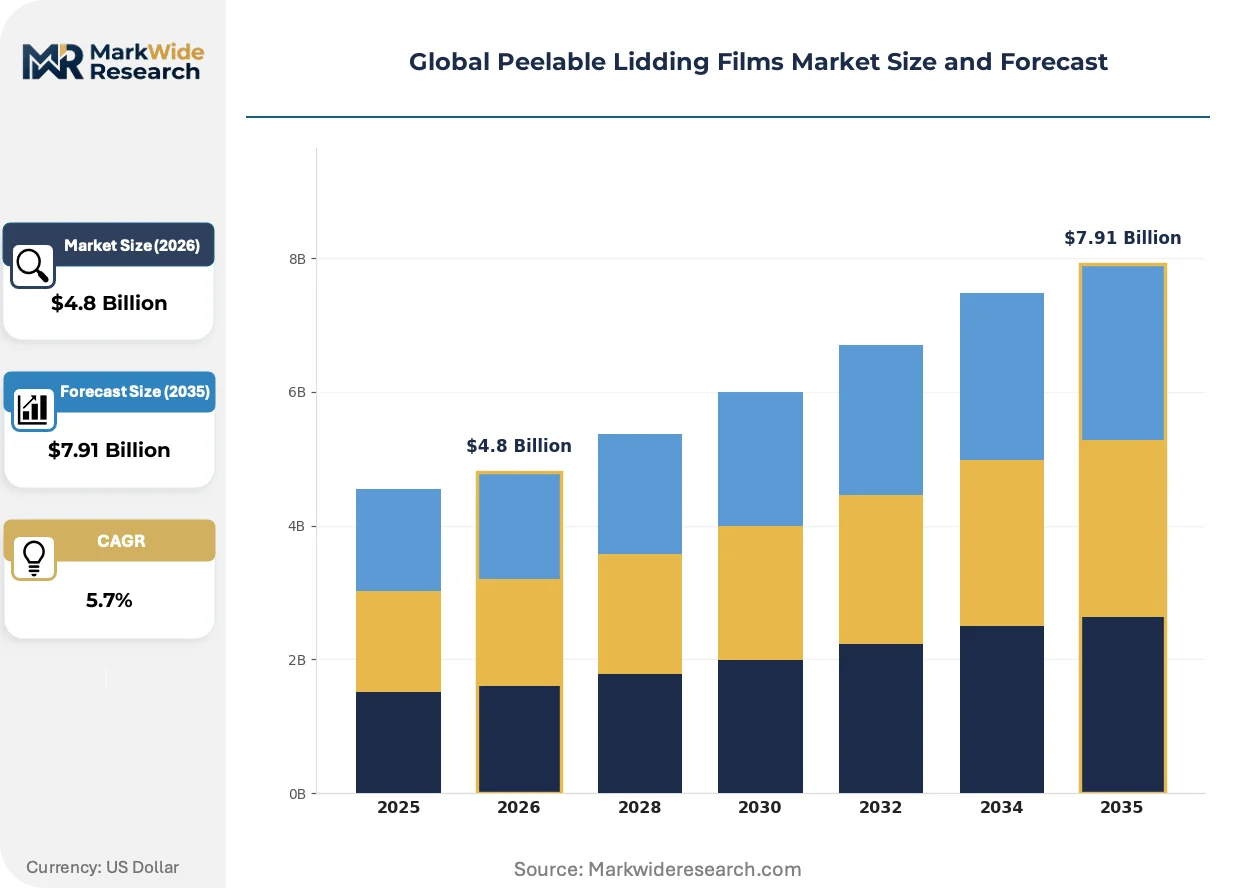
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent Films, Metalized Films, Coated Films, Laminated Films Application: Food Packaging, Medical Packaging, Consumer Goods, Electronics Packaging Material: Polypropylene, Polyethylene, Polyvinyl Chloride, Cellulose Seal Type: Heat Seal, Cold Seal, Pressure Seal, Adhesive Seal |
| Companies Covered | Amcor, Toray Plastics, DuPont Teijin Films, ProAmpac, Berry Global, Sealed Air, Uflex Limited, Mondi Group, Constantia Flexibles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Peelable Lidding Films Market Strategic Shifts
Material science advances and regulatory chemistry constraints are simultaneously expanding performance boundaries and compressing formulation freedom for multilayer film engineers.
Water-based acrylic cold seal coatings are fragmenting application-specific film portfolios by enabling tray sealing below forty degrees Celsius. Pharmaceutical contract packagers are qualifying these systems for biologic device containment where thermal exposure risks protein stability. The technology is fragmenting incumbent heat-seal equipment dependencies and opening medical packaging to film suppliers previously excluded by temperature limitations.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating fluoropolymer-based grease barriers from dairy lidding applications. ECHA's 2023 PFAS restriction proposal forces reformulation toward silicone-modified polyolefin alternatives with comparable lipid resistance. Premium ready-meal segments in France and Benelux are absorbing qualification costs fastest, while commodity cheese packaging delays transition pending cost parity.
Retail buyer consolidation is compressing supplier negotiation cycles and unbundling technical service from base film supply contracts. German and Dutch supermarket chains are centralizing lidding specifications across meat, produce, and ready-meal categories, displacing category-specific film sourcing. This concentration is most visible in protein tray programs where private-label volume aggregates through three national distribution hubs.
Global Peelable Lidding Films Market Segmentation
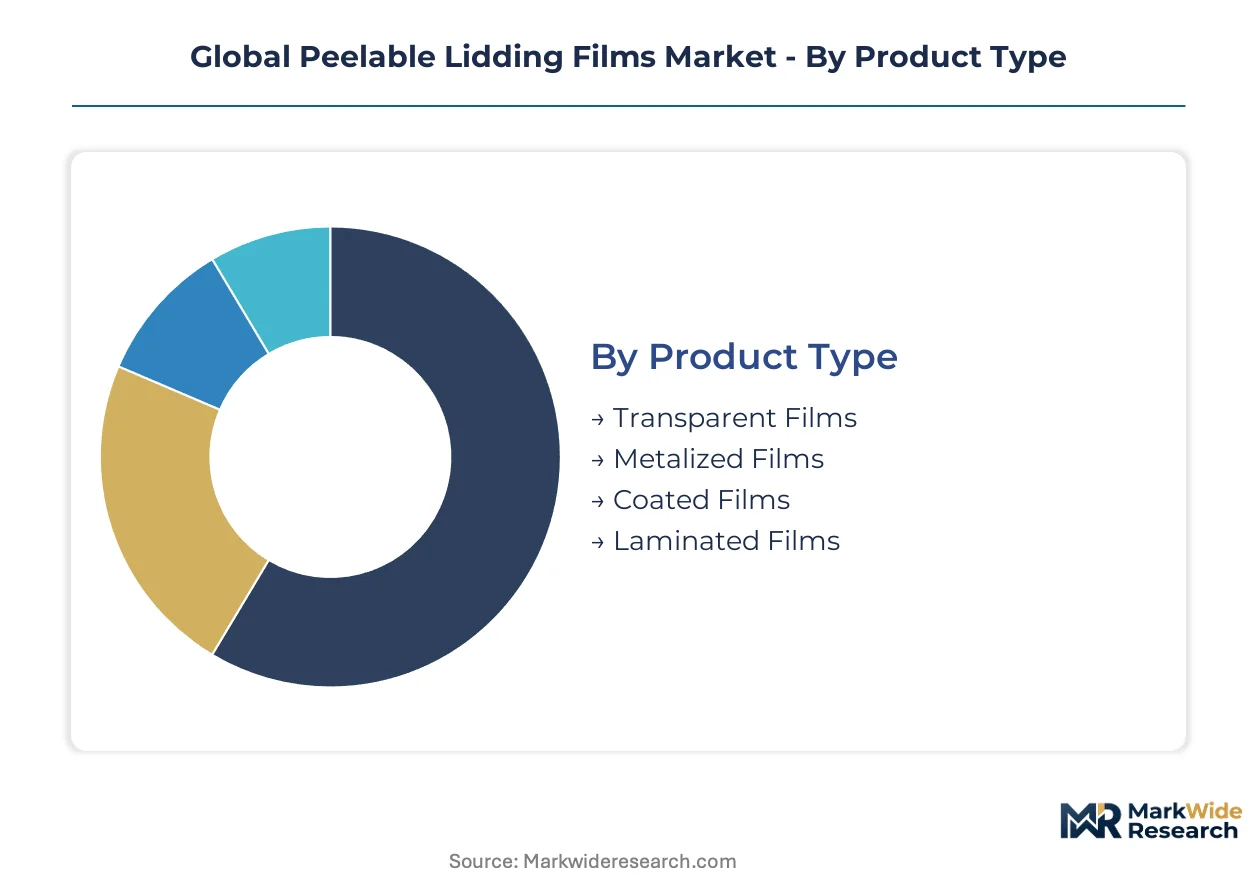
Channel configurations dictate film specification requirements across fresh protein, pharmaceutical, and retail-ready segments. Retailer consolidation in Germany and cold chain expansion in India create divergent demand profiles that suppliers must address through portfolio stratification.
Product Type:
Channel mix varies sharply by optical requirement and barrier specification, with fresh produce retailers demanding visual transparency while dairy processors prioritize oxygen exclusion through metalized constructions.
- Transparent Films:Multilayer coextrusions with clarified polypropylene or amorphous polyester cores deliver shelf visibility for fresh produce and protein trays. German supermarket chains standardize these specifications across private-label programs, pulling volume through centralized distribution hubs that favor optical consistency.
- Metalized Films:Vacuum-deposited aluminum layers on polyester or polypropylene substrates create oxygen barriers for oxygen-sensitive dairy and ready-meal applications. Premium positioning in French and Benelux retail channels absorbs higher material costs where extended shelf life justifies specification.
- Coated Films:Acrylic or polyvinylidene chloride surface treatments modify seal response and barrier performance.
- Laminated Films:Adhesive-bonded multilayer constructions combine dissimilar polymers for specialized functional requirements.
By volume, Transparent Films leads. By growth pace, Metalized Films is ahead.
Application:
End-use cost tiers separate commodity fresh food from qualification-intensive pharmaceutical segments, with regulatory burden determining margin capture potential.
- Food Packaging:Modified-atmosphere and vacuum-sealed tray closures for refrigerated protein, produce, and ready-meals dominate unit demand. India's FSSAI-mandated food safety audits are driving first-time MAP adoption in organized retail meat and dairy channels as cold chain infrastructure expands.
- Medical Packaging:Sterile barrier systems for devices and biologics require validated seal integrity and cold-seal compatibility to protect temperature-critical contents. Pharmaceutical contract packagers in Japan and Germany are qualifying ambient-temperature sealing systems to prevent protein degradation.
- Consumer Goods:Convenience-oriented opening features for household and personal care applications.
- Electronics Packaging:Static-dissipative and moisture-barrier specifications for sensitive components.
Food Packaging captures the largest revenue pool. Medical Packaging offers the steepest expansion trajectory.
Material:
Supply concentration in specialty polyester and polypropylene feedstock creates geographic dependencies that shape converter sourcing strategies.
- Polypropylene:Clarified homopolymer and random copolymer grades provide cost-efficient sealant layers with tunable peel-force response. Production clusters in Germany and Japan expose converters to single-source disruption risk during feedstock allocation cycles.
- Polyethylene:Linear low-density formulations offer cold-temperature flexibility for frozen food and medical applications.
- Polyvinyl Chloride:Declining share in food contact applications due to ECHA substance restrictions and retailer sustainability procurement.
- Cellulose:Emerging bio-based alternatives for fiber-compatible recycling streams under EU Green Deal packaging directives.
Polypropylene holds volume leadership. Cellulose is gaining share fastest.
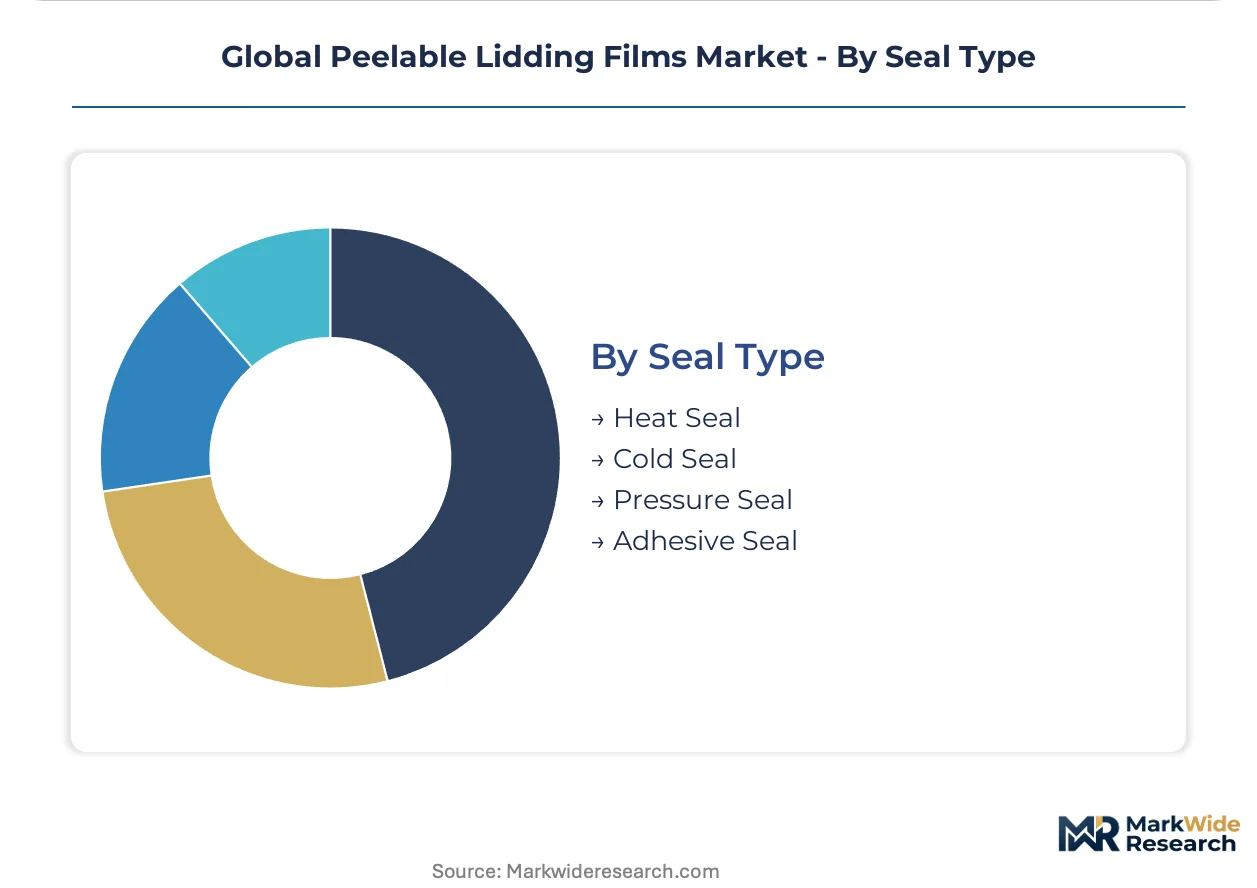
Seal Type:
Equipment installed base and thermal sensitivity requirements segment demand between heat-dominant food packaging and cold-seal medical applications.
- Heat Seal:Thermal-activated cohesive fracture layers compatible with dominant tray-sealing equipment bases across retail protein and produce operations. Legacy machine populations in European and North American converter networks create retrofit friction for alternative technologies.
- Cold Seal:Water-based acrylic coatings enable ambient-temperature sealing below forty degrees Celsius for temperature-critical pharmaceutical contents. Medical device manufacturers in Switzerland and the United States are adopting these systems to protect biologic stability.
- Pressure Seal:Mechanical interlock systems for reusable container applications.
- Adhesive Seal:Permanent or resealable constructions for extended-use consumer goods.
Heat Seal retains installed base dominance. Cold Seal is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's F-Gas Regulation and centralized retail distribution networks are accelerating material transitions and standardizing lidding specifications across European protein packaging programs.
Germany
Private-label protein tray consolidation through three national distribution hubs pulls standardized transparent film volumes. REACH substance restrictions and EFSA migration limits constrain sealant formulation choices. The Rhine-Ruhr industrial corridor hosts converter operations serving pan-European retail chains with qualified multilayer structures.
United States
FDA food contact substance notifications govern resin additive packages for fresh produce and ready-meal applications. Cold seal adoption in pharmaceutical contract packaging protects temperature-critical biologics. Greater Boston and Research Triangle Park clusters anchor medical device packaging qualification activity.
Japan
PMDA medical packaging requirements and METI industrial standards shape barrier film specifications for sterile device containment. Toray Plastics anchors domestic demand through specialized polyester lines with controlled peel-force tolerances. The Chubu region around Nagoya concentrates precision coextrusion capacity for export markets.
India
FSSAI-mandated food safety audits drive first-time modified-atmosphere packaging adoption in organized retail meat and dairy channels. Cold chain infrastructure expansion in Maharashtra and Gujarat enables tray-sealed protein distribution. Mumbai-Pune industrial corridor attracts converter investments serving domestic and Middle East export demand.
China
NMPA medical packaging requirements and GB standards create parallel compliance pathways for pharmaceutical and food contact applications. Yangtze River Delta manufacturing clusters supply both domestic retail and export converter demand. Shanghai-centered logistics networks distribute metalized barrier films for oxygen-sensitive dairy segments.
Global Peelable Lidding Films Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and qualification timelines. The vendor base stratifies into three tiers: multinational film converters with global manufacturing footprints, regional specialists with vertical resin-to-rollstock integration, and niche medical packaging qualifiers. Consolidation pressure concentrates in European fresh food segments where retailer procurement centralization favors scale. Dominant competitive moves include backward integration into resin compounding and geographic expansion through qualified toll manufacturing partnerships.
Within the multinational converter tier, Amcor leverages its global manufacturing footprint to sustain multi-regional supply contracts, while Berry Global exemplifies vertical integration from resin compounding through finished rollstock conversion. Toray Plastics occupies a specialist position anchoring Japanese demand through controlled peel-force polyester technologies. These three represent distinct archetypes: geographic scale, supply chain depth, and precision engineering specialization respectively.
| Leading Market Players |
|---|
| Amcor |
| Toray Plastics |
| DuPont Teijin Films |
| ProAmpac |
| Berry Global |
| Sealed Air |
| Uflex Limited |
| Mondi Group |
| Constantia Flexibles |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between German retail distribution hubs and specialty polyester converters lock in both supply access and price visibility across the forecast window. These arrangements insulate volume commitments from spot resin volatility while embedding REACH compliance costs into negotiated baselines.
Pricing Analysis
Certification level creates the primary spread between ISO 22000-qualified medical-grade films and commodity food-contact specifications. Three-tier pricing structure separates premium cold-seal medical constructions from standard heat-seal protein trays and economy produce-grade transparent films. Cost compression in the economy tier intensifies as fiber-based lidding alternatives capture sustainability-driven procurement. Pharmaceutical contract packagers exhibit lowest price sensitivity due to biologic stability requirements, while mass-market produce retailers negotiate aggressively on per-unit basis.
Supply Chain Analysis
Just-in-time inventory preferences dominate European fresh food channels, while Asian medical packaging converters maintain strategic stockpiles of Japanese-sourced specialty polyester. Supply concentrates in Germany, Japan, and China for clarified polypropylene and controlled-peel-force polyester substrates. Raw material dependencies include ethylene feedstock, acrylic cold-seal coatings, and vacuum-deposition aluminum. Single-source vulnerability from Toray's Chubu region production creates qualification risk for medical device manufacturers. Distribution runs through converter rollstock operations serving retail sealing equipment installed bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peelable lidding films occupy an early-cycle expansion phase as India's FSSAI-mandated food safety audits drive first-time modified-atmosphere packaging adoption in organized retail channels.
For Market Incumbents: Compound defensive positioning through backward integration into resin compounding and captive sealant layer production. Amcor and Berry Global already anchor multi-regional supply contracts; smaller converters must secure ISO 22000 certification before twelve-to-eighteen-month qualification windows close. Paperboard substitution in dry ambient categories threatens commodity tier margins. For New Entrants and Emerging Players: Anchor in India's cold chain expansion corridors around Mumbai-Pune and Maharashtra-Gujarat industrial belts. FSSAI audit requirements create first-time MAP demand among domestic meat and dairy processors lacking incumbent supplier relationships. Qualify transparent film specifications through German retail distribution hub pilots to access pan-European private-label volume aggregation. For Investors and Strategic Acquirers: Precision coextrusion specialists with controlled delamination expertise represent the most defensible acquisition archetype. Labor market scarcity for thin-gauge operators commands scarcity premiums that compound over five-to-ten year holding periods. Monitor ECHA PFAS restriction implementation timelines as inflection indicator for silicone-modified polyolefin substitution capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Berry Global's captive supply of sealant formulations insulates margin from specialty polyester allocation cycles. |
| Cold Seal Technology Qualification | Water-based acrylic coating adoption protects biologic stability for pharmaceutical contract packagers in Switzerland. |
| ISO 22000 Certification Investment | Twelve-to-eighteen-month implementation gates supplier access to German retail distribution hub contracts. |
| Mono-Material Recyclable Structure Development | EU Green Deal packaging directives premium-position recyclable films against incumbent multilayer barriers. |
| India Cold Chain Converter Capacity Expansion | Maharashtra and Gujarat infrastructure growth enables tray-sealed protein distribution for FSSAI-compliant organized retail. |
Study Parameters
Operator-level perspectives from coextrusion line supervisors, tray-sealing equipment engineers, retail category buyers, pharmaceutical contract packaging managers, and resin compounding technical directors anchored the qualitative base. Secondary validation drew from ECHA substance restriction filings, FDA food contact substance notifications, FSSAI audit protocol documents, and EU Green Deal packaging directive drafts. Bottom-up volume estimates triangulated against top-down resin consumption data from German and Japanese trade associations.
Sensitivity analysis tested forecast robustness across alternative penetration scenarios for cold seal technology and paperboard substitution rates. Segmentation dimensions modeled include product type, application, material chemistry, seal configuration, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to base-year volume estimates, with cross-checks against capital expenditure announcements from Toray Plastics and Amcor capacity additions.
Decision-makers should treat outputs as directional under assumptions of sustained REACH compliance cost pass-through and stable specialty polyester feedstock allocation; material deviation would warrant model refresh. Revision becomes warranted when ECHA PFAS restriction enforcement crosses thresholds that accelerate silicone-modified polyolefin reformulation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Self-Adhesive Films Market
Packaging Barrier Films
Transparent Barrier Packaging Films Market
Packaging Barrier Films
Barrier Coated Flexible Paper Packaging Market
Packaging Barrier Films
Pipe Insulation Film Market
Packaging Barrier Films
Biobased Anti-Blocking Agents for Flexible Packaging Films Market
Packaging Barrier Films
Anti-Static Packaging Film Market
Packaging Barrier Films
High Barrier Packaging Films for Pharmaceuticals Market
Packaging Barrier Films
Cold Seal Plastic Films Market
Packaging Barrier Films
Cap Liner Films Market
Packaging Barrier Films
Perforated Packaging Market
Packaging Barrier Films
Volatile Corrosion Inhibitors (VCI) Packaging Market
Packaging Barrier Films
Frisket Masking Film Market
Packaging Barrier Films
Decorative Films and Foils Market
Packaging Barrier Films
Breathable Lidding Film Packaging Market
Packaging Barrier Films
Child-Resistant Foil Packaging Market
Packaging Barrier Films
Heat Transfer Films Market