
 Pipe Insulation Film Market | 2026-2036
Pipe Insulation Film Market Size, Share, and Industry Trends Forecast 2026-2036
Pipe Insulation Film Market Insights
Preventive maintenance contracts bundled with insulation system audits is pivoting how distributors capture lifetime value from industrial buyers. Owens Corning leverages its fiberglass manufacturing scale to supply integrated jacketing and insulation kits for large-diameter piping. Armacell International S.A. specializes in engineered foam cores that dominate flexible elastomeric applications across commercial HVAC networks.
Pipe insulation film denotes flexible or semi-rigid polymeric barriers, typically polyethylene, polypropylene, or PVC-based, applied as wrapped or adhered layers to reduce conductive and convective heat transfer in fluid transport systems. These films function between approximately minus 50°C and 120°C service temperatures, with multilayer laminates incorporating vapor retarders to control moisture ingress beneath metal cladding. Polyethylene formulations lead volume shipments due to cost-positioning and chemical resistance in buried utility lines, while foam-based constructions command premium positioning in refrigeration and cryogenic service where closed-cell structures minimize thermal bridging. The HVAC application segment sustains the broadest end-use footprint, though industrial process piping generates disproportionate margin pools through specification-grade certification requirements.
The U.S. EPA and OSHA jointly govern worker exposure limits and material flammability standards for insulation products installed in occupied and process environments, with ASTM C547 and C1130 providing baseline thermal performance benchmarks that specifiers embed in procurement documents. The EU REACH framework and F-Gas Regulation constrain halogenated blowing agent chemistries in foam insulation films sold across member states, compelling reformulation investments from suppliers serving transatlantic project portfolios. Stakeholders must track evolving building energy codes in California and New York, where stretch goals for thermal efficiency in commercial structures are tightening permissible U-values for mechanical piping envelopes.
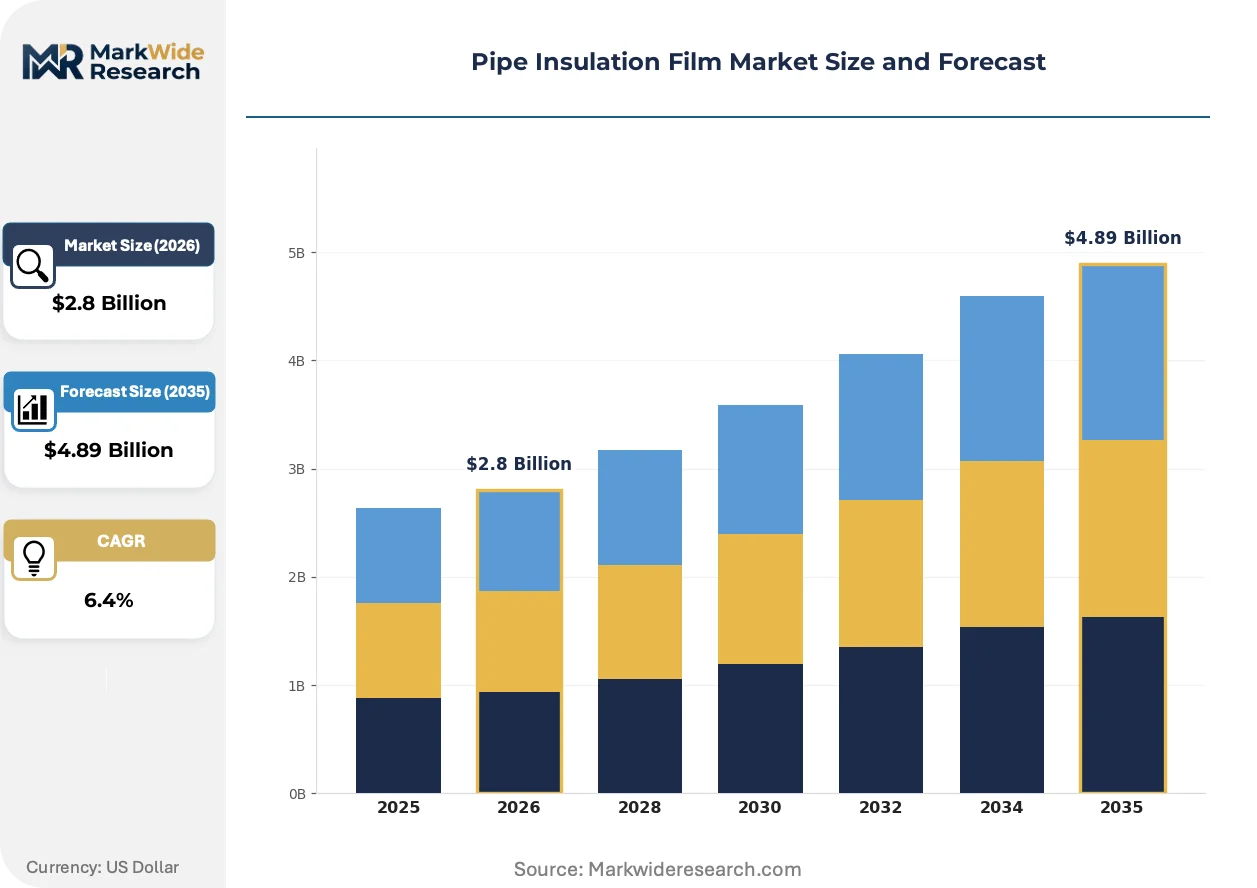
Market Dynamics
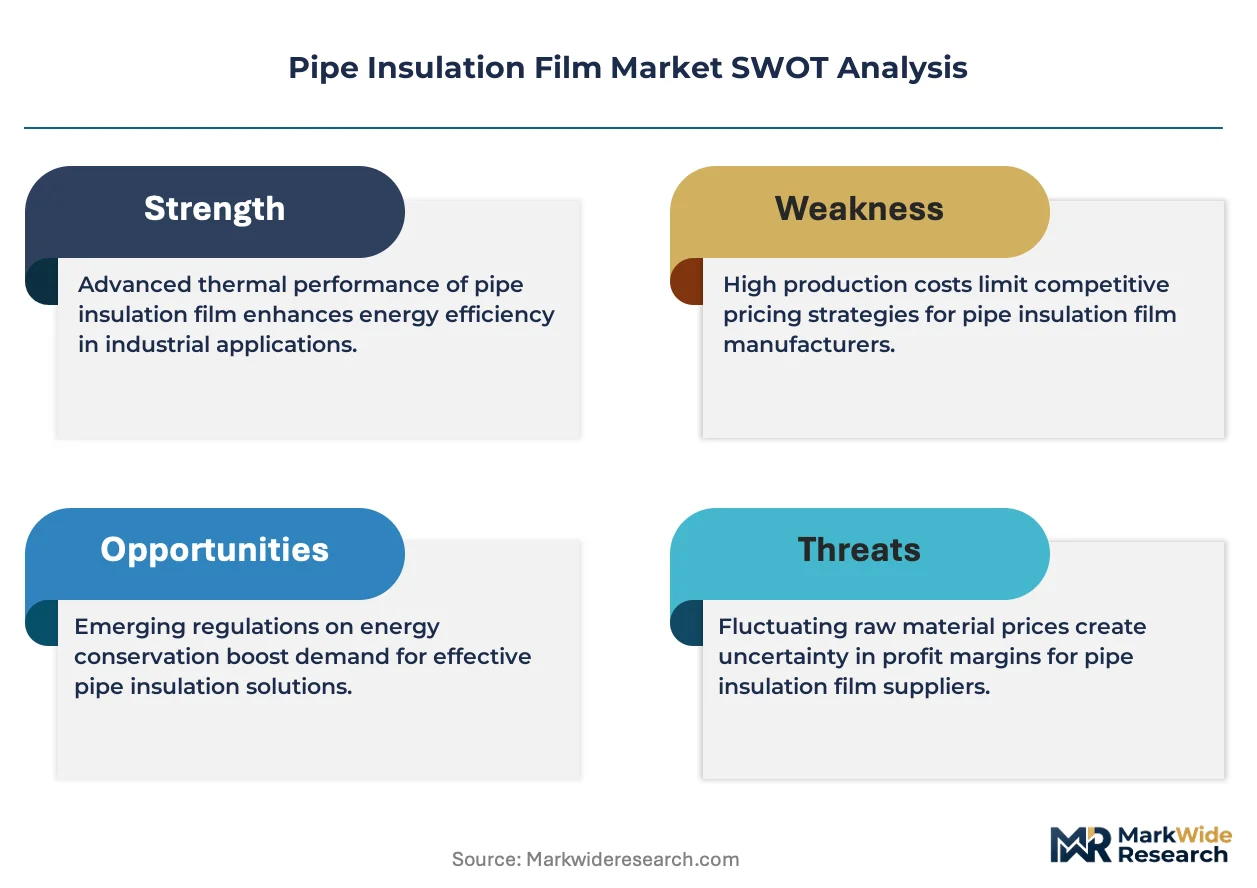
Multilayer insulation procurement by oil and gas pipeline operators is compressing thermal loss tolerances and forcing material specification upgrades across energy infrastructure supply chains. This operational imperative is reshaping vendor qualification protocols and long-term contracting structures.
Growth Catalysts
- LNG Export Terminal Construction:Cryogenic pipe wrapping demand concentrates in the Permian Basin and Gulf Coast petrochemical corridor, driving specification-grade multilayer system procurement.
- EPA Fugitive Emissions Protocols:Updated greenhouse gas reporting requirements tighten material specifications across U.S. energy infrastructure, mandating higher-performance vapor retarder laminates.
- Closed-Cell Foam Chemistry:Advanced elastomeric formulations minimize thermal bridging in refrigeration service, expanding addressable temperature ranges for flexible insulation films.
Market Restraints
- Halogenated Blowing Agent Constraints:EU F-Gas Regulation and REACH framework compel reformulation investments, elevating R&D costs for foam core suppliers serving transatlantic portfolios.
- Petrochemical Feedstock Volatility:Polyethylene and polypropylene resin prices fluctuate with crude oil indices, compressing margin stability for film manufacturers.
- Specification-Grade Certification Barriers:ASTM C547 and C1130 thermal performance benchmarks require extensive testing protocols that exclude smaller compounders from industrial process piping contracts.
Strategic Opportunities
- Preventive Maintenance Bundling:Insulation system audits packaged with material supply contracts capture lifetime value from industrial buyers and extend replacement cycle visibility.
- California and New York Energy Codes:Stretch goals for commercial building thermal efficiency tighten permissible U-values for mechanical piping envelopes, mandating upgraded film specifications.
- Cryogenic Service Expansion:Hydrogen transport infrastructure and carbon capture pipeline networks require sub-minus 50°C performance that premium foam laminates can address.
Industry Challenges
- Certification Timeline Compression:ASTM and ISO thermal performance validation cycles lag project procurement schedules, forcing speculative inventory positions.
- Moisture Ingress Detection:Corrosion under insulation monitoring requires integrated sensor compatibility that legacy film formulations lack, complicating retrofit specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipe Insulation Film Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, Foam Application: HVAC, Plumbing, Industrial, Refrigeration Thickness: Thin, Medium, Thick, Extra Thick Installation Method: Self-adhesive, Mechanical, Spray-on, Wrap |
| Companies Covered | Owens Corning, Armacell International S.A., Saint-Gobain, BASF SE, Rockwool International A/S, Kingspan Group, Johns Manville, K-FLEX, Knauf Insulation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipe Insulation Film Market Trends and Innovations
Material science advances and regulatory stringency are converging to redefine performance benchmarks across temperature ranges and service environments. Vendors must now engineer for thermal efficiency, chemical resistance, and environmental compliance simultaneously.
Multilayer vapor retarder laminates incorporating nanoclay barriers are decentralizing traditional single-film specifications in buried utility applications. Municipal water authorities and district heating operators specify these constructions for 50-year service life projections. The shift compresses commodity polyethylene volumes while elevating technical compounders with coextrusion capabilities.
REACH framework amendments and EU F-Gas Regulation constraints on hydrofluorocarbon blowing agents are forcing closed-cell foam reformulations across member states. Suppliers serving both European and North American project portfolios must maintain dual product lines or absorb conversion costs. Industrial process piping specifications in Germany and the Netherlands now prioritize pentane-blown alternatives despite modest thermal performance trade-offs.
Integrated jacketing and insulation kit procurement is displacing component-level purchasing among large-diameter piping contractors. EPC firms in the U.S. Gulf Coast and Middle Eastern petrochemical corridors consolidate vendor bases to reduce interface risk. This concentration rewards manufacturers with in-house fiberglass and film production capabilities, marginalizing specialized single-product suppliers.
Pipe Insulation Film Market Segmentation
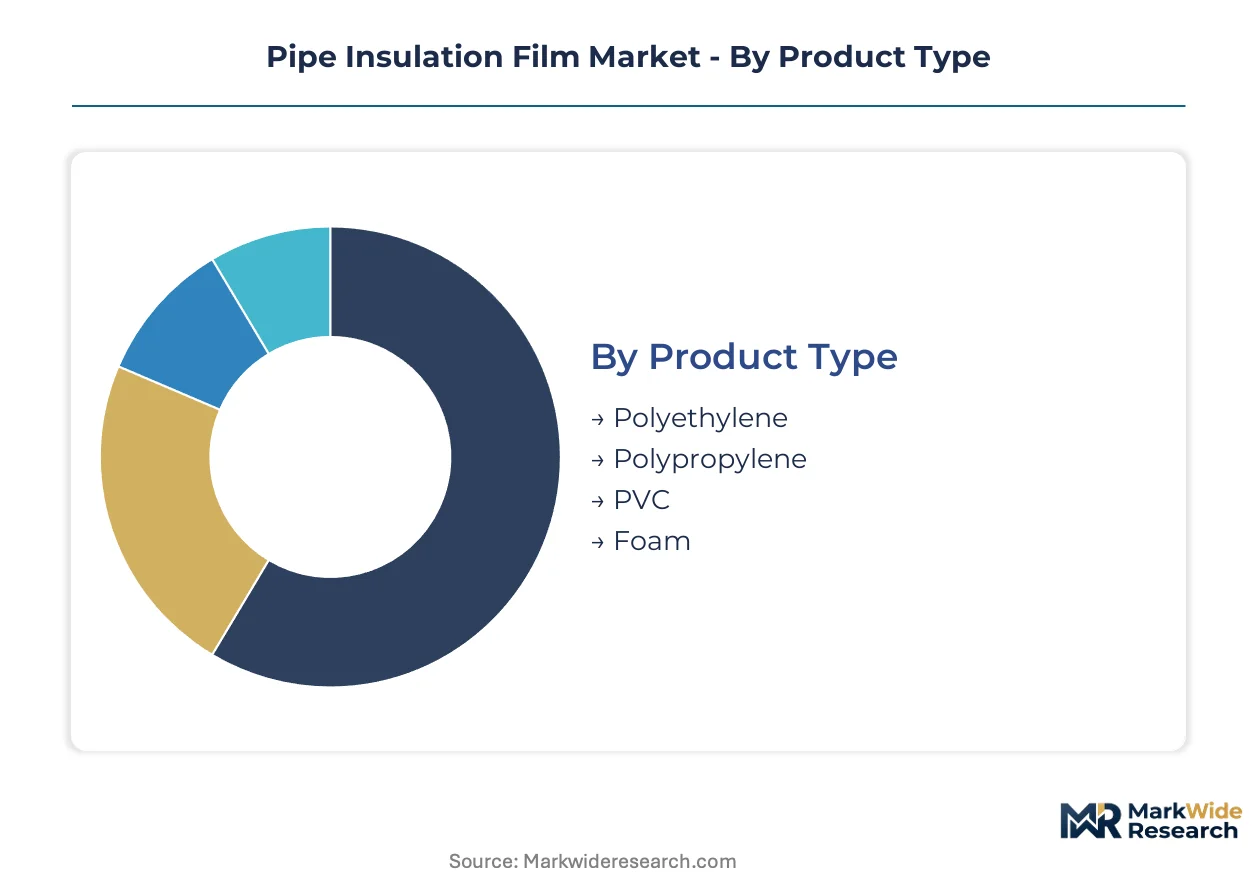
Pipe insulation film manufacturers configure production lines around resin chemistry, application temperature ranges, and installation labor requirements. Segment-specific capital allocation determines which compounders capture specification-grade contracts versus commodity volume.
Product Type:
Capital intensity escalates sharply with processing complexity and certification requirements for closed-cell foam structures.
- Polyethylene:Linear low-density formulations dominate buried utility applications through chemical resistance and moisture barrier performance. Municipal water authorities in Texas and California specify these films for 50-year service life projections beneath aggressive soil conditions.
- Foam:Closed-cell elastomeric structures require precision blowing agent control and multilayer lamination equipment. LNG export terminals along the U.S. Gulf Coast specify these constructions for cryogenic service where thermal bridging minimization commands premium positioning.
- Polypropylene:Higher melting point suits elevated temperature industrial process piping. German chemical processors favor these formulations for steam distribution networks.
- PVC:Rigid calendered films serve commercial HVAC jacketing with inherent flame retardancy. Japanese building codes mandate these specifications for high-rise mechanical enclosures.
Polyethylene absorbs the bulk of installed capacity; foam is expanding most quickly.
Application:
Margin pools concentrate where thermal performance validation and regulatory compliance create specification barriers.
- Industrial:Process piping in petrochemical corridors demands ASTM C547 certification and vapor retarder integration. Saudi Aramco and ExxonMobil procurement protocols exclude uncertified compounders from multilayer system contracts.
- HVAC:Commercial building envelopes sustain the broadest end-use footprint across climate zones. California Title 24 and New York Local Law 97 stretch goals tighten permissible U-values for mechanical piping, forcing specification upgrades.
- Refrigeration:Cold chain infrastructure and food processing facilities require sub-zero service performance. EU F-Gas Regulation constraints on hydrofluorocarbon blowing agents compel reformulation investments for transatlantic suppliers.
- Plumbing:Residential and light commercial hot water distribution favors cost-optimized polyethylene wraps. Indian urban housing authorities specify these for district heating retrofits in Delhi and Mumbai.
Industrial commands the steepest margin premiums; HVAC delivers the deepest volume base.
Thickness:
Production asset utilization varies with gauge control precision and raw material yield rates.
- Medium:3-6 mil constructions balance thermal resistance with installation flexibility across standard commercial applications. U.S. mechanical contractors specify these for mid-rise office buildings and healthcare facilities.
- Thick:8-15 mil laminates incorporate reinforced scrim and multiple vapor retarder layers. Buried pipeline operators in Alberta and North Dakota specify these for frost protection and cathodic isolation.
- Thin:Sub-3 mil films serve space-constrained retrofit applications and temporary protection. Japanese semiconductor fabrication facilities use these for cleanroom piping envelopes.
- Extra Thick:20+ mil specialized constructions address extreme cryogenic and high-temperature service. Hydrogen transport pilot projects in the Netherlands specify these for sub-minus 50°C performance validation.
Medium thickness handles the majority of unit volume; thick gauge laminates are climbing the fastest.
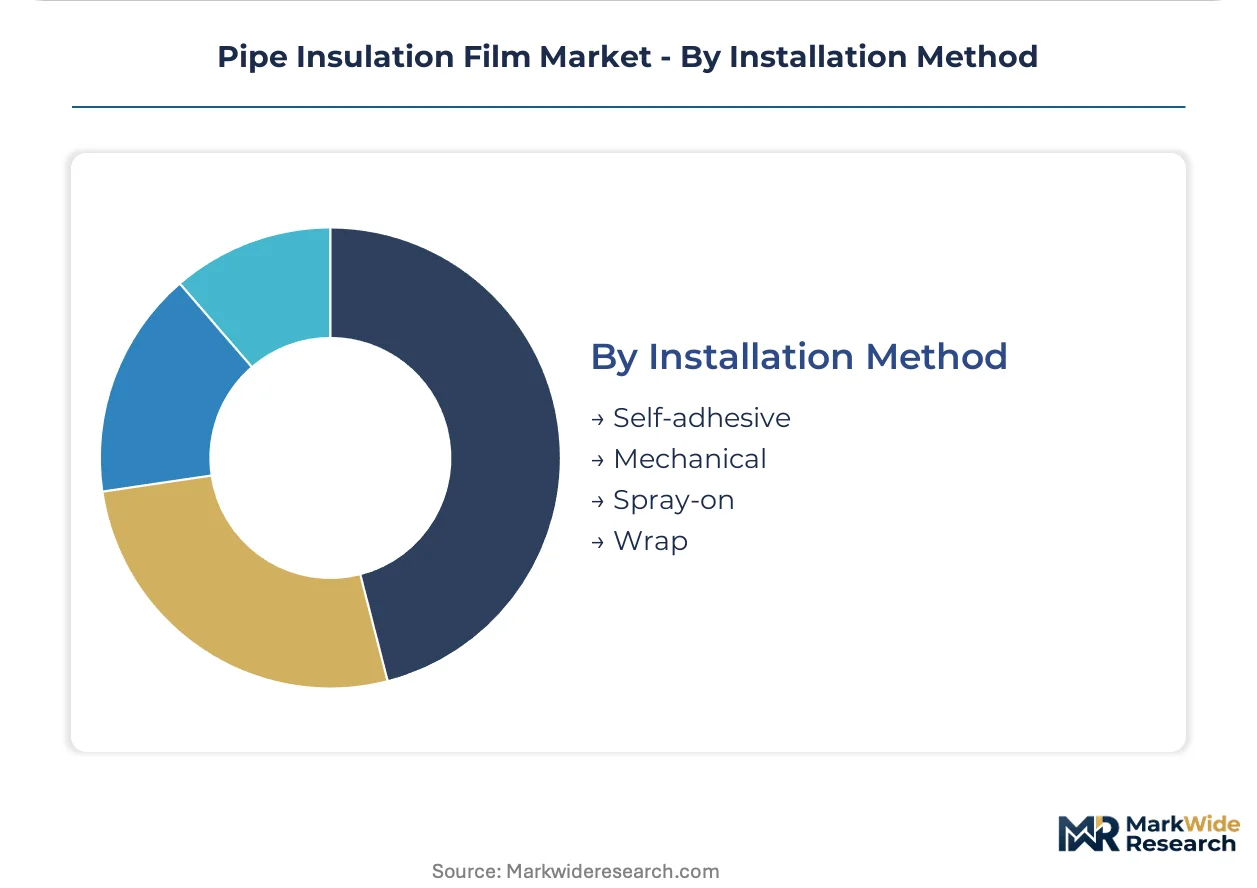
Installation Method:
Labor productivity and skill requirements shape contractor preference and distributor stocking decisions.
- Wrap:Spiral or butt-wrapped application dominates large-diameter industrial piping where field customization is essential. EPC firms in the Middle East consolidate procurement around pre-cut kit formats to reduce interface risk.
- Self-adhesive:Pressure-sensitive formulations accelerate residential and light commercial installation. Australian plumbing contractors favor these for retrofit markets where mechanical fastening is impractical.
- Mechanical:Banding and fastening systems suit high-vibration environments and removable maintenance access. Offshore platform operators in the North Sea specify these for inspection protocols.
- Spray-on:Field-applied polyurethane and elastomeric coatings conform to complex geometries. Brazilian petrochemical maintenance contractors use these for corrosion under insulation remediation projects.
Wrap methods retain the largest installed base; self-adhesive formats are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in the United States and Germany, while consumption growth concentrates in LNG export corridors and Asian industrial zones. This geographic split shapes procurement patterns and material specification standards across the value chain.
United States
LNG export terminal construction along the Gulf Coast and Permian Basin drives cryogenic-grade multilayer system procurement. The EPA's updated greenhouse gas reporting protocols tighten vapor retarder specifications for energy infrastructure. Houston and Corpus Christi anchor the densest concentration of specification-grade contracting activity.
Germany
Industrial process piping in chemical processing corridors demands REACH-compliant foam formulations without hydrofluorocarbon blowing agents. The EU F-Gas Regulation compels reformulation investments from suppliers serving transatlantic portfolios. The Rhine-Ruhr and Ludwigshafen clusters prioritize pentane-blown alternatives for steam distribution networks.
China
District heating retrofits and municipal water infrastructure expansion absorb polyethylene film volumes for buried utility applications. The country's national standards body governs thermal performance benchmarks for mechanical piping envelopes. Beijing and Shanghai municipal authorities specify 50-year service life projections for aggressive soil conditions.
Saudi Arabia
Petrochemical corridor expansion and hydrogen transport pilot projects require sub-minus 50°C performance validation for premium foam laminates. The national oil company procurement protocols exclude uncertified compounders from multilayer system contracts. The Eastern Province and Jubail Industrial City concentrate specification-grade demand.
Netherlands
Carbon capture pipeline networks and hydrogen transport infrastructure drive cryogenic service material development. The EU Green Deal implementation tightens permissible U-values for mechanical piping in commercial structures. The Port of Rotterdam and Eindhoven Region host pilot projects validating extra-thick laminate performance.
Pipe Insulation Film Market Competitive Landscape
Top-tier vendors anchor specification-grade certification, while mid-scale compounders compete on polyethylene volume and regional distribution density. The vendor base stratifies around thermal performance validation capabilities and coextrusion equipment scale. Three archetypes dominate: integrated fiberglass-film manufacturers, engineered foam core specialists, and commodity polyethylene compounders. Capacity expansion and preventive maintenance bundling represent the dominant competitive vectors for capturing lifetime value from industrial buyers.
Within the integrated manufacturing tier, Owens Corning exemplifies scale-driven positioning through in-house fiberglass and film production capabilities. Armacell International S.A. occupies a specialist position in engineered foam cores for flexible elastomeric applications. Among diversified materials conglomerates, Saint-Gobain and BASF SE represent archetypes of portfolio breadth spanning insulation films adjacent construction and industrial chemical markets. These anchors demonstrate how manufacturing scale and formulation expertise concentrate procurement consolidation among large-diameter piping contractors.
| Leading Market Players |
|---|
| Owens Corning |
| Armacell International S.A. |
| Saint-Gobain |
| BASF SE |
| Rockwool International A/S |
| Kingspan Group |
| Johns Manville |
| K-FLEX |
| Knauf Insulation |
| Others |
Pricing and Supply Chain Analysis
Polyethylene resin futures on the CME Group cascade through three distinct pricing tiers as Gulf Coast petrochemical capacity concentrates procurement leverage among integrated manufacturers. Specification-grade multilayer laminates command premium positioning through ASTM C1130 certification barriers, while commodity polyethylene wraps compete on resin yield and freight optimization to municipal water authorities.
Pricing Analysis
Margin tightening in standard-grade polyethylene traces to feedstock volatility indexed to WTI crude benchmarks, compressing compounder returns on non-certified volume. Three-tier pricing structure across specification-grade, commercial-grade, and commodity-grade levels separates certified multilayer systems from single-film wraps. Price differentiation hinges on vapor retarder lamination complexity and REACH compliance documentation. Buyers in the HVAC retrofit segment exhibit acute price sensitivity, whereas LNG terminal EPCs prioritize thermal performance validation over unit cost.
Supply Chain Analysis
Direct-to-EPC channels handle hyperscale demand from Gulf Coast LNG terminals and Saudi petrochemical corridors, bypassing distribution intermediaries for multilayer system procurement. Manufacturing gravity centers on the United States, Germany, and China, with each hub serving distinct specification regimes. Raw material flows draw from ethylene crackers along the Texas Gulf Coast, naphtha-fed complexes in Ludwigshafen, and coal-to-olefins capacity in Ningbo. Single-source vulnerability concentrates in hydrofluorocarbon blowing agent supply chains constrained by EU F-Gas Regulation phase-down schedules. Distribution runs through regional insulation distributors stocking pre-cut wrap formats for mechanical contractor convenience.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive resin supply and in-house lamination capacity determine specification-grade access. Players capturing both polyethylene extrusion and vapor retarder metallization assets command procurement consolidation from large-diameter piping contractors.
For Market Incumbents: Deploy coextrusion capacity expansion in the Permian Basin to anchor LNG terminal supply contracts. Integrated manufacturers must lock in 50-year service life validation with municipal water authorities before REACH-compliant European suppliers scale pentane-blown alternatives. Specification-grade certification investments in ASTM C547 thermal performance benchmarks exclude smaller compounders from industrial process piping margin pools. Channel control through preventive maintenance bundling extends replacement cycle visibility against emerging foam core specialists. For New Entrants and Emerging Players: Digital specification platforms for insulation system audits offer low-friction entry into commercial HVAC retrofit markets. White-space concentrates in cryogenic hydrogen transport pilot projects requiring sub-minus 50°C performance validation that incumbent polyethylene lines cannot address. The Netherlands and Saudi Arabia present penetrable geographies where national oil company procurement protocols still qualify new compounders for pilot-scale validation. Target EPC firms consolidating vendor bases through integrated jacketing kit procurement rather than component-level bidding. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale foam core specialists with REACH-compliant pentane formulations in the Rhine-Ruhr corridor. Long-term viability accrues to manufacturers with dual-product lines serving both European F-Gas constraints and North American specification regimes. Acquisition targets should demonstrate coextrusion equipment scale compatible with nanoclay barrier integration for buried utility applications. Monitor EU Green Deal implementation timelines for mechanical piping U-value tightening as inflection signals for premium laminate demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive polyethylene supply from Gulf Coast crackers insulates margin compression from crude-linked feedstock volatility. |
| REACH-Compliant Foam Reformulation | Pentane-blown alternatives replace hydrofluorocarbon chemistries for EU market access without dual product line costs. |
| Preventive Maintenance Contracting | Insulation system audits bundled with material supply capture lifetime value from Saudi Aramco and ExxonMobil procurement protocols. |
| Nanoclay Barrier Coextrusion | Multilayer laminates with mineral reinforcement displace commodity films in 50-year municipal water authority specifications. |
| Cryogenic Service Certification | ASTM C1130 validation for sub-minus 50°C performance opens hydrogen transport and carbon capture pipeline networks. |
Research Methodology
Trade publications, petrochemical capacity databases, and municipal procurement records formed the secondary backbone for demand quantification across application segments. Primary interviews with EPC procurement managers, insulation distributor inventory planners, plant engineers at LNG terminal developers, and regulatory affairs leads at REACH-registered suppliers validated specification trends and pricing dynamics. Bottom-up volume estimates from resin consumption data triangulated against top-down infrastructure investment flows from FERC filings and EU Green Deal implementation trackers.
Bottom-up modeling anchored forecasts in disclosed ethylene derivative consumption and thermal insulation retrofit cycle analysis across the projection horizon. Segmentation dimensions spanned resin chemistry, application temperature range, installation labor requirements, and regional regulatory framework intensity. CAGRs derived from weighted average of historical capacity utilization trends and announced petrochemical expansion timelines. Industry-specific inputs included EPA fugitive emissions protocol implementation schedules and EU F-Gas Regulation phase-down milestones for blowing agent chemistry transitions.
The model holds under stable crude-to-resin price pass-through assumptions; deviation in feedstock volatility spikes or REACH amendment acceleration would shift compounder margin trajectories. Practitioners should monitor EU Green Deal mechanical piping U-value announcements and hydrogen transport infrastructure tender awards for early demand inflection signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Barrier Coatings for Packaging Market
Packaging Barrier Films
High Barrier Packaging Films for Pharmaceuticals Market
Packaging Barrier Films
Global High Barrier Packaging Films Market
Packaging Barrier Films
Sealant Web Films Market
Packaging Barrier Films
Ultra-High Barrier Films Market
Packaging Barrier Films
Cling Films Market
Packaging Barrier Films
Global Medical Packaging Films Market
Packaging Barrier Films
Microwavable Barrier Films Market
Packaging Barrier Films
Self-Adhesive Films Market
Packaging Barrier Films
Antimicrobial Packaging Market
Packaging Barrier Films
Lining Market
Packaging Barrier Films
Protective Films Market
Packaging Barrier Films
Nano Sealers Market
Packaging Barrier Films
Middle East and Africa Airless Packaging Market
Packaging Barrier Films
72 Inch Paint Protection Film Market
Packaging Barrier Films
Super Barrier Coated Film Market