
 Global Low-Profile Additive Market | 2026-2036
Global Low-Profile Additive Market Size, Share, and Industry Trends Forecast 2026-2036
Global Low-Profile Additive Market Foresight
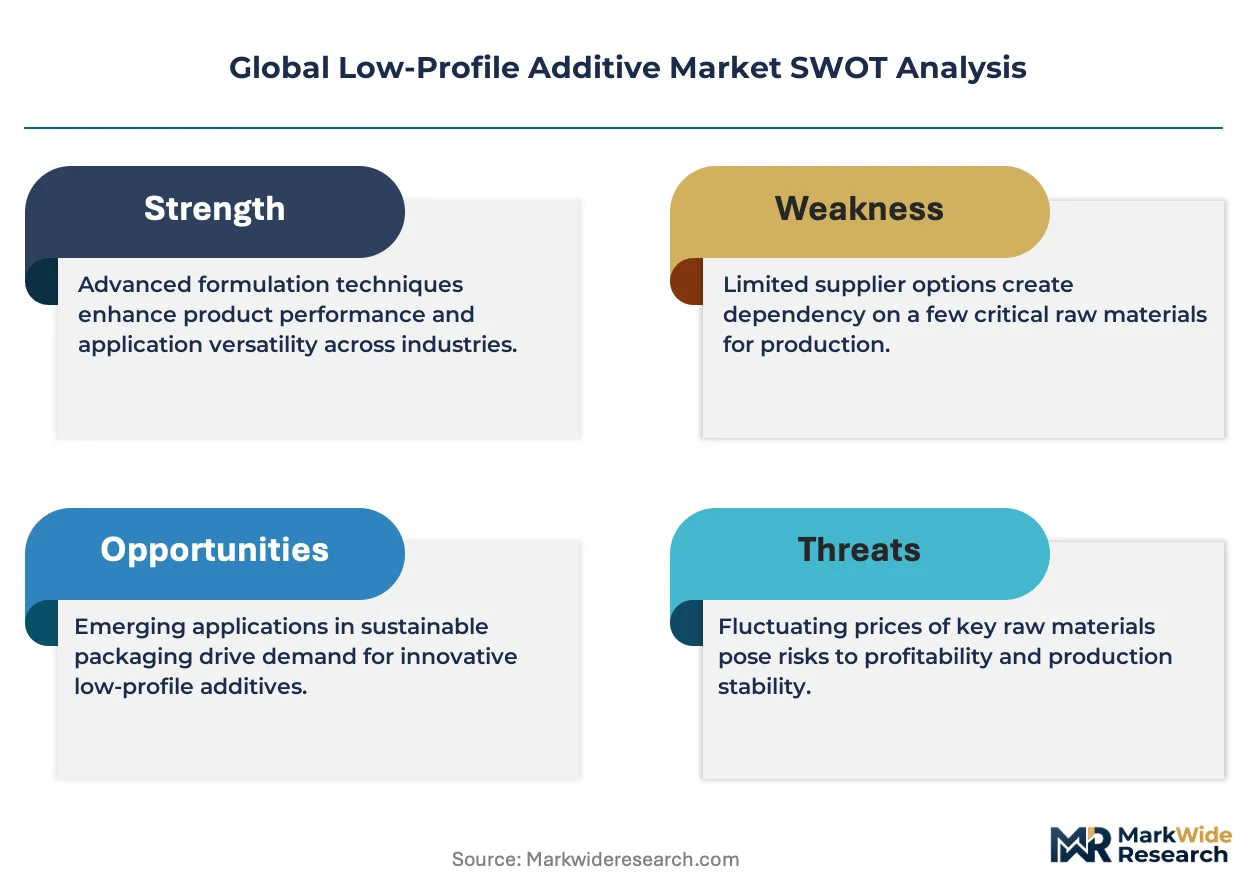
China is tilting capacity toward low-profile additives for unsaturated polyester resins used in wind turbine blades and automotive panels. Arkema S.A. leverages its specialty polymer expertise to anchor European supply chains for high-performance grades. Wacker Chemie AG sustains silicone-based additive leadership through backward integration into siloxane feedstocks. BASF SE competes on formulation breadth across solvent-based and water-based delivery systems.
Low-profile additives are thermoplastic or elastomeric compounds, typically 5-25 microns in particle size, that reduce resin shrinkage and surface waviness during the curing of unsaturated polyester and vinyl ester composites. They function by phase-separating during polymerization to create a microvoid structure that compensates for volumetric contraction, yielding Class-A automotive surfaces and aerodynamic profiles. Powder and granule forms dominate volume due to handling efficiency in automated compounding, while paste formulations capture margin pools in custom marine and aerospace applications. Water-based technology is displacing solvent-based systems in European coatings as VOC thresholds tighten, though UV-curable platforms are gaining in electronics laminates where thermal exposure risks component damage.
EPA emissions standards in the United States restrict styrene release during open-molding processes, compelling shifts toward closed-injection systems that favor engineered additive packages. REACH registration requirements in Europe mandate full substance characterization, raising compliance costs for imported formulations. China's GB standards on industrial chemical emissions are converging with OECD testing protocols, creating partial harmonization for multinationals. Stakeholders must monitor regulatory divergence between these jurisdictions when siting formulation capacity and qualifying raw material sources.
Market Dynamics
Automotive lightweighting mandates and wind turbine blade scaling are compressing formulation cycles for low-profile additives, forcing suppliers to reconcile thermoplastic compatibility with increasingly stringent VOC thresholds across multiple jurisdictions.
Growth Catalysts
- EPA emissions standards:Styrene release restrictions during open-molding processes accelerate closed-injection system adoption, expanding engineered additive package demand in US automotive composites manufacturing.
- Wind turbine blade production:China's domestic gigawatt-scale installations require unsaturated polyester resins with shrinkage control, pulling additive volumes toward East Asian compounding facilities.
- Water-based technology:REACH-driven VOC thresholds in European coatings favor aqueous delivery systems over solvent-based alternatives, redirecting R&D investment toward emulsion stability.
Market Restraints
- Siloxane feedstock concentration:Wacker Chemie AG's backward integration into siloxane monomers creates supply-side dependency for silicone-based additive competitors without captive raw material access.
- REACH registration burden:Full substance characterization mandates raise compliance costs for imported formulations entering European Union markets, disadvantaging smaller non-EU specialty chemical producers.
- Thermal curing limitations:Electronics laminate manufacturers face component damage risks from traditional thermal exposure, constraining additive selection in high-precision PCB applications.
Strategic Opportunities
- India automotive panels:Domestic electric vehicle production scaling under PLI scheme incentives creates first-mover positioning for low-profile additive suppliers establishing local technical service presence.
- UV-curable platform convergence:Radiation-curable resin chemistry combined with phase-separation additive technology addresses thermal sensitivity in microelectronics packaging without sacrificing surface finish.
- GB standard harmonization:China's industrial chemical emission protocols converging with OECD testing protocols reduce requalification costs for multinationals operating across Asia-Pacific formulation sites.
Industry Challenges
- Formulation chemist scarcity:Phase-separation kinetics expertise for thermoplastic-elastomer blend optimization remains concentrated among veteran technologists approaching retirement in European and Japanese specialty chemical firms.
- Multi-jurisdiction registration timelines:Divergent substance notification requirements between EPA, REACH, and China's MEE extend product launch cycles by 18-36 months for novel additive chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Low-Profile Additive Market |
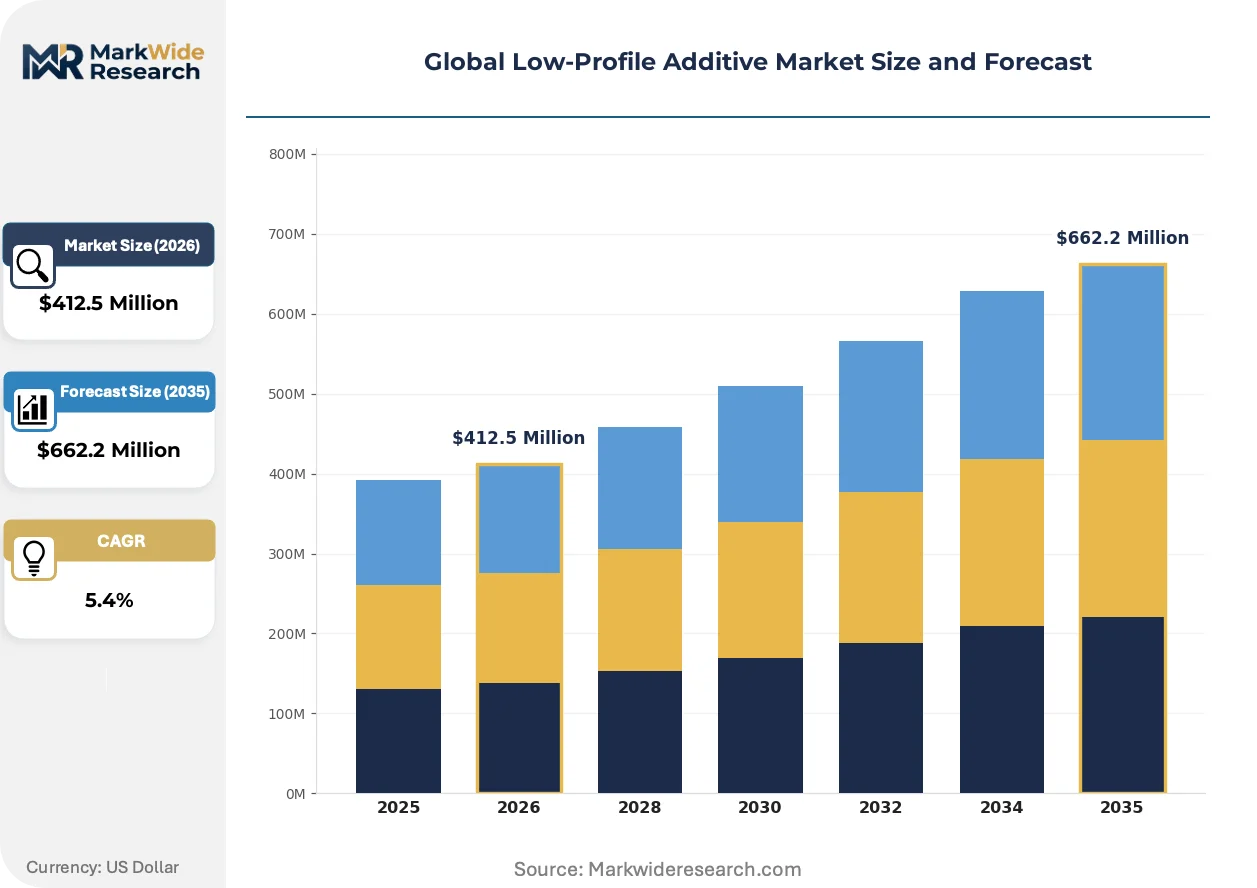
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Form: Powder, Granules, Pellets, Flakes, Paste Application: Coatings, Plastics, Ceramics, Electronics, Adhesives Technology: Solvent-Based, Water-Based, UV-Curable, Thermal Curing End User: Electronics Manufacturers, Paints & Coatings Suppliers, Plastic Compounders, Ceramic Producers |
| Companies Covered | Polynt S.p.A., Arkema S.A., Wacker Chemie AG, Ashland Global Holdings, LyondellBasell Industries Holdings B.V., BASF SE, Evonik Industries AG, AOC, LLC, INEOS AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Low-Profile Additive Market Shifts & Advancements
Digital formulation tools and predictive curing models are compressing development cycles for low-profile additive systems, while regulatory fragmentation forces parallel qualification tracks across major manufacturing geographies.
Computational rheology platforms are virtualizing traditional laboratory compounding workflows for low-profile additive development. Tier-1 automotive suppliers in Germany and Japan now simulate phase-separation behavior prior to physical trials, cutting formulation iterations by half. This capability is virtualizing the competitive moat historically held by incumbents with decades of empirical databases.
REACH authorization requirements for persistent organic pollutants are tightening acceptable thresholds for legacy additive chemistries containing certain phthalate plasticizers. Compounders serving marine and aerospace paste applications face reformulation deadlines by 2027. High-performance vinyl ester segments in Nordic wind blade manufacturing are responding fastest, accelerating bio-based thermoplastic alternative qualification.
Consolidated procurement by Chinese wind turbine OEMs now mandates direct technical service relationships with additive suppliers, bypassing traditional distributor channels. European resin compounders serving this segment must station application engineers in Tianjin or Yangzhou. This concentration is most visible in blade root and shear web components where surface waviness tolerances tightened to sub-millimeter specifications.
Global Low-Profile Additive Market Segmentation
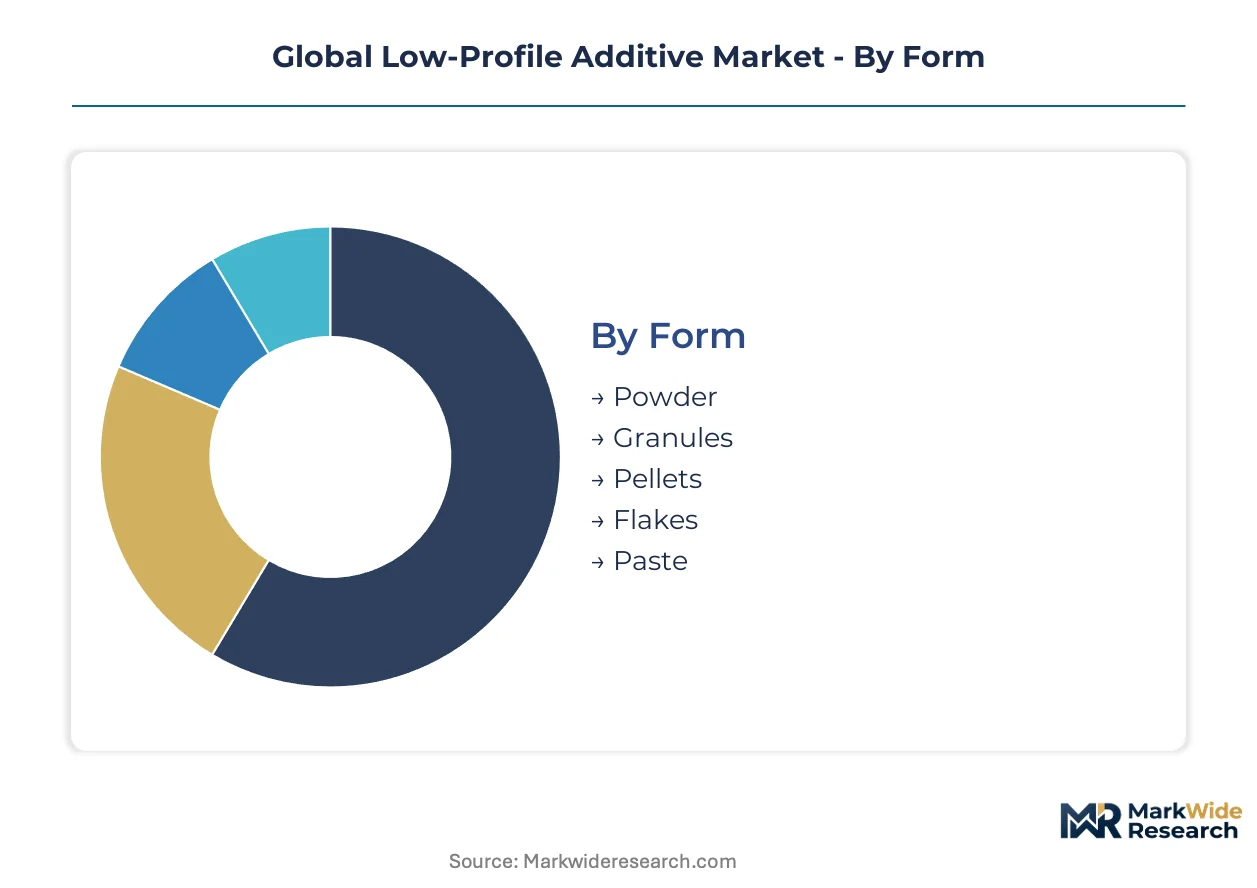
Segmentation in the low-profile additive market reveals divergent margin structures and qualification timelines. Powder and granule forms command volume leadership in automated compounding, while paste formulations serve niche marine and aerospace specifications with extended customer approval cycles.
Form:
Cycle times vary sharply by physical state, with free-flowing solids turning inventory fastest and paste grades requiring longest storage stability validation.
- Powder:Fine particulate grades, typically 5-25 microns, optimize dispersion in unsaturated polyester bulk molding compounds. Demand concentrates in Chinese wind blade root manufacturing where automated dosing systems predominate and surface waviness tolerances tightened to sub-millimeter specifications.
- Granules:Agglomerated forms reduce dust exposure and improve handling logistics in European automotive panel plants. German Tier-1 suppliers specify dust-free delivery for closed-injection molding lines that EPA styrene emission standards favor.
- Pellets:Extruded cylindrical forms suit high-throughput vinyl ester compounding in US Gulf Coast facilities.
- Flakes:Irregular platelet morphology serves specialty epoxy formulations in Japanese electronics laminates.
- Paste:Pre-dispersed concentrates in plasticizer carriers target manual lay-up marine applications in Italian and Turkish boatbuilding clusters.
Powder dominates installed base. Paste is where expansion concentrates in custom formulation services.
Application:
Margin tiers separate commodity-scale coatings from precision electronics where thermal sensitivity dictates additive selection.
- Coatings:REACH-driven VOC thresholds in European industrial finishes redirect solvent-based additive demand toward aqueous emulsion systems. French and Dutch automotive OEMs now mandate water-based low-profile additives in exterior body panel primers.
- Plastics:Thermoset composite shrinkage control represents the core volume application, with unsaturated polyester and vinyl ester systems in Chinese wind turbine blades pulling additive volumes toward Yangzhou and Tianjin compounding hubs.
- Ceramics:Refractory binders utilize micronized thermoplastic additives for green body strength in German and Italian technical ceramic manufacturing.
- Electronics:PCB laminate manufacturers face component damage risks from thermal curing, constraining additive selection and accelerating UV-curable platform adoption in South Korean semiconductor packaging facilities.
- Adhesives:Structural bonding applications in aerospace assembly require phase-separation control for void-free bondlines in Toulouse and Hamburg production lines.
Plastics commands the largest installed base. Electronics is climbing the fastest as thermal sensitivity drives chemistry shifts.
Technology:
Regulatory pressure on volatile emissions creates technology switching costs that fragment supplier qualification timelines across jurisdictions.
- Solvent-Based:Traditional hydrocarbon carrier systems retain cost advantage in open-molding marine applications where EPA styrene restrictions have not yet fully displaced legacy processes. Italian yacht builders continue solvent-based paste specifications for deep-draw hull sections.
- Water-Based:Aqueous emulsion technology captures margin premiums in European automotive coatings as ECHA REACH authorization tightens acceptable thresholds for legacy chemistries. BASF and Arkema formulation breadth spans both delivery systems.
- UV-Curable:Radiation-curable platforms address thermal damage risks in microelectronics packaging without sacrificing surface finish, gaining traction in South Korean and Taiwanese PCB laminate manufacturing.
- Thermal Curing:Conventional heat-activated systems remain entrenched in Chinese wind blade production where cure kinetics are optimized for 80-meter-plus rotor dimensions.
Thermal curing dominates installed base. UV-curable is where expansion concentrates in thermal-sensitive segments.
End User:
Procurement concentration varies by vertical, with consolidated Chinese wind OEMs mandating direct supplier relationships while coatings channels retain distributor intermediaries.
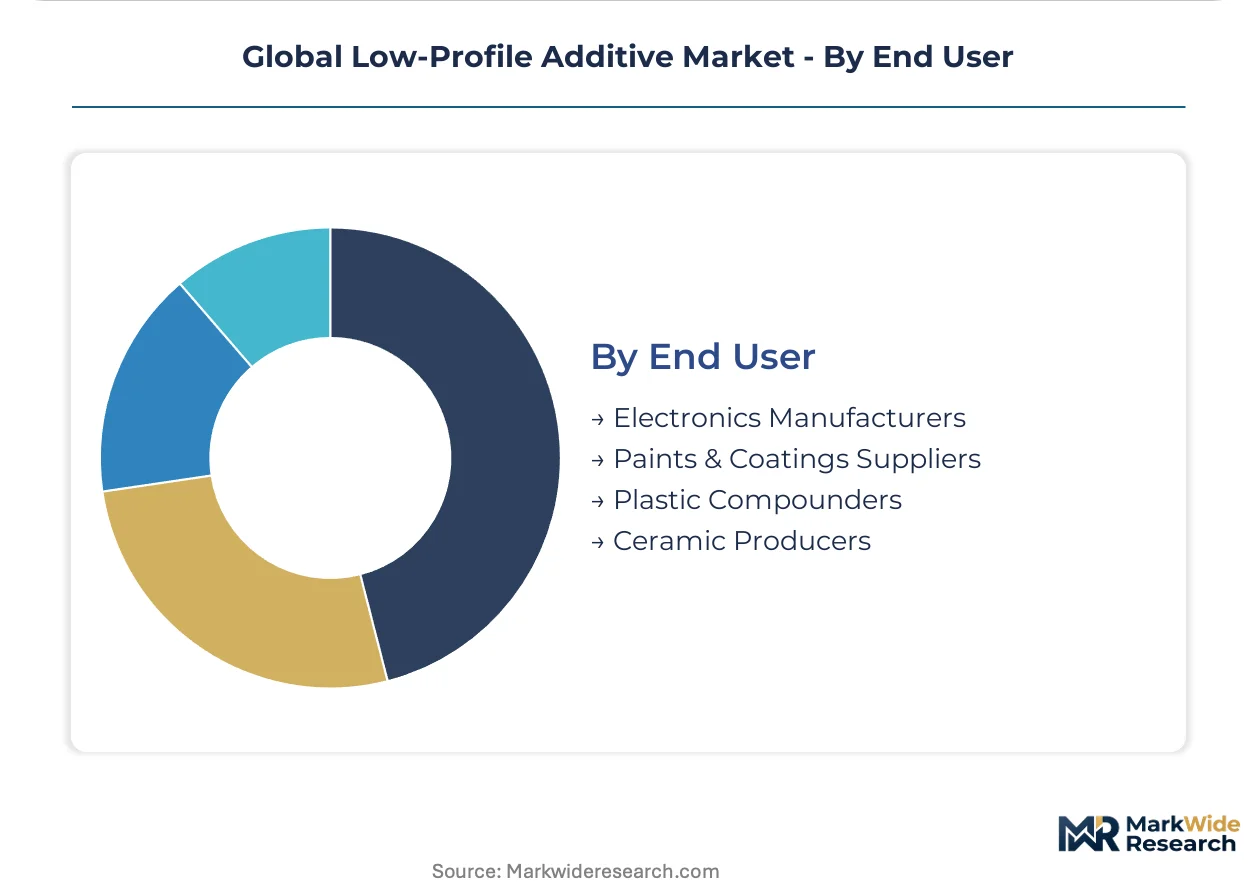
- Electronics Manufacturers:PCB and semiconductor packaging producers in South Korea and Taiwan specify low-profile additives for copper-clad laminates where thermal exposure risks component integrity. UV-curable technology penetration is steepest here.
- Paints & Coatings Suppliers:European automotive refinish and industrial OEM coatings producers face REACH-driven reformulation deadlines, redirecting additive sourcing toward aqueous emulsion specialists with ECHA registration dossiers.
- Plastic Compounders:Unsaturated polyester and vinyl ester bulk molders in China, Germany, and the US represent the core demand volume, with Chinese facilities pulling additive supply toward East Asian technical service stations.
- Ceramic Producers:Technical ceramic manufacturers in Germany and Italy utilize micronized thermoplastic additives for precision forming applications in medical and aerospace components.
Plastic compounders dominate installed base. Electronics manufacturers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Ningbo port complex channels siloxane feedstock flows that underpin Asia-Pacific formulation capacity. This maritime infrastructure locks in China's position as the primary demand sink for low-profile additives in wind blade and automotive panel manufacturing.
United States
EPA styrene emission restrictions accelerate closed-injection molding adoption across Michigan and Ohio automotive corridors. The agency's National Emission Standards for Hazardous Air Pollutants compel resin compounders to engineer additive packages compatible with sealed processing systems. Gulf Coast vinyl ester facilities in Texas and Louisiana pull pelletized additive supply for high-throughput bulk molding operations.
Germany
ECHA REACH authorization timelines extend substance notification cycles for imported formulations entering Baden-Württemberg automotive clusters. The regulation's persistent organic pollutant thresholds force reformulation of legacy phthalate-containing paste grades serving Bavarian aerospace subcontractors. Cologne-Düsseldorf chemical logistics hubs concentrate technical service capacity for aqueous emulsion systems.
China
GB standard convergence with OECD testing protocols reduces requalification burdens for multinationals operating Yangzhou and Tianjin compounding sites. MEE industrial emission protocols tighten at the same moment domestic wind turbine OEMs consolidate procurement around direct supplier relationships. Blade root manufacturing in Jiangsu province now mandates sub-millimeter surface waviness tolerances that strain additive dispersion consistency.
South Korea
MFDS chemical safety assessments run parallel to semiconductor packaging demand for UV-curable low-profile additives in Gyeonggi-do PCB laminate facilities. The regulator's substance registration requirements extend product launch timelines for novel radiation-curable chemistries. Busan-Ulsan port infrastructure supports siloxane monomer imports that feed domestic silicone-based additive production.
India
PLI scheme incentives for domestic electric vehicle production create first-mover positioning opportunities in Maharashtra and Tamil Nadu automotive panel supply chains. BIS certification requirements for industrial chemical imports raise compliance thresholds for European additive suppliers without local technical service presence. Gujarat chemical parks attract formulation capacity targeting unsaturated polyester resin compounding for wind energy components.
Global Low-Profile Additive Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream feeding formulation breadth into consolidated end-user procurement channels. The vendor base separates into three archetypes: diversified chemical conglomerates with captive resin operations, specialty additive houses with phase-separation expertise, and regional compounders serving single-industry verticals. Competitive intensity concentrates on M&A activity targeting emulsion technology assets and capacity expansion in Chinese wind blade corridors.
Within the specialty chemical tier, Arkema S.A. and Wacker Chemie AG exemplify divergent feedstock strategies, with the former anchoring European high-performance grades and the latter maintaining upstream control over siloxane monomers. BASF SE occupies a position spanning solvent-based and water-based delivery systems. These three entities represent the competitive spectrum from formulation breadth to backward-integrated raw material security.
| Leading Market Players |
|---|
| Polynt S.p.A. |
| Arkema S.A. |
| Wacker Chemie AG |
| Ashland Global Holdings |
| LyondellBasell Industries Holdings B.V. |
| BASF SE |
| Evonik Industries AG |
| AOC, LLC |
| INEOS AG |
| Others |
Supply & Pricing Matrix
The Shanghai-Ningbo port complex channels siloxane feedstock flows that underpin Asia-Pacific formulation capacity, with freight cost volatility translating directly into tiered pricing spreads between bulk contract buyers and spot purchasers in European automotive clusters.
Pricing Analysis
Volume-discount tiering structures separate multi-year offtake agreements for Chinese wind blade OEMs from spot purchases by Italian marine paste compounders. Price differentiation rests on REACH registration status and automated dosing compatibility, with certified aqueous emulsion grades commanding premiums over legacy solvent-based alternatives. Cost compression in standard powder grades is intensifying because Wacker Chemie AG's backward integration into siloxane monomers squeezes non-captive competitors. Chinese wind turbine manufacturers exhibit lowest price sensitivity due to consolidated procurement power, while Turkish boatbuilders remain most exposed to raw material pass-through volatility.
Supply Chain Analysis
Export-control regimes limiting advanced silicone chemistry transfers constrain technology diffusion from German and Japanese specialty chemical firms to emerging Asian compounders. Supply concentrates in China, Germany, and the United States, with raw material dependencies spanning siloxane monomers, unsaturated polyester resins, and micronized thermoplastic carriers. Single-source vulnerability runs through Wacker Chemie AG's captive siloxane feedstock position. Distribution runs through direct technical service relationships mandated by Chinese wind OEMs, bypassing traditional distributor channels in European coatings segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from bio-based thermoplastic alternatives as REACH authorization deadlines force phthalate plasticizer phase-out in marine and aerospace paste applications.
For Market Incumbents: Harden formulation moats by accelerating bio-based thermoplastic alternative qualification ahead of 2027 REACH reformulation deadlines. Deepen backward integration into siloxane feedstocks or secure long-term offtake agreements with Wacker Chemie AG to neutralize raw material cost volatility. Prioritize stationing application engineers in Tianjin and Yangzhou to satisfy Chinese wind OEM direct-service mandates. For New Entrants and Emerging Players: Pursue first-mover positioning in Indian automotive panel supply chains under PLI scheme incentives, where domestic electric vehicle production scaling outpaces established technical service presence. Target UV-curable platform development for South Korean PCB laminate facilities where thermal sensitivity constrains incumbent thermal-curing additive selection. Lead with aqueous emulsion expertise to capture REACH-driven European coatings reformulation cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty additive houses with phase-separation expertise and ECHA registration dossiers over diversified chemical conglomerates with resin-captive operations. Long-term viability hinges on emulsion technology assets and Chinese wind corridor capacity expansion rights. Watch for GB standard harmonization completion as inflection signal for Asia-Pacific requalification cost reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Feedstocks | Wacker Chemie AG's captive monomer supply locks in cost advantage against formulation-only competitors. |
| Aqueous Emulsion Technology Acquisition | REACH-driven VOC thresholds in European automotive coatings favor aqueous delivery system specialists. |
| Chinese Wind Corridor Capacity Expansion | Yangzhou and Tianjin compounding hubs pull additive volumes toward direct OEM technical service relationships. |
| UV-Curable Platform Development | South Korean PCB laminate manufacturers specify radiation-curable additives to avoid thermal component damage. |
| Bio-Based Thermoplastic Qualification | Nordic wind blade manufacturers accelerate alternative certification ahead of phthalate plasticizer deadlines. |
Research Methodology
A standing panel of resin compounders, automotive Tier-1 procurement leads, wind blade manufacturing engineers, and ECHA regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from customs trade data, Cefic sector reports, SEC 10-K filings, and GB standard harmonization documentation. Bottom-up additive volume estimates triangulated against top-down thermoset composite demand projections.
Scenario-bracketing framed low, base, and high cases across the analysis window, with segmentation modeling spanning form factor, application vertical, delivery technology, and end-user procurement concentration. CAGRs derived from regression analysis against wind turbine installation forecasts and automotive lightweighting program commitments. Industry-specific inputs incorporated EPA styrene emission compliance timelines and REACH authorization phase-out schedules.
Macroeconomic conditions sit as an overlay; deviation in industrial chemical feedstock costs or maritime freight rates would shift the trajectory. Forecasts reflect assumptions on regulatory harmonization pace and substitution technology readiness. Material shifts in GB standard implementation timing or bio-based alternative performance qualification would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Asia-Pacific Concrete Admixtures Market
Additives
Global Propyl Acetate Market
Additives
Global Glass Additives Market
Additives
Citric Acid Anhydrous Market
Additives
Chelating Agents Market
Additives
Allura Red AC Market
Additives
South America Sodium Reduction Agents Market
Additives
Oxygen Scavengers Market
Additives
Low Melt Inclusions Market
Additives
Ultraviolet Light Stabilizer Market
Additives
Global Formulation Additives Market
Additives
Glycyrrhizic Acid Glycosides Market
Additives
Micronized Powder Market
Additives
Sorbitan Tristearate Market
Additives
Inorganic Filler Market
Additives
North America Phosphate Esters Market