
 Europe Feed Additives Market | 2026-2036
Europe Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Feed Additives Market Intelligence
FAMI-QS certification is collapsing the supplier base as non-compliant blenders exit the European market. Cargill Inc. leverages its integrated supply chain from grain origination to premix formulation across multiple EU member states. dsm-firmenich sustains leadership in precision nutrition through its vitamin and enzyme portfolios tailored to species-specific requirements. BASF SE anchors its position in methionine production with manufacturing assets in Belgium and Germany.
Feed additives encompass biologically active substances incorporated into compound feeds at inclusion rates typically ranging from grams to kilograms per ton to enhance animal performance, health, or feed processing characteristics. These compounds function through enzymatic catalysis, metabolic modulation, or microbiome manipulation to improve nutrient absorption, growth efficiency, or disease resistance in food-producing animals. Amino acids command the largest value share within product type segmentation due to their indispensable role in protein synthesis and the cost economics of synthetic lysine and methionine versus plant protein sources. Enzymes represent the fastest-expanding category as phytase and non-starch polysaccharide enzymes reduce phosphorus excretion and improve energy digestibility in wheat and barley-based diets common in Northern Europe. The poultry end-user segment generates disproportionate margin pools because broiler operations prioritize feed conversion ratio optimization and operate at scale sufficient to justify premium additive expenditures.
EMA guidelines on veterinary medicinal products and EFSA feed additive evaluations determine market access timelines and safety thresholds for novel compounds. The EU Green Deal nitrogen emission targets and national derogation frameworks under the Nitrates Directive reshape formulation choices toward low-excretion nutrient technologies. REACH compliance for chemical additives and F-Gas Regulation constraints on processing technologies add layer costs that favor larger registrants with dedicated regulatory affairs capacity. Stakeholders must monitor the evolving interface between feed additive authorization and carbon accounting methodologies as livestock supply chains face mounting Scope 3 disclosure obligations.
Market Dynamics
FAMI-QS certification requirements are consolidating the European supplier base as non-compliant blenders exit, while the EU Green Deal nitrogen emission targets force reformulation toward low-excretion nutrient technologies across livestock operations.
Growth Catalysts
- Enzyme adoption in poultry:Phytase and non-starch polysaccharide enzymes reduce phosphorus excretion and improve energy digestibility in wheat and barley-based diets prevalent across Northern Europe.
- EU Green Deal implementation:Nitrogen emission targets and national derogation frameworks under the Nitrates Directive accelerate demand for precision nutrition solutions that minimize environmental footprint.
- German procurement concentration:Large-scale integrated poultry and swine operations in Germany drive volume procurement of amino acid and vitamin premixes, creating economies of scale for additive suppliers.
Market Restraints
- REACH compliance costs:Chemical additive registration under ECHA requirements imposes layer costs that favor larger registrants with dedicated regulatory affairs capacity, squeezing mid-tier competitors.
- Feed grain price volatility:Wheat and barley input cost fluctuations compress margins for compound feed producers, limiting their willingness to absorb premium additive pricing.
- F-Gas Regulation constraints:Processing technology limitations under EU fluorinated gas rules restrict manufacturing flexibility and capital deployment timelines for additive production facilities.
Strategic Opportunities
- Poland livestock expansion:Underpenetrated swine and poultry operations in Eastern Europe present volume growth potential as consolidation accelerates toward EU-scale efficiency standards.
- Carbon accounting integration:Emerging Scope 3 disclosure obligations for livestock supply chains create demand for additives with verified emission reduction credentials and lifecycle data.
- Microbiome modulation convergence:Combining precision fermentation-derived ingredients with enzyme systems opens new formulation categories targeting gut health and antibiotic reduction.
Industry Challenges
- FAMI-QS certification timelines:Extended audit and compliance verification periods delay market entry for novel additive suppliers, compressing effective patent windows.
- Toxicology data generation:EFSA feed additive evaluation requirements demand substantial safety dossier investment, creating capital intensity barriers for innovative small-scale entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Feed Additives Market |
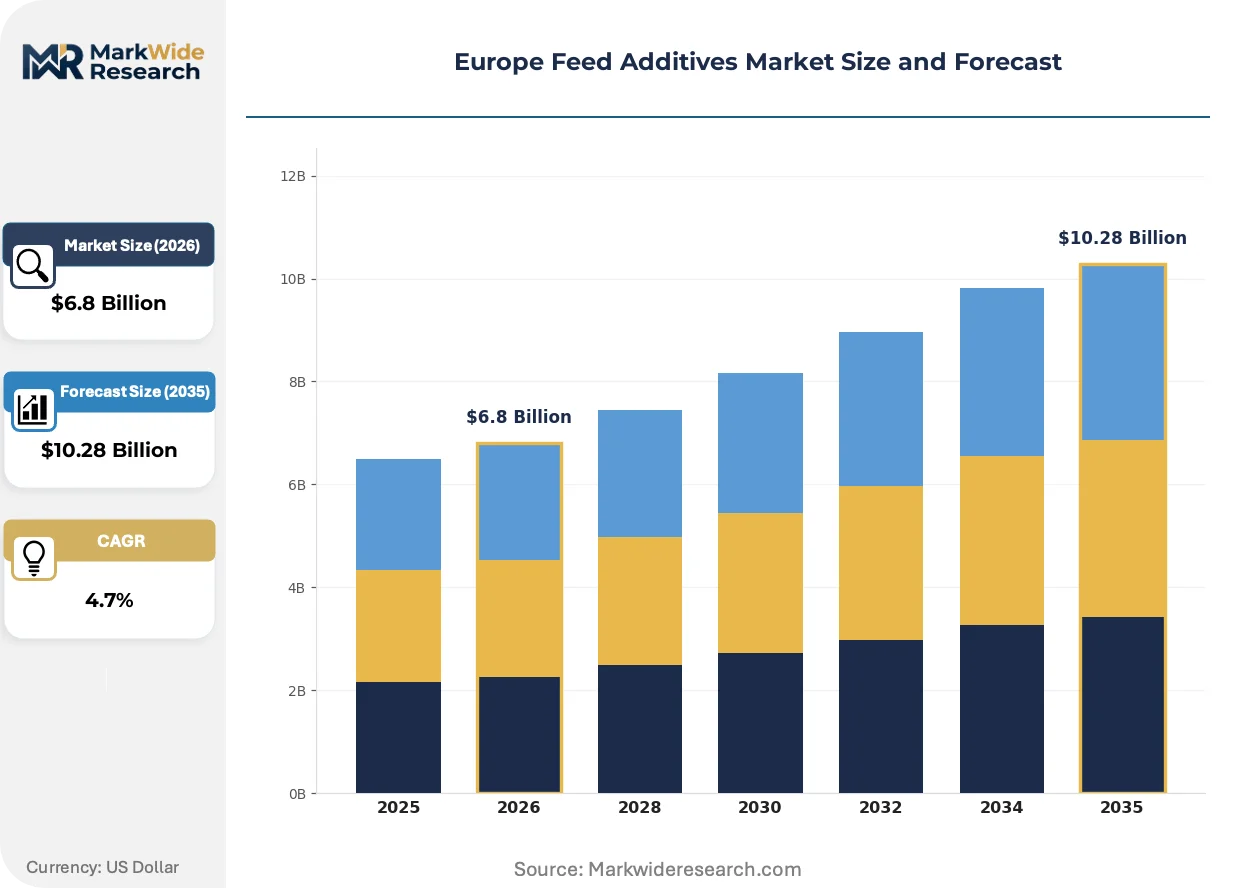
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amino Acids, Vitamins, Minerals, Enzymes End User: Poultry, Ruminants, Swine, Aquaculture Functionality: Digestibility Enhancers, Growth Promoters, Nutritional Supplements, Antioxidants Form: Powder, Liquid, Granules, Pelleted |
| Companies Covered | Adisseo, Cargill Inc., dsm-firmenich, Novonesis Group, Archer Daniels Midland Co., Evonik Industries AG, Nutreco, Kemin Industries, BASF SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Feed Additives Market Strategic Shifts & Innovations
Precision nutrition technologies are restructuring competitive advantage around species-specific formulation capabilities, while regulatory carbon accounting and microbiome science open adjacent value pools beyond traditional performance metrics.
Enzyme engineering is bifurcating the additive landscape between commodity phytase and next-generation multi-enzyme complexes tailored to specific cereal matrices. Northern European broiler operations with wheat-heavy diets are adopting these advanced formulations fastest. This technology split is compressing margins for standardized enzyme suppliers while enabling premium positioning for matrix-optimized portfolios.
EFSA feed additive evaluations under the EU veterinary medicinal products framework are extending authorization timelines and raising safety threshold requirements for novel compounds. The regulatory burden is shifting investment toward incremental improvements of established ingredients rather than breakthrough molecules. Amino acid and vitamin categories face moderate disruption, while probiotic and novel feed material segments encounter pronounced approval friction.
Integrated poultry and swine operations are consolidating procurement decisions at the corporate level, displacing decentralized mill-level purchasing. Large German and Dutch producers now negotiate direct premix supply agreements, bypassing traditional distribution intermediaries. This concentration is most visible in the Benelux corridor, where scale operators leverage volume commitments for formulation customization and technical service bundling.
Europe Feed Additives Market Segmentation
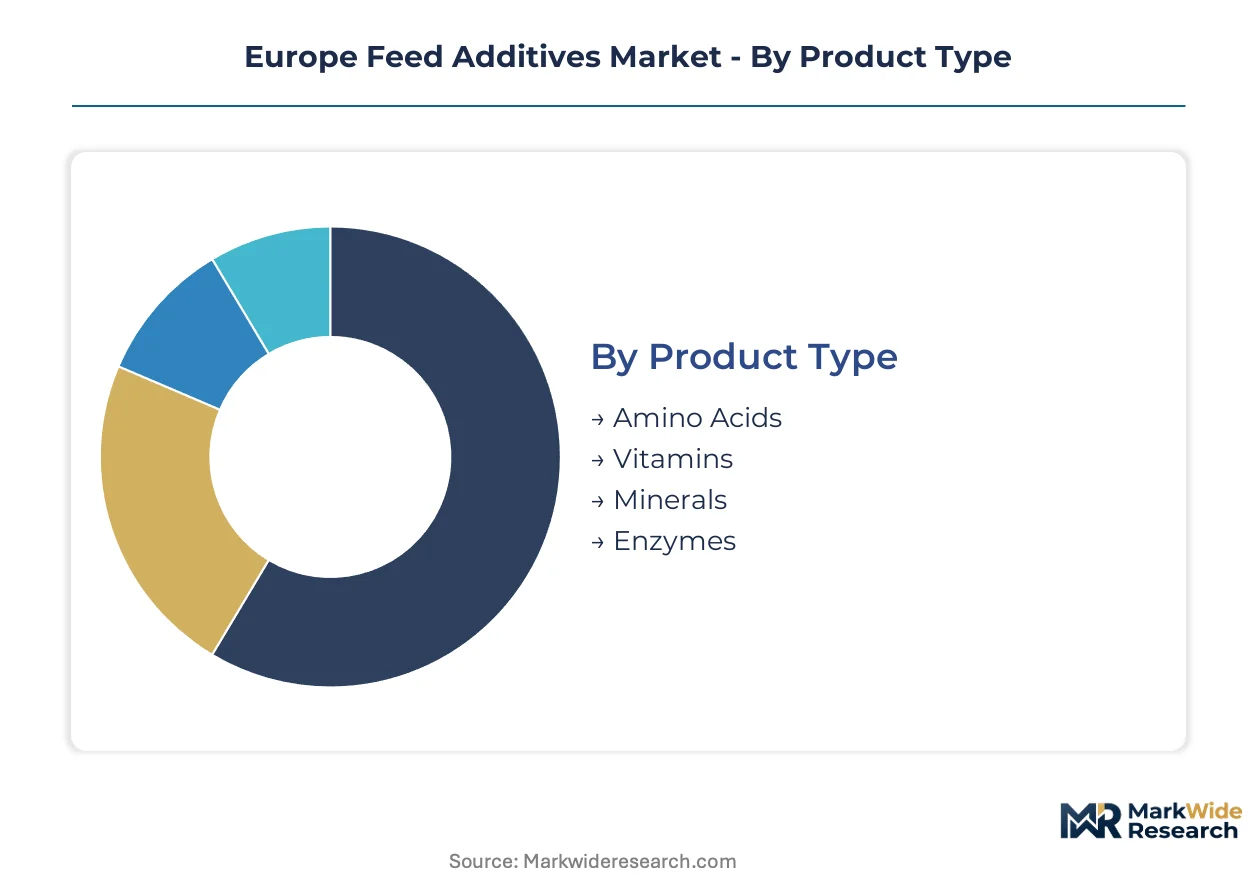
Feed additive purchasing patterns diverge sharply across livestock sectors and production geographies within Europe. Procurement specifications from German integrators differ materially from Polish family farm orders, forcing suppliers to maintain parallel formulation portfolios.
Product Type:
Domestic consumption dominates amino acid and vitamin categories through captive production at BASF's Ludwigshafen and dsm-firmenich's Grenzach sites. Enzyme demand shows stronger cross-border flow, with Danish and Dutch blenders exporting phytase formulations into Baltic and Eastern European markets.
- Amino Acids:Synthetic lysine and methionine manufactured at industrial scale in Germany and Belgium supply protein optimization for compound feed mills. German poultry integrators negotiate annual volume contracts directly with producers, bypassing distribution layers.
- Enzymes:Phytase and non-starch polysaccharide complexes tailored to wheat-barley diet matrices prevalent across Northern Europe. Danish Novozymes and dsm-firmenich supply multi-enzyme portfolios with species-specific activity profiles for broiler and swine operations.
- Vitamins:Fat-soluble and water-soluble premixes produced at concentrated European manufacturing assets serve regional blending facilities.
- Minerals:Trace element and macro-mineral formulations sourced from domestic mining operations and imported concentrates.
Amino Acids commands the established base. The steepest expansion runs through Enzymes.
End User:
Customer scale determines service model intensity. Large integrated operations demand technical formulation support and just-in-time delivery, while smaller independents purchase through cooperative buying groups.
- Poultry:Broiler and layer operations prioritize feed conversion ratio optimization through precision amino acid balancing and enzyme supplementation. Benelux and German integrators operate at sufficient scale to justify premium additive expenditures and direct supplier relationships.
- Swine:Sow and finishing unit formulations emphasize low-nitrogen excretion technologies to comply with Nitrates Directive derogation limits. Danish and Dutch producers lead adoption of precision phosphorus nutrition.
- Ruminants:Dairy and beef cattle operations utilize rumen-protected amino acids and buffer compounds, with demand concentrated in France and Ireland.
- Aquaculture:Salmon and trout feed producers in Norway and Scotland source specialized marine-grade additives with strict contaminant thresholds.
Poultry generates the dominant margin pool. Aquaculture presents the narrowest but highest-value niche.
Functionality:
Regulatory authorization status separates commercially viable categories from restricted applications. EFSA evaluation timelines and EU veterinary medicinal product classifications determine market access.
- Digestibility Enhancers:Phytase and carbohydrase enzymes improve nutrient absorption while reducing environmental excretion. Authorization under EU feed additive regulations permits broad commercial deployment across member states.
- Nutritional Supplements:Vitamin and mineral premixes address documented deficiency risks in cereal-based diets common across Northern European feed formulations.
- Growth Promoters:Antibiotic growth promoters face prohibition under EU veterinary medicinal products framework, shifting investment toward non-antibiotic alternatives.
- Antioxidants:Ethoxyquin and BHT compounds preserve fat-soluble vitamin stability in extended storage conditions.
Nutritional Supplements anchor volume throughput. Digestibility Enhancers gain share fastest as environmental compliance tightens.
Form:
Processing technology and handling requirements dictate format selection. F-Gas Regulation constraints on pelleting equipment influence capital deployment for granulated and pelleted production.
- Powder:Fine-ground premixes enable homogeneous distribution in mash feeds and integration into mineral supplements.
- Liquid:Pumpable enzyme and acidifier formulations suit automated dosing systems at large compound feed mills.
- Granules:Agglomerated products reduce dust generation during handling and improve flow characteristics in mechanical conveying systems.
- Pelleted:Compressed forms protect heat-sensitive actives during feed processing and enable species-specific size grading.
Powder maintains the volume foundation. Liquid formats expand most quickly in automated mill installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central Europe's dominance in feed additive logistics, connecting Ludwigshafen chemical complexes to Danube basin compound feed mills.
Germany
Integrated poultry and swine operations in Lower Saxony and North Rhine-Westphalia drive volume procurement of amino acid and vitamin premixes. EFSA feed additive evaluations and national implementation of EU Nitrates Directive derogations force reformulation toward low-excretion nutrient technologies. The Ludwigshafen chemical cluster anchors synthetic methionine and lysine production for domestic and export supply.
Netherlands
Dense livestock density in Gelderland and Overijssel provinces concentrates demand for precision phosphorus nutrition and enzyme-based digestibility enhancers. National nitrogen emission reduction targets under EU Green Deal implementation accelerate adoption of feed additives that minimize environmental excretion. The Port of Rotterdam handles bulk import of trace mineral concentrates and vitamin intermediates for regional blending facilities.
Denmark
Swine operations in Jutland and Zealand prioritize feed conversion optimization through phytase and non-starch polysaccharide enzyme supplementation. Strict national environmental regulations exceed EU baseline requirements for phosphorus and nitrogen excretion limits. Novozymes maintains enzyme research and production capabilities in the Copenhagen metropolitan area serving Northern European markets.
Poland
Consolidating poultry and swine operations in Wielkopolska and Mazovia regions present underpenetrated growth potential as efficiency standards converge toward EU norms. National derogation frameworks under the Nitrates Directive reshape formulation choices for expanding commercial livestock units. Poznań-based feed mills increasingly source amino acid premixes from German suppliers via established road freight networks.
France
Ruminant operations in Brittany and Normandy utilize rumen-protected amino acids and buffer compounds for dairy production optimization. ANSM oversight of feed additive safety and EMA veterinary medicinal product classifications determine market access for novel compounds. The Brittany livestock cluster maintains specialized demand for cattle-specific additive formulations distinct from monogastric-focused Northern European markets.
Europe Feed Additives Market Key Industry Players
Listed leaders compete with private specialists across certification and formulation capabilities, producing a tiered structure where FAMI-QS compliance separates viable suppliers from exiting blenders. Three archetypes dominate: integrated chemical conglomerates with captive amino acid production, specialized enzyme and vitamin houses with precision nutrition portfolios, and regional premix blenders serving national markets. Competitive moves concentrate on backward integration into active ingredient manufacturing and direct supply agreements with large-scale integrators that displace distribution intermediaries.
Within the integrated chemical tier, BASF SE and Evonik Industries AG exemplify producers with Ludwigshafen-based manufacturing assets anchoring methionine supply. Among specialized nutrition houses, dsm-firmenich and Adisseo occupy positions defined by species-specific formulation capabilities and enzyme portfolio breadth. Cargill Inc. represents the agribusiness-integrated archetype, leveraging grain origination networks across multiple EU member states to secure feed additive distribution channels.
| Leading Market Players |
|---|
| Adisseo |
| Cargill Inc. |
| dsm-firmenich |
| Novonesis Group |
| Archer Daniels Midland Co. |
| Evonik Industries AG |
| Nutreco |
| Kemin Industries |
| BASF SE |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between German poultry integrators and Ludwigshafen-based methionine producers lock in supply access and price visibility across volatile feed grain cycles. These contracts embed volume commitments with FAMI-QS certification tiers, creating procurement predictability for large-scale operations while squeezing flexibility for smaller compound feed mills.
Pricing Analysis
Volume-discount tiering structures stratify across premium FAMI-QS certified, standard compliant, and economy non-certified levels. German and Dutch integrators leverage annual volume commitments for formulation customization and technical service bundling, while Polish family farms face higher per-unit costs through cooperative buying groups. Pricing pressure stems from wheat and barley input cost fluctuations that compress compound feed producer margins. Smaller independent mills exhibit highest price sensitivity due to limited working capital buffers, whereas Benelux scale operators absorb premium additive expenditures.
Supply Chain Analysis
Rhine-Main-Danube waterway transit underwrites Central European additive logistics, connecting Ludwigshafen chemical complexes to Danube basin compound feed mills. Manufacturing concentrates in Germany, Belgium, and the Netherlands, with captive amino acid production at BASF's Ludwigshafen and dsm-firmenich's Grenzach sites. Raw material dependencies include phosphate rock for phytase production, vitamin intermediates from Asian fermentation facilities, and cereal matrices from Black Sea grain origins. Single-source vulnerability runs through F-Gas Regulation-constrained pelleting equipment for heat-sensitive actives. Distribution feeds from concentrated manufacturing assets through Rotterdam bulk handling into regional blending facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
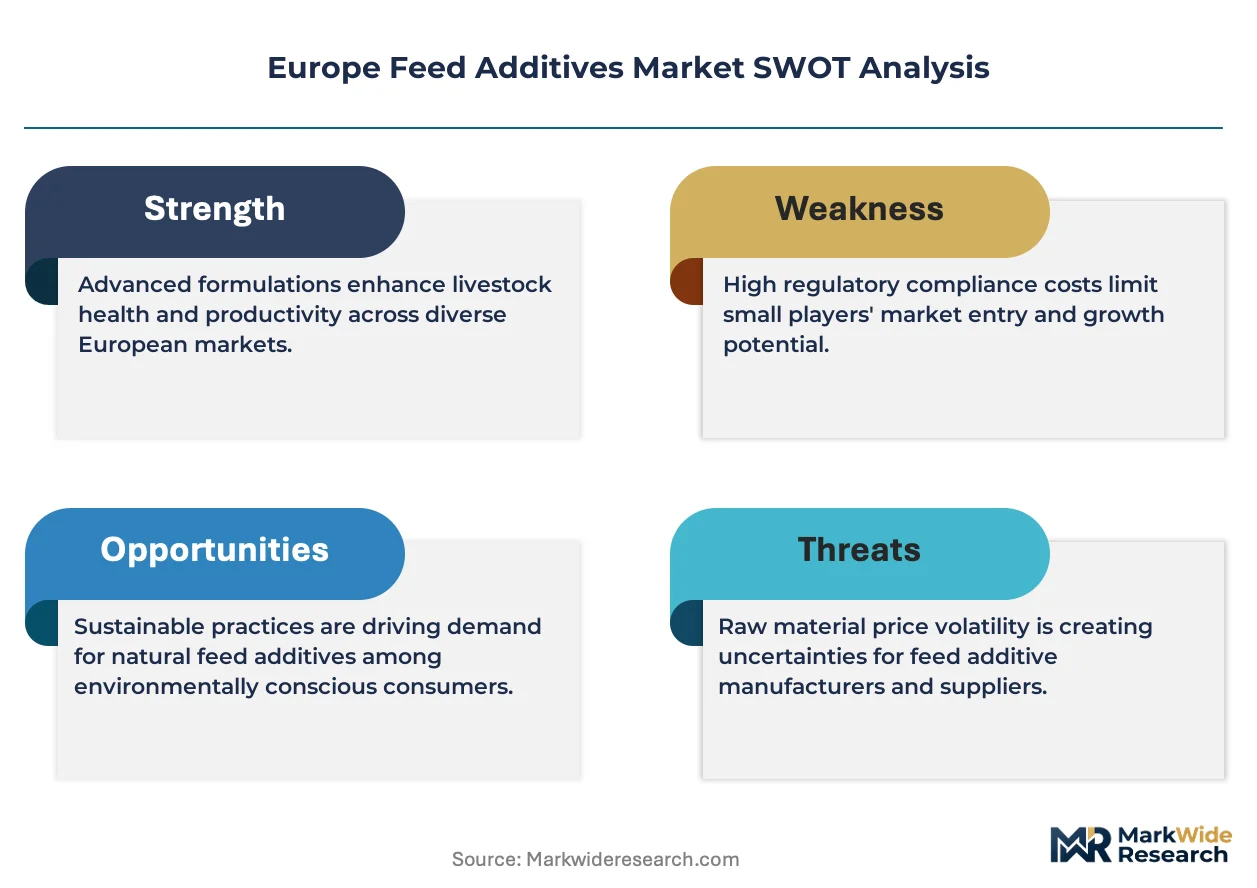
The Europe Feed Additives Market represents high-growth disruption as EU Green Deal nitrogen emission targets force reformulation toward low-excretion nutrient technologies across livestock operations.
For Market Incumbents: Secure backward integration into active ingredient manufacturing to defend margin position against commodity phytase margin compression. Prioritize FAMI-QS certification renewal investments as non-compliant blenders exit, creating channel control opportunities. Counter emerging precision fermentation entrants by accelerating species-specific enzyme portfolio development. For New Entrants and Emerging Players: Lead with microbiome modulation convergence targeting Polish swine and poultry operations where consolidation accelerates toward EU-scale efficiency standards. Exploit underpenetrated Eastern European markets via direct technical service partnerships with expanding commercial livestock units. Differentiate through carbon accounting integration with verified emission reduction credentials. For Investors and Strategic Acquirers: Capital is best deployed toward specialized enzyme and vitamin houses with precision nutrition portfolios and established EFSA regulatory affairs capacity. Long-term viability hinges on formulation capabilities beyond commodity amino acids as regulatory authorization timelines extend. Watch for Scope 3 disclosure obligation acceleration as the inflection signal indicating premium positioning for emission-verified additives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredient Manufacturing | Captive methionine production at Ludwigshafen insulates BASF from intermediate supply volatility. |
| FAMI-QS Certification Investment | Compliance verification separates viable suppliers from exiting blenders across EU member states. |
| Precision Fermentation Capacity Buildout | Novel microbiome-derived ingredients open formulation categories targeting antibiotic reduction mandates. |
| Direct Supply Agreement with German Integrators | Corporate-level procurement consolidation at Cargill displaces traditional distribution intermediaries. |
| Carbon Accounting Data Infrastructure | Lifecycle emission verification aligns with emerging Scope 3 disclosure obligations for livestock supply chains. |
Research Approach
Desk research of EFSA feed additive evaluation databases, EU Nitrates Directive implementation records, and FAMI-QS certification registries preceded structured interviews with compound feed procurement directors, regulatory affairs managers at additive suppliers, and technical service veterinarians at integrated poultry operations. Primary fieldwork with German and Dutch integrators validated secondary trade flow data from Rhine-Main-Danube logistics operators. Bottom-up volume modeling across amino acid, enzyme, and vitamin categories triangulated against top-down livestock production forecasts from national agricultural ministries.
Variance decomposition across product type, end-user species, and functionality segments structured the analytical framework over the projection horizon. Modeled dimensions included species-specific formulation requirements, FAMI-QS certification tiers, and regional environmental compliance stringency under EU Green Deal implementation. CAGRs derived from segmented volume trajectories weighted by value-per-ton differentials between premium matrix-optimized and commodity standardized enzyme portfolios. Forecast inputs incorporated EFSA authorization timeline probabilities and nitrogen emission reduction target acceleration scenarios.
Forecasts assume regulatory continuity in EU veterinary medicinal products frameworks and Nitrates Directive derogation regimes; material policy shifts would require re-modeling. Specific risks include REACH compliance cost escalation for novel chemical additives, F-Gas Regulation processing technology constraints, and feed grain price volatility from Black Sea supply disruptions. Practitioners should keep alternative scenarios live as carbon accounting methodology standardization and microbiome science validation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
LAMEA Driveline Additives Market
Additives
North America Potassium Nitrate Market
Additives
Asia Pacific Silage Additives Market
Additives
Antiblock Agents Market
Additives
Trioctyldodecyl Citrate Market
Additives
Cement Grinding Aid and Performance Enhancers Market
Additives
Tricalcium Citrate Market
Additives
Global Butylated Hydroxytoluene Market
Additives
Defoaming Coating Additives Market
Additives
Dishwashing Additives Market
Additives
Global Synthetic Tackifier Market
Additives
Stabilizers Market
Additives
Weighing Agents Market
Additives
Organic Friction Modifier Additives Market
Additives
Hydroxyethyl Cellulose Market
Additives
Gasoline Additives Market