
 Lubricity Improvers Market | 2026-2036
Lubricity Improvers Market Size, Share, and Industry Trends Forecast 2026-2036
Lubricity Improvers Market Analytics
The gap between premium synthetic formulations and commodity mineral-based lubricity improvers is realigning procurement patterns across end-use sectors. Afton Chemical Corporation leverages its integrated additive technology platform to serve aerospace hydraulics specifications. BASF SE anchors its position through backward integration into ester base stocks for metalworking fluids. Innospec Inc. differentiates via specialized fuel-borne lubricity chemistry for marine low-sulfur operations.
Lubricity improvers are surface-active chemical additives that reduce friction and wear between moving mechanical parts, typically formulated from fatty acid esters, amides, or synthetic polymers with film thickness ratings below one micron. Their primary industrial purpose is to restore lubricating properties in fuels and oils that have lost natural lubricity through refining processes such as hydrotreating. Organic additives occupy the largest volume share in engine oils where cost sensitivity dominates fleet purchasing decisions. Synthetic compounds represent the fastest-expanding category in aerospace hydraulics demanding thermal stability above 150 degrees Celsius. Metalworking applications concentrate margin pools due to specialized formulation requirements and direct technical service relationships.
The EPA enforces lubricity standards for diesel fuels under the Clean Air Act, compelling additive blending to prevent fuel pump failures in modern injection systems. REACH registration requirements in Europe restrict certain traditional fatty acid derivatives, redirecting formulation investment toward biodegradable ester alternatives. The International Maritime Organization's sulfur cap rules shape marine lubricity demand as ship operators treat ultra-low-sulfur distillate fuels. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate which chemistry platforms will retain market access.
Market Dynamics
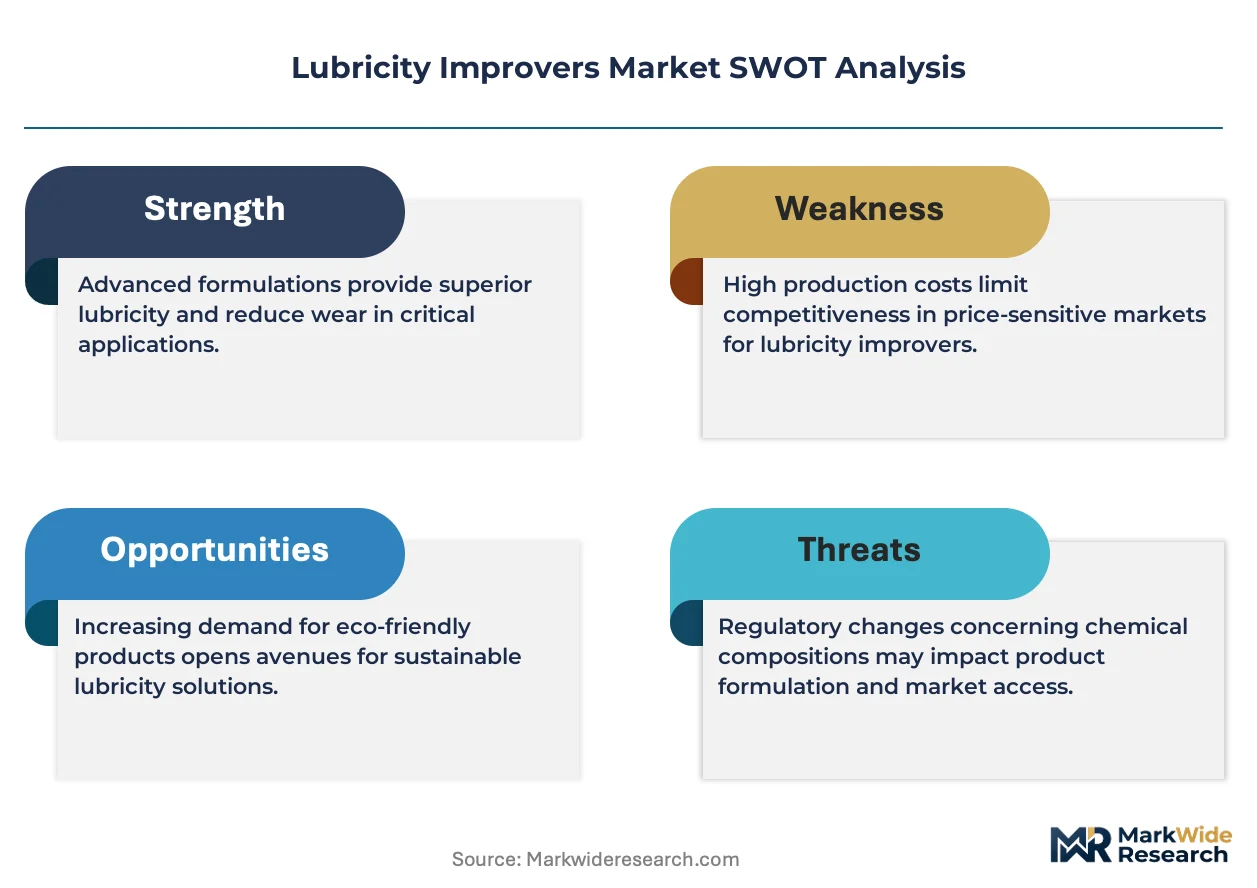
Synthetic ester chemistry is overtaking fatty acid derivatives in high-pressure hydraulic systems, forcing reformulation investments across metalworking and marine sectors. This technology transition concentrates margin pressure on additive suppliers lacking backward integration into ester base stocks.
Growth Catalysts
- IMO 2020 Low-Sulfur Mandates:Marine engine operators treat ultra-low-sulfur distillate fuels with specialized lubricity chemistry to prevent injection system failures. This regulatory pressure sustains additive demand across global shipping corridors.
- Germany's KBA Fleet Standards:Strict lubricant performance requirements for commercial vehicle fleets concentrate procurement volume toward certified synthetic formulations. Fleet operators prioritize warranty-compliant additive packages.
- Aerospace Thermal Specifications:Hydraulic systems demanding thermal stability above 150 degrees Celsius pull synthetic ester adoption. OEM qualification cycles lock in premium chemistry platforms for decade-long supply agreements.
Market Restraints
- Palm Oil Price Volatility:Fatty acid derivative feedstock costs fluctuate with agricultural commodity markets, compressing margins for commodity-grade lubricity improver producers.
- REACH Registration Barriers:ECHA restrictions on certain traditional fatty acid derivatives redirect R&D spending toward biodegradable ester alternatives before full cost recovery.
- Base Oil Supply Concentration:Group II/III refinery capacity clusters in the US Gulf Coast and Singapore, creating geographic dependency for blenders seeking consistent additive solubility.
Strategic Opportunities
- India's BIS Lubricant Standards:Emerging mandatory performance specifications for commercial vehicle fleets create first-mover advantage for additive suppliers establishing local technical service infrastructure.
- Wind Turbine Gearbox Fluids:Extreme-pressure synthetic ester formulations address pitch control system lubricity requirements in offshore installations. OEMs specify 20-year fluid life cycles.
- EU Green Deal Chemistry Incentives:Biodegradable ester platforms qualify for preferential procurement scoring in public infrastructure tenders. Formulators with Ecolabel certification access premium channel positioning.
Industry Challenges
- Formulation Chemist Shortage:Specialized expertise in tribology and surface chemistry remains scarce. Suppliers compete for talent capable of meeting OEM-specific qualification protocols.
- Multi-Jurisdiction Registration Timelines:Parallel EPA, REACH, and country-level chemical notifications extend product launch cycles. Regulatory divergence between jurisdictions fragments R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lubricity Improvers Market |
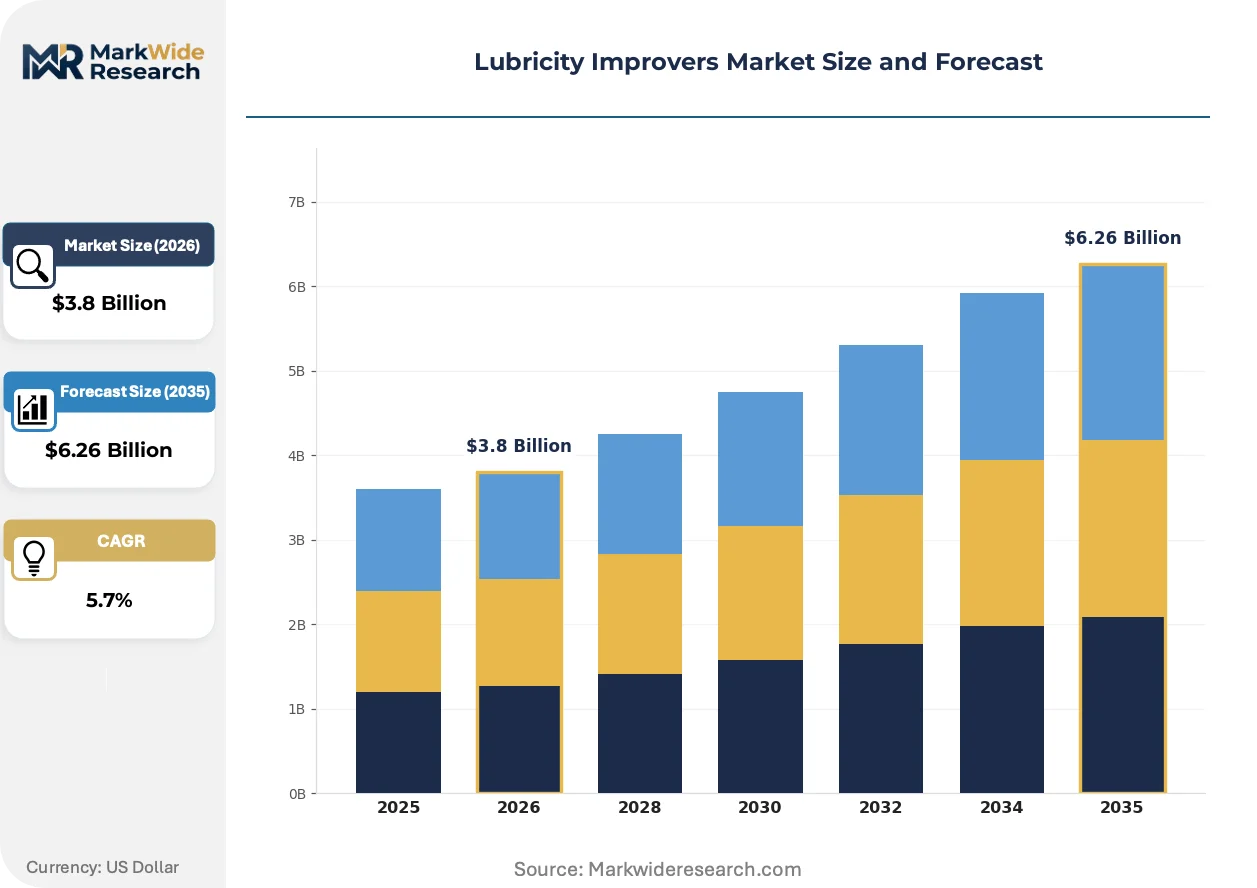
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Additives, Inorganic Additives, Synthetic Compounds, Biological Agents End User: Aerospace, Automotive, Manufacturing, Marine Application: Hydraulics, Metalworking, Engine Oils, Gear Oils Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Afton Chemical Corporation, The Lubrizol Corporation, BASF SE, Innospec Inc., Chevron Corporation, Dow Inc., TotalEnergies SE, Huntsman International LLC, Dorf Ketal Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lubricity Improvers Market Evolving Landscape
Formulation science is pivoting toward molecular architecture that delivers lubricity without compromising thermal oxidative stability. This shift compresses the viable chemistry set and elevates technical service intensity.
Polyol ester base stocks are overtaking traditional diester chemistry in aerospace hydraulic specifications. Boeing and Airbus qualification protocols now specify pour points below minus 54 degrees Celsius. Suppliers without captive polyol ester production face exclusion from long-term supply agreements.
EPA enforcement of lubricity standards under the Clean Air Act compels additive blending in diesel distribution infrastructure. Fuel marketers treat low-sulfur highway diesel at terminal racks to prevent high-pressure common rail pump failures. This regulatory pressure concentrates blending equipment investment around major US refining centers.
Fleet procurement departments now specify lubricity improver content through certificate-of-analysis requirements rather than brand loyalty. Large commercial vehicle operators in Germany and the US demand additive treat rate documentation for warranty compliance. This specification-driven buying compresses distributor margins and rewards technical documentation capabilities.
Lubricity Improvers Market Segmentation
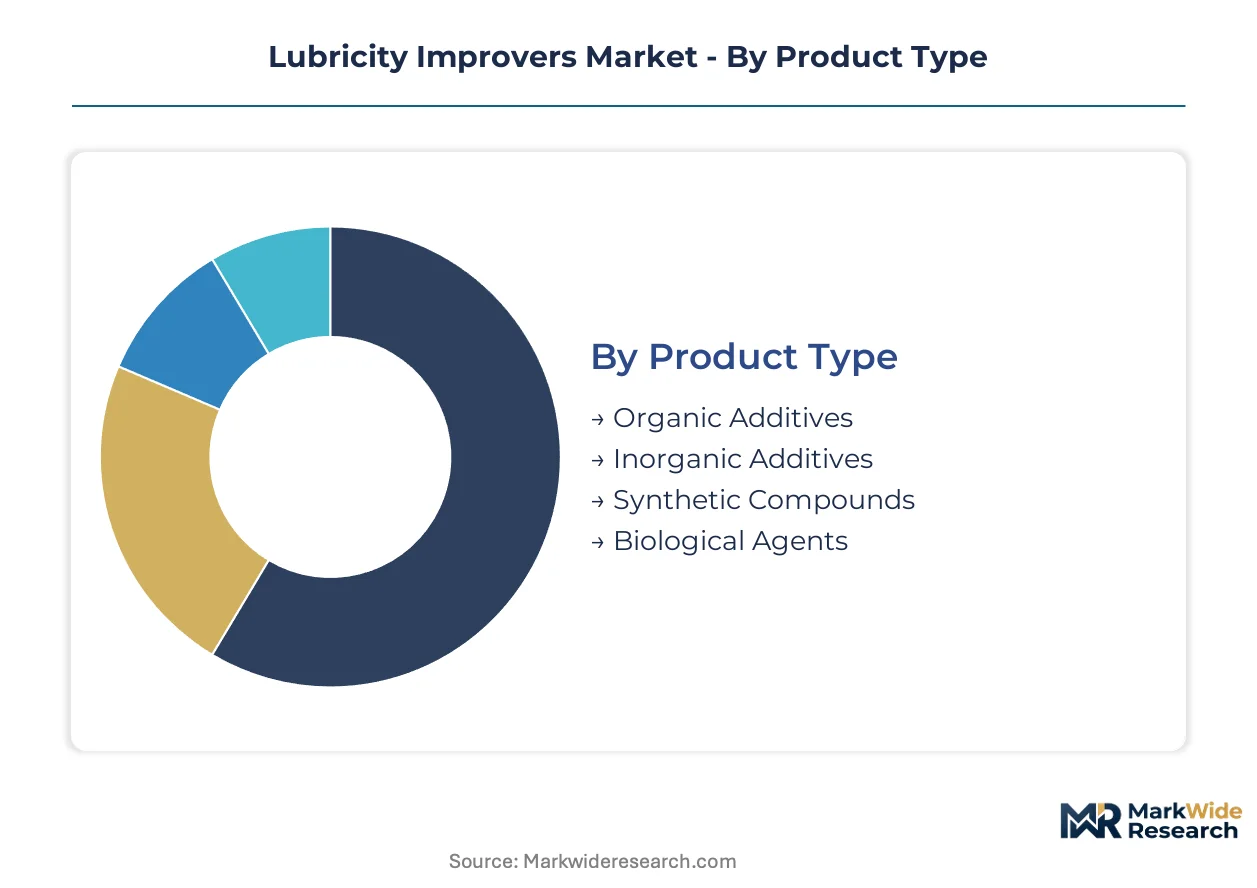
Lubricity improver procurement varies sharply by technical specification, regulatory exposure, and supply chain configuration. Buyers segment their additive portfolios across chemistry platforms, end-use criticality, and channel reliability to manage formulation risk and warranty compliance.
Product Type:
Cost sensitivity and performance tier separate buyers in this category, with fleet operators prioritizing unit economics and aerospace OEMs demanding thermal certification.
- Organic Additives:Fatty acid esters and amides derived from vegetable oils dominate engine oil formulations where treat rates balance friction reduction against base stock compatibility. Fleet procurement in Germany concentrates here due to KBA-mandated performance baselines for commercial vehicle warranty coverage.
- Synthetic Compounds:Polyol esters and diesters deliver thermal stability above 150 degrees Celsius for aerospace hydraulics and high-pressure metalworking systems. Boeing and Airbus qualification protocols lock in decade-long supply agreements for suppliers with captive ester production.
- Inorganic Additives:Molybdenum disulfide and graphite suspensions serve extreme-pressure gear applications in mining and heavy construction equipment.
- Biological Agents:Enzyme-based and bio-derived formulations qualify for EU Green Deal procurement scoring in public infrastructure tenders.
Organic additives lead volumes today; synthetic compounds are gaining share fastest.
End User:
Application criticality determines buyer behavior, with life-safety systems commanding premium chemistry and documentation intensity.
- Automotive:Commercial vehicle fleets specify lubricity improver content through certificate-of-analysis requirements rather than brand loyalty. EPA Clean Air Act enforcement compels terminal rack blending to prevent high-pressure common rail pump failures in low-sulfur highway diesel.
- Aerospace:Hydraulic system OEMs demand pour points below minus 54 degrees Celsius and thermal oxidative stability certification. Qualification cycles exclude suppliers without integrated polyol ester manufacturing.
- Marine:Ship operators treat ultra-low-sulfur distillate fuels to meet IMO 2020 injection system protection requirements across global shipping corridors.
- Manufacturing:Metalworking fluid formulators prioritize direct technical service relationships for specialized extreme-pressure applications.
Automotive commands the largest procurement volumes; aerospace exhibits the steepest expansion trajectory.
Application:
Operating pressure and temperature regime dictate chemistry selection, with boundary lubrication conditions favoring polar ester architectures.
- Engine Oils:Cost-optimized fatty acid derivatives restore lubricity lost to hydrotreating in Group II/III base stocks. Volume concentrates in markets with mandatory sulfur reduction programs.
- Hydraulics:High-pressure systems above 300 bar require synthetic ester film strength to prevent pump cavitation and valve wear. Adoption concentrates in Germany's precision manufacturing sector and US Gulf Coast petrochemical operations.
- Metalworking:Extreme-pressure formulations for cutting and forming operations generate concentrated margin pools through specialized formulation requirements.
- Gear Oils:Hypoid and worm gear applications demand sulfur-phosphorus extreme-pressure additives combined with ester lubricity boosters.
Engine oils dominate current offtake; hydraulics applications are climbing the fastest.
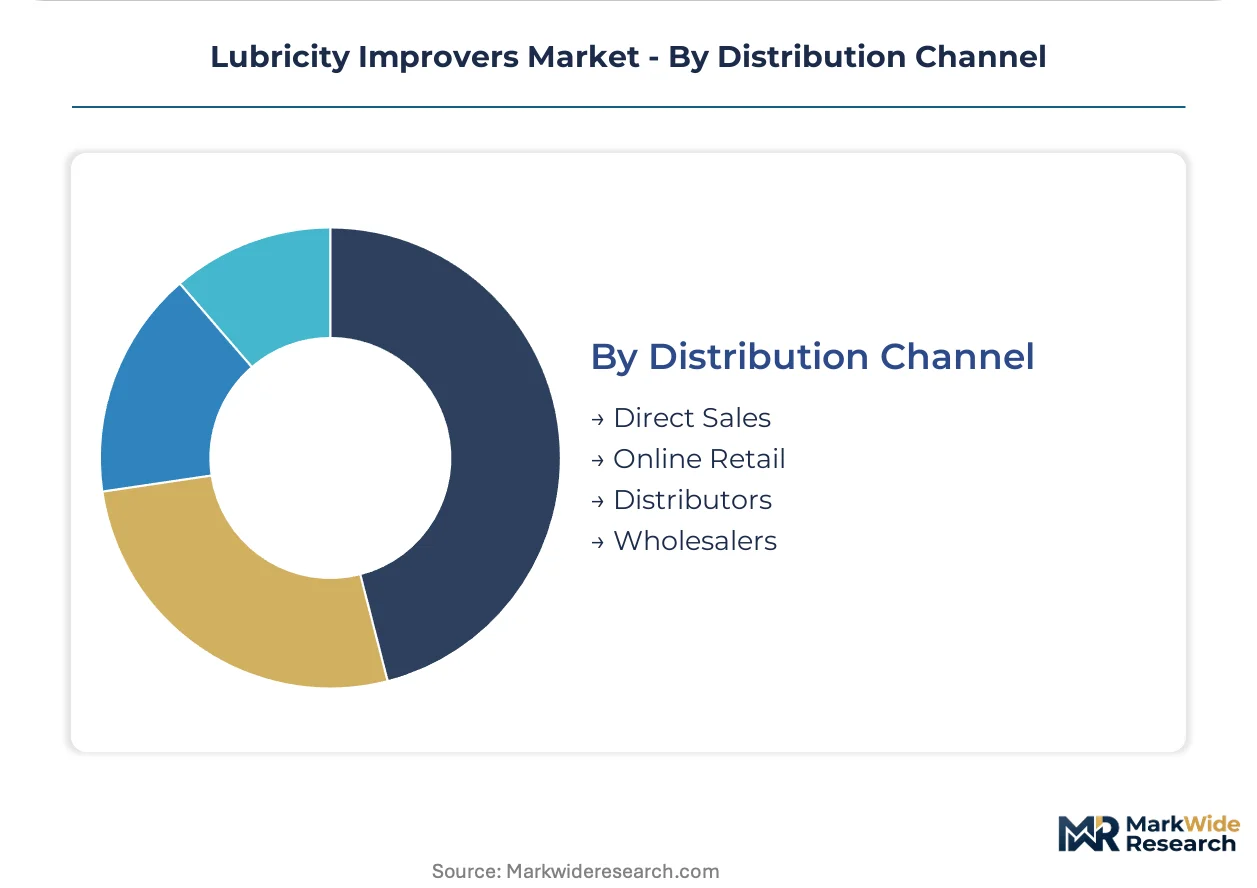
Distribution Channel:
Order scale and technical service intensity separate channel preferences, with large blenders bypassing intermediaries and smaller formulators relying on distributor inventory.
- Direct Sales:Major additive suppliers maintain dedicated technical service teams for multinational lubricant blenders and OEM fill plants. Contracts specify treat rate documentation and batch certification.
- Distributors:Regional chemical distributors stock commodity organic additives for independent blenders and smaller metalworking shops. Inventory concentration follows Group II/III base oil refinery locations.
- Wholesalers:Fuel marketers source lubricity improvers for terminal rack blending operations near US refining centers.
- Online Retail:Small-volume purchasers access packaged additive concentrates for aftermarket and specialty applications.
Direct sales channels capture the largest value; distributor networks are expanding most quickly in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany enforces stricter lubricant performance standards than the United States, while China scales additive production capacity faster than any other manufacturing economy. These divergent regulatory and industrial trajectories shape where formulation investments concentrate and which chemistry platforms gain regulatory permanence.
Germany
The KBA mandates certified synthetic additive packages for commercial vehicle fleet warranty compliance, redirecting procurement toward documented treat rate formulations. REACH registration requirements under ECHA restrict traditional fatty acid derivatives, accelerating biodegradable ester alternatives. Industrial additive blending concentrates in the Rhine-Ruhr corridor, where metalworking fluid formulators maintain direct technical service relationships with automotive OEMs.
United States
EPA enforcement of lubricity standards under the Clean Air Act compels terminal rack blending for low-sulfur highway diesel distribution. Fuel marketers treat ultra-low-sulfur distillate at major refining centers to prevent high-pressure common rail pump failures. Additive solubility testing clusters around Group II/III base oil production sites along the US Gulf Coast, where blenders optimize formulation compatibility.
China
Marine fuel treatment demand accelerates as Chinese ship operators adapt to IMO 2020 low-sulfur mandates across Asia-Pacific shipping corridors. The country's national chemical regulator enforces increasingly stringent additive registration protocols for imported lubricity chemistry. Synthetic ester manufacturing capacity expands in the Yangtze River Delta, where domestic suppliers backward integrate into polyol base stock production.
India
BIS mandatory performance specifications for commercial vehicle fleets create procurement volume for certified additive suppliers establishing local technical infrastructure. Fleet operators prioritize warranty-compliant treat rate documentation over brand loyalty in lubricant purchasing decisions. Formulation testing and certification activity concentrates in Maharashtra and Gujarat, where lubricant blenders serve domestic automotive and industrial machinery markets.
Japan
METI industrial standards for high-pressure hydraulic systems specify thermal stability thresholds that favor synthetic ester chemistry over traditional fatty acid derivatives. Aerospace hydraulic OEMs demand pour point certification below minus 54 degrees Celsius for qualification protocols. Precision manufacturing additive demand clusters in the Aichi prefecture around Nagoya, where metalworking fluid formulators serve automotive and machinery tool producers.
Lubricity Improvers Market Competitive Landscape
Top-tier vendors anchor the integrated additive technology segment, while regional blenders and specialty chemical distributors occupy service-intensive niches. The market structure rewards backward integration into ester base stocks and captive polyol production capabilities. Three strategic archetypes dominate: integrated petrochemical conglomerates with captive additive platforms, independent additive specialists with formulation expertise, and regional distributors with terminal blending infrastructure. Competitive moves center on technology licensing agreements and geographic expansion into emerging regulatory markets.
Among integrated chemical conglomerates, BASF SE and Dow Inc. exemplify the backward-integrated archetype with in-house ester base stock production. Afton Chemical Corporation occupies a position representing the independent additive specialist model focused on fuel-borne and lubricant chemistry platforms. These three companies illustrate how competitive positioning depends on control over critical raw material supply chains and qualification relationships with OEM specification committees.
| Leading Market Players |
|---|
| Afton Chemical Corporation |
| The Lubrizol Corporation |
| BASF SE |
| Innospec Inc. |
| Chevron Corporation |
| Dow Inc. |
| TotalEnergies SE |
| Huntsman International LLC |
| Dorf Ketal Chemicals |
| Others |
Value Network & Pricing Analysis
Formulation chemist scarcity in the Rhine-Ruhr corridor and Yangtze River Delta creates labor-cost differentials that widen pricing-tier spreads between commodity fatty acid derivatives and certified synthetic ester formulations. Fleet procurement departments exploit this spread through certificate-of-analysis requirements that compress distributor margins while rewarding technical documentation capabilities.
Pricing Analysis
Bundled technical service contracts command premiums over unbundled additive concentrate sales, particularly for aerospace hydraulic specifications requiring OEM qualification support. Three-tier pricing structure across aerospace-certified, automotive-fleet, and commodity metalworking levels reflects certification grade and volume scale differentiation. Cost compression in commodity organic additives intensifies because palm oil feedstock volatility erodes producer margins. Commercial vehicle fleet operators in Germany exhibit highest price sensitivity due to KBA-mandated treat rate documentation requirements, while aerospace OEMs prioritize thermal stability certification over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for synthetic ester formulations, while regional distributors serve independent blenders with commodity organic additives. Manufacturing concentrates in Germany, China, and the United States, where polyol ester production clusters around captive base stock facilities. Supply chains draw from vegetable oil feedstocks, petroleum-derived base oils, and specialized amide chemistries. Single-source vulnerability in Group II/III refinery capacity creates geographic dependency for additive solubility testing. Distribution runs through dedicated technical service teams for multinational lubricant blenders and terminal rack operators for fuel-borne lubricity applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as IMO 2020 mandates and REACH restrictions redirect procurement toward premium synthetic formulations with documented treat rates and biodegradable certification.
For Market Incumbents: Deploy backward integration into ester base stocks to defend margin position against commodity price volatility in palm oil derivatives. Lock in decade-long supply agreements through Boeing and Airbus qualification protocols before polyol ester manufacturing capacity expands in China. Counter emerging regional blenders in India by establishing local technical service infrastructure ahead of BIS mandatory performance specifications. For New Entrants and Emerging Players: Capture white-space opportunity in India's commercial vehicle fleet market where BIS standards create first-mover advantage for certified additive suppliers. Target wind turbine gearbox fluid specifications for offshore installations requiring 20-year synthetic ester life cycles. Lead with EU Green Deal Ecolabel certification to access preferential procurement scoring in public infrastructure tenders. For Investors and Strategic Acquirers: Integrated petrochemical conglomerates are the most active acquirer in this space, seeking captive additive platforms to secure downstream formulation control. Evaluate targets with polyol ester manufacturing capabilities and established OEM qualification relationships over pure distribution plays. Monitor REACH registration timelines for biodegradable ester alternatives as inflection indicator for chemistry platform permanence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ester Base Stocks | BASF SE and Dow Inc. anchor market position through captive polyol production. |
| OEM Qualification Protocol Completion | Boeing and Airbus thermal stability certifications lock in decade-long supply agreements. |
| Local Technical Service Infrastructure | First-mover advantage in India concentrates around Maharashtra and Gujarat testing clusters. |
| Biodegradable Ester Platform Development | EU Green Deal Ecolabel certification accesses preferential public infrastructure procurement. |
| Terminal Rack Blending Equipment Investment | EPA Clean Air Act enforcement compels fuel marketer treatment at US Gulf Coast refining centers. |
Research Methodology
Multiple input streams — additive formulation directors, lubricant blender procurement leads, marine fuel operations managers, and metalworking fluid technical service heads — were reconciled against customs trade data, ECHA REACH registration databases, SEC 10-K additive segment disclosures, and IMO marine fuel quality reports. Bottom-up treat rate modeling across end-use applications was cross-validated through top-down market sizing from base oil consumption patterns and additive blending capacity estimates.
Historical volume trajectories were cross-referenced against panel input from industry participants to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated chemistry platform, end-use criticality, distribution channel configuration, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted demand curves responding to IMO sulfur caps, REACH restriction timelines, and fleet procurement specification shifts.
Regulatory enforcement delays, feedstock price volatility, and qualification protocol extensions are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented base case assumptions regarding mandate implementation schedules and OEM specification adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Anti-Static Oil Market
Lubricants
North America Lubricants Market
Lubricants
Russia Automotive Lubricants Market
Lubricants
Synthetic Lubricants Market
Lubricants
Malaysia Commercial Vehicles Lubricants Market
Lubricants
Global Commercial Vehicles Lubricants Market
Lubricants
Plastic Lubricants Market
Lubricants
North America Automotive Lubricants Market
Lubricants
Wire Rope Lubricants Market
Lubricants
Spain Commercial Vehicles Lubricants Market
Lubricants
Poland Commercial Vehicles Lubricants Market
Lubricants
Sri Lanka Lubricants Market
Lubricants
Global Mineral Oil Market
Lubricants
South Korea Automotive Lubricants Market
Lubricants
China Refrigeration Lubricants Market
Lubricants
Thailand Lubricants Market