
 Mud Sediment Tester Market | 2026-2036
Mud Sediment Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Mud Sediment Tester Market Insights
Corrosion-resistant titanium alloys are restructuring procurement economics for submersible sensor housings in the mud sediment tester category. LEUTERT anchors its European installed base through backward integration into precision machining of pressure-rated enclosures. Fann Instrument Company sustains North American market presence by dominating API-standard calibration protocols for drilling-fluid compatibility. SINOMUD GROUP leverages captive supply of ceramic filtration membranes to differentiate its automated system offerings in Asia-Pacific tenders.
A mud sediment tester measures solid-phase concentration, particle-size distribution, and rheological properties of drilling fluids and environmental samples, typically operating at pressures up to 20,000 psi and temperatures exceeding 300°F to simulate downhole conditions. Portable testers command the largest volume share among product types due to field-deployment requirements on offshore platforms and remote construction sites. Electromagnetic technology leads the technology dimension for real-time downhole applications, while gravimetric methods retain margin strength in laboratory-certified environmental compliance testing where regulatory defensibility commands premium pricing.
EPA enforcement of NPDES permit limits for dredging discharge drives replacement demand among environmental agencies and construction firms operating in US coastal waters. The EU Marine Strategy Framework Directive, implemented by national regulators such as Germany's Federal Maritime and Hydrographic Agency, mandates standardized sediment-quality assessment protocols that elevate demand for laboratory-grade automated systems. REACH compliance on chemical sensor coatings shapes product access decisions for manufacturers serving European geotechnical engineers. Stakeholders must weigh capital allocation between portable field units for emerging-market infrastructure builds and laboratory-automation suites for tightening OECD environmental monitoring regimes.
Market Dynamics
Optical sensor technology is absorbing market share from legacy gravimetric methods as offshore drilling contractors face intensifying seabed disturbance protocols. The shift compresses equipment replacement cycles and restructures vendor qualification requirements across environmental compliance and drilling-fluid testing segments.
Growth Catalysts
- EPA NPDES permit enforcement:Stricter discharge limits for dredging operations in US coastal waters force construction firms and environmental agencies to upgrade sediment monitoring capabilities. Field-portable testers with real-time data logging now dominate tender specifications for federal infrastructure projects.
- Brazil pre-salt basin expansion:Deepwater drilling campaigns in the Santos Basin require high-pressure mud sediment testers rated above 15,000 psi. Petrobras-led consortia mandate automated particle-size distribution analysis to optimize drilling-fluid formulations.
- Electromagnetic sensing advancement:Downhole electromagnetic probes enable continuous solid-phase concentration measurement without fluid extraction. North Sea operators deploy these systems to reduce manual sampling labor on offshore platforms.
Market Restraints
- Titanium alloy input costs:Corrosion-resistant titanium sensor housings face price volatility tied to aerospace sector demand. Submersible enclosure manufacturers absorb margin compression or pass costs to buyers.
- Calibration infrastructure concentration:API-standard calibration protocols concentrate in Houston and Stavanger, creating logistics barriers for Asia-Pacific service providers seeking certified maintenance.
- Gravimetric method regulatory entrenchment:Laboratory-certified environmental compliance testing in OECD jurisdictions retains gravimetric methods for legal defensibility, slowing full optical sensor adoption.
Strategic Opportunities
- India coastal infrastructure buildout:Sagarmala port modernization and offshore wind leasing create demand for portable field units. Domestic environmental consultancies lack automated sediment-testing capacity.
- EU Marine Strategy Framework Directive implementation:Germany's Federal Maritime and Hydrographic Agency mandates standardized sediment-quality protocols. Laboratory-automation suites qualify for public-sector procurement preference.
- Ceramic membrane-optical sensor convergence:Integrated filtration-analysis systems reduce sample preparation time. SINOMUD GROUP's captive ceramic supply positions it for Asia-Pacific tender dominance.
Industry Challenges
- Cross-functional calibration expertise shortage:Technicians must bridge drilling-fluid rheology, optical physics, and EPA compliance documentation. Training pipelines lag equipment deployment timelines.
- Legacy system integration complexity:Offshore platforms operate mixed fleets of 1990s-era gravimetric benches and new electromagnetic probes. Data format standardization remains unresolved.
- REACH chemical coating recertification:European sensor manufacturers face batch-testing requirements for pressure-seal polymers. Registration timelines extend product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mud Sediment Tester Market |
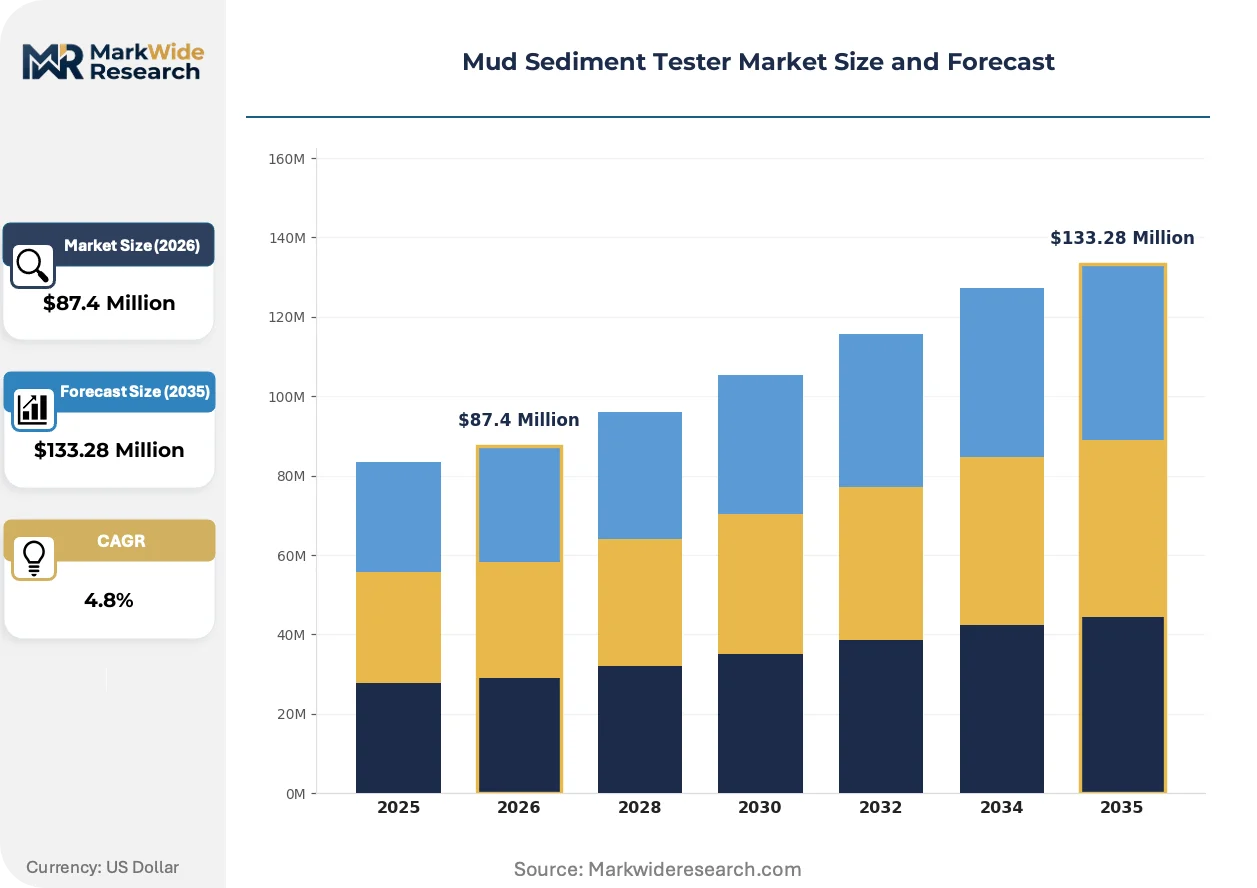
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $133.28 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Testers, Laboratory Testers, Automated Systems, Manual Testers Technology: Electromagnetic, Optical, Gravimetric, Pneumatic Application: Environmental Monitoring, Construction, Oil & Gas Exploration, Research End User: Geotechnical Engineers, Environmental Agencies, Construction Firms, Academic Institutions |
| Companies Covered | LEUTERT, SINOMUD GROUP, OFI Testing Equipment, Fann Instrument Company, Grace Instrument, Filtron Envirotech, Mudex, Tryte Technology, CONTROLS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mud Sediment Tester Market Trends and Innovations
Sensor miniaturization and real-time telemetry are compressing the boundary between field-portable and laboratory-grade systems. Vendors now compete on data integration rather than hardware specifications alone.
MEMS-based optical particle counters are absorbing demand from laser diffraction systems in offshore drilling applications. Statoil-led North Sea consortia specify these units for subsea deployment due to reduced power consumption and footprint. The technology is absorbing maintenance budget allocations previously directed at benchtop laboratory equipment, forcing vendors to restructure service revenue models.
REACH compliance on chemical sensor coatings is reshaping European procurement patterns. Manufacturers must submit full toxicity dossiers for pressure-seal polymers and optical window materials. Laboratory-grade automated systems face extended type-approval timelines, benefiting pre-certified incumbent suppliers with dedicated regulatory affairs teams.
Environmental agencies now unbundle after-sales service from capital equipment purchases. US Army Corps of Engineers districts and German state environmental offices negotiate separate calibration and data-management contracts. This shift is most visible in the North American Great Lakes region, where multi-jurisdictional monitoring programs consolidate service procurement across state boundaries.
Mud Sediment Tester Market Segmentation
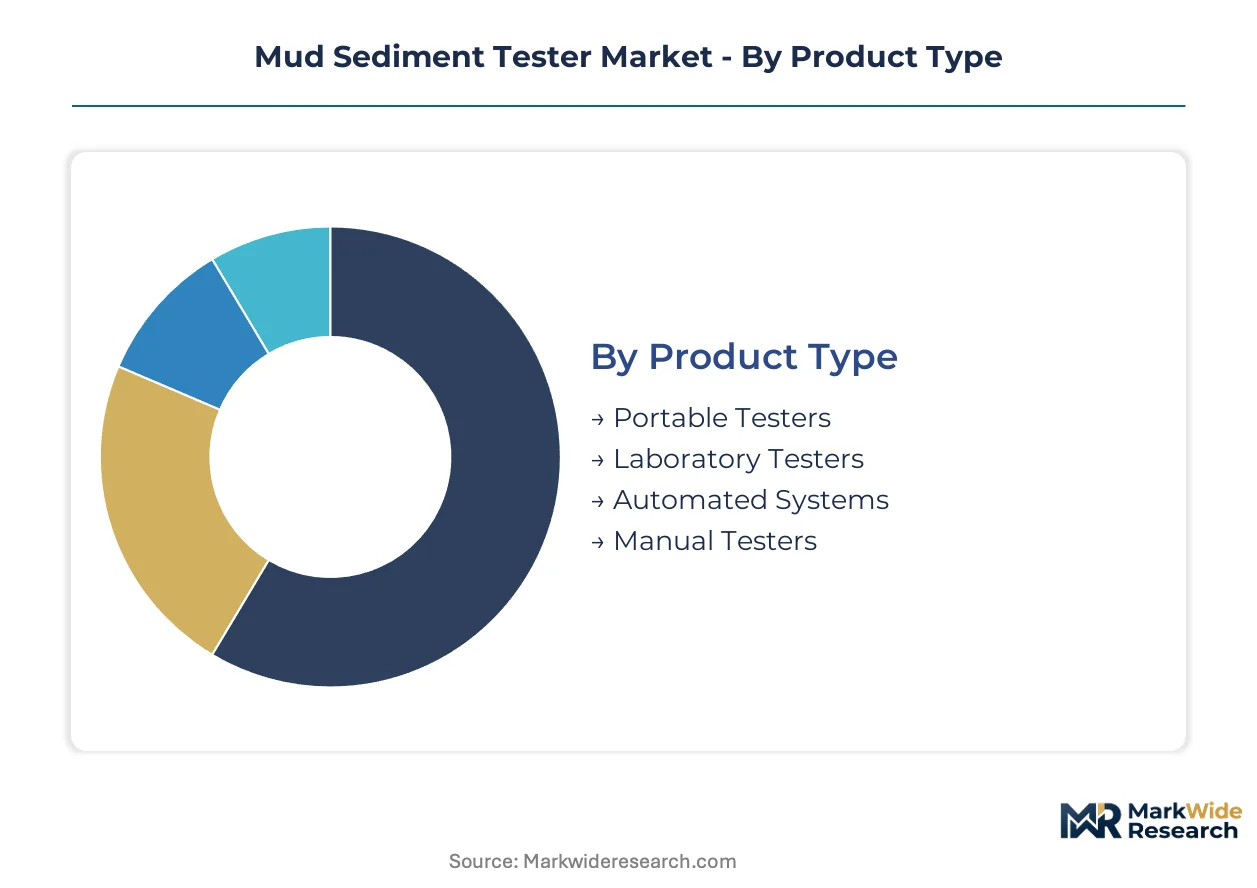
Equipment specifications in the mud sediment tester market diverge sharply between field-deployment imperatives and laboratory certification requirements. Procurement patterns cluster around pressure ratings, automation levels, and regulatory defensibility rather than price alone.
Product Type:
Pressure tolerance and deployment logistics determine equipment selection across offshore platforms and fixed-site laboratories.
- Portable Testers:Battery-powered units rated to 5,000 psi dominate offshore platform maintenance schedules. Norwegian North Sea contractors specify these for real-time sediment monitoring during drilling campaigns where manual sampling delays carry penalty clauses.
- Automated Systems:Robotic sample handling with ceramic membrane filtration reduces preparation time for high-throughput environmental labs. Germany's Federal Maritime and Hydrographic Agency mandates these for standardized sediment-quality protocols under EU Marine Strategy Framework Directive implementation.
- Laboratory Testers:Benchtop gravimetric systems retain regulatory entrenchment in EPA-certified environmental compliance testing.
- Manual Testers:Hand-operated pneumatic units serve budget-constrained construction firms in emerging-market coastal infrastructure projects.
Mature deployment sits with Portable Testers. Newer deployment is concentrated in Automated Systems.
Technology:
Measurement physics directly correlates with capital intensity and maintenance scheduling across drilling-fluid and environmental applications.
- Electromagnetic:Downhole probes enable continuous solid-phase concentration measurement without fluid extraction. North Sea operators deploy these systems to reduce manual sampling labor on offshore platforms where helicopter transport costs dominate operational budgets.
- Optical:MEMS-based particle counters absorb maintenance budgets previously directed at benchtop laboratory equipment. Statoil-led consortia specify these for subsea deployment due to reduced power consumption and footprint in constrained submersible housings.
- Gravimetric:Legacy mass-based methods retain legal defensibility in OECD environmental compliance testing where regulatory documentation standards are strictest.
- Pneumatic:Compressed-air-driven separation suits remote construction sites lacking reliable electrical infrastructure.
Gravimetric methods anchor laboratory certification. Optical sensors are gaining share fastest in offshore drilling applications.
Application:
Regulatory enforcement intensity and project scale create divergent equipment specifications across end-use sectors.
- Oil & Gas Exploration:Deepwater drilling campaigns in Brazil's Santos Basin require high-pressure testers rated above 15,000 psi. Petrobras-led consortia mandate automated particle-size distribution analysis to optimize drilling-fluid formulations and reduce non-productive time.
- Environmental Monitoring:EPA NPDES permit enforcement forces construction firms and environmental agencies to upgrade sediment monitoring capabilities. US Army Corps of Engineers districts now specify field-portable testers with real-time data logging for federal infrastructure projects.
- Construction:Dredging discharge compliance drives replacement demand among firms operating in US coastal waters and EU port modernization programs.
- Research:Academic institutions prioritize multi-physics measurement platforms for method validation studies.
Environmental Monitoring commands the steepest expansion trajectory. Oil & Gas Exploration retains the highest average selling prices.
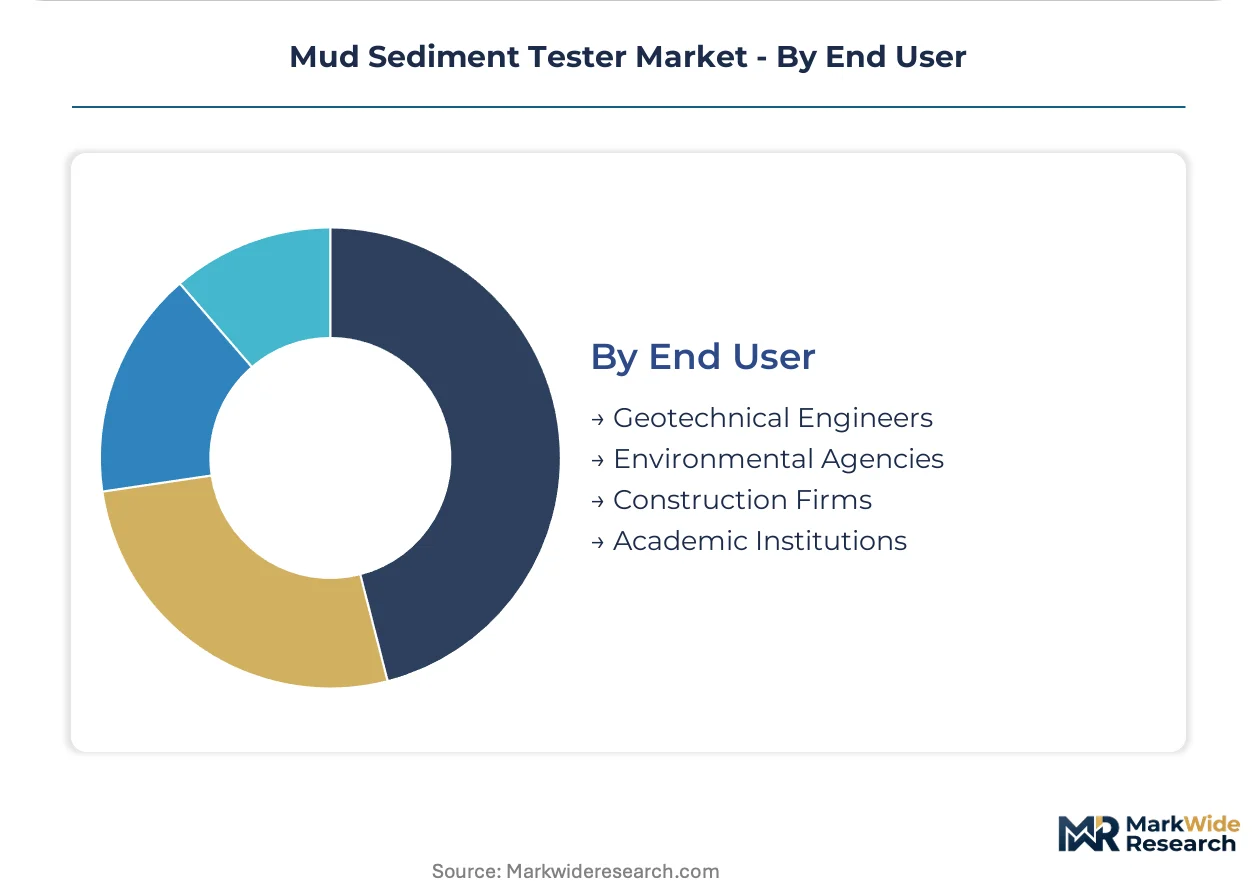
End User:
Technical expertise depth and procurement authority shape vendor qualification requirements across customer types.
- Environmental Agencies:US state environmental offices and German federal regulators unbundle after-sales service from capital equipment purchases. Multi-jurisdictional monitoring programs in the North American Great Lakes region consolidate service procurement across state boundaries.
- Geotechnical Engineers:REACH compliance on chemical sensor coatings shapes product access decisions for European practitioners. Registration timelines for pressure-seal polymers extend equipment qualification schedules.
- Construction Firms:Field-deployment requirements dominate tender specifications for coastal infrastructure builds in India under Sagarmala port modernization.
- Academic Institutions:Training pipelines for cross-functional calibration expertise lag equipment deployment timelines in university geoscience departments.
Environmental Agencies drive standardization. Geotechnical Engineers are expanding their instrumentation fleets most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stavanger's petroleum technology cluster concentrates deepwater instrumentation demand through Norway's tax-advantaged petroleum research regime. The city's subsea engineering corridor anchors European procurement for high-pressure mud sediment testers deployed across North Sea drilling campaigns.
United States
Gulf Coast offshore operators drive replacement demand for portable testers rated above 10,000 psi. EPA NPDES permit enforcement tightens discharge monitoring for dredging contractors in Louisiana and Texas coastal waters. Houston's energy corridor hosts API-standard calibration facilities that service drilling-fluid compatibility testing across the Americas.
Brazil
Petrobras-led consortia mandate automated particle-size distribution analysis for Santos Basin pre-salt drilling. ANVISA-equivalent environmental protocols under Brazil's national petroleum regulator shape equipment qualification timelines. Rio de Janeiro's offshore engineering cluster concentrates service provider capacity for deepwater sediment monitoring systems.
Germany
The Federal Maritime and Hydrographic Agency enforces EU Marine Strategy Framework Directive protocols for standardized sediment-quality assessment. Laboratory-automation suites qualify for public-sector procurement preference in Hamburg and Bremen port modernization programs. REACH compliance on chemical sensor coatings extends equipment registration timelines for European geotechnical engineers.
India
Sagarmala port modernization and offshore wind leasing create demand for portable field units among domestic environmental consultancies. The Central Pollution Control Board's coastal discharge guidelines tighten monitoring requirements for dredging contractors in Gujarat and Maharashtra. Chennai's marine engineering cluster lacks automated sediment-testing capacity, opening procurement opportunities for foreign equipment vendors.
China
Dual carbon goals accelerate offshore wind foundation drilling in Jiangsu and Guangdong provinces. MEE enforcement of marine sediment quality standards elevates demand for laboratory-grade systems in state environmental monitoring stations. Qingdao's subsea equipment manufacturing base develops indigenous high-pressure tester capabilities for domestic oilfield service companies.
Mud Sediment Tester Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated instrument houses commanding premium positioning in automated systems while regional fabricators compete on field-portable unit cost. The vendor base organizes into three tiers: precision-machining specialists with captive enclosure production, calibration-protocol incumbents with API-standard authority, and membrane-technology integrators with ceramic filtration supply chains. Consolidation pressure concentrates among mid-scale European manufacturers facing titanium alloy input volatility. Dominant competitive moves include backward integration into pressure-rated enclosure machining and geographic expansion through Asia-Pacific tender participation.
Among European precision-machining specialists, LEUTERT anchors the premium-tier segment through its Stavanger-based installed base and captive production of corrosion-resistant sensor housings. SINOMUD GROUP occupies a distinct position among Asia-Pacific membrane-technology integrators, leveraging its captive ceramic filtration supply to differentiate automated system offerings in regional tenders. Fann Instrument Company exemplifies the calibration-protocol incumbent archetype, sustaining North American presence through API-standard authority that shapes drilling-fluid compatibility testing requirements across the Gulf Coast.
| Leading Market Players |
|---|
| LEUTERT |
| SINOMUD GROUP |
| OFI Testing Equipment |
| Fann Instrument Company |
| Grace Instrument |
| Filtron Envirotech |
| Mudex |
| Tryte Technology |
| CONTROLS |
| Others |
Pricing and Supply Chain Analysis
Backward integration into precision machining of titanium sensor housings anchors both supply security and pricing power for incumbent vendors serving North Sea drilling contractors. Captive production of corrosion-resistant enclosures insulates LEUTERT and comparable specialists from aerospace-sector titanium volatility while supporting premium positioning against outsourced competitors.
Pricing Analysis
Volume concentrates in portable field units while margins accrue to automated laboratory systems. Three-tier pricing structure across premium, standard, and economy levels separates API-certified calibration protocols from uncertified field deployments. Cost compression in standard-tier portable testers is intensifying because Brazilian pre-salt basin contractors consolidate procurement around fewer qualified vendors. Environmental agencies exhibit lowest price sensitivity due to regulatory defensibility requirements, while emerging-market construction firms drive economy-tier negotiations.
Supply Chain Analysis
Regional distribution centers in Houston, Stavanger, and Singapore coordinate hub-and-spoke patterns for calibration equipment and replacement sensor modules. Manufacturing concentrates in Germany, Norway, and China, with precision machining anchored in European petroleum technology clusters and ceramic membrane production centered in Asia-Pacific. Raw material dependencies include titanium alloys for submersible housings, optical-grade sapphire windows, and ceramic filtration membranes. Single-source vulnerability sits with API-standard calibration facilities concentrated in Houston and Stavanger. Distribution runs through authorized service partners with captive calibration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where titanium alloy input volatility and REACH recertification burdens force weaker European manufacturers toward exit or acquisition.
For Market Incumbents: Deepen backward integration into titanium machining capacity to defend margin position against aerospace-sector demand spikes. Lock in long-term ceramic membrane supply agreements with SINOMUD GROUP or comparable captive producers to secure automated system cost structures. The priority lever centers on API calibration protocol authority as electromagnetic sensing displaces legacy gravimetric methods. For New Entrants and Emerging Players: EPA NPDES permit enforcement in US coastal waters opens a window for field-portable tester specialization without legacy gravimetric infrastructure burdens. White-space targets include India's Sagarmala port modernization where domestic environmental consultancies lack automated capacity, and Brazil's Santos Basin where ANVISA-equivalent protocols create qualification delays for established vendors. A calibration-service-first go-to-market angle bypasses capital-intensive hardware manufacturing. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by precision-machining houses seeking drilling-fluid testing exposure. Long-term viability favors vendors with integrated ceramic filtration supply or captive titanium enclosure production. The signal to watch is electromagnetic sensor adoption rates in North Sea drilling campaigns, which would accelerate replacement cycles and concentrate share among pre-certified incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Machining | Captive enclosure production insulates margins from aerospace demand volatility affecting Norwegian suppliers. |
| Ceramic Membrane Supply Agreement | Long-term sourcing from Asia-Pacific producers secures cost position for automated filtration-analysis systems. |
| API Calibration Protocol Investment | Certification authority in Houston or Stavanger creates switching costs for drilling-fluid compatibility testing. |
| Electromagnetic Sensor Platform Launch | Subsea deployment capability addresses Statoil-led North Sea consortium specifications for reduced platform labor. |
| India Field-Service Partnership | Local calibration capacity addresses Sagarmala infrastructure demand without import duty exposure on capital equipment. |
Research Methodology
Trade publications, petroleum engineering journals, and environmental regulatory filings formed the secondary backbone of this analysis. Primary interviews with offshore drilling contractors, environmental agency procurement officers, geotechnical engineering consultants, and subsea equipment distributors combined with customs data and API certification records. Bottom-up unit economics and top-down sectoral demand triangulated market sizing across portable, automated, laboratory, and manual tester categories.
Bottom-up modeling tracked equipment deployment by pressure rating, automation level, and regulatory certification tier across the projection horizon. Segmentation dimensions included product type, technology physics, application sector, and end-user technical depth. CAGRs derived from replacement cycle compression analysis and regulatory enforcement intensity scoring. Industry-specific inputs incorporated NPDES permit issuance rates, Santos Basin drilling campaign schedules, and EU Marine Strategy Framework Directive implementation timelines.
The model assumes a particular technology adoption path; alternative pathways for optical sensor displacement of gravimetric methods would alter the outlook. Forecasts reflect stated assumptions on regulatory enforcement continuity and titanium supply stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Glass Testing Equipment Market
Testing Equipment
Chromatography Market
Testing Equipment
Supercritical Fluid Chromatography (SFC) System Market
Testing Equipment
Global Rheometer and Viscometer Market
Testing Equipment
Carbon Black Content Tester Market
Testing Equipment
Total Reflection X Ray Fluorescence (TXRF) Spectrometer Market
Testing Equipment
Global Residue Testing Market
Testing Equipment
North America Dissolved Gas Analyzer Market
Testing Equipment
Melting Point Apparatus Market
Testing Equipment
Global Liquid Process Analyzer Market
Testing Equipment
Global Trace Metal Analysis Market
Testing Equipment
Corrosion Testing Services Market
Testing Equipment
Global Host Cell Contaminant Testing Market
Testing Equipment
Global Chiral Chromatography Column Market
Testing Equipment
Benchtop Density Meter for Solids Market
Testing Equipment
Global Liquid Chromatography Instruments Market