
 Global Energy Efficient HVAC Systems Market | 2026-2036
Global Energy Efficient HVAC Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Energy Efficient HVAC Systems Market Analysis
Asian compressor manufacturing clusters is realigning toward inverter-driven and low-GWP refrigerant platforms. Daikin Industries leverages captive compressor production and refrigerant IP to anchor premium positioning across VRF and heat pump segments. Carrier Global Corporation competes through deep chiller engineering heritage and building automation integration. Midea Group dominates cost-optimized residential air conditioning volume while extending manufacturing scale across Southeast Asian export hubs.
Energy efficient HVAC systems combine high-performance compressors, advanced heat exchangers, and intelligent controls to deliver heating, cooling, ventilation, and humidity management with minimized electrical input and refrigerant environmental impact. Coefficient of performance ratings and seasonal energy efficiency ratios serve as core functional parameters governing equipment selection in commercial and institutional procurement. Heat pumps are capturing the fastest expansion as building electrification mandates displace fossil-fuel boilers across temperate climates. Smart thermostat integration is concentrating margin pools at the building automation layer, where data analytics and predictive maintenance create recurring revenue attachment. Chillers retain structural importance in large-format commercial and industrial cooling but face elongating replacement cycles in mature North American and European installed bases.
The EPA's SNAP program and Significant New Alternatives Policy rulings govern refrigerant eligibility in US commercial and residential equipment, directly constraining product development roadmaps. EMA's alignment with EU F-Gas Regulation phase-down schedules, Japan's METI Top Runner standards, and China's GB energy efficiency labeling collectively compress allowable global warming potential thresholds and elevate minimum performance coefficients across major demand centers. Stakeholders must monitor refrigerant patent cliffs, raw material access for rare-earth magnet motors, and evolving carbon border adjustment mechanisms that will reshape competitive cost structures for cross-border equipment trade.
Market Dynamics
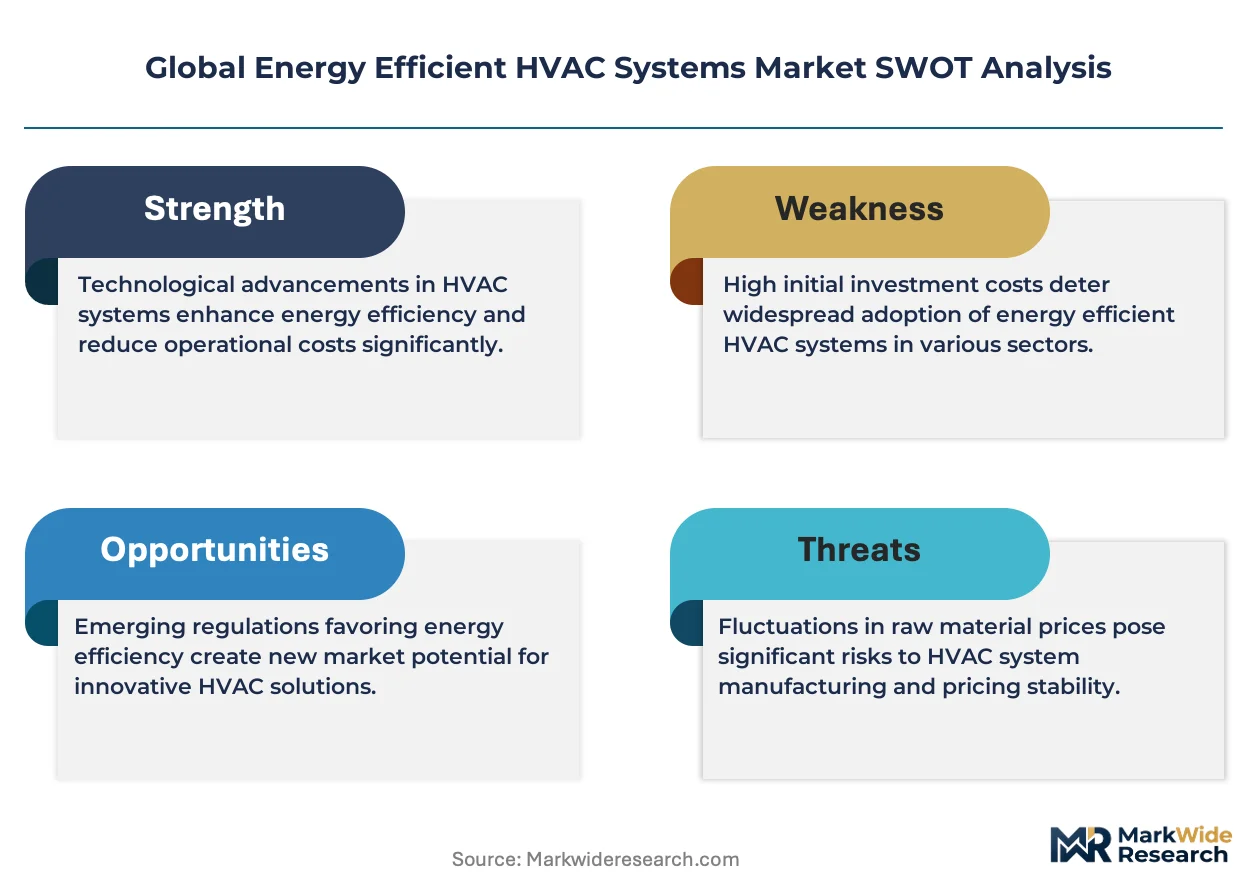
The EU F-Gas Regulation's refrigerant phase-down schedule is compressing product development timelines and forcing simultaneous transitions across compressor engineering, heat exchanger materials, and control system architectures.
Growth Catalysts
- Building electrification mandates:Germany's Building Energy Act and similar ordinances across France and the Netherlands are mandating heat pump installation in new construction and major renovations, eliminating fossil-fuel boiler options.
- China's GB energy efficiency labeling:Municipal building codes in Beijing, Shanghai, and Shenzhen now enforce minimum seasonal performance factors for commercial and residential equipment, creating compulsory replacement demand.
- Smart building automation convergence:Facility managers in US healthcare and data center verticals are bundling HVAC procurement with predictive maintenance platforms and energy management software.
Market Restraints
- Rare-earth magnet supply concentration:Neodymium and dysprosium processing for high-efficiency permanent magnet motors concentrates in Chinese refining operations, exposing inverter compressor supply chains to export control volatility.
- Low-GWP refrigerant cost premiums:R-32 and R-454B alternatives carry 15-40% material cost escalations versus phased-out R-410A, compressing margins on mid-tier residential equipment.
- Skilled technician scarcity:A2L mildly flammable refrigerant handling requires certified workforce retraining that outpaces vocational program capacity across US and European service networks.
Strategic Opportunities
- India's cooling action plan:The Bureau of Energy Efficiency's mandatory star rating expansion and room air conditioner efficiency standards create a regulatory tailwind for inverter technology penetration in a historically fixed-speed market.
- Industrial heat pump applications:Food processing and chemical manufacturing facilities in Japan and South Korea are piloting high-temperature heat pumps for process steam generation above 150°C.
- Refrigerant reclamation infrastructure:The EPA's SNAP program enforcement and EU F-Gas quota reductions are creating service revenue pools in refrigerant recovery, reclamation, and banking logistics.
Industry Challenges
- Dual refrigerant platform complexity:Manufacturers must simultaneously engineer for A2L flammability standards in North American and European markets while maintaining R-32 and R-410A legacy lines for developing economies with slower phase-down schedules.
- Integration friction with BAS protocols:BACnet and Mod interoperability gaps between legacy building automation systems and cloud-native HVAC controls delay smart retrofit deployments in US commercial real estate portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Energy Efficient HVAC Systems Market |
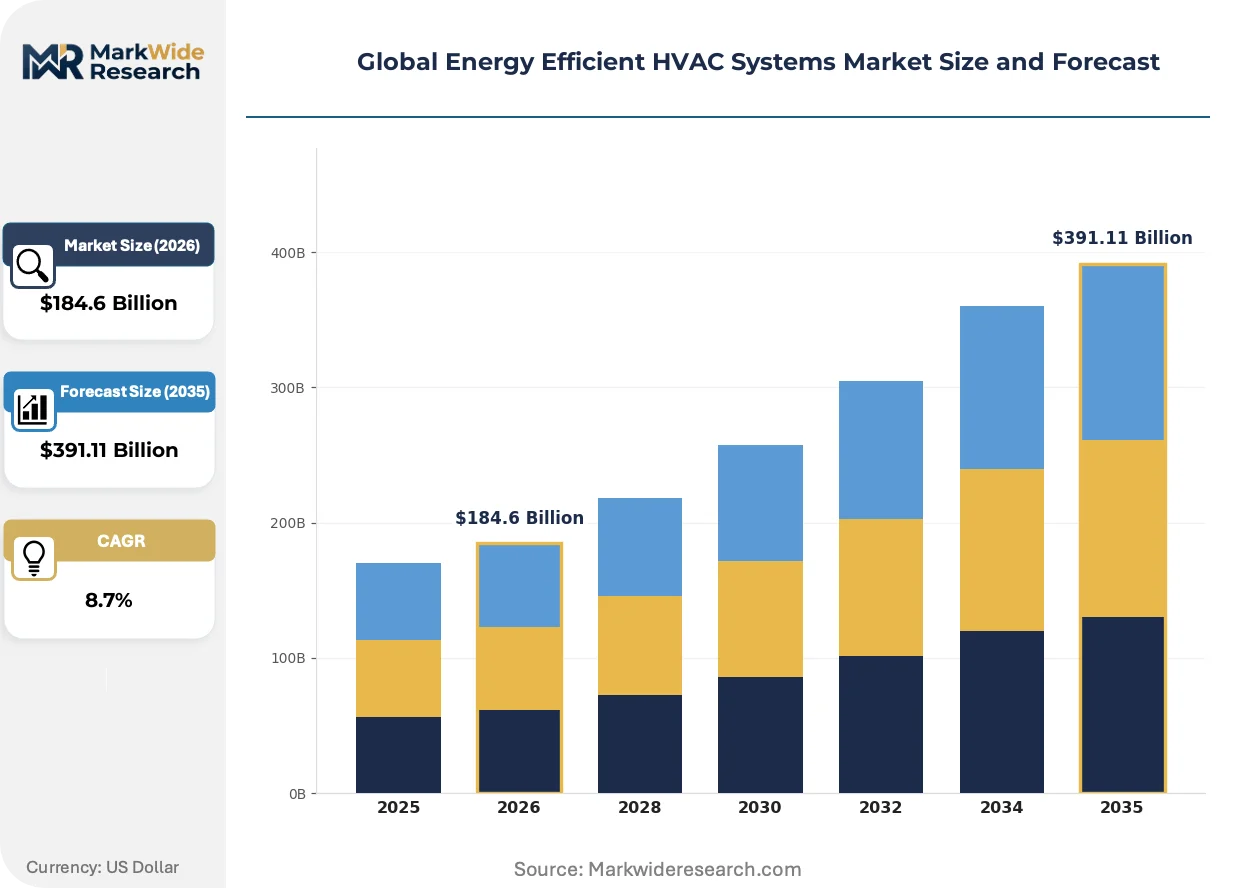
| Market Size in 2026 | $184.6 Billion |
| Market Size in 2035 | $391.11 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chillers, Heat Pumps, Air Conditioners, Ventilation Units Technology: Variable Refrigerant Flow, Smart Thermostats, Geothermal, Solar-Assisted End User: Commercial Buildings, Industrial Facilities, Residential Complexes, Educational Institutions Application: Heating, Cooling, Ventilation, Humidity Control |
| Companies Covered | Daikin Industries, Carrier Global Corporation, Trane Technologies, Midea Group, Johnson Controls International, Mitsubishi Electric Corporation, Lennox International, Siemens AG, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Energy Efficient HVAC Systems Market Emerging Trajectories
Equipment architecture is converging around electrification, refrigerant chemistry transformation, and software-defined performance optimization. Three developments are compressing legacy technology viability and redistributing margin pools across the value chain.
Variable refrigerant flow systems with integrated heat recovery are consolidating market share in multi-zone commercial applications. Property developers in Germany and the Netherlands specify VRF for mixed-use buildings where simultaneous heating and cooling loads occur. This technology is consolidating specification authority away from traditional chiller-boiler combinations toward integrated manufacturer ecosystems.
Japan's METI Top Runner program and the EU F-Gas Regulation are synchronizing efficiency and refrigerant mandates across previously divergent regulatory regimes. Equipment manufacturers now engineer single global platforms to satisfy both Japan's annual performance factor requirements and Europe's GWP-weighted quota calculations. Large-tonnage chillers and commercial rooftop units face the steepest redesign cycles as both jurisdictions tighten thresholds simultaneously.
Energy service company contracting models are displacing traditional equipment-only procurement in US institutional and federal building portfolios. Performance guarantees covering kilowatt-hour reductions and thermal comfort metrics now determine vendor selection for Veterans Affairs hospitals and General Services Administration facilities. This shift concentrates buyer power among ESCOs with balance-sheet capacity to underwrite multi-year savings commitments.
Global Energy Efficient HVAC Systems Market Segmentation
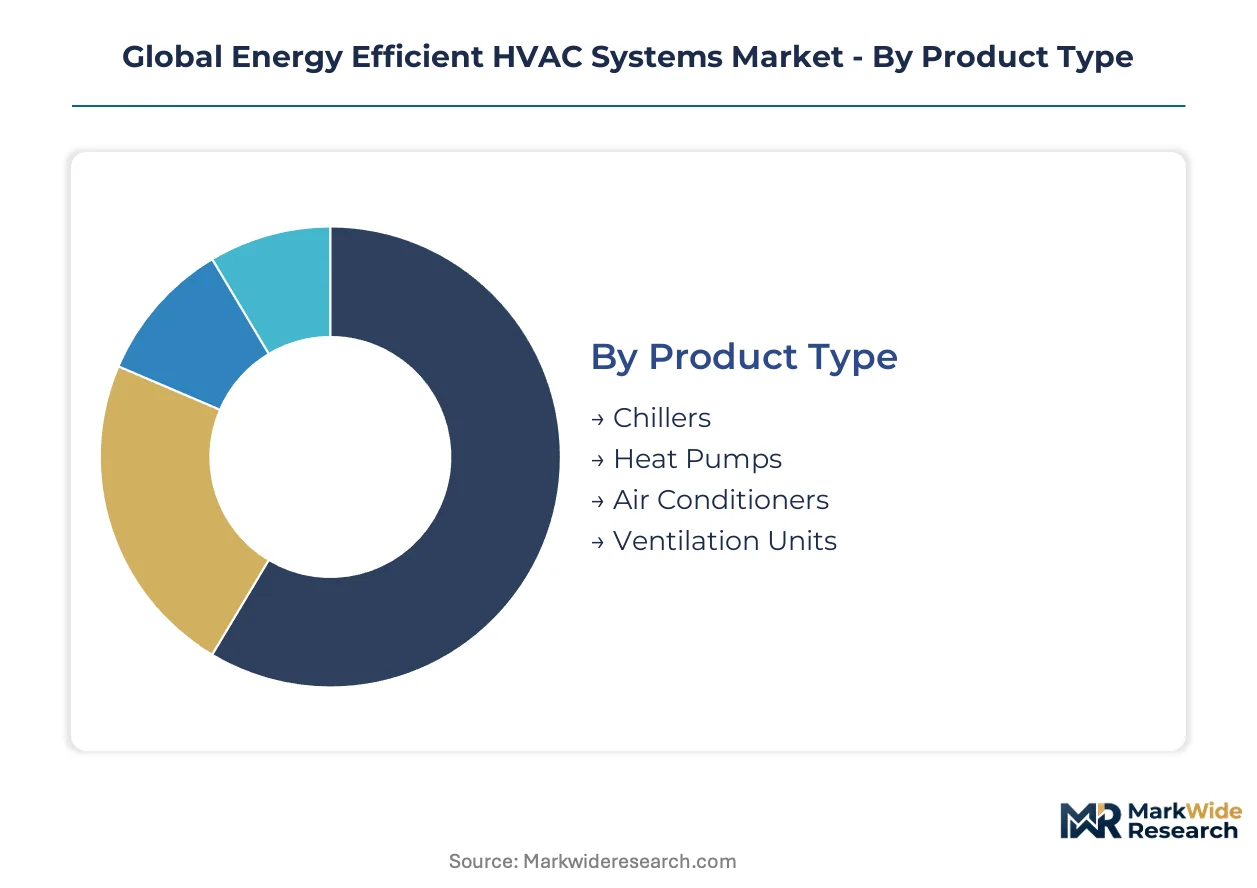
Equipment segmentation in energy efficient HVAC markets reflects divergent upgrade cycles across product categories. Technology roadmaps for refrigerant transitions and electrification mandates reshape procurement patterns differently across each segment cluster.
Product Type:
Replacement timelines stretch from 15-year chiller cycles to 8-year residential air conditioner turnover, compressing R&D prioritization for manufacturers serving multiple product tiers.
- Chillers:Large-tonnage centrifugal and screw compressor systems serve commercial and industrial base loads. Demand concentrates in US healthcare and data center verticals where EPA SNAP refrigerant rulings force simultaneous efficiency and chemistry upgrades.
- Heat Pumps:Air-source and ground-source systems deliver heating and cooling through vapor compression cycles with reversible refrigerant flow. Germany's Building Energy Act and similar ordinances across the Netherlands and France mandate heat pump installation in new construction, eliminating fossil-fuel boiler alternatives.
- Air Conditioners:Unitary and split systems dominate residential and light commercial cooling loads across tropical and subtropical climates.
- Ventilation Units:Energy recovery ventilators and heat recovery ventilators precondition incoming air using exhaust stream thermal energy.
Volume placements concentrate in Air Conditioners; the faster expansion belongs to Heat Pumps.
Technology:
Cost stratification across technology tiers separates premium inverter-driven platforms from baseline fixed-speed equipment, with smart control layers capturing margin expansion in retrofit applications.
- Variable Refrigerant Flow:Multi-zone refrigerant distribution systems modulate compressor speed and electronic expansion valves to match zone-level thermal loads. Property developers in Germany and the Netherlands specify VRF for mixed-use buildings with simultaneous heating and cooling requirements.
- Smart Thermostats:Networked control devices integrate occupancy sensing, weather forecasting, and utility rate signals to optimize equipment runtime. US healthcare and data center facility managers bundle HVAC procurement with predictive maintenance platforms and energy management software.
- Geothermal:Ground-source heat pumps exchange thermal energy with subsurface soil or aquifer formations for stable coefficient of performance.
- Solar-Assisted:Photovoltaic-thermal hybrid systems or absorption chillers leverage solar irradiance to reduce grid electricity draw.
Customer procurement gravitates toward Smart Thermostats for retrofit economics; Geothermal claims the steepest expansion trajectory where drilling costs decline.
End User:
Application maturity varies sharply across customer types, with commercial buildings driving specification authority while residential volume scales through cost-optimized manufacturing.
- Commercial Buildings:Office, retail, and hospitality facilities above 50,000 square feet deploy centralized chillers, VRF, or rooftop units with building automation integration. China's municipal building codes in Beijing, Shanghai, and Shenzhen enforce minimum seasonal performance factors for new commercial construction.
- Industrial Facilities:Manufacturing plants and process industries require precision temperature and humidity control for production environments. Food processing and chemical manufacturing facilities in Japan and South Korea pilot high-temperature heat pumps for process steam generation above 150°C.
- Residential Complexes:Single-family and multi-family housing units prioritize first-cost minimization with inverter penetration rising on regulatory pressure.
- Educational Institutions:K-12 and university campuses balance capital constraints against extended equipment lifecycle requirements.
Equipment shipments concentrate in Commercial Buildings; Industrial Facilities gain share fastest on process electrification mandates.
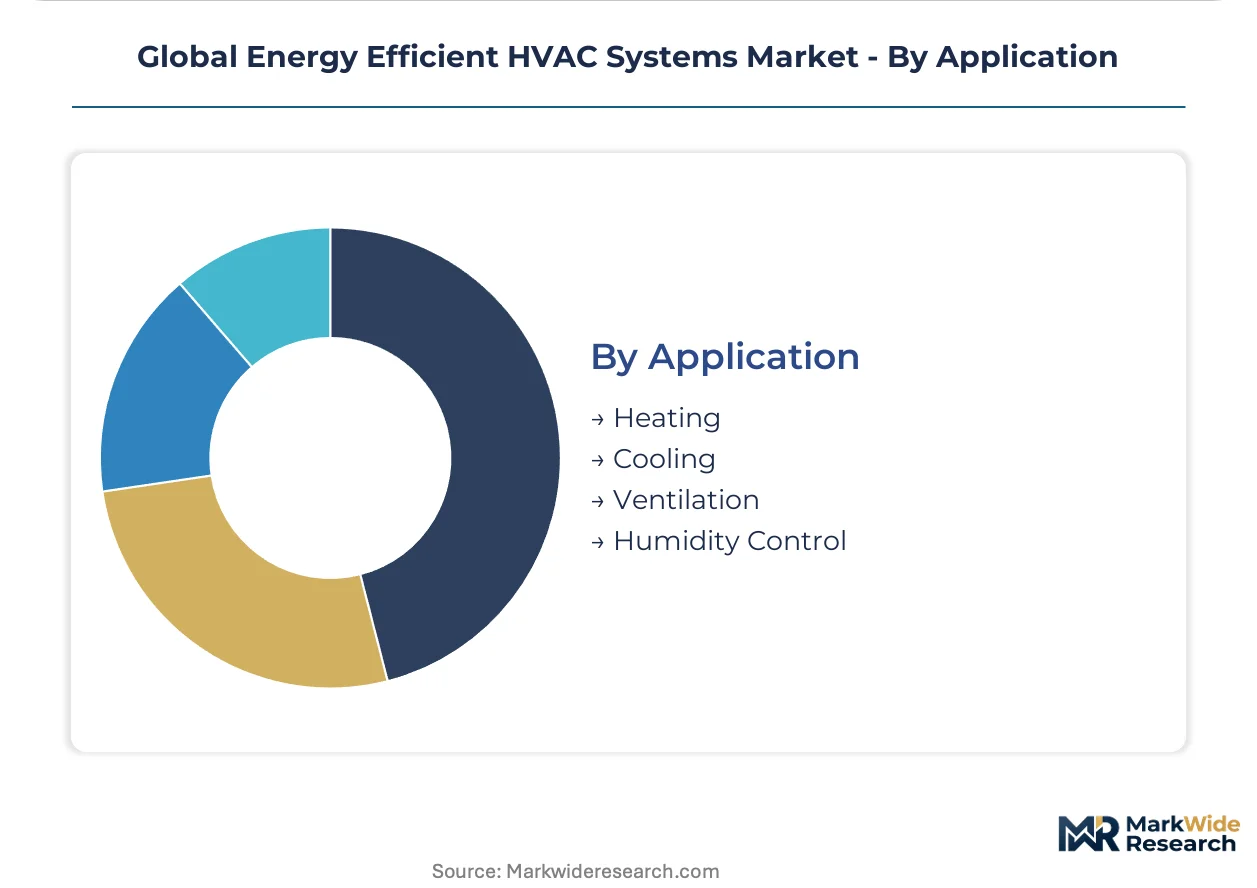
Application:
Functional specialization across heating, cooling, ventilation, and humidity control creates divergent equipment specifications and seasonal utilization patterns.
- Heating:Heat pump and boiler systems deliver space heating through hydronic distribution or forced air. Building electrification mandates across temperate European climates displace fossil-fuel combustion.
- Cooling:Vapor compression and absorption systems remove sensible and latent heat from conditioned spaces. Peak demand management programs in US utility territories incentivize thermal storage integration.
- Ventilation:Mechanical supply and exhaust systems maintain indoor air quality through filtered outdoor air introduction.
- Humidity Control:Dedicated outdoor air systems and desiccant wheels manage latent loads separately from temperature control.
Cooling dominates current installed capacity; Heating is climbing the fastest on building electrification policy alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare-earth magnet processing clusters in Jiangxi and Inner Mongolia anchor inverter compressor supply chains for Asian manufacturing. These material flows shape equipment cost structures across major demand centers.
United States
Data center construction in Northern Virginia and Phoenix drives chiller and precision cooling procurement. The EPA's SNAP program governs refrigerant eligibility for commercial equipment, compressing product development timelines. Houston and Dallas-Fort Worth concentrate service infrastructure for A2L refrigerant handling certification.
Germany
Building electrification mandates under the Building Energy Act eliminate fossil-fuel boilers in new construction. The EU F-Gas Regulation's phase-down schedule forces simultaneous heat pump and refrigerant transitions. Industrial clusters in Bavaria and Baden-Württemberg pilot high-temperature heat pumps for process applications.
China
Municipal building codes in Beijing, Shanghai, and Shenzhen enforce minimum seasonal performance factors for commercial construction. GB energy efficiency labeling creates compulsory replacement demand across tier-one cities. Compressor manufacturing concentrates in Guangdong and Zhejiang provinces for export hub scale.
Japan
METI Top Runner standards synchronize efficiency mandates with refrigerant chemistry requirements. Heat pump deployment accelerates in Tokyo and Osaka metro areas for building electrification alignment. Chubu region manufacturers engineer global platforms satisfying both Japanese and European regulatory thresholds.
India
The Bureau of Energy Efficiency's mandatory star rating expansion drives inverter technology penetration in residential cooling. Cooling action plan targets reshape procurement patterns in Delhi-Mumbai corridors. Tamil Nadu and Gujarat host assembly operations for cost-optimized equipment serving Southeast Asian export markets.
Global Energy Efficient HVAC Systems Market Vendor Landscape
Global majors compete with regional champions across refrigerant chemistry and control system integration. Market structure shows tiered consolidation with premium engineering specialists, scale-driven volume manufacturers, and building automation integrators occupying distinct competitive positions. Three archetypes dominate: captive compressor producers with refrigerant IP, deep chiller heritage players with service networks, and cost-optimized residential specialists with Southeast Asian manufacturing scale. Dominant competitive moves include strategic partnerships for smart building integration and geographic expansion through localized assembly operations.
Among Japanese industrial conglomerates, Daikin Industries and Mitsubishi Electric Corporation exemplify captive production archetypes with integrated compressor manufacturing and refrigerant technology positions. Carrier Global Corporation represents the deep engineering heritage tier with chiller-focused building automation integration. Midea Group anchors the scale-driven cost-optimization segment with volume manufacturing concentration across export hubs. These three players illustrate the competitive spectrum from premium technology capture to mass-market manufacturing efficiency.
| Leading Market Players |
|---|
| Daikin Industries |
| Carrier Global Corporation |
| Trane Technologies |
| Midea Group |
| Johnson Controls International |
| Mitsubishi Electric Corporation |
| Lennox International |
| Siemens AG |
| Schneider Electric |
| Others |
Supply Flow & Price Mechanics
Certified refrigerant technician concentrations in Texas and Bavaria create labor-cost differentials that widen pricing-tier spreads between premium factory-authorized service networks and independent contractor channels. These workforce asymmetries compound material cost premiums for low-GWP refrigerants, compressing margins on mid-tier equipment while sustaining pricing power at the premium installation tier.
Pricing Analysis
Warranty and service-bundling unbundling distinguishes pricing architectures across the market, with extended compressor coverage and predictive maintenance subscriptions separating premium manufacturer-direct channels from transactional equipment-only sales. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and geographic service density, with factory-authorized networks commanding spreads over independent channels. Pricing pressure stems from rare-earth magnet cost volatility and A2L refrigerant training requirements, squeezing mid-tier residential equipment. Commercial building operators show lowest price sensitivity where energy service company contracting wraps capital costs into performance guarantees, while residential replacement demand concentrates in cost-optimized segments.
Supply Chain Analysis
Warehouse-distribution layers operate through regional distribution centers in Houston, Rotterdam, and Singapore, feeding hub-and-spoke patterns that align with A2L refrigerant handling certification zones. Manufacturing concentrates in China, Japan, and the United States, with compressor production anchored in Guangdong and Zhejiang provinces. Rare-earth magnet motors draw from Chinese neodymium and dysprosium refining operations, copper tubing from Chilean and Peruvian smelters, and aluminum heat exchangers from domestic rolling mills. Single-source vulnerability in rare-earth processing exposes inverter compressor supply chains to export control volatility. Distribution runs through manufacturer-direct specification channels for large commercial projects and wholesale distribution for residential replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained through certified technician scarcity, with vocational program capacity bottlenecks propping pricing power for factory-authorized service networks.
For Market Incumbents: Lock in refrigerant IP positions and captive compressor manufacturing to defend against emerging low-cost inverter specialists from Southeast Asia. Prioritize backward integration into rare-earth magnet supply through offtake agreements with Australian and Canadian mining operations. Expand A2L certification training capacity in Texas and Bavaria to capture service revenue pools that independent contractors cannot access. For New Entrants and Emerging Players: Capture India's cooling action plan implementation window where mandatory star rating expansion forces fixed-speed-to-inverter conversion in Delhi-Mumbai corridors. Target industrial heat pump applications in Japan and South Korea where high-temperature process steam requirements exceed incumbent chiller heritage capabilities. Pursue ESCO partnership models that bundle equipment with performance guarantees, bypassing capital-constrained procurement committees. For Investors and Strategic Acquirers: Re-rating potential sits with refrigerant reclamation infrastructure specialists given EPA SNAP enforcement and EU F-Gas quota reductions accelerating service revenue capture. Long-term viability favors platforms with integrated building automation software layers where recurring data analytics revenue compounds equipment margins. Watch refrigerant patent cliff timing as the inflection indicator for margin compression in premium equipment tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Consolidation | Single global platforms satisfying METI Top Runner and EU F-Gas Regulation reduce R&D duplication. |
| ESCO Contracting Model Expansion | Performance guarantees for Veterans Affairs hospitals concentrate buyer power among balance-sheet-capable vendors. |
| A2L Certification Infrastructure Buildout | Houston and Dallas-Fort Worth training centers address technician scarcity constraining mid-tier residential deployment. |
| Industrial Heat Pump Pilot Programs | Food processing facilities in Bavaria validate high-temperature steam generation above 150°C. |
| Smart Building Automation Integration | BACnet and Mod interoperability investments unlock cloud-native retrofit opportunities in US commercial real estate. |
Methodological Framework
Multi-period observation of seasonal performance factor trajectories and refrigerant phase-down compliance timelines anchored the trend analysis, supplemented by interviews with HVAC engineering directors, facility managers at healthcare and data center verticals, refrigerant supply specialists, and building automation integrators. Secondary validation drew from EPA SNAP rulings, EU F-Gas Regulation quota filings, METI Top Runner standard disclosures, and GB energy efficiency labeling databases. Bottom-up equipment shipment tracking triangulated against top-down construction spend and building stock turnover models.
Input-output matrices mapped compressor manufacturing capacity, rare-earth magnet processing flows, and refrigerant chemistry transitions across product type, technology tier, end-user vertical, and application function segmentation dimensions. CAGRs were derived from regression-weighted trend extrapolation incorporating policy mandate enforcement schedules and equipment replacement cycle dynamics. Forecast inputs included municipal building code adoption timelines in Beijing, Shanghai, and Shenzhen, plus skilled technician training program graduation rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare-earth export control actions, refrigerant patent expiration sequencing, and carbon border adjustment mechanism implementation. Outputs reflect documented assumptions around regulatory enforcement intensity and supply chain resiliency investments. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Heat Pump (>100°C) Market
Cooling Systems
Air-Cooled Gas Coolers Market
Cooling Systems
Thawing System Market
Cooling Systems
Solar Air Conditioning Market
Cooling Systems
Global Condensing Unit Market
Cooling Systems
Fluid Coolers Market
Cooling Systems
Process Chillers Market
Cooling Systems
District Heating and Cooling Market
Cooling Systems
Solar Fan Market
Cooling Systems
Solar Ventilation Systems Market
Cooling Systems
Dry Cooler Market
Cooling Systems
Solar Cold Room Market
Cooling Systems
Industrial Water Cooling System Market
Cooling Systems
Solar Powered Cold Storage Market
Cooling Systems
Industrial Radiators Market
Cooling Systems
Global Magnetic Refrigeration Market