
 Global Cast Elastomers Market | 2026-2036
Global Cast Elastomers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cast Elastomers Market Foresight
Aftermarket service revenue for precision-molded elastomer components is reconfiguring margin distribution across the value chain. Lanxess AG leverages its backward integration into polyether polyol production to sustain cost advantages in high-performance grades. Mitsui Chemicals anchors its position through specialized catalyst technologies that differentiate its polyester polyurethane offerings in Asian industrial markets.
Cast elastomers are cross-linked polymer systems, typically polyurethane-based, formed through liquid casting processes where prepolymers react with curatives at controlled temperatures to achieve Shore hardness values from 60A to 75D. These materials deliver abrasion resistance, load-bearing capacity, and elastic recovery for demanding mechanical applications. Polyether polyurethane dominates in wet-environment seals and gaskets due to superior hydrolytic stability, while polyester polyurethane leads industrial roller applications where tensile strength and oil resistance command premium positioning. Thermoplastic polyurethane variants are gaining share in consumer electronics manufacturing where insert-molding compatibility accelerates processing cycles.
EPA oversight of volatile organic compound emissions shapes casting facility permitting and solvent-based system migration across United States production sites. REACH substance restrictions and CE marking requirements under EU MDR govern medical-grade elastomer qualification pathways in European markets. China's GB standards and MIIT industrial policy directives influence domestic formulation approvals and export certification timelines. Stakeholders must monitor regulatory divergence between jurisdictions to align product registration investments with regional demand trajectories.
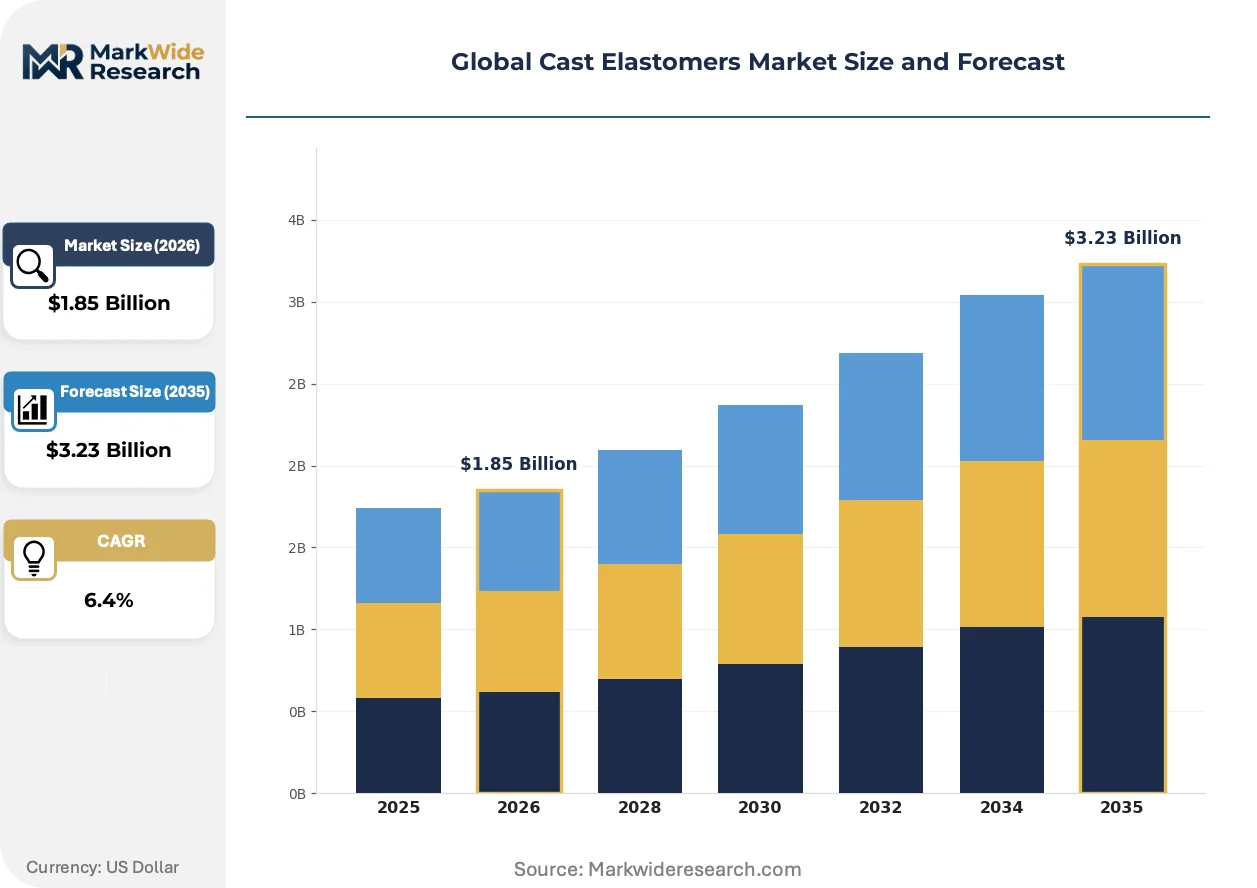
Market Dynamics
REACH substance restrictions and EPA volatile organic compound oversight are compressing formulation flexibility while simultaneously creating premium positioning for compliant grades across automotive and medical supply chains.
Growth Catalysts
- Transportation electrification:Battery module sealing and thermal management systems require cast polyurethane gaskets with dielectric stability. OEM procurement volumes in Germany and China are scaling dedicated production lines.
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon blowing agents is accelerating water-blown polyurethane system adoption in European insulation and seal applications.
- Industrial roller refurbishment:Mining and pulp processing operations in the United States are extending equipment life through precision-recast polyurethane coatings rather than metal replacement.
Market Restraints
- Polyether polyol feedstock volatility:Propylene oxide supply concentration in Gulf Coast petrochemical corridors exposes formulators to hurricane-related production interruptions and price spikes.
- Isocyanate handling infrastructure:Toluene diisocyanate and methylene diphenyl diisocyanate require specialized storage and ventilation systems that constrain new entrant facility siting.
- Thermoplastic polyurethane substitution:Injection-moldable TPU variants are capturing consumer electronics and wearable device applications previously served by cast systems.
Strategic Opportunities
- India industrial machinery buildout:PLI scheme incentives for textile and food processing equipment are generating first-time demand for abrasion-resistant rollers in Gujarat and Tamil Nadu manufacturing clusters.
- Medical device convergence:Combination products integrating drug-eluting cast elastomer coatings are opening qualification pathways under FDA 21 CFR Part 4 and EU MDR Article 117.
- Closed-loop recycling systems:Chemical depolymerization of post-industrial polyurethane scrap is enabling circular material flows for automotive seal manufacturers seeking Scope 3 emissions reductions.
Industry Challenges
- Formulation chemist scarcity:Expertise in prepolymer design and curative ratio optimization is concentrating among retiring specialists at legacy polyurethane houses.
- Multi-jurisdiction registration:Separate REACH dossiers, EPA TSCA section 5 notifications, and China NMPA medical device master file submissions extend product launch timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cast Elastomers Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic Polyurethane, Polyether Polyurethane, Polyester Polyurethane, Polybutadiene Rubber Application: Seals & Gaskets, Automotive Components, Industrial Rollers, Electrical Insulation End User Industry: Transportation OEMs, Consumer Electronics Manufacturers, Machinery Suppliers, Infrastructure Developers Technology: Casting, Reaction Injection Molding, Compression Molding, Transfer Molding |
| Companies Covered | Lanxess AG, Mitsui Chemicals Inc., BASF SE, Era Polymers Pty Ltd., Tosoh Corporation, Covestro AG, Dow Chemical Company, Wanhua Chemical Group Co. Ltd., Huntsman International LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cast Elastomers Market Shifts & Advancements
Digital manufacturing integration and bio-based feedstock substitution are restructuring competitive differentiation beyond traditional hardness and abrasion metrics toward traceability and carbon intensity credentials.
One-component moisture-cure polyurethane systems are simplifying field application for infrastructure sealing and conveyor belt repair. Mining maintenance crews and municipal water treatment operators are adopting cartridge-dispensed formulations that eliminate on-site mixing ratios. Cast two-part systems with pot-life constraints are rendering obsolete for remote-site installations where temperature control and waste minimization dominate procurement criteria.
EPA New Source Performance Standards for polyurethane foam fabrication are tightening permissible methylene chloride and n-methyl-2-pyrrolidone emissions at United States casting facilities. Plant operators are retrofitting enclosed pouring stations and thermal oxidizers to maintain operating permits. Small-batch custom molders without capital access are consolidating or exiting rather than absorbing compliance retrofit costs.
Original equipment manufacturers are unbundling aftermarket elastomer component replacement from bundled service contracts. Wind turbine blade leading edge protection and agricultural harvester reel fingers are migrating to direct-to-fleet parts procurement through specialized distributors. Component price transparency is compressing margins for integrated original equipment service networks while expanding addressable market for independent precision molders in Denmark and Brazil.
Global Cast Elastomers Market Segmentation
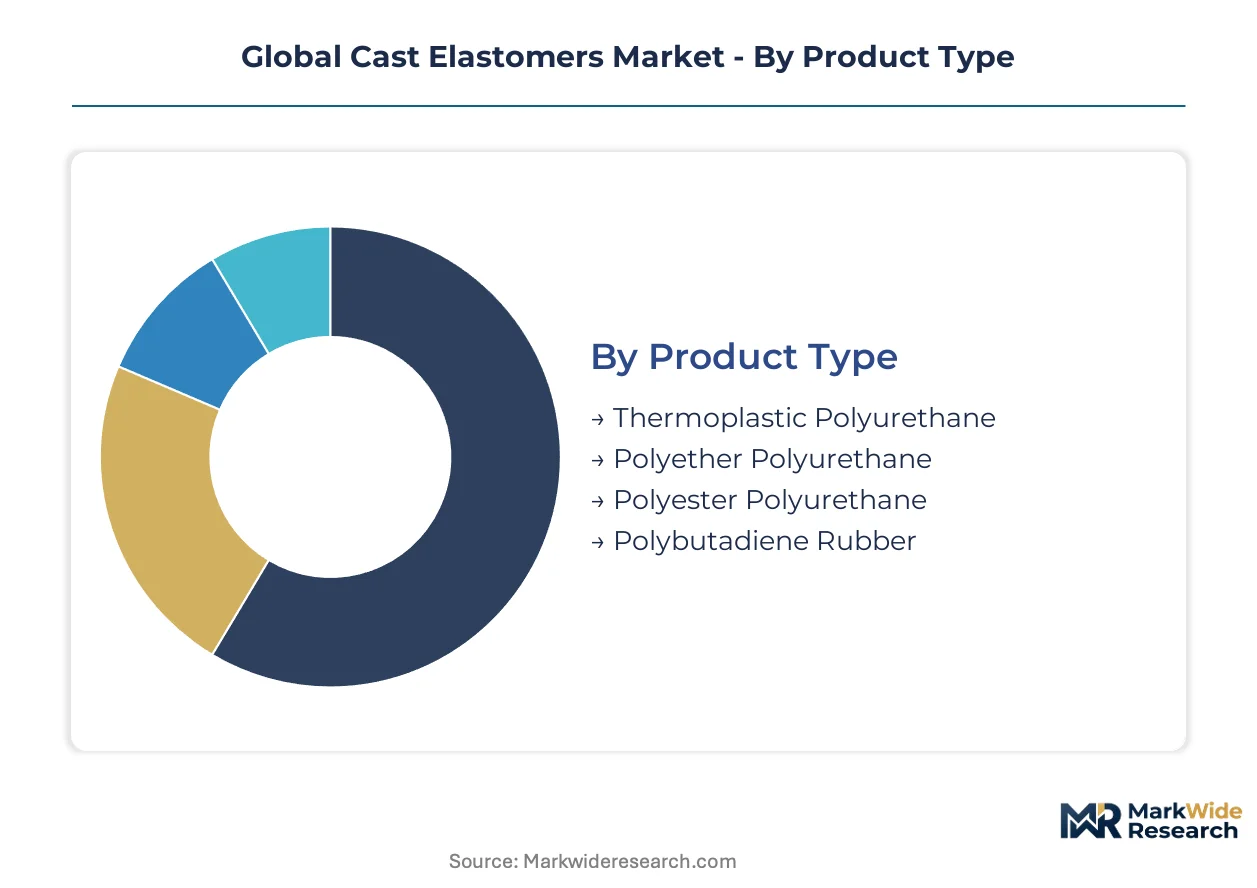
Cast elastomer procurement decisions pivot on Shore hardness specifications, hydrolytic stability requirements, and processing cycle constraints that vary sharply across transportation, electronics, and industrial end-uses. Segmentation clarity enables suppliers to align formulation investments with the diverging performance premiums each vertical commands.
Product Type:
Material selection traces directly to environmental exposure severity and load-bearing duty cycles across target applications.
- Polyether Polyurethane:Formulated from long-chain polyols with ether linkages, this chemistry resists hydrolytic degradation in prolonged water immersion. Demand concentrates in municipal water treatment seals and marine infrastructure gaskets where German OEMs specify Shore 70A-90A grades for 10-year service life guarantees.
- Polyester Polyurethane:Ester backbone structures deliver superior tensile strength and oil resistance for dynamic mechanical loads. Mining conveyor rollers and pulp processing equipment in the United States specify these grades for abrasion resistance exceeding 50 mm³ loss per DIN 53516 standards.
- Thermoplastic Polyurethane:Linear polymers enable injection molding compatibility with 30-40% faster cycle times than cast systems. Consumer electronics manufacturers in China specify TPU for wearable device housings requiring insert-molding with polycarbonate substrates.
- Polybutadiene Rubber:Hydrogenated grades provide low-temperature flexibility to -50°C for Arctic pipeline seals and cryogenic handling equipment. Specialized compounding with peroxide curatives serves niche oilfield applications.
Established volume favors polyester polyurethane; emerging adoption favors thermoplastic polyurethane.
Application:
Component geometry and failure-mode tolerance dictate whether open-cast pouring or precision-molded systems capture procurement specifications.
- Industrial Rollers:Precision-ground polyurethane coatings from 6mm to 50mm thickness recover metal core substrates in printing, textile, and materials handling equipment. Refurbishment demand from United States mining operations extends original equipment life cycles by 3-5x versus steel replacement.
- Seals & Gaskets:Dielectric-stable formulations serve battery module thermal management in electric vehicle platforms. Chinese and German OEM procurement volumes are scaling dedicated production lines for 800V architecture compatibility.
- Automotive Components:Bushings, bumpers, and suspension elements require dynamic fatigue resistance across -40°C to 120°C operating windows. REACH substance restrictions are compressing plasticizer options for European supply chains.
- Electrical Insulation:Cast polyurethane encapsulates transformers and cable joints with volume resistivity exceeding 10¹⁴ ohm-cm. Medium-voltage infrastructure buildout in India drives specification of flame-retardant grades meeting BIS IS 5831 standards.
Industrial rollers command the steepest expansion trajectory; electrical insulation offers margin stability through qualification barriers.
End User Industry:
Procurement sophistication ranges from commodity spot purchasing to collaborative formulation development with exclusive supply agreements.
- Transportation OEMs:Tier-1 suppliers specify custom prepolymers with 18-24 month qualification timelines for chassis and powertrain sealing systems. German and Chinese automotive clusters sustain the highest procurement volumes for high-durability grades.
- Machinery Suppliers:Abrasion-resistant roller coatings for mining, agriculture, and food processing equipment generate recurring refurbishment revenue. Gujarat and Tamil Nadu manufacturing clusters under India's PLI scheme are generating first-time demand for precision-cast components.
- Consumer Electronics Manufacturers:Miniaturization trends favor thermoplastic polyurethane over cast systems for wearable device integration. Insert-molding compatibility accelerates processing cycles but sacrifices the load-bearing capacity of cross-linked alternatives.
- Infrastructure Developers:Water treatment seals, pipeline gaskets, and bridge bearing pads specify 25-50 year service life ratings. Municipal procurement in Brazil and Denmark favors localized production to minimize logistics exposure.
Transportation OEMs anchor volume concentration; machinery suppliers offer the fastest-growing replacement parts revenue.
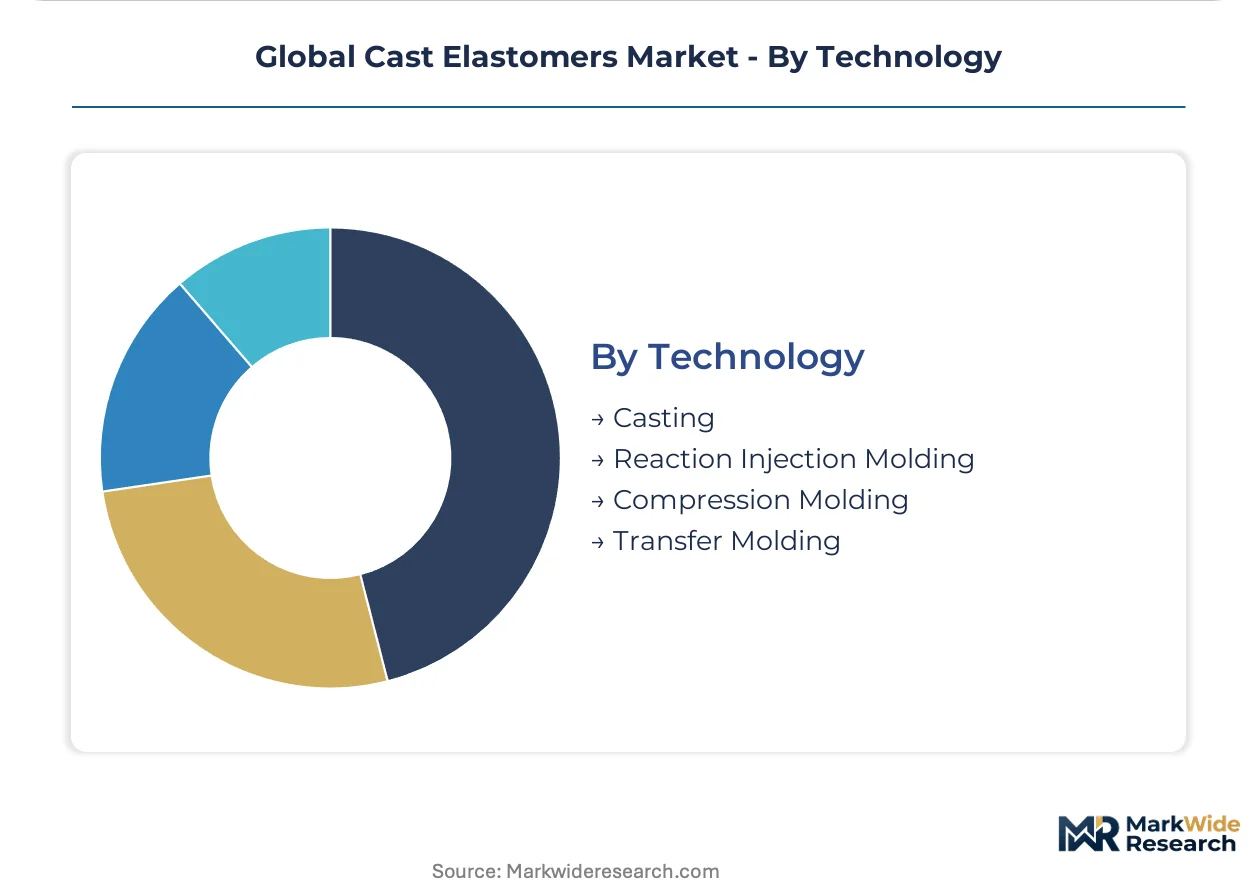
Technology:
Capital intensity and batch size flexibility determine process selection across custom molders and high-volume manufacturers.
- Casting:Open or centrifugal pouring of liquid prepolymer-curative mixtures serves prototype through production volumes with minimal tooling investment. Small-batch custom molders in Denmark and Brazil specialize in 1-100 unit runs for wind turbine blade protection systems.
- Reaction Injection Molding:High-pressure impingement mixing enables complex geometries with 2-5 minute demold times. Automotive interior trim and steering wheel applications in Germany favor this process for surface finish consistency.
- Compression Molding:Preformed blanks cure under heat and pressure for thick-section components requiring uniform cross-link density. Heavy-duty mining rollers and railroad suspension elements specify this method for void-free structures.
- Transfer Molding:Closed systems inject metered compound into heated cavities for precision tolerances in medical device components. FDA 21 CFR Part 4 and EU MDR Article 117 qualification pathways favor this contamination-controlled approach.
Casting retains broadest application coverage; reaction injection molding gains share in automotive volume production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and China demonstrate the lowest price elasticity for high-performance grades, while procurement in Brazil and India remains acutely sensitive to landed cost fluctuations. This divergence shapes regional formulation strategies and local production investments.
Germany
Transportation OEMs in Stuttgart and Munich sustain premium-grade consumption for electric vehicle battery sealing systems. REACH substance restrictions and EU F-Gas Regulation compliance requirements tighten material specifications for automotive supply chains. The Baden-Württemberg industrial corridor hosts specialized prepolymer blending facilities serving Tier-1 suppliers with 18-24 month qualification timelines.
China
Consumer electronics manufacturers in Shenzhen and Dongguan drive thermoplastic polyurethane adoption for wearable device housings. MIIT industrial policy directives and GB standards influence domestic formulation approvals and export certification timelines. The Yangtze River Delta concentrates casting operations for industrial rollers serving textile and food processing equipment buildouts under PLI-equivalent provincial incentives.
United States
Mining operations in Arizona and Nevada generate recurring demand for precision-recast polyurethane roller coatings. EPA New Source Performance Standards and volatile organic compound oversight constrain casting facility permitting and solvent-based system migration. The Gulf Coast petrochemical corridor exposes formulators to hurricane-related propylene oxide supply interruptions.
India
Textile and food processing machinery buildouts in Gujarat and Tamil Nadu create first-time demand for abrasion-resistant cast components. PLI scheme incentives for industrial equipment manufacturing accelerate procurement from domestic precision molders. Mumbai-Pune manufacturing clusters develop localized supply relationships to minimize logistics exposure for infrastructure seal applications.
Global Cast Elastomers Market Competitive Landscape
Capability concentration sits with specialized prepolymer designers; scale advantage sits with diversified chemical conglomerates with captive isocyanate supply. The market structures around three tiers: legacy polyurethane houses with retiring formulation expertise, integrated petrochemical players with backward control over polyol feedstocks, and regional custom molders serving aftermarket refurbishment demand. Dominant competitive moves include selective capacity expansion in low-cost manufacturing zones and technology licensing agreements to access specialized catalyst systems.
Within the integrated chemical conglomerate tier, BASF SE and Covestro AG exemplify scale-driven positioning through captive supply chain control over methylene diphenyl diisocyanate and polyether polyol production. Lanxess AG occupies a distinctive position through its backward integration into polyether polyol manufacturing, while Mitsui Chemicals anchors the specialized catalyst technology segment for polyester polyurethane differentiation in Asian industrial markets. Huntsman International LLC and Dow Chemical Company represent North American-based competitors with broad materials portfolios spanning cast and thermoplastic elastomer chemistries.
| Leading Market Players |
|---|
| Lanxess AG |
| Mitsui Chemicals Inc. |
| BASF SE |
| Era Polymers Pty Ltd. |
| Tosoh Corporation |
| Covestro AG |
| Dow Chemical Company |
| Wanhua Chemical Group Co. Ltd. |
| Huntsman International LLC |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese polyester polyol production is compressing spot-market pricing for standard-grade formulations while tightening margins for European producers with fixed-cost structures. This utilization asymmetry rewards integrated suppliers with captive feedstock supply and pressures custom molders toward long-term offtake contracts.
Pricing Analysis
Long-term offtake agreements dominate procurement for transportation OEMs, insulating Tier-1 suppliers from propylene oxide price volatility while spot purchasing prevails among aftermarket refurbishment operators. Three-tier pricing structure across REACH-compliant premium grades, standard industrial formulations, and economy-tier spot material separates qualification-intensive automotive seals from commodity roller coatings. Cost compression in standard polyester grades is intensifying because of Chinese capacity additions. Mining maintenance contractors in the United States exhibit the highest price sensitivity, while German battery module manufacturers accept premium positioning for dielectric-stable polyether systems.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for formulators serving dual-continent OEM footprints. Isocyanate production concentrates in Germany, China, and the United States, while polyether polyol supply draws from Gulf Coast petrochemical corridors and Asian propylene oxide complexes. Raw material dependencies rest on toluene diisocyanate, methylene diphenyl diisocyanate, and specialized curative packages. Single-source vulnerability in hurricane-prone Texas and Louisiana production zones threatens just-in-time delivery commitments. Distribution runs through regional blending facilities serving localized molding operations in Denmark, Brazil, and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cast elastomers market sustains defensive moats through regulatory entrenchment—REACH dossiers and FDA master files create 18-24 month switching costs that protect qualified supplier relationships.
For Market Incumbents: Pre-empt thermoplastic polyurethane substitution by accelerating water-blown system certification under EU F-Gas Regulation timelines. Capture stranded capacity from small-batch molders exiting under EPA New Source Performance Standards compliance costs. Backward integration into polyether polyol production secures margin control against propylene oxide volatility. For New Entrants and Emerging Players: Build out abrasion-resistant roller refurbishment capabilities in Gujarat and Tamil Nadu manufacturing clusters where India's PLI scheme generates first-time demand without entrenched supplier relationships. Target aftermarket service contracts for wind turbine blade protection systems in Denmark and Brazil. Lead with one-component moisture-cure polyurethane systems that eliminate field mixing complexity for mining maintenance crews. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across medical-grade cast elastomer production as FDA 21 CFR Part 4 and EU MDR Article 117 qualification pathways lengthen. Five-to-ten year viability favors specialized prepolymer designers with retiring formulation expertise and captive catalyst technology. The signal to watch is chemical depolymerization scale-up for circular material flows in automotive seal applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyether Polyol | Lanxess AG sustains cost advantages in high-performance grades through captive supply. |
| Specialized Catalyst Technology Licensing | Mitsui Chemicals differentiates polyester polyurethane offerings in Asian industrial markets. |
| Water-Blown System Certification | EU F-Gas Regulation compliance creates premium positioning for European automotive supply chains. |
| Chemical Depolymerization Scale-Up | Closed-loop recycling enables Scope 3 emissions reductions for automotive seal manufacturers. |
| Medical-Grade Qualification Pathway Investment | FDA 21 CFR Part 4 and EU MDR Article 117 govern combination product integration opportunities. |
Research Methodology
Desk research of customs trade data, chemical industry association reports, and regulatory filing databases preceded structured interviews with polyurethane plant managers, Tier-1 automotive procurement leads, distribution channel partners, and technical R&D directors. Primary fieldwork combined with secondary validation from SEC 10-K disclosures and ECHA REACH dossiers enabled bottom-up volume estimation and top-down market sizing triangulation.
Fixed assumptions across the projection horizon held battery electric vehicle penetration rates and EU F-Gas Regulation phase-down schedules constant while varying propylene oxide supply disruption scenarios and thermoplastic polyurethane substitution elasticities. Segmentation dimensions modeled include material chemistry tier, end-use application, Shore hardness specification, and regional production hub clustering. CAGRs were derived from elasticity-adjusted volume projections and value-per-unit trends across the analysis window.
Stress conditions across propylene oxide price spikes, hurricane-related production interruptions, and thermoplastic polyurethane capture rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and OEM qualification cycle stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Hydroxyl Terminated Polybutadiene Market
Rubber
Rubber Bulbs Market
Rubber
Reclaimed Rubber Market
Rubber
Chloroprene Rubber Modified Asphalt Emulsion Market
Rubber
Recycled Elastomers Market
Rubber
Nitrile Butadiene Rubber (NBR) Powder Market
Rubber
Butyl Reclaimed Rubber Market
Rubber
Isoprene Rubber (IR) Latex Market
Rubber
Global Styrene Butadiene Styrene Market
Rubber
Neoprene Rubber Market
Rubber
Global Automotive Elastomers Market
Rubber
Rubber Seal Plugs Market
Rubber
Nitrile Elastomers Market
Rubber
Rubber Choppers Market
Rubber
Global Elastomers Market
Rubber
Tire Chemicals Market