
 Coin Cell Lithium Batteries Market | 2026-2036
Coin Cell Lithium Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Coin Cell Lithium Batteries Market Insights
Medical device demand is consolidating as the dominant end-use vertical for coin cell lithium batteries, displacing traditional consumer electronics volumes. VARTA AG specializes in high-reliability cells for hearing aid OEMs across European markets. Energizer Holdings, Inc. leverages its retail channel control to maintain shelf presence in North American pharmacies and electronics stores. Renata AG SA, a Swatch Group subsidiary, dominates watch movement power supply with vertically integrated Swiss manufacturing.
Coin cell lithium batteries are compact electrochemical power sources, typically 5-25 mm in diameter and 1-6 mm thick, using lithium metal or lithium-ion chemistry with energy densities of 200-400 Wh/kg to deliver stable voltage in constrained spaces. Their primary purpose is powering miniaturized electronics where form factor and shelf life outweigh energy capacity needs. Primary batteries still occupy the largest volume share across watches and remote controls, though rechargeable batteries are capturing margin pools in fitness devices and medical wearables requiring cycle durability. Specialty batteries command premium pricing in automotive key fobs and industrial sensors where temperature extremes demand customized electrolyte formulations.
REACH in Europe restricts hazardous substances in battery chemistries, while the EU Battery Regulation mandates carbon footprint declarations and recycled content thresholds that reshape supplier qualification criteria. Japan's METI enforces collection and recycling targets through the Act on Promotion of Recycling of Small Waste Electrical and Electronic Equipment. The FDA in the United States classifies implantable coin cells as critical components in Class III medical devices, requiring biocompatibility and failure-rate documentation. Stakeholders must monitor how China's GB standards and evolving solid-state prototypes alter chemistry roadmaps and manufacturing equipment investments.
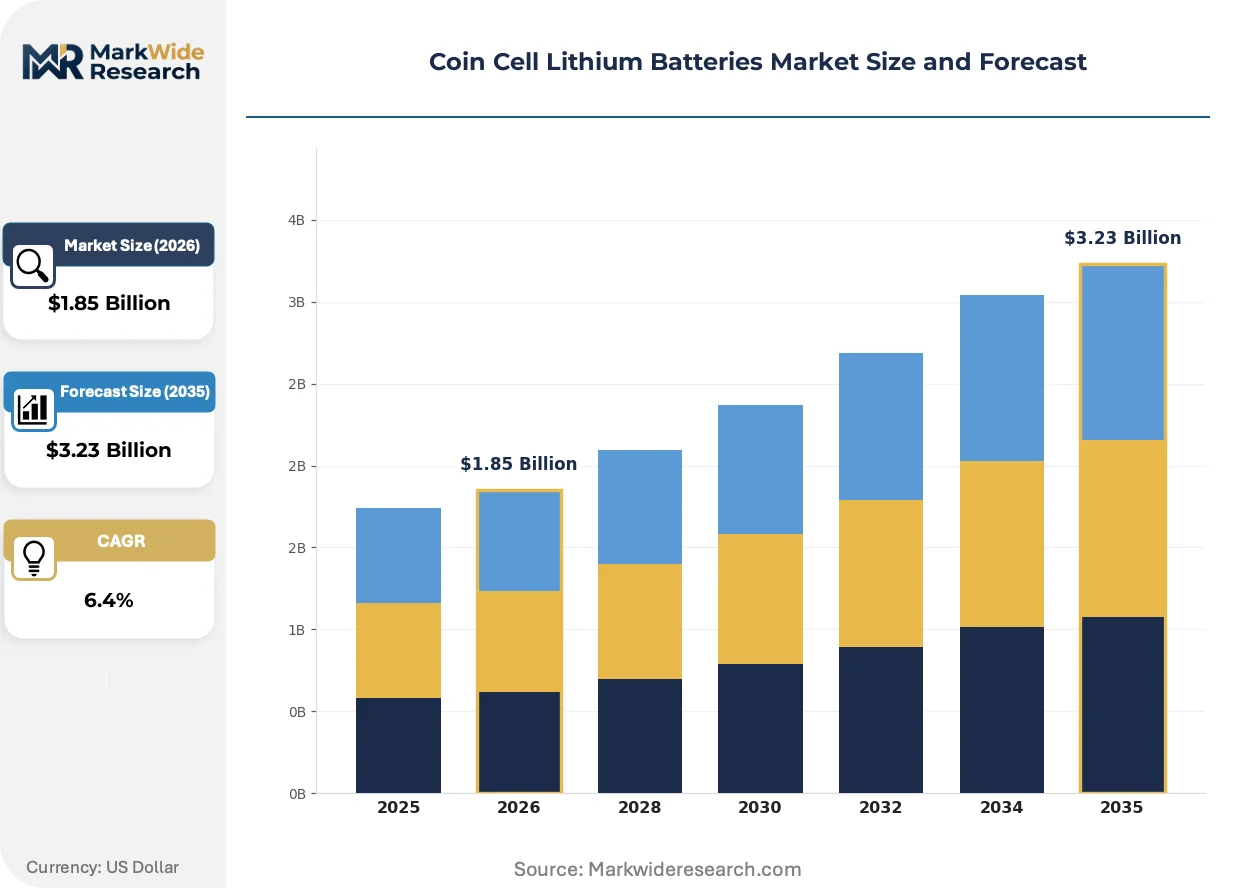
Market Dynamics
The coin cell lithium batteries market is being fundamentally restructured by medical device manufacturers' procurement consolidation, as hearing aid and cardiac monitor OEMs shift from disposable to rechargeable cell contracts that demand 500-plus cycle durability and biocompatibility certification.
Growth Catalysts
- EU Battery Regulation:Carbon footprint declarations and recycled content thresholds are forcing chemistry standardization that favors established suppliers with traceable supply chains.
- Hearing aid OEM procurement:European manufacturers are expanding rechargeable coin cell contracts to eliminate patient battery replacement burdens and reduce total cost of ownership.
- Solid-state electrolyte development:Laboratory breakthroughs in ceramic-polymer composites are approaching commercial viability for implantable applications requiring zero leakage risk.
Market Restraints
- Lithium metal price volatility:Raw material cost swings from South American brine operations compress margin predictability for primary cell producers.
- Supply concentration in East Asia:Separator membrane and electrolyte solvent production clusters in China and South Korea create single-source vulnerability for European and North American packagers.
- Energy density ceiling:Lithium-manganese dioxide chemistry approaches theoretical limits around 280 Wh/kg, constraining runtime extension for power-hungry wearables.
Strategic Opportunities
- India's medical device PLI scheme:Local manufacturing incentives for hearing aids and diagnostic equipment create demand for qualified coin cell suppliers establishing domestic assembly.
- Automotive key fob rechargeable conversion:Premium vehicle platforms are integrating wireless charging pads that enable elimination of primary cell replacement cycles.
- Industrial sensor networks:LoRaWAN and NB-IoT deployment in German manufacturing clusters is generating demand for wide-temperature-range cells with decade-long service life.
Industry Challenges
- Electrolyte formulation expertise gap:The specialized chemistry knowledge required for low-temperature performance cells is concentrated among retiring specialists in Japanese and German research centers.
- Cleanroom capex requirements:Medical-grade cell assembly demands ISO 14644 Class 7 facilities that require eight-figure capital commitments for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coin Cell Lithium Batteries Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primary Batteries, Rechargeable Batteries, Specialty Batteries, Lithium Iron Phosphate End User: Consumer Electronics, Medical Devices, Automotive, Industrial Equipment Application: Watches, Hearing Aids, Remote Controls, Fitness Devices Distribution Channel: Online Retail, Offline Retail, Distributors, OEMs |
| Companies Covered | Eveready Battery Company, Inc., Seiko, VARTA AG, EM Microelectronic, Camelion Batteries GmbH, Duracell Inc., Renata AG SA, Zeus Battery Products, Energizer Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coin Cell Lithium Batteries Market Trends and Innovations
Solid-state prototypes and chemistry roadmaps are compressing development timelines while regulatory carbon accounting is rewiring supplier qualification. These forces are converging to privilege vertically integrated manufacturers with captive material traceability.
Solid-state lithium-metal cells with sulfide-glass electrolytes are decentralizing the traditional separator-electrolyte supply structure. Medical implant manufacturers in Switzerland and Germany are piloting these cells for next-generation cardiac monitors. The technology is decentralizing procurement authority from commodity chemical suppliers toward integrated device manufacturers controlling cell architecture.
Japan's METI recycling mandates under the Act on Promotion of Recycling of Small Waste Electrical and Electronic Equipment are tightening collection targets for coin cells below five grams. Manufacturers must now fund reverse logistics networks or face market access restrictions. The hearing aid sector is responding by designing battery compartments for automated disassembly.
Hospital procurement departments are consolidating hearing aid battery purchasing through group purchasing organizations that negotiate multi-year sole-source contracts. Traditional pharmacy and retail electronics channels are losing volume in Germany and France. This consolidation is most visible in public healthcare systems where standardization reduces clinical variation costs.
Coin Cell Lithium Batteries Market Segmentation
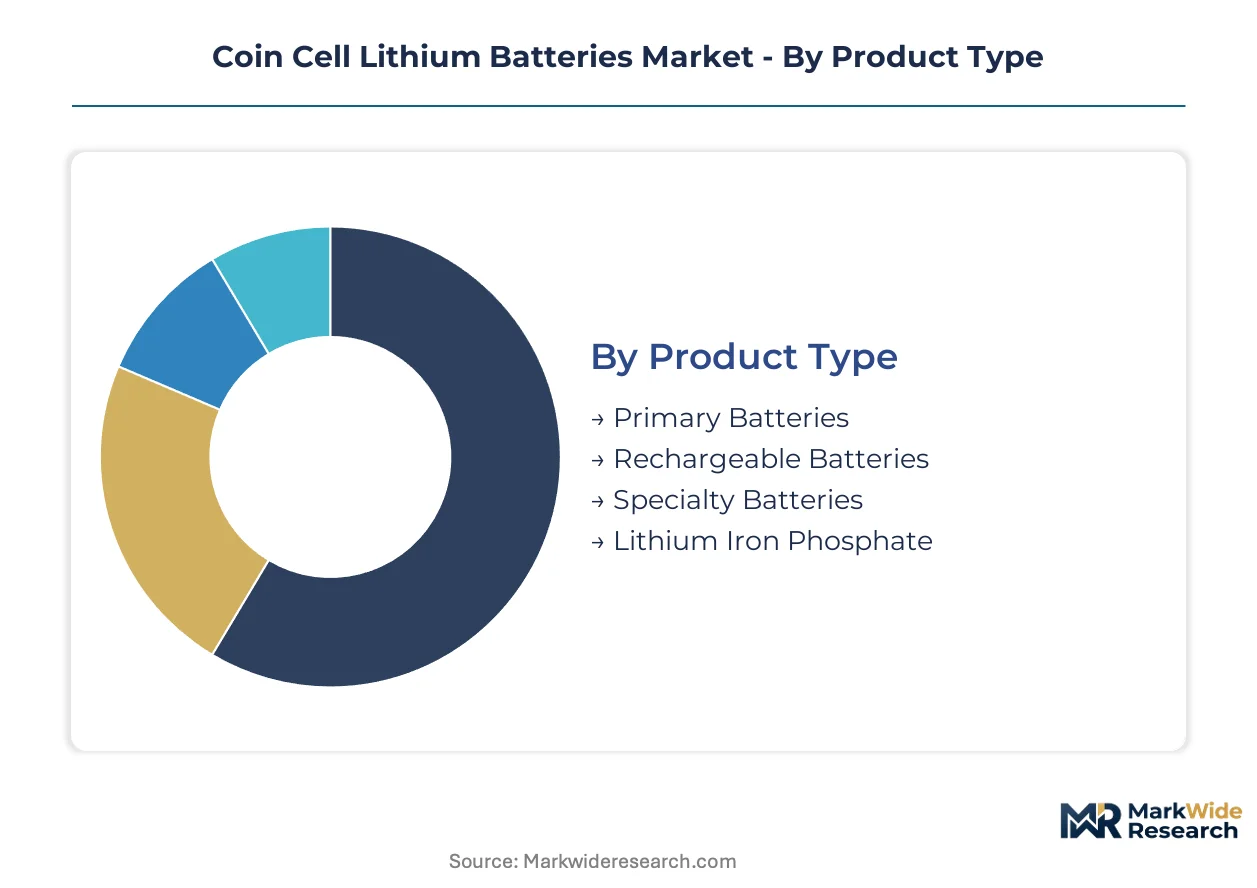
Coin cell lithium batteries serve radically different performance requirements across medical implants, consumer wearables, and industrial sensors. Supply chain configuration varies dramatically by segment—primary cells flow through retail pharmacy networks while rechargeable variants demand direct OEM partnerships with biocompatibility documentation.
Product Type:
Supply concentration in East Asian electrolyte and separator manufacturing creates divergent procurement risks across chemistry formats, with rechargeable variants facing tighter bottleneck exposure than mature primary cell supply chains.
- Primary Batteries:Lithium-manganese dioxide chemistry dominates with 280 Wh/kg energy density and decade-long shelf stability. Demand concentrates in German and Swiss watch manufacturing clusters where Renata AG and VARTA AG maintain captive supply relationships with movement assemblers.
- Rechargeable Batteries:Lithium-ion coin formats with 500-plus cycle durability are displacing primary cells in hearing aids. Procurement is consolidating through European hospital group purchasing organizations that negotiate multi-year sole-source contracts with biocompatibility certification requirements.
- Specialty Batteries:Custom electrolyte formulations for automotive key fobs and industrial sensors command premium pricing through direct OEM channels.
- Lithium Iron Phosphate:Thermal stability chemistry serves niche industrial sensor applications requiring wide temperature operation.
Today's leader: Primary Batteries. Tomorrow's challenger: Rechargeable Batteries.
End User:
Cost tier stratification separates medical device procurement—with its ISO 14644 cleanroom requirements and FDA Class III documentation—from price-sensitive consumer electronics volume.
- Medical Devices:Implantable cardiac monitors and hearing aids demand zero-leakage solid-state prototypes. Swiss and German manufacturers pilot sulfide-glass electrolyte cells with decentralized procurement authority shifting toward integrated device manufacturers.
- Consumer Electronics:Fitness devices and wearables drive rechargeable adoption with cycle durability requirements. Volume concentrates in Chinese and South Korean precision electronics manufacturing clusters serving global brand OEMs.
- Automotive:Premium vehicle key fobs are integrating wireless charging pads that enable primary cell elimination.
- Industrial Equipment:LoRaWAN and NB-IoT sensor networks in German manufacturing clusters demand decade-long service life with wide temperature range performance.
Medical Devices capture the steepest expansion trajectory as hearing aid OEMs eliminate patient battery replacement burdens.
Application:
Volume distribution reflects divergent replacement cycle economics—disposable formats in remote controls versus rechargeable contracts in clinical settings.
- Watches:Swiss movement manufacturers source through vertically integrated supply chains with Swatch Group subsidiary Renata AG dominating power supply integration.
- Hearing Aids:Rechargeable conversion is accelerating as European public healthcare systems standardize procurement through group purchasing organizations, displacing traditional pharmacy channels in Germany and France.
- Remote Controls:Primary cell replacement cycles sustain retail pharmacy and electronics store volume, particularly in North American markets where Energizer Holdings maintains shelf presence dominance.
- Fitness Devices:Cycle durability requirements favor rechargeable formats with direct OEM supply relationships.
Hearing Aids are gaining share fastest as clinical procurement consolidation restructures distribution economics.
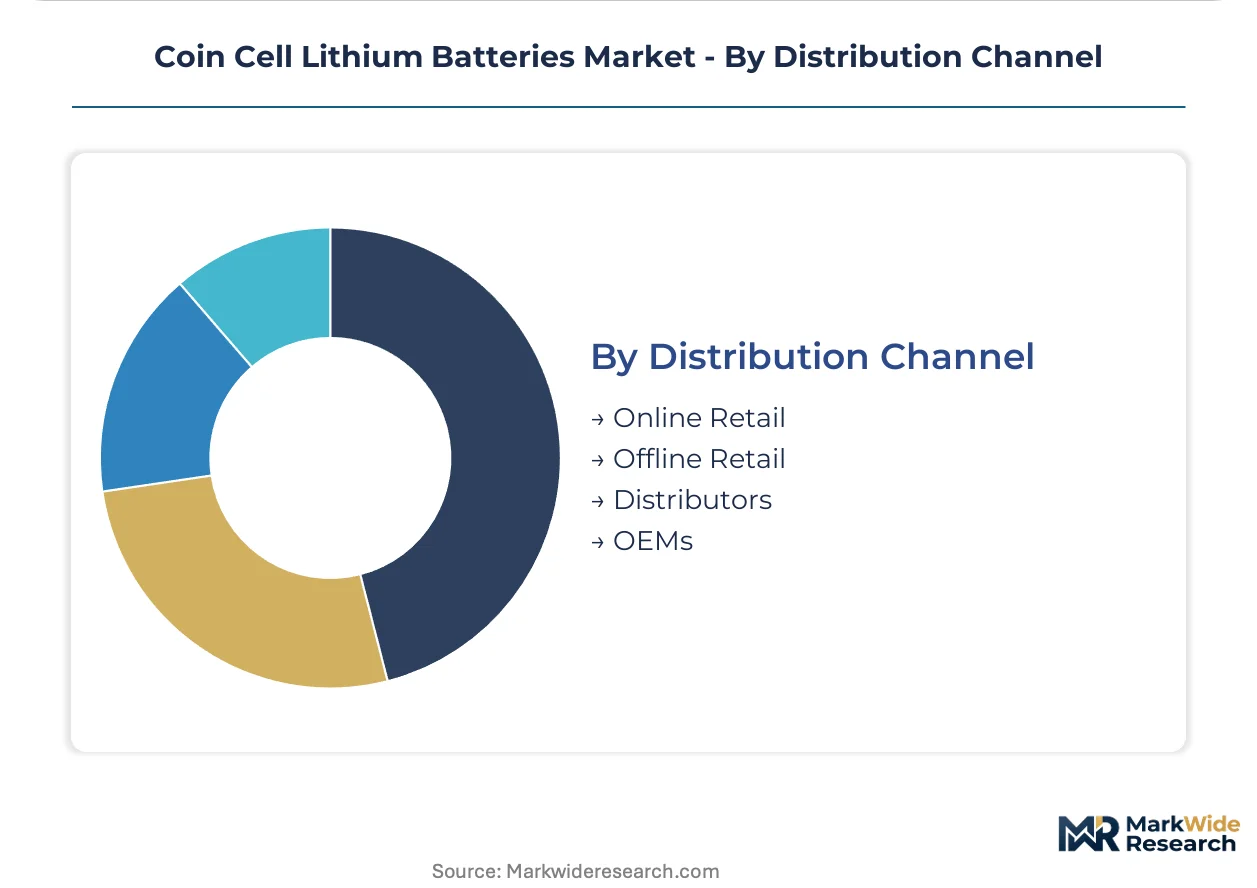
Distribution Channel:
Customer type separation is sharpening—hospital procurement departments bypass retail entirely while consumer segments fragment across digital and physical touchpoints.
- OEMs:Direct supply relationships dominate medical device and automotive segments with long-term contracts requiring carbon footprint declarations under EU Battery Regulation compliance.
- Distributors:Industrial sensor networks and specialty battery applications flow through technical distributors with formulation expertise concentrated among retiring specialists in Japanese and German research centers.
- Online Retail:Consumer electronics and replacement battery volume shifts toward e-commerce platforms with price transparency pressures.
- Offline Retail:Pharmacy and electronics store channels retain primary cell volume for watches and remote controls, though losing share to consolidated healthcare procurement in European markets.
OEMs anchor current revenue concentration. Distributors face capability scarcity as electrolyte formulation expertise concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating assembly operations to jurisdictions with lighter carbon-accounting burdens while maintaining material sourcing from established East Asian clusters. This regulatory arbitrage reshapes investment flows without disrupting upstream chemical supply chains.
China
Precision electronics manufacturing in Shenzhen and Dongguan drives rechargeable coin cell demand for fitness device OEMs. GB standards under SAMR oversight mandate safety testing protocols that exceed legacy IEC requirements. The Yangtze River Delta concentration of separator membrane production creates bottleneck exposure for European packagers dependent on Chinese supply.
Germany
Hearing aid manufacturers in Berlin and Munich are consolidating procurement through hospital group purchasing organizations. The EU Battery Regulation's carbon footprint declarations force chemistry standardization that favors established suppliers with traceable supply chains. The Baden-Württemberg industrial cluster hosts VARTA AG's high-reliability cell production for medical device OEMs.
United States
FDA Class III documentation requirements for implantable coin cells create qualification barriers that privilege incumbent suppliers. Retail pharmacy and electronics store channels sustain primary cell volume, particularly in markets where Energizer Holdings maintains shelf presence dominance. The Boston medical device corridor pilots solid-state prototypes for next-generation cardiac monitors.
Japan
METI recycling mandates under the Act on Promotion of Recycling of Small Waste Electrical and Electronic Equipment tighten collection targets for coin cells below five grams. Osaka-based research centers retain concentrated expertise in low-temperature electrolyte formulations. The Nagoya precision manufacturing belt supplies ceramic-polymer composite materials for solid-state development programs.
Switzerland
Swatch Group subsidiary Renata AG dominates watch movement power supply through vertically integrated Swiss manufacturing. Swissmedic oversight of implantable devices drives biocompatibility certification requirements that filter supplier pools. The Jura arc watchmaking cluster maintains captive supply relationships with movement assemblers demanding decade-long shelf stability.
Coin Cell Lithium Batteries Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers scale ISO 14644 Class 7 cleanroom facilities to capture medical device contracts. The vendor base stratifies into three tiers: vertically integrated European specialists, East Asian scale producers, and North American retail channel operators. Two strategic archetypes have emerged: chemistry innovators pursuing solid-state electrolyte breakthroughs, and logistics integrators building reverse collection networks for recycling compliance. M&A activity concentrates on electrolyte formulation expertise, while strategic partnerships lock in separator membrane supply.
Among European specialists, VARTA AG exemplifies the high-reliability archetype serving hearing aid OEMs, while Renata AG SA anchors the vertically integrated tier through Swatch Group ownership. Energizer Holdings, Inc. occupies the retail channel control position in North American markets. These three entities represent distinct competitive vectors: direct OEM partnerships with biocompatibility documentation, captive manufacturing integration, and pharmacy shelf presence dominance.
| Leading Market Players |
|---|
| Eveready Battery Company, Inc. |
| Seiko |
| VARTA AG |
| EM Microelectronic |
| Camelion Batteries GmbH |
| Duracell Inc. |
| Renata AG SA |
| Zeus Battery Products |
| Energizer Holdings, Inc. |
| Others |
Pricing and Supply Chain Analysis
Captive separator membrane production in Chinese and South Korean chemical clusters anchors both cost structures and procurement leverage for European and North American packagers. This upstream concentration enables electrolyte solvent suppliers to extract margin from downstream assemblers while ISO 14644 Class 7 cleanroom requirements for medical-grade cells erect capital barriers that protect incumbent pricing power.
Pricing Analysis
Distributor margins in European hospital procurement channels absorb 15-25 percent of ex-factory value before cells reach hearing aid OEMs. Three-tier pricing structure across premium, standard, and economy levels separates FDA Class III implantable grades from consumer electronics volume and industrial sensor mid-market offerings. Cost compression in primary cell tiers is intensifying because lithium metal price volatility from South American brine operations squeezes margin predictability. Pharmacy retail channels serving remote control replacement demand exhibit highest price sensitivity, while medical device procurement through group purchasing organizations prioritizes biocompatibility certification over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from hearing aid and cardiac monitor manufacturers requiring carbon footprint declarations under EU Battery Regulation compliance. Geographic supply concentration centers on China for separator membranes, South Korea for electrolyte solvents, and Japan for ceramic-polymer composite materials. Raw material dependencies draw from lithium brine operations in Chile and Argentina, cobalt hydroxide from the Democratic Republic of Congo, and specialized polymer feedstocks from German chemical clusters. Single-source vulnerability in Yangtze River Delta separator production creates chokepoint exposure for European assemblers. Distribution runs through technical distributors with formulation expertise for industrial sensors, hospital procurement consolidation for medical devices, and retail pharmacy networks for consumer replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The coin cell lithium batteries market functions as a regulatory compounder where EU Battery Regulation carbon accounting mandates and Japan's METI recycling targets continuously reshape supplier qualification criteria and procurement economics.
For Market Incumbents: Anchor market position through backward integration into electrolyte formulation capabilities as retiring specialist knowledge concentrates in Osaka and Munich research centers. Expand ISO 14644 Class 7 cleanroom capacity in Baden-Württemberg to capture sole-source contracts from consolidating European hospital group purchasing organizations. Solid-state electrolyte breakthroughs threaten primary cell incumbents with technology substitution. For New Entrants and Emerging Players: The mid-market price-point gap between VARTA AG's premium medical-grade cells and commodity consumer electronics batteries creates white-space opportunity for qualified challengers. Target India's medical device PLI scheme for hearing aid manufacturing incentives where local assembly requirements outrun domestic cell supplier presence. Pursue technical distributor partnerships with LoRaWAN sensor network deployers in German industrial clusters as the fastest penetrable application segment. For Investors and Strategic Acquirers: Consolidation pressure builds where electrolyte formulation expertise concentrates among aging specialist cohorts without succession pipelines. Long-term viability over the next decade hinges on captive material traceability systems compliant with evolving recycled content thresholds. Acquisition focus should center on mid-scale European packagers with existing biocompatibility documentation and carbon accounting infrastructure. The signal to watch is solid-state prototype commercialization timelines from Swiss and German cardiac monitor pilot programs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrolyte Formulation | Captures margin from Japanese and German specialty chemical suppliers while securing IP for low-temperature performance cells. |
| ISO 14644 Class 7 Cleanroom Expansion | Qualifies suppliers for FDA Class III implantable contracts and EU hospital group purchasing organization sole-source agreements. |
| Carbon Footprint Declaration Infrastructure | Enables compliance with EU Battery Regulation thresholds for recycled content and supply chain traceability. |
| Solid-State Electrolyte R&D Partnership | Positions manufacturers for next-generation cardiac monitor contracts requiring zero-leakage sulfide-glass cell architectures. |
| Reverse Logistics Network Buildout | Satisfies Japan's METI collection targets for coin cells below five grams while generating feedstock for recycled lithium recovery. |
Research Methodology
Coverage spans China, Germany, Japan, Switzerland, and the United States, with primary inputs from each market's precision electronics and medical device manufacturing clusters. The analysis combines primary interviews with hearing aid OEM procurement directors, cardiac monitor biomedical engineers, hospital GPO contracts managers, and electrolyte formulation specialists with secondary validation from SAMR GB standards documentation, FDA 510(k) filings, METI recycling compliance reports, and EU Battery Regulation implementation guidance. Bottom-up demand modeling from end-use application volumes triangulates against top-down supply-side capacity assessments across East Asian chemical clusters.
Granularity-level modeling disaggregates volume and value across primary, rechargeable, specialty, and lithium iron phosphate chemistry formats; medical device, consumer electronics, automotive, and industrial equipment end-use segments; and OEM direct, distributor, online retail, and offline retail channels. CAGRs derive from regression analysis of procurement contract tenors, replacement cycle economics, and technology substitution curves. Forecast inputs incorporate solid-state prototype commercialization timelines, hospital procurement consolidation trajectories, and recycling mandate enforcement intensity across jurisdictions.
Caveats apply where lithium metal price volatility from South American brine operations, single-source separator membrane concentration in the Yangtze River Delta, or accelerated solid-state electrolyte breakthroughs could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Europe Battery Systems for Electric Vehicles Market
Batteries
Hybrid Flow Battery Market
Batteries
Carbon Foam Battery Market
Batteries
Automotive Start-Stop Battery Market
Batteries
Nickel-Based Battery Charger Market
Batteries
High Voltage Air-cooled Battery Compartment Market
Batteries
China Rechargeable Battery Market
Batteries
Nanicl Battery Market
Batteries
HIT Battery Market
Batteries
Aluminum-Air Battery Market
Batteries
Lithium Starters Market
Batteries
East Europe Battery Market
Batteries
Nuclear Battery Sales Market
Batteries
Battery Simulator Market
Batteries
Europe Industrial Battery Market
Batteries
North America Consumer Battery Market