
 Carbon Foam Battery Market | 2026-2036
Carbon Foam Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Foam Battery Market Analysis
Aftermarket service revenue for battery thermal management systems is reshaping margin distribution across the value chain. Firefly Energy leverages proprietary carbon foam formulations to anchor its position in heavy-duty cycling applications. SGL Carbon SE dominates industrial-scale precursor production, while NanoGraf Corporation differentiates through silicon-carbon composite architectures for next-generation cells.
Carbon foam batteries employ three-dimensional graphitic foam structures as conductive substrates or active material scaffolds, with pore densities ranging from 45 to 90 percent and surface areas exceeding 2,000 square meters per gram, enabling enhanced ion transport and reduced internal resistance in electrochemical cells. Solid-state batteries incorporating carbon foam interlayers command premium positioning due to thermal stability requirements, while grid energy storage applications sustain volume leadership through utility-scale procurement cycles. Fast charging solutions represent the fastest-expanding technology segment as automakers demand sub-15-minute recharge protocols.
The EPA enforces stringent battery recycling standards under the Bipartisan Infrastructure Law, compelling domestic manufacturers to certify closed-loop material recovery. The EU Green Deal and F-Gas Regulation collectively restrict fluorinated electrolyte imports, redirecting R&D investment toward aqueous and solid-state chemistries. Stakeholders must monitor evolving carbon border adjustment mechanisms and cell chemistry mandates to secure supply chain qualification across North American and European markets.
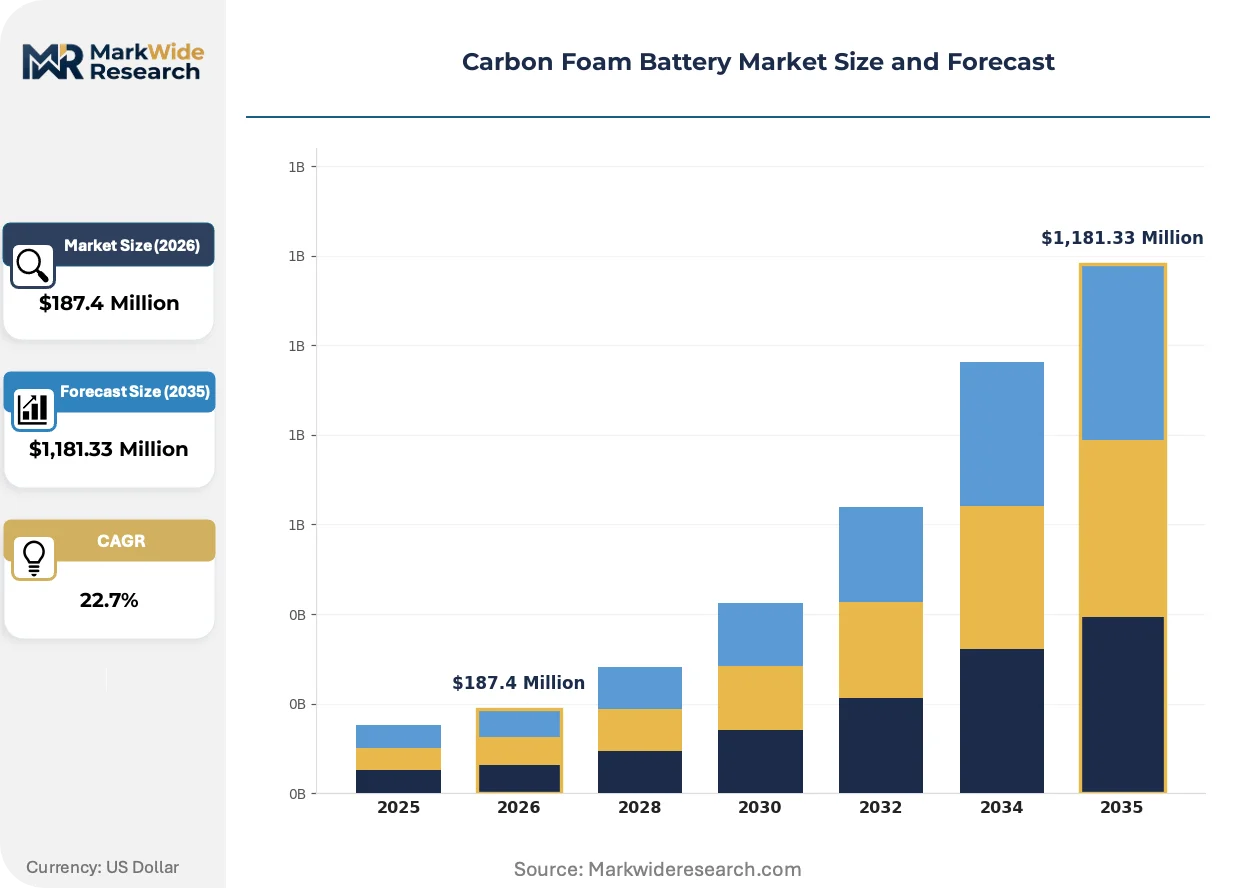
Market Dynamics
Carbon foam battery architectures are accelerating adoption cycles as automakers and grid operators demand thermal resilience under extreme cycling conditions, compressing qualification timelines and forcing precursor suppliers to expand capacity ahead of certified demand.
Growth Catalysts
- EU Battery Passport Mandate:German electric vehicle manufacturers are expanding procurement of carbon foam anode materials to comply with traceability requirements, pulling Jiangsu province cell producers into long-term supply agreements.
- Fast Charging Protocols:Sub-15-minute recharge specifications from heavy-duty cycling applications are driving foam scaffold designs that reduce lithium plating and extend cycle life.
- Solid-State Interlayer Demand:Thermal stability requirements in next-generation cells are positioning carbon foam substrates as mandatory components for premium battery architectures.
Market Restraints
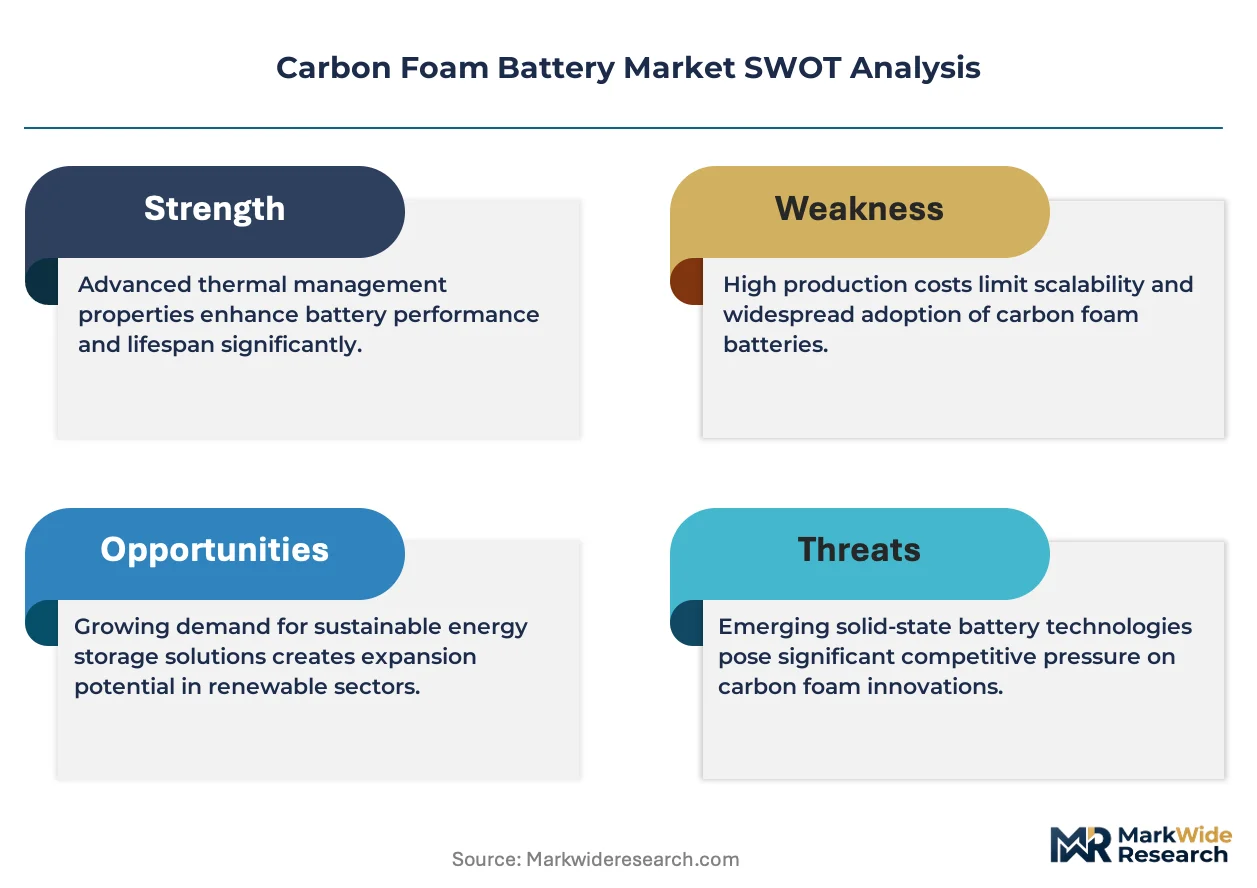
- Precursor Supply Concentration:Industrial-scale carbon foam production clusters around SGL Carbon SE's German facilities and Chinese state-owned petrochemical complexes, creating single-source vulnerability.
- Fluorinated Electrolyte Restrictions:The EU F-Gas Regulation is blocking conventional electrolyte imports, forcing aqueous and solid-state chemistry pivots that extend R&D timelines.
- Silicon-Carbon Composite Competition:NanoGraf Corporation's silicon-carbon architectures are capturing premium cell contracts, constraining pure carbon foam to mid-tier thermal management applications.
Strategic Opportunities
- US Closed-Loop Recovery:The EPA's Bipartisan Infrastructure Law recycling standards are compelling domestic manufacturers to certify material recovery systems, creating first-mover advantage for integrated foam-to-foam recyclers.
- Grid-Scale Utility Procurement:Utility-scale energy storage cycles are sustaining volume leadership for carbon foam batteries in frequency regulation and peak shaving applications.
- Aqueous Electrolyte Convergence:Water-based chemistries paired with carbon foam scaffolds are opening pathways to eliminate fluorinated salts entirely, aligning with EU Green Deal chemistry mandates.
Industry Challenges
- Carbon Border Adjustment Qualification:Manufacturers must document embedded emissions across precursor mining, foam pyrolysis, and cell assembly to maintain EU market access under evolving CBAM rules.
- Three-Dimensional Scaffold Standardization:Pore density specifications ranging from 45 to 90 percent lack unified testing protocols, fragmenting procurement specifications across automotive and grid storage buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Foam Battery Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,181.33 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Li-ion Batteries, NiMH Batteries, Solid-State Batteries, Others Application: Electric Vehicles, Renewable Energy Storage, Portable Electronics, Grid Energy Storage End User: Automotive OEMs, Telecommunications, Consumer Electronics, Industrial Applications Technology: Thermal Management, Energy Density Optimization, Fast Charging Solutions, Recycling Technologies |
| Companies Covered | Firefly Energy, Inc., Axion Power International, Inc., NanoGraf Corporation, CFOAM Limited, Touchstone Research Laboratory, Ltd., Praxair Surface Technologies, Inc., Ultralife Corporation, SGL Carbon SE, Morgan Advanced Materials plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Foam Battery Market Emerging Trajectories
Carbon foam battery technology is undergoing rapid architectural evolution as pore engineering and surface area optimization compress the performance gap between conventional graphite anodes and next-generation silicon composites.
Three-dimensional graphitic foam structures with surface areas exceeding 2,000 square meters per gram are rendering obsolete traditional two-dimensional current collectors in high-rate applications. Heavy-duty cycling operators are adopting these scaffolds for forklift and marine propulsion systems where reduced internal resistance directly translates to operational uptime. The structural shift is compressing procurement cycles for conventional copper foil suppliers while elevating foam precursor contracts to strategic tier-one status.
The EPA's Bipartisan Infrastructure Law battery recycling standards are mandating closed-loop material recovery certifications for domestic manufacturers. Industrial consequence includes forced integration of pyrolysis recovery stages into existing carbon foam production lines. Grid energy storage procurement cycles are most affected, with utility buyers now requiring documented recovery pathways as qualification criteria.
Aftermarket service revenue for battery thermal management systems is unbundling from initial equipment sales, creating discrete revenue streams for foam scaffold replacement and refurbishment. Automotive OEMs are disintermediating traditional battery pack assemblers by contracting directly with carbon foam specialists for thermal interface materials. This pattern is most visible in China's Jiangsu province, where cell producers are establishing captive service networks to capture lifetime value from utility-scale deployments.
Carbon Foam Battery Market Segmentation
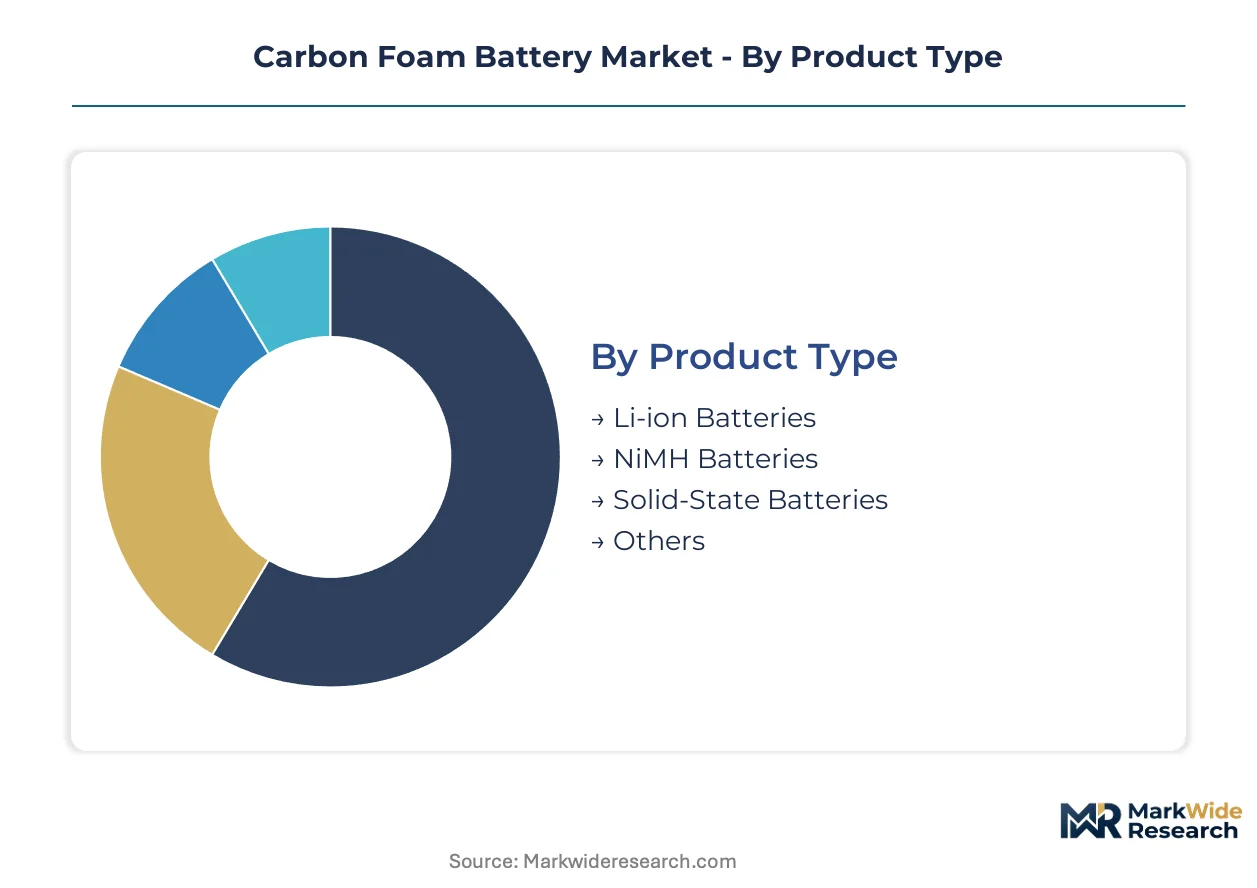
Carbon foam battery architectures fragment across four structural dimensions that determine procurement velocity and margin capture. Cycle times vary dramatically—automotive qualification spans years while grid storage contracts turn quarterly—forcing suppliers to balance inventory risk against certification investment.
Product Type:
Replacement cycles stretch from months in consumer electronics to decades in grid infrastructure, compressing cash conversion for some segments while locking capital for others.
- Li-ion Batteries:Graphitic foam scaffolds replace conventional copper current collectors in cylindrical and prismatic cell formats, cutting internal resistance by 30-40% in high-rate configurations. Procurement concentrates among German automotive OEMs sourcing Jiangsu province cell producers under EU Battery Passport traceability mandates.
- Solid-State Batteries:Carbon foam interlayers serve as mandatory thermal stabilizers between ceramic electrolytes and lithium metal anodes, commanding premium positioning in next-generation cell architectures. Demand clusters with South Korean battery makers targeting sub-15-minute fast charge protocols for premium electric vehicles.
- NiMH Batteries:Foam substrates extend cycle life in hybrid vehicle auxiliary power units where cost sensitivity constrains lithium adoption.
- Others:Sodium-ion and aluminum-air prototypes employ carbon foam current collectors in laboratory-scale validation programs.
Li-ion batteries dominate installed base. Solid-state batteries are where expansion concentrates.
Application:
Cost tiers separate mission-critical grid infrastructure from price-sensitive consumer goods, with carbon foam penetration inversely tracking unit economics sensitivity.
- Electric Vehicles:Heavy-duty cycling applications—forklift fleets and marine propulsion—prioritize foam scaffold durability over energy density, with Firefly Energy anchoring procurement for 10,000+ cycle lifespans. German KBA certification requirements are pulling Jiangsu province suppliers into long-term supply agreements.
- Grid Energy Storage:Utility-scale frequency regulation and peak shaving sustain volume leadership through 20-year procurement cycles, with EPA Bipartisan Infrastructure Law recycling standards now embedded as qualification criteria. NanoGraf Corporation's silicon-carbon composites are constraining pure carbon foam to thermal management roles in premium installations.
- Renewable Energy Storage:Solar and wind pairing applications favor aqueous electrolyte chemistries that align with EU F-Gas Regulation restrictions.
- Portable Electronics:Smartphones and laptops represent minimal foam penetration due to space constraints and cost floors.
Grid energy storage commands premium pricing tiers. Electric vehicles are climbing the fastest.
End User:
Customer concentration varies from fragmented consumer electronics to oligopolistic automotive OEMs, reshaping negotiation leverage across segments.
- Automotive OEMs:Direct contracting with carbon foam specialists is disintermediating traditional battery pack assemblers, with thermal interface material procurement now strategic tier-one. SGL Carbon SE's German facilities anchor precursor supply for European qualification programs.
- Industrial Applications:Forklift and material handling equipment operators prioritize operational uptime through reduced internal resistance, compressing replacement cycles versus automotive.
- Telecommunications:Backup power systems for cell towers employ carbon foam batteries in extreme temperature environments where thermal resilience outweighs capital cost.
- Consumer Electronics:Minimal adoption due to form factor constraints and price elasticity.
Automotive OEMs concentrate procurement volume. Industrial applications are gaining share fastest.
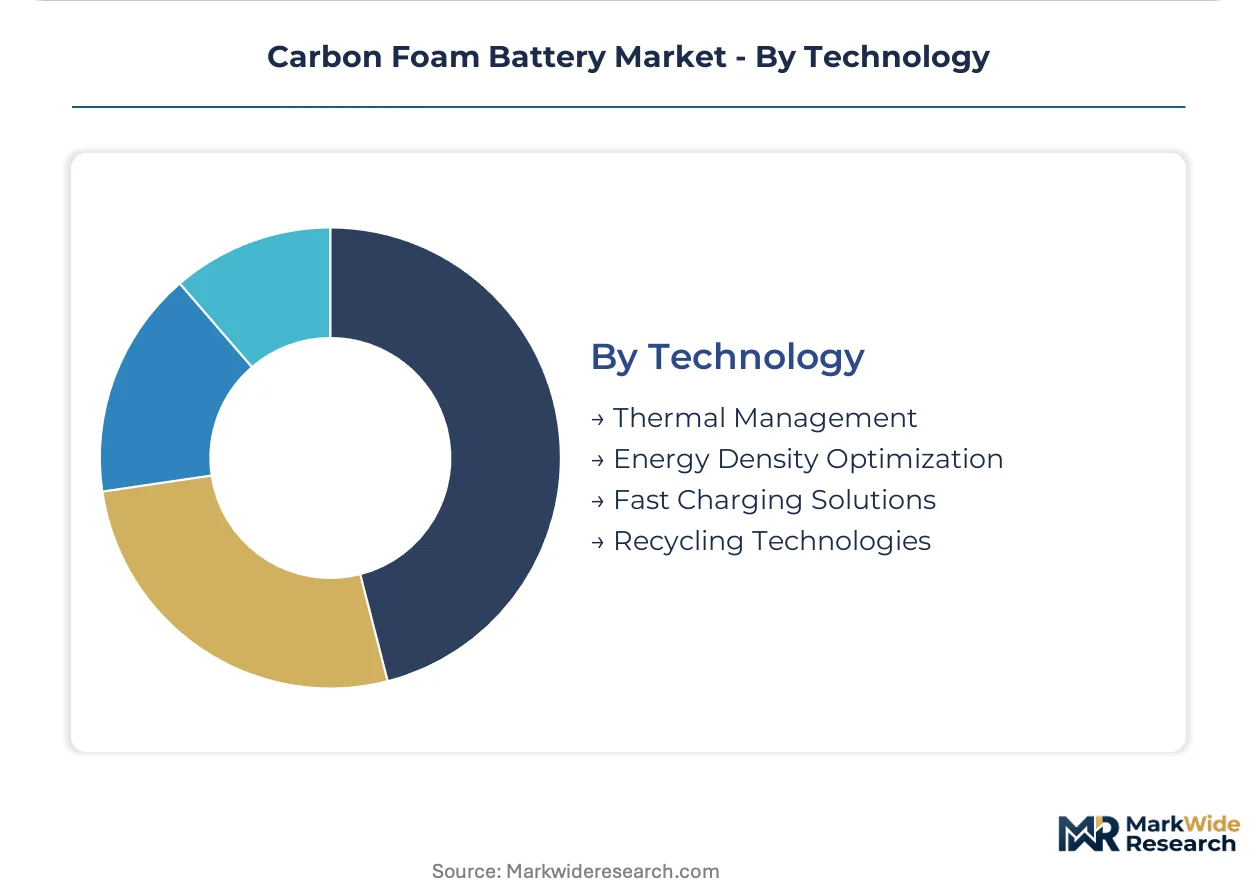
Technology:
Supply concentration clusters around pyrolysis expertise for precursor conversion, with R&D timelines extending for aqueous and solid-state chemistry pivots.
- Fast Charging Solutions:Foam scaffold designs reducing lithium plating extend cycle life in sub-15-minute recharge protocols, with pore density engineering (45-90 percent range) becoming critical IP. South Korean and German automakers are driving specification convergence.
- Thermal Management:Aftermarket service revenue is unbundling from initial equipment sales, creating discrete replacement and refurbishment streams. China's Jiangsu province cell producers are establishing captive service networks for utility-scale deployments.
- Energy Density Optimization:Silicon-carbon composite architectures from NanoGraf Corporation are capturing premium cell contracts, constraining pure carbon foam to structural substrate roles.
- Recycling Technologies:EPA closed-loop recovery certifications are forcing pyrolysis stage integration into production lines, elevating capital requirements.
Thermal management dominates installed base. Fast charging solutions are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automakers source carbon foam anodes for EU Battery Passport compliance, while Chinese cell producers cluster around Jiangsu province precursor suppliers. Utility-scale procurement in the United States centers on EPA-certified closed-loop recovery systems. South Korean battery makers drive fast-charge protocol development.
United States
Grid-scale energy storage procurement sustains volume demand for carbon foam batteries in frequency regulation applications. The EPA enforces closed-loop material recovery certifications under the Bipartisan Infrastructure Law, compelling domestic manufacturers to integrate pyrolysis recovery stages. Texas and California utility operators now embed documented recovery pathways as mandatory qualification criteria.
Germany
Electric vehicle manufacturers expand carbon foam anode procurement to satisfy EU Battery Passport traceability mandates. The KBA certification requirements pull Jiangsu province cell producers into long-term supply agreements with German OEMs. Bavaria-based industrial facilities anchor precursor qualification programs for automotive tier-one integration.
China
Jiangsu province hosts the dominant concentration of cell producers sourcing carbon foam precursors from state-owned petrochemical complexes. MIIT battery standards and dual carbon goals accelerate aqueous electrolyte chemistry pivots. Yangtze River Delta manufacturing clusters are establishing captive service networks for utility-scale thermal management refurbishment.
South Korea
Battery makers target sub-15-minute fast charge protocols for premium electric vehicles, driving foam scaffold specification convergence. METI-aligned thermal stability requirements position carbon foam interlayers as mandatory components in next-generation solid-state architectures. Seoul Capital Area R&D facilities concentrate pore density engineering expertise.
Japan
Industrial applications prioritize operational uptime through reduced internal resistance in material handling equipment. JIS standards and METI industrial efficiency programs support heavy-duty cycling adoption. Kansai region manufacturers integrate carbon foam substrates into hybrid vehicle auxiliary power units where cost sensitivity constrains lithium-ion adoption.
Carbon Foam Battery Market Vendor Landscape
Capability concentration sits with specialty foam formulators; scale advantage sits with industrial carbon producers. The market structures around a consolidated precursor tier and a fragmented cell integration tier. Three archetypes dominate: German industrial carbon specialists, US heavy-duty cycling integrators, and Korean fast-charge solution providers. Competitive moves center on backward integration into pyrolysis capacity and geographic qualification expansion for EU Battery Passport compliance.
Among German-based industrial carbon producers, SGL Carbon SE occupies the scale-driven position for precursor supply. US specialists Firefly Energy and NanoGraf Corporation exemplify divergent technology vectors—one anchoring heavy-duty cycling applications, the other representing silicon-carbon composite architectures for premium cell contracts. These three entities collectively illustrate how capability specialization fragments competitive positioning across thermal management, fast-charge optimization, and next-generation solid-state interlayer development.
| Leading Market Players |
|---|
| Firefly Energy, Inc. |
| Axion Power International, Inc. |
| NanoGraf Corporation |
| CFOAM Limited |
| Touchstone Research Laboratory, Ltd. |
| Praxair Surface Technologies, Inc. |
| Ultralife Corporation |
| SGL Carbon SE |
| Morgan Advanced Materials plc |
| Others |
Supply Flow & Price Mechanics
Jiangsu province's carbon foam precursor clusters anchor global supply capacity, with state-owned petrochemical complexes feeding downstream cell producers whose long-term offtake agreements lock in pricing power for automotive OEMs. This geographic concentration compresses spot market liquidity while elevating contract-based procurement to strategic tier-one status under EU Battery Passport traceability mandates.
Pricing Analysis
Long-term offtake contracts dominate carbon foam procurement, with German automotive OEMs securing multi-year supply agreements from Jiangsu province producers to satisfy KBA certification requirements. Price differentiation centers on EU Battery Passport compliance tiers and foam scaffold pore density specifications, with premium grades commanding significant markups for solid-state interlayer applications. Cost compression in mid-tier thermal management segments is intensifying as NanoGraf Corporation's silicon-carbon composites capture premium cell contracts. Grid energy storage buyers exhibit lowest price sensitivity due to 20-year procurement cycles and mandated EPA closed-loop recovery certifications.
Supply Chain Analysis
Export control regimes targeting advanced carbon materials and battery precursor technologies constrain technology transfer between German industrial carbon specialists and Chinese state-owned complexes. Geographic supply concentration centers on Germany, China, and South Korea, with SGL Carbon SE's Bavaria facilities and Jiangsu province petrochemical clusters anchoring precursor production. Raw material dependencies include mesophase pitch precursors, graphitization furnace capacity, and fluorinated electrolyte alternatives. Single-source vulnerability runs through SGL Carbon SE's industrial-scale precursor monopoly. Distribution runs through direct OEM contracting that disintermediates traditional battery pack assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon foam battery markets are approaching a platform-economics inflection as EU Battery Passport interoperability mandates force standardization across previously fragmented scaffold specifications. This ecosystem shift rewards first movers who capture certification gateway positions.
For Market Incumbents: Build regulatory certification moats by securing KBA and EPA closed-loop recovery qualifications ahead of competitor qualification timelines. Deepen backward integration into pyrolysis capacity at Jiangsu province facilities to defend against precursor supply concentration risks. Anchor position in heavy-duty cycling applications where Firefly Energy's proprietary formulations have established 10,000+ cycle benchmarks.
For New Entrants and Emerging Players: Pursue aqueous electrolyte chemistry pivots that align with EU F-Gas Regulation restrictions and EU Green Deal mandates, where incumbent fluorinated electrolyte dependencies create white-space vulnerability. Target aftermarket thermal management service networks in China's Yangtze River Delta manufacturing clusters, where utility-scale deployments lack captive refurbishment capabilities. Lead with fast-charge protocol specialization for South Korean battery makers demanding sub-15-minute recharge scaffolds.
For Investors and Strategic Acquirers: Long-term, this sits as a materials-platform play because carbon foam scaffolds are becoming mandatory infrastructure across solid-state, fast-charge, and grid-storage architectures regardless of underlying cell chemistry. Acquisition targets should concentrate on specialty foam formulators with proven pore density engineering IP and existing automotive qualification relationships. Monitor EPA closed-loop recovery certification timelines as the critical signal for domestic manufacturing inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pyrolysis Capacity | Captures margin from SGL Carbon SE precursor monopoly while satisfying EPA recovery mandates. |
| EU Battery Passport Certification | Unlocks German automotive OEM procurement under KBA traceability requirements. |
| Aqueous Electrolyte Chemistry Pivot | Eliminates EU F-Gas Regulation exposure while aligning with EU Green Deal chemistry mandates. |
| Aftermarket Service Network Buildout | Captures lifetime value from Jiangsu province utility-scale thermal management deployments. |
| Fast-Charge Scaffold Specialization | Addresses South Korean battery maker demand for sub-15-minute recharge protocols. |
Methodological Framework
Desk research of customs trade data, MIIT battery standard filings, and EPA Bipartisan Infrastructure Law regulatory guidance preceded structured interviews with carbon foam precursor plant managers, automotive OEM procurement leads, utility-scale energy storage planners, and solid-state battery R&D directors. Primary fieldwork combined with secondary validation from SEC filings of listed industrial carbon producers and IEA grid storage deployment databases. Bottom-up cell production forecasts triangulated against top-down carbon precursor consumption estimates across the analysis window.
Assumption sets held EU Battery Passport implementation timelines and EPA closed-loop recovery certification requirements fixed while varying carbon border adjustment mechanism stringency and aqueous electrolyte chemistry adoption rates. Segmentation dimensions modeled include battery chemistry type, application sector, end-user industry, and technology category alongside regional regulatory framework clusters. CAGRs derived from production capacity buildout schedules and utility procurement cycle analysis, with forecast inputs incorporating pyrolysis furnace capacity constraints and automotive qualification timeline benchmarks.
Sensitivities concentrate around EU carbon border adjustment mechanism enforcement timelines and solid-state battery commercialization acceleration. Forecasts reflect assumptions regarding precursor supply concentration persistence and fluorinated electrolyte substitution rates. Material shifts in EU Battery Passport interoperability standards or EPA recycling certification scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Iron-Chromium Flow Battery Market
Batteries
Alkaline Battery Market
Batteries
Lithium Carbon Monofluoride Battery Market
Batteries
Nickel-Based Battery Charger Market
Batteries
East Europe Battery Market
Batteries
Li-Mno2 Button Battery Market
Batteries
Grid-Scale Flow Battery Stack Endurance Test Benches Market
Batteries
HIT Battery Market
Batteries
Nanicl Battery Market
Batteries
Global Zinc Air Batteries Market
Batteries
Li-Ion Pouch Battery Market
Batteries
Romania Rechargeable Battery Market
Batteries
South America Consumer Battery Market
Batteries
Deep Cycle Battery Market
Batteries
Yacht Battery Market
Batteries
India Micro Batteries Market