
 Rechargeable Coin Cell Market | 2026-2036
Rechargeable Coin Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Rechargeable Coin Cell Market Intelligence
Modular battery-pack bundling is pivoting how OEMs specify coin cell procurement, shifting from standalone cell purchases to pre-certified sub-assemblies. Panasonic Corporation leverages vertical integration across cathode materials and cell finishing to control cost structures. Samsung SDI anchors its position through membrane electrode assembly expertise in prismatic formats. VARTA Microbattery specializes in hearing-device configurations, sustaining premium positioning through medical-grade reliability standards.
Rechargeable coin cells are compact secondary electrochemical cells, typically measuring 5–25 mm in diameter and 1–6 mm in height, employing lithium-ion or silver-zinc chemistries with aqueous or non-aqueous electrolytes to deliver cyclic energy storage for space-constrained devices. Their primary purpose centers on powering miniaturized electronics where disposable alternatives prove economically or environmentally untenable. Lithium-ion product types dominate current volume given superior energy density and cycle life for wearable electronics applications. IoT sensors represent the fastest-expanding application segment as low-power wireless protocols multiply deployment nodes. Cylindrical technology maintains manufacturing scale advantages, though pouch configurations capture margin pools in ultra-thin wearable designs.
Japan's METI enforces strict recycling quotas and substance disclosure under its battery labeling regime, while the EU F-Gas Regulation and REACH restrict fluorinated compounds and hazardous substances in cell construction. China's SAMR and GB standards mandate compulsory product certification, creating compliance barriers for non-domestic suppliers. Stakeholders must monitor evolving chemistry restrictions and recyclability mandates across these jurisdictions to preserve market access and avoid reformulation costs.
Market Dynamics
Chemistry transitions under tightening substance thresholds are compressing legacy supply chains while solid-state and silicon-anode architectures redraw performance baselines for wearable and medical OEMs.
Growth Catalysts
- Wearable electronics proliferation:Fitness trackers and hearables manufacturers in Germany and Japan are expanding orders for sub-6mm cell heights. Lithium-ion configurations dominate these specifications.
- EU Battery Regulation substance mandates:Cadmium and mercury thresholds are forcing chemistry reformulations, creating replacement demand for compliant silver-zinc and lithium-ion alternatives.
- IoT sensor deployment acceleration:Low-power wireless protocols across South Korean smart manufacturing clusters are multiplying node counts requiring cyclic energy storage.
Market Restraints
- Cathode material cost volatility:Cobalt and nickel price swings compress margins for lithium-ion variants, pressuring cell finishers without captive material supply.
- Supply concentration in East Asian membrane electrode assembly:Japanese and South Korean specialists control critical coating and stacking equipment, creating bottleneck risk for European and North American packagers.
- Silver-zinc cycle life limitations:Aqueous electrolyte degradation restricts deep-cycle applications, constraining uptake in industrial IoT relative to lithium-ion.
Strategic Opportunities
- Underpenetrated medical implant segment:Germany's precision manufacturing clusters lack certified suppliers for biocompatible rechargeable micro-cells, creating entry points for compliant finishers.
- China GB standards certification services:SAMR compulsory product certification creates advisory and testing revenue streams for technical consultancies guiding foreign entrants.
- Solid-state electrolyte convergence with MEMS packaging:Thin-film deposition advances enable cell-sensor co-packaging for ultra-miniaturized wearable devices.
Industry Challenges
- Electrolyte formulation talent scarcity:Non-aqueous lithium salt expertise concentrates in Japanese and South Korean research institutes, limiting European and North American cell development velocity.
- Medical-grade reliability certification timelines:IEC 60601 and ISO 13485 compliance cycles extend 18-24 months, delaying revenue recognition for hearing-device and implant suppliers.
- Legacy disposable cell integration friction:OEMs with established primary battery supply chains face redesign costs and BMS adaptation for secondary cell architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rechargeable Coin Cell Market |
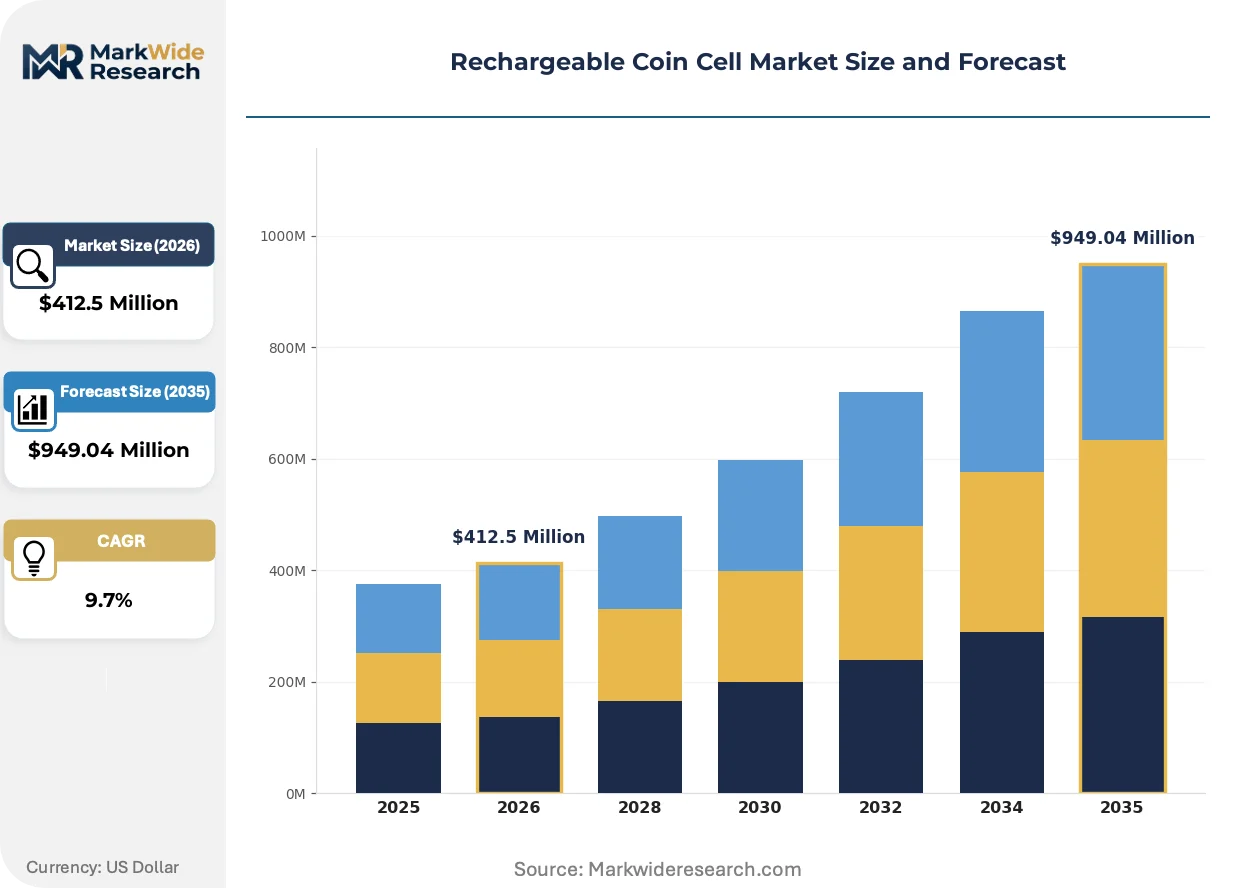
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $949.04 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silver Zinc, Lithium-Ion, Nickel-Metal Hydride, Lead Acid Technology: Cylindrical, Prismatic, Pouch, Membrane Electrode Assembly Application: Wearable Electronics, Hearing Devices, Remote Keyless Entry, IoT Sensors End User: Consumer Electronics Manufacturers, Medical Equipment Producers, Security System Suppliers, Industrial Sensor Makers |
| Companies Covered | Panasonic Corporation, Samsung SDI, Sony Group Corporation, VARTA Microbattery, LG Chem, Energizer Holdings, Maxell Holdings, Renata, Toshiba Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rechargeable Coin Cell Market Strategic Shifts & Innovations
Solid-state architectures and silicon-dominant anodes are compressing form-factor constraints while regulatory substance bans accelerate chemistry turnover across precision manufacturing clusters.
Solid-state electrolyte architectures are integrating ceramic and sulfide-based ionic conductors to replace flammable liquid electrolytes in sub-10mm diameter formats. Medical implant and premium hearable manufacturers in Switzerland and Japan are piloting these configurations for enhanced thermal stability. This integration is compressing traditional separator and electrolyte wetting equipment investments, forcing cell finishers to retool deposition lines.
Japan's METI battery labeling regime now enforces strict recycling quotas and substance disclosure thresholds for nickel, cobalt, and lithium content. Cell importers must register chemistries and fund end-of-life collection infrastructure. Medical device and IoT sensor suppliers targeting Japanese distribution channels are accelerating silver-zinc and cobalt-reduced lithium-ion formulations to preempt compliance penalties.
Modular battery-pack bundling is displacing standalone cell procurement across German and South Korean wearable OEMs. Pre-certified sub-assemblies integrating protection circuits, connectors, and thermal management reduce in-house engineering burdens. This pattern concentrates specification authority with cell finishers possessing vertical membrane electrode assembly and electronics integration capabilities.
Rechargeable Coin Cell Market Segmentation
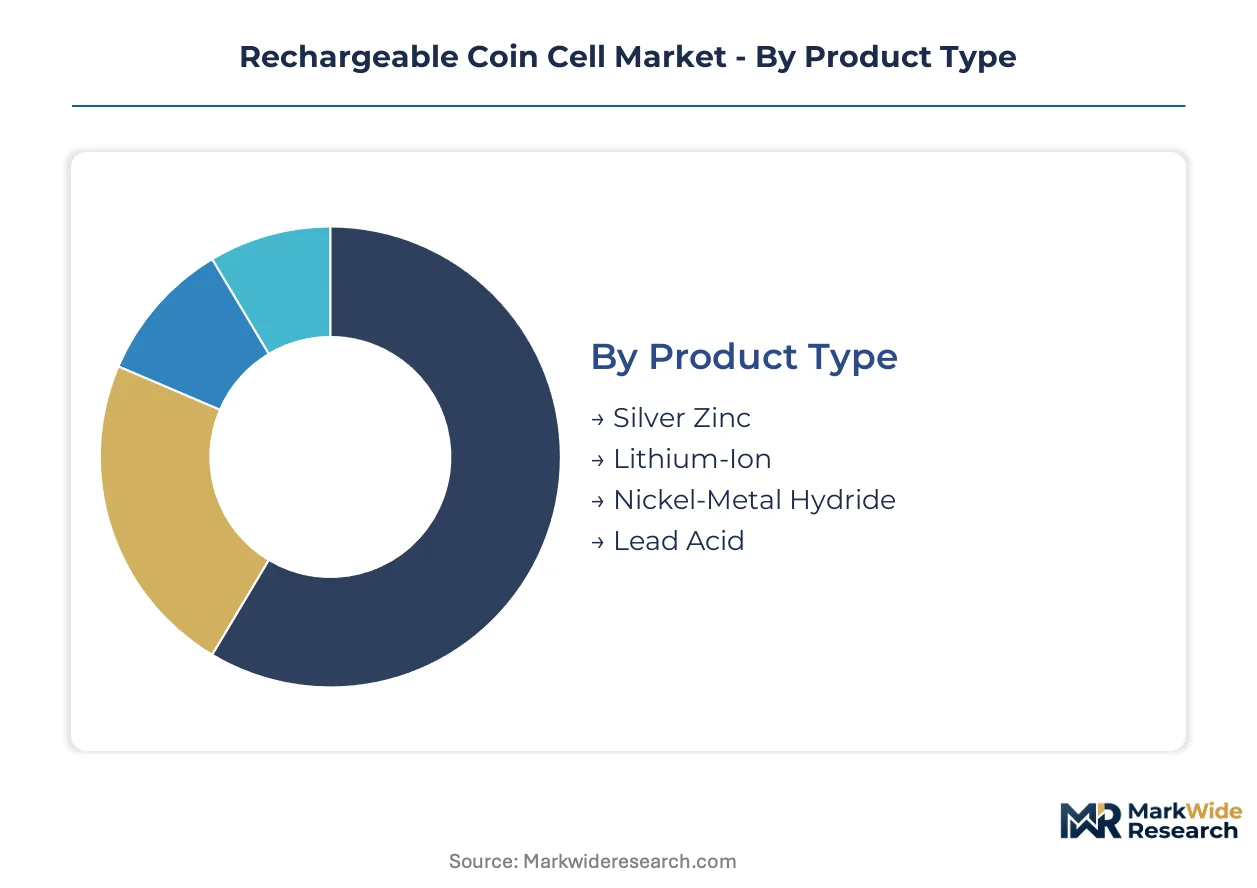
Rechargeable coin cell procurement patterns diverge sharply across chemistry choices and form-factor requirements. OEM specification authority concentrates with finishers who can bridge material science and miniaturized electronics integration.
Product Type:
Customization intensity spans from commodity nickel-metal hydride to precision-tuned silver-zinc formulations for medical-grade reliability.
- Lithium-Ion:Non-aqueous electrolyte systems with cobalt or nickel-rich cathodes deliver superior energy density above 200 Wh/L. German fitness tracker manufacturers and Japanese hearable OEMs dominate procurement for sub-6mm heights where cycle life exceeds 500 cycles.
- Silver-Zinc:Aqueous alkaline electrolyte with silver oxide cathodes offers biocompatibility and stable voltage discharge. Hearing-device specialists in Switzerland and South Korea specify these for IEC 60601-compliant medical electronics despite aqueous degradation limiting deep-cycle utility.
- Nickel-Metal Hydride:Rare-earth hydrogen storage alloys in cylindrical formats serve cost-sensitive remote keyless entry fobs with moderate cycle requirements.
- Lead Acid:Mature flooded and gel configurations persist in legacy industrial backup applications where form-factor constraints relax and lowest unit cost dominates.
Leading the category by volume: Lithium-Ion. Growing fastest: Silver-Zinc.
Technology:
Manufacturing scale advantages concentrate in cylindrical winding equipment, while margin pools shift toward membrane electrode assembly integration.
- Cylindrical:Automated winding and stacking lines achieve lowest per-unit cost at million-cell monthly volumes. Panasonic Corporation and Samsung SDI anchor capacity in Japan and South Korea for wearable electronics procurement.
- Membrane Electrode Assembly:Precision coating and lamination of cathode-anode-separator stacks enables thinnest formats below 2mm height. South Korean specialists control critical equipment for German medical implant suppliers seeking solid-state electrolyte convergence.
- Pouch:Aluminum-laminate enclosures maximize volumetric efficiency for ultra-thin wearable designs where rigid can constraints fail.
- Prismatic:Stacked electrode configurations with hard-case protection serve industrial IoT sensors requiring mechanical robustness in field deployment.
Cylindrical formats dominate unit economics. Pouch configurations gain share fastest in premium wearable segments.
Application:
Power budget constraints and duty-cycle profiles fragment specification requirements across consumer, medical, and industrial deployment contexts.
- Wearable Electronics:Fitness bands, smartwatches, and hearables demand sub-6mm heights with wireless charging compatibility. Japanese OEMs specify lithium-ion pouch cells for premium designs while German manufacturers prioritize cobalt-reduced cathodes for EU Battery Regulation compliance.
- IoT Sensors:Low-power wireless protocols across South Korean smart manufacturing clusters multiply deployment nodes requiring decade-long service intervals. Solid-state electrolyte pilots target this segment for thermal stability in unattended installations.
- Hearing Devices:Behind-the-ear and in-canal configurations require medical-grade reliability certification under ISO 13485. VARTA Microbattery sustains premium positioning through German precision manufacturing.
- Remote Keyless Entry:Automotive fob specifications prioritize cost minimization and cold-temperature performance over cycle life, favoring nickel-metal hydride alternatives.
Wearable Electronics commands procurement volume. IoT Sensors shows steepest expansion trajectory.
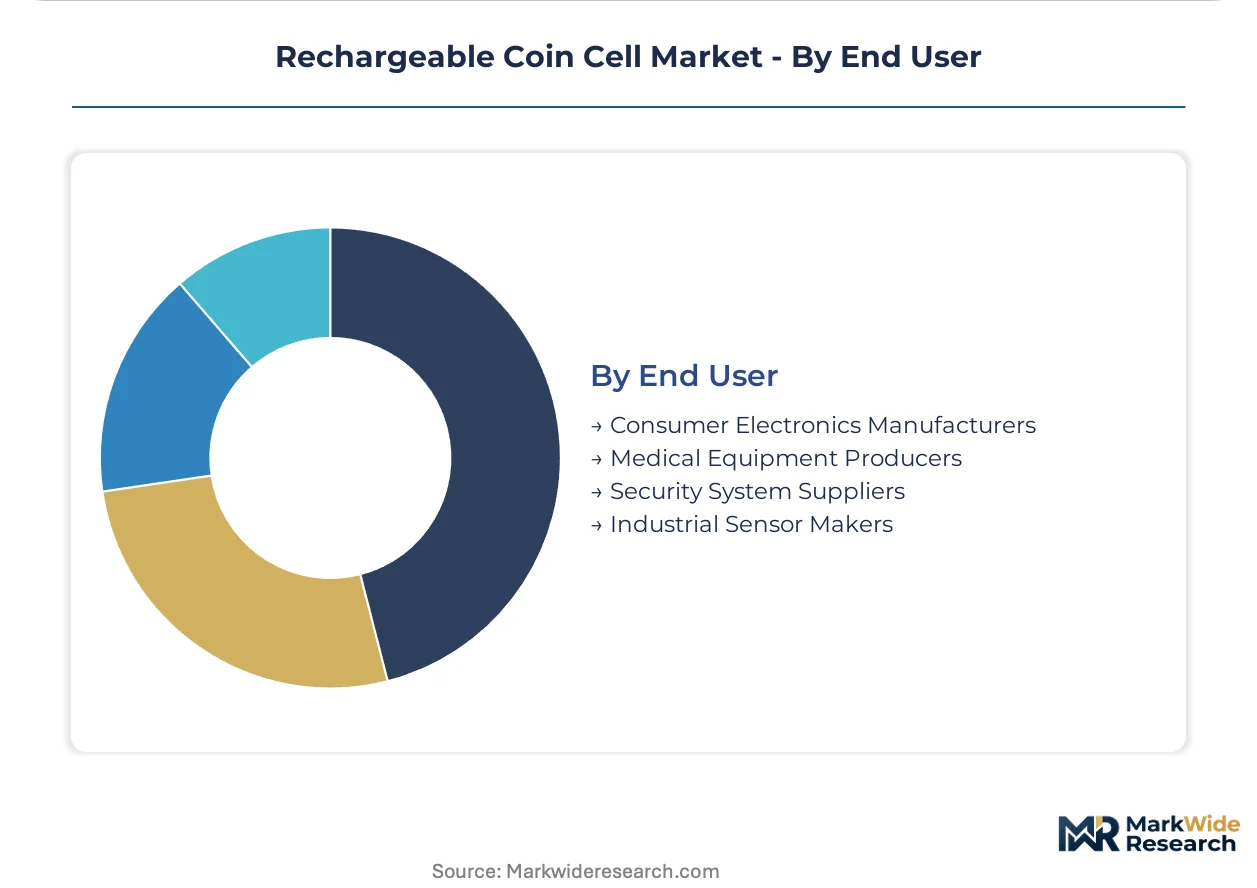
End User:
Certification burden and supply chain integration depth separate medical equipment producers from consumer electronics procurement patterns.
- Consumer Electronics Manufacturers:Scale-driven procurement with modular battery-pack bundling preferences. South Korean and German wearable OEMs shift specification authority to finishers offering pre-certified sub-assemblies with protection circuits and connectors integrated.
- Medical Equipment Producers:IEC 60601 and ISO 13485 compliance cycles extend 18-24 months, delaying revenue recognition. Germany's precision manufacturing clusters lack sufficient certified suppliers for biocompatible rechargeable micro-cells.
- Industrial Sensor Makers:South Korean smart factory deployments drive demand for wide-temperature operation and decade-long service life in unattended nodes.
- Security System Suppliers:Cost-optimized procurement for access control and surveillance backup power with moderate reliability requirements.
Consumer Electronics Manufacturers lead procurement volume. Medical Equipment Producers expand specifications fastest as implantable device electrification advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian membrane electrode assembly specialists supply precision coating equipment to European and North American packagers, while German and Japanese OEMs drive specification authority for medical-grade and wearable applications.
Germany
Precision manufacturing clusters in Bavaria and Baden-Württemberg demand IEC 60601-certified cells for hearing-device and implant applications. The EU Battery Regulation's cadmium and mercury thresholds force chemistry transitions toward silver-zinc and cobalt-reduced lithium-ion alternatives. Stuttgart-based VARTA Microbattery anchors medical-grade reliability standards through ISO 13485-compliant production.
Japan
Hearable and fitness tracker OEMs in Tokyo and Osaka specify sub-6mm lithium-ion pouch configurations with wireless charging compatibility. METI's battery labeling regime enforces strict recycling quotas and substance disclosure for nickel, cobalt, and lithium content. Panasonic Corporation leverages vertical integration across cathode materials and cell finishing to control cost structures in Kansai manufacturing corridors.
South Korea
Smart manufacturing clusters in Gyeonggi Province multiply IoT sensor deployments requiring decade-long service intervals and wide-temperature operation. The country's national industrial regulator mandates compulsory product certification aligned with international standards. Samsung SDI anchors membrane electrode assembly expertise in prismatic formats for industrial automation nodes.
China
Domestic wearable electronics manufacturers in Guangdong and Jiangsu provinces scale procurement of compact power sources for export markets. SAMR and GB standards mandate compulsory product certification, creating compliance barriers for non-domestic suppliers. Shenzhen-based packagers increasingly specify pre-certified sub-assemblies integrating protection circuits and thermal management.
Switzerland
Medical implant manufacturers in the Basel-Zurich corridor pilot solid-state electrolyte configurations for enhanced thermal stability in biocompatible applications. Swissmedic regulates device electrification under medical device directives harmonized with EU MDR requirements. Precision watchmaking clusters in the Jura Arc adapt micro-cell integration expertise for hearable and wearable device applications.
Rechargeable Coin Cell Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across chemistry and form-factor segments. The vendor base stratifies into three tiers: diversified electronics conglomerates with captive material supply, mid-cap cell finishers with membrane electrode assembly specialization, and niche medical-grade suppliers with extended certification cycles. Two dominant competitive moves define current positioning: backward integration into cathode material production to offset cobalt and nickel volatility, and strategic partnerships with wearable OEMs for modular battery-pack bundling specifications.
Among diversified conglomerates, Panasonic Corporation and Samsung SDI exemplify scale-driven archetypes with upstream control over critical production inputs. VARTA Microbattery occupies a specialist position within the medical-grade tier, representing premium positioning through extended reliability certification. These three anchors illustrate the competitive divergence between volume-driven consumer electronics supply and precision-tuned medical device integration.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Samsung SDI |
| Sony Group Corporation |
| VARTA Microbattery |
| LG Chem |
| Energizer Holdings |
| Maxell Holdings |
| Renata |
| Toshiba Corporation |
| Others |
Cost & Logistics Intelligence
EU Battery Regulation cadmium thresholds and Japan's METI substance disclosure mandates are forcing chemistry reformulations across German and Japanese OEM procurement specifications, compelling cell finishers to absorb retooling costs while silver-zinc and cobalt-reduced lithium-ion alternatives command premium positioning.
Pricing Analysis
Margin tightening in medical-grade tiers reflects IEC 60601 certification burdens and 18-24 month compliance cycles that delay revenue recognition. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified implant suppliers from consumer electronics packagers and cost-optimized remote keyless entry providers. Pricing pressure intensifies in standard tiers as South Korean and Chinese manufacturers scale cylindrical winding capacity. Consumer electronics manufacturers exhibit highest price sensitivity, while medical equipment producers accept premium positioning for biocompatibility assurance.
Supply Chain Analysis
Cathode active material supply rests on Japanese and South Korean precursor producers controlling nickel and cobalt sulfate refining. Cell finishers draw from Chinese separator membrane suppliers, German precision coating equipment manufacturers, and Taiwanese protection circuit integrators. Single-source vulnerability concentrates in East Asian membrane electrode assembly equipment, where Japanese specialists control critical coating and stacking lines. Distribution runs through modular battery-pack bundlers offering pre-certified sub-assemblies to German and South Korean wearable OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state electrolyte architectures are displacing liquid electrolyte legacy formats across medical implant and premium hearable segments, compressing traditional separator and wetting equipment investments while redrawing competitive baselines for cell finishers.
For Market Incumbents: Cement membrane electrode assembly specialization through captive coating equipment investments in South Korean and Japanese manufacturing corridors. Defend against modular battery-pack bundlers by integrating protection circuits and thermal management in-house. Prioritize silver-zinc formulation expertise to preempt EU Battery Regulation compliance penalties.
For New Entrants and Emerging Players: The gap between premium medical-grade certification pricing and economy-tier consumer electronics commoditization creates entry space for mid-tier specialists. Target Germany's precision manufacturing clusters lacking sufficient IEC 60601-certified rechargeable micro-cell suppliers. Pursue SAMR advisory and testing services for foreign entrants navigating China's GB standards compulsory certification.
For Investors and Strategic Acquirers: The window for entry favors membrane electrode assembly specialists with solid-state electrolyte pilot capabilities and medical-grade certification track records. Long-term viability hinges on chemistry transition execution across the next decade. Watch for solid-state electrolyte convergence with MEMS packaging as inflection signal for cell-sensor co-packaging viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Materials | Panasonic Corporation controls cost structures through captive nickel-cobalt precursor supply in Kansai corridors. |
| Modular Battery-Pack Bundling Partnership | Samsung SDI anchors specification authority with German wearable OEMs through pre-certified sub-assembly integration. |
| Solid-State Electrolyte Pilot Scale-Up | Swiss medical implant manufacturers in Basel-Zurich corridor pilot ceramic and sulfide-based ionic conductors for thermal stability. |
| Medical-Grade Certification Investment | VARTA Microbattery sustains premium positioning through ISO 13485-compliant Stuttgart production for hearing-device applications. |
| China GB Standards Advisory Services | Technical consultancies capture revenue streams guiding foreign cell suppliers through SAMR compulsory product certification. |
Research Approach
Trade databases, customs records, and SEC filings formed the secondary backbone, cross-referenced with METI battery labeling registrations and EU Battery Regulation compliance disclosures. Primary interviews with cell finishing plant managers, wearable OEM procurement leads, medical device regulatory affairs directors, and membrane electrode assembly equipment suppliers informed chemistry transition timelines and certification burden quantification. Bottom-up and top-down triangulation validated procurement volume estimates across German, Japanese, and South Korean precision manufacturing clusters.
Bottom-up modeling aggregated individual facility capacity and utilization rates across cylindrical, pouch, and prismatic formats, while top-down analysis calibrated against aggregate electronics production data from hearable and IoT sensor OEMs. Segmentation dimensions spanned chemistry type, technology format, application vertical, and end-user certification tier across the projection horizon. CAGRs derived from weighted average of segment growth trajectories, incorporating solid-state electrolyte adoption curves and regulatory compliance phase-in schedules as industry-specific forecast inputs.
Underlying measurement precision varies by segment; medical-grade reliability certification timelines carry tighter precision than consumer electronics procurement forecasts. Projections reflect assumptions regarding EU Battery Regulation enforcement consistency and Japan's METI recycling quota implementation. Chemistry transition delays, raw material price volatility, and solid-state electrolyte manufacturing yield improvements warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Indonesia Battery Market
Batteries
South and Central America Battery Market
Batteries
Battery Pack for Marine Hybrid and Full Electric Propulsion Market
Batteries
Industrial Battery Charger Market
Batteries
AAA Battery Market
Batteries
Breathing Battery Market
Batteries
Yacht Battery Market
Batteries
Maintenance-Free Lead-Acid Battery Market
Batteries
Middle-East Battery Market
Batteries
China Electric Vehicle Vrla Batteries Market
Batteries
Electric Battery Market
Batteries
Watch Battery Market
Batteries
UAV Battery Pack Market
Batteries
India Alkaline Battery Market
Batteries
Tubular GEL Battery Market
Batteries
HIT Battery Market