
 Nanicl Battery Market | 2026-2036
Nanicl Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Nanicl Battery Market Insights
Market Context
Stationary energy storage is expanding as the dominant demand vertical for Nanicl batteries, displacing earlier reliance on niche industrial backup applications. NGK Insulators leverages its ceramic expertise to dominate solid-electrolyte architectures for grid-scale deployments. Saft Groupe anchors long-duration storage contracts through its specialized industrial battery portfolio. Natron Energy differentiates on rapid-cycling Prussian blue cathode designs for data center and telecom backup.
Technical Profile and Segment Structure
Nanicl batteries are sodium-nickel-chloride electrochemical cells operating at elevated temperatures with ceramic beta-alumina solid electrolytes, delivering energy densities of 90–120 Wh/kg for heavy-duty cycling applications. The rechargeable segment leads volume absorption, while non-rechargeable formats occupy specialized military and aerospace niches with premium margin profiles. Automotive end-use is accelerating fastest among application categories, though medical devices sustains the most stable pricing environment due to certification barriers.
Regulatory Environment
China's MIIT governs battery cell manufacturing standards and recycling mandates under GB specifications, while Japan's METI directs national sodium-ion R&D consortia through JIS certification pathways. The EU Battery Regulation and REACH compliance requirements shape market access for imported cells, forcing chemistry disclosure and carbon footprint accounting. Stakeholders must monitor how solid-state sodium chemistry patents and thermal safety certifications evolve as competitive gatekeepers.
Market Dynamics
Solid-electrolyte sodium-nickel-chloride architectures are forcing a recalibration of procurement priorities among grid-scale storage developers, as thermal stability and raw material security displace energy density as the primary selection criterion for long-duration assets.
Growth Catalysts
- China's dual carbon goals:National decarbonization mandates under MIIT direction are accelerating sodium-ion chemistry investments. State-backed procurement quotas for non-lithium storage systems are redirecting utility capital toward ceramic-electrolyte alternatives.
- Grid-scale renewable integration:Wind and solar intermittency is driving demand for 4-8 hour discharge duration assets. Nanicl battery thermal characteristics align with cycling requirements for photovoltaic smoothing and evening peak shaving.
- Cathode material supply security:Prussian blue analog production capacity is concentrating in East Asian manufacturing clusters. Proximity of precursor chemical processing to cell assembly facilities is compressing lead times for utility-scale orders.
Market Restraints
- Input cost volatility:Nickel sulfate and high-purity alumina prices fluctuate with stainless steel and ceramic substrate demand. Battery-grade ceramic beta-alumina electrolyte production requires specialized sintering infrastructure with limited supplier alternatives.
- Technical limitation:Elevated operating temperatures (270-350°C) necessitate thermal management subsystems that add parasitic load and system complexity. Startup energy consumption degrades round-trip efficiency for infrequently cycled assets.
- Substitution threat:Lithium iron phosphate cells continue cost reduction trajectories through manufacturing scale. Iron-based cathode chemistries from competing sodium-ion developers threaten to undercut nickel-chloride architectures on materials cost.
Strategic Opportunities
- India's storage procurement:Central Electricity Authority mandates for renewable energy storage obligation compliance are creating first-mover advantages for sodium-ion technology demonstrations. Domestic manufacturing incentives under PLI scheme support localized cell assembly.
- Data center backup power:Rapid-cycling requirements for hyperscale facility resilience favor electrochemical systems with high power density. Prussian blue cathode variants enable sub-second response times for uninterruptible power supply integration.
- EU Battery Regulation tailwind:Carbon footprint disclosure mandates and recycled content thresholds are advantaging chemistries with established recycling pathways. Ceramic-electrolyte cell designs facilitate material recovery at end-of-life compared to organic liquid electrolyte alternatives.
Industry Challenges
- Thermal safety certification timelines:UN 38.3 transportation testing and IEC 62619 industrial safety validation require extended duration cycling data. High-temperature operation protocols complicate third-party verification compared to ambient-temperature lithium-ion equivalents.
- Solid-state manufacturing skill gap:Ceramic electrolyte fabrication demands expertise in high-temperature sintering and hermetic sealing uncommon in conventional battery production. Workforce development lags capacity expansion timelines for gigawatt-scale facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanicl Battery Market |
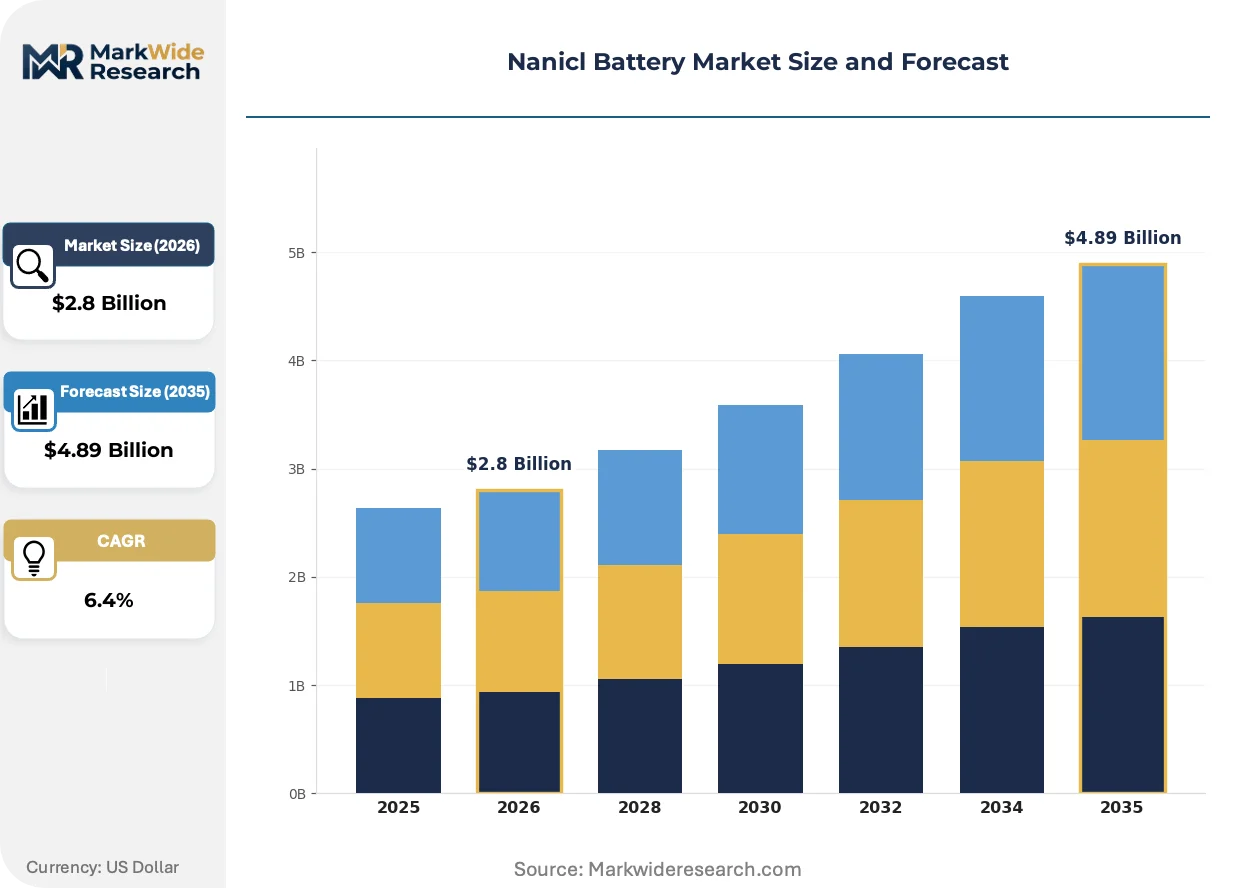
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rechargeable, Non-Rechargeable, Lithium-Ion, Nickel-Metal Hydride End User: Consumer Electronics, Automotive, Industrial, Medical Devices Capacity: Low Capacity, Medium Capacity, High Capacity, Ultra High Capacity Manufacturing Stage: Raw Material Processing, Component Assembly, Final Assembly, Quality Testing |
| Companies Covered | NGK Insulators, Saft Groupe, FIAMM Energy Technology, Natron Energy, Faradion, Altris AB, HiNa Battery Technology, Aquion Energy, FZ Sonick, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanicl Battery Market Trends and Innovations
Electrochemical system design is pivoting toward thermal management integration and solid-state architecture standardization, as developers prioritize operational safety and supply chain resilience over incremental energy density gains.
Ceramic beta-alumina electrolyte manufacturing is integrating continuous sintering processes that reduce production energy intensity and improve ionic conductivity uniformity. Grid-scale storage integrators are specifying these solid-electrolyte cells for 20-year service life projections. The technology is integrating thermal cycling durability as a procurement screening criterion alongside capital cost per kilowatt-hour.
EU Battery Regulation carbon footprint accounting rules are forcing chemistry disclosure and supply chain documentation for imported cells. Industrial battery suppliers must establish measurement protocols for precursor material extraction through cell assembly. Long-duration storage project developers in Germany and France are prioritizing vendors with verified lifecycle assessments to secure permitting approvals.
Utility procurement committees are consolidating supplier relationships around integrated system providers offering 15-year performance guarantees. Turnkey engineering-procurement-construction contracts are displacing component sourcing from multiple vendors. This concentration is most visible in Japanese and South Korean utility tenders, where single-source accountability reduces interface risk for first-of-a-kind sodium-ion deployments.
Nanicl Battery Market Segmentation
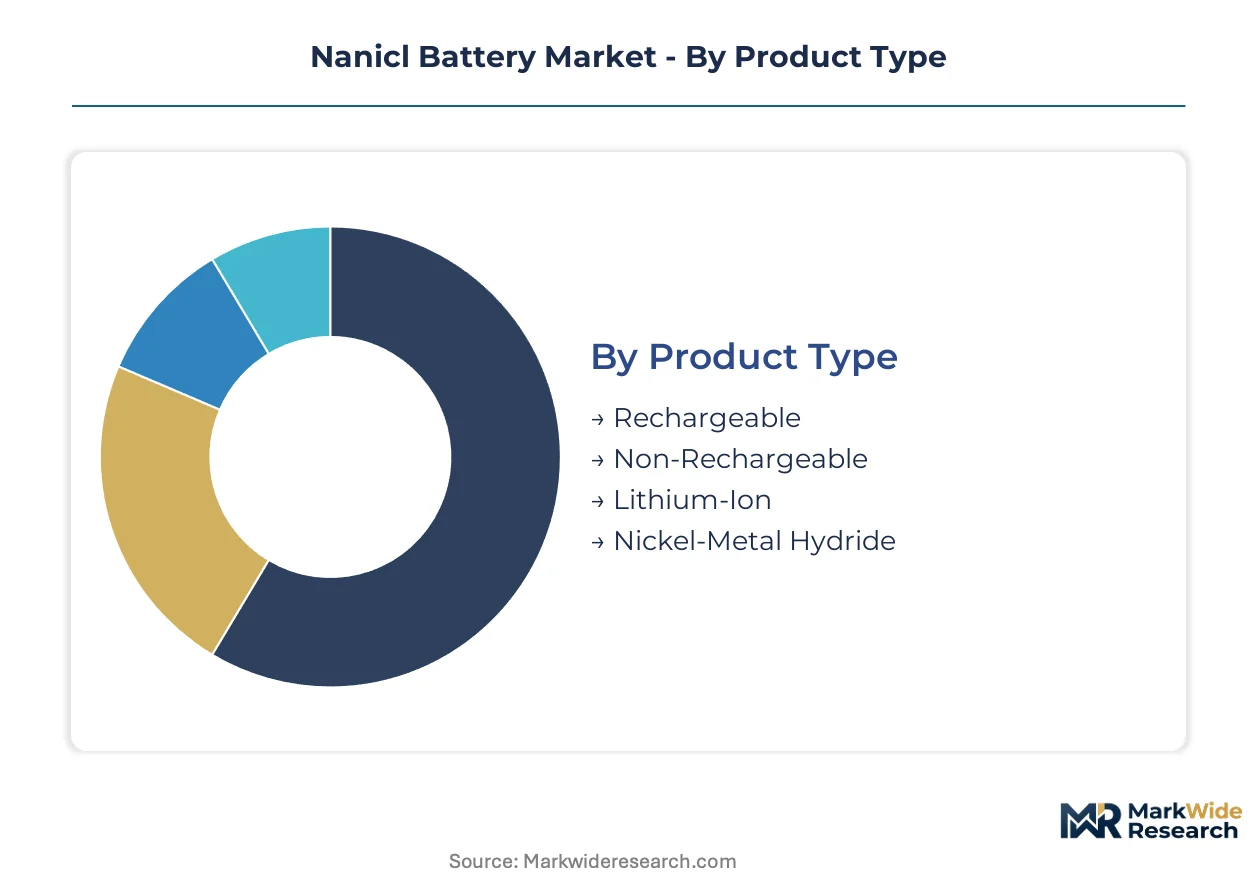
Segmentation reveals how Nanicl battery procurement priorities diverge across thermal operating requirements, cycling intensity, and certification barriers. Buyers select architectures based on discharge duration needs and regulatory compliance pathways rather than energy density alone.
Product Type:
Procurement committees weight thermal management complexity against cycle life guarantees when selecting electrochemical formats.
- Rechargeable:Sodium-nickel-chloride cells with ceramic beta-alumina electrolytes enable 4,500+ deep discharge cycles at 270-350°C operating temperatures. Grid-scale storage developers in China and Japan favor these for photovoltaic smoothing contracts requiring 20-year service life.
- Non-Rechargeable:Primary cell architectures deliver stable voltage output across extreme temperature ranges without thermal conditioning overhead. Military and aerospace applications in Germany and France absorb volume despite premium unit economics.
- Lithium-Ion:Competing chemistry with established manufacturing scale and ambient-temperature operation.
- Nickel-Metal Hydride:Mature technology occupying hybrid vehicle auxiliary power niches with lower energy density.
Rechargeable formats lead on scale; non-rechargeable variants lead on margin stability.
End User:
Application-specific duty cycles determine thermal subsystem specifications and warranty structuring.
- Automotive:Electric bus and commercial vehicle fleets in India leverage rapid-charge tolerance for depot-based operations. CEA mandates for renewable energy storage obligation compliance are accelerating sodium-ion demonstrations in state transport utilities.
- Industrial:Forklift motive power and stationary backup systems absorb high-volume orders from manufacturing clusters. METI-directed R&D consortia in Japan prioritize ceramic-electrolyte durability for factory automation resilience.
- Consumer Electronics:Limited adoption due to thermal management bulk and startup energy requirements.
- Medical Devices:Stable procurement from implantable and portable diagnostic equipment makers with stringent certification barriers.
Industrial applications anchor current revenue; automotive deployments are expanding most quickly.
Capacity:
System integrators specify energy content tiers based on discharge duration requirements and footprint constraints.
- High Capacity:Multi-megawatt-hour configurations for utility-scale renewable integration dominate tender volumes. German and French long-duration storage developers prioritize these for evening peak shaving with verified lifecycle assessments.
- Ultra High Capacity:Containerized systems exceeding 10 MWh enable transmission-deferral projects. Indian grid operators specify these under PLI scheme incentives for domestic assembly.
- Medium Capacity:Commercial and industrial behind-the-meter installations with 2-4 hour discharge profiles.
- Low Capacity:Telecom backup and remote monitoring applications with intermittent cycling needs.
High capacity segments dominate capital deployment; ultra high capacity systems show steepest expansion trajectory.
Manufacturing Stage:
Supply chain positioning determines margin capture and technical risk allocation across production phases.
- Raw Material Processing:High-purity alumina and nickel sulfate refining concentrates in East Asian chemical processing hubs. MIIT governance of GB standards for precursor quality shapes procurement specifications for ceramic electrolyte sintering.
- Component Assembly:Beta-alumina electrolyte fabrication and cathode formation require specialized high-temperature infrastructure. Japanese ceramic expertise from NGK Insulators anchors solid-electrolyte production capacity.
- Final Assembly:Cell stacking, hermetic sealing, and thermal subsystem integration.
- Quality Testing:UN 38.3 transportation validation and IEC 62619 industrial safety certification.
Raw material processing commands upstream value; component assembly concentrates technical differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting ceramic-electrolyte cell production toward jurisdictions with streamlined thermal safety certification pathways and state-backed procurement quotas. Manufacturers migrate to markets where MIIT-style production incentives offset elevated sintering infrastructure costs.
China
Dual carbon mandates under MIIT direction are accelerating sodium-ion chemistry investments across Jiangsu and Zhejiang manufacturing corridors. State-backed utility procurement quotas for non-lithium storage systems are redirecting capital toward beta-alumina electrolyte fabrication. Ningbo and Suzhou industrial clusters concentrate precursor chemical processing adjacent to gigawatt-scale cell assembly facilities.
Japan
METI-directed R&D consortia prioritize ceramic-electrolyte durability for grid-scale renewable integration contracts. JIS certification pathways for high-temperature electrochemical systems are streamlining market entry for solid-state sodium architectures. Nagoya and Osaka metropolitan areas anchor specialized sintering expertise and hermetic sealing infrastructure.
Germany
EU Battery Regulation carbon footprint disclosure mandates are advantaging chemistries with established ceramic-electrolyte recycling pathways. Long-duration storage developers in Bavaria and North Rhine-Westphalia prioritize vendors with verified lifecycle assessments for evening peak shaving projects. Industrial safety validation under IEC frameworks is concentrating procurement around integrated system providers.
India
Central Electricity Authority renewable energy storage obligation compliance is creating first-mover advantages for sodium-ion technology demonstrations. PLI scheme incentives support localized cell assembly in Gujarat and Maharashtra manufacturing zones. State transport utilities in Delhi and Bangalore are deploying rapid-charge tolerant systems for electric bus depot operations.
United States
Data center backup power procurement favors electrochemical systems with sub-second response times for uninterruptible power supply integration. Prussian blue cathode variants are penetrating hyperscale facility resilience contracts in Northern Virginia and Phoenix metro clusters. FERC interconnection queue reforms are accelerating transmission-deferral project development for containerized storage configurations.
Nanicl Battery Market Competitive Landscape
Capacity expansion dominates the current landscape as developers race to secure beta-alumina electrolyte sintering infrastructure ahead of utility-scale tender deadlines. The vendor base stratifies across three tiers: integrated ceramic specialists with captive supply chains, industrial battery incumbents diversifying into sodium chemistry, and venture-backed pure-plays commercializing Prussian blue architectures. Geographic clustering concentrates technical differentiation in East Asian manufacturing corridors. Competitive intensity centers on thermal management subsystem integration capabilities and 20-year performance guarantee structuring.
Within the ceramic-specialist tier, NGK Insulators anchors solid-electrolyte production capacity leveraging Nagoya-based sintering expertise. Saft Groupe and Natron Energy exemplify contrasting strategic positions: the former occupying long-duration industrial storage through specialized portfolio depth, the latter targeting rapid-cycling data center applications with differentiated cathode chemistry. These three entities collectively represent the spectrum of thermal operating regimes and end-use specializations currently contesting procurement committees.
| Leading Market Players |
|---|
| NGK Insulators |
| Saft Groupe |
| FIAMM Energy Technology |
| Natron Energy |
| Faradion |
| Altris AB |
| HiNa Battery Technology |
| Aquion Energy |
| FZ Sonick |
| Others |
Pricing and Supply Chain Analysis
EU Battery Regulation carbon footprint disclosure mandates gate qualified supply for premium-tier Nanicl battery contracts, forcing ceramic-electrolyte manufacturers to document precursor extraction through cell assembly before accessing utility-scale procurement committees in Germany and France.
Pricing Analysis
Distributor margins for ceramic beta-alumina electrolyte cells compress pricing stratification across premium, standard, and economy tiers based on JIS certification level and thermal cycling warranty duration. Cost compression in standard-tier cells is intensifying because iron-based cathode alternatives from competing sodium-ion developers undercut nickel-chloride architectures on materials cost. Data center backup buyers exhibit lowest price sensitivity due to sub-second response requirements, while Indian state transport utilities face acute budget constraints under CEA renewable storage mandates.
Supply Chain Analysis
Workforce availability for high-temperature sintering and hermetic sealing expertise concentrates in Nagoya and Osaka metropolitan areas, feeding from China's Jiangsu and Zhejiang chemical processing corridors for high-purity alumina and nickel sulfate refining. Single-source vulnerability for battery-grade ceramic beta-alumina electrolyte production creates chokepoint risk given limited qualified sintering infrastructure alternatives. Distribution runs through integrated system providers offering turnkey engineering-procurement-construction contracts to Japanese and South Korean utility tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Nanicl battery market reads as a late-cycle quality story where grid-scale procurement committees now prioritize 20-year thermal cycling guarantees over capital cost per kilowatt-hour, reflecting demand-shift toward premium solid-electrolyte specifications.
For Market Incumbents: Deepen captive control over beta-alumina sintering capacity in Nagoya manufacturing corridors to defend against iron-based cathode substitution threats from venture-backed sodium-ion pure-plays. Prioritize IEC 62619 certification investment for high-temperature operation protocols before UN 38.3 transportation testing timelines extend competitive gaps. For New Entrants and Emerging Players: Direct-to-utility digital procurement platforms offer lowest-friction entry for Prussian blue cathode variants targeting rapid-cycling data center backup contracts in Northern Virginia and Phoenix metro clusters. India's PLI scheme incentives for Gujarat and Maharashtra cell assembly represent the most penetrable geography for first-mover sodium-ion technology demonstrations. For Investors and Strategic Acquirers: Valuations sit cheapest among ceramic-electrolyte specialists with stranded sintering assets and established METI-directed R&D consortia relationships. Long-term viability over the coming decade hinges on solid-state manufacturing skill gap resolution and thermal safety certification standardization. Monitor FERC interconnection queue reform implementation for transmission-deferral project acceleration signals.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Electrolyte Capacity Expansion | NGK Insulators leverages Nagoya sintering expertise to anchor solid-state production for grid-scale deployments. |
| Backward Integration into Precursor Processing | Ningbo and Suzhou industrial clusters concentrate high-purity alumina refining adjacent to gigawatt-scale cell assembly. |
| Thermal Safety Certification Investment | IEC 62619 validation and UN 38.3 testing streamline market entry for high-temperature sodium-ion architectures. |
| Long-term Utility offtake Agreements | Japanese and South Korean procurement committees consolidate around 15-year performance guarantee structures. |
| Joint Venture for Localized Assembly | India's PLI scheme supports Gujarat and Maharashtra manufacturing zones under CEA renewable storage mandates. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with ceramic electrolyte fabrication engineers, utility planning officers at grid operators, EPC contractors for long-duration storage projects, and procurement leads at hyperscale data center operators with secondary validation through MIIT GB standard filings, METI R&D consortium disclosures, FERC interconnection queue data, and EU Battery Regulation carbon footprint accounting protocols. Bottom-up cell production capacity estimates and top-down utility tender volume analysis were triangulated for cross-verification.
Historical reference periods anchored the projection horizon to observed deployment cycles across prior renewable integration waves and industrial battery replacement timelines. Segmentation modeling incorporated product type differentiation between rechargeable and non-rechargeable formats, end-use verticals spanning automotive and industrial applications, capacity tiers from commercial behind-the-meter to transmission-deferral scale, and manufacturing stage positioning from raw material processing through final assembly. CAGRs were derived from fitted growth curves calibrated to state-backed procurement quota announcements and sintering infrastructure expansion timelines.
The model assumes a particular technology adoption path favoring ceramic-electrolyte architectures over iron-based cathode alternatives; accelerated cost reduction in competing sodium-ion chemistries would alter the outlook substantially. Forecasts reflect assumptions about thermal safety certification standardization timelines and workforce development pacing for high-temperature sintering expertise. Practitioners should monitor nickel sulfate price volatility and iron-based cathode pilot project announcements for early signals of substitution pressure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Battery Swapping Market
Batteries
Home Inverter Battery Market
Batteries
Europe Lead-Acid Battery Market
Batteries
North Africa Battery Market
Batteries
Watch Battery Market
Batteries
Global Coke Oven Batteries Market
Batteries
Asia-Pacific Battery Market
Batteries
Europe Battery Cell Market
Batteries
ASEAN Countries Electric Vehicle Battery Electrolyte Market
Batteries
Modular Battery Market
Batteries
India Rechargeable Battery Market
Batteries
Battery Plate Market
Batteries
48 Volt Battery System Market
Batteries
Middle-East and Africa Battery Cell Market
Batteries
Europe Battery Market
Batteries
Li-Mno2 Button Battery Market