
 Europe Battery Systems for Electric Vehicles Market | 2026-2036
Europe Battery Systems for Electric Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Battery Systems for Electric Vehicles Market Foresight
A shift from single-source Asian supply to multi-source regional procurement is restructuring how European automakers secure battery capacity. Northvolt AB anchors Sweden's emerging cell manufacturing corridor with in-house cathode production. LG Energy Solution competes through its Polish gigafactory network, while Samsung SDI leverages differentiated cylindrical cell architectures for premium German OEM programs.
Europe battery systems for electric vehicles integrate electrochemical cells, thermal management hardware, and power electronics into a unified energy storage platform, typically operating at 400–800 volts to deliver traction power for passenger and commercial vehicles. Lithium-ion chemistry dominates installed capacity, though solid-state formats are attracting R&D investment for their energy density potential. Fast Charging technology leads deployment among infrastructure-facing segments, while Battery Management Systems concentrate margin pools through software-defined safety and cycle-life optimization. Extended Range capacity configurations are gaining share among fleet operators seeking to minimize downtime on long-haul routes.
The EU Green Deal and REACH framework mandate carbon footprint disclosure and restricted substance compliance across the battery value chain, forcing pack producers to document lifecycle emissions and material provenance. EMA and national regulators in Germany and France are aligning clinical-grade safety assessments with automotive battery standards for emerging solid-state chemistries. Stakeholders must monitor how the EU AI Act and forthcoming battery passport requirements reshape data architecture and supplier qualification protocols.
Market Dynamics
The EU Green Deal's carbon border adjustment mechanism is forcing pack producers to restructure supply chains around documented lifecycle emissions, transforming procurement from cost-based to provenance-verified sourcing.
Growth Catalysts
- EU Battery Passport Mandate:Digital product passports will trace material origin and carbon footprint across the value chain, creating compliance-driven replacement cycles for legacy packs.
- Fast Charging Infrastructure:Deployment of 350kW+ highway charging networks in Germany and France is pulling demand for 800-volt architectures and thermal-optimized cell formats.
- Poland Cell Manufacturing Corridor:Concentration of gigafactory investments near Wrocław and Poznań is shortening lead times for European OEM assembly programs.
Market Restraints
- Lithium Price Volatility:Spodumene and lithium hydroxide contract pricing swings are compressing cathode producer margins and destabilizing pack cost forecasts.
- Asian Cathode Concentration:Over 70% of NCM precursor refining capacity remains concentrated in China, exposing European cell makers to supply disruption and tariff exposure.
- Solid-State Technical Limitations:Dendrite suppression and ceramic electrolyte manufacturing yield rates remain below commercial viability thresholds for automotive-scale deployment.
Strategic Opportunities
- Eastern European Underpenetration:Romania and Bulgaria currently host minimal EV assembly capacity, creating first-mover advantages for localized pack production serving southeast European markets.
- Battery-as-a-Service Models:Fleet operators in long-haul trucking are piloting subscription-based energy services that separate asset ownership from utilization, opening recurring revenue streams.
- Critical Raw Materials Act:EU domestic recycling quotas and strategic stockpiling incentives are accelerating investment in hydrometallurgical recovery facilities for lithium, nickel, and cobalt.
Industry Challenges
- Electrochemical Engineering Talent Gap:European universities produce insufficient cell design and thermal simulation specialists relative to gigafactory hiring targets in Sweden and Germany.
- REACH Compliance Timelines:Substance of very high concern assessments for novel electrolyte additives are extending qualification cycles by 18-24 months versus Asian competitors.
- Legacy Vehicle Integration Complexity:Retrofitting 400-volt platforms to accept 800-volt fast-charge architectures requires complete redesign of power electronics and thermal loops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Battery Systems for Electric Vehicles Market |
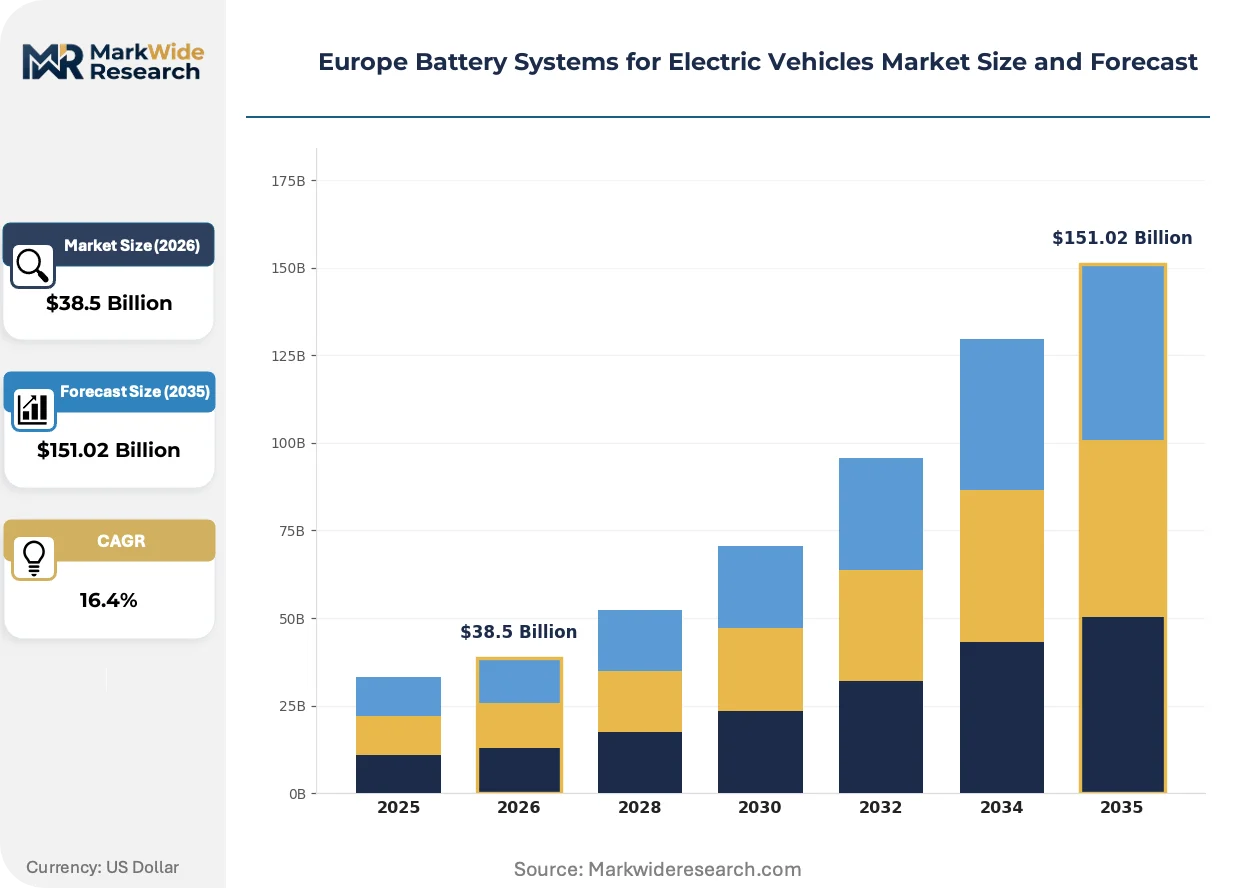
| Market Size in 2026 | $38.5 Billion |
| Market Size in 2035 | $151.02 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Nickel-metal Hydride, Solid-state End User: OEMs, Aftermarket Providers, Fleet Operators, Charging Infrastructure Technology: Fast Charging, Wireless Charging, Battery Management System, Recycling Technology Capacity: Standard Range, Extended Range, Ultra-high Capacity, Custom Solutions |
| Companies Covered | LG Energy Solution, Panasonic Holdings Corporation, Samsung SDI, Northvolt AB, CATL, Robert Bosch GmbH, Continental AG, SK Innovation, BYD Europe, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Battery Systems for Electric Vehicles Market Shifts & Advancements
Solid-state cell formats and software-defined battery management are converging to redefine energy density and safety benchmarks. These shifts are compressing development cycles and forcing capital reallocation across the supplier base.
Silicon-anode chemistries are absorbing graphite capacity in premium passenger vehicle programs. BMW and Mercedes-Benz sourcing teams have qualified silicon-oxide blends for 2026 model year platforms. This absorption is compressing traditional graphite anode demand in the high-performance segment while pulling investment into silicon deposition equipment.
REACH framework amendments are mandating perfluorinated substance restrictions in electrolyte formulations. Cell producers must reformulate wetting agents and separator coatings by 2027. Polish and German manufacturing sites face the steepest reformulation costs given their NCM chemistry concentrations.
Fleet procurement teams are consolidating supplier relationships around vertically integrated pack producers capable of cell-to-pack delivery. Long-haul trucking operators in the Netherlands and Belgium now require single-source accountability for cycle life warranties. This concentration is marginalizing module-tier suppliers lacking in-house cell production.
Europe Battery Systems for Electric Vehicles Market Segmentation
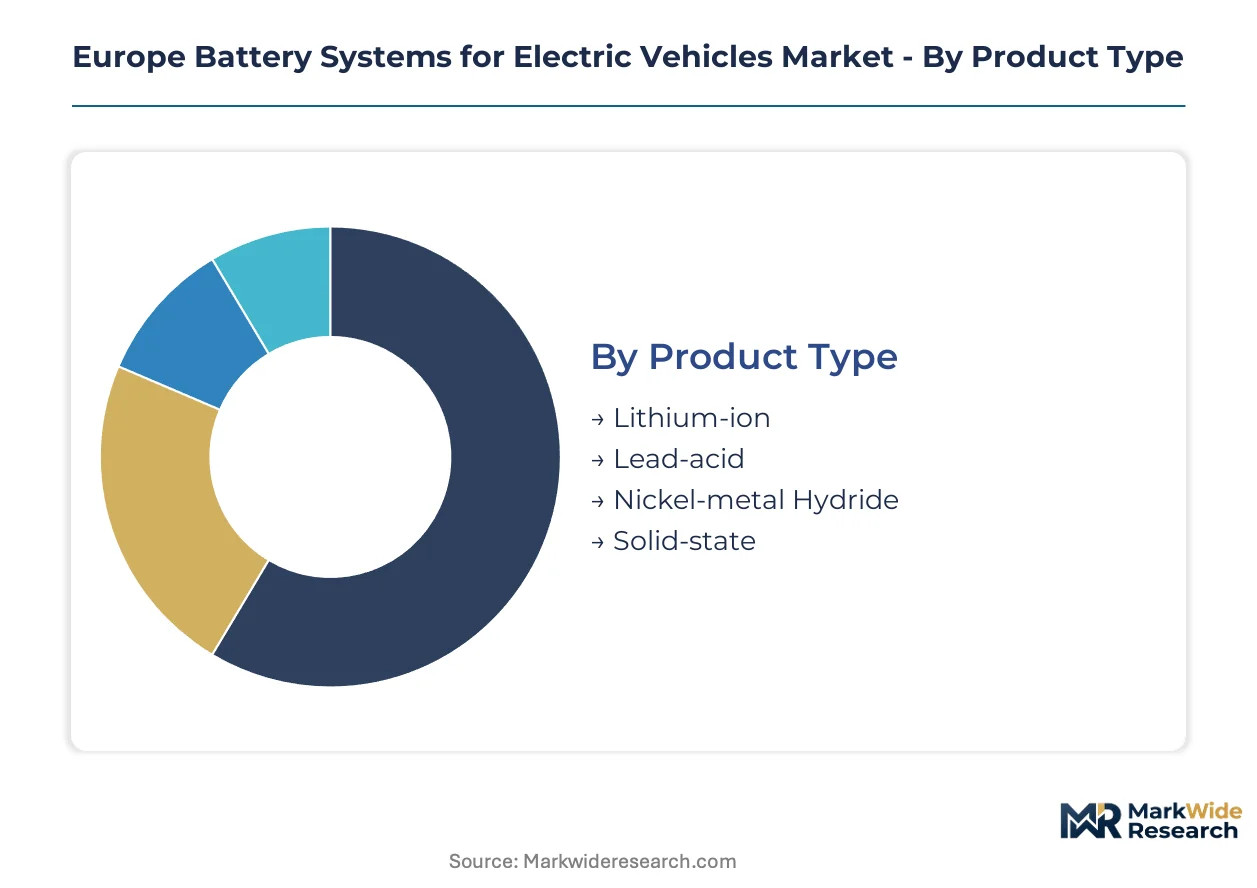
European automakers source battery systems through distinct procurement channels shaped by vehicle platform voltage, fleet utilization intensity, and regulatory compliance tiers. Segmentation reveals where margin pools concentrate and which technology transitions command capital allocation across cell chemistry, thermal architecture, and power electronics integration.
Product Type:
OEM sourcing teams differentiate chemistries primarily by energy density requirements and thermal stability thresholds for 400-volt versus 800-volt platforms.
- Lithium-ion:NCM and LFP formulations dominate installed capacity across European passenger vehicle programs. German OEM assembly lines in Stuttgart and Munich pull cylindrical and prismatic cell formats for premium sedan and SUV platforms, with Poland's gigafactory corridor supplying regional pack integration.
- Solid-state:Ceramic electrolyte architectures promise energy density gains above 400 Wh/kg once manufacturing yields stabilize. French and German pilot lines are qualifying sulfide-based cells for 2030 model year platforms, though dendrite suppression remains unresolved at automotive scale.
- Lead-acid:Auxiliary power units in commercial vehicle starter systems retain niche demand. Bulgarian and Romanian aftermarket distributors stock flooded and AGM variants for legacy truck fleets.
- Nickel-metal Hydride:Toyota-sourced hybrid programs in France and the UK sustain limited procurement volumes for mild-hybrid architectures transitioning to full electrification.
Volume sits with Lithium-ion; growth tilts toward Solid-state.
End User:
Procurement authority and warranty accountability diverge sharply between vehicle manufacturers owning design specifications and third parties managing asset utilization.
- OEMs:Volkswagen, Stellantis, and BMW Group dictate cell form factor, thermal interface, and BMS software architecture through direct supplier contracts. Their technical service bulletins cascade qualification requirements to tier-two pack assemblers.
- Fleet Operators:Dutch and Belgian long-haul trucking consortia negotiate cycle-life guarantees and residual value clauses separately from vehicle purchase. Lease structures in Rotterdam and Antwerp now embed battery health monitoring as a service component.
- Aftermarket Providers:Independent service chains in Italy and Spain source remanufactured packs for out-of-warranty EVs, relying on diagnostic tools that interrogate CAN bus data for state-of-health verification.
- Charging Infrastructure:Ionity and Fastned specify buffer storage systems for grid-stabilized 350kW+ highway stations, procuring separate battery assets from vehicle-integrated supply chains.
Contract value concentrates with OEMs; margin expansion favors Fleet Operators.
Technology:
Technology selection tracks infrastructure availability and software integration depth rather than hardware cost alone.
- Fast Charging:800-volt architectures with active liquid cooling enable 10-80% state-of-charge cycles below 20 minutes. German highway corridor deployments along A3 and A9 routes are pulling demand for silicon-carbide inverters and enhanced thermal interface materials.
- Battery Management System:ASIL-D functional safety software optimizes cell balancing and thermal runaway detection. French engineering centers in Grenoble and Paris-Saclay concentrate firmware development talent for predictive state-of-charge algorithms.
- Wireless Charging:Inductive pad systems for fixed-route applications—airport shuttles in Amsterdam, urban delivery in Copenhagen—operate at lower power densities than conductive alternatives.
- Recycling Technology:Hydrometallurgical recovery facilities in Germany and Finland process black mass from production scrap and end-of-life packs, extracting lithium, nickel, and cobalt for cathode precursor resynthesis.
Deployment scale favors Fast Charging; R&D intensity clusters on Battery Management System.
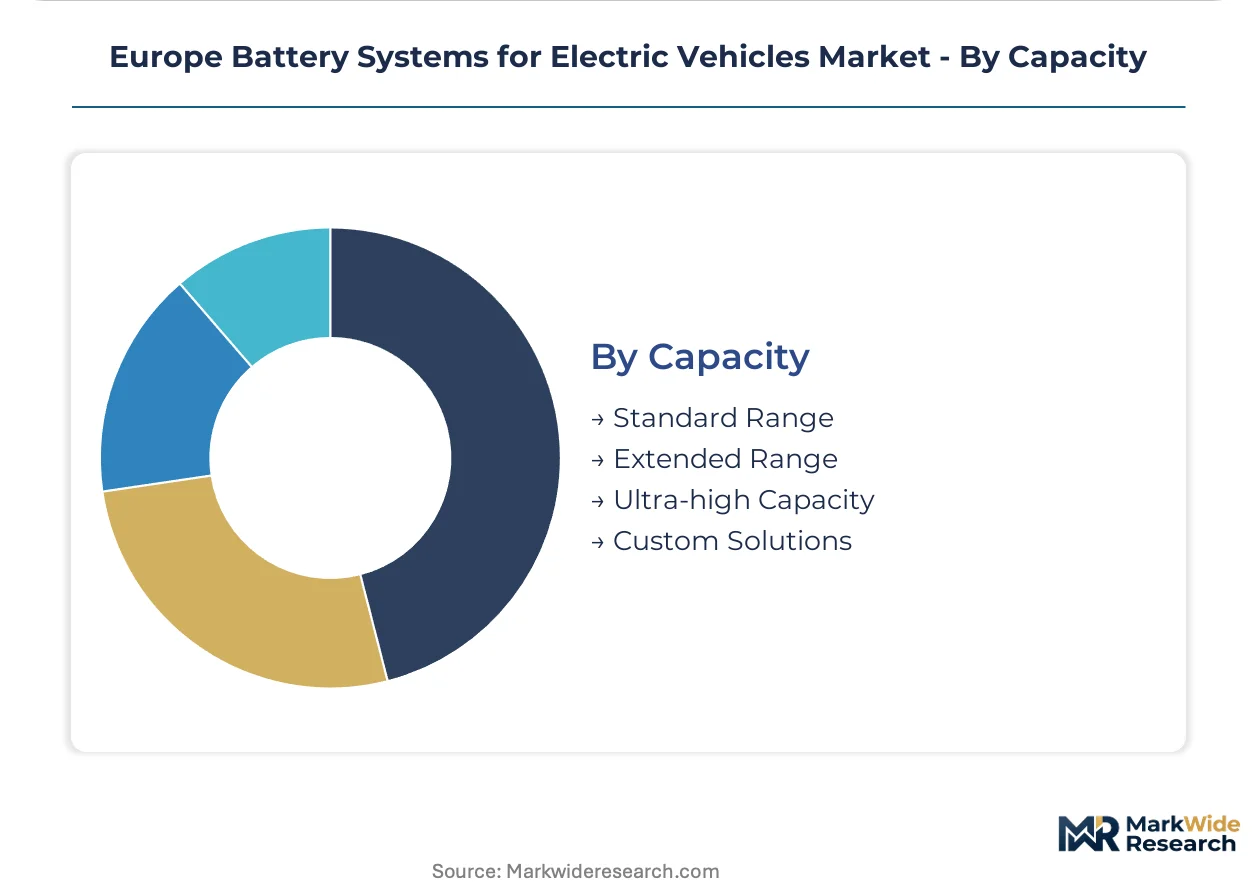
Capacity:
Range anxiety and duty cycle economics drive divergence between urban commuter specifications and commercial vehicle energy storage.
- Extended Range:100-120 kWh pack configurations serve long-haul trucking and premium passenger segments where downtime minimization justifies cell cost premiums. Swedish and German fleet operators specify these capacities for cross-border routes between Malmö and Hamburg.
- Standard Range:50-75 kWh systems satisfy urban delivery and commuter vehicle programs with predictable daily mileage. French and Italian compact vehicle platforms source these configurations for cost-sensitive market segments.
- Ultra-high Capacity:Prototype 150+ kWh architectures for heavy-duty mining and construction equipment are testing cell-to-pack thermal management at Finnish and Norwegian demonstration sites.
- Custom Solutions:Niche commercial applications—electric marine in Norway, airport ground support in Switzerland—require non-standard form factors and IP-rated enclosures outside automotive norms.
Production volume anchors Standard Range; value-per-unit climbs fastest in Extended Range.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for battery systems concentrates in Germany, Poland, and France where OEM assembly capacity and gigafactory investments cluster. National subsidy programs and EU Green Deal compliance timelines are accelerating cell and pack localization across these markets.
Germany
Volkswagen, BMW, and Mercedes-Benz assembly plants in Stuttgart, Munich, and Wolfsburg pull high-voltage pack capacity for 800-volt platforms. The KBA enforces UNECE R100 battery safety certifications for all new electric vehicle registrations. Cell-to-pack production lines in Lower Saxony and Baden-Württemberg are scaling silicon-anode qualification programs for 2026 model year releases.
Poland
LG Energy Solution and SK Innovation gigafactories near Wrocław and Poznań supply cylindrical and prismatic cells to German and Czech OEM assembly programs. Polish Investment and Trade Agency tax incentives have attracted over €10 billion in battery manufacturing commitments since 2020. The country's central European logistics position shortens lead times for Just-in-Sequence delivery to Volkswagen Bratislava and Stellantis Tychy.
France
Stellantis and Renault electrification programs in Douai and Maubeuge require localized LFP and NCM cell supply for compact and mid-size vehicle platforms. EMA clinical-grade safety assessments are being adapted for solid-state chemistry qualification through 2027. The Automotive Cells Company joint venture in Douvrin anchors a northern France battery valley with cathode active material precursor capacity under construction.
Sweden
Northvolt AB's Skellefteå gigafactory anchors Europe's first fully integrated cell and cathode production corridor. Swedish Energy Agency grants support hydropower-fed manufacturing with documented near-zero direct emissions. The company's in-house recycling facility in Västerås processes production scrap for closed-loop lithium and nickel recovery.
Netherlands
Rotterdam and Antwerp port logistics hubs concentrate inbound raw material flows for European cell producers. Dutch fleet operators pilot Battery-as-a-Service contracts for long-haul trucking routes to Germany and Belgium. The country's national charging infrastructure program mandates 350kW+ highway station deployment along A1, A2, and A4 corridors by 2026.
Europe Battery Systems for Electric Vehicles Market Competitive Landscape
Capacity expansion dominates the current landscape as Asian and European producers race to secure OEM offtake agreements. The vendor base stratifies between integrated cell-to-pack suppliers and module-tier assemblers lacking cathode production. Three archetypes occupy distinct positions: Asian scale leaders with established European manufacturing footprints, European challengers building captive supply chains, and diversified industrial conglomerates leveraging power electronics integration. Competitive intensity centers on securing qualified cell supply and qualifying for EU Battery Passport traceability requirements.
Among Asian scale leaders, LG Energy Solution and Samsung SDI represent the established manufacturing archetype with operational Polish capacity. CATL occupies a position as the volume-driven benchmark for LFP chemistry supply to European passenger programs. Northvolt AB exemplifies the European challenger model with integrated cathode production and recycling capabilities in Sweden.
| Leading Market Players |
|---|
| LG Energy Solution |
| Panasonic Holdings Corporation |
| Samsung SDI |
| Northvolt AB |
| CATL |
| Robert Bosch GmbH |
| Continental AG |
| SK Innovation |
| BYD Europe |
| Others |
Supply & Pricing Matrix
Fleet procurement consolidation around Battery-as-a-Service contracts in the Netherlands and Belgium is forcing pack producers to absorb residual value risk and restructure pricing models toward subscription-based recurring revenue streams.
Pricing Analysis
Volume anchors standard-range LFP packs for compact passenger platforms while margin concentrates in extended-range NCM configurations for premium German OEM programs. Price differentiation rests on certification tier—packs qualified for EU Battery Passport traceability command premiums over legacy undocumented supply. Cost compression in standard-range segments is intensifying because cathode producers face lithium hydroxide contract volatility. Fleet operators exhibit highest price sensitivity due to total-cost-of-ownership calculations, while premium passenger OEMs prioritize energy density and fast-charge capability over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Chinese NCM precursor refining capacity, where over seventy percent of global output feeds European cell production. Raw material flows draw from Australian spodumene, Chilean lithium brine, and Indonesian nickel laterite. Tariff exposure on cathode active materials threatens margin stability for Polish and German gigafactory operations. Distribution runs through Rotterdam and Antwerp port logistics hubs for inbound raw materials, with Just-in-Sequence rail links to Stuttgart, Munich, and Wolfsburg assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Battery Passport mandate operates as a cost-of-compliance moat, favoring incumbents with documented supply chain provenance and capital reserves to retrofit legacy pack architectures before the regulatory deadline.
For Market Incumbents: Cement qualification advantages by securing ECHA-compliant cathode precursor supply before REACH substance restrictions tighten. Prioritize backward integration into hydrometallurgical recycling to lock in domestic lithium and nickel recovery capacity. The threat of solid-state chemistry disruption from Asian R&D programs demands accelerated pilot line investment in sulfide electrolyte manufacturing.
For New Entrants and Emerging Players: Capture aftermarket service contracts for out-of-warranty EV fleets in Italy and Spain where diagnostic capabilities and remanufacturing expertise remain fragmented. Eastern European pack assembly—Romania and Bulgaria specifically—offers first-mover positioning with lower labor costs and proximity to southeast European markets. A go-to-market angle anchored to EU Battery Passport compliance-as-a-service can differentiate against undocumented Asian imports.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated cell-to-pack producers with captive cathode production and recycling capabilities. Long-term viability hinges on securing qualified supply relationships with European OEMs before offtake agreements harden around incumbent players. Watch solid-state manufacturing yield rates as the inflection signal—commercial-scale sulfide electrolyte production will reshape competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Passport Compliance Investment | EU regulatory deadlines force documentation infrastructure spend ahead of competitor qualification. |
| Cathode Precursor Backward Integration | Swedish and German producers secure supply independence from Chinese refining concentration. |
| Hydrometallurgical Recycling Scale-Up | Finnish and German facilities extract lithium and nickel from production scrap for closed-loop resynthesis. |
| 800-Volt Platform Fast-Charge Partnership | German highway corridor deployments along A3 and A9 routes pull silicon-carbide inverter demand. |
| Solid-State Pilot Line Qualification | French and German sulfide electrolyte programs target 2030 model year platform integration. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Europe battery systems analysis. Primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, gigafactory operations managers, and fleet operator sustainability directors cross-validated capacity expansion timelines and offtake contract structures. ECHA substance restriction databases, KBA vehicle registration records, and EU customs trade flows provided demand-side calibration. Bottom-up cell production capacity estimates triangulated against top-down vehicle electrification targets from the European Automobile Manufacturers Association.
Production volume data from vehicle registration databases reconciled with cathode active material trade flows and gigafactory equipment procurement disclosures across the analysis window. Segmentation modeling incorporated chemistry type, voltage architecture, end-user procurement authority, and regional manufacturing cluster. CAGRs derived from fitted adoption curves weighted by EU Green Deal compliance timelines and national subsidy program durations. Forecast inputs included silicon-anode qualification progress, solid-state manufacturing yield trajectories, and REACH reformulation cost estimates for electrolyte additives.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to solid-state chemistry breakthroughs, lithium contract pricing volatility, and EU Battery Passport implementation enforcement. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
UAV Battery Pack Market
Batteries
Aluminum Based Battery Market
Batteries
West Africa Battery Market
Batteries
Global Electric Scooter Batteries Market
Batteries
Wide Temperature Battery Market
Batteries
Taiwan Battery Market
Batteries
High Voltage Battery Market
Batteries
Asia-Pacific Consumer Battery Market
Batteries
Portable Battery Station Market
Batteries
USA Forklift Battery Market
Batteries
Automotive Start-Stop Battery Market
Batteries
Stretchable Battery Market
Batteries
India Battery Cell Market
Batteries
Bio Based Battery Market
Batteries
Australia Battery Market
Batteries
United States Household Battery Market