
 Australia Oil and Gas Midstream Market | 2026-2036
Australia Oil and Gas Midstream Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Oil and Gas Midstream Market Outlook
Asian LNG import dependence is repositioning Australian midstream capacity toward marine terminals and deepwater export channels. Woodside Energy Group Ltd. anchors the North West Shelf infrastructure network through long-dated offtake contracts. Santos Ltd. leverages its Cooper Basin pipeline grid to supply eastern seaboard gas-fired power stations. APA Group dominates east-west transmission corridors with regulated asset bases spanning Queensland, South Australia, and Victoria.
Australia oil and gas midstream encompasses the transportation, storage, and processing infrastructure bridging upstream extraction with downstream refining and distribution, operating at pressures between 700 and 1,440 psi in major trunk pipelines and requiring corrosion-resistant coatings for subsea segments. Pipeline service types carry the largest installed base but face margin compression from regulated tariff reviews, while marine transportation segments capture premium returns from LNG carrier scheduling and floating storage offloading. Processing plants represent the highest capital intensity per tonne of throughput, with cryogenic treatment and acid gas removal units commanding extended payback periods.
NOPSEMA enforces offshore facility integrity standards that dictate inspection intervals and emergency response capabilities across Bass Strait and Browse Basin assets. TGA hazardous materials protocols intersect with pipeline construction codes in populated corridors, elevating compliance costs for cross-state projects. Stakeholders must weigh brownfield expansion against greenfield regulatory timelines when committing capital to hydrogen-ready pipeline retrofits.
Market Dynamics
Asian LNG offtake contracts are compressing Australian midstream investment timelines, forcing operators to prioritize marine terminal capacity over onshore pipeline expansion in Queensland and Western Australia corridors.
Growth Catalysts
- North West Shelf export corridor concentration:Deepwater infrastructure near Karratha and Dampier channels Asian buyer demand into long-dated throughput commitments. Floating production storage and offloading vessels reduce greenfield development risk.
- NOPSEMA facility integrity mandates:Offshore inspection protocols accelerate replacement cycles for subsea risers and flowlines. Asset owners deploy remotely operated vehicles to satisfy annual structural assessment requirements.
- Carbon capture readiness clauses:New pipeline construction codes in Western Australia require CO2-compatible metallurgy and compression station footprints. Engineering contractors stockpile hydrogen-ready valve specifications.
Market Restraints
- Specialized vessel charter rate volatility:LNG carrier day-rates swing with Asian spot market liquidity. Project developers delay final investment decisions when shipping cost projections exceed 15% of delivered cargo value.
- Browse Basin supply concentration:Three upstream consortia control 80% of undeveloped gas reserves. Pipeline tariff negotiations lack competitive tension.
- Acid gas removal unit complexity:High-CO2 feedstock from Cooper Basin fields requires amine treatment trains that extend commissioning timelines by 18-24 months.
Strategic Opportunities
- Pilbara hydrogen export corridor:Renewable ammonia projects near Port Hedland demand repurposed gas pipelines and cryogenic loading arms. State government funding rounds favor brownfield conversion over greenfield hydrogen infrastructure.
- East coast LNG import terminal gap:New South Wales and Victorian gas-fired generators face pipeline capacity constraints during winter peak demand. Floating storage regasification units offer 36-month deployment timelines versus 7-year onshore builds.
- Digital twin integration:Real-time pipeline integrity monitoring converges with predictive corrosion modeling. Operators in Queensland's Surat Basin reduce unplanned outage frequency through sensor fusion.
Industry Challenges
- Subsea welding certification backlog:NOPSEMA-qualified hyperbaric welders number fewer than 120 nationally. Project schedules slip 4-6 months waiting for inspection-qualified crews.
- Cross-state environmental approval sequencing:Queensland's Coordinator-General and Western Australia's EPA run parallel but uncoordinated assessment tracks. Developers file duplicate heritage and groundwater studies.
- Legacy SCADA system integration:1980s-era pipeline control networks in the Cooper Basin resist API 1164 cybersecurity upgrades. Replacement requires 48-hour flow interruptions that power station offtakers reject.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Oil and Gas Midstream Market |
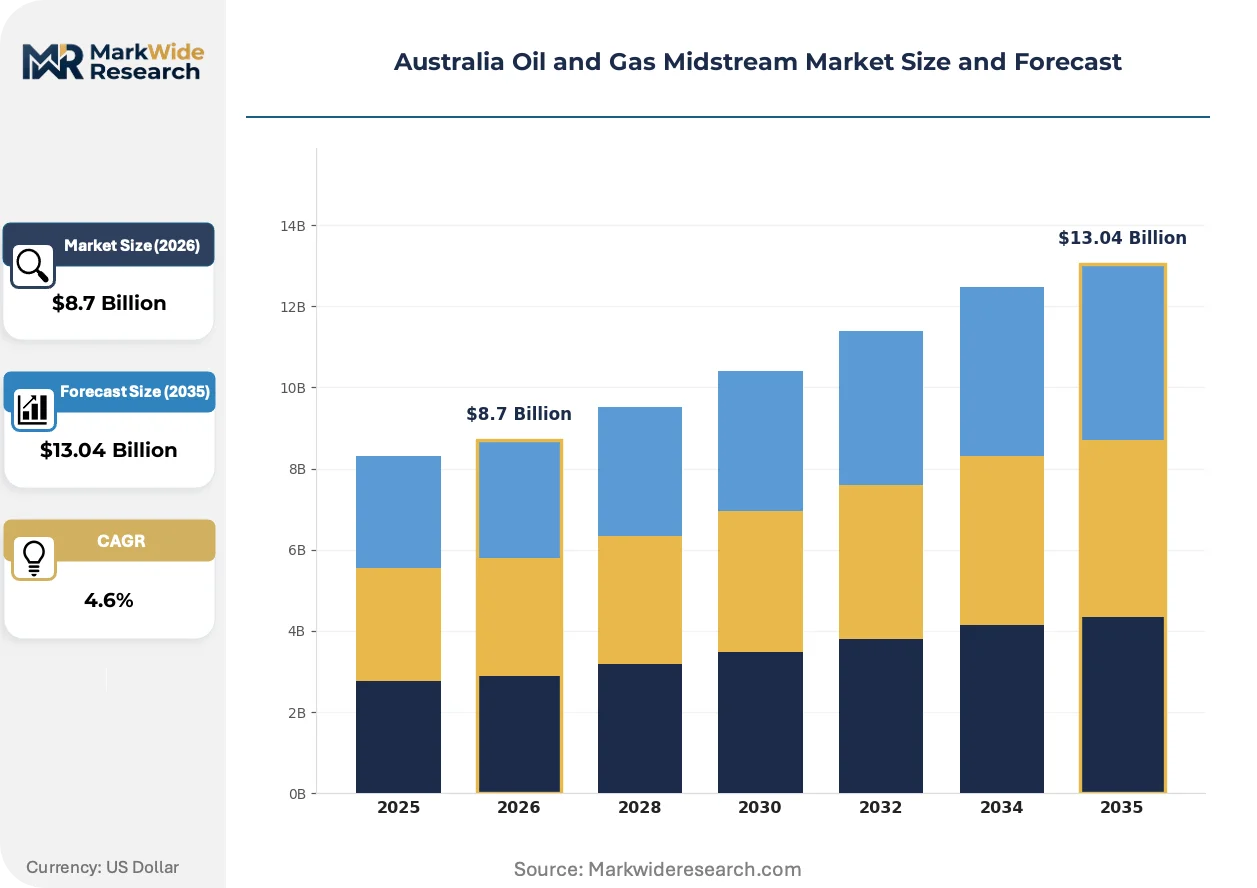
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Pipelines, Storage Facilities, Processing Plants, Marine Transportation End User: Energy Traders, Utilities, Oil Companies, Refineries Technology: Flow Measurement, Liquid Extraction, Compressor Systems, Leak Detection Capacity: Small Scale, Medium Scale, Large Scale, Mega Projects |
| Companies Covered | APA Group, Shell Australia Pty Limited, Santos Ltd., Chevron Australia Pty Ltd., Woodside Energy Group Ltd., INPEX Corporation, Beach Energy Limited, Origin Energy Limited, SGSP (Australia) Assets Pty Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Oil and Gas Midstream Market Strategic Shifts
Modular processing architectures and predictive maintenance platforms are compressing capital deployment cycles across Australian midstream corridors. Regulatory pressure on methane intensity is accelerating technology substitution.
Standardized skid-mounted gas treatment packages are modularizing field development economics in the Surat Basin. Unconventional gas producers deploy 50-MMSCFD units on 18-week delivery schedules versus 24 months for stick-built plants. This compression is modularizing how junior operators sequence field expansion, reducing upfront capital exposure and enabling phased reserve commitment.
TGA hazardous materials transport protocols now mandate real-time temperature and pressure telemetry for LNG road tankers serving remote Western Australia mine sites. Fleet operators retrofit satellite-linked data loggers to satisfy 15-minute reporting intervals. The regulation most affects Cooper Basin-to-Port Adelaide corridors, where carriers consolidate loads to minimize trip frequency under stricter driver hour limits.
Power station buyers in Victoria and New South Wales now unbundle firm transportation from commodity supply, contracting pipeline capacity separately through APA Group's auction platform. This procurement fragmentation displaces traditional bundled gas sales agreements. The shift concentrates price discovery in Queensland's Wallumbilla hub, where daily trading volumes now exceed 100 terajoules.
Australia Oil and Gas Midstream Market Segmentation
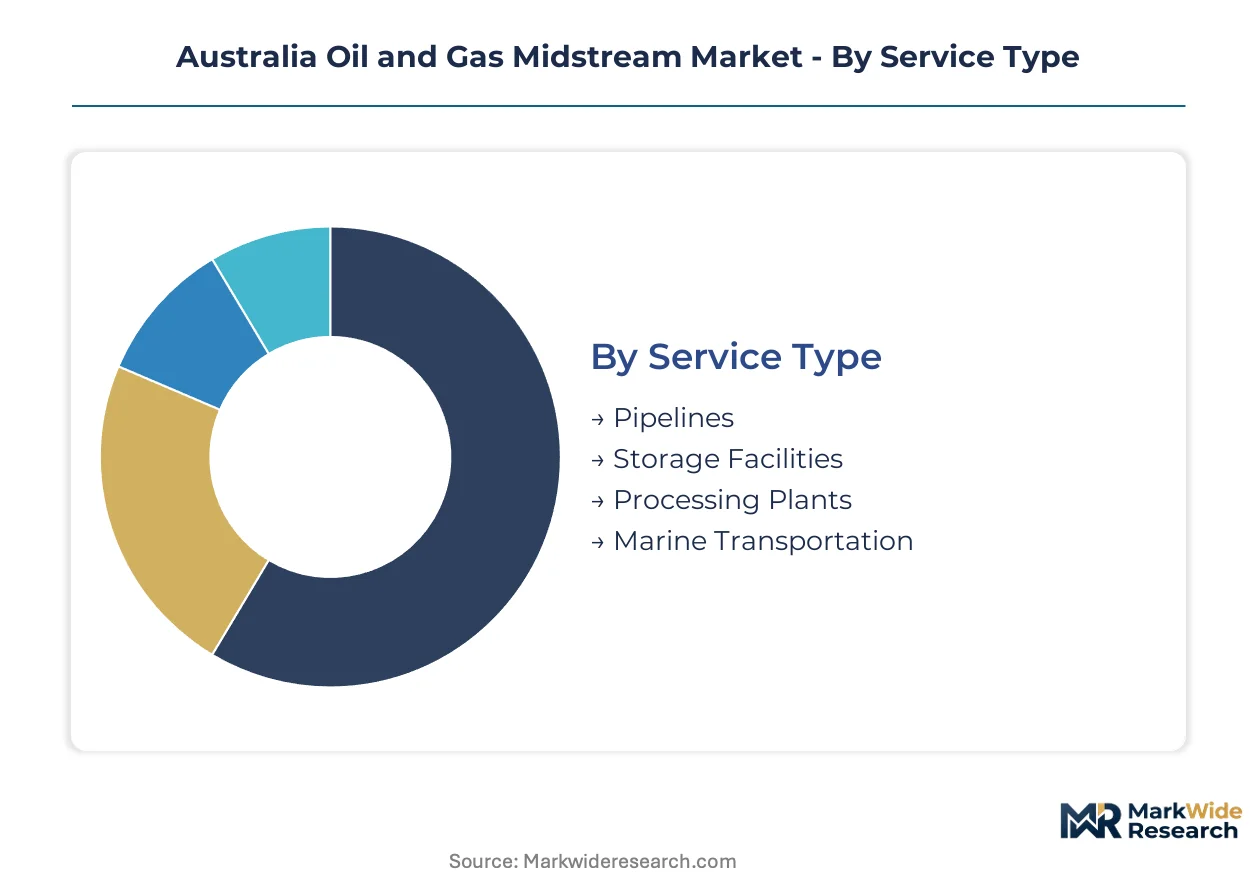
Australian midstream infrastructure segments by operational function, asset scale, and technical sophistication. Each category carries distinct capital intensity profiles and regulatory exposure across Queensland and Western Australia corridors.
Service Type:
Replacement cycles for aging infrastructure drive upgrade prioritization across all service categories, with subsea assets facing accelerated timelines under NOPSEMA integrity mandates.
- Pipelines:Steel trunk lines operating at 700-1,440 psi transport raw gas from Bass Strait and Browse Basin fields to onshore processing nodes. APA Group's east-west corridors and Santos's Cooper Basin grid dominate throughput, though regulated tariff compression limits margin expansion.
- Processing Plants:Cryogenic treatment and acid gas removal units command the highest capital intensity per tonne of throughput. Amine treatment trains for high-CO2 Cooper Basin feedstock extend commissioning timelines by 18-24 months, concentrating ownership among integrated operators with balance sheet capacity.
- Storage Facilities:Underground salt caverns and above-ground tanks buffer seasonal demand swings across eastern seaboard markets. Queensland's Surat Basin operators deploy modular storage to match unconventional production ramps.
- Marine Transportation:LNG carriers and floating storage offloading vessels link North West Shelf terminals to Asian buyers. Charter rate volatility tied to spot market liquidity forces developers to delay final investment decisions when shipping costs exceed cargo value thresholds.
Volume placements concentrate in Pipelines; the faster expansion belongs to Marine Transportation.
End User:
Customer procurement patterns fragment along risk tolerance and volume commitment horizons, with power sector buyers unbundling transportation from commodity supply.
- Utilities:Gas-fired generators in Victoria and New South Wales contract firm pipeline capacity separately through auction platforms, displacing traditional bundled agreements. Winter peak demand strains east coast infrastructure.
- Oil Companies:Integrated majors anchor long-dated offtake commitments at North West Shelf terminals, underwriting greenfield liquefaction capacity. Their balance sheets absorb construction risk that traders cannot assume.
- Energy Traders:Wallumbilla hub participants exploit daily price discovery exceeding 100 terajoules, arbitraging Queensland supply against southern demand. Short-term positioning dominates their logistics requirements.
- Refineries:Kwinana and Geelong facilities source domestic crude and condensate through dedicated pipeline corridors, with throughput declining as conversion capacity shifts to import dependence.
Contract tenors stretch longest for Oil Companies; trading volumes are climbing the fastest among Energy Traders.
Technology:
Digital infrastructure investments concentrate where sensor deployment reduces unplanned outages and satisfies tightening telemetry mandates.
- Leak Detection:Fiber-optic and acoustic monitoring systems span subsea flowlines and populated onshore corridors. Real-time alerts satisfy TGA hazardous materials protocols and reduce environmental liability exposure.
- Flow Measurement:Ultrasonic and Coriolis meters enable custody transfer accuracy for Wallumbilla hub settlements. Calibration drift in high-pressure sour gas service accelerates replacement cycles.
- Compressor Systems:Reciprocating and centrifugal units maintain pipeline pressure across Western Australia's vast distances. Hydrogen-ready metallurgy specifications now govern new procurement.
- Liquid Extraction:Joule-Thomson and mechanical refrigeration units strip condensate from wet gas streams. Modular skid-mounted packages compress field development economics in Surat Basin unconventional plays.
Deployment density peaks for Leak Detection; steepest expansion trajectory belongs to Flow Measurement as trading volumes multiply.
Capacity:
Project scale determines financing structure, with smaller assets attracting non-bank capital and mega developments requiring consortium arrangements.
- Large Scale:Integrated pipeline networks and multi-train processing facilities serve export-oriented developments. Browse Basin and Scarborough projects exemplify this tier, with three consortia controlling 80% of undeveloped reserves.
- Mega Projects:North West Shelf expansion and Pilbara hydrogen export corridors demand decade-long construction timelines and state government co-investment. Final investment decisions hinge on Asian buyer commitment.
- Medium Scale:Brownfield expansions and lateral pipeline extensions match reserve growth to infrastructure without greenfield regulatory exposure. Santos leverages this tier across Cooper Basin maturing fields.
- Small Scale:Modular treatment skids and satellite storage serve junior operators in Surat Basin coal seam gas. Fifty-MMSCFD units deploy on 18-week schedules versus 24 months for stick-built alternatives.
Capital deployment concentrates in Large Scale; Small Scale is gaining share fastest as modular architectures democratize field development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North West Shelf project area anchors midstream infrastructure concentration through Petroleum Resource Rent Tax incentives and state co-investment frameworks. Western Australia's Pilbara and Karratha-Dampier corridor channel export capacity toward Asian buyers.
Western Australia
Deepwater LNG terminals at Karratha and Dampier process Browse Basin and North West Shelf feedstock for Japanese and Chinese buyers. NOPSEMA facility integrity mandates accelerate subsea inspection cycles. The Burrup Peninsula industrial cluster hosts cryogenic treatment trains and acid gas removal units serving export markets.
Queensland
Coal seam gas from the Surat Basin feeds Curtis Island liquefaction trains and east coast domestic pipelines. The state's Coordinator-General administers parallel environmental assessments with federal EPBC Act processes. Gladstone's LNG export corridor concentrates marine terminal capacity for Asia-Pacific offtake contracts.
Victoria
Bass Strait offshore platforms supply declining reserves through subsea pipelines to Longford processing facilities. TGA hazardous materials protocols intersect with pipeline construction codes in populated Gippsland corridors. The Latrobe Valley power station cluster drives winter peak demand for firm transportation capacity.
New South Wales
Gas-fired generators at Tallawarra and Colongra face pipeline capacity constraints during winter demand peaks. The state's planning regulator assesses LNG import terminal proposals for Port Kembla. Sydney Basin industrial buyers unbundle transportation from commodity supply through Wallumbilla-linked auction platforms.
South Australia
Cooper Basin gas fields feed the Moomba processing hub and east-west transmission corridors. Santos Ltd. leverages regulated pipeline grids to supply eastern seaboard markets. The Moomba carbon capture and storage project anchors emissions reduction infrastructure for future hydrogen export corridors.
Australia Oil and Gas Midstream Market Competitive Environment
Top-tier vendors anchor integrated infrastructure networks, while mid-tier operators specialize in regional pipeline grids or modular processing units. The market exhibits tiered concentration around export corridor control and regulated transmission assets. Three archetypes dominate: integrated majors with liquefaction capacity, pure-play pipeline operators with regulated asset bases, and unconventional gas specialists with modular field development capabilities. Competitive moves center on brownfield expansion to avoid greenfield regulatory timelines and strategic positioning for hydrogen-ready infrastructure retrofits.
Among integrated operators with liquefaction exposure, Woodside Energy Group Ltd. and Santos Ltd. exemplify contrasting geographic strategies. APA Group anchors the pure-play pipeline archetype through east-west transmission corridors. These three entities represent the dominant competitive positions: export-oriented integration, regulated domestic transmission, and upstream-backed midstream development.
| Leading Market Players |
|---|
| APA Group |
| Shell Australia Pty Limited |
| Santos Ltd. |
| Chevron Australia Pty Ltd. |
| Woodside Energy Group Ltd. |
| INPEX Corporation |
| Beach Energy Limited |
| Origin Energy Limited |
| SGSP (Australia) Assets Pty Ltd |
| Others |
Value Chain & Pricing Dynamics
NOPSEMA facility integrity mandates gate qualified supply access and premium-tier pricing for subsea inspection services. Operators without certified hyperbaric welding crews face 4-6 month schedule penalties that compress margins below viable thresholds.
Pricing Analysis
Short lead-time premiums dominate LNG carrier charter negotiations, with spot-market bookings commanding substantial markups over term contracts. Contract-based long-term offtake agreements anchor North West Shelf export economics, while volume scale and certification tier differentiate pipeline tariff structures. Cost compression in regulated east-west transmission corridors intensifies as APA Group's auction platform unbundles transportation from commodity supply. Energy traders exhibit highest price sensitivity through Wallumbilla hub arbitrage, whereas integrated oil companies absorb premium pricing for firm capacity commitments.
Supply Chain Analysis
Freight cost volatility in specialized LNG vessel chartering shapes project economics across Western Australia's Karratha-Dampier corridor. Australia sources high-grade pipeline steel from Japan and South Korea, with hydrogen-ready valve specifications stockpiled by engineering contractors in anticipation of Pilbara hydrogen export corridor demand. Single-source vulnerability concentrates in NOPSEMA-qualified hyperbaric welders, numbering fewer than 120 nationally. Distribution runs through integrated operator networks that control terminal capacity allocation and marine loading schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where TGA hazardous materials protocols and NOPSEMA facility integrity mandates erect barrier-to-entry moats. Compliant operators capture premium pricing and preferential queue positioning for inspection-qualified crews.
For Market Incumbents: Anchor brownfield expansion strategies to avoid greenfield regulatory timelines that stretch 7 years for onshore LNG terminals. Prioritize hydrogen-ready pipeline retrofits in Western Australia corridors to preempt Pilbara export corridor demand. Defensive consolidation through Moomba carbon capture infrastructure integration counters emerging hydrogen specialist entrants.
For New Entrants and Emerging Players: Enter via floating storage regasification unit deployment for New South Wales and Victorian winter peak demand gaps, where 36-month timelines beat 7-year onshore construction. Target modular 50-MMSCFD gas treatment skids for Surat Basin junior operators seeking 18-week delivery schedules. Go-to-market leverage rests on digital twin integration partnerships with Queensland sensor fusion providers.
For Investors and Strategic Acquirers: Final investment decision announcements on Browse Basin developments are the leading indicator that long-dated throughput commitments will tighten available capital for competing infrastructure. Five-to-ten year viability favors regulated pipeline operators with east-west corridor control over pure-play liquefaction exposure. Acquisition focus should center on APA Group-tier transmission assets with tariff indexation protection.
| Strategic Initiative | Industry Significance |
|---|---|
| Brownfield Pipeline Conversion | Repurposed Cooper Basin infrastructure satisfies TGA protocols faster than greenfield hydrogen corridors. |
| Floating Storage Regasification Deployment | FSRU units at Port Kembla address New South Wales winter peak constraints within 36-month windows. |
| Digital Twin Platform Integration | Real-time corrosion modeling reduces Surat Basin unplanned outages below industry benchmarks. |
| Carbon Capture Infrastructure Buildout | Moomba CCS project anchors Santos emissions positioning for future hydrogen export certification. |
| NOPSEMA Certification Investment | Hyperbaric welding crew qualification secures premium pricing in subsea inspection backlogs. |
Study Parameters
Regulatory filings from NOPSEMA and TGA, Australian Bureau of Statistics energy accounts, and operator annual reports formed the secondary backbone. Primary interviews with pipeline integrity managers, LNG shipping schedulers, EPC contractors, and Queensland Coordinator-General assessment officers combined with secondary validation. Bottom-up project databases triangulated against top-down macroeconomic indicators across service type, end user, technology, and capacity segmentation dimensions.
Historical trendline analysis of petroleum production, pipeline throughput, and LNG export volumes established baseline trajectories across the projection horizon. Modeled dimensions span service type operational function, end user procurement pattern, technology deployment density, and capacity tier financing structure. CAGRs derived from regression-adjusted growth rates incorporating Asian LNG import elasticity and domestic power generation fuel-switching dynamics. Forecast inputs included Browse Basin reserve commitment timelines and Pilbara renewable ammonia project development schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Asian spot LNG price volatility and Australian federal election regulatory uncertainty. Stakeholders should weight assumptions against their own operating context and contract tenor portfolios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Casing and Cementation Hardware Market
Oil & Gas
Oilfield Drilling Elevator Market
Oil & Gas
India Oil and Gas Midstream Market
Oil & Gas
Japan LNG Bunkering Market
Oil & Gas
Latin America AI in Oil and Gas Market
Oil & Gas
South-East Asia Oil and Gas Pipeline Market
Oil & Gas
United Kingdom Oil and Gas Midstream Market
Oil & Gas
Process Simulation Software in Oil and Gas Market
Oil & Gas
Planned LNG Market
Oil & Gas
LNG Loading Skid Market
Oil & Gas
Global Deep-Well Disposal Services Market
Oil & Gas
Europe Oil and Gas Drones Market
Oil & Gas
Oil and Gas Refinery Maintenance Services Market
Oil & Gas
Subsea Flowlines Market
Oil & Gas
Asia-Pacific Liner Hanger System Market
Oil & Gas
Oriented Perforating System Market