

Mechanical and Electronic Fuzes Market Size, Share, and Industry Trends Forecast 2026-2036
Mechanical and Electronic Fuzes Market Insights
MIL-STD-1316 qualification is unwinding the competitive landscape for fuze suppliers, raising barriers for entrants without proven ordnance testing records. BAE Systems leverages decades of UK Ministry of Defence contracts to sustain its position in naval torpedo fuzing. Lockheed Martin anchors US Army precision fires programs through captive integration with guided artillery systems. Rheinmetall competes aggressively for European joint procurement frameworks, particularly in air defense missile applications.
Mechanical and electronic fuzes are electromechanical or fully solid-state initiation devices that detect target proximity, impact, or time-based triggers through accelerometers, radar microcircuits, or magnetic sensors, typically operating within milliseconds to microseconds to optimize warhead detonation geometry. Their primary purpose is to maximize lethality while minimizing collateral damage through precise burst-point control. The technology dimension shows electronic and solid-state architectures displacing purely mechanical designs in precision-strike applications, while electro-mechanical hybrids retain cost advantages in high-volume artillery shell programs where sensor-based fuzes command premium pricing. Application segmentation reveals artillery shells and air defense missiles as the dominant volume pools, with anti-tank munitions representing the fastest-growing category due to top-attack fuze requirements.
US DoD MIL-STD-1316 and NATO STANAG 4439 shape fuze safety and interoperability standards, while the EU Green Deal's REACH chemical restrictions affect pyrotechnic composition sourcing across European supply chains. India's BIS ordnance standards and the PLI scheme for defense manufacturing are opening new qualification pathways for foreign fuze suppliers seeking offset partnerships. Stakeholders must monitor how insensitive munitions mandates propagate beyond NATO to Middle Eastern and Asia-Pacific procurement specifications.
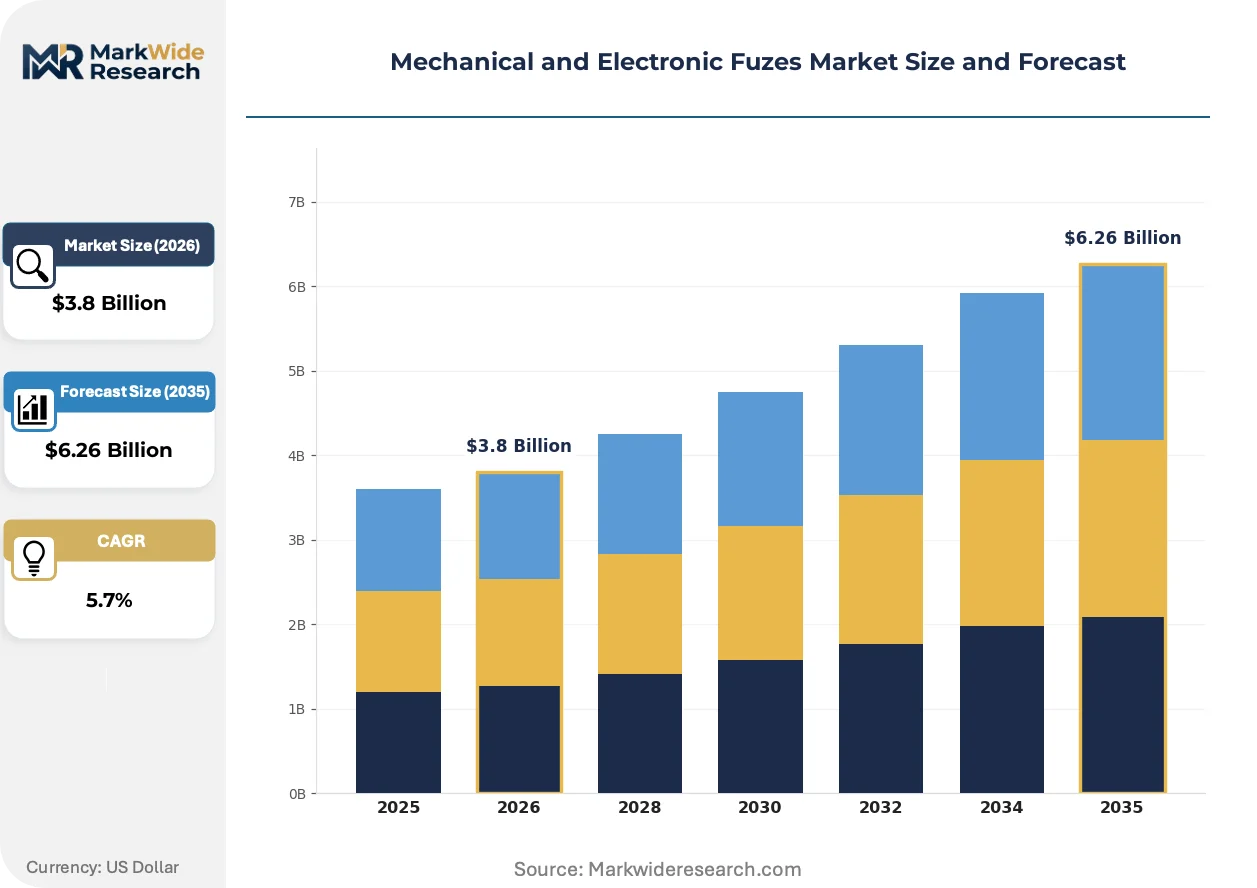
Market Dynamics
The US Department of Defense's Insensitive Munitions mandate is compressing qualification timelines while forcing architecture redesigns across NATO-aligned supplier bases, creating asymmetric pressure on mechanical versus electronic fuze portfolios.
Growth Catalysts
- STANAG 4439 harmonization:NATO's insensitive munitions standard creates cross-border interoperability requirements that favor qualified European suppliers with existing test infrastructure.
- Top-attack fuze proliferation:Anti-tank munitions programs in Eastern Europe are specifying multi-mode sensor fusion for overhead detonation geometry.
- Precision fires modernization:US Army Long-Range Precision Fires programs are mandating electronic proximity fuzing for extended-range artillery systems.
Market Restraints
- Pyrotechnic chemical sourcing:ECHA REACH restrictions on lead styphnate and diazodinitrophenol are forcing reformulation of primary explosive trains at elevated R&D cost.
- Ordnance test range scarcity:Live-fire qualification capacity concentrates at US Army Yuma Proving Ground and French DGA Essais de missiles, creating bottlenecks for new entrants.
- Mechanical fuze obsolescence pressure:Purely mechanical point-detonating designs face displacement from solid-state alternatives in precision-strike applications.
Strategic Opportunities
- India's PLI defense corridor:Foreign fuze suppliers can establish joint ventures under the Production Linked Incentive scheme to access domestic artillery shell procurement.
- Naval torpedo fuze modernization:Undersea warfare programs in Australia and Japan are specifying magnetic-influence proximity sensors for wake-homing applications.
- Drone-delivered munitions:Loitering munition programs require miniaturized electronic time fuzes with microsecond accuracy for swarm coordination.
Industry Challenges
- MIL-STD-1316E certification backlog:Revised safety criteria for electro-explosive devices extend qualification timelines by 18-24 months for redesigned products.
- Accelerometer supply concentration:High-g MEMS sensors for artillery shell applications source from a limited qualified vendor base, creating single-point vulnerability.
- Legacy system integration:New electronic fuzes must maintain backward compatibility with Vietnam-era artillery firing circuits, constraining digital architecture options.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mechanical and Electronic Fuzes Market Trends and Innovations
Solid-state architectures are displacing electromechanical hybrids across precision applications while regulatory mandates cascade from NATO procurement standards into bilateral defense agreements with non-member states.
Multi-function programmable fuzes are fragmenting the traditional segmentation between point-detonating, proximity, and time modes. US Army Excalibur and similar guided artillery programs demand single devices capable of airburst, point-detonation, and delay functions selectable in-flight. This convergence compresses the addressable market for single-mode mechanical alternatives while elevating firmware and radar microcircuit content.
EU Green Deal chemical restrictions are forcing pyrotechnic composition reformulation across European supply chains. ECHA's candidate list expansion for Substances of Very High Concern affects lead-based primers and mercury fulminate alternatives, requiring suppliers to qualify green primary explosives without compromising initiation reliability. German and French ordnance manufacturers are accelerating non-toxic explosive train development to maintain export eligibility.
Buyer consolidation through NATO joint procurement frameworks is compressing vendor negotiation leverage. The NATO Support and Procurement Agency's multi-nation ammunition contracts favor suppliers with pre-qualified fuze portfolios across multiple national stock numbers, marginalizing single-product specialists. This concentration is most visible in air defense missile applications where Germany, Netherlands, and Norway coordinate joint replenishment.
Mechanical and Electronic Fuzes Market Segmentation
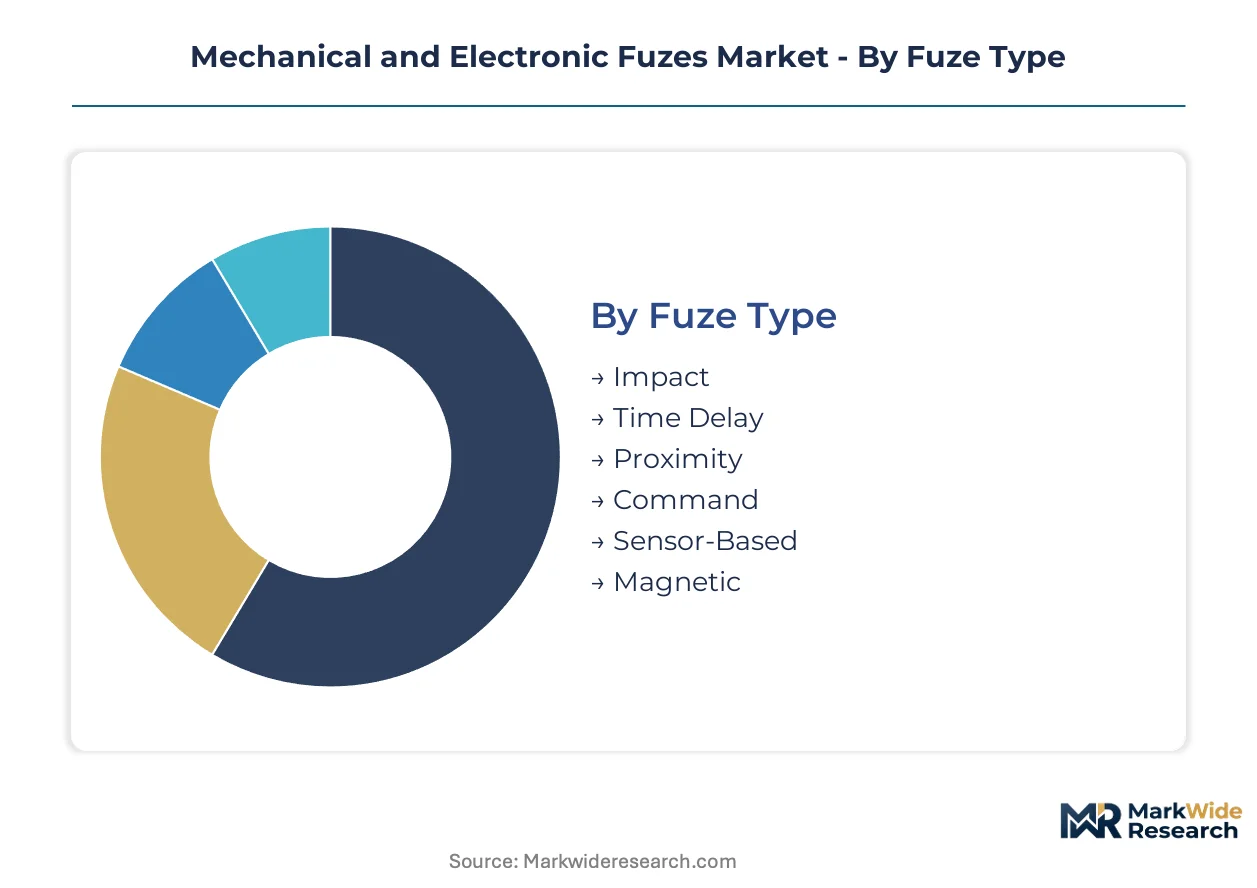
Fuze segmentation determines procurement channel access, with defense forces buying through national stock numbers while ammunition manufacturers source via subcontractor frameworks. Technology and application dimensions dictate qualification requirements, creating distinct competitive arenas.
Fuze Type:
Channel mix varies sharply by fuze type: impact and time-delay variants flow through high-volume artillery shell contracts, while proximity and sensor-based units concentrate in missile prime contractor supply chains.
- Impact:Point-detonating mechanisms trigger on direct target contact through striker-pin and detonator assemblies. Demand concentrates in NATO artillery shell procurement, where cost minimization favors proven mechanical designs over electronic alternatives.
- Proximity:Radio-frequency or laser rangefinding circuits detect target presence before physical contact, enabling airburst detonation for anti-personnel effects. US Army precision fires programs are specifying electronic proximity fuzing for extended-range artillery, compressing mechanical supplier margins.
- Time Delay:Clockwork or electronic timers enable post-impact or airburst delay for bunker penetration or area denial.
- Command:Hardwired or encrypted wireless signals allow remote detonation authorization from firing platforms.
- Sensor-Based:Multi-mode fusion combines accelerometer, radar, and magnetic inputs for target discrimination.
- Magnetic:Induction coils detect ferrous mass for naval mine and torpedo applications.
By volume, impact fuzes lead. By growth pace, proximity variants are climbing the fastest.
Technology:
Cost tier stratification separates qualified electronic architectures from commodity mechanical production, with MEMS and solid-state commanding premium positioning in precision-strike contracts.
- Electronic:Fully solid-state designs replace mechanical moving parts with radar microcircuits, accelerometers, and programmable logic. US DoD MIL-STD-1316E certification requirements favor established suppliers with ordnance testing infrastructure at Yuma Proving Ground.
- Solid-State:Semiconductor-based initiation chains eliminate pyrotechnic primers in favor of exploding foil initiators. REACH chemical restrictions on lead styphnate are accelerating European procurement migration toward solid-state alternatives.
- Mechanical:Spring-driven striker assemblies remain dominant in high-volume artillery where unit cost dominates specification.
- Electro-Mechanical:Hybrid architectures combine mechanical safety arming with electronic firing circuits for cost-sensitive precision applications.
- Hybrid:Modular designs allow field conversion between mechanical and electronic modes.
- Microelectromechanical Systems (MEMS):Silicon-based high-g accelerometers enable miniaturized multi-axis sensing for top-attack munitions.
By installed base, mechanical technologies dominate. By procurement momentum, solid-state architectures are gaining share fastest.
Application:
Customer type varies by application: artillery shells and infantry weapons serve defense forces directly, while naval torpedoes and air defense missiles route through systems integrators.
- Artillery Shells:155mm and 105mm gun systems require fuzes compatible with Vietnam-era firing circuits and modern digital fire control. Demand concentrates in NATO replenishment programs and India's PLI defense corridor.
- Air Defense Missiles:Proximity fuzing for fragmentation warheads demands radar microcircuits with microsecond timing accuracy. Joint procurement through NATO Support and Procurement Agency favors suppliers with multi-national qualification.
- Anti-Tank Munitions:Top-attack geometry requires multi-mode sensor fusion for overhead detonation against armored vehicle roof armor.
- Naval Torpedoes:Magnetic-influence and wake-homing fuzes serve undersea warfare programs in Australia and Japan.
- Infantry Weapons:Rifle grenades and mortar fuzes prioritize cost minimization and reliability in harsh field conditions.
- Demolition Charges:Time and command fuzes for explosive ordnance disposal and combat engineering applications.
By procurement volume, artillery shells lead. By specification intensity, air defense missiles are expanding most quickly.
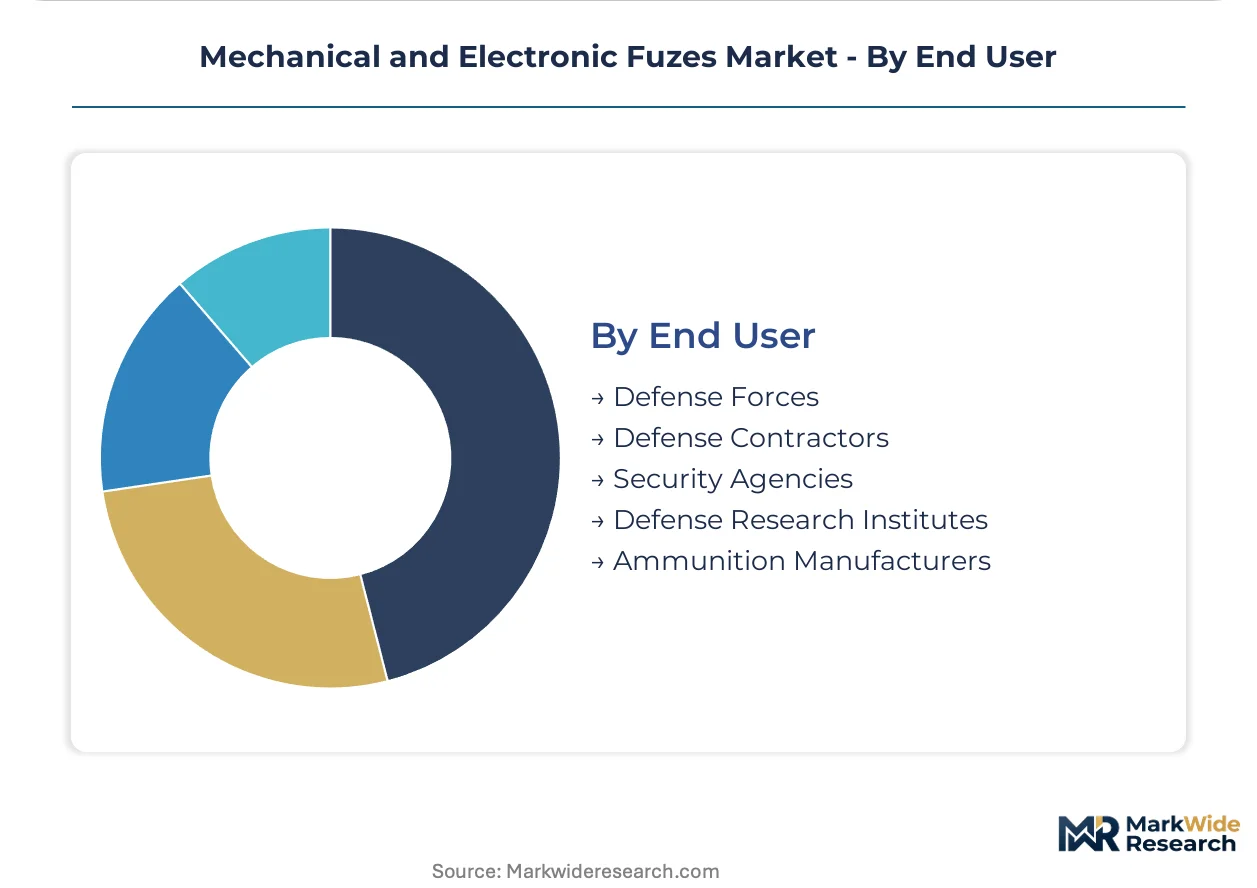
End User:
Supply concentration differs by buyer category: defense forces consolidate through NATO frameworks, while ammunition manufacturers fragment across national industrial bases.
- Defense Forces:National military procurement agencies specify fuze requirements through stock number catalogs. India's BIS ordnance standards and PLI scheme are opening qualification pathways for foreign suppliers.
- Defense Contractors:Systems integrators for guided missiles and precision munitions source fuzes as subcontracted components. Lockheed Martin and BAE Systems maintain captive integration with preferred fuze suppliers.
- Ammunition Manufacturers:Rheinmetall and Diehl Defence anchor European supply chains with in-house fuze production and external sourcing.
- Defense Research Institutes:National laboratories qualify experimental fuze technologies for future procurement cycles.
- Security Agencies:Domestic law enforcement and border security organizations procure limited quantities of specialized fuzes for explosive ordnance disposal.
By contract value, defense forces lead. By technology access, defense contractors are moving fastest on next-generation specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US DoD procurement mandates are compressing qualification timelines for fuze suppliers while European REACH chemical restrictions force pyrotechnic reformulation across NATO-aligned production bases.
United States
US Army Long-Range Precision Fires programs are mandating electronic proximity fuzing for extended-range artillery systems. MIL-STD-1316E certification requirements at Yuma Proving Ground create bottlenecks for new entrants lacking ordnance testing infrastructure. Lockheed Martin anchors precision fires programs through captive integration with guided artillery systems in Arizona and Texas defense corridors.
Germany
Rheinmetall and Diehl Defence anchor European supply chains with in-house fuze production and external sourcing for artillery shell programs. EU Green Deal REACH restrictions on lead styphnate are accelerating non-toxic explosive train development to maintain export eligibility. The Bavaria and North Rhine-Westphalia industrial clusters concentrate air defense missile fuze manufacturing for NATO joint procurement frameworks.
United Kingdom
BAE Systems leverages decades of UK Ministry of Defence contracts to sustain its position in naval torpedo fuzing. STANAG 4439 harmonization creates cross-border interoperability requirements that favor qualified suppliers with existing test infrastructure. The South West England defense cluster around Bristol and Portsmouth houses torpedo and missile fuze development facilities.
India
India's PLI scheme for defense manufacturing is opening new qualification pathways for foreign fuze suppliers seeking offset partnerships through joint ventures. BIS ordnance standards create domestic certification requirements for artillery shell procurement. The Maharashtra and Gujarat defense corridors are attracting foreign fuze manufacturers to establish production under the Production Linked Incentive framework.
France
Thales competes for European joint procurement frameworks with multi-mode sensor fusion capabilities for air defense applications. DGA Essais de missiles at Biscarrosse provides live-fire qualification capacity that concentrates testing for new fuze designs. The Provence-Alpes-Côte d'Azur region hosts missile systems integration facilities that source proximity fuzing for naval and air defense programs.
Mechanical and Electronic Fuzes Market Competitive Landscape
Player mix skews toward diversified defense primes with captive ordnance capabilities and specialized fuze manufacturers with deep qualification records. Market structure concentrates around suppliers with MIL-STD-1316E certification and NATO STANAG test histories, creating tiered access to precision fires and air defense contracts. Two strategic archetypes dominate: vertically integrated systems integrators controlling end-to-end munitions production, and component specialists with exclusive supplier status on specific national stock numbers. Competitive moves center on qualification portfolio expansion into insensitive munitions architectures and joint venture formation to access India's PLI defense corridor.
Within the diversified defense prime tier, BAE Systems, Lockheed Martin, and Rheinmetall occupy positions that exemplify contrasting geographic anchoring strategies. BAE Systems represents UK-centric naval and air defense fuze integration through sustained Ministry of Defence contract relationships. Lockheed Martin sits within the US precision fires ecosystem where captive fuze supply supports guided artillery system differentiation. Rheinmetall exemplifies European multi-national positioning through aggressive pursuit of NATO Support and Procurement Agency frameworks, particularly for air defense missile applications where joint replenishment contracts favor pre-qualified portfolios across German, Dutch, and Norwegian national stock numbers.
| Leading Market Players |
|---|
| BAE Systems |
| Lockheed Martin |
| Raytheon |
| Northrop Grumman |
| L3Harris Technologies |
| General Dynamics |
| Saab |
| Thales |
| Rheinmetall |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four month MIL-STD-1316E certification timelines concentrate supply-side leverage among Yuma Proving Ground-qualified suppliers, compressing pricing power for mechanical fuze specialists while elevating premiums for solid-state architectures with insensitive munitions compliance.
Pricing Analysis
Certification level creates the primary spread across the Mechanical and Electronic Fuzes Market, with MIL-STD-1316E-qualified electronic proximity units commanding substantial premiums over mechanical point-detonating alternatives. Three-tier pricing structure separates insensitive munitions-compliant solid-state designs from electro-mechanical hybrids and legacy mechanical assemblies. Cost compression in high-volume artillery shell procurement is intensifying because NATO joint frameworks consolidate buyer power through multi-national stock number contracts. Ammunition manufacturers sourcing for 155mm replenishment programs exhibit highest price sensitivity, while air defense missile prime contractors demonstrate lowest sensitivity due to mission-critical performance requirements.
Supply Chain Analysis
Ordnance test range inventory concentrates at US Army Yuma Proving Ground and French DGA Essais de missiles, creating eighteen-to-twenty-four month qualification bottlenecks that constrain new supplier entry. Manufacturing gravity centers on Germany, the United States, and the United Kingdom, with Rheinmetall and BAE Systems anchoring European and Atlantic supply chains respectively. High-g MEMS accelerometers and radar microcircuits draw from a limited qualified vendor base, creating single-point vulnerability for precision fuze production. REACH chemical restrictions on lead styphnate force pyrotechnic reformulation across European production bases. Distribution runs through NATO Support and Procurement Agency frameworks for defense forces, while ammunition manufacturers source via national subcontractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mechanical and Electronic Fuzes Market represents a high-growth disruption as solid-state architectures displace mechanical designs under insensitive munitions mandates, with regulatory inflection at MIL-STD-1316E and STANAG 4439 harmonization reshaping competitive access.
For Market Incumbents: Compound qualification portfolio advantages by accelerating insensitive munitions architecture deployment before REACH chemical restrictions propagate to Middle Eastern procurement specifications. Expand Yuma Proving Ground testing capacity commitments to defend against emerging European suppliers leveraging DGA Essais de missiles infrastructure. Deepen backward integration into high-g MEMS accelerometer sourcing to mitigate single-point supply vulnerability.
For New Entrants and Emerging Players: India's PLI scheme certification fast-track offers the most penetrable entry pathway for foreign suppliers seeking joint venture partnerships under BIS ordnance standards. Target drone-delivered munition programs requiring miniaturized electronic time fuzes with microsecond accuracy, where incumbent qualification records remain thinner. Pursue loitering munition swarm coordination applications as the primary go-to-market angle, positioning solid-state programmable designs against mechanical legacy alternatives.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified defense primes seeking to divest non-core fuze manufacturing capabilities amid consolidation pressure. Long-term viability favors suppliers with multi-national NATO qualification spanning artillery shell and air defense missile applications. Watch for STANAG 4439 adoption acceleration in Asia-Pacific bilateral defense agreements as the signal indicating qualification demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Insensitive Munitions Architecture Migration | REACH chemical restrictions on lead styphnate force primary explosive train reformulation across European supply chains. |
| NATO Joint Procurement Framework Qualification | Multi-national stock number pre-qualification compresses vendor negotiation leverage through buyer consolidation. |
| India PLI Defense Corridor Joint Venture | BIS ordnance standards create domestic certification requirements opening offset partnership pathways for foreign suppliers. |
| High-g MEMS Accelerometer Supply Security | Single-source concentration in qualified sensor vendors creates vulnerability requiring upstream supply agreements. |
| Drone-Delivered Munition Fuze Miniaturization | Loitering munition programs demand microsecond-accuracy electronic time fuzes for swarm coordination applications. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with defense procurement officers, ammunition manufacturer supply chain directors, ordnance test range qualification managers, and insensitive munitions R&D leads; alongside secondary validation through NATO STANAG documentation, US DoD MIL-STD-1316E revision records, ECHA REACH candidate list expansions, and national stock number procurement databases. Bottom-up triangulation across fuze type, technology architecture, and application segmentation combined with top-down macro validation against defense budget appropriation trends.
Across the projection horizon, the analytical framework modeled volume and value outputs through technology displacement curves, regulatory mandate propagation timelines, and procurement framework adoption patterns. Segmentation dimensions spanned fuze type, technology tier, application intensity, and end-user procurement channel. CAGRs derived from historical qualification backlog trends, replenishment cycle observations, and architecture substitution elasticity estimates. Forecast inputs incorporated REACH chemical restriction implementation schedules and PLI scheme incentive disbursement trajectories.
The analysis sits within stated boundaries; outcomes outside sustained NATO defense expenditure growth or accelerated insensitive munitions mandate propagation would require recalibration. Forecasts reflect documented assumptions regarding qualification timeline stability and pyrotechnic reformulation success rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.