
 Defense Integrated Antenna Market | 2026-2036
Defense Integrated Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
Defense Integrated Antenna Market Insights
Gallium nitride is expanding its displacement of gallium arsenide in active phased array transmit-receive modules, cutting thermal management overhead by half while doubling power density. L3Harris Technologies leverages captive GaN foundry partnerships to control module cost curves. Lockheed Martin Corporation anchors the F-35 Lightning II antenna ecosystem through sole-source integration contracts. BAE Systems specializes in conformal array architectures for naval stealth platforms.
Defense integrated antennas are aperture-integrated electromagnetic transducers designed for simultaneous multi-function operation across radar, communications, and electronic warfare bands, typically fabricated on low-loss substrates with embedded beamforming networks and operating at frequencies from VHF through millimeter-wave. Their primary purpose is to collapse multiple discrete apertures into single structural elements, reducing radar cross-section and aerodynamic drag on manned and unmanned platforms. Active phased array configurations now command the dominant share of new procurement value, driven by element-level digital beamforming requirements. Multi-band technology adoption outpaces wideband alternatives in naval and space applications where spectrum agility trumps instantaneous bandwidth. Military branches represent the most concentrated end-user category, with intelligence agencies representing the fastest-growing demand pool for signals intelligence collection payloads.
The US Department of Defense mandates MIL-STD-461G electromagnetic compatibility and MIL-STD-810H environmental qualification for all integrated antenna systems, creating a certification moat that filters non-domestic suppliers from prime platform awards. The EU AI Act and CE marking requirements under the Radio Equipment Directive are extending compliance burdens for antennas with embedded cognitive processing. NATO's Standardization Agreement 5516 for tactical data links further harmonizes interface specifications across allied procurement. Stakeholders must monitor how software-defined radio mandates reshape hardware-software boundary definitions in source selection criteria.
Market Dynamics
Active phased array architectures are compressing hardware development cycles across NATO fighter modernization programs, forcing suppliers to restructure around software-defined radio mandates and open architecture qualification pathways.
Growth Catalysts
- MIL-STD-461G Electromagnetic Compatibility Mandate:US Department of Defense certification requirements filter non-domestic suppliers from prime platform awards, creating protected demand pools for qualified integrators.
- Gallium Nitride Material Transition:Active phased array transmit-receive modules achieve doubled power density with halved thermal management overhead, accelerating platform refresh decisions.
- Signals Intelligence Payload Expansion:Intelligence agencies represent the fastest-growing demand pool for multi-band collection systems, outpacing traditional military branch procurement velocity.
Market Restraints
- GaN Substrate Supply Concentration:Captive foundry partnerships at L3Harris Technologies and limited merchant supply create input bottlenecks for second-tier module integrators.
- EU AI Act Compliance Burden:CE marking requirements under the Radio Equipment Directive extend certification timelines for antennas with embedded cognitive processing capabilities.
- Conformal Array Technical Limitation:Naval stealth platform integration demands impose severe form-factor constraints that wideband alternatives cannot satisfy, restricting supplier eligibility.
Strategic Opportunities
- Israeli Sovereign Manufacturing Gap:Domestic antenna production capabilities anchor national security supply chains, creating partnership entry points for qualified foreign subsystem suppliers.
- Space-Based Multi-Band Convergence:Spectrum agility requirements in orbital payloads favor element-level digital beamforming architectures over conventional wideband approaches.
- NATO Standardization Agreement 5516 Harmonization:Tactical data link interface specifications across allied procurement create modular product platform opportunities for compliant integrators.
Industry Challenges
- MIL-STD-810H Environmental Qualification Timeline:Extended certification cycles for integrated antenna systems compress program award windows and strain working capital.
- Software-Hardware Boundary Redefinition:Open architecture directives reshape source selection criteria, forcing hardware suppliers to absorb firmware development competencies or partner dependencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Defense Integrated Antenna Market |
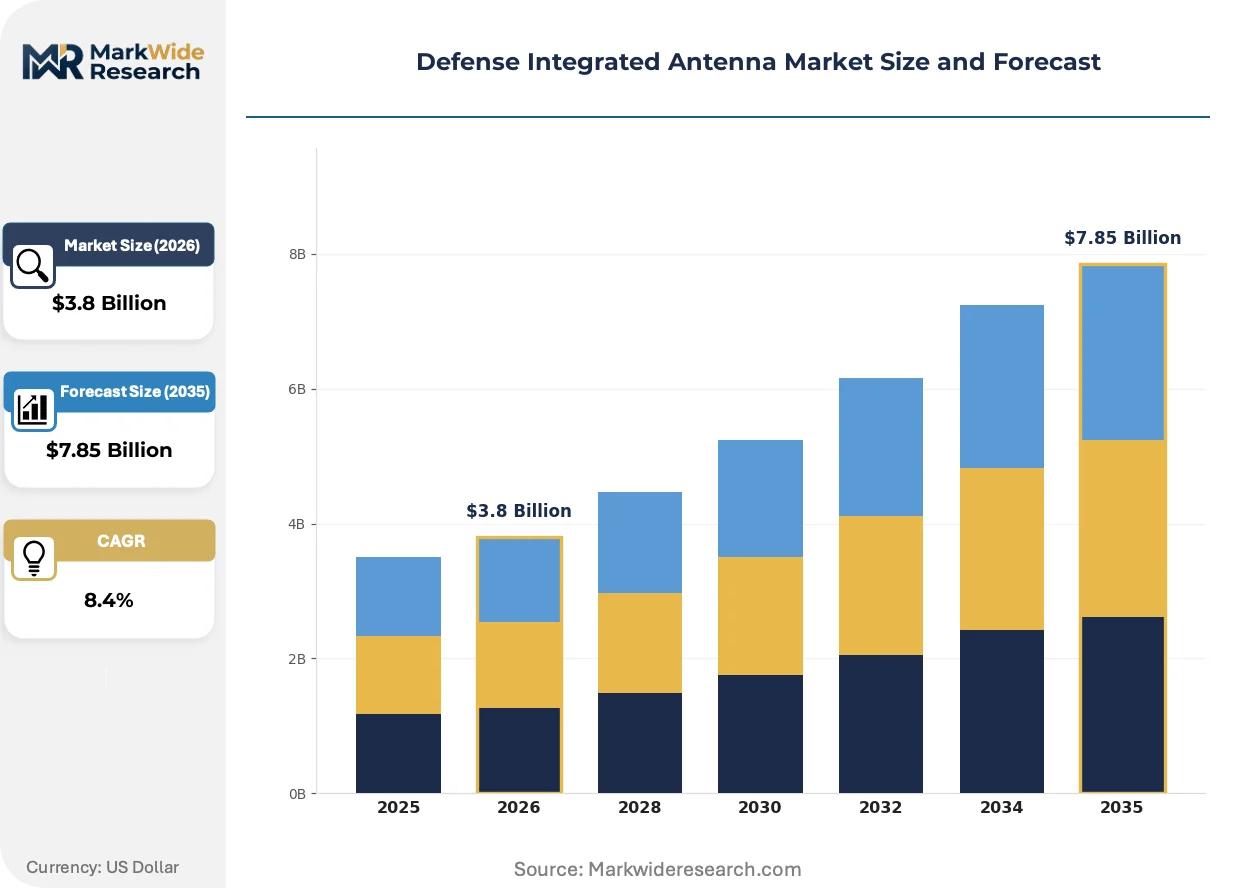
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conformal, Active Phased Array, Passive Phased Array, Microstrip Patch, Helical, Slot Technology: Beamforming, Frequency Agile, Multi-band, Wideband, MIMO, Adaptive Application: Radar Systems, Electronic Warfare, Communications, Surveillance, Missile Guidance, Signal Intelligence End User: Defense Contractors, Military Branches, Intelligence Agencies, Aerospace Manufacturers, Security Firms, Research Institutions |
| Companies Covered | L3Harris Technologies, General Dynamics Corporation, Lockheed Martin Corporation, Thales Group, Honeywell International Inc., Raytheon Technologies, BAE Systems, Northrop Grumman, Rohde & Schwarz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Defense Integrated Antenna Market Trends and Innovations
Digital beamforming at the element level is collapsing traditional subsystem boundaries, compressing supplier margins while enabling new platform integration architectures across manned and unmanned defense systems.
GaN-on-SiC power amplifiers are consolidating transmit-receive module designs across fighter and naval platforms. Military procurement offices specify these devices for all new active phased array awards. The technology is consolidating three generations of discrete component architectures into single-chip solutions, eliminating redundant thermal management subsystems from platform designs.
REACH substance restrictions and RoHS compliance extensions are forcing substrate material substitutions in European defense supply chains. Component suppliers face reformulation costs for embedded beamforming networks. Naval stealth platforms in the United Kingdom and France experience the longest qualification delays as legacy tin-lead solder exemptions expire.
Platform primes now unbundle antenna subsystem integration from airframe contracts, creating direct procurement relationships with qualified module suppliers. This channel disintermediation concentrates volume with captive foundry operators while marginalizing traditional tier-two integrators. The United States exhibits the most pronounced shift, with the F-35 program office establishing separate source selection streams for aperture-integrated electromagnetic transducers.
Defense Integrated Antenna Market Segmentation
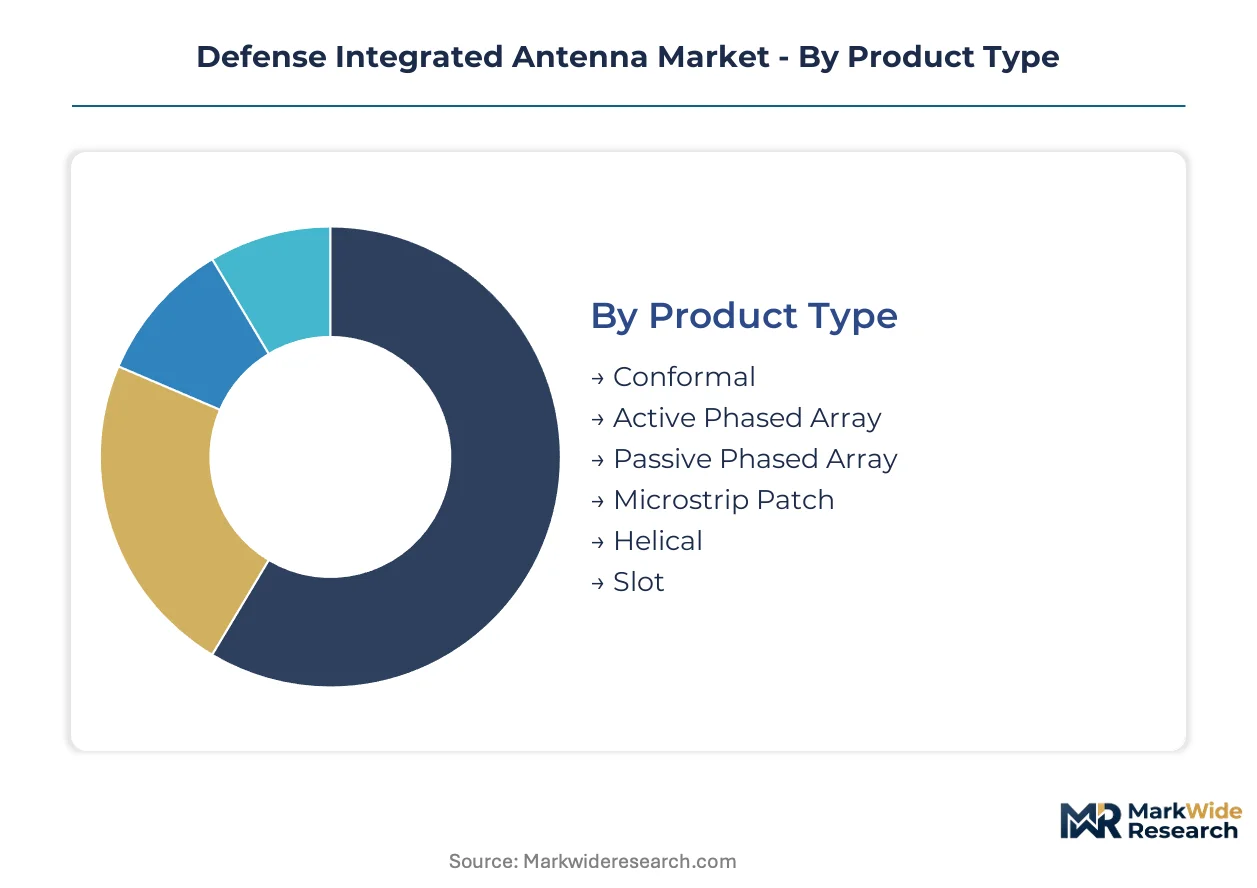
Defense integrated antenna procurement splits across multiple technical and operational dimensions, each carrying distinct qualification burdens and volume concentrations. Platform primes source differently across these categories depending on mission profile requirements and sovereign content mandates.
Product Type:
Capital intensity varies sharply across antenna architectures, with active phased array configurations demanding the heaviest upfront foundry investment and thermal management engineering.
- Active Phased Array:Element-level transmit-receive modules integrate gallium nitride power amplifiers on silicon carbide substrates. Fighter modernization programs across NATO allies specify these architectures exclusively for new procurements.
- Conformal:Structurally integrated apertures embed beamforming networks directly into platform skin panels. Naval stealth programs in the United Kingdom and France impose severe form-factor constraints that only conformal designs satisfy.
- Passive Phased Array:Centralized transmitter architectures reduce module count but limit beam agility.
- Microstrip Patch:Low-profile substrates suit unmanned platforms with severe weight restrictions.
- Helical:Circular polarization characteristics serve satellite communications terminals.
- Slot:Waveguide-fed apertures persist in legacy radar refurbishments.
Active phased array absorbs the bulk of installed capacity; conformal architectures are expanding most quickly.
Technology:
Beamforming sophistication determines supplier qualification tiers, with digital architectures separating prime integrators from subsystem vendors.
- Beamforming:Analog and digital implementations divide the supplier base, with digital variants at the element level commanding sole-source relationships with captive foundry operators.
- Multi-band:Spectrum agility across discrete frequency blocks outperforms wideband alternatives in naval and orbital applications where interference rejection trumps instantaneous bandwidth.
- Frequency Agile:Rapid hopping capabilities serve electronic warfare countermeasure systems.
- Wideband:Continuous spectrum coverage suits signals intelligence collection payloads.
- MIMO:Multiple spatial streams enhance communications throughput in contested spectrum environments.
- Adaptive:Cognitive processing algorithms adjust patterns in response to electromagnetic threats.
Beamforming technology commands the deepest integration relationships; multi-band implementations are climbing the fastest.
Application:
Mission-criticality shapes procurement channel structure, with radar and electronic warfare systems flowing through platform prime contracts while intelligence applications enable direct supplier relationships.
- Radar Systems:Fire control and surveillance apertures integrate at the airframe level through sole-source contracts with Lockheed Martin and BAE Systems. MIL-STD-461G electromagnetic compatibility mandates filter non-domestic suppliers from these awards.
- Signal Intelligence:Multi-band collection payloads for intelligence agencies bypass platform primes, creating direct procurement channels with qualified module suppliers. This segment exhibits the steepest expansion trajectory in the analysis window.
- Electronic Warfare:Jamming and countermeasure systems require rapid beam steering.
- Communications:Tactical data link terminals implement NATO Standardization Agreement 5516 interfaces.
- Surveillance:Persistent wide-area coverage drives large aperture installations.
- Missile Guidance:Seeker antennas demand miniaturized conformal packaging.
Radar systems absorb the bulk of installed capacity; signal intelligence is gaining share fastest.
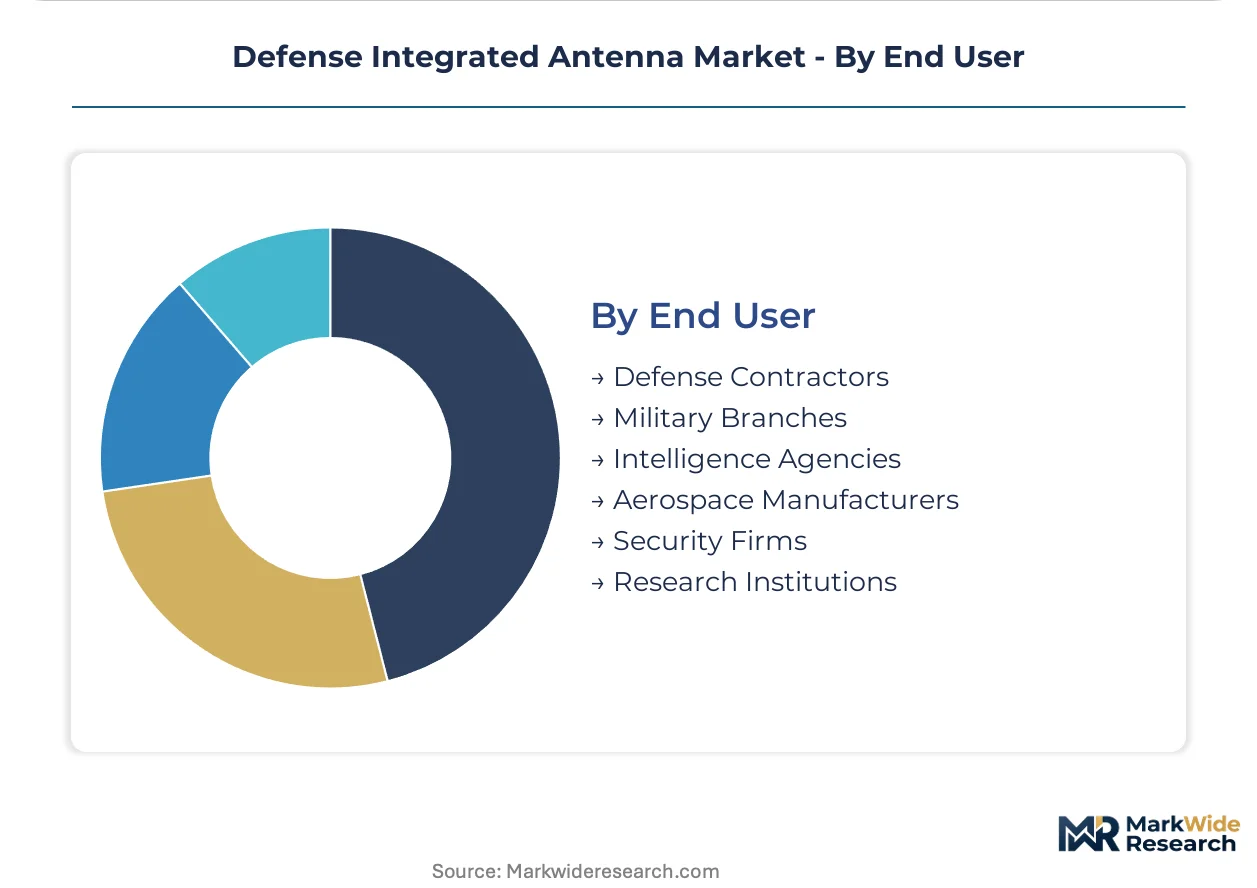
End User:
Contracting authority determines specification complexity, with military branches enforcing full MIL-STD qualification while research institutions accept pre-production prototypes.
- Military Branches:Service-level procurement offices mandate MIL-STD-810H environmental qualification and MIL-STD-461G electromagnetic compatibility, creating certification moats that protect domestic integrators. The US Department of Defense's software-defined radio directives reshape hardware-software boundary definitions in source selection.
- Intelligence Agencies:Signals intelligence directorates prioritize multi-band collection performance over platform integration, enabling faster procurement cycles and direct relationships with specialized module suppliers.
- Defense Contractors:Prime platform integrators intermediate antenna subsystem sourcing.
- Aerospace Manufacturers:Airframe builders specify aperture-integrated electromagnetic transducers.
- Security Firms:Private sector counter-UAS applications drive commercial derivative demand.
- Research Institutions:Experimental programs tolerate higher technical risk.
Military branches absorb the bulk of installed capacity; intelligence agencies are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentration centers on the United States, the United Kingdom, and Israel where sovereign manufacturing capabilities anchor national security supply chains and filter non-domestic suppliers from prime platform awards.
United States
F-35 Lightning II modernization and software-defined radio mandates drive active phased array demand. The Department of Defense enforces MIL-STD-461G electromagnetic compatibility and MIL-STD-810H environmental qualification. Lockheed Martin anchors sole-source integration contracts in Fort Worth, Texas, while L3Harris controls GaN module cost curves through captive foundry partnerships.
United Kingdom
Naval stealth platform requirements impose severe form-factor constraints favoring conformal array architectures. BAE Systems specializes in structurally integrated apertures for surface combatants. REACH substance restrictions and RoHS compliance extensions force substrate material substitutions, extending qualification timelines at facilities in Lancashire and Bristol.
Israel
Domestic antenna production capabilities anchor national security supply chains against supply disruption. The Ministry of Defense prioritizes multi-band collection systems for signals intelligence directorates. Elta Systems and Rafael Advanced Defense Systems maintain sovereign manufacturing clusters around Haifa and Tel Aviv, creating partnership entry points for qualified foreign subsystem suppliers.
Germany
Eurofighter Typhoon upgrade programs and NATO Standardization Agreement 5516 harmonization drive tactical data link terminal procurement. The Federal Office of Bundeswehr Equipment mandates CE marking under the Radio Equipment Directive for antennas with embedded processing. Hensoldt and Rohde & Schwarz operate development centers in Munich and Taufkirchen, consolidating beamforming module design for allied platforms.
France
Rafale fighter modernization and naval frigate programs sustain conformal array demand. The Direction Générale de l'Armement enforces EU AI Act compliance for cognitive processing capabilities. Thales Group integrates aperture-optimized electromagnetic transducers at facilities in Élancourt and Bordeaux, serving both domestic and export customers across NATO procurement frameworks.
Defense Integrated Antenna Market Competitive Landscape
Strategic partnerships dominate the current landscape as platform primes unbundle antenna subsystem integration from airframe contracts. The supplier base concentrates around three tiers: captive foundry operators controlling GaN substrate supply, sole-source integrators holding prime platform relationships, and specialized module vendors serving intelligence agency direct procurement channels. Competitive positioning hinges on MIL-STD qualification moats and open architecture certification pathways rather than price differentiation.
Among US-based defense primes, Lockheed Martin Corporation and L3Harris Technologies exemplify contrasting archetypes. Lockheed Martin occupies the sole-source integrator position through F-35 ecosystem control. L3Harris represents the captive foundry model, leveraging upstream semiconductor partnerships to secure module cost advantages. Thales Group anchors the European competitive vector, while BAE Systems exemplifies naval specialization. Rohde & Schwarz occupies the test and measurement-to-integration pathway typical of German industrial conglomerates.
| Leading Market Players |
|---|
| L3Harris Technologies |
| General Dynamics Corporation |
| Lockheed Martin Corporation |
| Thales Group |
| Honeywell International Inc. |
| Raytheon Technologies |
| BAE Systems |
| Northrop Grumman |
| Rohde & Schwarz |
| Others |
Pricing and Supply Chain Analysis
REACH substance restrictions and RoHS compliance extensions gate both qualified supply and premium-tier pricing access for defense integrated antenna systems, forcing substrate material substitutions that bifurcate the supplier base between qualified integrators commanding sole-source premiums and non-compliant vendors locked out of NATO procurement channels.
Pricing Analysis
High-volume fighter modernization programs absorb margin compression through multi-year sole-source contracts, while low-volume naval stealth applications sustain premium pricing tiers. Pricing stratifies across MIL-STD-461G certified integrators, open-architecture qualified module suppliers, and non-certified component vendors. Cost compression in conformal array modules is intensifying because REACH-driven substrate reformulations extend qualification timelines. Intelligence agencies exhibit lowest price sensitivity due to mission-critical performance requirements; security firms and research institutions face highest budget constraints.
Supply Chain Analysis
Direct-to-platform-prime channels handle F-35 and Eurofighter Typhoon procurement volumes, while direct-to-intelligence-agency relationships serve signals intelligence payload demand. GaN substrate supply concentrates in the United States through captive foundry partnerships and in Japan through merchant wafer suppliers. Active phased array module production draws from silicon carbide substrates, gallium nitride epitaxy services, and ceramic packaging substrates. Single-source vulnerability around GaN-on-SiC foundry capacity creates input bottlenecks for second-tier integrators. Distribution runs through platform prime contracts, intelligence agency direct awards, and defense contractor subsystem sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The defense integrated antenna market sits in a material-transition phase as gallium nitride power amplifiers displace legacy gallium arsenide transmit-receive modules, compressing thermal management costs while reshaping supplier qualification hierarchies.
For Market Incumbents: Extend sole-source integration relationships through accelerated open-architecture certification investments that preempt software-defined radio mandate compliance. Lockheed Martin and BAE Systems must defend against channel disintermediation by absorbing firmware development competencies or securing captive module partnerships. Backward integration into GaN epitaxy services represents the critical lever for cost curve control.
For New Entrants and Emerging Players: Direct intelligence agency procurement portals offer the most penetrable entry vector for qualified module suppliers lacking platform prime relationships. Israeli sovereign manufacturing gaps create partnership opportunities for foreign subsystem vendors with MIL-STD-810H environmental qualification. A specialized signals intelligence collection payload positioning bypasses the F-35 ecosystem's sole-source barriers.
For Investors and Strategic Acquirers: F-35 program office unbundling of antenna subsystem contracts from airframe awards is the leading indicator that channel structure disruption will accelerate value migration toward captive foundry operators. The five-to-ten-year viability window favors acquisition targets with element-level digital beamforming capabilities and existing NATO Standardization Agreement 5516 compliance. Watch for Israeli Ministry of Defense partnership announcements with non-domestic module suppliers as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive GaN Foundry Partnership | L3Harris controls module cost curves through upstream semiconductor supply security. |
| Open Architecture Certification Investment | Suppliers absorb firmware competencies to meet US Department of Defense software-defined radio mandates. |
| Conformal Array Naval Specialization | BAE Systems captures UK and French stealth platform awards through form-factor expertise. |
| Intelligence Agency Direct Channel Development | Module vendors bypass platform primes for signals intelligence payload procurement relationships. |
| NATO Standardization Agreement 5516 Compliance | Modular product platforms unlock allied procurement harmonization across tactical data link terminals. |
Research Methodology
Document review covered defense procurement databases, MIL-STD certification registries, and EU regulatory filings, complemented by interviews with platform integration engineers at prime contractors, signals intelligence program officers at allied agencies, GaN foundry operations directors, and defense procurement officials at NATO standardization bodies. Secondary validation drew from US Department of Defense contract announcements, EU Official Journal procurement notices, and national security supply chain assessments. Bottom-up module shipment analysis and top-down platform production forecasts were triangulated to establish volume baselines.
Historical contract award patterns were cross-referenced against expert panel input from antenna subsystem architects and thermal management specialists. The analytical framework modeled product type, beamforming technology, application mission profile, and end-user contracting authority across the projection horizon. CAGRs were derived from platform modernization program schedules and intelligence agency budget trajectory assessments. Forecast inputs included fighter fleet refresh timelines, naval stealth platform production rates, and signals intelligence payload procurement velocity.
The model holds under sustained NATO defense spending commitments and stable GaN substrate supply; deviation in allied procurement harmonization or export control tightening would shift volume distributions. Forecasts reflect documented platform program schedules, regulatory compliance timelines, and technology substitution curves. Periodic stress-testing of base assumptions against program delay announcements and foundry capacity expansion disclosures is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Global Non Lethal Biochemical Weapon Market
Defense and Military Systems and Equipment
Global Battlefield Management System Market
Defense and Military Systems and Equipment
Military Rifle Market
Defense and Military Systems and Equipment
Military Software Market
Defense and Military Systems and Equipment
Military Actuators Market
Defense and Military Systems and Equipment
Search and Rescue Equipment Market
Defense and Military Systems and Equipment
Missiles and Missile Defense Systems Market
Defense and Military Systems and Equipment
Mechanical and Electronic Fuzes Market
Defense and Military Systems and Equipment
Military Laser Systems Market
Defense and Military Systems and Equipment
Military Exoskeleton Market
Defense and Military Systems and Equipment
Military Aerospace and Defense Lifecycle Management Market
Defense and Military Systems and Equipment
Radar Warning Receiver Market
Defense and Military Systems and Equipment
Mergers and Acquisitions (Manda) in Aerospace and Defense Market
Defense and Military Systems and Equipment
Military Embedded System Market
Defense and Military Systems and Equipment
Global Military Laser Rangefinder Market
Defense and Military Systems and Equipment
Global Military Laser Designator Market