
 Bio-Defense Market | 2026-2036
Bio-Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Defense Market Outlook
BARDA Project BioShield qualification is reorganizing competitive access for countermeasure suppliers. Emergent BioSolutions leverages its ACAM2000 manufacturing infrastructure to anchor domestic smallpox vaccine readiness. SIGA Technologies specializes in orthopoxvirus antiviral development, sustaining its position through TPOXX procurement contracts. Bavarian Nordic competes across multiple pathogen categories, extending its Jynneos platform into expanded indications.
Bio-defense encompasses the detection, prevention, and response systems targeting biological threat agents including Category A pathogens, with core technologies requiring Biosafety Level 3 or 4 containment validation and FDA approval under the Animal Rule when human efficacy trials are not ethical. Vaccines occupy the largest value pool given multi-year stockpile replenishment cycles and cold-chain infrastructure requirements, while molecular diagnostics represents the fastest-expanding segment driven by point-of-need detection platforms. Antibodies command premium positioning where rapid post-exposure prophylaxis is specified in national response protocols.
FDA Animal Rule requirements, BARDA procurement guidelines, and DOD Joint Program Executive Office for Chemical, Biological, Radiological and Nuclear Defense standards collectively determine product development feasibility and contract eligibility for bio-defense suppliers. The FDA's framework shapes clinical trial design, while BARDA funding mechanisms determine which platforms advance to stockpile integration. Stakeholders must monitor shifts in government pandemic preparedness appropriations and international biodefense cooperation frameworks to anticipate procurement priority changes.
Market Dynamics
The FDA Animal Rule pathway is compressing product development timelines while simultaneously elevating technical barriers for bio-defense developers seeking US government stockpile contracts.
Growth Catalysts
- BARDA Advanced Research and Development Authority funding:Sustained appropriations for Project BioShield are accelerating platform qualification for novel countermeasure categories.
- United States military procurement acceleration:NATO member states are modernizing legacy stockpiles through multi-year replenishment programs.
- Point-of-need molecular diagnostics:Field-deployable detection platforms are expanding addressable use cases beyond laboratory-confirmed identification.
Market Restraints
- Biosafety Level 3/4 containment infrastructure:Limited global capacity for high-consequence pathogen validation constrains throughput for preclinical efficacy studies.
- Cold-chain distribution concentration:Vaccine stockpiles require specialized storage networks with redundant backup systems that concentrate operational risk.
- FDA Animal Rule evidentiary requirements:The regulatory framework demands species-specific correlates of protection that extend development timelines and compress margins.
Strategic Opportunities
- United Kingdom pandemic preparedness frameworks:Post-COVID-19 institutional reforms are creating procurement pathways for rapid-response platform technologies.
- Antibody-drug conjugate convergence with monoclonal platforms:Hybrid modalities are opening post-exposure prophylaxis applications previously restricted to vaccine-only protocols.
- EU Health Emergency Preparedness and Response Authority joint procurement:Centralized purchasing mechanisms are consolidating demand across member state stockpiles.
Industry Challenges
- High-containment manufacturing workforce scarcity:Specialized technicians with dual competencies in GMP operations and BSL-3 protocols command premium compensation that strains fixed-price contract economics.
- Animal Rule clinical validation timelines:The requirement for two animal species with demonstrated correlation to human response creates sequential dependency risks that compress commercialization windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Defense Market |
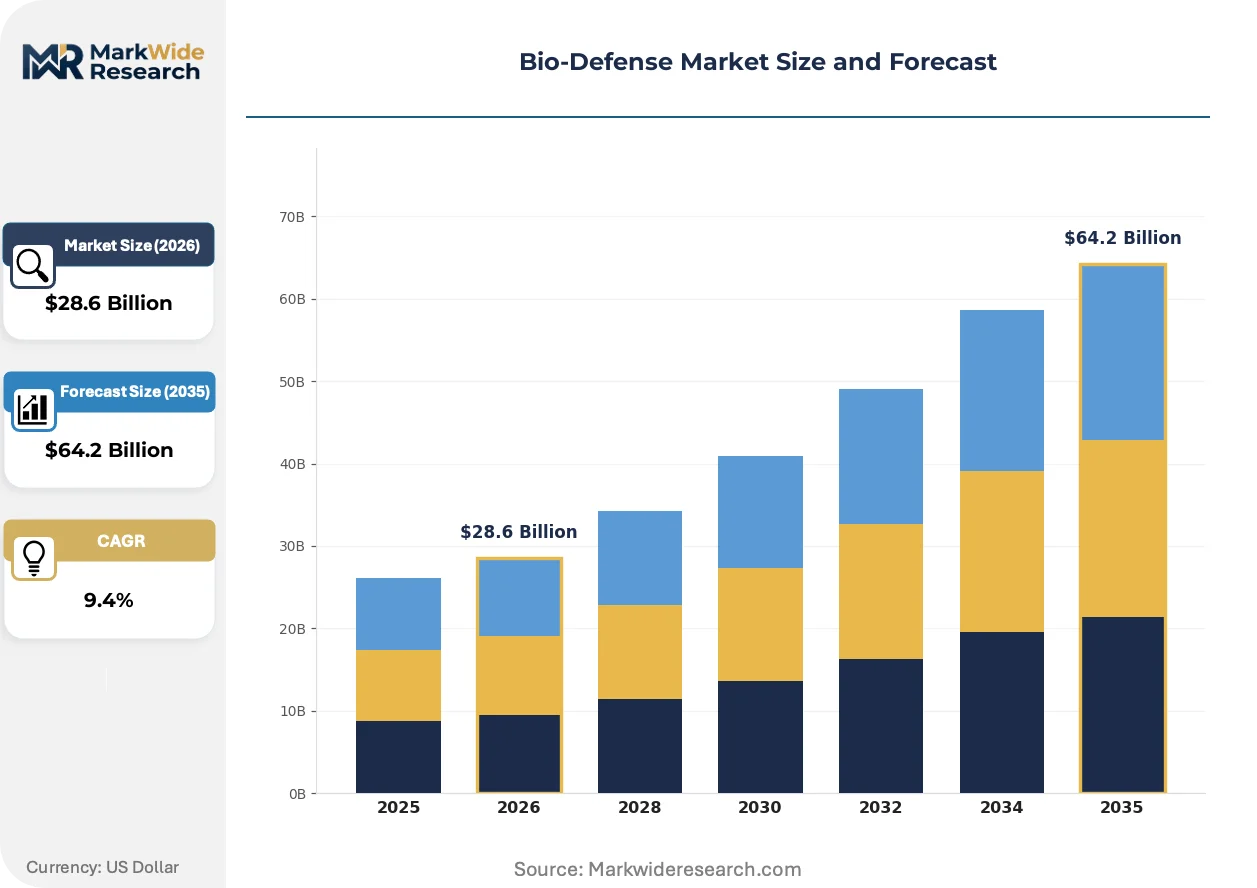
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antivirals, Antibodies, Diagnostics Application: Public Health, Biosecurity, Research, Military End User: Government Agencies, Hospitals, Research Institutions, Pharmaceutical Companies Technology: Molecular Techniques, Immunological Methods, Bioinformatics, Surveillance Systems |
| Companies Covered | Emergent BioSolutions Inc., SIGA Technologies Inc., Bavarian Nordic, Dynavax Technologies Corporation, XOMA Corporation, Altimmune Inc., Elusys Therapeutics Inc., Ichor Medical Systems, Cleveland Biolabs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Defense Market Strategic Shifts
Platform standardization and modular manufacturing architectures are displacing purpose-built single-pathogen production systems across the bio-defense value chain.
Messenger RNA manufacturing infrastructure is supplanting conventional egg-based and cell-culture vaccine production for rapid-response countermeasure categories. The US Department of Defense Joint Program Executive Office for Chemical, Biological, Radiological and Nuclear Defense is prioritizing platform technologies with sub-100-day response timelines. This acceleration is compressing incumbent supplier advantages rooted in legacy stockpile relationships.
The FDA's Animal Rule guidance revisions are tightening correlates-of-protection evidentiary standards for orthopoxvirus countermeasures. Developers must now demonstrate cross-species immunological bridging with greater statistical rigor than prior qualification cycles required. Small-molecule antiviral developers are responding by investing in non-human primate model standardization earlier in development timelines.
Stockpile procurement is consolidating toward multi-year indefinite-delivery contracts with performance-based milestone structures. BARDA and DOD buyers are shifting from product-specific awards to platform-agnostic technology maturation programs. This behavioral pivot is most pronounced in United States federal procurement, where vendor diversification mandates now accompany major platform acquisitions.
Bio-Defense Market Segmentation
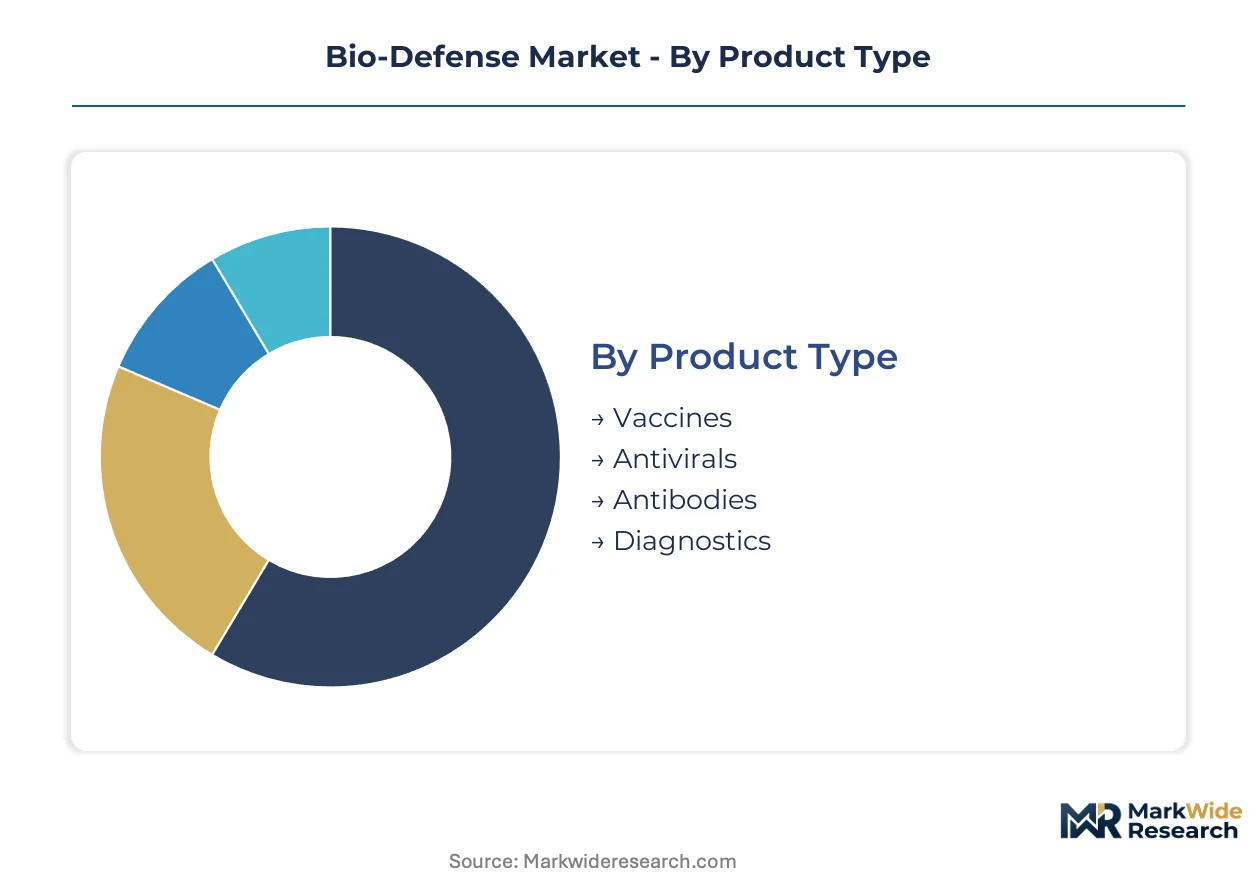
Bio-defense procurement allocates capital across distinct technical and institutional boundaries. Understanding where budget authority concentrates within each segmentation dimension determines supplier positioning and R&D prioritization.
Product Type:
Vaccines capture the deepest margin pools due to multi-year stockpile replenishment cycles and specialized cold-chain infrastructure requirements that limit competitive entry.
- Vaccines:Multi-dose regimens targeting Category A pathogens require BSL-3/4 validation and FDA Animal Rule approval. BARDA and DOD procurement programs in the United States anchor demand through Project BioShield indefinite-delivery contracts.
- Antivirals:Small-molecule therapeutics deliver post-exposure prophylaxis where vaccination windows have closed. SIGA Technologies' TPOXX platform demonstrates the procurement concentration around orthopoxvirus-specific antiviral stockpiles.
- Antibodies:Monoclonal platforms command premium positioning for rapid neutralization of toxin-mediated threats.
- Diagnostics:Molecular and immunological detection systems enable field-deployable identification at point-of-need.
The dominant share belongs to vaccines, while diagnostics is closing the gap fastest.
Application:
Military procurement operates on accelerated timelines that compress development-to-deployment cycles compared to civilian stockpile programs.
- Public Health:CDC and state health department stockpiles emphasize community-wide prophylaxis and surge capacity for outbreak response.
- Biosecurity:Facility protection and personnel screening protocols drive demand for detection and decontamination systems.
- Research:BSL-3/4 laboratory networks require validated reagents and reference materials for threat characterization.
- Military:Joint Program Executive Office for Chemical, Biological, Radiological and Nuclear Defense specifications prioritize platform technologies with sub-100-day response timelines.
Public health applications retain the largest installed base, though military procurement is expanding most quickly.
End User:
Government agencies control procurement volume through centralized stockpile authorities that aggregate demand across dispersed operational units.
- Government Agencies:BARDA, DOD, and CDC coordinate national stockpile composition through multi-year procurement frameworks.
- Hospitals:Acute care facilities require limited post-exposure therapeutics for emergency department presentation protocols.
- Research Institutions:NIH and university BSL-3/4 facilities consume specialized reagents for fundamental threat biology studies.
- Pharmaceutical Companies:Contract manufacturers and platform technology developers supply finished dosage forms to government stockpiles.
Government agencies dominate procurement volume, with pharmaceutical companies gaining share through platform technology maturation programs.
Technology:
Molecular techniques attract R&D investment due to regulatory pathway clarity and platform extensibility across multiple pathogen targets.
- Molecular Techniques:PCR and next-generation sequencing platforms enable rapid pathogen identification with high analytical specificity.
- Immunological Methods:Serological assays and lateral flow devices support field-deployable screening without laboratory infrastructure.
- Bioinformatics:Pathogen genomic databases and predictive modeling tools accelerate countermeasure design and threat assessment.
- Surveillance Systems:Environmental monitoring networks integrate aerosol detection with automated reporting to public health authorities.
Molecular techniques command the largest technology investment, while bioinformatics shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BARDA and DOD procurement authority concentrates demand among NATO-aligned defense ministries and national public health agencies with biodefense stockpile mandates.
United States
Federal stockpile replenishment cycles and Project BioShield indefinite-delivery contracts drive procurement volume. FDA Animal Rule requirements shape product development feasibility for domestic suppliers. Maryland's I-270 biotechnology corridor hosts multiple developers with BSL-3/4 validation capabilities and BARDA contract history.
Germany
EU Health Emergency Preparedness and Response Authority joint procurement mechanisms aggregate member state demand. Paul-Ehrlich-Institut regulatory standards align with EMA frameworks for high-consequence pathogen countermeasures. The Rhine-Main region clusters pharmaceutical manufacturing infrastructure with dual-use civilian-military production certifications.
United Kingdom
Post-pandemic institutional reforms at the UK Health Security Agency accelerate rapid-response platform procurement. The National Institute for Biological Standards and Control sets reference material specifications for domestic stockpile integration. Oxfordshire's Harwell Science Campus concentrates BSL-3 containment facilities with MOD co-funding arrangements.
Israel
Ministry of Defense procurement prioritizes platform technologies with sub-60-day response timelines for regional threat scenarios. Israel Institute for Biological Research maintains sovereign manufacturing capacity for Category A pathogen vaccines. Ness Ziona's biotechnology cluster houses state-affiliated research institutions with dedicated biodefense program funding.
Japan
Ministry of Defense and Ministry of Health, Labour and Welfare coordinate dual-use stockpile composition through centralized procurement frameworks. PMDA guidelines for emergency use authorization accelerate countermeasure deployment timelines. Kanto region pharmaceutical manufacturers maintain BSL-3 validation for government contract eligibility.
Bio-Defense Market Competitive Environment
Player mix skews toward vertically integrated vaccine manufacturers with legacy government contract relationships and specialized antiviral developers with single-pathogen platform focus. Market structure concentrates around BARDA-qualified suppliers with established Animal Rule approval histories. Strategic archetypes include stockpile-anchored incumbents, rapid-response platform specialists, and dual-use civilian-military technology providers. Competitive dynamics center on multi-year indefinite-delivery contract capture and BSL-4 manufacturing capacity expansion.
Within the stockpile-anchored tier, Emergent BioSolutions Inc. and Bavarian Nordic occupy positions defined by ACAM2000 and Jynneos manufacturing infrastructure respectively. SIGA Technologies Inc. represents the specialized antiviral archetype through TPOXX platform positioning. These three developers exemplify the contract concentration pattern where BARDA procurement history creates qualification barriers for new market entrants. Dynavax Technologies Corporation and Altimmune Inc. sit within the adjacency-expansion segment, leveraging platform technologies from civilian infectious disease applications toward biodefense qualification pathways.
| Leading Market Players |
|---|
| Emergent BioSolutions Inc. |
| SIGA Technologies Inc. |
| Bavarian Nordic |
| Dynavax Technologies Corporation |
| XOMA Corporation |
| Altimmune Inc. |
| Elusys Therapeutics Inc. |
| Ichor Medical Systems |
| Cleveland Biolabs |
| Others |
Value Chain & Pricing Dynamics
Messenger RNA manufacturing infrastructure replacing legacy egg-based and cell-culture systems is redrawing supply geography toward United States and European biotech corridors while compressing cost structures for rapid-response countermeasure categories. This substitution simultaneously elevates technical qualification barriers and shifts pricing power toward developers with validated BSL-4 containment and FDA Animal Rule approval histories.
Pricing Analysis
Cost-plus contracts with Bureau of Labor Statistics producer price index adjustment clauses dominate BARDA and DOD procurement, insulating qualified suppliers from raw material volatility while capping margin expansion. Price differentiation rests on FDA Animal Rule qualification status and BSL-4 manufacturing certification tier, with fully validated platforms commanding substantial premiums over developmental-stage alternatives. Pricing pressure stems from vendor diversification mandates embedded in multi-year indefinite-delivery contracts, compressing economics for incumbents without platform extensibility. Military procurement offices exhibit lowest price sensitivity given mission-critical specifications, while civilian public health stockpile managers demonstrate higher elasticity on non-Category A pathogen categories.
Supply Chain Analysis
Multi-year stockpile inventory requirements and 18-to-24-month manufacturing lead times for high-consequence pathogen vaccines create deliberate supply redundancy that strains working capital for contract manufacturers. Production concentrates in the United States, Germany, and Denmark, with the I-270 biotechnology corridor, Rhine-Main pharmaceutical cluster, and Copenhagen-area BSL-4 facilities anchoring global capacity. Raw material dependencies span specialized cell culture media, viral seed stocks, and cold-chain packaging systems sourced from Switzerland, Japan, and domestic suppliers. Single-source vulnerability concentrates in BSL-4 technician labor pools, where dual GMP-containment competency scarcity constrains throughput expansion. Distribution runs through CDC Strategic National Stockpile depots and NATO allied defense logistics networks with redundant temperature-controlled infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bio-defense market sits in early-cycle expansion as post-COVID-19 pandemic preparedness institutional reforms accelerate procurement velocity for rapid-response platform technologies across NATO member states.
For Market Incumbents: Fortify BSL-4 manufacturing capacity expansion in Maryland and Denmark to preempt emerging mRNA platform specialists from securing Animal Rule qualification. Lock in multi-year indefinite-delivery contract renewals before BARDA vendor diversification mandates fully phase in, while accelerating cross-species immunological bridging studies to tighten correlates-of-protection evidentiary standards that new entrants cannot quickly replicate. For New Entrants and Emerging Players: Differentiate on sub-100-day response timeline capabilities aligned with DOD Joint Program Executive Office specifications, targeting the United Kingdom's post-pandemic rapid-response procurement reforms as the most penetrable geography. Prioritize point-of-need molecular diagnostics and antibody-drug conjugate platforms where regulatory pathways remain less encumbered by legacy stockpile relationships, deploying BARDA technology maturation program partnerships as the primary go-to-market mechanism. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed contract manufacturers possessing BSL-3 validation but lacking full BSL-4 containment and Animal Rule approval histories. Five-to-ten year viability hinges on successful platform qualification transitions from civilian infectious disease adjacencies into biodefense stockpile integration. Acquisition target archetypes include rapid-response mRNA developers with DOD Joint Program Executive Office relationships and European dual-use civilian-military technology providers. The signal to watch is BARDA appropriation trajectory shifts for Project BioShield and international biodefense cooperation framework expansions.| Strategic Initiative | Industry Significance |
|---|---|
| BSL-4 Manufacturing Scale-Up | Expands throughput for Category A pathogen vaccines under FDA Animal Rule requirements. |
| Animal Rule Qualification Pathway | Enables correlates-of-protection approval for orthopoxvirus and hemorrhagic fever countermeasures. |
| Platform Technology Licensing | Accelerates mRNA and viral vector access for rapid-response DOD procurement specifications. |
| Multi-Year Supply Agreement | Locks in CDC Strategic National Stockpile replenishment cycles against vendor diversification mandates. |
| Dual-Use Civilian-Military Certification | Qualifies European production for EU Health Emergency Preparedness and Response Authority joint procurement. |
Study Parameters
The analysis maps vaccines, antivirals, antibodies, and diagnostics segments, each validated through procurement officers at BARDA, DOD Joint Program Executive Office for Chemical, Biological, Radiological and Nuclear Defense, and CDC Strategic National Stockpile, supplemented by regulatory affairs leads at developers with Animal Rule approval histories and BSL-4 facility operations directors. Secondary sources encompass FDA guidance documents and Animal Rule determinations, BARDA contract award databases, DOD budget justification materials, EMA scientific advice letters, and Paul-Ehrlich-Institut regulatory frameworks. Bottom-up stockpile procurement volume estimates triangulate against top-down national biodefense appropriation analysis.
Consistency checks validate volume and value outputs against NATO member state defense ministry budget disclosures, EU Health Emergency Preparedness and Response Authority joint procurement announcements, and United Kingdom Health Security Agency rapid-response framework documentation. Segmentation dimensions span product type, application, end user, and technology platform, with additional modeling across regulatory approval pathway tier and containment level certification. CAGRs derive from procurement cycle analysis and stockpile replenishment schedule modeling, incorporating BSL-4 capacity expansion timelines and FDA Animal Rule evidentiary requirement evolution as industry-specific forecast inputs across the projection horizon.
Material uncertainties — government pandemic preparedness appropriation volatility, international biodefense cooperation framework durability, and FDA Animal Rule guidance revision timing — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding BARDA funding continuity and NATO allied procurement coordination. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Smart War Weapon Market
Defense and Military Systems and Equipment
Missiles and Missile Defense Systems Market
Defense and Military Systems and Equipment
Saudi Arabia Defense Market
Defense and Military Systems and Equipment
Military Parachute Market
Defense and Military Systems and Equipment
Asia-Pacific Digital Battlefield Market
Defense and Military Systems and Equipment
Mechanical and Electronic Fuzes Market
Defense and Military Systems and Equipment
Counter-IED Systems Market
Defense and Military Systems and Equipment
Military Load Carriage System Market
Defense and Military Systems and Equipment
Defense Integrated Antenna Market
Defense and Military Systems and Equipment
Europe Missiles and Missile Defense Systems Market
Defense and Military Systems and Equipment
Search and Rescue Equipment Market
Defense and Military Systems and Equipment
Explosive Ordnance Disposal (EOD) Equipment Market
Defense and Military Systems and Equipment
Military Actuators Market
Defense and Military Systems and Equipment
Mine Clearance System Market
Defense and Military Systems and Equipment
Military Embedded System Software Market
Defense and Military Systems and Equipment
Defense Tactical Computers Market