
 Anti-Jamming Equipment Market | 2026-2036
Anti-Jamming Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Jamming Equipment Market Outlook
Software-defined feature licensing is consolidating as a discrete revenue layer in anti-jamming equipment contracts, shifting vendor economics from hardware margins to recurring capability upgrades. RTX Corporation leverages its radar heritage to anchor long-term service agreements across naval platforms. Northrop Grumman Corporation sustains R&D intensity in quantum-resistant signal processing. Lockheed Martin Corporation dominates classified military procurement channels through integrated electronic warfare suites.
Anti-jamming equipment encompasses electronic systems designed to detect, nullify, or circumvent deliberate interference across radio frequency spectra, typically operating across L-band through Ka-band with adaptive null-steering antenna arrays and real-time spectral analysis. These systems protect critical navigation, communication, and timing infrastructure from intentional disruption in contested electromagnetic environments. Military Operations application segments command the deepest margin pools due to classified performance requirements and multi-year program cycles. Software-Defined Radio technology segments are expanding fastest as firmware-upgradable architectures displace fixed-function hardware in both vehicle jammer and portable jammer form factors. Spread Spectrum technology segments retain mature positions in civil aviation where certification inertia preserves incumbent supplier relationships.
FCC spectrum allocation rulings and EU Electronic Warfare directives shape permissible frequency agility ranges for commercial-grade anti-jamming systems, while ITAR export controls constrain cross-border technology transfer for military-tier products. NATO standardization agreements increasingly mandate interoperable jamming resistance protocols across member nation defense procurement. Stakeholders must monitor evolving cryptographic certification timelines and electromagnetic compatibility testing regimes to align product roadmaps with fragmented national security requirements.
Market Dynamics
Defense procurement officers are consolidating vendor relationships around firmware-upgradable architectures, compressing hardware replacement cycles and elevating software licensing to primary contract value.
Growth Catalysts
- GPS denial warfare doctrine:NATO electronic warfare mandates now require interoperable jamming resistance across member state naval and aerial platforms. Military procurement channels are prioritizing systems with real-time spectral adaptation.
- FCC spectrum agility rulings:Commercial aviation operators in the United States must deploy adaptive null-steering arrays to maintain navigation integrity in contested electromagnetic environments. Certification timelines are accelerating for L-band through Ka-band systems.
- Software-defined radio firmware:Vehicle-mounted and portable jammer form factors are transitioning from fixed-function hardware to field-upgradable architectures. Defense contractors are embedding recurring revenue streams through capability licensing.
Market Restraints
- ITAR export control friction:Cross-border technology transfer for military-tier anti-jamming systems faces multi-month approval delays. Non-US allies experience procurement timeline extensions for quantum-resistant signal processing components.
- Gallium nitride substrate concentration:High-frequency power amplifier supply depends on concentrated semiconductor foundry capacity in East Asian manufacturing clusters. Input cost volatility affects adaptive antenna array production economics.
- Spread spectrum certification inertia:Civil aviation regulators maintain lengthy validation protocols for legacy signal modulation standards. Incumbent supplier relationships in commercial air transport resist displacement by null-steering alternatives.
Strategic Opportunities
- Quantum-resistant algorithm integration:Post-quantum cryptographic standards from NIST are creating upgrade cycles for existing military communications infrastructure. Vendors with early algorithm certification capture multi-year service agreements.
- Unmanned platform integration:Naval drone swarms and autonomous aerial systems require miniaturized anti-jamming modules with sub-watt power budgets. Form factor innovation opens procurement channels outside traditional manned vehicle programs.
- EU Electronic Warfare directive harmonization:Standardized electromagnetic compatibility testing across European member states reduces fragmentation in commercial-grade system certification. Pan-European procurement frameworks are consolidating vendor qualification processes.
Industry Challenges
- Electromagnetic compatibility test facility scarcity:Validated anechoic chamber capacity for adaptive null-steering certification is concentrated at defense agency laboratories. Commercial product development timelines face 6-12 month queue delays.
- Legacy system integration complexity:Fielded military platforms with fixed-function radio architectures require hardware retrofitting to accommodate software-defined upgrade paths. Platform-specific engineering consumes non-recurring engineering budgets.
- RF engineer talent pipeline:Specialized expertise in real-time spectral analysis and adaptive beamforming is concentrated among defense contractor workforces with security clearance requirements. Civilian-sector hiring competes for limited qualified personnel.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Jamming Equipment Market |
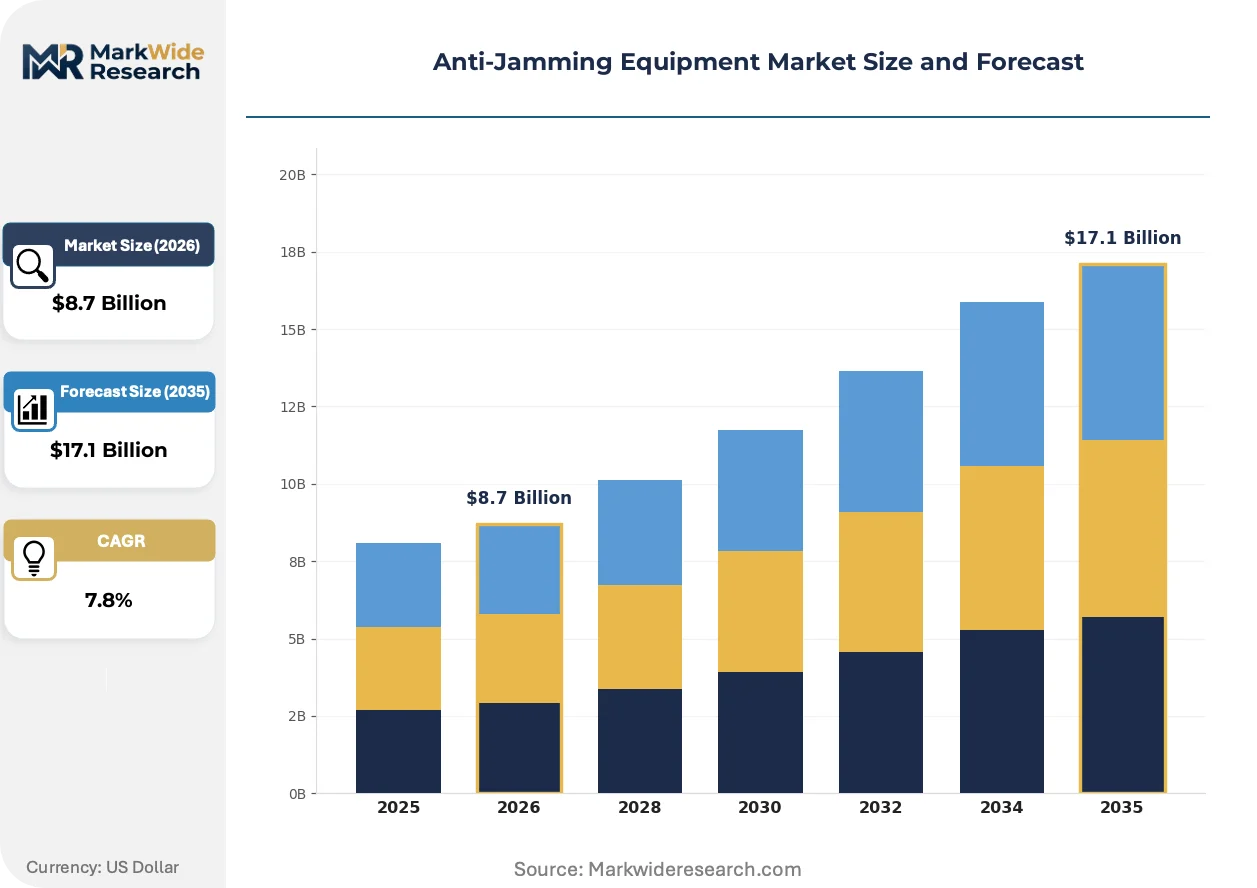
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Jammer, Vehicle Jammer, Network Jammer, Desktop Jammer Technology: Frequency Hopping, Spread Spectrum, Software-Defined Radio, Active Jamming Application: Military Operations, Civil Aviation, Private Security, Telecommunications End User: Government Agencies, Commercial Enterprises, Defense Contractors, Police Forces |
| Companies Covered | RTX Corporation, Northrop Grumman Corporation, Lockheed Martin Corporation, Thales Group, BAE Systems, L3Harris Technologies, Elbit Systems, Leonardo S.p.A., General Dynamics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Jamming Equipment Market Strategic Shifts
Adaptive null-steering algorithms are migrating from dedicated signal processors to general-purpose computing fabrics, collapsing hardware bill-of-materials while expanding firmware-defined feature scope.
Cognitive radio architectures with machine-learning-based interference prediction are expanding into naval surface combatant programs, where electromagnetic spectrum congestion demands predictive rather than reactive jamming mitigation. The US Navy's integrated electronic warfare suites are adopting these systems for carrier strike group coordination. Firmware-defined capability expansion is compressing hardware refresh cycles from decade-long platform programs to annual software releases.
EU Electronic Warfare directives are mandating interoperable jamming resistance protocols across member state procurement, forcing vendors to disclose previously proprietary signal processing interfaces. Industrial consequence includes standardization of antenna control bus specifications and null-steering algorithm benchmarking methodologies. German and French defense procurement agencies are coordinating electromagnetic compatibility testing regimes to reduce duplicate certification costs for cross-border platform sales.
Service contract unbundling is separating hardware procurement from capability upgrade subscriptions across NATO military procurement channels. Traditional system integrators are losing margin to specialized software vendors with cryptographic certification authority. This pattern is most visible in United Kingdom Ministry of Defence satellite navigation protection programs, where five-year hardware warranties now exclude firmware feature releases requiring separate licensing.
Anti-Jamming Equipment Market Segmentation
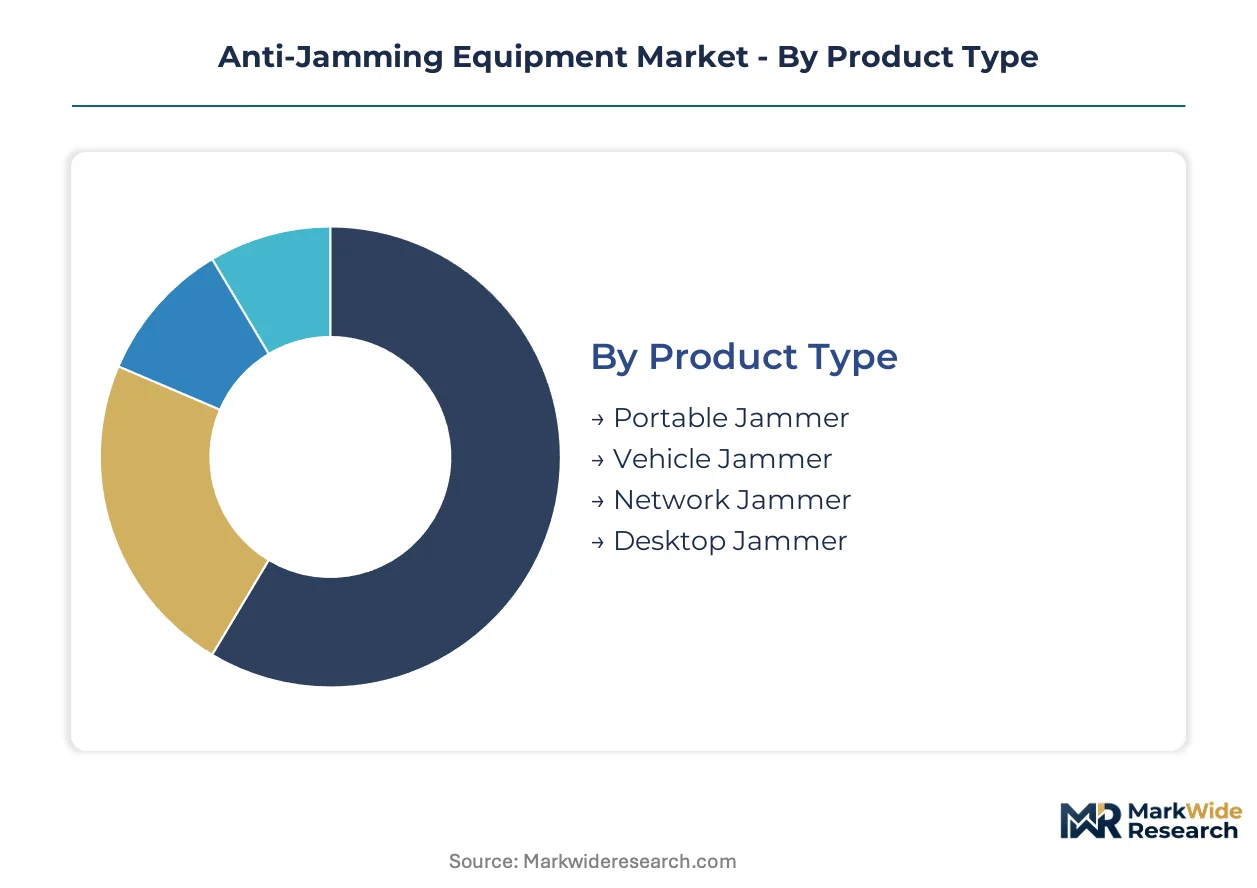
Anti-jamming equipment procurement patterns diverge sharply across form factors, signal processing architectures, and security clearance tiers. Vendors must architect product lines spanning field-portable units to integrated naval suites while navigating distinct certification regimes for military versus civil applications.
Product Type:
Standardization dominates portable and desktop units with modular subassemblies, while vehicle and network jammers demand extensive platform-specific customization.
- Portable Jammer:Battery-powered units with sub-watt power budgets integrate adaptive null-steering arrays for dismounted soldier operations. Demand concentrates in special forces procurement channels across NATO member states, driven by GPS denial warfare doctrine mandating individual navigation protection.
- Vehicle Jammer:Platform-integrated systems with active antenna arrays protect convoy communications across contested electromagnetic environments. German and French defense procurement agencies specify these for armored vehicle modernization programs, constrained by ITAR export control friction for non-allied nations.
- Network Jammer:Enterprise-scale systems protect critical infrastructure timing and communication backbones.
- Desktop Jammer:Fixed-site units secure command center operations with reduced mobility requirements.
Gaining share fastest: Vehicle Jammer. Leading by volume: Portable Jammer.
Technology:
Cost tiers separate mature modulation techniques from firmware-upgradable architectures commanding premium licensing revenue.
- Software-Defined Radio:Field-programmable signal processors enable real-time spectral adaptation through firmware updates without hardware replacement. US Navy integrated electronic warfare suites and UK Ministry of Defence satellite navigation programs anchor demand, with capability licensing now unbundled from hardware procurement.
- Spread Spectrum:Legacy direct-sequence and frequency-hopping modulation retains entrenched positions in civil aviation where FAA certification inertia preserves incumbent supplier relationships.
- Frequency Hopping:Rapid channel switching architectures protect tactical communications from targeted interference.
- Active Jamming:Countermeasure systems detect and neutralize hostile jamming sources through responsive transmission.
Expanding most quickly: Software-Defined Radio. Maturest position: Spread Spectrum.
Application:
Margin concentration aligns with security classification levels, from classified military programs to commercial certification-driven aviation markets.
- Military Operations:Classified performance requirements and multi-year program cycles command the deepest margin pools. NATO electronic warfare mandates now require interoperable jamming resistance across member state naval and aerial platforms, consolidating procurement around firmware-upgradable architectures.
- Civil Aviation:FAA adaptive null-steering array certifications and EU Electronic Warfare directive harmonization shape commercial aviation operator requirements. FCC spectrum agility rulings accelerate L-band through Ka-band system deployment timelines.
- Private Security:Corporate and critical infrastructure protection drives demand for commercial-grade systems with reduced capability tiers.
- Telecommunications:Network operators deploy anti-jamming to protect timing synchronization and backhaul integrity.
Deepest margins: Military Operations. Steepest certification barriers: Civil Aviation.
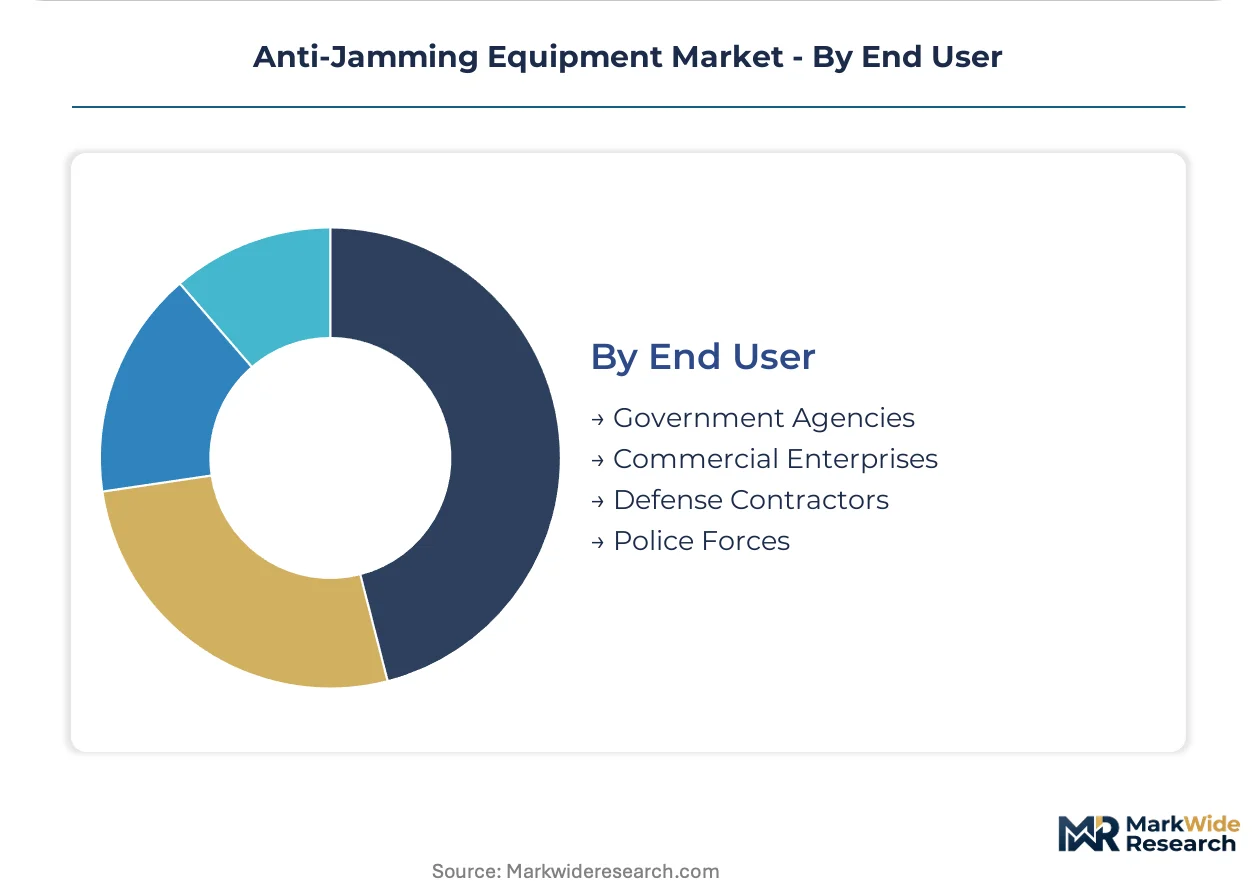
End User:
Customer type determines contract structure, from classified military service agreements to commercial volume procurement with discrete feature licensing.
- Government Agencies:Intelligence and homeland security organizations require quantum-resistant signal processing with NIST post-quantum cryptographic certification. Multi-year service agreements with embedded firmware upgrade subscriptions dominate contract economics.
- Defense Contractors:System integrators source anti-jamming modules for platform integration across naval, aerial, and ground vehicle programs. NATO standardization agreements increasingly mandate interoperable jamming resistance protocols, forcing interface disclosure.
- Commercial Enterprises:Telecommunications operators and critical infrastructure owners procure commercial-grade systems under FCC and EU regulatory frameworks.
- Police Forces:Law enforcement agencies deploy portable and vehicle-mounted units for tactical operations and dignitary protection.
Longest contract cycles: Government Agencies. Fastest procurement velocity: Police Forces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement concentrates in NATO member states while semiconductor fabrication for RF components clusters in East Asian manufacturing hubs, creating a geographic split between system integration and upstream component supply.
United States
The Pentagon's GPS denial warfare doctrine and FCC spectrum agility rulings drive demand for adaptive null-steering arrays across naval and aerial platforms. ITAR export controls constrain cross-border technology transfer, privileging domestic contractors in classified procurement channels. RTX Corporation leverages its radar heritage to anchor long-term service agreements from its Virginia and Massachusetts facilities.
Germany
The Bundeswehr's armored vehicle modernization programs specify vehicle-integrated anti-jamming systems with active antenna arrays for convoy protection. EU Electronic Warfare directives mandate interoperable jamming resistance protocols, forcing interface standardization across member state procurement. Defense contractors in Bavaria and North Rhine-Westphalia coordinate electromagnetic compatibility testing with French agencies to reduce certification duplication.
France
Thales Group anchors naval electronic warfare suite development for carrier strike group coordination, with machine-learning-based interference prediction migrating into surface combatant programs. The country's national defense procurement agency coordinates with German counterparts on pan-European vendor qualification frameworks. Paris-region laboratories concentrate validated anechoic chamber capacity for adaptive null-steering certification.
United Kingdom
Ministry of Defence satellite navigation protection programs unbundle hardware procurement from firmware capability licensing, compressing traditional system integrator margins. Post-quantum cryptographic standards from NIST create upgrade cycles for existing military communications infrastructure. UK-based specialists capture multi-year service agreements through early algorithm certification.
Israel
Elbit Systems exemplifies miniaturized anti-jamming module development for unmanned platform integration, addressing sub-watt power budgets required by naval drone swarms. The country's national security establishment prioritizes quantum-resistant signal processing for tactical communications. Tel Aviv-area engineering clusters concentrate RF expertise in adaptive beamforming and real-time spectral analysis.
Anti-Jamming Equipment Market Competitive Environment
Capital-heavy producers with captive semiconductor fabrication compete with asset-light designers dependent on foundry partnerships for gallium nitride substrate supply. The vendor base stratifies across three tiers: integrated defense conglomerates with platform-level electronic warfare suites, specialized RF component suppliers with cryptographic certification authority, and emerging software vendors unbundling capability licensing from hardware procurement. Dominant competitive moves include strategic partnerships for electromagnetic compatibility test facility access and technology licensing agreements for quantum-resistant algorithm integration.
Within the integrated defense conglomerate tier, RTX Corporation, Northrop Grumman Corporation, and Lockheed Martin Corporation exemplify contrasting strategic positions. RTX Corporation occupies a position anchored in radar heritage and naval platform service agreements. Northrop Grumman Corporation represents sustained R&D intensity in signal processing architectures. Lockheed Martin Corporation sits within classified military procurement channels through integrated electronic warfare suite dominance. These three US-based corporations illustrate how firmware-defined capability expansion is compressing hardware refresh cycles and elevating software licensing to primary contract value.
| Leading Market Players |
|---|
| RTX Corporation |
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| Thales Group |
| BAE Systems |
| L3Harris Technologies |
| Elbit Systems |
| Leonardo S.p.A. |
| General Dynamics Corporation |
| Others |
Value Chain & Pricing Dynamics
NATO electronic warfare mandates requiring interoperable jamming resistance protocols are compressing hardware replacement cycles and elevating firmware licensing to primary contract value, forcing suppliers to restructure around recurring revenue models and away from one-time equipment sales.
Pricing Analysis
Cost-down pressure on military-tier systems accelerates because defense procurement officers are consolidating vendor relationships around firmware-upgradable architectures. Three-tier pricing structure across classified, dual-use, and commercial-grade levels separates systems by ITAR export control tier and NIST cryptographic certification status. Price differentiation traces to electromagnetic compatibility testing completion and quantum-resistant algorithm integration. Commercial aviation operators exhibit highest price sensitivity due to FAA certification cost absorption, while intelligence agencies accept premium positioning for post-quantum cryptographic standards compliance.
Supply Chain Analysis
Gallium nitride substrate supply rests on concentrated semiconductor foundry capacity in Taiwan, South Korea, and Japan. High-frequency power amplifier production draws from specialized epitaxial wafer suppliers and precision antenna array fabricators. Single-source vulnerability concentrates in East Asian manufacturing clusters for RF component substrates. Distribution runs through defense contractor prime channels with ITAR-controlled logistics and classified facility clearances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where FCC spectrum agility rulings and EU Electronic Warfare directives erect barrier-to-entry moats for vendors with completed certification timelines.
For Market Incumbents: Deploy firmware licensing unbundling to capture recurring revenue streams from hardware procurement relationships. RTX Corporation's naval platform service agreements exemplify anchoring long-term contracts through radar heritage integration. Counter emerging software vendors with cryptographic certification authority by accelerating NIST post-quantum algorithm integration into existing military communications infrastructure. For New Entrants and Emerging Players: The gap between premium classified military systems and economy-tier commercial aviation equipment opens procurement channels in private security and telecommunications timing protection. Police forces and critical infrastructure operators present fastest procurement velocity with reduced capability requirements. Pursue electromagnetic compatibility test facility partnerships to bypass 6-12 month queue delays at defense agency laboratories. For Investors and Strategic Acquirers: The window for entry favors specialized RF component suppliers with cryptographic certification authority and adaptive beamforming expertise. Long-term viability centers on vendors positioned for quantum-resistant algorithm upgrade cycles across NATO member state procurement. Watch for EU Electronic Warfare directive harmonization completion as inflection indicator for pan-European vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Quantum-Resistant Algorithm Certification | NIST post-quantum standards create multi-year service agreement capture opportunities for early certifiers. |
| Electromagnetic Compatibility Test Facility Partnership | Access to validated anechoic chambers collapses commercial product development timelines by 6-12 months. |
| Firmware Capability Licensing Unbundling | UK Ministry of Defence satellite navigation programs demonstrate hardware procurement separation from upgrade subscriptions. |
| Unmanned Platform Miniaturization | US Navy drone swarm requirements open procurement channels outside traditional manned vehicle programs. |
| EU Directive Harmonization Alignment | German-French coordination on vendor qualification reduces certification duplication costs for cross-border sales. |
Study Parameters
Independent corroboration across defense procurement officers, RF engineering directors, and electromagnetic compatibility test facility managers underwrites the qualitative findings in this analysis. Primary interviews with platform integration specialists, cryptographic certification authorities, and naval electronic warfare suite program managers combined with secondary validation from FCC spectrum allocation rulings, EU Electronic Warfare directive filings, NATO standardization agreement documentation, and ITAR export control disclosure records. Bottom-up segment sizing and top-down market triangulation anchored the quantitative framework.
Comparable-period anchoring to historical defense procurement cycles established the forecast window baseline across the analysis window. The modeling framework segmented by product type, technology architecture, application security classification, and end-user contract structure. CAGRs derived from trend extrapolation of firmware-upgradable adoption rates and quantum-resistant upgrade cycle timing. Industry-specific inputs included gallium nitride substrate supply constraints and electromagnetic compatibility certification queue dynamics.
Inputs from defense contractor program managers and regulatory filing documentation were available through the study window; gaps in classified military procurement channel visibility introduce uncertainty bands around platform-specific demand quantification. Forecasts reflect documented assumptions regarding NATO mandate implementation timelines and NIST cryptographic standard adoption velocity. A small set of triggers—including ITAR export control relaxation, anechoic chamber capacity expansion, and post-quantum algorithm acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Defense Tactical Computers Market
Defense and Military Systems and Equipment
Military Phased Array Antenna Market
Defense and Military Systems and Equipment
Land-Based Smart Weapons Market
Defense and Military Systems and Equipment
Global Digital Battlefield Market
Defense and Military Systems and Equipment
Smart War Weapon Market
Defense and Military Systems and Equipment
Military Rifle Market
Defense and Military Systems and Equipment
Global Battlefield Management System Market
Defense and Military Systems and Equipment
Europe Defense Market
Defense and Military Systems and Equipment
Mine Clearance System Market
Defense and Military Systems and Equipment
Defense Integrated Antenna Market
Defense and Military Systems and Equipment
Bio-Defense Market
Defense and Military Systems and Equipment
Military Aerospace and Defense Lifecycle Management Market
Defense and Military Systems and Equipment
United States Defense Market
Defense and Military Systems and Equipment
Military Laser Systems Market
Defense and Military Systems and Equipment
Military Vetronics Market
Defense and Military Systems and Equipment
Global Military Laser Designator Market