
 Airborne Electronic Warfare Market | 2026-2036
Airborne Electronic Warfare Market Size, Share, and Industry Trends Forecast 2026-2036
Airborne Electronic Warfare Market Outlook
REACH compliance is shifting material sourcing and subsystem certification costs for European suppliers of airborne electronic warfare components. Lockheed Martin leverages captive semiconductor fabrication to sustain margins on advanced jamming pods. BAE Systems anchors its position through deep integration with UK Ministry of Defence platform programs. Northrop Grumman differentiates via dominance in next-generation electronic attack architectures for manned-unmanned teaming.
Airborne electronic warfare encompasses the suite of technologies, systems, and tactics designed to exploit, deceive, or deny adversary use of the electromagnetic spectrum, typically operating across frequency ranges from HF through millimeter wave with power outputs scaling from watts to megawatts depending on mission profile. These systems serve primarily to protect strike aircraft, enable intelligence collection, and suppress enemy air defenses during contested operations. Electronic Attack platforms command the largest value share due to integration complexity and platform-specific engineering requirements, while UAV-mounted electronic warfare systems represent the fastest-expanding segment as drone swarm tactics mature. Signal Intelligence capabilities concentrate margin pools where software-defined radio architectures enable rapid reprogramming against evolving threat signatures.
The US Department of Defense, the European Defence Agency, and NATO's Electronic Warfare Working Group collectively shape procurement standards, interoperability mandates, and spectrum allocation protocols that determine market access for subsystem vendors. FAA certification requirements for unmanned platforms carrying electronic payloads add a civilian regulatory layer that constrains dual-use technology transfer timelines. Stakeholders must monitor electromagnetic spectrum policy evolution across multiple defense ministries to anticipate platform modernization cycles and allied interoperability investments.
Market Dynamics
Electromagnetic spectrum superiority mandates from the US Department of Defense are compressing platform procurement cycles while forcing subsystem vendors to rearchitect around software-defined radio cores. This pressure cascades through NATO supply chains as interoperability certifications become non-negotiable for market access.
Growth Catalysts
- Next-Generation Air Dominance programs:The US Air Force's NGAD initiative is accelerating demand for integrated electronic attack suites that operate across contested spectrum environments. Platform-specific engineering requirements are expanding contract values for specialized subsystem vendors.
- REACH material compliance:European suppliers face mandatory substance restrictions that favor domestic component manufacturers with established certification pathways. This regulatory framework is reshaping sourcing decisions for gallium nitride and other critical semiconductor materials.
- Manned-unmanned teaming architectures:Distributed electronic warfare nodes operating across drone swarms require miniature high-power amplifiers. Military procurement offices in Germany, France, and the United Kingdom are funding rapid prototyping programs for these payload categories.
Market Restraints
- Gallium nitride substrate concentration:Single-source dependency on Japanese and US wafer suppliers creates vulnerability in high-power amplifier production chains. Price volatility for six-inch SiC substrates directly impacts jamming pod manufacturing economics.
- FAA unmanned platform certification:Civilian airworthiness requirements for electronic payload carriage impose multi-year validation timelines on dual-use technology developers. These procedural barriers delay revenue recognition for cross-over subsystem vendors.
- Legacy analog system substitution:Existing vacuum tube-based threat warning receivers in older fighter fleets resist digital retrofit due to airframe integration constraints. Platform operators face binary choices between full modernization and capability gaps.
Strategic Opportunities
- Poland and Baltic states:NATO's eastern flank members are procuring standoff jamming capabilities without established domestic supplier relationships. Foreign vendors with rapid fielding track records can capture foundational platform positions before long-term maintenance contracts lock in.
- AI-enabled threat library updates:Machine learning architectures for real-time signal classification are converging with software-defined radio hardware. This technology pairing enables subscription-style recurring revenue from threat database refreshes rather than one-time hardware sales.
- CE marking pathway expansion:European Defence Fund incentives for cross-border consortium participation reduce certification cost burdens for small and mid-sized subsystem developers. Qualified vendors gain preferential access to Franco-German next-generation fighter programs.
Industry Challenges
- Electromagnetic spectrum engineering talent:Specialized RF design expertise for millimeter-wave power combining remains concentrated among a narrow cohort of defense-aerospace veterans. Universities in the United States and United Kingdom are struggling to replenish this human capital pipeline.
- Platform integration complexity:Fifth-generation stealth aircraft impose severe thermal and signature constraints on external jamming pod carriage. Subsystem vendors must co-develop with prime contractors from preliminary design review forward, compressing independent margin capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airborne Electronic Warfare Market |
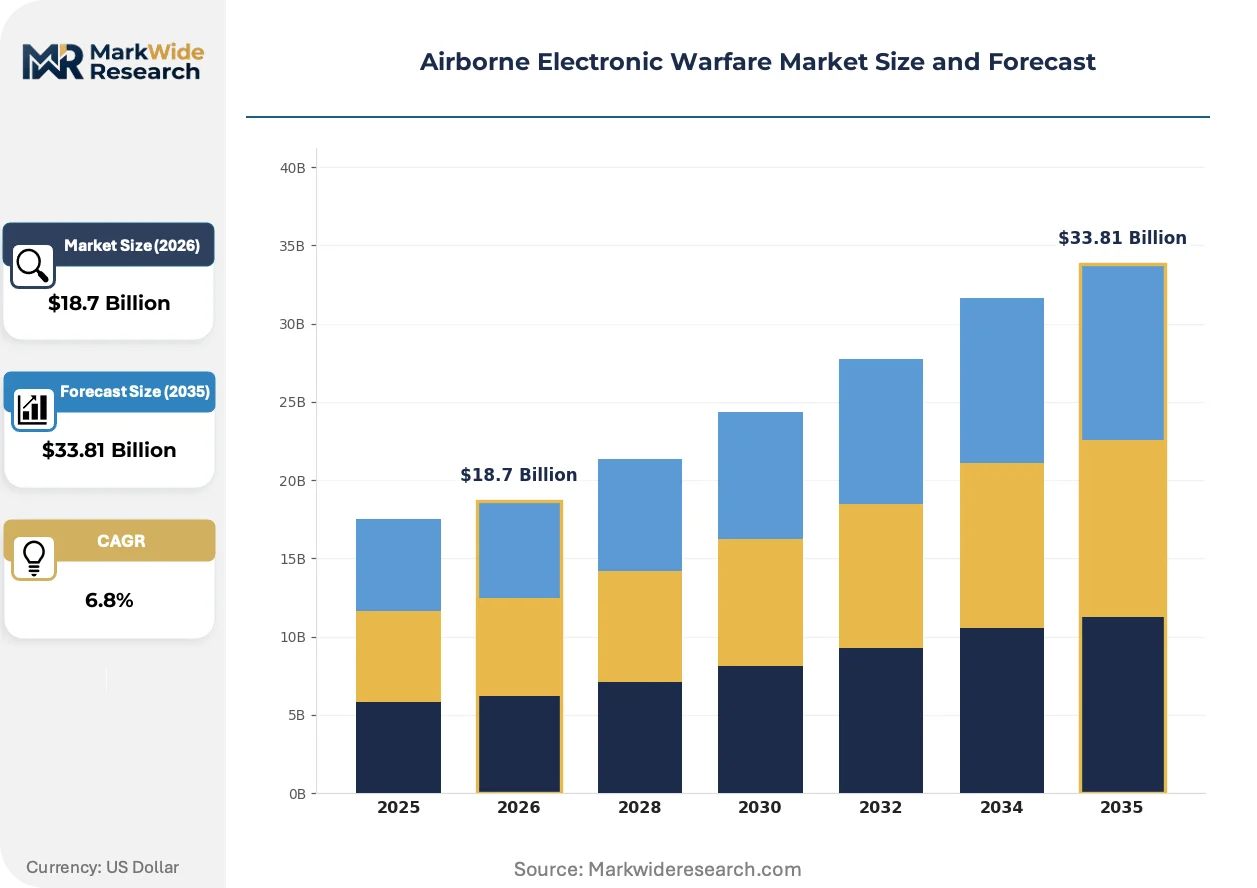
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electronic Support Measures, Electronic Attack, Electronic Countermeasures, Signal Intelligence End User: Military Forces, Defense Contractors, Government Agencies, Private Sector Platform Type: Fixed-Wing Aircraft, Rotary-Wing Aircraft, UAVs, Drones Type: Counter-Radar Systems, Jammers, Communication Disruption Systems, Simulation Equipment |
| Companies Covered | Lockheed Martin, RTX, BAE Systems, Elbit Systems, Leonardo, Northrop Grumman, Thales Group, General Dynamics, L3Harris Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airborne Electronic Warfare Market Strategic Shifts
Digital radio frequency memory technology is displacing analog deception techniques across electronic attack platforms. This transition is compressing development cycles while elevating software architecture competence above hardware-centric legacy capabilities.
Software-defined electronic warfare payloads are consolidating mission functions previously distributed across dedicated hardware boxes. The US Navy's Next Generation Jammer program and Royal Air Force Tempest initiatives are both specifying reprogrammable architectures that adapt to emerging threat signatures without physical retrofit. This consolidation is collapsing the traditional segmentation between electronic attack, electronic protect, and signals intelligence subsystems into unified software stacks.
REACH substance restrictions are forcing reformulation of conformal coating materials and thermal interface compounds used in high-power amplifier modules. European subsystem suppliers face 18-month recertification timelines for revised material specifications, advantaging competitors with pre-qualified alternative chemistries. The F-35 European partner nations represent the most affected procurement segment, with national maintenance facilities scrambling to establish compliant repair pathways.
Defense ministries are unbundling electronic warfare subsystem procurement from prime platform contracts, creating direct vendor relationships for spiral capability upgrades. The US Navy's Airborne Electronic Attack Systems Program Office now issues separate indefinite-delivery contracts for pod hardware, software, and sustainment. This disaggregation is most visible in the Pacific theater, where expeditionary maintenance units require rapid module swap capabilities without prime contractor technical assistance.
Airborne Electronic Warfare Market Segmentation
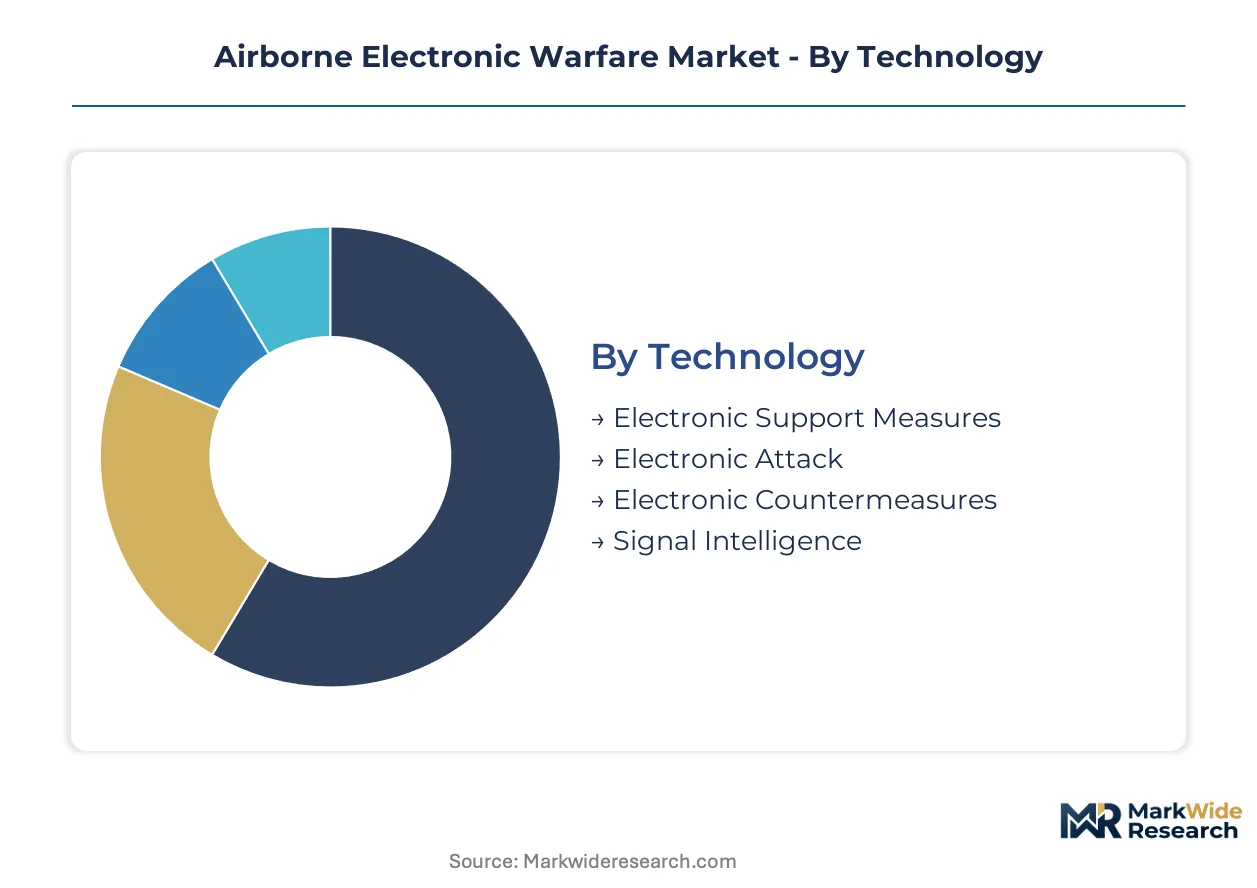
Segmentation in airborne electronic warfare reveals how mission requirements dictate technology selection across platform types. Procurement patterns diverge sharply between sovereign military operators and defense contractors serving allied export markets.
Technology:
Customization intensity spans from reprogrammable software-defined cores to fixed-function hardware architectures.
- Electronic Support Measures:Passive detection systems intercept and analyze adversary emissions across frequency bands. Military forces in the United States prioritize wideband digital receivers for threat warning applications. Procurement concentrates where platform survivability depends on real-time emitter geolocation.
- Electronic Attack:Active jamming and deception platforms deliver high-power electromagnetic interference against radar and communications. The US Department of Defense's Next Generation Jammer program exemplifies demand for software-reprogrammable attack capabilities. Integration complexity elevates contract values for specialized subsystem vendors.
- Electronic Countermeasures:Defensive suites protect aircraft from guided missile threats through signature reduction and decoy deployment. NATO member states fund rapid upgrades to counter hypersonic weapon seekers.
- Signal Intelligence:Collection and analysis systems exploit adversary communications for operational intelligence. Software-defined radio architectures enable rapid reconfiguration against evolving encryption standards.
Most installed capacity flows through Electronic Support Measures. Expansion is steepest in Electronic Attack.
End User:
Volume concentration versus margin capture separates sovereign procurement from commercial defense supply.
- Military Forces:Uniformed services operate the majority of fielded electronic warfare platforms. The US Air Force, US Navy, and UK Royal Air Force drive specifications for integrated electronic attack suites. Budget authority for spiral upgrades creates recurring revenue streams for subsystem vendors.
- Defense Contractors:Prime manufacturers integrate electronic warfare subsystems into complete weapon systems. BAE Systems and Northrop Grumman maintain captive capabilities while sourcing specialized components. Margin pressure intensifies where interoperability certifications become mandatory.
- Government Agencies:Intelligence community operators fund specialized signals collection platforms. National technical means requirements sustain niche procurement outside standard military budget cycles.
- Private Sector:Commercial entities explore electronic warfare applications for counter-drone and spectrum monitoring services. FAA certification barriers constrain dual-use technology transfer timelines.
Procurement volume concentrates with Military Forces. Technology advancement funding flows most heavily through Defense Contractors.
Platform Type:
Payload power-to-weight ratios and endurance requirements segment engineering approaches.
- Fixed-Wing Aircraft:Manned combat aircraft carry the highest-power electronic attack systems. The F-35 and Eurofighter Typhoon integrate conformal antenna arrays for signature management. Thermal constraints on fifth-generation stealth platforms drive co-development partnerships.
- Rotary-Wing Aircraft:Helicopter-mounted systems prioritize compact, vibration-resistant packaging. US Army and UK Army Air Corps requirements emphasize survivability against man-portable air defense threats.
- UAVs:Medium-altitude long-endurance platforms extend electronic warfare reach without crew risk. NATO's Alliance Ground Surveillance program funds payload integration for contested spectrum operations.
- Drones:Small unmanned systems enable distributed electronic warfare node architectures. Swarm tactics development in Germany, France, and the United Kingdom accelerates miniature high-power amplifier demand.
Fixed-Wing Aircraft host the largest installed base. Drone platforms are expanding most quickly.
Type:
Functional specialization versus integrated multi-mission capability shapes subsystem procurement.
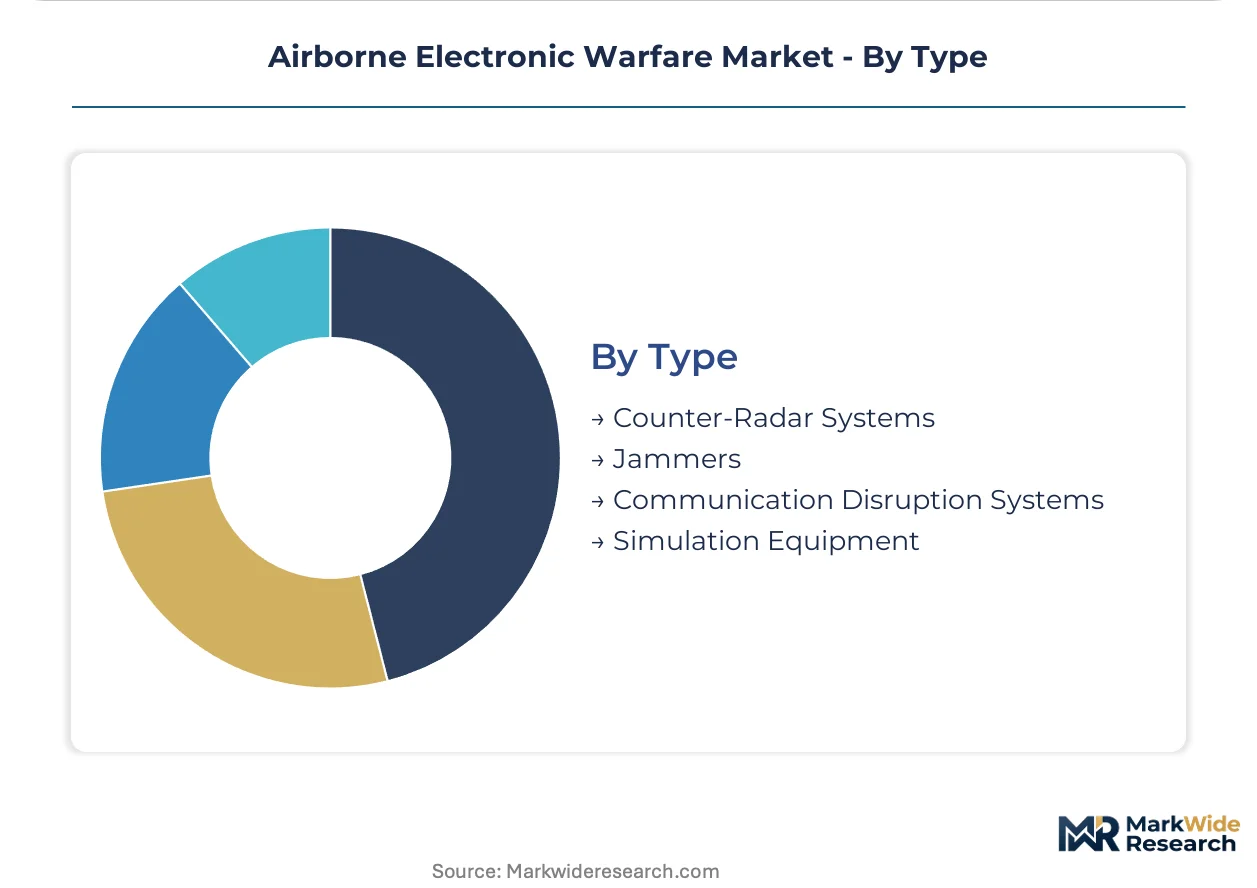
- Counter-Radar Systems:Anti-radiation weapons and jamming platforms suppress enemy air defenses. US Navy and Royal Air Force expeditionary requirements sustain standoff capability investment.
- Jammers:High-power transmitters deny adversary use of specific frequency bands. Gallium nitride amplifier technology is displacing legacy traveling-wave tube designs.
- Communication Disruption Systems:Tactical networks and command links face targeted interference. Electronic attack against satellite communications represents the fastest-climbing capability priority.
- Simulation Equipment:Threat emitters and anechoic chambers support operator training and system validation. European maintenance facilities face REACH-compliant material recertification for thermal interface compounds.
Jammers constitute the largest installed equipment category. Communication Disruption Systems show the steepest capability investment trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electromagnetic spectrum engineering talent concentrates disproportionately in the United States and United Kingdom, with specialized RF design expertise for millimeter-wave applications remaining scarce across NATO member states. Universities in these countries struggle to replenish human capital pipelines even as demand accelerates for software-defined radio architectures.
United States
The Pentagon's budget allocations for airborne electronic warfare systems outpace all other national defense markets, with the US Air Force's Next Generation Air Dominance program driving integrated electronic attack suite procurement. FAA certification requirements for unmanned platforms carrying electronic payloads constrain dual-use technology transfer timelines. The Washington-Baltimore corridor hosts prime contractor engineering centers where co-development partnerships with subsystem vendors compress independent margin capture.
United Kingdom
The UK Ministry of Defence platform programs anchor BAE Systems' captive electronic warfare capabilities, with Royal Air Force Tempest initiatives specifying reprogrammable architectures. REACH substance restrictions force 18-month recertification timelines for revised material specifications in conformal coatings and thermal interface compounds. The South West England aerospace cluster around Bristol maintains deep integration between prime contractors and specialized subsystem developers.
Germany
Military procurement offices in Germany fund rapid prototyping programs for miniature high-power amplifiers serving drone swarm architectures. The European Defence Agency shapes interoperability mandates that determine market access for subsystem vendors across allied supply chains. The Bavarian aerospace corridor around Munich concentrates RF engineering expertise for contested spectrum operations.
France
The French Directorate General of Armaments drives specifications for Franco-German next-generation fighter programs, with CE marking pathway expansion reducing certification cost burdens for qualified vendors. Thales Group anchors domestic electronic attack capabilities through platform integration partnerships. The Paris-Saclay technology cluster hosts signal intelligence software development for real-time threat classification.
Poland
NATO's eastern flank procurement of standoff jamming capabilities proceeds without established domestic supplier relationships, creating entry opportunities for foreign vendors with rapid fielding track records. The country's national defense ministry prioritizes foundational platform positions before long-term maintenance contracts lock in incumbent relationships. The Warsaw-Łódź manufacturing corridor attracts subsystem assembly operations serving Baltic states demand.
Airborne Electronic Warfare Market Competitive Environment
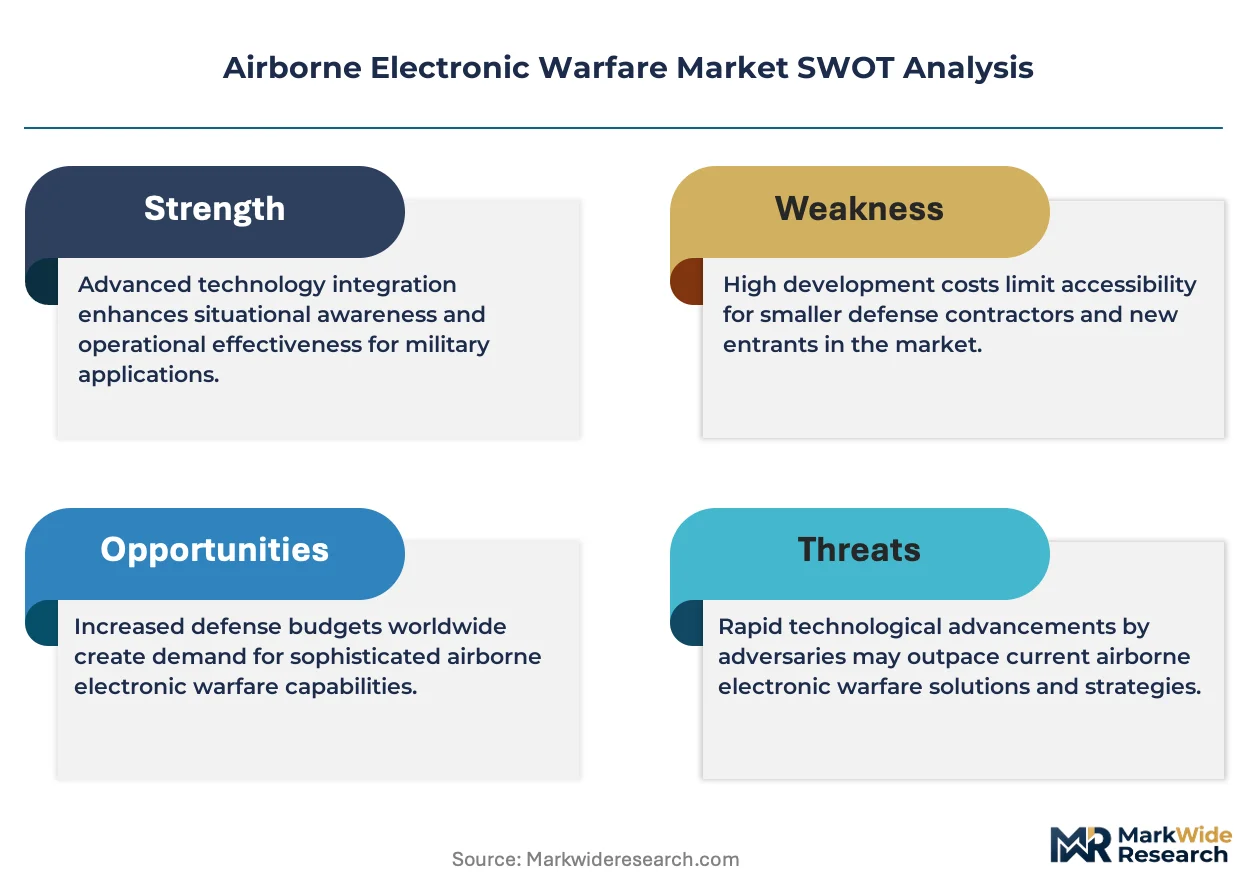
The competitive structure tilts toward prime contractors with captive semiconductor fabrication and deep ministry integration. Consolidation around systems integrators persists alongside fragmentation among specialized subsystem vendors. Three archetypes dominate: vertically integrated defense conglomerates with platform prime contracts, RF component specialists with software-defined radio cores, and regional champions anchored to single-nation procurement. Competitive moves concentrate on strategic partnerships for manned-unmanned teaming architectures and technology licensing for gallium nitride amplifier production.
Among US-based systems integrators, Lockheed Martin and Northrop Grumman occupy positions exemplifying the vertically integrated archetype, with the former sustaining margins through captive semiconductor fabrication and the latter differentiating via next-generation electronic attack architectures. BAE Systems represents the regional champion model through deep integration with UK Ministry of Defence platform programs. These three companies anchor the competitive landscape without exhausting the vendor ecosystem.
| Leading Market Players |
|---|
| Lockheed Martin |
| RTX |
| BAE Systems |
| Elbit Systems |
| Leonardo |
| Northrop Grumman |
| Thales Group |
| General Dynamics |
| L3Harris Technologies |
| Others |
Value Chain & Pricing Dynamics
REACH substance restrictions gate qualified supply for conformal coatings and thermal interface compounds while segmenting pricing access across three tiers. European maintenance facilities face 18-month recertification timelines that advantage pre-qualified suppliers with premium-tier positioning. The Pentagon's electromagnetic spectrum superiority mandates compress procurement cycles for software-defined radio cores, forcing buyers toward certified vendors regardless of cost.
Pricing Analysis
Bundled hardware-software-sustainment contracts dominate prime platform awards while unbundled module procurement expands for spiral upgrades. Price differentiation hinges on software reprogrammability depth and NATO interoperability certification tier. Cost compression in legacy analog retrofit segments intensifies as platform operators defer full modernization. Defense contractors serving allied export markets exhibit highest price sensitivity; sovereign military operators prioritize capability assurance over unit economics.
Supply Chain Analysis
Dual-sourcing requirements for gallium nitride substrates mandate multi-supplier qualification across Japanese and US wafer vendors. High-power amplifier production draws from six-inch SiC substrate supply concentrated in Japan, the United States, and Germany. Single-source dependency on Japanese wafer suppliers creates vulnerability in jamming pod manufacturing chains. Distribution runs through prime contractor assembly facilities with expeditionary maintenance units requiring rapid module swap capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The airborne electronic warfare market compounds steadily as electromagnetic spectrum superiority mandates drive recurring modernization cycles across NATO fleets. Platform-specific engineering requirements and software-defined architecture transitions sustain vendor pricing power.
For Market Incumbents: Cement platform integration partnerships from preliminary design review forward to compress independent challenger margin capture. Deepen captive semiconductor fabrication for gallium nitride amplifiers to defend against emerging RF component specialists with software-defined radio cores. Prioritize REACH-compliant material certification pathways to lock out European subsystem competitors facing 18-month recertification timelines.
For New Entrants and Emerging Players: Enter via Poland and Baltic states procurement of standoff jamming capabilities where established domestic supplier relationships remain absent. Target drone swarm payload categories funded by German, French, and British rapid prototyping programs as the most penetrable segment. Pursue CE marking pathway expansion through European Defence Fund consortium participation to access Franco-German next-generation fighter supply chains.
For Investors and Strategic Acquirers: Roll-up economics work for RF component specialists with software-defined radio cores because platform disaggregation creates direct vendor relationships for spiral upgrades outside prime contractor capture. Five-to-ten year viability rests on machine learning-enabled threat library architectures converging with reprogrammable hardware. Watch for electromagnetic spectrum policy evolution across multiple defense ministries as the inflection signal for platform modernization cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Payload Integration | Consolidates electronic attack, protect, and signals intelligence into unified reprogrammable stacks for NGAD and Tempest programs. |
| Gallium Nitride Amplifier Backward Integration | Captive wafer supply secures margins against Japanese and US substrate supplier price volatility. |
| CE Marking Pathway Expansion | European Defence Fund incentives reduce certification burdens for Franco-German fighter program access. |
| AI-Enabled Threat Library Development | Machine learning architectures enable subscription revenue from real-time signal classification database refreshes. |
| Expeditionary Maintenance Partnership | Pacific theater disaggregation creates direct vendor relationships for rapid module swap without prime contractor technical assistance. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged program office directors at the US Navy's Airborne Electronic Attack Systems Program Office, RF engineering leads at Bavarian aerospace corridor firms, procurement officers at the UK Ministry of Defence, and subsystem vendor executives at South West England cluster companies. Secondary validation drew from Pentagon budget justification documents, European Defence Agency capability development reports, NATO Electronic Warfare Working Group interoperability standards, and FAA unmanned platform certification filings. Bottom-up platform installation forecasts triangulated against top-down defense expenditure allocations.
Comparable historical periods anchored the projection horizon to established modernization cycle patterns. Segmentation modeling spanned technology type, platform category, end-user archetype, and regional procurement cluster. CAGRs were derived from installed base growth adjusted for platform retirement schedules and spiral upgrade penetration rates. Forecast inputs included electromagnetic spectrum superiority mandate implementation timelines and REACH substance restriction phase-in schedules.
Inputs from Pentagon program offices and European Defence Agency planning documents were available through the study window; gaps in classified threat signature evolution timelines introduce uncertainty bands around electronic attack capability refresh rates. Deviation in NATO eastern flank procurement acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Radar Warning Receiver Market
Defense and Military Systems and Equipment
Global Digital Battlefield Market
Defense and Military Systems and Equipment
Explosive Ordnance Disposal Market
Defense and Military Systems and Equipment
Bio-Defense Market
Defense and Military Systems and Equipment
Network Centric Warfare (NCW) Market
Defense and Military Systems and Equipment
Defense Integrated Antenna Market
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Display Systems Market
Defense and Military Systems and Equipment
Military Phased Array Antenna Market
Defense and Military Systems and Equipment
Cognitive Electronic Warfare System Market
Defense and Military Systems and Equipment
GCC Defense Market
Defense and Military Systems and Equipment
Defense Tactical Computers Market
Defense and Military Systems and Equipment
Mechanical and Electronic Fuzes Market
Defense and Military Systems and Equipment
Global Non Lethal Biochemical Weapon Market
Defense and Military Systems and Equipment
Explosive Ordnance Disposal (EOD) Equipment Market
Defense and Military Systems and Equipment
India Defense Market
Defense and Military Systems and Equipment
Land-Based Smart Weapons Market