
 Global Military Defense Vehicle Intercom System Market | 2026-2036
Global Military Defense Vehicle Intercom System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Military Defense Vehicle Intercom System Market Outlook
The gap between field-proven analog architectures and software-defined digital platforms is repositioning procurement criteria across defense ministries. Thales Group leverages its European installed base to sustain upgrade contracts for legacy vehicle fleets. L3Harris Technologies anchors North American supply through captive manufacturing of noise-canceling headsets and vehicle control units. Elbit Systems competes on integrated battle management systems that embed intercom functions within broader vehicle electronics suites.
Military defense vehicle intercom systems comprise audio distribution networks, crew station terminals, and power amplifiers engineered to operate across temperature extremes from minus 40 to plus 71 degrees Celsius while suppressing ambient noise exceeding 120 decibels. These systems enable coordinated crew communication under armor, integrating radio gateways and warning tone generators essential for situational awareness in combat vehicles. Wired systems retain dominance in heavy armor applications where electromagnetic hardening against jamming takes precedence over installation flexibility. Digital technology segments expand fastest as VoIP-enabled architectures replace copper harnesses with Ethernet backbones, concentrating margin pools in software licensing and encryption modules. Mesh technology remains nascent but attracts development funding for dismounted-vehicle connectivity trials.
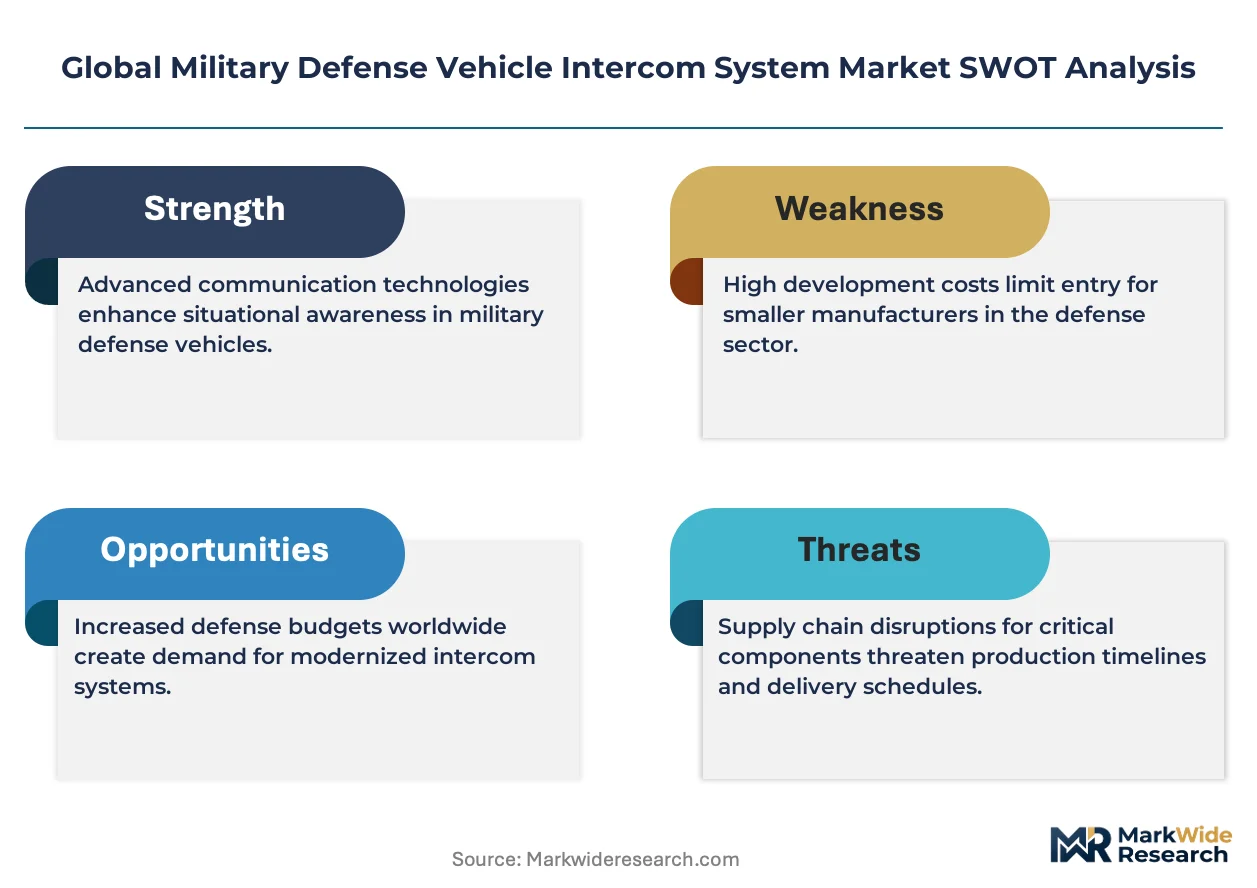
The US Department of Defense enforces MIL-STD-810H environmental qualification and MIL-STD-461G electromagnetic compatibility standards that dictate product design thresholds and test protocols for all vehicle-mounted electronics. European procurement through NATO standardization agreements and national military specifications such as German VG standards creates dual compliance burdens for cross-border suppliers. Stakeholders must monitor divergence between allied interoperability mandates and sovereign data-localization requirements as allied nations harden supply chains against foreign component dependencies.
Market Dynamics
Analog-to-digital migration is compressing procurement timelines as defense ministries mandate IP-based architectures for electromagnetic survivability against near-peer electronic warfare threats.
Growth Catalysts
- Armored Vehicle Modernization:NATO member states are funding fleet-wide retrofits of legacy platforms with digital intercom backbones to satisfy interoperability mandates under STANAG standards.
- MIL-STD-188-141B Cybersecurity Hardening:US Department of Defense encryption requirements for tactical communications are forcing replacement of unencrypted analog voice distribution systems in ground combat vehicles.
- VoIP-Enabled Ethernet Architectures:Software-defined radio integration is driving demand for packet-switched intercom networks that collapse separate audio, data, and video harnesses into unified vehicle electronics.
Market Restraints
- Copper Harness Replacement Costs:Retrofit programs for legacy armored vehicles face structural cost barriers from complete rewiring of internal communications infrastructure.
- Domestic Defense Industrial Base Concentration:Indigenous integration capabilities in the United States, Germany, and South Korea limit market access for foreign subsystem suppliers lacking local partnerships.
- Temperature Hardening Requirements:MIL-STD-810H qualification for operation across minus 40 to plus 71 degrees Celsius imposes extended development cycles and specialized component sourcing.
Strategic Opportunities
- Mesh Network Dismounted Connectivity:Experimental programs linking vehicle intercoms to soldier-worn radios present white space for wireless extension modules in NATO rapid reaction forces.
- Integrated Battle Management Convergence:Embedding intercom functions within broader vehicle electronics suites opens paths for system-of-systems contractors to capture audio distribution value pools.
- Indo-Pacific Fleet Expansion:Australia's Land 400 and South Korea's KF-21 Boramae programs are generating demand for indigenous vehicle communications capabilities outside traditional Atlantic supply chains.
Industry Challenges
- Cross-Border Certification Burden:Suppliers must simultaneously satisfy US MIL-STD-461G electromagnetic compatibility and German VG standards, fragmenting engineering resources across divergent test protocols.
- Legacy Platform Integration Complexity:Digital intercom retrofits must maintain backward compatibility with analog radio gateways in fielded vehicles, constraining architecture optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Military Defense Vehicle Intercom System Market |
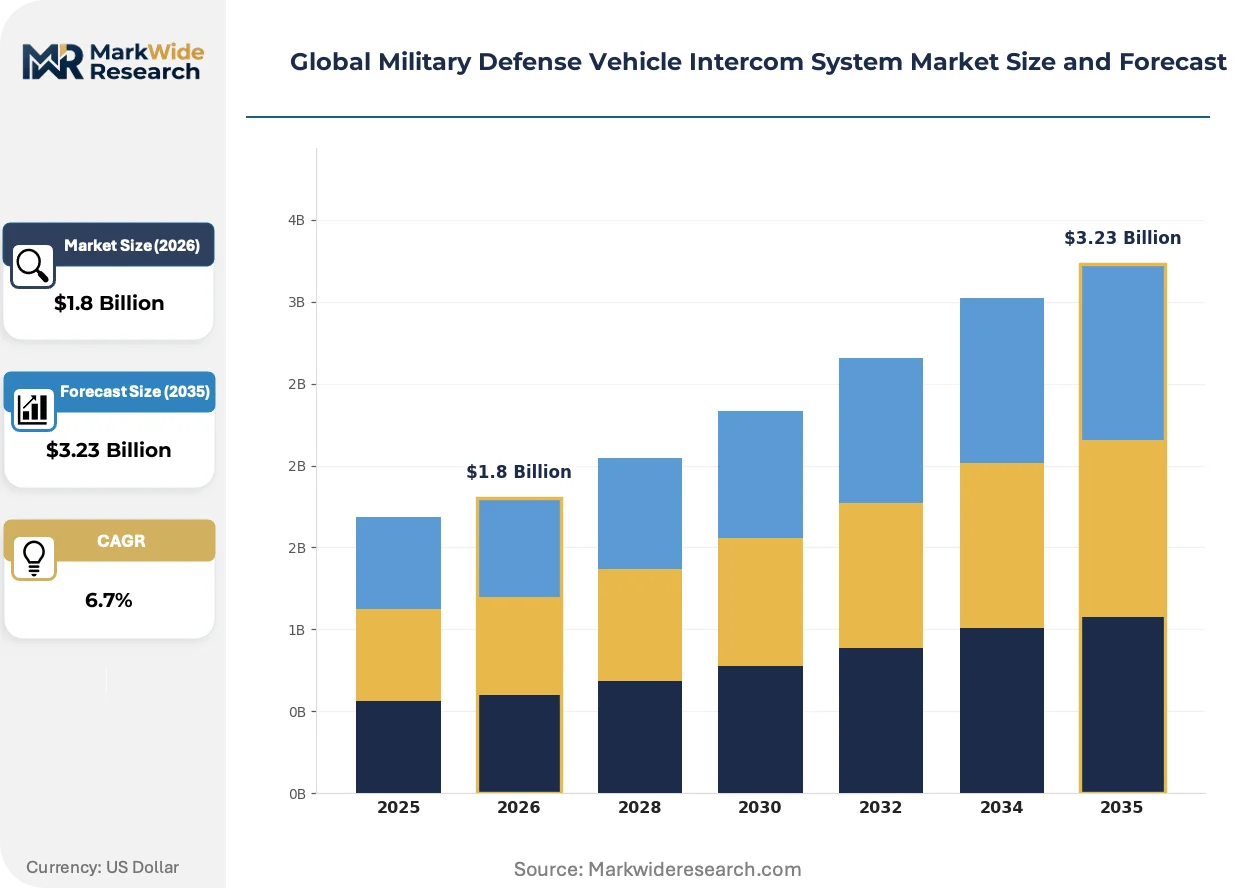
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Systems, Wireless Systems, Hybrid Systems, Digital Systems End User: Military, Defense Contractors, Government Agencies, Law Enforcement Technology: Analog Technology, Digital Technology, VoIP Technology, Mesh Technology Installation Type: Fixed Installation, Portable Installation, Vehicle Integration, Retrofit |
| Companies Covered | David Clark Company, Telephonics, Thales Group, Elbit Systems, Rohde & Schwarz, L3Harris Technologies, Racal Acoustics, Northrop Grumman, Cobham, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Military Defense Vehicle Intercom System Market Strategic Shifts
Defense procurement offices are rewriting technical specifications to prioritize software modularity over hardware longevity, compressing supplier R&D cycles and elevating firmware update capabilities as competitive differentiators.
Ethernet-based audio distribution is consolidating vehicle communications onto unified digital backbones. This technology replaces discrete copper harnesses for crew stations, radio gateways, and warning systems with packet-switched networks. Armored vehicle prime contractors in NATO member states are mandating IP architectures for new-build platforms. The shift is consolidating margin pools into software licensing and encryption module suppliers while commoditizing legacy amplifier hardware.
REACH substance restrictions and EU Green Deal circularity mandates are reshaping component qualification for European defense exports. The European Chemicals Agency has added candidate substances affecting cable insulation and connector plating to the authorization list. German and French vehicle integrators are now screening intercom subsystems for restricted materials ahead of formal regulatory deadlines. Suppliers without established green chemistry compliance pathways face exclusion from cross-border NATO procurement.
Long-term through-life support contracts are displacing transactional hardware purchases in major armored vehicle programs. Defense ministries in Australia and the United Kingdom are unbundling initial system delivery from sustainment services, awarding separate multi-year logistics agreements. This bifurcation favors integrators with established depot maintenance networks over component specialists lacking field service infrastructure. The model is most advanced in British Army Ajax and Australian Land 121 programs where availability-based contracting now governs intercom subsystem performance.
Global Military Defense Vehicle Intercom System Market Segmentation
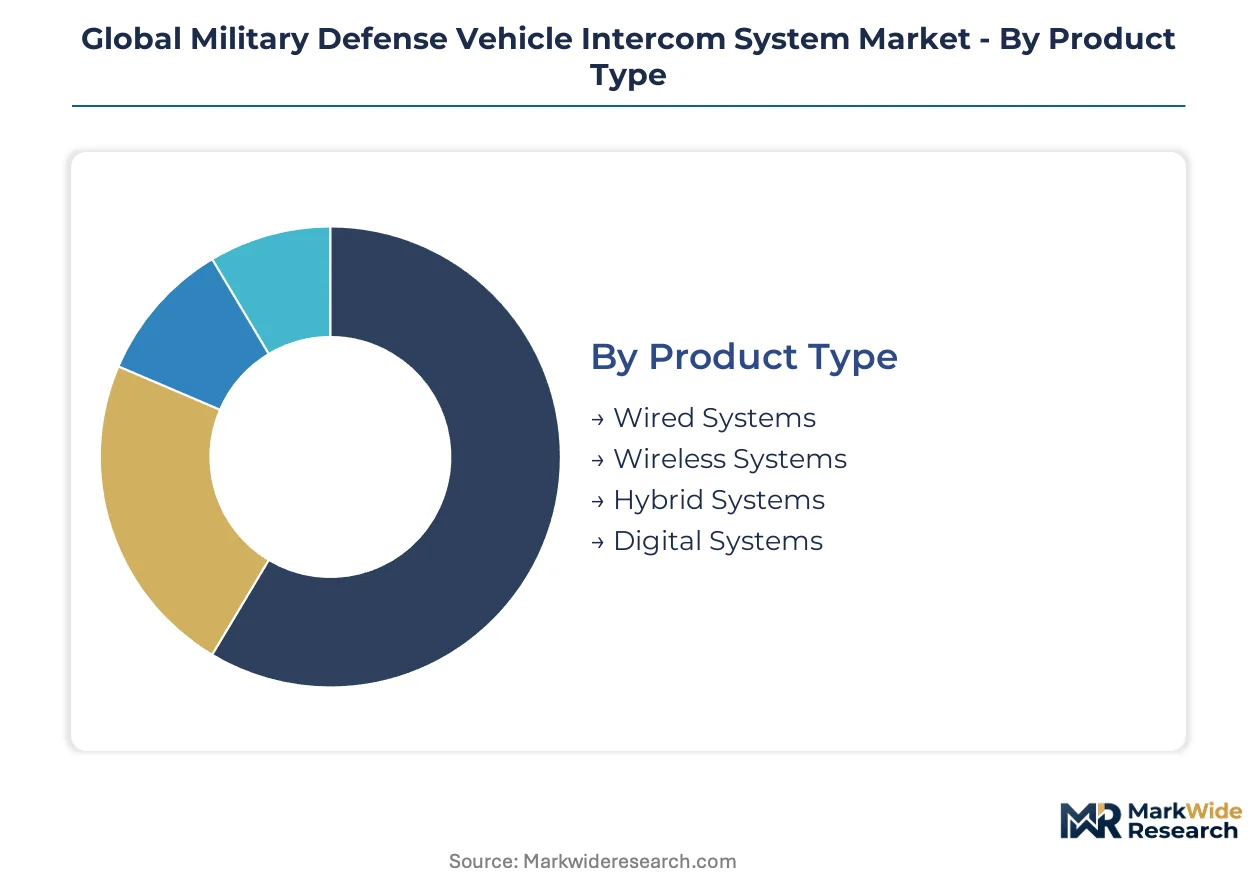
Segmentation in military vehicle intercom systems reveals how procurement priorities diverge between heavy armor platforms requiring electromagnetic hardening and rapid reaction forces demanding installation flexibility. Understanding these divides exposes where margin pools concentrate and which technology transitions reshape competitive positioning.
Product Type:
Wired architectures dominate standalone heavy armor applications where jamming resilience outweighs reconfiguration needs, while hybrid and wireless configurations embed within broader vehicle electronics suites for lighter platforms.
- Wired Systems:Copper harness architectures deliver electromagnetic pulse immunity for main battle tanks and infantry fighting vehicles. The US Army's Abrams modernization and Germany's Puma fleet sustain demand where MIL-STD-461G compliance is non-negotiable.
- Digital Systems:IP-based packet-switched networks consolidate audio, data, and video onto Ethernet backbones with software-defined encryption modules. NATO STANAG interoperability mandates in Poland and Romania are accelerating procurement of these architectures for new-build armored vehicles.
- Wireless Systems:Radio-frequency extensions for dismounted crew connectivity operate in contested spectrum environments.
- Hybrid Systems:Dual-mode configurations preserve wired backbone integrity while adding wireless access points for command vehicles.
Wired systems lead volumes today; digital systems are gaining share fastest.
End User:
Customer type determines contracting mechanisms, with military end-users driving standardization while defense contractors capture integration value through prime vehicle contracts.
- Military:National armed forces specify intercom subsystems through platform-level procurement, embedding requirements within armored vehicle tenders. The US Department of Defense, British Army, and Australian Defence Force anchor demand through multi-year fleet modernization programs with through-life support clauses.
- Defense Contractors:Vehicle prime contractors source intercom modules for integration into complete combat systems. Rheinmetall, Hanwha Aerospace, and General Dynamics Land Systems exercise specification authority that constrains subsystem supplier access without partnership structures.
- Government Agencies:Border security and counter-terrorism units procure portable configurations for non-standard vehicles.
- Law Enforcement:Tactical response teams require hardened communications for armored rescue vehicles.
Military end-users generate the highest absolute spend; defense contractors represent the fastest-climbing customer segment as prime integration consolidates.
Technology:
Technology segments track the forced migration from legacy analog voice distribution to encrypted digital architectures under cybersecurity hardening mandates.
- Digital Technology:Pulse-code modulation and software-defined processing enable AES-256 encryption with firmware-updatable threat response. South Korea's KF-21 Boramae and Australia's Land 400 Phase 3 mandate these capabilities for electromagnetic survivability against near-peer electronic warfare.
- VoIP Technology:Voice-over-IP packet distribution collapses separate harnesses for intercom, radio, and warning systems onto unified Ethernet infrastructure. German VG standards and US MIL-STD-188-141B encryption requirements are converging procurement specifications around these architectures.
- Analog Technology:Legacy amplitude-modulation systems persist in fielded vehicle fleets requiring backward-compatible retrofit paths.
- Mesh Technology:Self-healing network protocols for dismounted-vehicle connectivity remain experimental with limited procurement beyond NATO rapid reaction force trials.
Analog technology retains installed base dominance; VoIP-enabled architectures are expanding most quickly.
Installation Type:
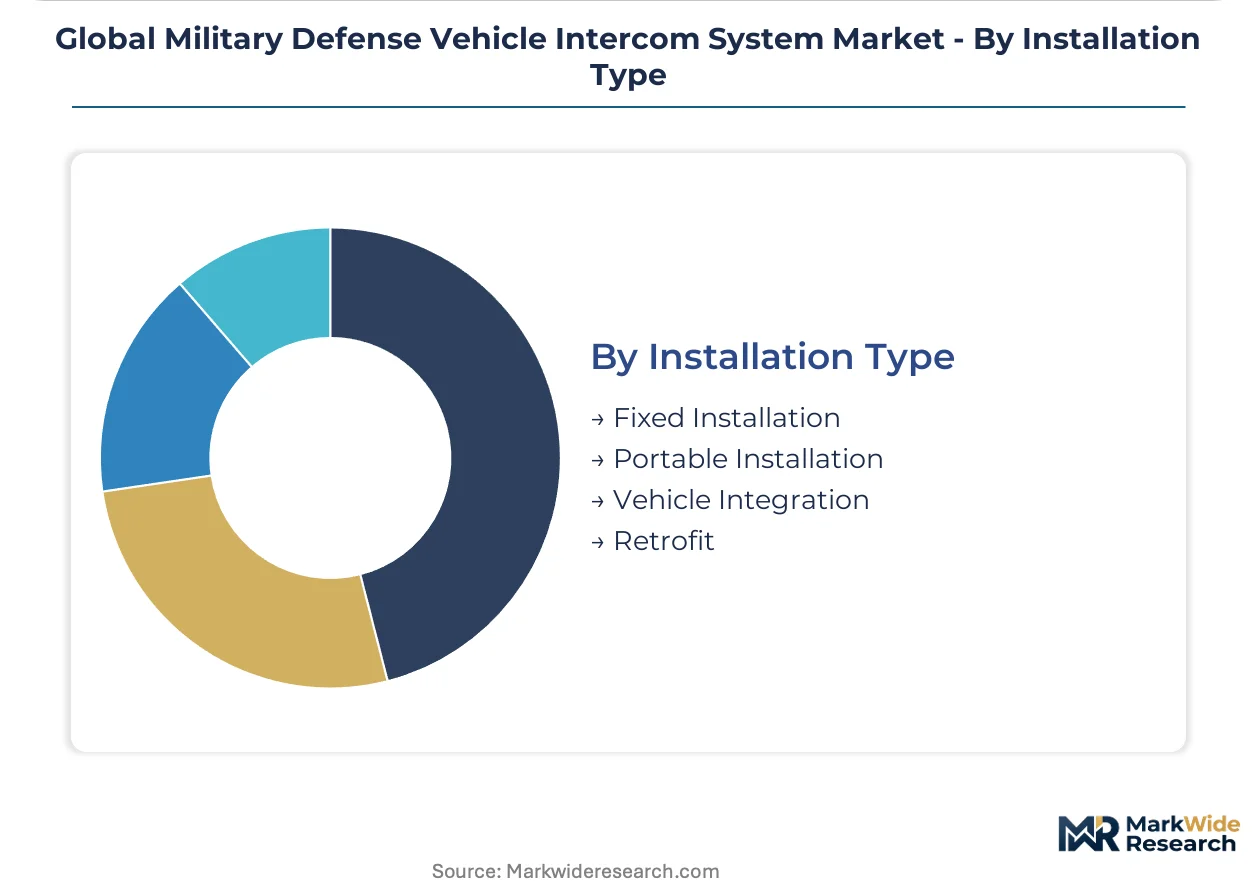
Installation modality separates new-build platform integration from the structural cost barriers of legacy vehicle rewiring.
- Vehicle Integration:Factory-installed systems specified by armored vehicle prime contractors during initial production. This channel concentrates in South Korea, Germany, and the United States where domestic industrial bases sustain indigenous integration capabilities.
- Retrofit:Field modification of operational vehicle fleets with digital backbone replacement. Complete copper harness removal in legacy Abrams, Leopard 2, and K1 platforms imposes cost barriers that compress procurement timelines and favor modular overlay solutions.
- Fixed Installation:Permanent mounting in command post vehicles and artillery platforms.
- Portable Installation:Rapidly deployable systems for temporary vehicle assignment and coalition interoperability exercises.
Vehicle integration captures the majority of new procurement value; retrofit programs are climbing fastest as modernization timelines compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense electronics engineering clusters in Massachusetts, Bavaria, and Seoul anchor vehicle intercom development. Procurement concentrates where domestic armored vehicle production sustains captive integration demand.
United States
The US Army's Abrams modernization and Marine Corps ACV programs drive digital intercom procurement. MIL-STD-188-141B encryption mandates under DoD cybersecurity directives force analog system replacement. Worcester, Massachusetts hosts headset manufacturing and vehicle control unit assembly for North American supply chains.
Germany
Rheinmetall's Puma fleet expansion and Leopard 2 retrofits sustain demand for electromagnetic-hardened architectures. German VG standards and NATO STANAG interoperability requirements create dual compliance frameworks. Bavaria's defense corridor around Munich concentrates subsystem integration for European vehicle programs.
South Korea
Hanwha Aerospace's KF-21 Boramae and K2 Black Panther production mandates indigenous communications capabilities. Domestic content requirements under Defense Acquisition Program Administration guidelines limit foreign supplier access. Changwon and Sacheon industrial complexes house vehicle electronics integration facilities.
Australia
Land 400 Phase 3 and Boxer CRV programs generate demand for through-life support contracting. TGA certification alignment with MIL-STD-810H enables trans-Pacific supplier qualification. Victoria's defense precinct near Melbourne anchors vehicle modification and depot maintenance networks.
United Kingdom
British Army Ajax and Warrior Capability Sustainment Programme drive availability-based intercom procurement. UK Defence Standard 00-35 environmental qualification runs parallel to NATO agreements. Midlands manufacturing clusters around Telford sustain legacy platform retrofit capabilities.
Global Military Defense Vehicle Intercom System Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the military vehicle intercom market. Prime vehicle contractors exercise specification authority that constrains subsystem supplier access without partnership structures. Three archetypes dominate: European integrators with legacy installed bases, North American captive manufacturers, and Israeli system-of-systems specialists. Consolidation proceeds through strategic partnerships with domestic vehicle primes and technology licensing for encryption modules.
Within the European integrator tier, Thales Group and Rohde & Schwarz exemplify archetypes leveraging regional standards influence. L3Harris Technologies anchors North American supply through Massachusetts-based manufacturing operations. Elbit Systems occupies a position bridging intercom functions with broader battle management integration. These three represent distinct competitive vectors: standards-driven European procurement, captive US industrial base supply, and converged electronics warfare platforms.
| Leading Market Players |
|---|
| David Clark Company |
| Telephonics |
| Thales Group |
| Elbit Systems |
| Rohde & Schwarz |
| L3Harris Technologies |
| Racal Acoustics |
| Northrop Grumman |
| Cobham |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed defense primes in Germany, South Korea, and the United States anchor supply-side concentration, translating captive integration capabilities into pricing discipline that resists commoditization pressure from foreign subsystem vendors. This ownership structure reinforces long-term contracting preferences that bundle hardware procurement with through-life sustainment services, compressing margins for standalone component suppliers lacking depot maintenance networks.
Pricing Analysis
The bundled-vs-unbundled service split distinguishes availability-based contracting from transactional hardware sales. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under MIL-STD-810H and German VG standards, with encryption module integration commanding substantial premiums. Cost compression in retrofit copper harness replacement is intensifying because defense ministries prioritize new-build vehicle integration over legacy platform rewiring. Defense contractors sourcing for prime vehicle programs exhibit lowest price sensitivity; government agencies procuring portable configurations for border security applications demonstrate highest sensitivity to unit costs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Rheinmetall, Hanwha Aerospace, and General Dynamics Land Systems, constraining subsystem supplier access without established partnership frameworks. Manufacturing concentration in Massachusetts, Bavaria, and Seoul draws from specialized semiconductor foundries in Taiwan, rare earth magnet suppliers in China, and cable insulation compound producers in Germany. Single-source vulnerability in AES-256 encryption module fabrication creates supply chain risk exposure for European and Indo-Pacific procurement programs. Distribution runs through prime contractor specification authority rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play: Australian Land 400 and British Army Ajax programs impose through-life support mandates that domestic US and German suppliers can fulfill at lower operational cost than local entrants lacking established depot networks.
For Market Incumbents: Extend firmware update capabilities as competitive differentiators against emerging software-defined radio integrators threatening to subsume intercom functions within broader vehicle electronics suites. Deepen backward integration into noise-canceling headset manufacturing to defend margin position from component commoditization. Prioritize certification investment in German VG standards and US MIL-STD-461G electromagnetic compatibility to maintain cross-border procurement eligibility.
For New Entrants and Emerging Players: Enter via mesh network dismounted connectivity modules for NATO rapid reaction force trials, the most penetrable white space given limited incumbent development focus. Target Australian and South Korean defense procurement channels where indigenous integration requirements have historically constrained foreign access but are now relaxing under fleet expansion pressures. Pursue technology licensing arrangements with established encryption module suppliers rather than independent certification pathways.
For Investors and Strategic Acquirers: Valuations sit cheapest among component specialists lacking field service infrastructure, as defense ministries bifurcate hardware delivery from sustainment contracts. Long-term viability hinges on through-life support contract capture rather than initial system sales volume. Acquisition target archetype: mid-tier integrators with established partnerships in South Korea or Australia. The signal to watch is divergence between allied interoperability mandates and sovereign data-localization requirements hardening supply chains against foreign component dependencies.
| Strategic Initiative | Industry Significance |
|---|---|
| Encryption Module Backward Integration | Captive supply of AES-256 modules insulates margins from semiconductor foundry pricing volatility. |
| VoIP-Enabled Ethernet Architecture Launch | Packet-switched consolidation captures software licensing value pools from legacy copper harness suppliers. |
| Depot Maintenance Network Expansion | Australian Land 400 availability-based contracting favors integrators with Victoria-based service infrastructure. |
| Green Chemistry Compliance Pathway | REACH substance screening ahead of EU deadlines secures German and French vehicle integrator qualification. |
| Mesh Network Development Partnership | NATO rapid reaction force trials create first-mover positioning for wireless extension module suppliers. |
Study Parameters
Bottom-up armored vehicle platform modeling reconciled against top-down defense electronics supply tracking forms the analytical core. Primary interviews with vehicle prime contractor procurement officers, subsystem integration engineers, defense ministry program managers, and depot maintenance directors combined with secondary validation against NATO standardization agreement documentation, national military specification registries, and defense industrial base trade filings. Triangulation across bottom-up fleet modernization timelines and top-down contractor revenue segment disclosures ensures statistical integrity.
Input-output matrices map intercom system content per vehicle across platform classes, installation modalities, and technology generations. Segmentation dimensions include product architecture, end-user contracting mechanism, technology maturity stage, and regional procurement framework. CAGRs derive from vehicle production forecasts cross-referenced with analog-to-digital replacement curves and cybersecurity hardening mandate compliance timelines. Industry-specific forecast inputs incorporate STANAG interoperability adoption rates and domestic content requirement enforcement intensity in South Korea and Australia.
The model holds under sustained NATO member state defense expenditure; deviation in Indo-Pacific fleet expansion acceleration or REACH regulatory enforcement relaxation would shift procurement volume distribution. Forecasts reflect documented assumptions regarding electromagnetic hardening standards convergence and encryption module supply availability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Middle East and Africa Defense Market
Defense and Military Systems and Equipment
Network Centric Warfare (NCW) Market
Defense and Military Systems and Equipment
Search and Rescue Equipment Market
Defense and Military Systems and Equipment
GCC Defense Market
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Displays Market
Defense and Military Systems and Equipment
Global Non Lethal Biochemical Weapon Market
Defense and Military Systems and Equipment
India Defense Market
Defense and Military Systems and Equipment
Europe Defense Logistics Market
Defense and Military Systems and Equipment
Explosive Ordnance Disposal (EOD) Equipment Market
Defense and Military Systems and Equipment
Military Phased Array Antenna Market
Defense and Military Systems and Equipment
Mergers and Acquisitions (Manda) in Aerospace and Defense Market
Defense and Military Systems and Equipment
Military Embedded System Market
Defense and Military Systems and Equipment
Asia-Pacific Digital Battlefield Market
Defense and Military Systems and Equipment
Military Exoskeleton Market
Defense and Military Systems and Equipment
Radar Warning Receiver Market
Defense and Military Systems and Equipment
Anti-Drone Guns Market